
 Indonesia Financial Technology Services Market | 2026-2036
Indonesia Financial Technology Services Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Financial Technology Services Market Insights
Bank-grade API reliability is bifurcating the Indonesia fintech landscape into licensed infrastructure providers and unregulated app-layer intermediaries. PT GoTo Gojek Tokopedia Tbk leverages its super-app ecosystem to sustain payment volume dominance across ride-hailing and commerce verticals. Grab Holdings Limited anchors its position through captive logistics networks that control merchant onboarding velocity. PT Fintek Karya Nusantara differentiates via specialized B2B treasury APIs for regional bank partnerships.
Indonesia Financial Technology Services encompass digitally native platforms delivering payment clearing, credit origination, wealth aggregation, and risk scoring through cloud-hosted architectures with sub-second transaction latency. These systems replace legacy branch-based distribution with algorithmic customer acquisition and automated KYC verification. Mobile Payments and Online Lending command the largest transaction volumes, while Digital Banking captures expanding margin pools as neobanks secure full operating licenses. Investment Platforms represent the fastest-growing segment as retail participation in mutual funds and government bonds accelerates through fractionalized interfaces.
Bank Indonesia governs payment system oversight through BI-FAST integration mandates and electronic money licensing tiers, while OJK supervises peer-to-peer lending caps and digital bank capital requirements. The Financial Services Authority's sandbox criteria shape product launch timelines and foreign ownership structures for entrants. Stakeholders must monitor evolving data localization rules and open-banking standardization deadlines that will determine platform interoperability and competitive moat durability.
Market Dynamics
Bank Indonesia's BI-FAST real-time settlement mandate is compressing transaction latency standards across Indonesian payment infrastructure, forcing legacy banks to rebuild core systems or cede volume to licensed neobanks with cloud-native architectures.
Growth Catalysts
- BI-FAST Integration Mandate:Bank Indonesia's real-time gross settlement protocol forces interoperability upgrades across tier-1 and tier-2 banks, accelerating API standardization for fintech middleware providers serving regional lenders.
- Micro-merchant credit demand:SME lending platforms deepen penetration among warung operators across Java's urban corridors, replacing informal moneylender networks with algorithmic scoring based on e-wallet transaction histories.
- OJK Digital Bank Licensing:The Financial Services Authority's capital requirement framework and sandbox pathways enable full-stack neobanks to capture deposit-taking privileges previously reserved for conventional institutions.
Market Restraints
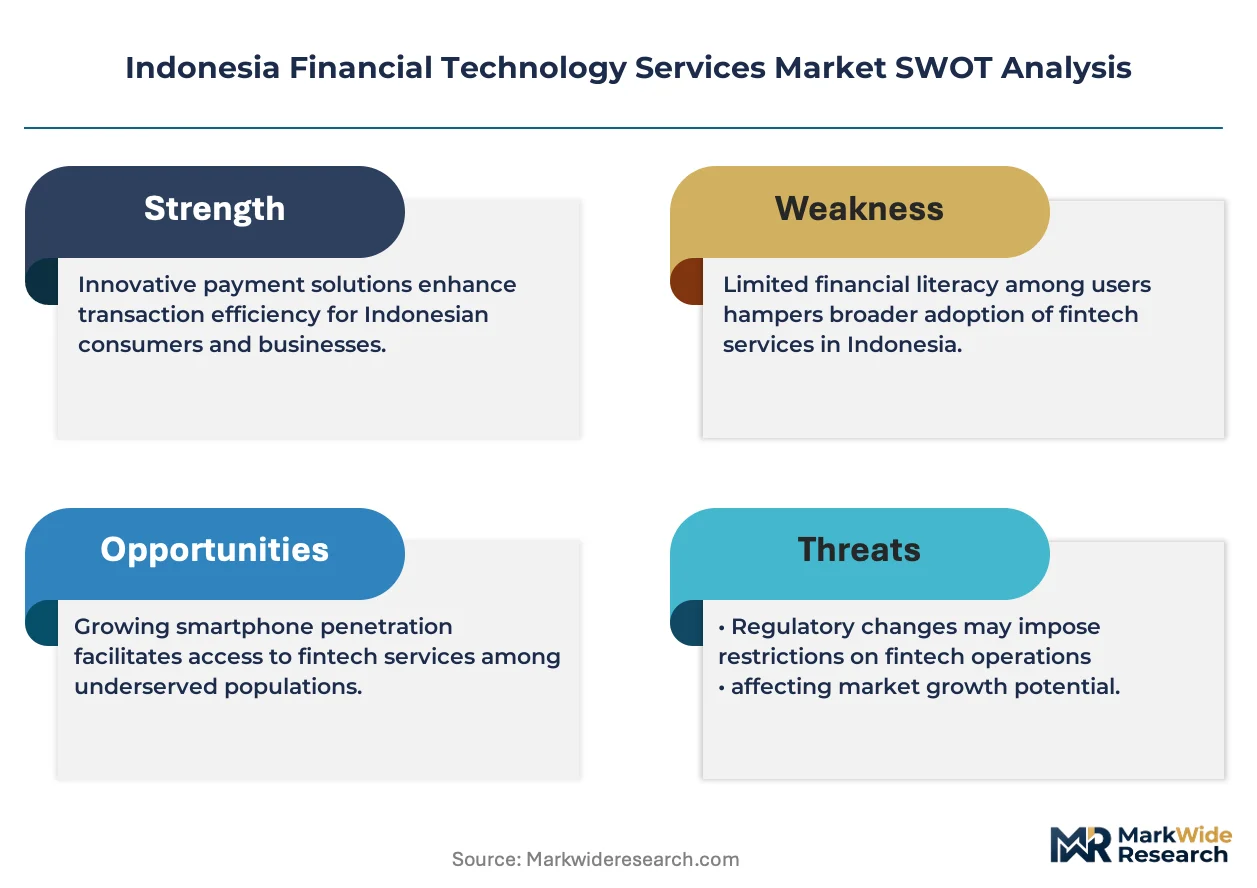
- Data localization compliance costs:Indonesia's data sovereignty rules mandate domestic server placement for transaction records, elevating capex for cloud-reliant entrants compared to regional peers with lighter residency requirements.
- Core banking system concentration:Legacy mainframe dependencies at state-owned banks create integration friction for API-first fintechs, slowing pilot-to-production timelines for partnership models.
- Cash preference persistence:Informal sector merchants across Sumatra and Sulawesi maintain paper-based settlement habits, constraining digital payment adoption velocity outside Java's metropolitan corridors.
Strategic Opportunities
- Sharia-compliant fintech:OJK's regulatory sandbox includes dedicated pathways for Islamic digital banking products, opening white space for mudarabah-based investment platforms and syariah P2P lending structures.
- Eastern Indonesia expansion:Papua and Maluku provinces show underpenetrated mobile money density relative to Java, creating first-mover advantages for agents with localized KYC workflows.
- Embedded finance convergence:Agriculture supply chain platforms in Kalimantan integrate crop financing APIs directly into commodity trading interfaces, collapsing the traditional bank-merchant-borrower distance.
Industry Challenges
- Cloud engineering talent scarcity:Domestic universities produce insufficient Kubernetes and distributed systems specialists, forcing fintechs to compete for Singapore-based engineering talent at premium compensation multiples.
- Legacy core migration complexity:Regional banks' COBOL-dependent infrastructure resists API layer grafting, extending integration timelines and inflating professional services costs for middleware vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Financial Technology Services Market |
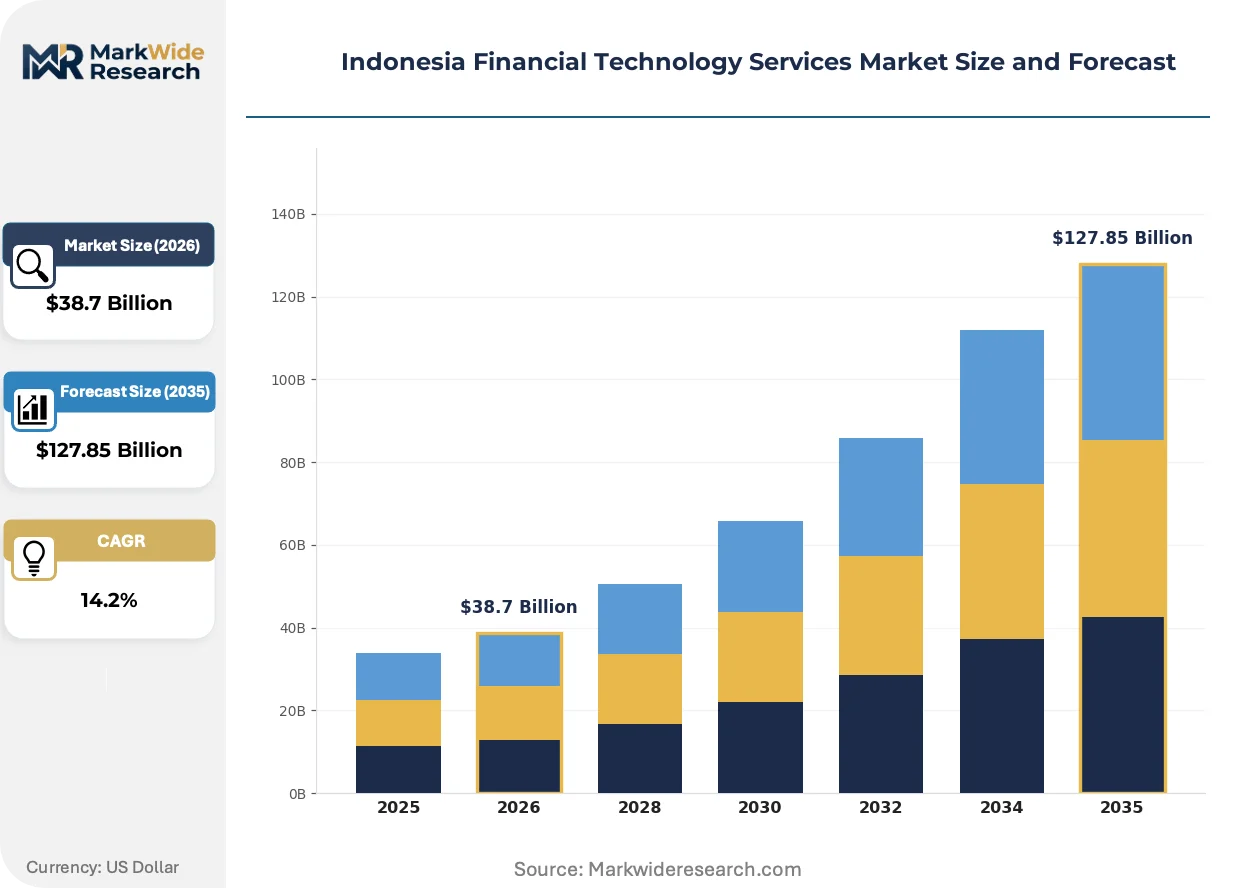
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Payments, Online Lending, Digital Banking, Investment Platforms Customer Type: SMEs, Individual Consumers, Corporates, Startups Application: Payment Processing, Wealth Management, Credit Scoring, Insurance Services Technology: Blockchain, AI, Cloud Computing, Big Data |
| Companies Covered | PT GoTo Gojek Tokopedia Tbk, Grab Holdings Limited, PT Espay Debit Indonesia Koe, PT Fintek Karya Nusantara, ShopeePay, PT Ajaib Teknologi Indonesia, PT Investree Radhika Jaya, Kredivo Holdings, PT Akulaku Silvrr Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Financial Technology Services Market Trends and Innovations
Algorithmic underwriting engines are displacing manual credit committees across Indonesian lending platforms, compressing origination timelines from weeks to minutes while embedding alternative data streams from ride-hailing and e-commerce histories into risk models.
Edge computing nodes deployed at telco towers across the archipelago are miniaturizing transaction processing latency for rural payment terminals, enabling sub-second authorization for BI-FAST messages even in bandwidth-constrained outer island locations. Micro-merchants in Nusa Tenggara adopt these low-latency terminals for real-time settlement, while platform operators compress infrastructure costs through shared edge resources rather than dedicated data center builds.
OJK's risk-based capital framework for digital banks tightens liquidity coverage requirements proportionate to deposit growth velocity, forcing neobanks to build treasury management capabilities that match conventional institutions. The regulation most acutely affects venture-backed entrants with aggressive customer acquisition strategies, pushing several to slow deposit product rollouts while securing wholesale funding lines.
Buyers across Indonesian e-commerce and logistics verticals consolidate vendor relationships around full-stack financial platforms rather than point-solution providers, unbundling separate payment, lending, and treasury management contracts. This procurement compression favors super-app ecosystems with captive user bases, while standalone fintechs face margin pressure from integration demands and longer enterprise sales cycles. The shift concentrates most visibly in Jakarta's digital banking corridor, where conglomerate procurement teams centralize fintech vendor selection under group treasury functions.
Indonesia Financial Technology Services Market Segmentation
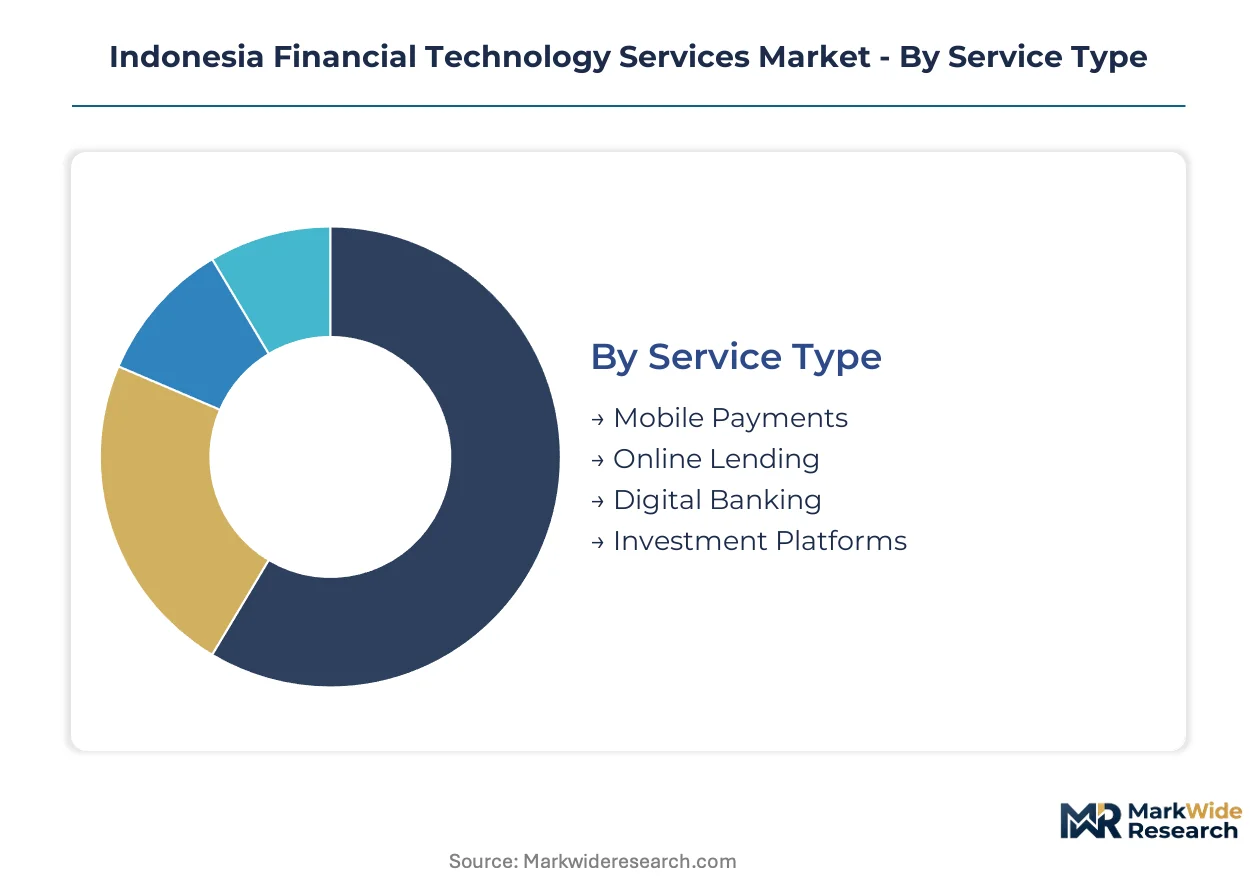
Indonesia's fintech segmentation reflects regulatory licensing tiers that determine capital requirements, operational scope, and permissible customer bases. Bank Indonesia and OJK classifications create distinct competitive arenas where service type and technology choices carry compliance consequences.
Service Type:
Bank Indonesia's electronic money licensing framework and OJK's P2P lending caps create differentiated regulatory burdens across service categories, with capital reserves and audit frequencies scaling with deposit-taking authority.
- Mobile Payments:QRIS-standardized transaction rails process real-time settlements through BI-FAST integration, with volume concentrating among warung operators in Jakarta's digital banking corridor where e-wallet density supports merchant onboarding at scale. Telco-tower edge nodes compress authorization latency for rural terminal deployment.
- Online Lending:Algorithmic underwriting engines embed alternative data from ride-hailing and commerce histories, displacing manual credit committees across Java and Sumatra. OJK's interest rate caps and provisioning rules constrain margin structures for venture-backed platforms.
- Digital Banking:Full-stack neobanks with OJK operating licenses capture deposit-taking privileges previously reserved for conventional institutions, though liquidity coverage requirements tighten proportionate to deposit growth velocity.
- Investment Platforms:Fractionalized mutual fund and government bond interfaces accelerate retail participation, with Sharia-compliant products gaining dedicated sandbox pathways under OJK supervision.
Mobile Payments handles the majority of throughput; Investment Platforms is the fastest mover on share.
Customer Type:
Customer acquisition costs and lifetime value calculations vary sharply across segments, with micro-merchant onboarding requiring agent networks while corporate mandates demand API reliability guarantees and dedicated support tiers.
- SMEs:Warung operators and micro-merchants across Java's urban corridors drive credit demand, with lending platforms replacing informal moneylender networks through algorithmic scoring based on transaction histories. Agent density and localized KYC workflows determine penetration rates.
- Individual Consumers:Retail users consolidate financial activity within super-app ecosystems, unbundling separate payment, lending, and wealth management relationships into single-platform experiences with captive loyalty programs.
- Corporates:Regional banks and conglomerate treasury functions procure full-stack platforms under centralized vendor relationships, demanding B2B treasury APIs with sub-second settlement latency and bank-grade reliability certifications.
- Startups:Early-stage ventures access embedded finance APIs for payment acceptance and working capital, with procurement decisions driven by integration speed rather than feature depth.
SMEs absorb the largest share of platform development resources; Corporates deliver the highest margin per customer.
Application:
Application layer concentration mirrors infrastructure investment patterns, with payment processing commanding the deepest technical integration while insurance services remain constrained by distribution cost structures.
- Payment Processing:BI-FAST real-time gross settlement protocols force interoperability upgrades across tier-1 and tier-2 banks, creating middleware opportunities for API providers serving regional lenders with legacy core dependencies.
- Wealth Management:Robo-advisory interfaces aggregate mutual fund and bond exposure through fractionalized denominations, with demand clustering in Jakarta's metropolitan corridors where financial literacy and disposable income intersect.
- Credit Scoring:Alternative data streams from e-commerce, logistics, and ride-hailing histories feed machine learning models that compress origination timelines from weeks to minutes for thin-file borrowers.
- Insurance Services:Digital distribution platforms embed micro-policies into transaction flows, though persistency rates lag other applications due to limited agent follow-through in outer island provinces.
Payment Processing carries the highest transaction volume; Credit Scoring is expanding most quickly on adoption velocity.
Technology:
Technology stack choices determine compliance posture and scalability ceilings, with data localization mandates elevating infrastructure costs for cloud-reliant architectures compared to on-premise alternatives.
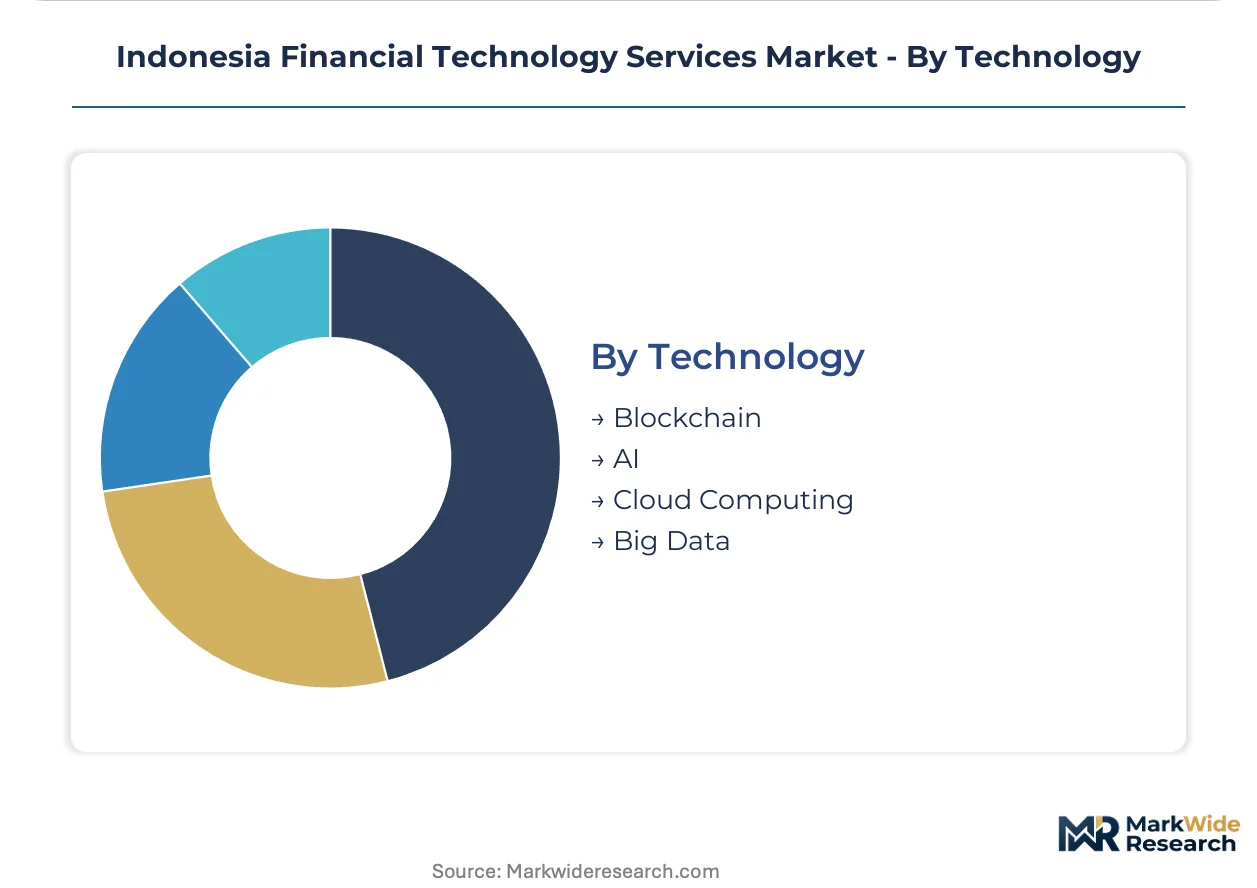
- AI:Machine learning pipelines power real-time fraud detection and dynamic pricing engines, with model training constrained by domestic data residency requirements that prevent cross-border cloud processing.
- Cloud Computing:Domestic server placement mandates under Indonesia's data sovereignty rules elevate capex for entrants, forcing multi-region redundancy strategies that inflate operational overhead relative to regional peers.
- Blockchain:Distributed ledger pilots focus on trade finance and supply chain documentation, with regulatory clarity pending on cryptocurrency adjacent activities that limit mainstream deployment.
- Big Data:Transaction history aggregation enables predictive analytics for customer lifetime value and churn modeling, though consent frameworks under evolving privacy rules complicate cross-platform data fusion.
Cloud Computing underpins the majority of platform infrastructure; AI is gaining share fastest on competitive differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's fintech trade balance tilts toward service imports, with domestic platforms licensing core payment infrastructure from Singapore-based middleware providers while exporting localized credit scoring algorithms to Malaysian and Vietnamese markets.
Jakarta and the Digital Banking Corridor
Jakarta concentrates BI-FAST real-time settlement volume, with merchant density in the capital's commercial districts driving QRIS transaction throughput. Bank Indonesia's electronic money licensing framework mandates capital reserves scaling with deposit-taking authority. The Sudirman-Thamrin corridor hosts super-app headquarters and neobank operations centers competing for cloud engineering talent.
Java's Urban Manufacturing Belt
Surabaya and Bandung anchor SME lending platform expansion, with warung operators in East and West Java provinces replacing informal moneylender networks. OJK's peer-to-peer lending caps constrain interest rate structures for venture-backed platforms. Malang's emerging tech campus supplies backend developers for algorithmic underwriting engines.
Sumatra's Resource-Linked Commerce Zones
Medan and Palembang process palm oil and rubber supply chain financing through embedded finance APIs integrated into commodity trading platforms. Bank Indonesia's data localization rules mandate domestic server placement for transaction records. Batam's free trade zone attracts Singaporean fintechs seeking Indonesian market entry with lighter regulatory friction.
Eastern Indonesia's Archipelago Frontier
Papua and Maluku provinces exhibit underpenetrated mobile money density relative to Java, with agent networks requiring localized KYC workflows for thin-file borrowers. OJK's regulatory sandbox includes pathways for Islamic digital banking products suited to majority-Muslim outer island populations. Sorong's port logistics cluster experiments with telco-tower edge nodes for rural payment terminal authorization.
Kalimantan's Agriculture Supply Chain Hubs
Pontianak and Samarinda integrate crop financing APIs directly into palm oil and mining commodity trading interfaces. The Financial Services Authority's capital requirement framework shapes neobank deposit product rollouts. Balikpapan's energy sector payroll concentration drives demand for B2B treasury management platforms with sub-second settlement latency.
Indonesia Financial Technology Services Market Competitive Landscape
Concentration sits with super-app ecosystems that bundle payment, lending, and commerce verticals under unified user interfaces. The vendor base stratifies into three tiers: licensed infrastructure providers with BI-FAST integration capabilities, unregulated app-layer intermediaries dependent on bank partnerships, and specialized B2B middleware vendors serving regional lenders. Competitive dynamics center on merchant onboarding velocity and API reliability guarantees rather than price competition. Dominant moves include strategic partnerships with state-owned banks for deposit-taking privileges and backward integration into captive logistics networks that control last-mile delivery data streams.
Within the super-app tier, PT GoTo Gojek Tokopedia Tbk and Grab Holdings Limited exemplify platform consolidation strategies that collapse separate financial service relationships into unified ecosystems. PT Fintek Karya Nusantara occupies a position among specialized infrastructure providers focused on B2B treasury APIs for bank partnerships. These three entities represent contrasting archetypes: the commerce-integrated super-app, the logistics-anchored regional platform, and the bank-facing middleware specialist. Their positioning reflects Indonesia's regulatory bifurcation between licensed deposit-takers and payment intermediaries operating under lighter oversight tiers.
| Leading Market Players |
|---|
| PT GoTo Gojek Tokopedia Tbk |
| Grab Holdings Limited |
| PT Espay Debit Indonesia Koe |
| PT Fintek Karya Nusantara |
| ShopeePay |
| PT Ajaib Teknologi Indonesia |
| PT Investree Radhika Jaya |
| Kredivo Holdings |
| PT Akulaku Silvrr Indonesia |
| Others |
Pricing and Supply Chain Analysis
Forty-five-day API integration timelines at regional banks compress vendor selection cycles and concentrate pricing power among middleware providers with pre-certified BI-FAST connectivity. This lead-time pressure elevates contract values for cloud-native infrastructure specialists while squeezing margins for unregulated app-layer intermediaries dependent on bank partnerships.
Pricing Analysis
Corporate treasury buyers anchor SaaS-tiered pricing structures across Indonesian fintech procurement. Three-tier pricing separates premium API reliability tiers with dedicated support from standard self-service packages and economy pay-per-transaction models. Price differentiation stems from certification grade—Bank Indonesia electronic money licensing carries material premiums—and geographic delivery cost for edge-node deployment to outer islands. Pricing pressure stems from consolidation of vendor relationships under group treasury functions, compressing standalone fintech margins. Startups exhibit highest price sensitivity due to limited working capital, while state-owned banks prioritize reliability over cost.
Supply Chain Analysis
Singapore and Malaysia anchor payment middleware production for Indonesian market entry. Domestic cloud infrastructure draws from state-owned telco tower networks and private data center operators in Jakarta and Surabaya. Raw material dependencies center on NVIDIA GPU clusters for AI underwriting engines, submarine cable bandwidth for cross-border settlement, and domestic server hardware for data localization compliance. Single-source vulnerability concentrates in Singapore-based core banking software licensors. Distribution runs through direct enterprise sales teams for corporate mandates and agent networks for micro-merchant onboarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory sandbox fragmentation across OJK and Bank Indonesia jurisdictions creates niche entry points for specialized compliance providers. Micro-merchant credit demand in Eastern Indonesia remains underserved by incumbent super-app coverage.
For Market Incumbents: Shield deposit-taking privileges through accelerated BI-FAST certification investments at regional bank partners. Consolidate API reliability guarantees with backward integration into captive data center infrastructure across Java. The threat of OJK liquidity coverage tightening demands treasury capabilities matching conventional institutions. For New Entrants and Emerging Players: OJK's Sharia-compliant sandbox fast-track opens white-space in mudarabah-based investment platforms for majority-Muslim outer island populations. Target Papua and Maluku provinces with localized KYC workflows and telco-tower edge partnerships. Go-to-market leverage rests with agriculture supply chain embeds in Kalimantan commodity trading interfaces. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital banking as liquidity coverage requirements scale with deposit growth velocity. Long-term viability favors acquisition targets with existing OJK operating licenses rather than sandbox-stage entrants. The signal to watch is wholesale funding line secured versus venture runway remaining.| Strategic Initiative | Industry Significance |
|---|---|
| BI-FAST Certification Investment | Pre-certified middleware providers capture regional bank procurement cycles ahead of competitors. |
| Sharia-Compliant Product Launch | OJK sandbox pathways enable first-mover positioning in underserved Islamic finance segments. |
| Edge Computing Node Deployment | Telco-tower partnerships compress rural authorization latency for Nusa Tenggara micro-merchants. |
| Data Center Backward Integration | Domestic server placement satisfies Bank Indonesia residency mandates while reducing third-party dependency. |
| Agriculture Supply Chain Embed | Kalimantan commodity trading APIs collapse traditional bank-merchant-borrower distance for crop financing. |
Research Methodology
A standing panel of neobank CTOs, OJK regulatory affairs leads, regional bank procurement managers, and cloud infrastructure engineers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from Bank Indonesia payment system reports, OJK sandbox disclosures, BI-FAST integration documentation, and SEC filings of listed fintech entities. Bottom-up transaction volume modeling and top-down regulatory framework analysis triangulated market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, customer archetype, application layer, and technology stack choice. CAGRs derived from algorithmic adoption curves for mobile payments and regulatory velocity for digital banking licensing. Forecast inputs incorporated BI-FAST penetration rates and OJK capital requirement phase-ins without year-specific assumptions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and BI-FAST adoption trajectories; material deviation in sandbox approval timelines or data localization interpretation would warrant model refresh. Specific risks include OJK interest rate cap adjustments and cloud engineering talent scarcity accelerating cost structures. Recalibration cycles align with material shifts in regulatory framework updates and infrastructure investment patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Robotic Process Automation (RPA) in Financial Services Market
FinTech
Asia-Pacific Financial Analytics Market
FinTech
Intelligent Cash Deposit Machine Market
FinTech
Financial Services Cloud Market
FinTech
India AI in Fintech Market
FinTech
Autonomous Finance Market
FinTech
Africa AI in Fintech Market
FinTech
Smart Finance Technologies Market
FinTech
Stock Trading App Market
FinTech
IoT for Finance Market
FinTech
Europe Fintech Cloud Market
FinTech
Fintech-As-A-Service Market
FinTech
Malaysia Fintech Market
FinTech
United Kingdom Fintech Market
FinTech
IT Financial Management Tools Market
FinTech
Global Fin Tech Blockchain Market