
 Europe Fintech Market | 2026-2036
Europe Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fintech Market Analysis
SME banking is reorganizing Europe's fintech demand profile as traditional corporate treasury services lose relative share. Adyen N.V. dominates enterprise payment orchestration across multiple European jurisdictions. Klarna Bank AB anchors buy-now-pay-later distribution through deep retail integrations. Revolut Ltd leverages super-app architecture to sustain cross-border consumer acquisition at scale.
Europe fintech encompasses digitally native financial services infrastructure spanning payment processing, alternative lending, insurtech, wealth management, and embedded finance, typically delivered through API-first platforms or mobile-native interfaces with sub-second transaction latency and multi-currency settlement capabilities. The Payments segment leads absolute revenue generation due to persistent card-to-digital migration among merchants and consumers. Robo-Advisors within the Technology dimension represent the fastest-growing structural pocket as fee compression drives automated wealth allocation. Cloud-Based deployment captures dominant share among neobanks seeking elastic infrastructure economics.
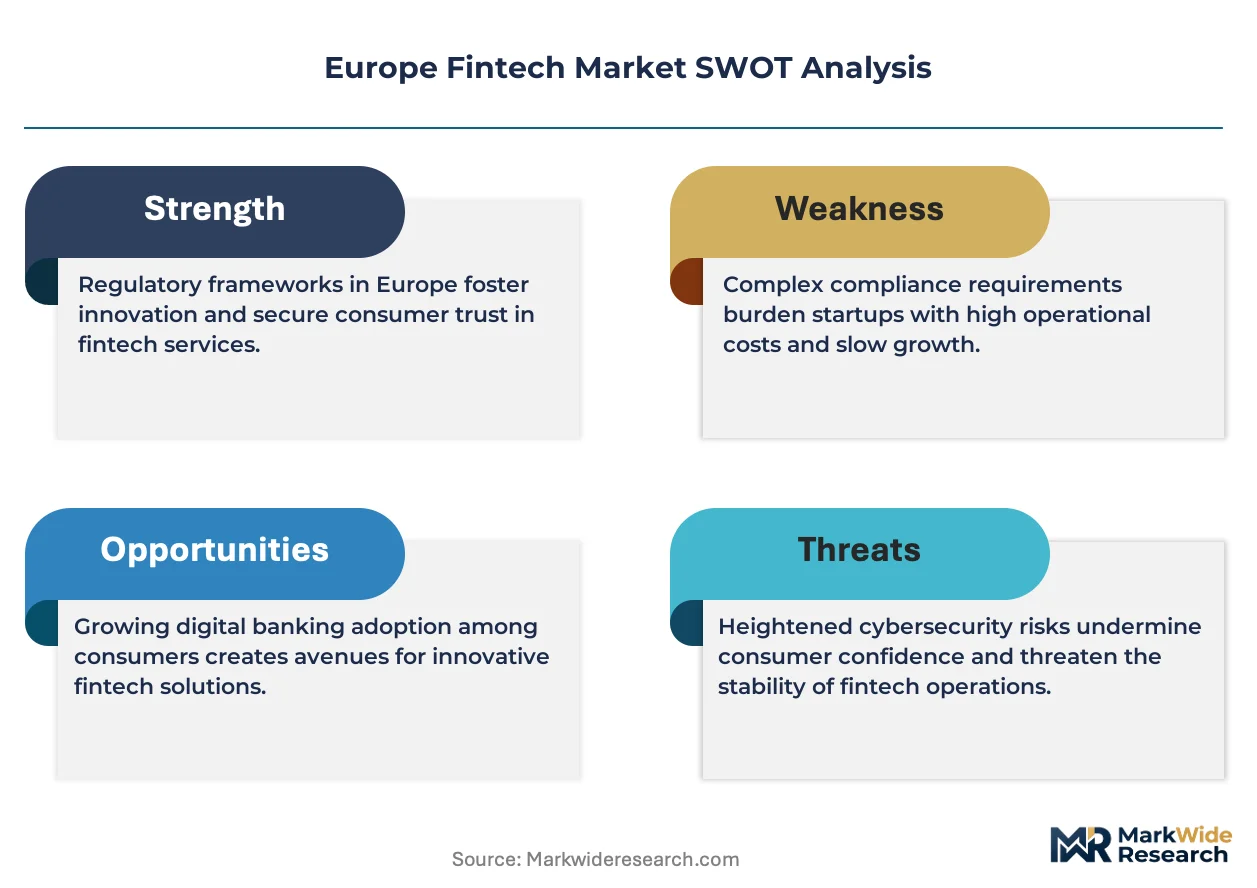
PSD3, the EU AI Act, and GDPR collectively impose algorithmic transparency, data sovereignty, and open-banking interoperability mandates that elevate compliance costs while creating licensed-access moats for compliant operators. EBA stress-testing frameworks and national regulators including the UK's FCA further segment market entry by capital adequacy thresholds. Stakeholders must monitor regulatory divergence between EU-wide directives and member-state implementations as the decisive variable for cross-border platform economics.
Market Dynamics
PSD3 and the EU AI Act are forcing European fintechs to rebuild compliance architectures from the ground up, diverting engineering resources from product velocity toward regulatory certification. This regulatory compression is redistributing competitive advantage toward well-capitalized incumbents who can absorb multi-year licensing timelines.
Growth Catalysts
- PSD3 Open Banking Mandates:The revised directive compels tier-one banks to expose payment initiation and account information APIs, creating standardized entry points for third-party fintech orchestration.
- Cloud-Native Core Banking:Elastic infrastructure economics allow neobanks to operate at one-tenth the cost base of legacy operators, unlocking sustainable unit economics in mass-market segments.
- SME Treasury Automation:Small business demand for integrated cash management, invoicing, and foreign exchange hedging is pulling specialized fintech platforms into corporate banking adjacencies.
Market Restraints
- GDPR Data Sovereignty:Strict localization requirements for personal financial data prevent seamless cross-border cloud deployments, fragmenting infrastructure strategies across member states.
- Algorithmic Audit Costs:The EU AI Act's high-risk system classification imposes mandatory conformity assessments on credit scoring and fraud detection models, elevating fixed compliance overhead.
- Banking License Capital Requirements:EBA stress-testing frameworks and national regulator mandates for deposit-taking institutions create capital adequacy thresholds that exclude sub-scale entrants.
Strategic Opportunities
- Embedded Finance in Retail:Non-financial platforms in Germany and France are white-labeling banking services through API integrations, expanding distribution without customer acquisition costs.
- Climate Risk Data Layer:CSRD disclosure requirements are generating demand for carbon accounting and sustainability-linked treasury products that fintechs can productize faster than incumbents.
- Cross-Border SME Lending:Underpenetrated corridors between Eastern European manufacturing hubs and Western European buyers present origination opportunities for trade finance specialists.
Industry Challenges
- Legacy Core Integration:Fintechs partnering with established banks face multi-year system migration timelines to connect with decades-old mainframe infrastructure.
- Regulatory Divergence:Member-state implementations of EU directives vary in supervisory intensity, forcing platform operators to maintain jurisdiction-specific compliance playbooks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fintech Market |
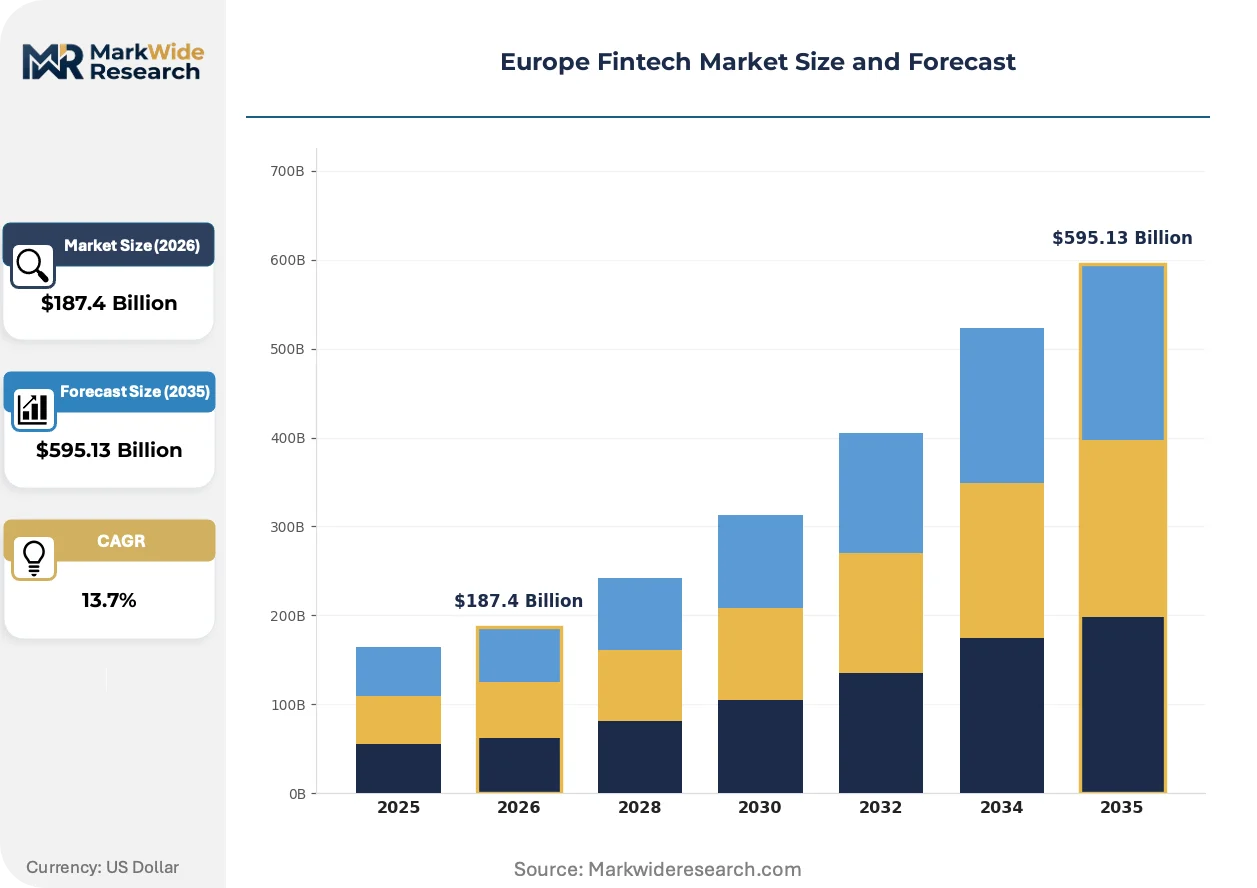
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $595.13 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payments, Lending, Insurance, Investment Customer Type: Individuals, Small Businesses, Enterprises, Corporates Technology: Blockchain, Mobile Payments, Robo-Advisors, Crowdfunding Deployment: Cloud-Based, On-Premises, Hybrid, Embedded |
| Companies Covered | Adyen N.V., Klarna Bank AB, Revolut Ltd, Checkout.com Group, Wise plc, Stripe Inc., N26 GmbH, Starling Bank Ltd, OakNorth Bank plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fintech Market Emerging Trajectories
Artificial intelligence deployment is bifurcating European fintech between algorithmic personalization engines and regulatory compliance automation, with capital allocation increasingly favoring the latter. This shift is compressing product development cycles while extending time-to-market for customer-facing innovations.
Generative AI for customer service and credit decisioning is bifurcating platform economics. Neobanks with sufficient training data are deploying conversational interfaces at scale, compressing support cost structures. Smaller operators lacking proprietary datasets face widening capability gaps, forcing reliance on third-party model providers with opaque audit trails.
The EU AI Act's high-risk system classification is reshaping product roadmaps for credit scoring and fraud detection platforms. Fintechs must now document algorithmic explainability and human oversight protocols before deployment. British operators face parallel FCA algorithmic accountability consultations, creating dual-track compliance obligations for UK-EU dual licensees.
Merchant acquisition through embedded finance partnerships is displacing direct-to-consumer marketing for payment orchestration platforms. Retailers in France and Germany now expect checkout solutions bundled with working capital advances and foreign exchange hedging. This unbundling of traditional banking relationships is most visible in mid-market e-commerce verticals where treasury complexity exceeds in-house capabilities.
Europe Fintech Market Segmentation
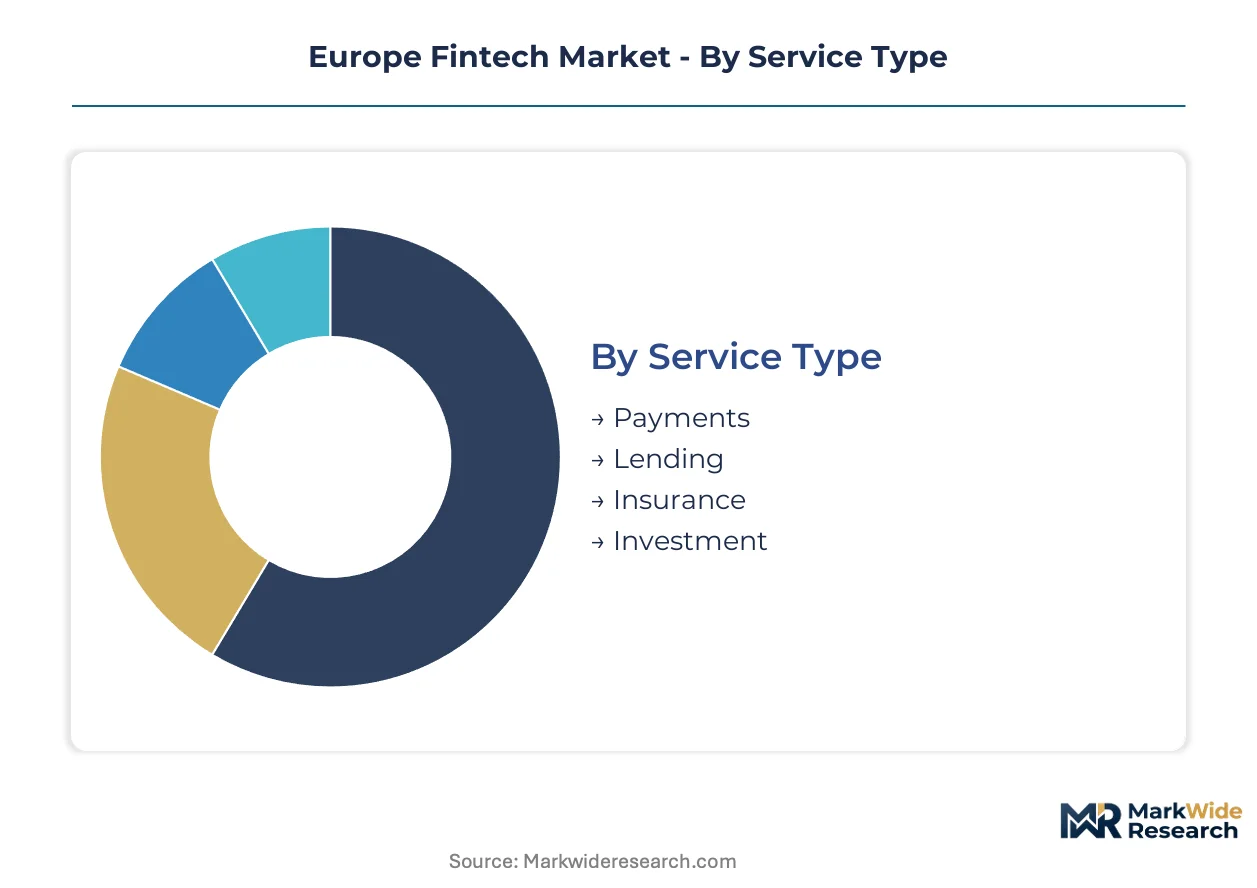
Segmentation in European fintech reveals how regulatory fragmentation and cross-border commerce create divergent demand profiles. Understanding these splits helps operators allocate engineering resources toward compliant, high-velocity corridors.
Service Type:
Payments and Lending services dominate cross-border flows between Germany, France, and the United Kingdom, while Insurance and Investment products cluster in domestic retail markets.
- Payments:Real-time payment initiation and multi-currency settlement infrastructure delivered through API-first platforms. Merchant demand concentrates in German and French retail corridors where card-to-digital migration accelerates checkout modernization.
- Lending:Alternative credit origination spanning consumer installment, SME working capital, and trade finance. Cross-border origination between Eastern European manufacturing hubs and Western European buyers drives specialized platform development.
- Insurance:Parametric and usage-based coverage products embedded in digital distribution channels. Domestic regulatory complexity limits passporting, keeping most insurtech activity within national boundaries.
- Investment:Fractional securities access and automated portfolio allocation tools. Retail participation clusters in London, Amsterdam, and Frankfurt where MiFID II compliance frameworks are established.
Payments holds the largest share; momentum sits with Lending as SME treasury automation accelerates.
Customer Type:
Small Businesses and Individuals represent volume-heavy domestic segments, while Enterprises and Corporates drive export-oriented platform economics through cross-border treasury complexity.
- Individuals:Consumer-facing neobanks and personal finance management tools delivered through mobile-native interfaces. Demand concentrates in urban UK and German markets where super-app bundling reduces customer acquisition costs.
- Small Businesses:Integrated cash management, invoicing, and foreign exchange hedging for sub-enterprise operators. French and German mid-market e-commerce verticals pull specialized fintech platforms into corporate banking adjacencies.
- Enterprises:Payment orchestration and treasury automation for multi-jurisdiction operators. GDPR data sovereignty requirements fragment infrastructure strategies across member states.
- Corporates:Capital markets access and sophisticated risk management for large balance-sheet entities. EBA stress-testing frameworks create capital adequacy thresholds that favor established platform providers.
Small Businesses command the largest addressable base; Individuals are expanding most quickly as neobank penetration deepens.
Technology:
Mobile Payments and Robo-Advisors scale through consumer distribution, while Blockchain and Crowdfunding face regulatory headwinds that constrain cross-border deployment.
- Blockchain:Distributed ledger infrastructure for settlement finality and programmable compliance. MiCA implementation timelines create licensing uncertainty that fragments development roadmaps across EU member states.
- Mobile Payments:NFC-enabled proximity transactions and QR-code based remote settlement. German and French retail integration drives merchant acquisition through embedded checkout solutions.
- Robo-Advisors:Algorithmic portfolio construction with automated rebalancing and tax-loss harvesting. Fee compression in wealth management accelerates automated allocation adoption in UK and Dutch markets.
- Crowdfunding:Securities-based and donation-based capital formation platforms. National prospectus exemptions limit cross-border investor participation, keeping origination domestic.
Mobile Payments captures dominant volume; Robo-Advisors are gaining share fastest as automated wealth allocation penetrates mass-affluent segments.
Deployment:
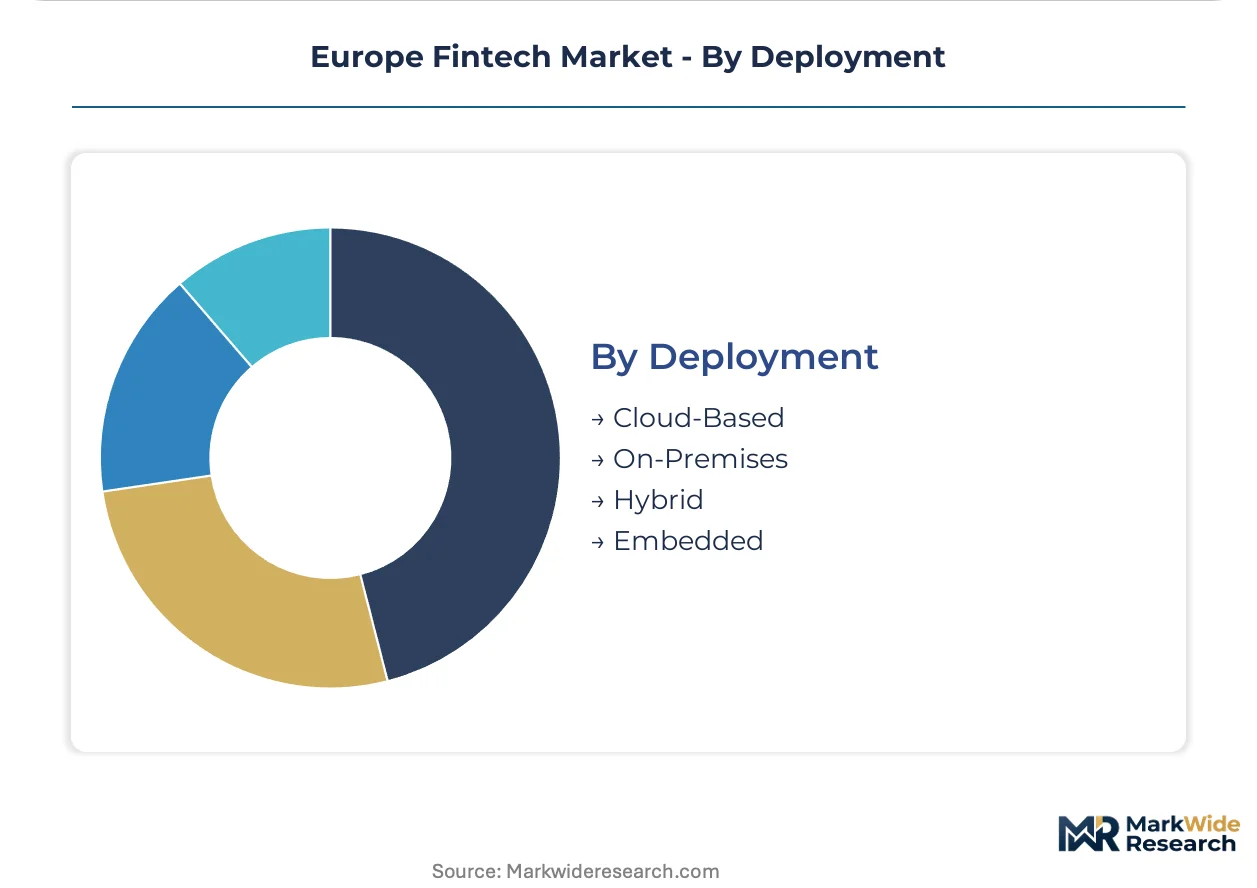
Cloud-Based and Hybrid architectures support multi-jurisdiction scaling, while On-Premises and Embedded models respond to data sovereignty and vertical integration imperatives.
- Cloud-Based:Elastic infrastructure with API-first service delivery and sub-second transaction latency. Neobanks leverage this model to operate at fractional cost bases compared to legacy operators.
- On-Premises:Dedicated hardware deployments for institutions with strict data residency mandates. GDPR localization requirements in France and Germany sustain demand despite higher capital intensity.
- Hybrid:Workload-specific allocation between private infrastructure and public cloud resources. Banks undergoing multi-year mainframe migrations adopt this architecture to manage transition risk.
- Embedded:White-labeled financial services integrated into non-financial platforms. Retailers in Germany and France now expect checkout solutions bundled with working capital advances.
Cloud-Based holds the largest share; Embedded is climbing the fastest as non-financial platforms seek banking service differentiation without license acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform headquarters and engineering talent concentrate in London, Amsterdam, and Berlin, creating a three-node infrastructure corridor that processes the majority of European fintech transaction volume. This geographic clustering reflects regulatory arbitrage opportunities, capital access depth, and proximity to legacy banking infrastructure requiring API integration.
United Kingdom
Open banking API penetration and super-app bundling drive consumer acquisition in London and Manchester. The Financial Conduct Authority's algorithmic accountability consultations impose dual-track compliance obligations for operators holding both UK and EU licenses. The Square Mile anchors enterprise payment orchestration platforms serving cross-border e-commerce merchants.
Germany
SME treasury automation and embedded checkout solutions pull specialized platforms into corporate banking adjacencies in Frankfurt and Berlin. BaFin's implementation of PSD3 mandates creates standardized entry points for third-party payment initiation services. The Bavarian manufacturing corridor generates demand for trade finance origination between Eastern suppliers and Western buyers.
France
Retail embedded finance partnerships and climate risk data productization accelerate platform development in Paris and Lyon. The CNIL enforces GDPR data sovereignty requirements that fragment cloud deployment strategies across member states. Île-de-France hosts insurtech clusters focused on parametric coverage distribution through digital channels.
Netherlands
Payment orchestration infrastructure and multi-currency settlement capabilities concentrate in Amsterdam's financial district. DNB supervision of e-money institutions creates licensing moats that favor well-capitalized operators. The Randstad region attracts engineering talent for API-first platform development serving German and French retail corridors.
Sweden
Buy-now-pay-later distribution and mobile-native banking interfaces drive consumer platform adoption in Stockholm. Finansinspektionen's stress-testing frameworks align with EBA capital adequacy thresholds for deposit-taking institutions. The Stockholm fintech cluster specializes in retail credit origination technology exported to continental markets.
Europe Fintech Market Vendor Landscape
Concentration sits with payment orchestration specialists and neobank operators who have secured multi-jurisdiction banking licenses. The vendor base stratifies across three tiers: enterprise-grade infrastructure providers serving multinational merchants, consumer-facing super-apps acquiring users through cross-border remittance and foreign exchange services, and vertical specialists embedding treasury automation into SME software stacks. Competitive moves center on strategic partnerships with non-financial platforms seeking white-labeled banking differentiation, and geographic expansion through passporting mechanisms under EU regulatory frameworks.
Among Amsterdam-listed infrastructure providers, Adyen N.V. anchors enterprise payment processing across multiple European jurisdictions. Klarna Bank AB occupies a position within the retail credit origination tier, exemplifying buy-now-pay-later distribution through deep merchant integrations. Revolut Ltd sits within the consumer super-app archetype, leveraging multi-product bundling to sustain cross-border user acquisition at scale.
| Leading Market Players |
|---|
| Adyen N.V. |
| Klarna Bank AB |
| Revolut Ltd |
| Checkout.com Group |
| Wise plc |
| Stripe Inc. |
| N26 GmbH |
| Starling Bank Ltd |
| OakNorth Bank plc |
| Others |
Supply Flow & Price Mechanics
EU AI Act high-risk system classification gates both supplier qualification and price differentiation simultaneously, elevating compliance certification to a tiering mechanism that separates premium orchestration platforms from commodity payment processors. This regulatory architecture compresses margins for sub-scale operators while licensing moats protect pricing power for compliant incumbents serving cross-border enterprise merchants.
Pricing Analysis
EU AI Act dictates the pricing tier structure across European fintech, segmenting platforms by algorithmic audit depth and human oversight protocols. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with premium tiers commanding spreads for documented explainability and GDPR-aligned data sovereignty. Cost compression in standard tiers is intensifying because neobanks compete on transactional unit economics. Small businesses exhibit highest price sensitivity, while multinational corporates prioritize compliance bundling over per-transaction rates.
Supply Chain Analysis
Ireland and the Netherlands anchor cloud infrastructure provisioning for European fintech, hosting hyperscale data centers that feed elastic compute into API-first platforms. Engineering talent pipelines draw from Estonia, Poland, and Portugal, creating distributed development capacity that rests on specialized fintech recruitment networks. Single-source vulnerability concentrates in payment scheme access controlled by Visa and Mastercard. Distribution runs through embedded finance partnerships with German and French retail platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent fintech operators face substitution pressure from big tech platforms embedding financial services into commerce ecosystems, requiring defensive repositioning around regulatory licensing and specialized treasury capabilities.
For Market Incumbents: Consolidate payment orchestration capabilities through API standardization that locks enterprise merchants into multi-year contracts. Deepen vertical integration into proprietary fraud detection models to escape third-party algorithmic audit dependencies. The threat of Amazon and Apple expanding checkout financing demands licensing moats as the primary defensive lever.
For New Entrants and Emerging Players: SME treasury automation in Eastern European manufacturing corridors offers white-space expansion where incumbent coverage remains thin. Cross-border trade finance origination between Polish suppliers and German buyers presents the most penetrable segment. A go-to-market angle anchored in CSRD-aligned carbon accounting tools differentiates against generic working capital providers.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy banks spinning off payment infrastructure units under PSD3 pressure. Long-term viability hinges on multi-jurisdiction licensing depth rather than user growth velocity. The signal to watch is BaFin and FCA convergence on algorithmic accountability timelines, which will accelerate consolidation among dual-track compliance operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Licensing Acquisition | PSD3 and EU AI Act compliance creates defensible moats against unlicensed competitors. |
| Embedded Finance Partnership Expansion | German and French retail platforms demand bundled checkout and working capital solutions. |
| Cloud-Native Core Banking Migration | Elastic infrastructure economics enable neobanks to operate at fractional legacy cost bases. |
| Algorithmic Explainability Investment | EU AI Act mandates documentation protocols before high-risk credit scoring deployment. |
| SME Treasury Automation Buildout | French mid-market e-commerce verticals pull specialized platforms into corporate adjacencies. |
Methodological Framework
Operator-level perspectives from neobank CTOs, payment platform compliance officers, SME treasury managers, and BaFin supervisory staff anchored the qualitative base. Primary interviews combined with secondary validation from ECB statistical releases, EBA stress-testing frameworks, national regulator consultation papers, and hyperscaler infrastructure capex disclosures. Bottom-up transaction volume modeling and top-down GDP-correlation approaches triangulated market sizing across the analysis window.
Sensitivity analysis framed the projection methodology, testing alternative regulatory implementation timelines and cloud migration velocity assumptions. Segmentation dimensions modeled include service type, customer archetype, technology deployment, and national regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for PSD3 and EU AI Act compliance cost absorption. Forecast inputs incorporated open banking API penetration rates and SME digital treasury adoption curves.
Material uncertainties — regulatory divergence between member-state implementations, algorithmic audit cost inflation, and hyperscaler pricing power — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance timeline adherence and capital adequacy threshold stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Robotic Process Automation (RPA) in Financial Services Market
FinTech
Singapore AI in Fintech Market
FinTech
Canada AI in Fintech Market
FinTech
Europe Embedded Finance Market
FinTech
Financial Forecasting Software Market
FinTech
Smart Financial Solutions Market
FinTech
AI Finance Market
FinTech
Europe Financial Analytics Market
FinTech
Lendtech Market
FinTech
IT Financial Management Tools Market
FinTech
Financial Consolidation Software Market
FinTech
Germany Fintech Market
FinTech
Autonomous Finance Market
FinTech
Robo-Advisory Services Market
FinTech
Multichannel Digital Banking Integration Software Market
FinTech
Robo-Advisory Software Market