
 Lithium Ion Capacitor Market | 2026-2036
Lithium Ion Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Ion Capacitor Market Analysis
Modular energy storage packaging is rebalancing procurement patterns across industrial buyers. TAIYO YUDEN leverages its ceramic capacitor heritage to anchor high-reliability LIC modules for automotive voltage stabilization. VINATech Co., Ltd. competes through vertical control over activated carbon electrode production in South Korea. Murata Manufacturing Co., Ltd. differentiates via surface-mountable form factors that slot directly into existing PCB layouts for consumer electronics OEMs.
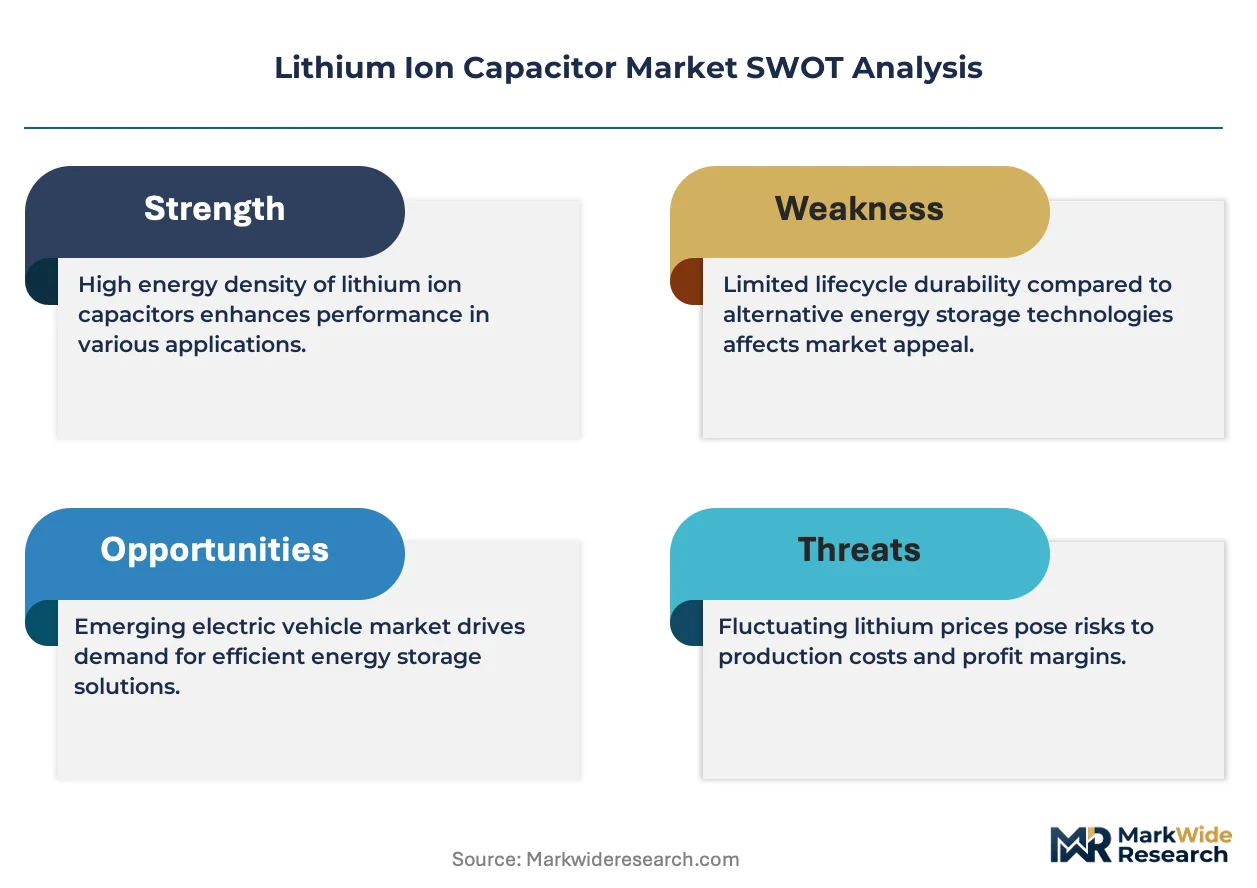
A lithium ion capacitor combines a battery-type negative electrode with an electric double-layer capacitor-type positive electrode, achieving energy densities of 10–30 Wh/kg while retaining power densities exceeding 10 kW/kg and cycle lives beyond 100,000 charge/discharge events. This hybrid architecture serves applications requiring rapid charge acceptance alongside moderate energy retention, bridging the performance gap between batteries and conventional supercapacitors. Hybrid capacitors lead volume shipments due to their balanced power-energy profile, though graphene-based configurations represent the fastest-growing technology segment as manufacturers refine cost-effective synthesis routes. Automotive applications command the deepest margin pools because OEMs specify extended temperature ranges and vibration tolerance that justify premium pricing over consumer-grade alternatives.
Japan's METI enacts battery safety benchmarks under the Electrical Appliance and Material Safety Act that govern LIC thermal runaway protocols, while China's SAMR administers GB standards for energy storage system integration. The EU's REACH and RoHS frameworks restrict hazardous substances in electrode materials, compelling reformulation of electrolyte salts and current collector coatings. Stakeholders must monitor how evolving carbon footprint disclosure rules under the EU Green Deal reshape supplier qualification timelines and raw material sourcing requirements.
Market Dynamics
Japan's METI safety protocols and China's GB certification standards are forcing electrode material reformulation across the lithium ion capacitor supply base, compressing supplier qualification timelines and elevating compliance costs for cross-border shipments.
Growth Catalysts
- Automotive voltage stabilization demand:Hybrid electric vehicle manufacturers in Japan specify LIC modules for regenerative braking energy capture, creating sustained procurement volumes with multi-year contracts.
- REACH substance restrictions:ECHA's evolving candidate list for hazardous substances is accelerating electrolyte salt substitution toward fluorine-free formulations that retain ionic conductivity.
- Activated carbon electrode localization:South Korean producers have achieved captive supply of high-surface-area carbon precursors, reducing import dependency and shortening lead times for domestic module assembly.
Market Restraints
- Lithium carbonate price volatility:Battery-grade lithium compound fluctuations transmit directly into negative electrode cost structures, compressing margins for producers without long-term offtake agreements.
- Electrolyte salt supply concentration:Fluorinated electrolyte production concentrates among Japanese and Chinese chemical specialists, creating single-source vulnerability for European and North American LIC assemblers.
- Energy density ceiling:The 30 Wh/kg practical limit for hybrid capacitors constrains penetration into electric vehicle traction applications where lithium-ion batteries dominate.
Strategic Opportunities
- Grid-scale frequency regulation:Utility-scale energy storage procurement in Germany and the Netherlands is opening to rapid-response LIC systems for primary frequency control services.
- EU Green Deal carbon disclosure:The CSRD's Scope 3 reporting requirements favor suppliers with verified low-carbon electrode material sourcing, creating qualification advantages for early adopters.
- Medical device power backup:Portable diagnostic equipment manufacturers are specifying surface-mount LICs for mission-critical memory retention during battery swap operations.
Industry Challenges
- Cell balancing engineering shortage:The specialized electrochemical expertise required for series-connected LIC module design remains concentrated among Japanese and Korean engineering teams, constraining European and North American production scale-up.
- Multi-standard certification overlap:Simultaneous compliance with Japan's Electrical Appliance and Material Safety Act, China's GB standards, and EU REACH creates redundant testing cycles that extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Ion Capacitor Market |
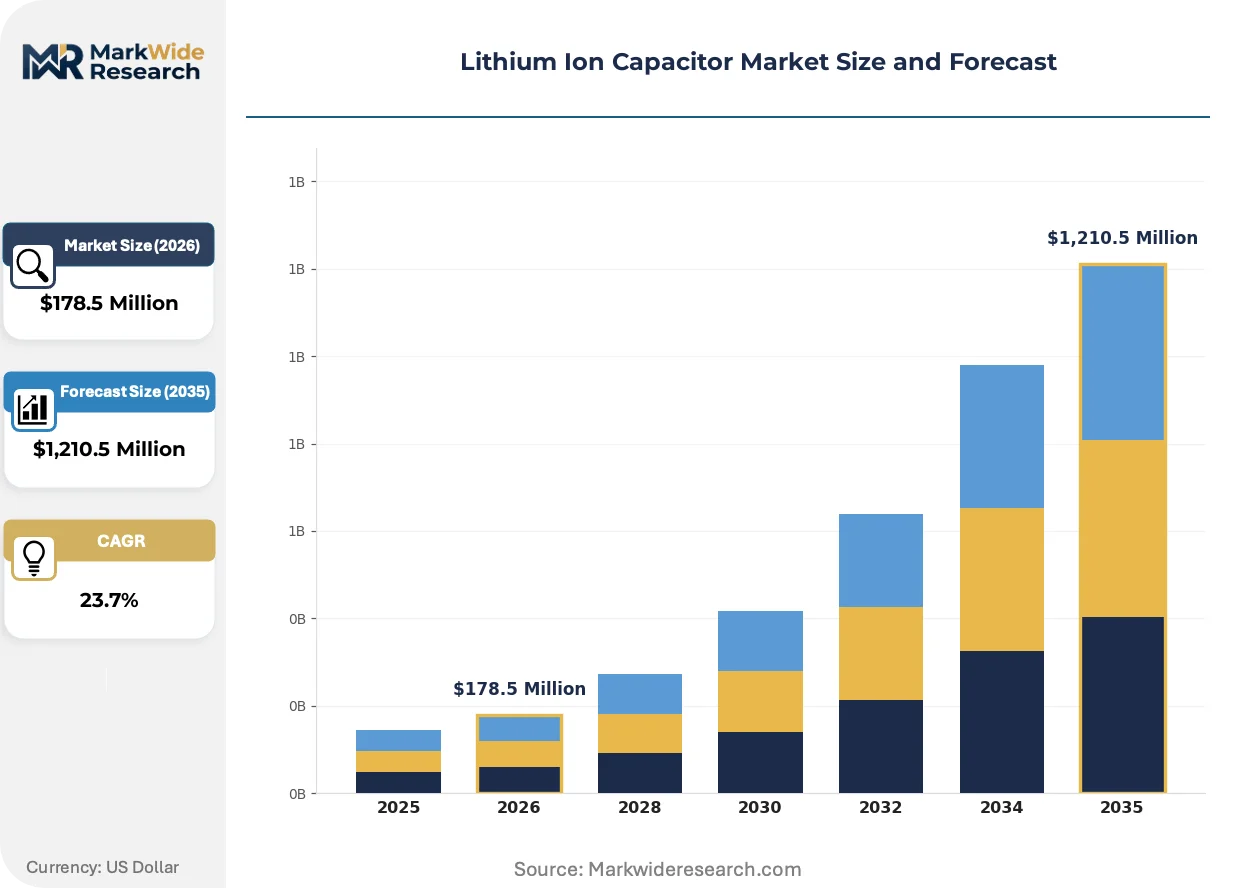
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $1,210.5 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Capacitors, Supercapacitors, Energy Storage Devices, Power Backup Systems End User: Consumer Electronics, Automotive Applications, Renewable Energy Systems, Industrial Equipment Installation: Embedded Systems, Standalone Units, On-board Energy Storage, Portable Applications Technology: Conductive Polymer, Carbon Nanotubes, Metal Oxide, Graphene |
| Companies Covered | LICAP Technologies, Inc., TAIYO YUDEN, JSR Micro NV, Electro Standards Laboratories, VINATech Co., Ltd., Spel Technologies Pvt. Ltd., Murata Manufacturing Co., Ltd., Socomec Group, Yunasko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Ion Capacitor Market Emerging Trajectories
Electrode architecture refinement and regulatory disclosure mandates are compressing product development cycles while opening new application categories for hybrid energy storage systems.
Graphene-enhanced activated carbon electrodes are converging with conventional LIC manufacturing lines as Korean materials suppliers achieve cost parity through chemical vapor deposition process optimization. Industrial uninterruptible power supply manufacturers are qualifying these electrodes for 15-year service life specifications. The technology is converging with existing carbon production infrastructure, avoiding the capital intensity of standalone graphene synthesis facilities.
China's SAMR has tightened GB/T 36276 certification requirements for energy storage system safety testing, mandating thermal runaway propagation resistance for all grid-connected installations. Module producers must now submit third-party test reports covering nail penetration and overcharge abuse scenarios. This regulatory shift most affects export-oriented Chinese manufacturers supplying European utility projects, forcing parallel certification track investments.
Buyers are consolidating vendor relationships around suppliers offering integrated cell-to-system engineering support rather than discrete component transactions. Automotive OEMs now require LIC suppliers to co-develop thermal management interfaces and battery management system communication protocols. This pattern is most pronounced in Japan, where Tier 1 suppliers are absorbing module design responsibility previously held by vehicle manufacturers.
Lithium Ion Capacitor Market Segmentation
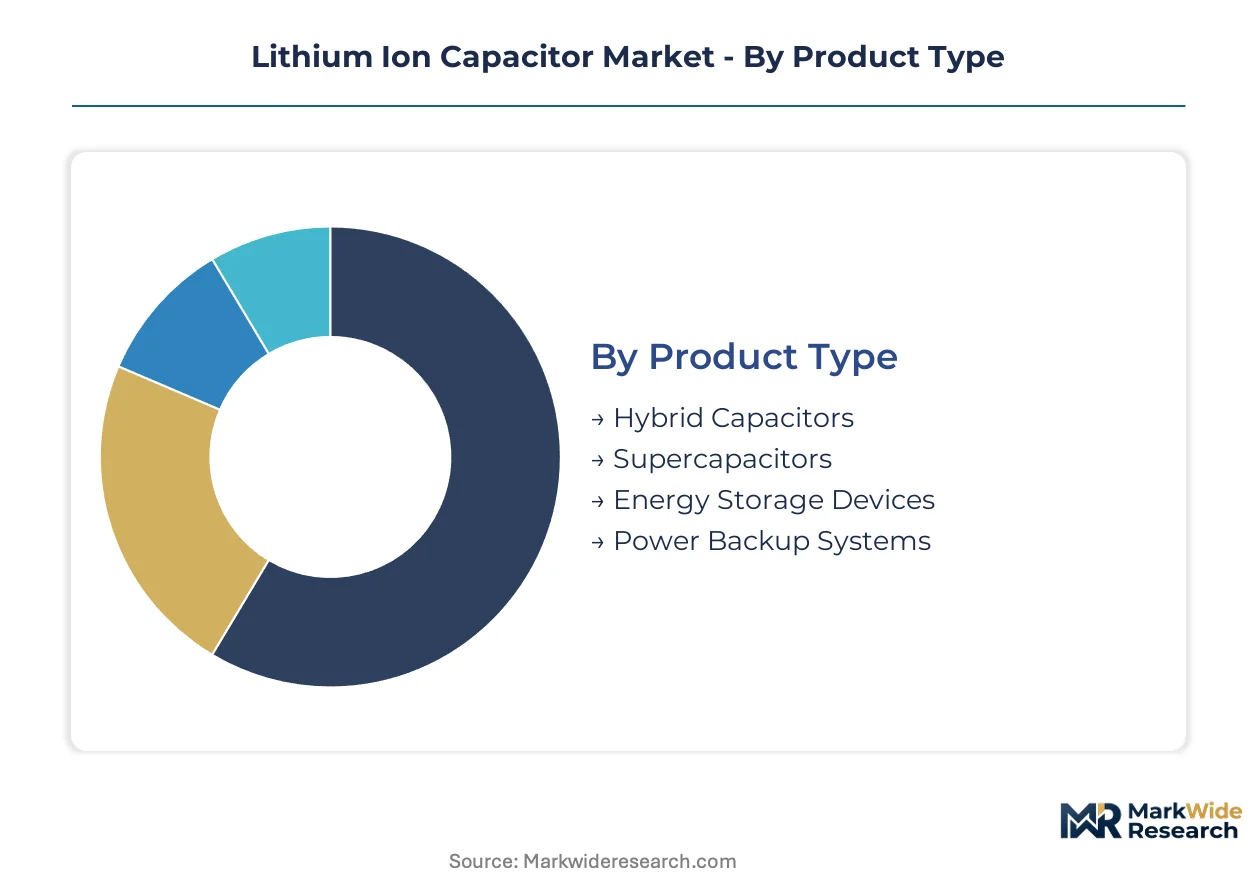
Segmentation in the lithium ion capacitor market reveals distinct capital allocation patterns across manufacturing technologies and installation architectures. Procurement decisions diverge sharply between automotive OEMs demanding module-level integration and industrial buyers prioritizing standalone energy density specifications.
Product Type:
Capital intensity varies dramatically across product architectures, with hybrid capacitor manufacturing requiring electrode material synthesis lines that consume 60-70% of facility investment versus assembly equipment.
- Hybrid Capacitors:These devices pair battery-type negative electrodes with electric double-layer positive electrodes, achieving 10-30 Wh/kg energy density while retaining supercapacitor-grade power density. Japanese automotive manufacturers specify hybrid modules for regenerative braking systems, where rapid charge acceptance and million-cycle durability justify premium procurement contracts.
- Supercapacitors:Pure electric double-layer configurations deliver power densities exceeding 15 kW/kg but sacrifice energy density to 5-8 Wh/kg. Korean industrial electronics clusters around Seoul deploy these for automated manufacturing line voltage stabilization, where millisecond response times matter more than total energy storage.
- Energy Storage Devices:Grid-scale installations favor these larger-format units for frequency regulation services in German and Dutch utility markets.
- Power Backup Systems:Medical equipment and telecommunications infrastructure specify these for mission-critical continuity during primary power interruptions.
Hybrid capacitors absorb the bulk of installed capacity; graphene-enhanced configurations are expanding most quickly as Korean suppliers achieve cost parity in electrode production.
End User:
Customer type determines pricing tolerance and certification burden, with automotive applications commanding 40-60% price premiums over consumer-grade alternatives due to extended temperature range and vibration tolerance requirements.
- Consumer Electronics:Smartphone and wearable manufacturers specify surface-mount LICs for memory retention and graceful shutdown functions. Murata Manufacturing dominates this segment through PCB-compatible form factors that slot directly into existing layouts without redesign.
- Automotive Applications:Hybrid electric vehicle producers in Japan integrate LIC modules for start-stop systems and kinetic energy recovery. METI safety protocols under the Electrical Appliance and Material Safety Act govern thermal runaway containment, forcing dedicated production lines with enhanced quality systems.
- Renewable Energy Systems:Solar and wind installations pair these with lithium-ion batteries to smooth power output fluctuations and extend battery cycle life.
- Industrial Equipment:Automated manufacturing lines specify these for crane regenerative braking and robotic actuator power buffering.
Automotive applications command the deepest margin pools; consumer electronics shipments generate the highest unit volumes with compressed pricing.
Installation:
Physical integration architecture shapes thermal management requirements and supplier qualification complexity, with embedded systems demanding co-development partnerships that standalone units avoid.
- Embedded Systems:These units integrate directly into host device electronics, requiring custom thermal interface design and battery management system protocol compatibility. Tier 1 automotive suppliers in Japan have absorbed module design responsibility previously held by vehicle manufacturers, consolidating vendor relationships around engineering-capable partners.
- Standalone Units:Self-contained enclosures with independent cooling and control systems serve grid-scale frequency regulation and industrial UPS applications. Dutch utility procurement specifications favor these for primary frequency control services requiring 15-year service life guarantees.
- On-board Energy Storage:Rail and marine applications specify these for traction power assistance and station-to-station energy management.
- Portable Applications:Medical diagnostic equipment and field instrumentation favor these for battery swap continuity and lightweight power buffering.
Embedded systems concentrate engineering value capture; standalone units are climbing the fastest as European utility procurement opens to rapid-response LIC technology.
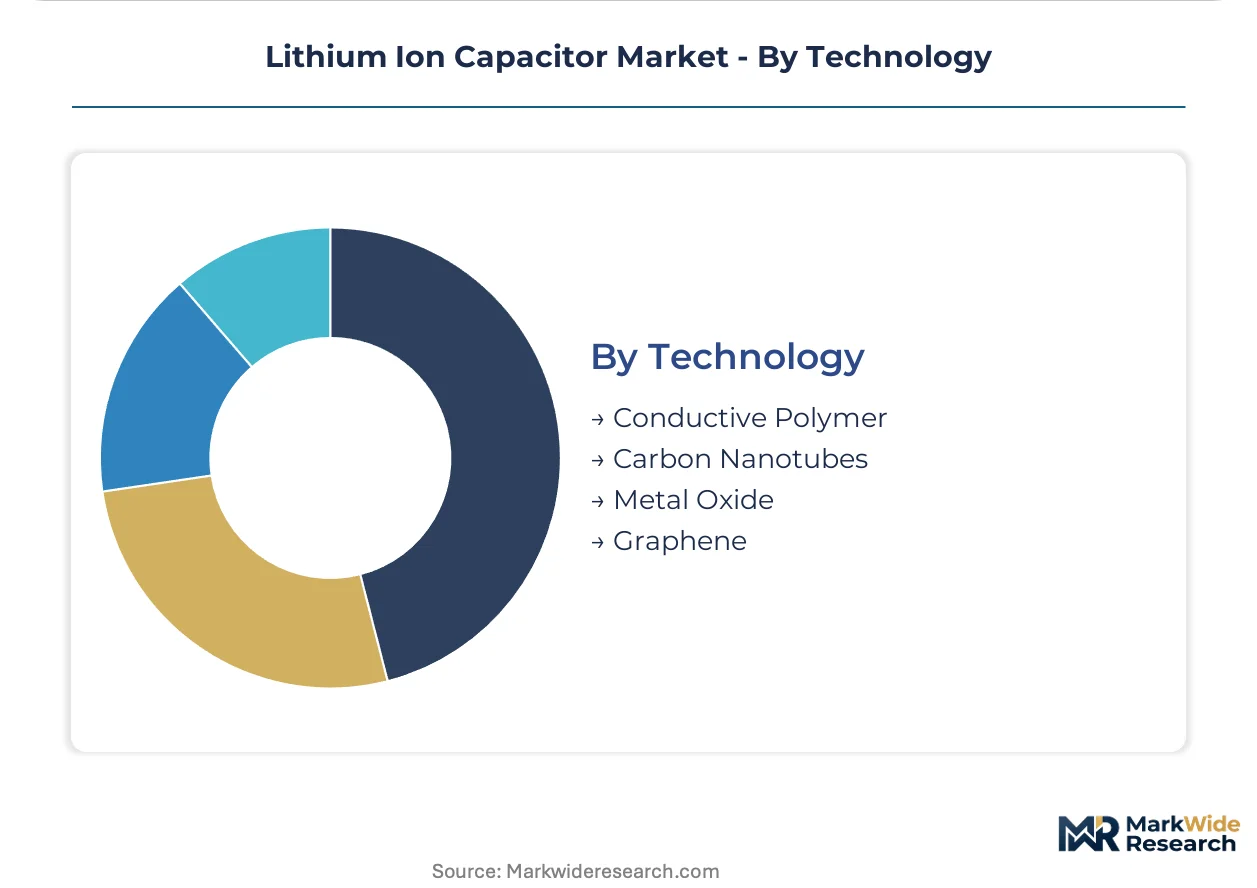
Technology:
Electrode material selection determines performance ceiling and regulatory exposure, with carbon-based architectures facing fewer REACH substance restrictions than metal oxide alternatives containing restricted elements.
- Graphene:Enhanced activated carbon electrodes achieve surface areas exceeding 2,000 m²/g through chemical vapor deposition processes optimized by Korean materials suppliers. Industrial UPS manufacturers are qualifying these for extended service life specifications as production costs converge with conventional carbon.
- Conductive Polymer:These electrodes deliver high capacitance through pseudocapacitive charge storage mechanisms, though cycle life limitations constrain deployment to consumer electronics with 5-7 year replacement horizons.
- Carbon Nanotubes:Vertically aligned architectures offer exceptional conductivity but remain cost-prohibitive for mass-market applications outside aerospace and defense.
- Metal Oxide:Ruthenium and manganese oxide electrodes provide high specific capacitance but face RoHS compliance challenges for ruthenium content and supply concentration risks for battery-grade manganese.
Carbon-based technologies dominate current production; graphene-enhanced electrodes are gaining share fastest as manufacturing scale drives cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan and South Korea dominate production capacity while China absorbs the largest share of installed demand. European utility procurement is opening new consumption nodes as frequency regulation markets mature.
Japan
Hybrid electric vehicle manufacturers specify LIC modules for regenerative braking systems and start-stop applications. METI enforces battery safety benchmarks under the Electrical Appliance and Material Safety Act that govern thermal runaway protocols and abuse testing. The Nagoya industrial corridor hosts concentrated module assembly operations serving Toyota and Honda supply chains.
China
Dual carbon goals and aggressive renewable energy deployment are driving grid-scale energy storage procurement. SAMR administers GB/T 36276 certification requirements mandating thermal runaway propagation resistance for all grid-connected installations. The Yangtze River Delta manufacturing belt around Shanghai and Suzhou concentrates electrode material synthesis and module assembly capacity.
South Korea
Industrial electronics manufacturers around Seoul and Suwon deploy LIC systems for automated manufacturing line voltage stabilization. The country's national industrial regulator enforces KC certification for electrical safety in energy storage equipment. Busan-Ulsan hosts specialized activated carbon precursor production that feeds domestic electrode manufacturing.
Germany
Utility-scale frequency regulation procurement is opening to rapid-response LIC systems for primary frequency control services. ECHA's REACH framework restricts hazardous substances in electrode materials, compelling electrolyte salt reformulation. The Eindhoven Region industrial cluster serves as a distribution hub for European module deployment.
United States
Medical device manufacturers specify surface-mount LICs for mission-critical memory retention during battery swap operations. FDA quality system regulations govern power backup components in portable diagnostic equipment. The Pacific Northwest hosts emerging grid storage pilot projects testing LIC-battery hybrid configurations.
Lithium Ion Capacitor Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology vectors. Japanese and Korean producers command premium positioning through captive electrode material capabilities and automotive qualification heritage. Three archetypes dominate: integrated materials-to-modules specialists, surface-mount component incumbents leveraging PCB design relationships, and grid-system integrators bundling LICs with power electronics. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure long-term offtake agreements for activated carbon precursors.
Among Japanese diversified electronics manufacturers, TAIYO YUDEN and Murata Manufacturing Co., Ltd. occupy positions anchored by ceramic capacitor heritage and surface-mount form factor expertise. VINATech Co., Ltd. represents the Korean pure-play archetype with backward integration into activated carbon electrode production. These three exemplify how geographic clustering around specific manufacturing competencies shapes competitive positioning.
| Leading Market Players |
|---|
| LICAP Technologies, Inc. |
| TAIYO YUDEN |
| JSR Micro NV |
| Electro Standards Laboratories |
| VINATech Co., Ltd. |
| Spel Technologies Pvt. Ltd. |
| Murata Manufacturing Co., Ltd. |
| Socomec Group |
| Yunasko |
| Others |
Supply Flow & Price Mechanics
Battery-grade lithium carbonate price volatility cascades through electrode cost structures into three distinct procurement tiers, compressing margins for producers lacking long-term offtake agreements while rewarding integrated manufacturers with captive precursor supply.
Pricing Analysis
Cost-down pressure on automotive-grade modules accelerates because Japanese OEMs are consolidating vendor relationships around engineering-capable partners. Three-tier pricing structure across automotive, industrial, and consumer electronics levels separates premium temperature-tolerant configurations from standard commercial-grade units. Price differentiation hinges on METI certification compliance and volume scale, with consumer electronics buyers exhibiting highest price sensitivity due to PCB layout commoditization.
Supply Chain Analysis
Regional distribution centers in Busan, Nagoya, and Shanghai anchor hub-and-spoke patterns feeding module assembly operations. Electrode production concentrates in Japan, South Korea, and China, with activated carbon precursor supply drawing from Korean petrochemical feedstock and Chinese coal-based synthesis routes. Single-source vulnerability in fluorinated electrolyte salts creates procurement risk for European assemblers. Distribution runs through Tier 1 automotive supplier channels in Japan and direct industrial procurement in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium ion capacitor market functions as a vertical-integration race where electrode material control determines margin capture, with backward integration into activated carbon synthesis emerging as the decisive competitive lever.
For Market Incumbents: Anchor automotive qualification heritage through co-development partnerships with Tier 1 suppliers absorbing module design responsibility. Deepen upstream control over high-surface-area carbon precursors to defend against Korean pure-play competitors with captive electrode capabilities. METI safety protocol evolution threatens non-compliant producers with 8-14 month certification delays. For New Entrants and Emerging Players: Begin with German utility frequency regulation procurement as the most penetrable white-space target, where rapid-response LIC systems face limited incumbent saturation. Target medical device power backup applications requiring surface-mount form factors for battery swap continuity. Pursue partnership-based go-to-market models with industrial UPS manufacturers seeking 15-year service life guarantees. For Investors and Strategic Acquirers: Distressed-cycle entries favor Korean materials specialists with chemical vapor deposition process optimization in the Busan-Ulsan corridor. Long-term viability centers on graphene-enhanced electrode cost convergence with conventional carbon architectures. Watch ECHA REACH candidate list expansion for electrolyte salt reformulation inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Activated Carbon | Korean suppliers achieve cost parity through chemical vapor deposition optimization. |
| Automotive Co-Development Partnership | Tier 1 suppliers absorb module design responsibility from Japanese OEMs. |
| GB/T 36276 Parallel Certification | Export-oriented Chinese manufacturers invest in redundant testing for European utility projects. |
| Fluorine-Free Electrolyte Reformulation | ECHA REACH restrictions accelerate substitution toward alternative ionic conductivity formulations. |
| Grid-Scale Frequency Regulation Deployment | German and Dutch utilities open procurement to rapid-response LIC systems for primary control services. |
Methodological Framework
Multi-period observation of electrode material pricing indices, certification timeline patterns, and automotive procurement contract structures anchored the trend analysis, supplemented by interviews with module design engineers, activated carbon procurement leads, Tier 1 supplier quality managers, and utility energy storage planners. Secondary validation drew from METI safety bulletins, ECHA REACH candidate list updates, SAMR GB standard revisions, and customs trade data for lithium compound imports. Bottom-up segment sizing triangulated against top-down energy storage deployment forecasts.
Segment-weighting across product architecture, end-user industry, installation format, and electrode technology dimensions shaped the analytical framework over the projection horizon. CAGRs derived from installed base growth rates, replacement cycle assumptions, and penetration elasticity by application. Forecast inputs incorporated lithium carbonate price trajectory scenarios and regulatory compliance cost escalators for multi-standard certification.
Underlying measurement precision varies by segment; automotive applications carry tighter precision than emerging medical device deployments due to established procurement reporting. Forecasts reflect documented assumptions around electrode cost convergence timelines and utility procurement acceleration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Air Battery Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Ternary Lithium Battery Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Lithium Hydroxide Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Solid-State Battery Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
Lithium Ion Battery Cathodes Market