
 Lithium Battery Cells for Passenger Car Market | 2026-2036
Lithium Battery Cells for Passenger Car Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Battery Cells for Passenger Car Market Insights
China is narrowing its cost advantage through integrated cathode-to-cell manufacturing corridors in Fujian and Shenzhen. CATL leverages vertical integration into lithium refining and separator production to lock in raw material flows. BYD Co. Ltd. anchors its competitive position through in-house production of LFP cells for its own vehicle platforms. LG Energy Solution competes by operating joint-venture plants with US and European automakers to circumvent trade barriers.
Lithium battery cells for passenger cars are electrochemical energy storage devices using lithium-ion chemistry, typically operating at 3.2–4.2 volts per cell with energy densities ranging from 150–300 watt-hours per kilogram depending on cathode composition, and they serve as the primary traction power source for electrified automobiles. Prismatic cells dominate current OEM assembly lines due to their efficient pack-level space utilization and structural integration with vehicle chassis. Cylindrical cells, led by Tesla's 4680 format, are gaining structural share as larger formats reduce cell-to-pack complexity and manufacturing overhead. Solid-state cells remain pre-commercial but attract concentrated R&D investment as the technology promises higher energy density and improved thermal stability.
EPA vehicle emissions rules, EU Green Deal CO2 fleet targets, and China's dual carbon goals are collectively mandating electrified powertrains and reshaping cell chemistry roadmaps toward lower-carbon intensity supply chains. NHTSA battery safety standards and UN 38.3 transport testing protocols enforce rigorous thermal runaway containment and abuse tolerance requirements that filter market access. Stakeholders must monitor cathode chemistry cost curves and regional content rules to align capacity investments with qualifying supply chains.
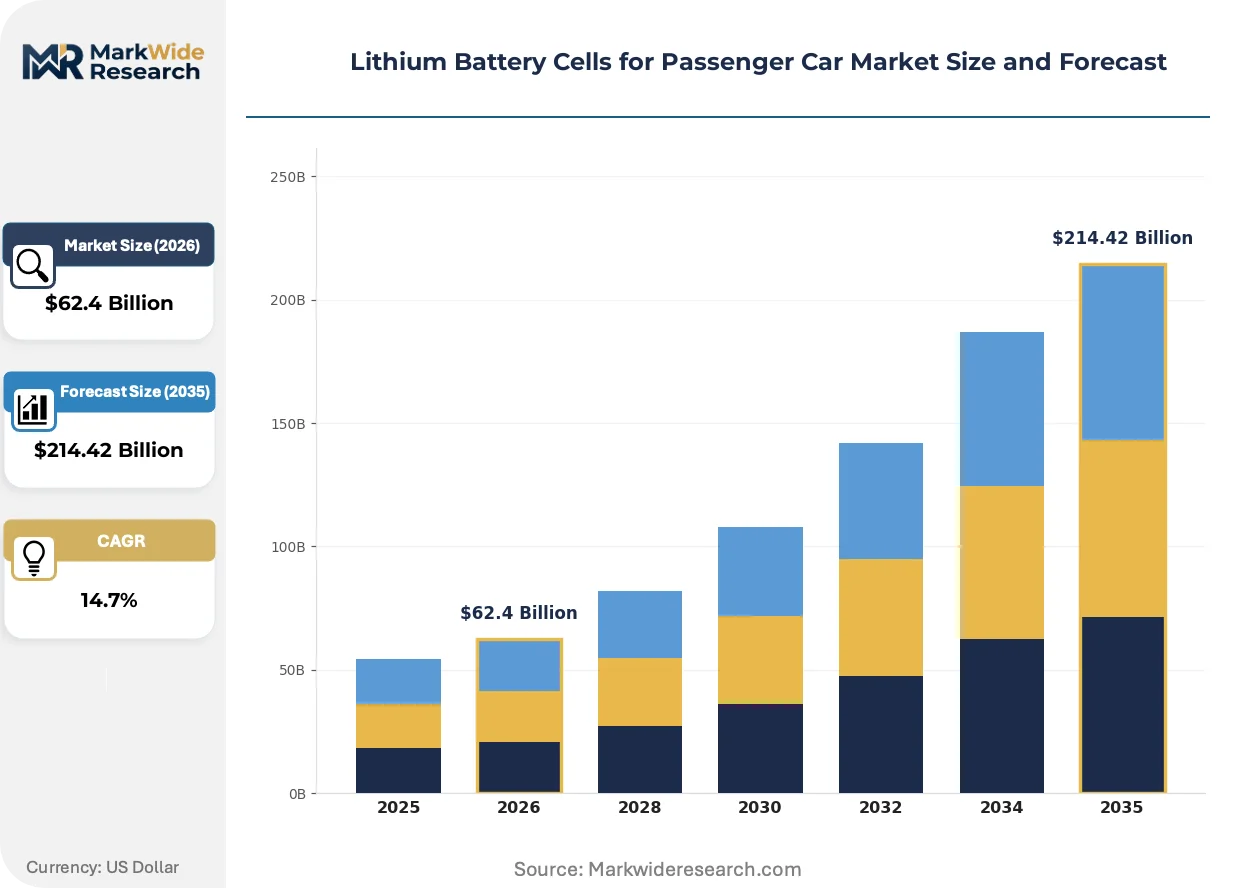
Market Dynamics
EPA tailpipe emissions standards are compressing vehicle electrification timelines and forcing OEMs to secure multi-year cell supply contracts ahead of platform launches. This regulatory pressure is concentrating procurement power among large-scale battery manufacturers with proven gigafactory deployment capabilities.
Growth Catalysts
- US EPA Fleet Standards:The tightened tailpipe emissions framework mandates electrified powertrains for model years through 2032, locking in decade-long cell demand visibility for qualified suppliers.
- LFP Chemistry Maturation:Lithium iron phosphate formulations eliminate cobalt supply risk while delivering sufficient range for mass-market passenger vehicles, expanding addressable OEM budgets.
- China:Dual carbon goals and NEV purchase subsidies sustain the world's largest single-country demand pool, with domestic production clusters capturing scale economies.
Market Restraints
- Lithium Carbonate Volatility:Spodumene concentrate and brine-derived lithium prices swing with extraction project delays, compressing cell margin predictability for non-integrated producers.
- Separator Supply Concentration:Wet-process polyolefin separator production clusters in East Asia create single-source vulnerability for Western cell plants seeking regional content compliance.
- Thermal Runaway Physics:High-nickel cathode chemistries carry inherent thermal instability that demands redundant containment engineering, adding pack-level cost and mass.
Strategic Opportunities
- India:PLI scheme incentives for advanced chemistry cell manufacturing create first-mover advantage for producers establishing local cathode-to-module corridors before domestic EV adoption inflects.
- Solid-State Convergence:Sulfide-based electrolyte research intersecting with dry electrode coating processes promises manufacturing compatibility with existing lithium-ion infrastructure.
- Direct OEM-Cellmaker Contracts:Long-term offtake agreements are displacing spot-market procurement, enabling capital commitment visibility for greenfield capacity in qualifying supply chain jurisdictions.
Industry Challenges
- Electrochemical Engineering Talent:Cell design and manufacturing process engineering expertise concentrates at a handful of institutions, constraining workforce scaling for new market entrants.
- UN 38.3 Certification Timelines:Transport safety testing protocols for new cell formats add 12-18 month qualification delays that misalign with compressed vehicle platform launch schedules.
- Pack-to-Chassis Integration Complexity:Structural battery architectures demand concurrent engineering between cell suppliers and OEM chassis teams, fragmenting legacy tiered supply relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Battery Cells for Passenger Car Market |
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $214.42 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic Cells, Cylindrical Cells, Pouch Cells, Solid-State Cells End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships Technology: LFP, NMC, NCA, LiCoO2 Application: Electric Vehicles, Hybrid Vehicles, Plug-in Hybrids, Vehicle Assemblers |
| Companies Covered | CATL, BYD Co. Ltd., LG Energy Solution, Panasonic Holdings Corporation, Samsung SDI, CALB, SK On, EVE Energy, Gotion High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Battery Cells for Passenger Car Market Trends and Innovations
Cell format evolution and chemistry roadmaps are converging with vehicle platform engineering cycles, compressing development timelines and forcing simultaneous advances in manufacturing process control.
Dry electrode coating is digitizing cell manufacturing by eliminating solvent-based slurry processing and its associated drying energy consumption. Tesla and established Asian producers are retrofitting pilot lines to validate roll-to-roll calendering of PTFE-bonded active material layers. This process shift is compressing factory energy intensity and enabling thicker electrodes that boost energy density without chemistry changes.
The EU Battery Regulation mandates recycled content thresholds and full supply chain due diligence disclosure, effective in phased implementation through 2031. Cell producers must deploy digital passport systems tracking cobalt, lithium, and nickel from extraction to module assembly. High-nickel cathode formulations face the steepest compliance burden, accelerating European OEM interest in LFP and sodium-ion alternatives for entry-segment vehicles.
Automotive procurement teams are consolidating supplier relationships around cell makers with captive cathode and lithium refining assets. Tier-1 battery system integrators are losing share to direct OEM-cellmaker partnerships that bypass traditional module and pack assembly margins. This disintermediation is most visible in Germany and the US, where IRA domestic content rules reward supply chain transparency that only vertically structured producers can document.
Lithium Battery Cells for Passenger Car Market Segmentation
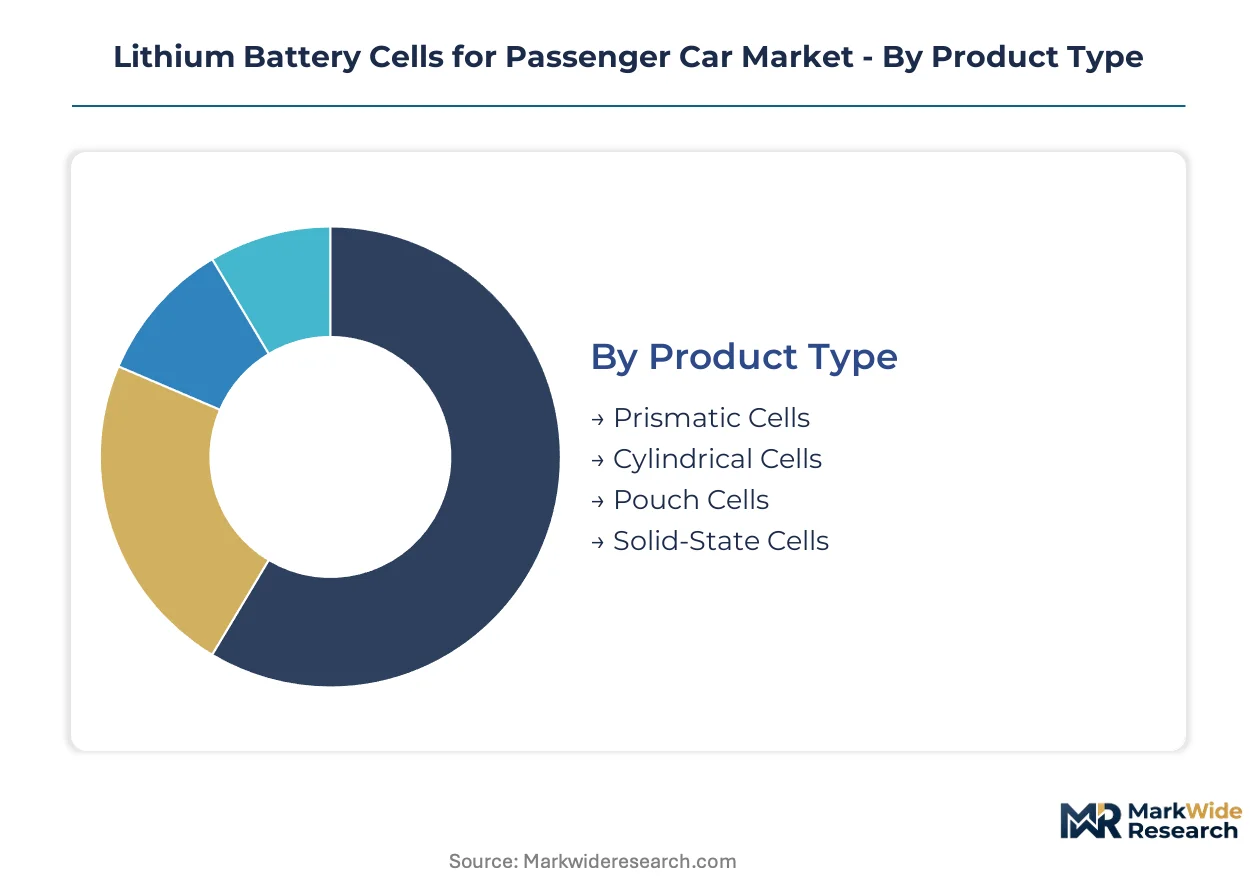
Cell format selection dictates pack architecture, thermal management complexity, and manufacturing capital requirements for passenger car programs. Chemistry and end-user channel choices determine margin structure, supply chain qualification burden, and exposure to raw material volatility.
Product Type:
Prismatic formats serve structural battery integration priorities across premium and mass-market vehicle platforms.
- Prismatic Cells:Rectangular aluminum-housed cells enable direct cell-to-pack assembly with minimal module overhead. CATL and BYD deploy these formats for blade battery architectures in China, where OEMs prioritize pack-level space efficiency and chassis integration.
- Cylindrical Cells:Larger formats reduce welding joints and simplify thermal management. Tesla's 4680 production lines in Nevada and Texas demonstrate manufacturing scalability, though yield optimization remains ongoing for the dry electrode coating process.
- Pouch Cells:Flexible polymer-laminated housings suit hybrid applications with irregular packaging constraints. SK On and LG Energy Solution supply Korean and European OEMs for PHEV programs requiring custom form factors.
- Solid-State Cells:Pre-commercial sulfide and oxide electrolyte architectures promise energy density above 400 Wh/kg. Toyota and QuantumScape target limited production runs for luxury EVs before mass-market scaling.
The dominant share belongs to prismatic cells, while cylindrical formats are closing the gap fastest through larger format adoption.
End User:
Procurement channel structure reflects vehicle electrification maturity and regulatory compliance requirements.
- OEMs:Direct cell contracts span 5-10 year horizons with volume commitments tied to platform launches. Ford, GM, and Volkswagen negotiate joint-venture structures to secure IRA domestic content qualification.
- Aftermarket Providers:Independent repair networks source replacement modules for out-of-warranty vehicles. These channels face UN 38.3 transport certification barriers and limited cell maker willingness to supply non-OEM volumes.
- Fleet Operators:Commercial buyers negotiate bulk service agreements with guaranteed residual value terms. Amazon's Rivian delivery van deployment and Hertz's Tesla rental fleets exemplify volume aggregation strategies.
- Dealerships:Franchise networks handle warranty replacements and regional inventory positioning. Dealer margin pressure limits this channel to low-volume, high-margin service events.
OEM direct procurement commands absolute volume concentration, though fleet operators are expanding fastest as commercial electrification accelerates.
Technology:
Cathode chemistry selection balances energy density targets against raw material cost curves and supply chain risk.
- LFP:Iron phosphate formulations eliminate cobalt and nickel exposure. BYD and CATL dominate production for entry and mid-market vehicles in China, with European OEMs adopting for cost-sensitive segments.
- NMC:Nickel-manganese-cobalt layered oxides deliver 250-300 Wh/kg cell-level density. Korean cell makers prioritize NMC 811 and 9½½ variants for US and European premium EVs requiring maximum range.
- NCA:Nickel-cobalt-aluminum cathodes from Panasonic supply Tesla's long-range programs. Cobalt content remains higher than NMC alternatives, constraining cost reduction trajectories.
- LiCoO2:Cobalt-dense formulations persist in limited hybrid applications where cell mass is less critical than discharge rate performance.
NMC retains the dominant chemistry position for range-critical applications, while LFP is gaining share fastest through mass-market vehicle program adoption.
Application:
Powertrain electrification degree determines cell specification, cycle life requirements, and thermal management intensity.
- Electric Vehicles:Full battery electric platforms demand 60-100+ kWh packs with 1500+ cycle durability. Cell-to-chassis integration in Tesla's structural packs and BYD's blade designs exemplifies optimization for this segment.
- Hybrid Vehicles:Small 1-2 kWh batteries prioritize power density and rapid charge acceptance. Toyota's NiMH-to-lithium transition programs and Honda's e:HEV architecture drive specialized cell formats.
- Plug-in Hybrids:10-20 kWh packs enable 30-50 mile electric range with daily cycling. European OEMs favor this technology for fleet CO2 compliance during charging infrastructure buildout phases.
- Vehicle Assemblers:Contract manufacturing arrangements for startup EV brands without captive cell supply. Fisker, Lucid, and Rivian rely on external cell sourcing for initial production ramps.
Pure electric vehicles command the dominant application share, while plug-in hybrids are expanding most quickly as transitional technology for markets with charging infrastructure gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA tailpipe emissions standards and IRA domestic content rules are concentrating cell procurement decisions in the United States, while China's dual carbon goals and NEV subsidies sustain the world's largest manufacturing footprint.
United States
Ford, GM, and Tesla are securing multi-year offtake agreements to meet IRA qualification thresholds for federal tax credits. The EPA's tightened fleet standards through model year 2032 mandate electrified powertrains across light-duty segments. Gigafactory clusters in Nevada, Texas, and Michigan are scaling cylindrical and prismatic cell output for domestic OEM platforms.
China
CATL and BYD anchor massive cathode-to-cell manufacturing corridors serving both local automakers and export markets. The country's dual carbon goals and MIIT production quotas enforce NEV penetration targets that lock in decade-long cell demand visibility. Fujian and Shenzhen production clusters capture integrated refining and separator supply chain economies.
Germany
Volkswagen, BMW, and Mercedes-Benz negotiate joint-venture structures with Asian cell makers to circumvent EU Battery Regulation compliance burdens. The EU Green Deal CO2 fleet targets mandate 100% zero-emission new car sales by 2035. Cell-to-pack assembly plants in Thuringia and Lower Saxony are qualifying for CSRD supply chain disclosure requirements.
South Korea
LG Energy Solution and Samsung SDI prioritize NMC chemistry output for US and European premium EV programs requiring maximum range density. The country's national industrial policy channels KRW-denominated financing toward solid-state R&D commercialization. Gyeonggi-do and Ulsan production bases supply joint-venture plants in Poland and the United States.
Japan
Panasonic Holdings Corporation supplies high-nickel cylindrical cells for Tesla's long-range platforms while Toyota accelerates sulfide-based solid-state development. METI production subsidies and JIS safety standards enforce rigorous thermal runaway containment protocols. Kyoto and Osaka R&D clusters concentrate electrochemical engineering talent for next-generation electrolyte architectures.
Lithium Battery Cells for Passenger Car Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, creating a bifurcated structure where technology leadership and manufacturing throughput occupy separate competitive positions. The market consolidates around vertically integrated producers with captive cathode supply and gigafactory deployment experience. Three archetypes dominate: integrated chemistry-to-cell manufacturers, joint-venture operators with OEM partners, and specialist solid-state developers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players racing to lock in raw material flows and qualify for regional content rules.
Within the integrated manufacturing tier, CATL, BYD Co. Ltd., and LG Energy Solution occupy positions that exemplify divergent geographic and chemistry strategies. CATL represents the China-anchored, LFP-capable archetype with backward integration into lithium refining. BYD Co. Ltd. exemplifies the captive-demand model where in-house cell production serves proprietary vehicle platforms. LG Energy Solution sits within the Korean-led, NMC-focused camp that relies on joint-venture structures to access US and European markets under trade-compliant supply chains.
| Leading Market Players |
|---|
| CATL |
| BYD Co. Ltd. |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| Samsung SDI |
| CALB |
| SK On |
| EVE Energy |
| Gotion High-Tech |
| Others |
Pricing and Supply Chain Analysis
Overcapacity signals from China's Fujian and Shenzhen production corridors are forcing cell producers into aggressive price positioning to maintain utilization rates, compressing margins for non-integrated Western competitors while accelerating contract renegotiations for OEM buyers seeking cost relief.
Pricing Analysis
Contract-based long-term offtake agreements dominate the pricing architecture, with spreads between Chinese domestic and US-qualifying supply widening due to IRA domestic content rules. Price differentiation rests on cathode chemistry grade and volume scale, with LFP cells commanding lower absolute prices but higher margin stability than NMC alternatives. Cost compression in high-nickel tiers is intensifying because lithium carbonate volatility and cobalt supply risk concentrate input cost uncertainty. Fleet operators exhibit the highest price sensitivity due to total-cost-of-ownership procurement models, while premium OEMs prioritize energy density and thermal performance over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with CATL, BYD, and LG Energy Solution, which collectively control cathode-to-cell assembly capacity across China, South Korea, and Japan. The supply chain draws from spodumene concentrate in Australia, brine-derived lithium in Chile, and wet-process polyolefin separators from East Asian chemical producers. Single-source vulnerability in separator supply creates qualification bottlenecks for Western cell plants seeking regional content compliance. Distribution runs through direct OEM-cellmaker partnerships that displace traditional Tier-1 battery system integrators, with aftermarket channels facing UN 38.3 certification barriers that limit non-OEM volume access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA tailpipe emissions standards and IRA domestic content rules are compressing electrification timelines, creating a high-growth disruption where cell procurement decisions made in the current window will lock in competitive positioning for platform lifecycles.
For Market Incumbents: Harden supply chain resilience by securing captive lithium refining capacity in qualifying jurisdictions before regional content rules tighten further. Accelerate dry electrode coating process validation to defend manufacturing cost position against emerging solid-state entrants. Prioritize joint-venture structures with US and European OEMs to circumvent trade barriers and secure decade-long offtake visibility. For New Entrants and Emerging Players: India's PLI scheme incentives for advanced chemistry cell manufacturing represent the most penetrable white-space opportunity, with domestic EV adoption curves still early and local cathode-to-module corridors underdeveloped. Target fleet operator aggregation strategies as the go-to-market angle, leveraging bulk service agreements with guaranteed residual value terms to bypass OEM direct procurement concentration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cell makers with captive cathode assets and multi-year OEM offtake structures. Long-term viability across the analysis window favors vertically integrated producers with proven gigafactory deployment capabilities. Watch solid-state electrolyte research milestones as the inflection indicator for next-generation chemistry disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | LG Energy Solution's US plant partnerships with GM and Honda secure IRA tax credit qualification. |
| Backward Integration | CATL's lithium refining investments in Jiangxi lock in raw material flows for LFP production. |
| Dry Electrode Scale-Up | Tesla's 4680 pilot lines validate roll-to-roll calendering that eliminates solvent processing energy. |
| Solid-State R&D Partnership | Toyota's sulfide electrolyte research with METI funding targets luxury EV production runs. |
| Regional Content Compliance | European cell plants in Thuringia qualify for EU Battery Regulation recycled content thresholds. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement leads, cell manufacturing process directors, and aftermarket distribution managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC filings from cell makers, EPA regulatory dockets, MIIT production quota disclosures, and IHS Markit vehicle production databases. Bottom-up cell demand modeling triangulated against top-down OEM electrification commitment tracking.
Scenario-bracketing around EPA fleet standard stringency and IRA domestic content rule evolution shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include cell format, cathode chemistry, end-user channel, and regional production cluster. CAGRs were derived from installed capacity trajectories and platform launch timelines. Forecast inputs incorporated lithium carbonate price curve assumptions and joint-venture plant commissioning schedules.
Practitioners should monitor EPA rulemaking revisions and EU Battery Regulation implementation timelines for early signals of demand inflection or supply chain qualification disruption. Forecasts reflect assumptions about cathode chemistry cost curves and regional trade policy stability. Quarterly review of cell capacity utilization rates and OEM offtake contract renegotiation activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
HEV Li-Ion Battery Market
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market
Lithium-ion Battery
Lithium-Ion Battery Wet-Process Separator Market
Lithium-ion Battery
Lithium-Ion Battery Metal Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
China Electric Vehicle Battery Anode Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
Li-Sulfur Battery Market