
 United States Electric Vehicle Battery Electrolyte Market | 2026-2036
United States Electric Vehicle Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Vehicle Battery Electrolyte Market Insights
Direct supply contracts between electrolyte producers and gigafactory operators is rewriting procurement patterns across the US battery value chain. BASF SE leverages its integrated chemical platform to anchor large-format lithium-ion cell supply in the Midwest. LG Chem Ltd. competes through captive R&D facilities tied to its Michigan joint-venture operations. Mitsubishi Chemical Holdings sustains position via specialized high-purity LiPF6 output serving premium EV platforms.
Electric vehicle battery electrolyte comprises ion-conducting media—typically lithium hexafluorophosphate dissolved in carbonate solvents—that facilitates lithium-ion transport between anode and cathode during charge and discharge cycles, with conductivity thresholds exceeding 10 mS/cm at room temperature for acceptable power density. Liquid electrolyte formulations currently dominate installed capacity due to mature manufacturing infrastructure and established compatibility with graphite anodes, while solid electrolyte segments attract concentrated capital as silicon-anode and lithium-metal architectures approach commercial scale. Polymer electrolyte applications occupy niche positions in thin-film configurations where mechanical flexibility outweighs ionic conductivity constraints.
The US Environmental Protection Agency oversees chemical safety and waste protocols affecting electrolyte manufacturing facilities, while the Department of Energy administers loan programs conditioning capital access on domestic sourcing thresholds. NHTSA battery safety standards and OSHA process safety management requirements jointly elevate compliance costs for new market entrants. Stakeholders must monitor how forthcoming EPA PFAS regulations and state-level extended producer responsibility frameworks reshape material selection and end-of-life liability structures.
Market Dynamics
The Inflation Reduction Act's domestic content thresholds are forcing electrolyte producers to reconfigure supply chains around Michigan's battery corridor and Texas energy storage clusters, compressing procurement timelines for gigafactory operators.
Growth Catalysts
- IRA Domestic Content Mandates:Battery cell manufacturers must source electrolyte from North American facilities to qualify for federal tax credits, pulling production capacity toward Ohio and Tennessee chemical parks.
- Solid-State Battery Scale-Up:Silicon-anode and lithium-metal architectures nearing commercial deployment require specialized high-conductivity formulations, expanding addressable demand beyond conventional lithium-ion.
- Energy Storage Procurement Surge:Texas and California grid-scale battery installations are absorbing surplus electrolyte capacity originally built for automotive offtake.
Market Restraints
- LiPF6 Supply Concentration:Three Asian chemical conglomerates control over 80% of high-purity lithium hexafluorophosphate feedstock, exposing US formulators to shipping disruptions and currency volatility.
- Fluorinated Solvent Regulatory Friction:Forthcoming EPA PFAS reporting requirements will force reformulation of electrolyte additives used in fast-charging cells, extending R&D cycles by 12-18 months.
- Capital Intensity of Dry Room Infrastructure:Electrolyte blending facilities require humidity-controlled environments below 1% relative moisture, driving facility costs to 3-4x standard chemical plant levels.
Strategic Opportunities
- Southeast Battery Corridor Expansion:Kentucky and Georgia gigafactory announcements lack proximate electrolyte supply, creating greenfield entry points for producers willing to co-locate with cell manufacturers.
- Recycled Lithium Salt Recovery:Spent battery black mass processing in Nevada and Arizona yields recoverable lithium compounds suitable for electrolyte regeneration, closing loop on virgin material dependence.
- Department of Energy Loan Programs:Conditional capital access for facilities meeting domestic sourcing thresholds is accelerating project finance for independent electrolyte specialists outside established chemical conglomerates.
Industry Challenges
- Electrochemical Engineer Scarcity:US universities produce fewer than 200 graduates annually with specialized battery chemistry training, forcing producers to recruit from semiconductor and pharmaceutical sectors.
- NHTSA Thermal Runaway Certification:New cell-level safety testing protocols require electrolyte formulators to validate flame-retardant additive packages across multiple cathode chemistries, multiplying qualification costs.
- Legacy Solvent Disposal Liability:California and New York extended producer responsibility frameworks are shifting end-of-life disposal costs upstream to electrolyte manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Vehicle Battery Electrolyte Market |
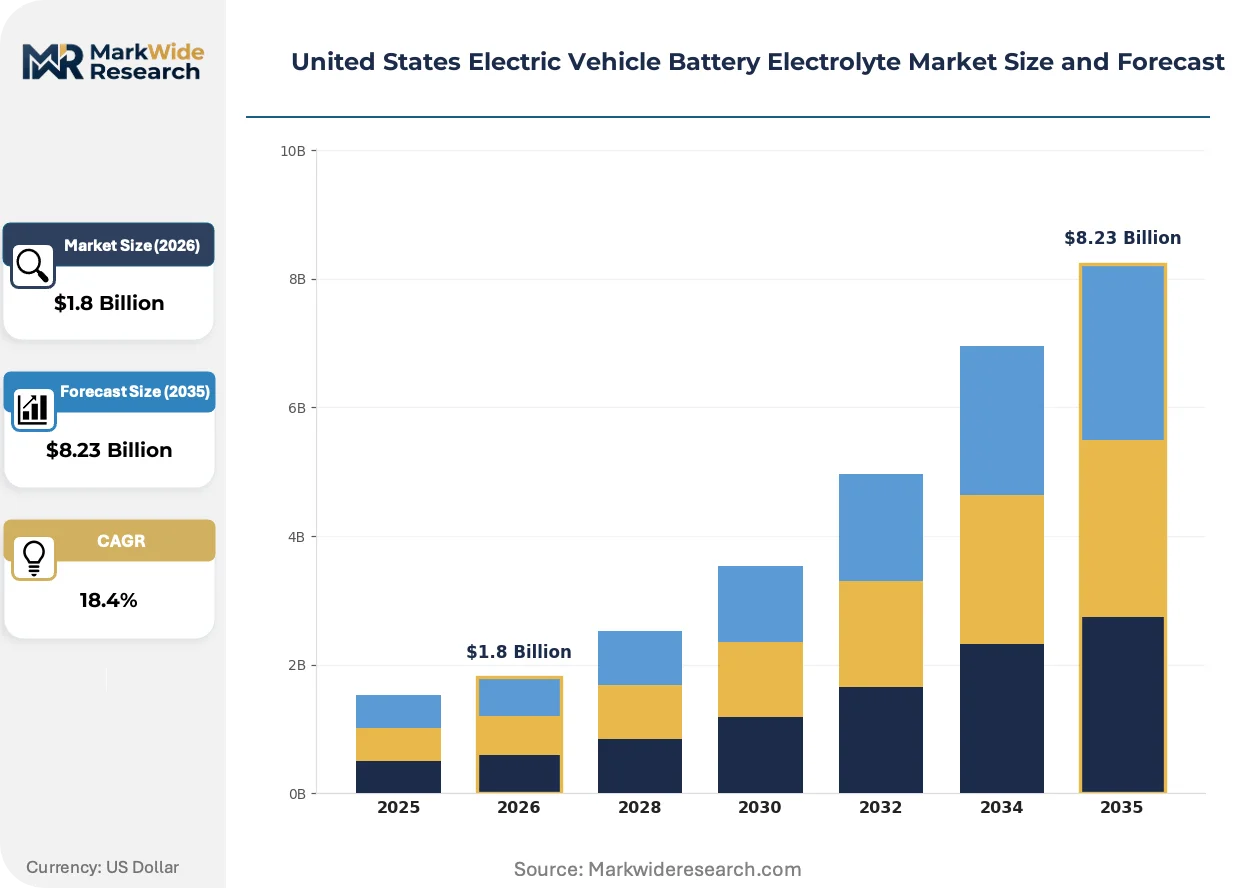
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Liquid Electrolyte, Solid Electrolyte, Gel Electrolyte, Polymer Electrolyte Material: LiPF6, LiTFSI, LiBF4, Others Application: Electric Vehicles, Hybrid Vehicles, Energy Storage Systems, Motorcycles End User: Automobile Manufacturers, Battery Manufacturers, Research Institutes, Specialty Chemical Companies |
| Companies Covered | Advanced Electrolyte Technologies LLC, Mitsubishi Chemical Holdings, Nohms Technologies Inc., Ohara Corporation, BASF SE, LG Chem Ltd., 3M Company, FMC Corporation, NEI Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Vehicle Battery Electrolyte Market Trends and Innovations
Electrolyte formulation is undergoing rapid evolution as solid-state architectures displace liquid systems in premium automotive segments, while regulatory pressure on fluorinated compounds forces material substitution across the value chain.
Localized ionic liquid additives are digitizing thermal management in high-nickel cathode cells, enabling Ford and General Motors to push fast-charging protocols beyond 350kW without dendrite formation. Tier-one suppliers are qualifying these formulations for 2026 platform launches. The technology is digitizing cell-level simulation workflows, compressing design cycles from 18 months to 6 months.
EPA PFAS reporting mandates under TSCA Section 8(a)(7) are forcing disclosure of fluorinated electrolyte salts and additives by 2025, compelling formulators to inventory entire supply chains. Battery producers face reformulation costs or substitution with phosphazene-based flame retardants. Midwest gigafactory operators are responding by pre-qualifying non-fluorinated electrolyte suppliers ahead of enforcement deadlines.
Direct long-term offtake contracts are displacing spot market purchasing as the dominant procurement mode, with cell manufacturers locking 5-7 year supply agreements to secure IRA compliance. Tier-two electrolyte specialists are bypassing distributors to contract directly with Detroit OEMs. This shift is most visible in Michigan, where Ford's BlueOval SK joint venture has consolidated supplier panels to three approved electrolyte sources.
United States Electric Vehicle Battery Electrolyte Market Segmentation
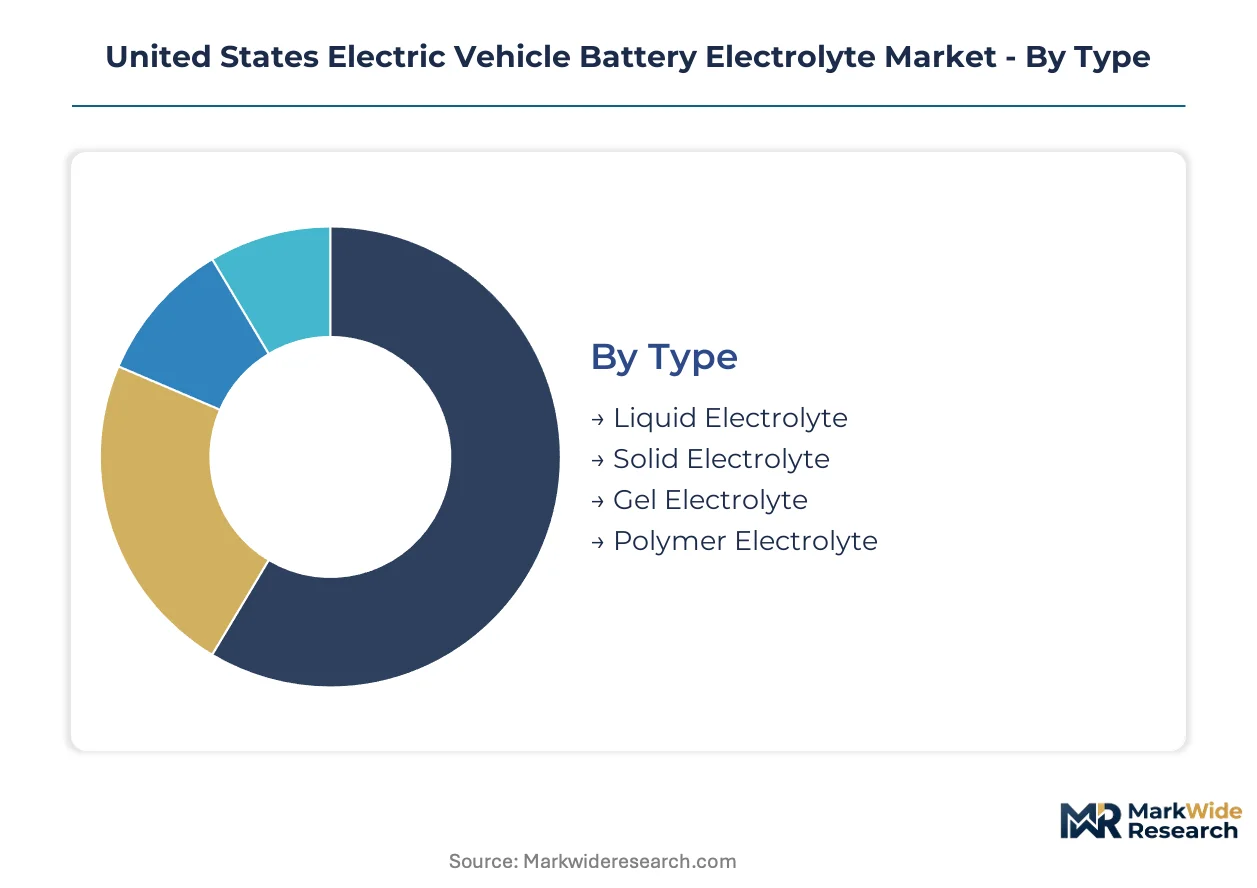
Electrolyte segmentation in the US market reflects divergent technology maturities and regulatory pressures shaping procurement decisions. Formulation type determines manufacturing infrastructure requirements, while material chemistry and end-use application dictate qualification timelines and margin structures across the value chain.
Type:
Liquid formulations anchor current installed capacity, while solid-state alternatives command concentrated R&D investment as automotive platforms electrify.
- Liquid Electrolyte:Lithium hexafluorophosphate dissolved in carbonate solvents dominates Michigan gigafactory supply agreements due to mature blending infrastructure and graphite anode compatibility. Ford and General Motors have locked multi-year procurement contracts with Ohio-based formulators to satisfy IRA domestic content thresholds.
- Solid Electrolyte:Sulfide and oxide ceramic conductors enable lithium-metal anode architectures approaching commercial scale in Detroit OEM pilot programs. Dry room processing requirements and brittle mechanical properties constrain near-term volume, though DOE loan programs are de-risking Tennessee facility investments.
- Gel Electrolyte:Semi-solid matrices occupy niche medical and aerospace battery applications where leakage elimination outweighs conductivity penalties.
- Polymer Electrolyte:Thin-film configurations serve flexible electronics and solid-state prototype cells from California research institutes.
Liquid electrolyte retains volume leadership; solid electrolyte holds the steepest expansion curve.
Material:
Cost tier stratification separates commodity salts from specialty formulations commanding qualification premiums.
- LiPF6:The standard lithium salt for commercial lithium-ion cells requires sub-10 ppm moisture specifications and fluorinated solvent compatibility. BASF SE and LG Chem Ltd. have secured dedicated supply pipelines from Asian feedstock producers to anchor Midwest gigafactory demand.
- LiTFSI:Bis(trifluoromethanesulfonyl)imide lithium salt enables high-voltage cathode operation above 4.4V in premium EV platforms from Detroit manufacturers. Limited domestic production capacity forces US formulators to import from European specialty chemical suppliers.
- LiBF4:Tetrafluoroborate salt offers improved thermal stability for high-temperature energy storage applications in Texas grid installations.
- Others:Lithium bis(oxalato)borate and proprietary additive packages serve solid-state prototype development at national laboratories.
LiPF6 commands absolute volume share; LiTFSI is climbing the fastest as high-voltage cathodes proliferate.
Application:
Customer type determines formulation specification stringency and contract duration across transportation and stationary segments.
- Electric Vehicles:Long-range passenger platforms require electrolytes validated for 10-year calendar life and fast-charging protocols above 350kW. NHTSA thermal runaway certification mandates flame-retardant additive packages that extend qualification cycles.
- Hybrid Vehicles:Smaller-format cells with moderate energy density requirements utilize standardized carbonate formulations with reduced purity specifications.
- Energy Storage Systems:Texas and California grid-scale installations prioritize cost-optimized formulations with extended cycle life over power density.
- Motorcycles:Lightweight two-wheeler batteries from California and Florida manufacturers employ simplified electrolyte blends with relaxed thermal management requirements.
Electric vehicles absorb the dominant volume; energy storage systems are expanding most quickly as IRA storage tax credits activate.
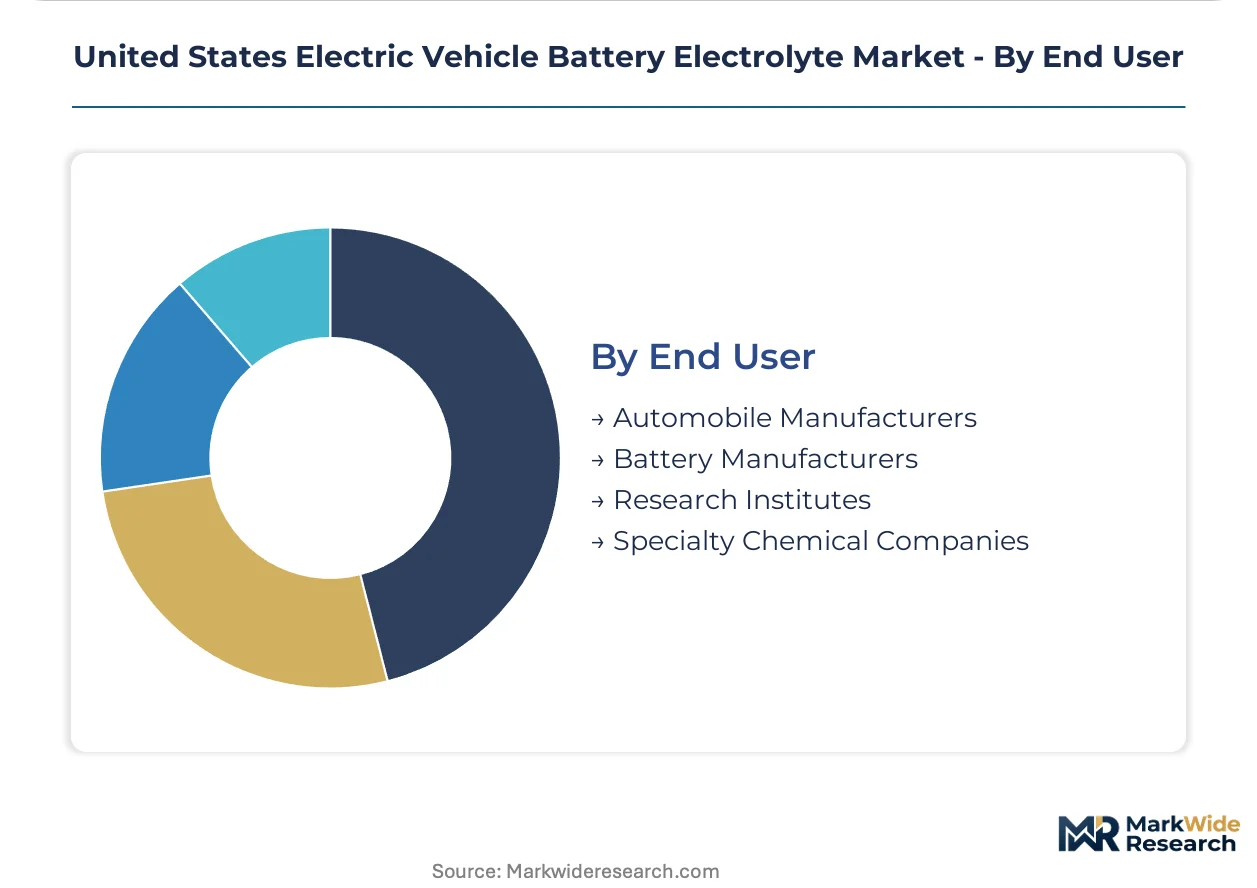
End User:
Procurement concentration varies sharply between integrated OEMs and independent cell manufacturers.
- Automobile Manufacturers:Detroit-based OEMs with captive joint ventures in Michigan and Tennessee are consolidating supplier panels to three approved electrolyte sources per platform. Direct long-term offtake contracts displace distributor relationships.
- Battery Manufacturers:Independent cell producers in Kentucky and Georgia lack proximate electrolyte supply, creating greenfield entry opportunities for formulators willing to co-locate.
- Research Institutes:National laboratories and university consortia in California and Massachusetts drive next-generation solid-state formulation development through ARPA-E funding.
- Specialty Chemical Companies:Diversified chemical conglomerates leverage integrated platforms to supply electrolyte additives and solvents to multiple downstream customers.
Automobile manufacturers concentrate procurement leverage; battery manufacturers represent the fastest-growing customer segment as independent gigafactory construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach rail intermodal complex underwrites California's dominance in Pacific Rim chemical feedstock imports, while the Colonial Pipeline network anchors Southeast electrolyte distribution to Georgia and Kentucky gigafactory sites.
Michigan
Ford's BlueOval SK joint venture and General Motors' Ultium Cells operations absorb the majority of Midwest electrolyte supply. NHTSA battery safety standards require thermal runaway certification for all formulations entering automotive platforms. Detroit's battery corridor concentrates blending facilities in Warren and Holland, where humidity-controlled plants service OEM demand.
Texas
ERCOT grid-scale storage procurement surged following winter storm hardening mandates, pulling electrolyte capacity toward Houston and Dallas-Fort Worth chemical parks. The Department of Energy administers loan programs conditioning capital on domestic sourcing thresholds. The Texas energy storage cluster now rivals automotive offtake for regional formulator attention.
Ohio
LG Chem's joint-venture operations in Lordstown anchor high-purity LiPF6 demand from Asian feedstock pipelines. OSHA process safety management requirements elevate compliance costs for new blending facilities. Toledo chemical parks host BASF SE integrated operations serving Detroit OEM supply chains.
Tennessee
SK Innovation's BlueOval City development drives electrolyte co-location decisions among suppliers seeking IRA-compliant procurement contracts. EPA chemical safety protocols govern waste handling at manufacturing facilities. The Memphis-Nashville corridor attracts dry room infrastructure investment from producers qualifying for federal tax credit eligibility.
Georgia
Hyundai Motor Group's Metaplant America and Rivian's planned facility create greenfield entry opportunities absent proximate electrolyte supply. Georgia Power's renewable energy procurement supports carbon-neutral manufacturing claims. The Savannah port infrastructure enables direct chemical import bypassing traditional Northeast distribution hubs.
United States Electric Vehicle Battery Electrolyte Market Competitive Landscape
On the supply side, the industry is consolidating around three approved supplier panels per OEM platform, with direct long-term offtake contracts displacing spot market relationships. Tier-one chemical conglomerates leverage integrated solvent and additive platforms, while independent specialists compete through DOE loan program qualification. Strategic archetypes include diversified multinational chemical producers, captive R&D joint ventures, and emerging domestic formulators. Competitive moves center on co-location with gigafactory operators and backward integration into lithium salt purification.
Within the integrated chemical platform tier, BASF SE and LG Chem Ltd. exemplify multinational producers leveraging existing infrastructure. Mitsubishi Chemical Holdings occupies a specialist position in high-purity lithium salt supply. These three anchors represent distinct competitive vectors: European chemical integration, Korean joint-venture captive supply, and Japanese specialty materials focus.
| Leading Market Players |
|---|
| Advanced Electrolyte Technologies LLC |
| Mitsubishi Chemical Holdings |
| Nohms Technologies Inc. |
| Ohara Corporation |
| BASF SE |
| LG Chem Ltd. |
| 3M Company |
| FMC Corporation |
| NEI Corporation |
| Others |
Pricing and Supply Chain Analysis
Asian lithium hexafluorophosphate producers in China, Japan, and South Korea anchor upstream supply concentration, pushing margin capture toward electrolyte formulators with captive salt purification or direct long-term offtake contracts with Detroit OEMs. IRA domestic content mandates are compressing procurement timelines and amplifying price premiums for North American-qualified supply.
Pricing Analysis
Volume-discount tiering structures dominate procurement between electrolyte formulators and gigafactory operators, with contract duration and qualification status driving price differentiation. Premium formulations validated for NHTSA thermal runaway certification command substantial markups over standard carbonate blends. Cost compression in commodity LiPF6 supply is intensifying because of feedstock oversupply from Asian chemical conglomerates. Independent battery manufacturers in Kentucky and Georgia exhibit highest price sensitivity, while Detroit OEMs with captive joint ventures prioritize qualification security over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with BASF SE's integrated chemical platforms in Ohio and Tennessee, LG Chem's captive Michigan operations, and Mitsubishi Chemical's specialty salt facilities. Raw material dependencies center on high-purity LiPF6 feedstock, fluorinated carbonate solvents, and lithium salt precursors sourced predominantly from East Asian chemical parks. Single-source vulnerability in LiPF6 supply exposes US formulators to shipping disruptions and currency volatility. Distribution runs through direct long-term offtake contracts displacing spot market relationships, with rail networks from the Port of Long Beach and Colonial Pipeline terminals anchoring Southeast logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolyte formulation is fragmenting across solid-state, high-voltage, and non-fluorinated niches as Detroit OEMs diversify supplier panels and IRA compliance creates procurement complexity. Solid-state battery scale-up and EPA PFAS regulatory pressure are spawning specialized demand pockets outside incumbent chemical conglomerate dominance.
For Market Incumbents: Pre-empt non-fluorinated electrolyte qualification by accelerating phosphazene-based flame retardant validation ahead of EPA enforcement deadlines. Secure backward integration into lithium salt purification through Nevada black mass recovery partnerships to reduce Asian feedstock dependence. Capacity expansion in Tennessee dry room infrastructure anchors IRA-compliant supply for BlueOval City demand. For New Entrants and Emerging Players: Georgia's electrolyte supply gap around Hyundai Motor Group's Metaplant America and Rivian's planned facility offers greenfield entry with co-location advantages. Kentucky independent gigafactory construction lacks proximate formulator supply, creating white-space for domestic specialists qualifying for DOE loan programs. Target direct long-term offtake contracts bypassing distributor relationships as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward electrolyte specialists with IRA-compliant domestic sourcing and solid-state formulation capabilities positioned for lithium-metal anode commercialization. Five-to-ten year viability hinges on qualification breadth across multiple OEM platforms rather than single-customer concentration. Watch NHTSA thermal runaway certification timelines as the inflection indicator for premium pricing power versus commodity blend competition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Salt Recovery | Nevada black mass processing closes virgin material loops for IRA-compliant supply. |
| Dry Room Infrastructure Expansion | Tennessee and Georgia facilities anchor humidity-controlled blending for automotive qualification. |
| Non-Fluorinated Formulation Development | Phosphazene-based flame retardants preempt EPA PFAS reporting mandate disruption. |
| Direct Long-Term Offtake Contracts | Ford's BlueOval SK consolidated supplier panels reward qualified formulators with volume security. |
| Solid-State Electrolyte Co-Development | SK Innovation's BlueOval City partnerships de-risk sulfide ceramic conductor commercialization. |
Research Methodology
Desk research of SEC 10-K filings, customs and trade data, EPA regulatory dockets, and DOE loan program disclosures preceded structured interviews with electrolyte plant managers, OEM procurement leads at Detroit manufacturers, distribution channel partners, and technical R&D directors at national laboratories. Primary fieldwork with gigafactory operators and chemical formulators combined with secondary validation against NHTSA safety standards and IRA domestic content guidance. Bottom-up electrolyte volume estimates triangulated against top-down automotive production forecasts.
Assumptions held IRA domestic content thresholds and NHTSA thermal runaway certification timelines fixed across the analysis window, while solid-state battery commercialization pace and EPA PFAS enforcement stringency were varied in sensitivity scenarios. Segmentation modeling incorporated formulation type, material chemistry tier, end-use application, and regional production cluster dimensions. CAGRs derived from electrolyte demand per vehicle content trajectories and grid-scale storage procurement pipelines, with lithium salt feedstock pricing and dry room capital costs as key variable inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian chemical conglomerates or accelerated solid-state displacement would shift outcomes substantially. Cross-checking against DOE loan program approval velocity and gigafactory construction timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
China Electric Vehicle Battery Manufacturing Market
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
Power Lithium Battery Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
Lithium Cobalt Oxide Market