
 Canada Horse Riding Equipment Market | 2026-2036
Canada Horse Riding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Horse Riding Equipment Market Insights
Market Context
Alberta's equine producer base is hardening its grip on Canadian saddle and tack output as ranchland consolidation reduces supplier fragmentation. Tailored Equestrian leverages deep leather-craft heritage to dominate premium English-style saddlery out of Ontario's Niagara region. System Equine anchors Western discipline supply chains through Calgary-area manufacturing partnerships with professional rodeo circuits. Horse Gear Canada Ltd. competes on price-accessible synthetic lines distributed through Prairie farm cooperatives and Alberta equestrian centers.
Technical Definition and Segment Structure
Canada horse riding equipment encompasses bridles, saddle pads, stirrups, and horse blankets engineered to rider biomechanics and equine anatomy, with leather goods typically requiring vegetable-tanned hides graded above 1.2 mm thickness for stress-bearing components. This equipment serves competitive show jumping, dressage, rodeo, and recreational trail riding across climatic zones from coastal British Columbia to subarctic Quebec. The product type dimension shows saddle pads and horse blankets commanding the strongest margin pools as climate adaptation drives seasonal replacement cycles, while synthetic material formulations displace leather in amateur segments where maintenance simplicity outweighs traditional aesthetics. Distribution through equine shows captures the highest value-per-transaction channel as trainers and professionals test-fit equipment before purchase, though online retail extends fastest among rural amateurs beyond specialty store catchment areas.
Regulatory Framework and Outlook
Health Canada and the Canadian Food Inspection Agency shape animal welfare standards that propagate into equipment safety requirements, particularly for pressure-distributing tack designs. The Competition Bureau enforces labeling integrity on leather versus synthetic claims, constraining material substitution strategies. ASTM International and Equine Canada safety protocols further filter which helmets and protective gear gain access to insured equestrian facilities. Stakeholders must monitor how provincial veterinary college guidelines on equine back health could tighten saddle fit certification requirements and reshape R&D priorities for pad and tree manufacturers.
Market Dynamics
Alberta's ranchland consolidation is compressing supplier networks while Ontario's leather-craft heritage anchors premium English-style saddlery, creating a bifurcated supply structure that rewards regional specialization over national scale.
Growth Catalysts
- Health Canada animal welfare oversight:Pressure-distributing tack designs gain mandatory traction as veterinary guidelines tighten, forcing equipment upgrades across insured equestrian facilities.
- Synthetic material substitution:Weather-resistant polymer formulations displace vegetable-tanned leather in amateur segments where maintenance simplicity outweighs traditional aesthetics.
- Calgary-Okotoks corridor density:Professional rodeo circuits and ranching operations sustain premium equipment turnover through concentrated show-season demand.
Market Restraints
- Hide grade scarcity:Vegetable-tanned hides above 1.2 mm thickness face sourcing constraints from declining North American cattle processing volumes.
- Alberta supplier concentration:Ranchland consolidation reduces fragmentation, creating single-source vulnerability for Western discipline supply chains.
- Competition Bureau labeling enforcement:Material substitution strategies face compliance friction as synthetic-versus-leather claims trigger verification costs.
Strategic Opportunities
- Quebec subarctic climate adaptation:Seasonal replacement cycles for horse blankets and pads accelerate as temperature volatility intensifies, opening margin-rich recurring revenue.
- Equine Canada safety protocol alignment:Helmet and protective gear certification creates barrier-to-entry advantages for compliant manufacturers.
- Online retail channel extension:Rural amateurs beyond specialty store catchment areas shift to direct-to-rider fulfillment, compressing distributor capture.
Industry Challenges
- Saddle fit certification complexity:Provincial veterinary college guidelines on equine back health threaten to mandate fitter training programs, raising service delivery costs.
- Biomechanical R&D capex:Pressure-mapping and tree-design investments strain mid-tier manufacturers without rodeo circuit partnerships.
- ASTM International protocol lag:Cross-border helmet standard harmonization delays product launches for dual-certified equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Horse Riding Equipment Market |
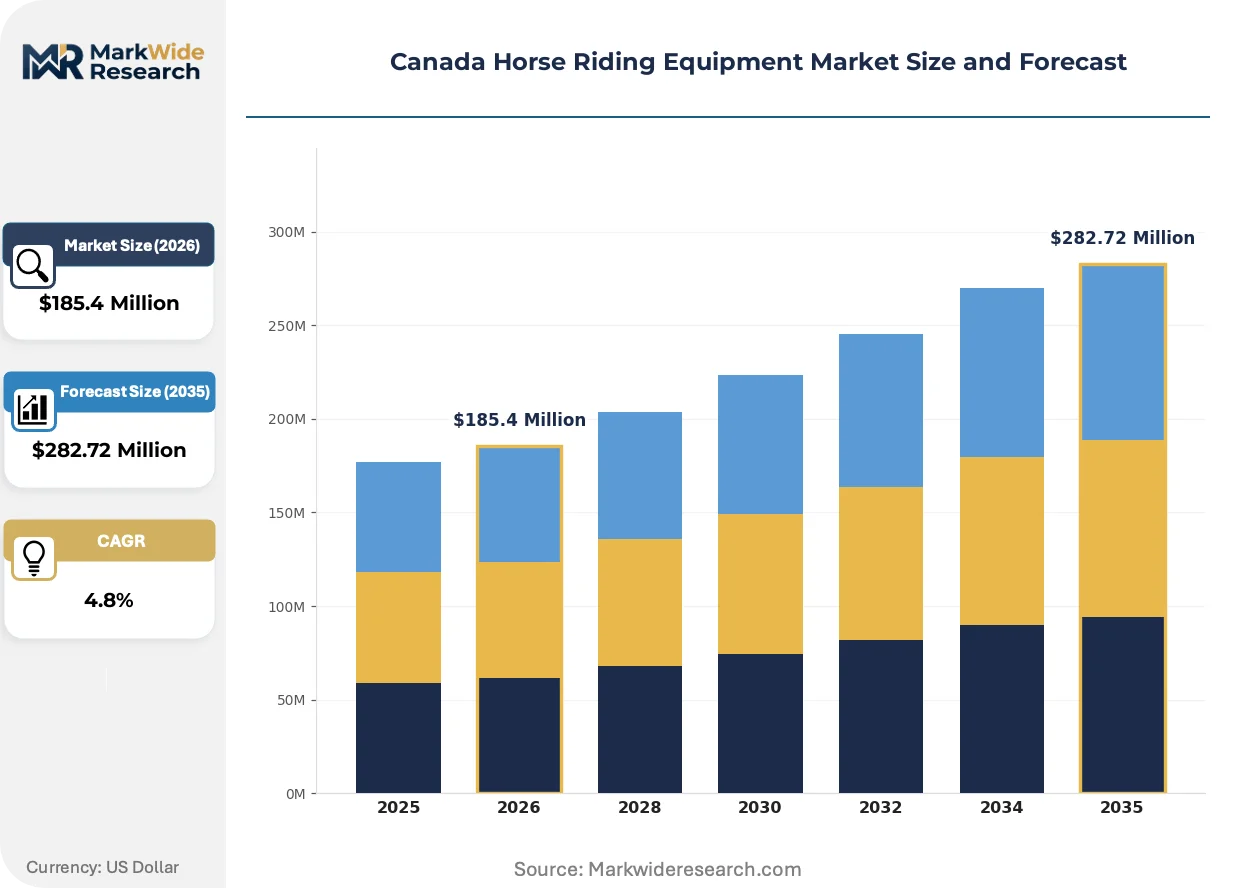
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $282.72 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bridles, Saddle Pads, Stirrups, Horse Blankets End User: Amateurs, Professionals, Trainers, Equestrian Centers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Equine Shows Material: Leather, Synthetic, Cotton, Neoprene |
| Companies Covered | Tailored Equestrian, Shires Equestrian, System Equine, Flex-On, JPC Equestrian, Centurion Supply Inc., Horse Pilot, Kevin Bacon's, Horse Gear Canada Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Horse Riding Equipment Market Trends and Innovations
Material science breakthroughs and regulatory tightening are rewiring how Canadian manufacturers compete, with climate adaptation and safety certification emerging as the primary axes of differentiation.
Smart saddle pad sensor integration is electrifying competitive positioning among Ontario-based English-style manufacturers. Amateur dressage riders in the Niagara region adopt pressure-mapping inserts at accelerating rates. This convergence of wearable tech and traditional tack is electrifying premium pricing tiers while compressing margins for undifferentiated leather goods.
Health Canada's expanding oversight of animal welfare products is propagating into equipment safety mandates. Pressure-distributing tree designs now face pre-market scrutiny that delays launch timelines by six to nine months. Saddle pad and tree manufacturers in Alberta and Ontario are responding by embedding veterinary consultation into R&D workflows.
Trainer-led test-fit purchasing at equine shows is ceding ground to digital channel migration among recreational riders. Rural amateurs in Prairie provinces now initiate equipment searches through cooperative-affiliated platforms before visiting physical centers. British Columbia's coastal trail-riding communities exhibit the sharpest behavioral shift, with seasonal gear replacement increasingly managed through subscription-style replenishment programs.
Canada Horse Riding Equipment Market Segmentation
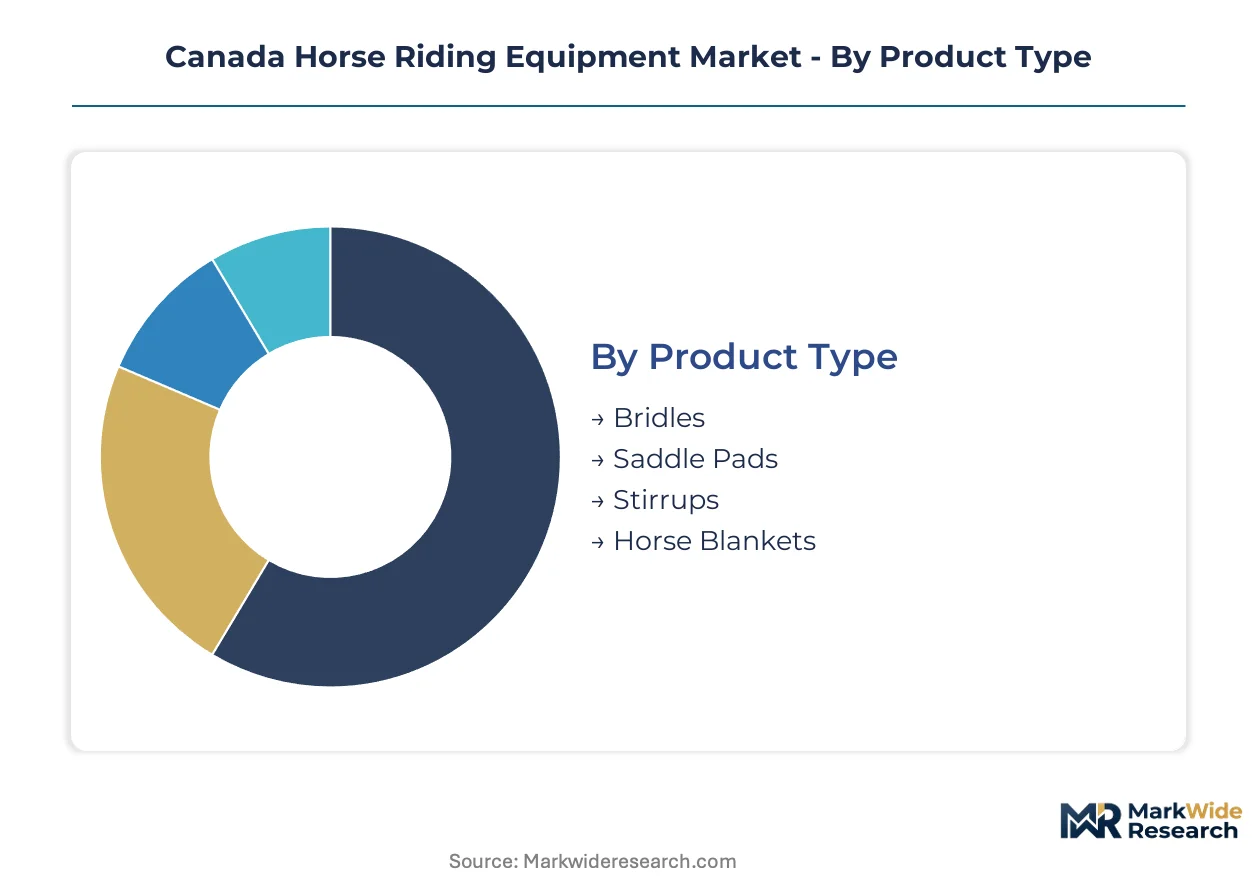
Segmentation in Canadian horse riding equipment reveals how climatic extremes and discipline-specific demands fragment purchasing behavior. Manufacturers must calibrate material durability, distribution reach, and price positioning across distinct rider profiles and geographic conditions.
Product Type:
Volume concentrates in consumable, climate-driven categories while premium margins attach to biomechanically complex equipment with longer replacement cycles.
- Saddle Pads:Engineered with moisture-wicking base layers and contoured spine clearance to distribute rider weight across the equine back. Demand clusters in Alberta's Calgary-Okotoks corridor where competitive circuits mandate frequent replacement to maintain veterinary compliance. Health Canada pressure-distribution guidelines are forcing upgrades across insured facilities.
- Horse Blankets:Constructed with denier-rated outer shells and adjustable belly bands for subarctic temperature swings. Quebec's volatile winters drive the steepest expansion trajectory as seasonal replacement cycles compress from biannual to quarterly in some stables.
- Bridles:Vegetable-tanned leather or beta-biotane synthetic constructions with anatomical crown and noseband shaping. Ontario's Niagara region English-style specialists dominate premium leather supply.
- Stirrups:Aluminum alloy or polymer composite frames with tread grip patterns matched to discipline. Western rodeo circuits in Alberta favor heavier traditional irons.
Today's leader: Horse Blankets. Tomorrow's challenger: Saddle Pads.
End User:
Professional and institutional buyers anchor premium pricing while amateur volume sustains manufacturer throughput across Prairie distribution networks.
- Professionals:Competitive riders and licensed coaches requiring ASTM International and Equine Canada certified protective gear. Equipment decisions follow veterinary consultation and insurance facility mandates.
- Equestrian Centers:Commercial stables purchasing standardized tack inventories with volume pricing and maintenance service contracts. Concentrated in Alberta ranching corridors and Ontario recreational zones.
- Trainers:Independent coaches sourcing discipline-specific equipment for client instruction. Test-fit purchasing at equine shows dominates procurement patterns.
- Amateurs:Recreational riders prioritizing maintenance simplicity and price accessibility. British Columbia coastal communities and Prairie rural areas shift fastest toward online cooperative platforms.
Professionals command margin. Amateurs command volume.
Distribution Channel:
Channel selection reflects the tension between tactile evaluation requirements and geographic accessibility constraints across Canada's dispersed population.
- Equine Shows:Trainer-led test-fit purchasing with highest value-per-transaction ratios. Alberta rodeo circuits and Ontario dressage circuits sustain concentrated seasonal demand.
- Online Retail:Direct-to-rider fulfillment accelerating among rural amateurs beyond specialty store catchment areas. Prairie farm cooperatives operate affiliated platforms.
- Specialty Stores:Brick-and-mortar centers with saddle fitter services and veterinary consultation partnerships. Niagara region and Calgary-Okotoks corridor maintain densest presence.
- Department Stores:Limited entry-level synthetic lines targeting casual recreational riders. Margins compressed by inventory turnover requirements.
Physical inspection still wins at the top. Digital convenience is climbing fastest.
Material:
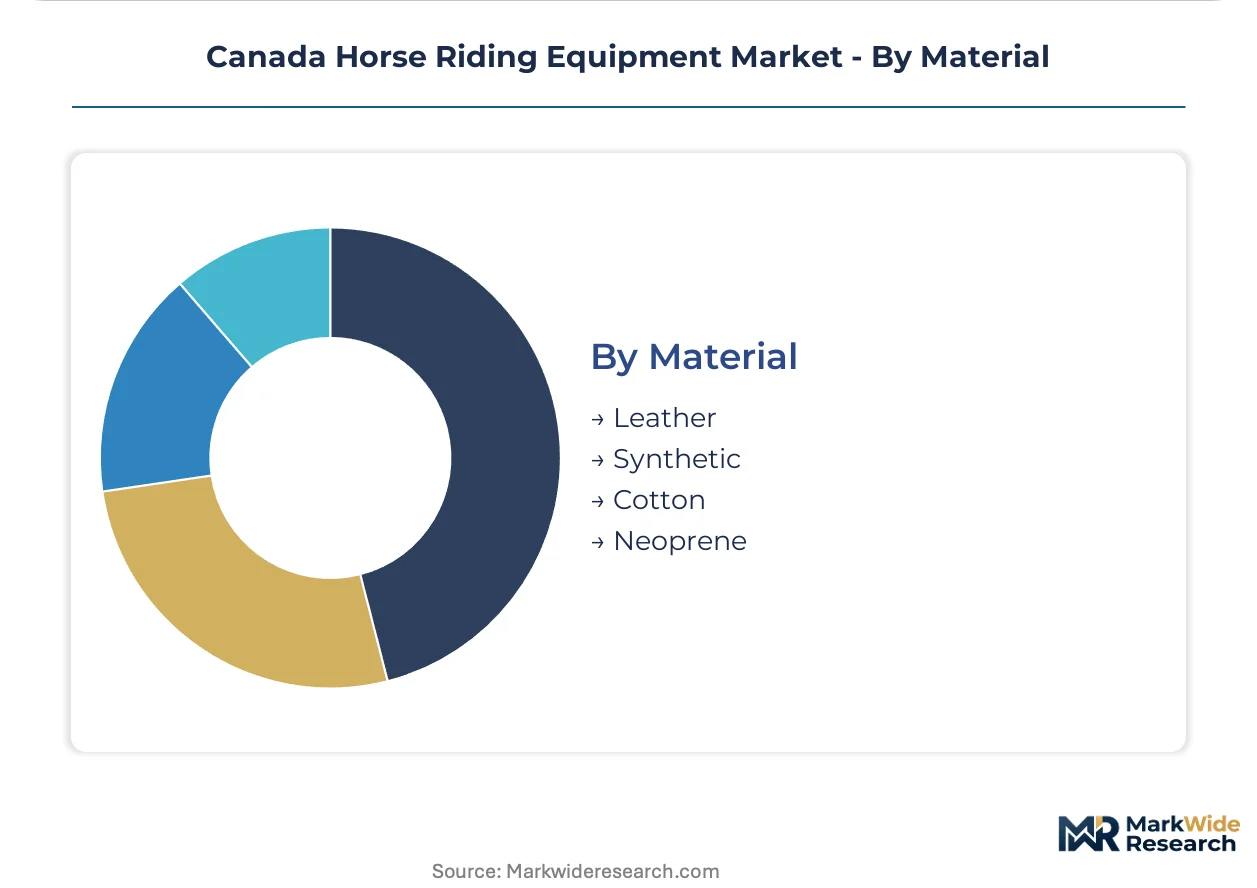
Substitution dynamics between traditional and engineered materials reshape competitive positioning as maintenance expectations and regulatory scrutiny intensify.
- Synthetic:Polymer and beta-biotane formulations offering weather resistance and washability. Displacing leather fastest in amateur segments where maintenance simplicity outweighs traditional aesthetics.
- Leather:Vegetable-tanned hides graded above 1.2 mm thickness for stress-bearing components. Ontario leather-craft heritage anchors premium English-style saddlery supply.
- Neoprene:Closed-cell synthetic rubber providing cushioning and grip in girth and boot applications. Favored in Western discipline equipment for durability.
- Cotton:Natural fiber base layers and quilted pad linings with breathable properties. Seasonal demand spikes align with summer trail riding in British Columbia.
Synthetics capture share. Leather defends premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are minimal across Canadian provinces given harmonized federal standards, yet cost-of-compliance gaps emerge where provincial veterinary college guidelines diverge on saddle fit certification. Equipment manufacturers track these sub-national variations to optimize service delivery footprints.
Ontario
Niagara region leather-craft heritage anchors premium English-style saddlery production for dressage and show jumping disciplines. Health Canada oversight of animal welfare products propagates into mandatory pressure-distribution standards for insured equestrian facilities. Toronto-area equestrian centers concentrate procurement volume through trainer-led purchasing cooperatives.
Alberta
Calgary-Okotoks corridor density sustains premium equipment turnover through professional rodeo circuit partnerships and consolidated ranchland operations. Provincial veterinary college guidelines on equine back health are tightening saddle fit certification requirements for commercial stables. Edmonton-area manufacturing partnerships supply Western discipline tack to Prairie distribution networks.
Quebec
Subarctic temperature volatility accelerates seasonal replacement cycles for horse blankets and climate-adaptive pad systems. Canadian Food Inspection Agency animal welfare standards shape import compliance for European synthetic material suppliers. Montreal-area recreational stables drive volume demand through cooperative purchasing platforms.
British Columbia
Coastal trail-riding communities exhibit the sharpest digital channel migration, with subscription-style replenishment programs displacing traditional equine show procurement. Health Canada labeling enforcement on leather versus synthetic claims constrains material substitution strategies for Vancouver-area retailers. Interior ranching operations maintain conventional trainer-led test-fit purchasing patterns.
Canada Horse Riding Equipment Market Competitive Landscape
Ontario producers anchor premium English-style saddlery tier; Alberta specialists hold Western discipline supply chains through rodeo circuit partnerships. Market structure bifurcates along regional craft traditions rather than consolidating around national scale players. Three archetypes dominate: heritage leather-craft houses, synthetic material specialists, and rodeo-aligned Western equipment fabricators. Competitive moves concentrate on provincial veterinary consultation partnerships and digital channel migration for rural amateur segments.
Within the heritage leather-craft tier, Tailored Equestrian and Shires Equestrian occupy positions exemplifying Niagara region English-style specialization. System Equine represents the Western discipline archetype through Calgary-area manufacturing alignment. Horse Gear Canada Ltd. anchors the synthetic material specialist position serving Prairie cooperative networks. These named entities illustrate how regional craft traditions and material science capabilities stratify competitive positioning without national market consolidation.
| Leading Market Players |
|---|
| Tailored Equestrian |
| Shires Equestrian |
| System Equine |
| Flex-On |
| JPC Equestrian |
| Centurion Supply Inc. |
| Horse Pilot |
| Kevin Bacon's |
| Horse Gear Canada Ltd. |
| Others |
Pricing and Supply Chain Analysis
Health Canada pressure-distribution mandates for insured equestrian facilities are forcing equipment upgrades across Ontario and Alberta, compelling manufacturers to absorb veterinary consultation costs into R&D workflows and compressing margins on mid-tier synthetic lines.
Pricing Analysis
Distributor margin capture runs deepest through equine show channels where trainer-led test-fit purchasing commands premium positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and material origin, with vegetable-tanned leather goods defending premium tiers against polymer displacement. Cost compression in synthetic amateur segments is intensifying because Prairie cooperative platforms consolidate procurement volume. Amateur recreational riders in British Columbia exhibit highest price sensitivity, while professional rodeo circuits in Alberta tolerate elevated pricing for biomechanically certified equipment.
Supply Chain Analysis
Single-source vulnerability sits with North American vegetable-tanned hide suppliers as cattle processing volumes decline. Manufacturing draws from Ontario leather-craft heritage for English-style saddlery and Alberta polymer formulation partnerships for Western discipline synthetics. Supply chain risk centers on tariff exposure for European synthetic material imports subject to Canadian Food Inspection Agency compliance verification. Distribution feeds from Calgary-Okotoks manufacturing partnerships through Prairie farm cooperatives and Niagara-region specialty store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory layering, with Health Canada animal welfare oversight propagating into mandatory equipment upgrade cycles across insured facilities.
For Market Incumbents: Deepen veterinary consultation partnerships in Ontario and Alberta to pre-empt provincial saddle fit certification mandates. Anchor capacity control through captive leather-craft operations in Niagara region, defending against synthetic substitution pressure from Prairie cooperative distributors. Prioritize ASTM International dual-certification investments to lock out cross-border competitors facing harmonization delays. For New Entrants and Emerging Players: Launch via subscription-style replenishment programs targeting British Columbia coastal trail-riding communities where digital procurement behavior shifts fastest. Penetrate Quebec subarctic climate adaptation segment through horse blanket seasonal replacement cycles. Exploit underdeveloped online cooperative platforms in Prairie rural amateur segments beyond Calgary-Okotoks corridor density. For Investors and Strategic Acquirers: Asymmetric upside sits with synthetic material specialists possessing Health Canada pre-market consultation relationships. Long-term viability hinges on regulatory compounder dynamics where veterinary guideline tightening accelerates replacement demand. Target acquisition archetype: mid-tier manufacturers with rodeo circuit partnerships and unexploited digital channel infrastructure. Watch for provincial veterinary college saddle fit certification mandates as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Consultation Partnership | Pre-empts Health Canada pre-market scrutiny delays by embedding regulatory expertise into R&D workflows. |
| Synthetic Material R&D Investment | Captures amateur segment volume as beta-biotane formulations displace vegetable-tanned leather maintenance burdens. |
| Digital Channel Infrastructure Buildout | Compresses distributor capture among British Columbia and Prairie rural amateurs shifting to direct fulfillment. |
| Provincial Certification Pre-Compliance | Creates barrier-to-entry advantage as Alberta and Ontario veterinary colleges tighten saddle fit standards. |
| Rodeo Circuit Manufacturing Alignment | Secures premium equipment turnover through Calgary-Okotoks professional show-season demand concentration. |
Research Methodology
Bottom-up equestrian center and trainer procurement modeling reconciled against top-down manufacturing output tracking forms the analytical core. Primary interviews with saddle fitters, veterinary college guideline drafters, cooperative procurement managers, and rodeo circuit equipment officers combined with secondary validation from Equine Canada safety protocol filings, Health Canada animal welfare product registrations, and Prairie agricultural cooperative sales records. Triangulation across demand-side purchasing patterns and supply-side production footprints anchors volume estimates.
Historical trendline analysis of replacement cycle compression in Quebec subarctic climates and synthetic material substitution rates across amateur segments informed projection parameters. Segmentation dimensions span product type, end user archetype, distribution channel, and material formulation across the analysis window. CAGRs derive from discipline-specific participation trajectories and regulatory mandate propagation timelines, with climate volatility indices and veterinary guideline adoption curves as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under provincial veterinary college guideline divergence or hide supply disruption scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Cattle Supplies Market
Livestock Equipment
Europe Livestock Monitoring Market
Livestock Equipment
Livestock Trailers Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Automatic Cattle Waterer Market
Livestock Equipment
Poultry Feeder Market
Livestock Equipment
Cattle Feeder Panels Market
Livestock Equipment
Animal Cage Market
Livestock Equipment
Sheep Supplies Market
Livestock Equipment
Bird Feeding and Watering Suppliers Market
Livestock Equipment
Horse Bunk Feeder Market
Livestock Equipment
Automatic Hog Feeder Market
Livestock Equipment
Nigeria Horse Riding Equipment Market
Livestock Equipment
Chicken Coop Market
Livestock Equipment
Slaughtering Equipment Market