
 Asia Pacific Smart Transformers Market | 2026-2036
Asia Pacific Smart Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Smart Transformers Market Outlook
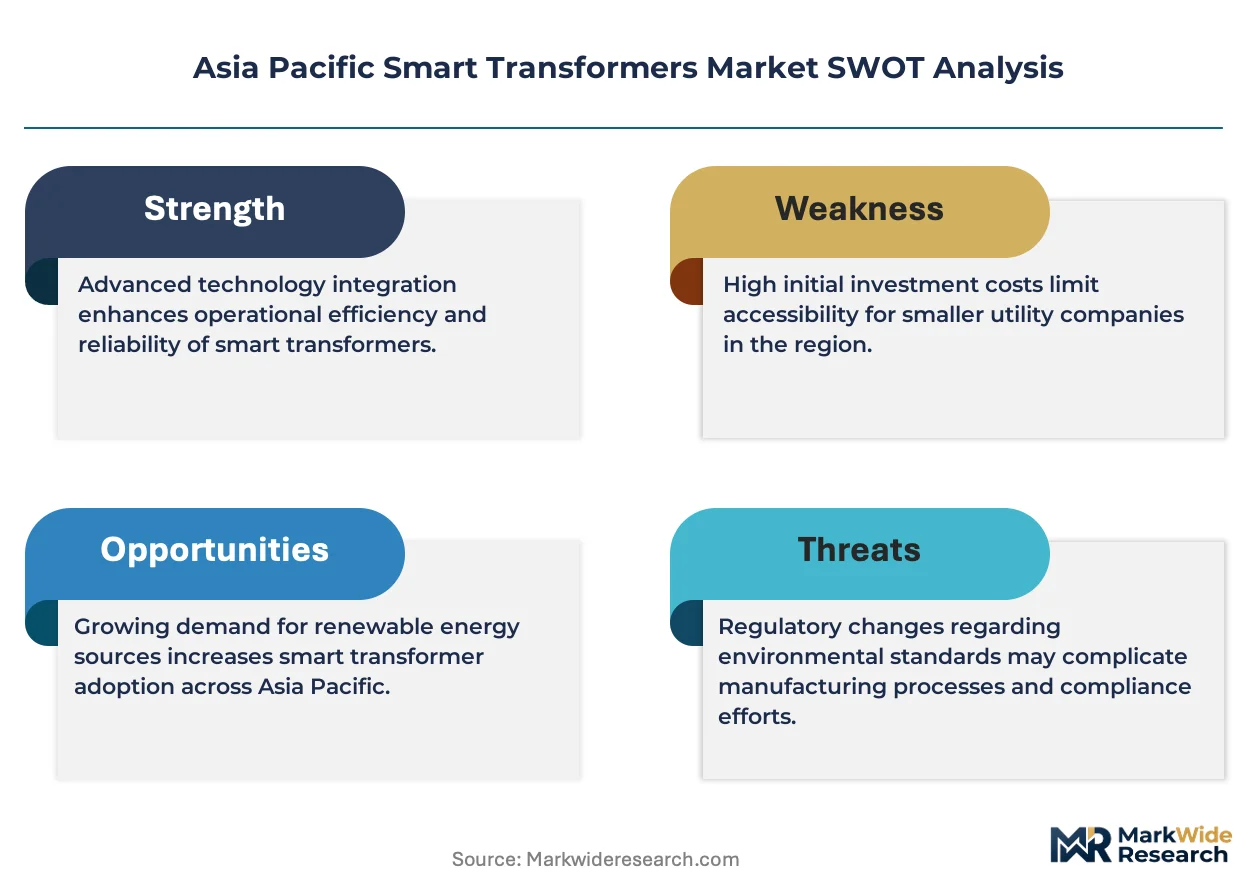
Software-defined voltage regulation is recalibrating what utilities purchase, shifting capital from hardware-only procurement to bundled digital service contracts. Hitachi Ltd leverages its IoT platform heritage to anchor premium positioning in Japan's utility modernization wave. ABB Ltd sustains competitive density through deep specialization in hybrid control architectures for high-renewable grids. Schneider Electric SE differentiates via channel control across Southeast Asian markets where local integration capability determines contract outcomes.
Asia Pacific smart transformers are intelligent power conditioning apparatuses that incorporate embedded sensors, digital control modules, and two-way communication interfaces to enable real-time load balancing, fault isolation, and predictive maintenance across medium-voltage distribution networks. These units typically operate at 11-33 kV class with IEC 60076-7 thermal monitoring compliance, serving primarily to stabilize voltage quality amid rising photovoltaic and wind penetration. Distribution transformers occupy the dominant revenue position due to massive fleet replacement cycles across aging Asia Pacific grids, while digital control technology commands the fastest expansion trajectory as utilities mandate remote operability for new installations. Step-down transformers retain mature volume status but face margin compression from commoditized analog variants, whereas hybrid control systems capture concentrated margin pools by bridging legacy analog infrastructure with modern SCADA integration.
India's CEA mandates smart metering and grid digitalization timelines that directly accelerate transformer procurement with embedded monitoring capability, while China's GB standards under MIIT enforce efficiency tiers that disqualify conventional silicon-steel designs from state grid tenders. Japan's METI circular economy directives for electrical equipment extend product lifecycle accountability back to manufacturers, reshaping R&D allocation toward modular, upgradeable platforms. Stakeholders must monitor how Australia's AEMO integrates distributed energy resource standards with transformer interoperability requirements, as this will determine which control technology architectures achieve cross-border scale in the region.
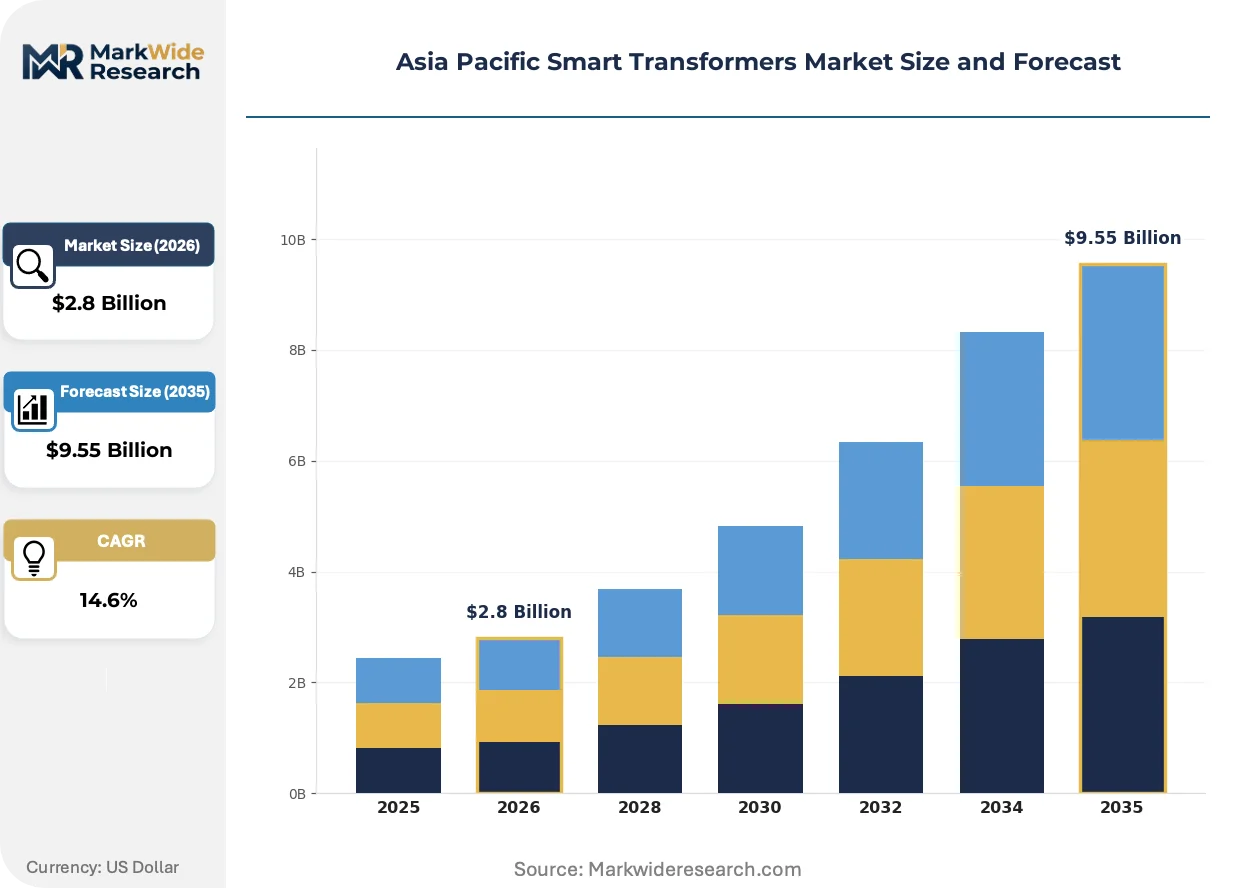
Market Dynamics
Software-defined voltage regulation is compressing hardware margins while expanding recurring revenue pools for integrated digital service providers across Asia Pacific distribution grids.
Growth Catalysts
- India's PLI scheme for power sector manufacturing:Production-linked incentives redirect domestic capital toward intelligent transformer assembly, accelerating local capacity for digitally monitored grid assets.
- Embedded thermal monitoring systems:IEC 60076-7 compliance mandates are forcing fleet replacement cycles across aging Southeast Asian substations, pulling sensor-equipped units into procurement pipelines.
- China's dual carbon goals:State Grid Corporation tenders now disqualify conventional silicon-steel designs, channeling procurement toward efficiency-tiered intelligent distribution infrastructure.
Market Restraints
- Grain-oriented electrical steel concentration:Japanese and South Korean mills control premium core material supply, exposing transformer manufacturers to input cost volatility and allocation constraints.
- Legacy SCADA protocol fragmentation:Proprietary communication standards from incumbent automation vendors create technical lock-in, complicating interoperability for new digital control modules.
- Extended type-approval timelines:India's BIS certification for intelligent electrical equipment stretches 14-18 months, delaying commercialization of upgraded monitoring platforms.
Strategic Opportunities
- Vietnam's central highlands wind corridors:Underpenetrated renewable zones lack grid-stabilizing infrastructure, creating first-mover positioning for hybrid control architectures.
- Edge computing convergence with transformer-mounted sensors:Real-time analytics at the distribution node enables predictive maintenance contracts, shifting revenue from unit sales to performance guarantees.
- Australia's AEMO distributed energy resource standards:Interoperability mandates for DER-connected transformers open specification windows for control technology architectures with cross-border scale potential.
Industry Challenges
- Power systems cyber-physical engineering talent:Scarce expertise in both electrical protection and network security constrains deployment velocity for digitally intensive substation projects.
- Legacy analog infrastructure integration:Retrofitting 1980s-era distribution transformers with two-way communication interfaces demands custom engineering, eroding project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Smart Transformers Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step-Up Transformers, Step-Down Transformers, Isolation Transformers, Distribution Transformers End User: Utilities, Industrial, Commercial, Residential Installation Type: Outdoor, Indoor, Mobile, Compact Control Technology: Digital Control, Analog Control, Hybrid Control, Remote Monitoring |
| Companies Covered | Eaton Corporation PLC, Hitachi Ltd, ABB Ltd, Alstom, Crompton Greaves, Siemens AG, General Electric Company, State Grid Corporation of China, Schneider Electric SE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Smart Transformers Market Strategic Shifts
Digital twin simulation is compressing design-validation cycles while enabling utilities to model transformer fleet performance under variable renewable penetration scenarios before capital deployment.
Silicon carbide power semiconductors in solid-state transformer prototypes is electrifying medium-voltage distribution architectures by enabling bidirectional power flow and sub-cycle voltage regulation. Japanese utilities in Tokyo and Osaka are piloting these units for data center microgrid integration. The technology is electrifying competitive positioning by collapsing the functional boundary between power conditioning and grid automation.
China's GB standards under MIIT are enforcing efficiency tiers that disqualify conventional silicon-steel designs from state grid tenders, compressing demand toward amorphous metal core and advanced laminated configurations. Domestic manufacturers are reconfiguring production lines to capture premium-tier qualification. High-renewable provinces including Inner Mongolia and Gansu face the steepest compliance deadlines.
State discoms in India's western industrial corridor from Gujarat to Maharashtra are unbundling transformer procurement from engineering-procurement-construction contracts, creating direct vendor relationships for digital control modules. System integrators are losing gatekeeper status as utilities build in-house specification expertise. This pattern is most visible in Maharashtra State Electricity Distribution Company's ongoing substation modernization program.
Asia Pacific Smart Transformers Market Segmentation
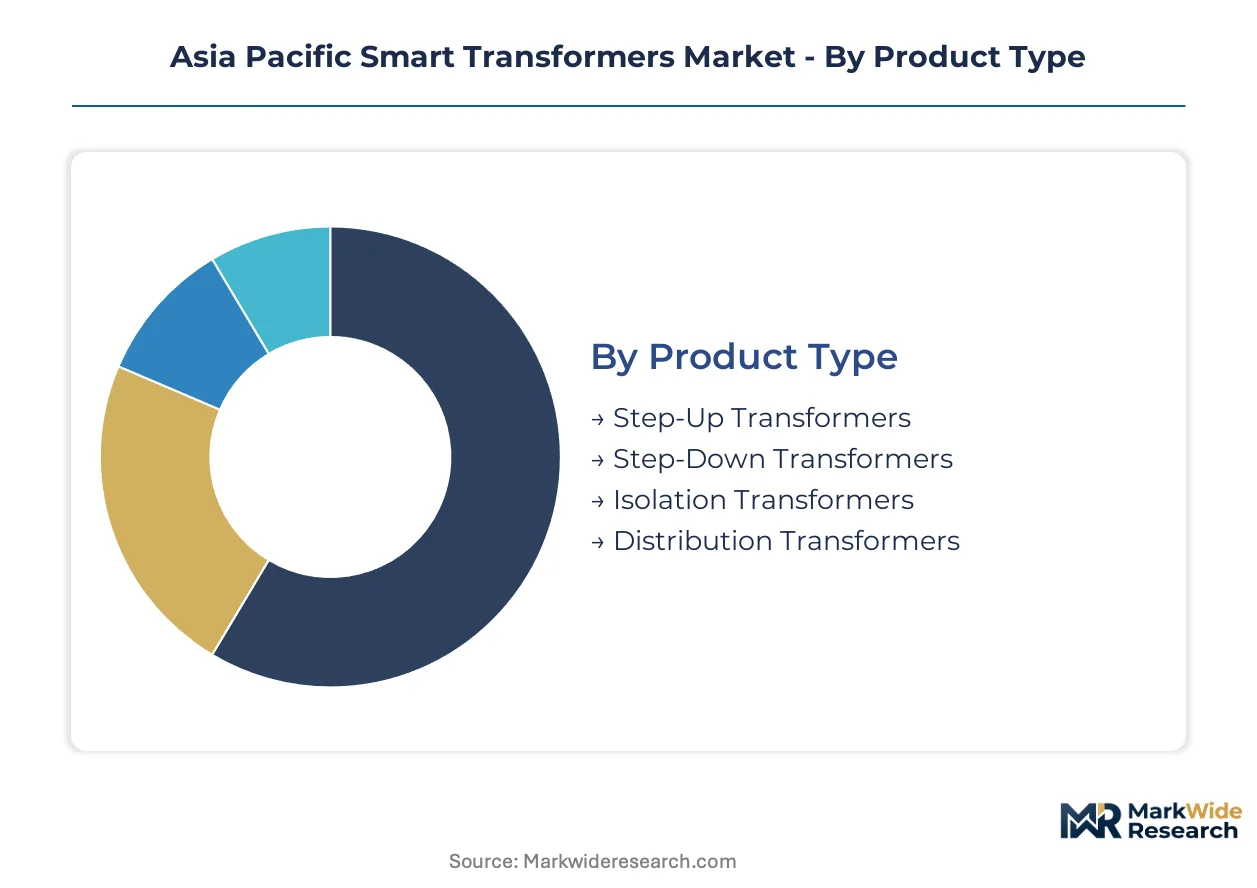
Smart transformer procurement patterns diverge sharply across voltage classes and end-use applications, with utility buyers prioritizing remote operability while industrial customers emphasize power quality assurance. Understanding these segment boundaries reveals where control technology premiums command pricing power versus where hardware commoditization dominates.
Product Type:
Core material sourcing and winding specifications cluster around regional steel mill capabilities, with grain-oriented electrical steel availability shaping transformer design economics.
- Distribution Transformers:These 11-33 kV class units incorporate embedded thermal sensors and IEC 60076-7 compliant monitoring modules. Demand concentrates across India's western industrial corridor from Gujarat to Maharashtra, where state discoms are modernizing aging substations under CEA-mandated digitalization timelines.
- Step-Down Transformers:Voltage reduction units for medium-voltage distribution networks face margin compression from commoditized analog variants. Procurement volumes remain substantial across Southeast Asian utilities, though price competition from regional manufacturers erodes profitability.
- Step-Up Transformers:Voltage elevation equipment for renewable integration projects requires specialized insulation systems.
- Isolation Transformers:Galvanic separation units serve niche industrial power quality applications.
Distribution transformers absorb the bulk of installed capacity; digital control modules are expanding most quickly within new procurement specifications.
End User:
Customer sophistication tiers separate specification complexity, with integrated utilities demanding bundled digital service contracts while commercial buyers prioritize capital efficiency.
- Utilities:State Grid Corporation tenders and India's state discoms mandate embedded monitoring capability, creating concentrated demand for intelligent distribution infrastructure. Procurement unbundling from EPC contracts in Maharashtra and Gujarat enables direct vendor relationships for control modules.
- Industrial:Manufacturing facilities across Vietnam's central highlands wind corridors require grid-stabilizing equipment with predictive maintenance interfaces. Power quality sensitivity drives premium positioning for hybrid control architectures.
- Commercial:Data center operators in Tokyo and Osaka pilot solid-state transformer prototypes for microgrid integration.
- Residential:Smart meter deployment creates downstream demand for distribution-level voltage regulation.
Utility procurement dominates absolute volume; industrial applications are climbing the fastest as renewable penetration destabilizes legacy distribution networks.
Installation Type:
Physical deployment constraints vary with population density and land availability, with urban substations demanding space-optimized configurations.
- Outdoor:Open-air installations accommodate large-scale distribution transformers across rural and suburban networks, with weatherproofing specifications varying by coastal versus inland exposure.
- Indoor:Enclosed substations in dense urban environments require compact designs with enhanced fire safety ratings.
- Mobile:Trailer-mounted units serve temporary construction sites and emergency restoration.
- Compact:Space-constrained urban installations demand reduced footprint through advanced cooling systems.
Outdoor installations retain the largest installed base; compact configurations are gaining share fastest in metropolitan grid densification projects.
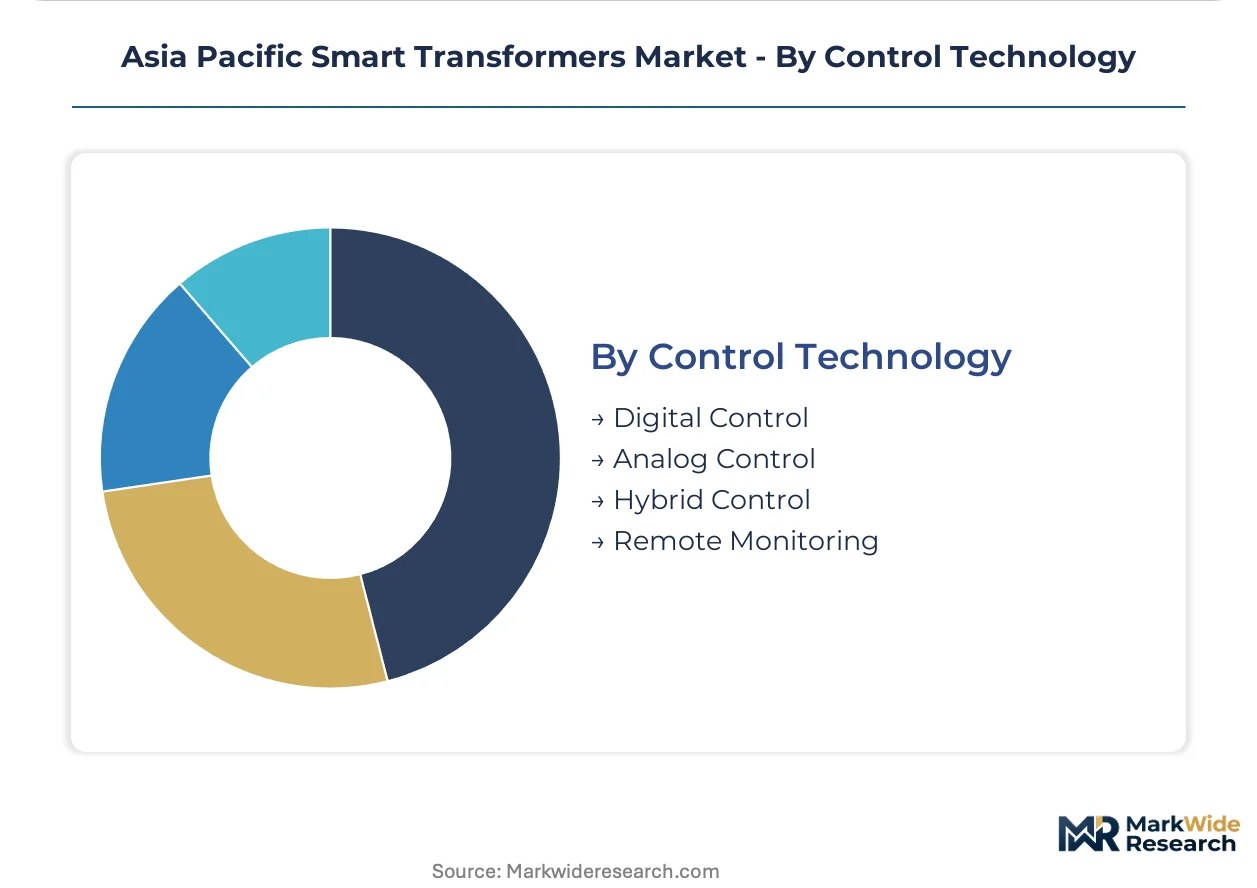
Control Technology:
Software-defined functionality is displacing hardware-only procurement, with communication protocol compatibility determining vendor selection.
- Digital Control:Embedded microprocessor platforms enable real-time load balancing and fault isolation through two-way SCADA interfaces. Australia's AEMO distributed energy resource standards are driving interoperability requirements that favor open-architecture digital systems.
- Hybrid Control:Bridging architectures connect legacy analog infrastructure with modern SCADA integration, capturing concentrated margin pools in retrofit applications across aging Asia Pacific grids.
- Remote Monitoring:Telemetry-enabled units support predictive maintenance contracts and performance-based service agreements.
- Analog Control:Conventional electromechanical regulation faces disqualification from state grid tenders under China's GB efficiency standards.
Hybrid control systems anchor current revenue concentration; fully digital platforms are expanding most quickly as greenfield installations dominate procurement pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's western industrial corridor from Mumbai to Pune anchors Asia Pacific smart transformer procurement intensity, where state discoms unbundle substation modernization from EPC contracts and establish direct vendor relationships for digital control modules.
China
State Grid Corporation tenders now disqualify conventional silicon-steel designs under MIIT's GB efficiency standards, channeling procurement toward amorphous metal core configurations. High-renewable provinces including Inner Mongolia and Gansu face the steepest compliance deadlines for intelligent distribution infrastructure.
India
CEA-mandated digitalization timelines accelerate transformer procurement with embedded IEC 60076-7 thermal monitoring across Gujarat and Maharashtra state discoms. Maharashtra State Electricity Distribution Company's ongoing substation modernization program exemplifies procurement unbundling from engineering-procurement-construction contracts.
Japan
METI circular economy directives extend electrical equipment lifecycle accountability back to manufacturers, reshaping R&D allocation toward modular upgradeable platforms. Tokyo and Osaka utilities pilot solid-state transformer prototypes for data center microgrid integration.
Vietnam
Central highlands wind corridors lack grid-stabilizing infrastructure, creating first-mover positioning for hybrid control architectures. Manufacturing facilities across these renewable zones require predictive maintenance interfaces as photovoltaic and wind penetration destabilizes legacy distribution networks.
Australia
AEMO distributed energy resource standards drive interoperability requirements for DER-connected transformers, opening specification windows for control technology architectures with cross-border scale potential. Edge computing convergence with transformer-mounted sensors enables real-time analytics at distribution nodes.
Asia Pacific Smart Transformers Market Competitive Environment
Capital-heavy producers compete with asset-light designers across Asia Pacific smart transformer procurement, creating a tiered structure where integrated conglomerates anchor premium positioning while regional specialists capture retrofit margin pools. Three strategic archetypes dominate: diversified electrical equipment conglomerates with IoT platform heritage, pure-play transformer manufacturers with deep core material sourcing relationships, and automation specialists bridging legacy SCADA with digital control modules. Dominant competitive moves include backward integration into grain-oriented electrical steel supply chains and strategic partnerships with state grid utilities for pilot deployment programs.
Among diversified electrical equipment conglomerates, Hitachi Ltd and ABB Ltd occupy positions representing hybrid control architecture specialization and premium digital service bundling respectively. Schneider Electric SE exemplifies channel control archetypes across Southeast Asian markets where local integration capability determines contract outcomes. These three anchors illustrate how competitive positioning separates platform-integrated players from component suppliers in utility procurement decisions.
| Leading Market Players |
|---|
| Eaton Corporation PLC |
| Hitachi Ltd |
| ABB Ltd |
| Alstom |
| Crompton Greaves |
| Siemens AG |
| General Electric Company |
| State Grid Corporation of China |
| Schneider Electric SE |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals under MIIT's GB efficiency standards gate qualified supply for premium-tier transformer procurement, restricting state grid tender access to manufacturers with amorphous metal core capability and IEC 60076-7 thermal monitoring compliance. This environmental mandate compresses hardware margins for conventional silicon-steel producers while elevating pricing power for digital service bundling among qualified vendors.
Pricing Analysis
Performance-based service contracts anchor value-based pricing for uptime-guaranteed transformer fleets across Asia Pacific utilities. Three-tier pricing structure across premium, standard, and economy levels separates digital control module bundling from hardware-only procurement. Cost compression in analog step-down variants intensifies because regional manufacturers flood Southeast Asian tenders with commoditized units. Industrial buyers in Vietnam's wind corridors demonstrate least price sensitivity due to power quality requirements, while state discoms in India exhibit highest sensitivity amid unbundled procurement mandates.
Supply Chain Analysis
Container freight volatility from Japanese and South Korean grain-oriented electrical steel mills amplifies landed cost uncertainty for core material-dependent manufacturers. Supply concentrates in China, Japan, and South Korea for amorphous metal ribbon and advanced laminated steel. Transformer production draws from grain-oriented electrical steel, copper winding stock, and silicon carbide semiconductors. Single-source vulnerability concentrates in premium core material allocation from Nippon Steel and POSCO. Distribution runs through state grid tender platforms and direct vendor relationships with unbundled procurement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around digital control capability as China's GB standards and India's CEA mandates disqualify analog-only suppliers, forcing weaker hardware-centric players toward exit or acquisition.
For Market Incumbents: Extend hybrid control architecture specialization to capture retrofit margin pools across aging Southeast Asian grids. State discoms unbundling procurement from EPC contracts in Maharashtra and Gujarat threaten traditional system integrator gatekeepers. Backward integration into grain-oriented electrical steel supply chains secures allocation priority amid Japanese and South Korean mill concentration. For New Entrants and Emerging Players: Regional EPC contractors with state utility relationships offer the fastest channel access for digital control module vendors lacking established tender track records. Vietnam's central highlands wind corridors present the most penetrable geography for first-mover hybrid control positioning. Target predictive maintenance service contracts to bypass capital-intensive transformer manufacturing barriers. For Investors and Strategic Acquirers: Maharashtra State Electricity Distribution Company's procurement unbundling announcements are the leading indicator that direct vendor relationships will displace EPC-mediated distribution across Indian state discoms. The five-to-ten year viability window favors acquisition of automation specialists bridging legacy SCADA with digital control modules. Monitor BIS certification timeline compression as the inflection signal for commercialization velocity of upgraded monitoring platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Material Supply | Captive grain-oriented electrical steel access insulates margin pressure from Japanese and South Korean mill allocation constraints. |
| Digital Control Module Certification Investment | IEC 60076-7 compliance unlocks premium-tier procurement pipelines across India's CEA-mandated digitalization timelines. |
| Predictive Maintenance Service Platform Launch | Performance-based contracts shift revenue from unit sales to uptime guarantees amid software-defined voltage regulation trends. |
| Hybrid Control Architecture R&D Partnership | Collaboration with Tokyo and Osaka utilities accelerates solid-state transformer prototyping for data center microgrid integration. |
| Regional EPC Contractor Alliance Formation | Channel partnerships with Vietnam and Philippines engineering firms bypass state grid tender barriers for new market entrants. |
Study Parameters
Independent corroboration across utility planning officers, EPC contractor procurement leads, transformer manufacturing executives, and grid operator technical directors underwrites the qualitative findings in this study. Primary fieldwork with state discoms in Gujarat and Maharashtra, alongside distribution transformer OEMs in China and Japan, combined with secondary validation from MIIT GB standard filings, CEA digitalization circulars, State Grid Corporation tender databases, and IEC technical committee documentation. Bottom-up unit economics triangulate against top-down addressable market sizing across voltage class and control technology segments.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions span product type, end user archetype, installation configuration, and control technology sophistication, with additional modeling for regulatory compliance tier and renewable penetration intensity. CAGRs derive from installed base replacement cycles, procurement pipeline analysis, and efficiency standard enforcement timelines. Forecast inputs incorporate grain-oriented electrical steel price indices and BIS certification queue lengths.
Caveats apply where extended type-approval timelines, grain-oriented electrical steel allocation disruptions, or legacy SCADA protocol fragmentation could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement consistency and core material supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Renewable Energy Transformer Market
Transformers
Saudi Arabia Transformer Market
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
Europe Transformer Market
Transformers
Canada Transformer Market
Transformers
Liquid-Immersed Transformers Market
Transformers
Middle East Distribution Transformer Market
Transformers
India Power Transformer Market
Transformers
United States Distribution Transformer Market
Transformers
Neon Transformer Market
Transformers
Green Transformer Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
Oil Filled Transformer Market
Transformers
Distribution Transformer Market
Transformers
US Oil Filled Distribution Transformer Market