
 Solar System in Kuwait Market | 2026-2036
Solar System in Kuwait Market Size, Share, and Industry Trends Forecast 2026-2036
Solar System in Kuwait Market Insights
Buyer concentration among Kuwaiti government entities and national oil companies is hardening as the Ministry of Electricity and Water consolidates procurement authority for renewable energy projects. ACWA Power leverages its independent power producer model to secure long-term offtake agreements in the Kuwaiti market. Kharafi National anchors its position through EPC capabilities and local construction expertise. JinkoSolar Holding Co. Ltd. competes on module cost and manufacturing scale to supply utility-scale installations.
A solar system comprises photovoltaic panels, inverters, mounting structures, and electrical components that convert sunlight into usable electricity through the photovoltaic effect, with crystalline silicon modules typically achieving conversion efficiencies between 18% and 22% in Kuwait's high-irradiance desert conditions. The technology serves Kuwait's primary purpose of reducing fossil fuel dependence for power generation while meeting peak summer cooling loads. Photovoltaic technology dominates current deployments due to modularity and declining unit costs, while battery storage represents the fastest-expanding segment as grid operators seek to manage intermittency from solar generation. Government end users command the largest project volumes through sovereign procurement, though commercial adoption is accelerating among industrial consumers seeking energy cost hedging.
Kuwait's Ministry of Electricity and Water sets renewable energy procurement mandates that shape project development timelines, while the country's national building codes administered by the Public Authority for Housing Welfare increasingly require solar readiness in new construction. The Central Tendering Committee governs competitive bidding processes that determine market access for international equipment suppliers and developers. Stakeholders must monitor how Kuwait's sovereign wealth fund deployment into domestic energy infrastructure reshapes financing structures and local content requirements for solar projects.
Market Dynamics
Kuwait's Ministry of Electricity and Water consolidates procurement authority for renewable energy projects, hardening buyer concentration among government entities and national oil companies while reshaping competitive access for international developers and equipment suppliers.
Growth Catalysts
- Shagaya Renewable Energy Park expansion:The flagship solar complex in Al-Jahra Governorate creates anchor demand for utility-scale photovoltaic installations and establishes technical benchmarks for subsequent projects.
- National building code solar readiness mandates:The Public Authority for Housing Welfare increasingly requires new construction to accommodate photovoltaic integration, expanding addressable market beyond utility procurement.
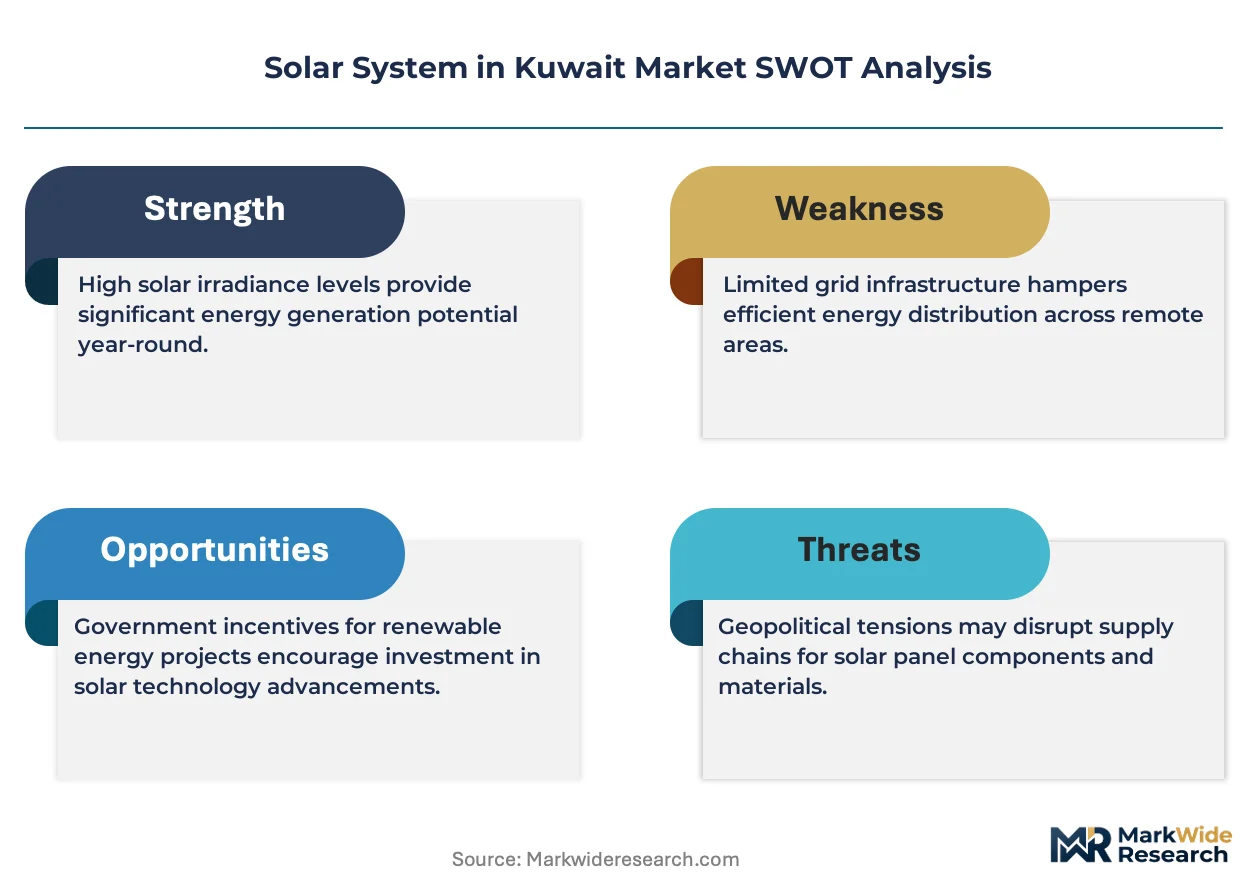
- High irradiance desert conditions:Kuwait's solar resource quality supports capacity factors above global averages, improving project economics for crystalline silicon deployments.
Market Restraints
- Grid interconnection bottlenecks:Limited transmission infrastructure in Al-Ahmadi and Al-Jahra governorates constrains utility-scale project timelines and increases connection costs for developers.
- Petrochemical-linked input cost volatility:Aluminum and polysilicon prices fluctuate with hydrocarbon feedstock markets, compressing module supplier margins and creating EPC pricing uncertainty.
- Desert soiling degradation:Dust accumulation on photovoltaic surfaces reduces energy yield by substantial margins without automated cleaning systems, adding operational expenditure burdens.
Strategic Opportunities
- Industrial consumer self-generation:Petrochemical and desalination facilities in Al-Ahmadi Governorate seek behind-the-meter solar to hedge against grid tariff volatility and secure power cost predictability.
- Battery storage convergence:Lithium-ion and emerging flow battery technologies paired with photovoltaic installations address grid intermittency management needs for Kuwait's summer peak cooling loads.
- Central Tendering Committee process streamlining:Competitive bidding governance reforms may reduce procurement cycle duration and improve developer access to sovereign offtake contracts.
Industry Challenges
- Local content requirement navigation:Kuwait's sovereign wealth fund deployment into domestic energy infrastructure creates evolving domestic sourcing obligations that complicate supply chain planning for international EPC contractors.
- Skilled technician scarcity:Photovoltaic installation and maintenance expertise concentrates among a limited pool of regional specialists, constraining project execution velocity and quality assurance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar System in Kuwait Market |
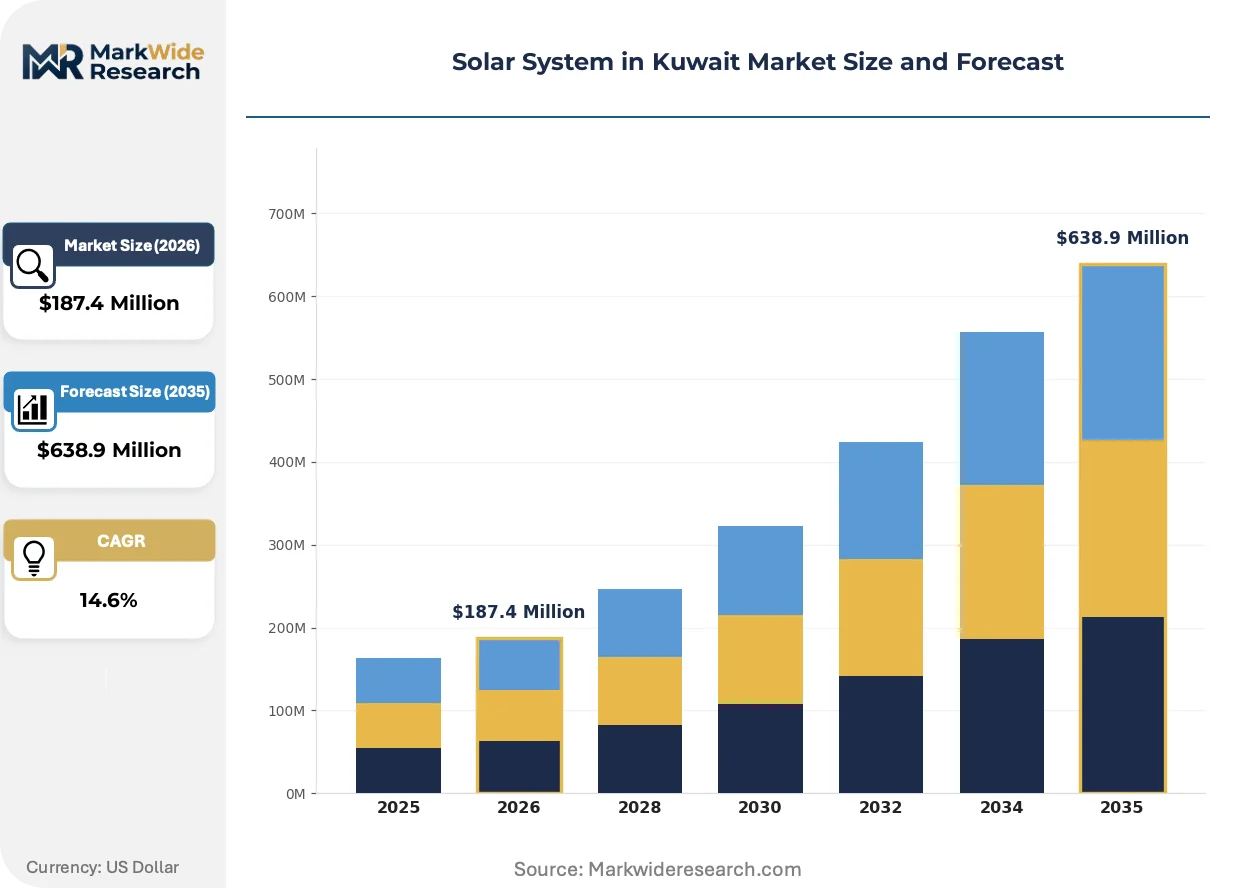
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Inverters, Battery Storage, Monitoring Systems Installation Type: Roof-mounted, Ground-mounted, Building-integrated, Off-grid End User: Residential, Commercial, Industrial, Government Technology: Photovoltaic, Concentrated Solar Power, Hybrid Systems, Thin Film |
| Companies Covered | Kuwait Institute for Scientific Research (KISR), Kuwait Oil Company, Alternative Energy Projects Co. (AEPCo), Kuwait National Petroleum Company, Solarity, JinkoSolar Holding Co. Ltd., ACWA Power, Masdar, Kharafi National, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar System in Kuwait Market Trends and Innovations
Photovoltaic technology deployment patterns in Kuwait are shifting from pure generation assets toward integrated solar-plus-storage configurations, driven by grid operator requirements for dispatchable renewable capacity and industrial buyer preferences for firm power supply.
Bifacial photovoltaic modules paired with single-axis tracking systems are automating yield optimization in Kuwait's desert environments. The Ministry of Electricity and Water evaluates these configurations for Shagaya phase expansions. Dual-sided energy capture and automated sun positioning compress levelized cost thresholds and reduce manual operational intervention requirements.
Kuwait's renewable energy procurement framework administered by the Central Tendering Committee tightens competitive bidding standards for international developers. Qualification criteria now emphasize local construction partnerships and technology transfer commitments. Foreign independent power producers respond by deepening relationships with Kuwaiti EPC contractors to satisfy evaluation scoring.
Industrial energy consumers in Al-Ahmadi's petrochemical corridor are consolidating solar procurement into multi-site power purchase agreements. Long-term offtake structures replace fragmented facility-level contracting. This concentration favors developers with balance sheet capacity to underwrite portfolio-scale installations serving Kuwait Oil Company and petrochemical complex operators.
Solar System in Kuwait Market Segmentation
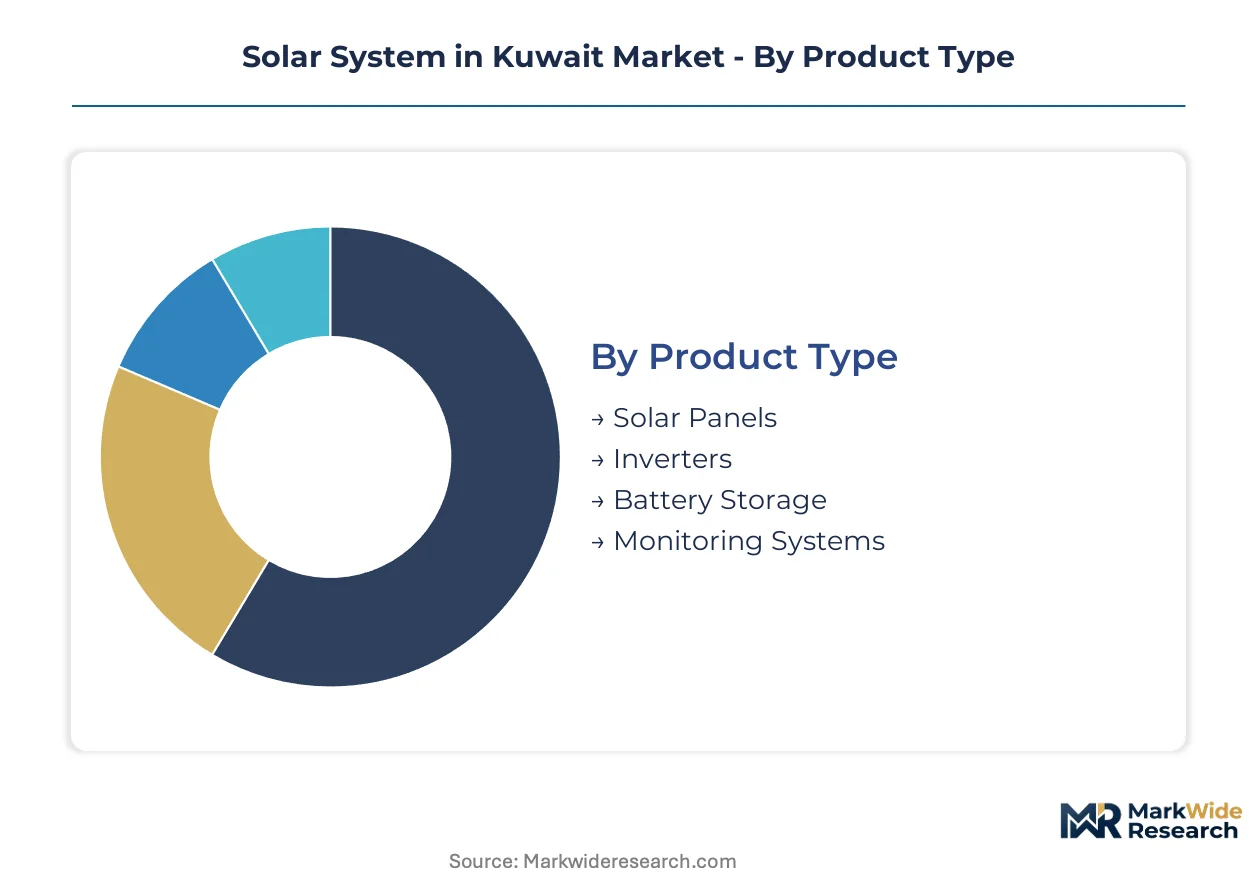
Segmentation in Kuwait's solar market reveals distinct procurement patterns across product types and installation configurations. Government procurement concentrates on utility-scale ground-mounted systems, while commercial and industrial buyers drive demand for battery-integrated solutions. Understanding these divisions clarifies where technology suppliers and EPC contractors should prioritize capability investments.
Product Type:
Crystalline silicon modules operate as standalone generation assets, while inverters and battery storage function as embedded system components that determine overall plant performance.
- Solar Panels:Crystalline silicon modules dominate Kuwaiti deployments, achieving conversion efficiencies between 18% and 22% under the country's high-irradiance desert conditions. Demand concentrates at Shagaya Renewable Energy Park and planned utility-scale parks in Al-Ahmadi Governorate, where the Ministry of Electricity and Water procures multi-hundred-megawatt installations requiring standardized module specifications.
- Battery Storage:Lithium-ion systems represent the fastest-expanding product category as grid operators seek to manage intermittency from photovoltaic generation during Kuwait's summer peak cooling loads. Industrial consumers in Al-Ahmadi's petrochemical corridor increasingly specify storage-integrated solutions to secure firm power supply and hedge against grid tariff volatility.
- Inverters:String and central inverter configurations convert DC photovoltaic output to grid-synchronous AC power, with utility-scale projects favoring central architectures for efficiency optimization.
- Monitoring Systems:SCADA and asset management platforms enable remote performance tracking and predictive maintenance across dispersed solar installations.
Solar panels lead volumes today; battery storage is gaining share fastest.
Installation Type:
Mounting configurations stratify by project scale and land availability, with ground-mounted systems commanding sovereign procurement and roof-mounted installations serving distributed commercial demand.
- Ground-mounted:Utility-scale solar parks in Al-Jahra and Al-Ahmadi governorates employ fixed-tilt and single-axis tracking structures to maximize energy yield across Kuwait's flat desert terrain. The Ministry of Electricity and Water's Shagaya expansion phases anchor demand for this installation category.
- Building-integrated:Photovoltaic facades and rooftop-integrated modules serve new construction mandates from the Public Authority for Housing Welfare, which increasingly requires solar readiness in residential and commercial building codes.
- Roof-mounted:Retrofit installations on existing commercial and industrial structures provide behind-the-meter generation for energy cost hedging.
- Off-grid:Standalone systems serve remote oil field operations and border facilities beyond centralized grid infrastructure.
Ground-mounted installations dominate utility procurement; building-integrated configurations are expanding most quickly through housing code mandates.
End User:
Customer type determines procurement process complexity, with government entities consolidating authority through the Central Tendering Committee while industrial buyers negotiate bilateral power purchase agreements.
- Government:The Ministry of Electricity and Water consolidates procurement authority for renewable energy projects, hardening buyer concentration among sovereign entities and national oil companies. Central Tendering Committee competitive bidding governs developer access and shapes qualification criteria emphasizing local construction partnerships.
- Industrial:Petrochemical and desalination facilities in Al-Ahmadi Governorate seek behind-the-meter solar to secure power cost predictability. Multi-site power purchase agreements are consolidating procurement across Kuwait Oil Company and petrochemical complex operators.
- Commercial:Retail, hospitality, and logistics facilities specify rooftop installations to manage operational expenditure volatility.
- Residential:Single-family and multi-family housing developments represent emerging demand as solar readiness mandates expand addressable market beyond utility procurement.
Government end users anchor project volumes; industrial adoption is climbing the fastest through portfolio-scale contracting.
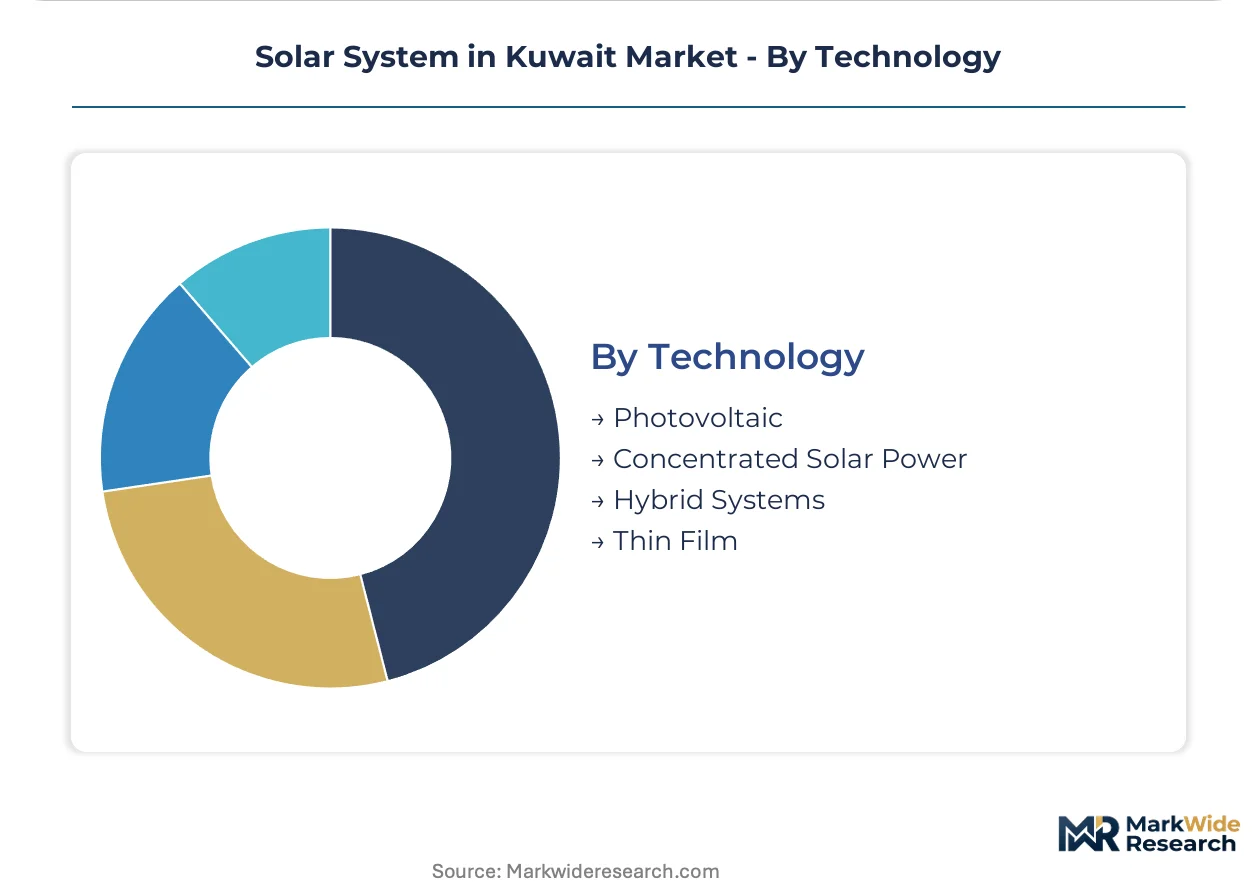
Technology:
Technology selection reflects maturity gradients and application specificity, with photovoltaic systems dominating current deployments while concentrated solar power serves specialized dispatch requirements.
- Photovoltaic:Crystalline silicon and emerging bifacial modules paired with single-axis tracking systems automate yield optimization in Kuwait's desert environments. The Ministry of Electricity and Water evaluates these configurations for Shagaya phase expansions based on levelized cost thresholds and reduced operational intervention requirements.
- Concentrated Solar Power:Parabolic trough and solar tower configurations with thermal storage provide dispatchable renewable capacity for grid operators managing summer peak loads, though deployment remains limited compared to photovoltaic alternatives.
- Hybrid Systems:Photovoltaic-battery and photovoltaic-diesel configurations address intermittency management and backup power requirements for critical infrastructure.
- Thin Film:Cadmium telluride and copper indium gallium selenide technologies offer temperature coefficient advantages in extreme desert heat conditions.
Photovoltaic technology commands current deployment volumes; hybrid systems are expanding most quickly through storage convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands utility-scale solar deployment volumes across the Gulf Cooperation Council, while the United Arab Emirates concentrates concentrated solar power innovation and advanced photovoltaic manufacturing capabilities.
Saudi Arabia
The Saudi Arabian renewable energy procurement framework drives gigawatt-scale solar park development through the Public Investment Fund's utility mandates. ACWA Power anchors independent power producer contracts under the National Renewable Energy Program. The Riyadh-Qassim corridor hosts multiple photovoltaic complexes serving grid integration targets.
United Arab Emirates
Masdar's clean energy platform consolidates utility-scale and distributed solar assets across Abu Dhabi and Dubai emirates. The Emirates Water and Electricity Company governs competitive auctions for independent power producers. Mohammed bin Rashid Al Maktoum Solar Park in Dubai anchors concentrated solar power and photovoltaic hybrid configurations.
Qatar
Qatar General Electricity and Water Corporation procurement mandates reshape solar integration timelines for the FIFA World Cup legacy infrastructure. Kahramaa's renewable energy targets concentrate project development in Ras Laffan Industrial City. The Mesaieed industrial zone hosts behind-the-meter installations serving petrochemical and LNG facility operators.
Oman
Oman Power and Water Procurement Company renewable energy auctions attract international developers to utility-scale photovoltaic and wind-solar hybrid projects. The Dhofar Governorate hosts grid-connected installations serving rural electrification and industrial load centers. Sohar Port and Freezone concentrates commercial and industrial solar adoption among aluminum and steel producers.
Bahrain
The Bahrain Petroleum Company solar integration mandates drive renewable energy adoption across refinery and petrochemical operations. The Electricity and Water Authority governs distributed generation licensing for commercial rooftop installations. The Askar and Al Dur industrial zones host pilot photovoltaic projects serving aluminum smelter and desalination facility loads.
Solar System in Kuwait Market Competitive Landscape
Gulf-based national oil companies and sovereign entities anchor one tier; international independent power producers and Chinese module manufacturers hold procurement and supply positions. Buyer concentration hardens around Ministry of Electricity and Water consolidated tendering authority. Three archetypes dominate: state-linked EPC contractors, independent power producers with long-term offtake expertise, and vertically integrated module suppliers. Competitive moves center on local partnership formation and technology transfer commitments to satisfy Central Tendering Committee qualification scoring.
Within the state-linked contractor tier, Kharafi National exemplifies EPC capability anchored in regional construction execution. ACWA Power occupies a position representing independent power producer models securing sovereign offtake agreements. Among module suppliers, JinkoSolar Holding Co. Ltd. sits within the scale-driven manufacturing archetype competing on crystalline silicon cost structures.
| Leading Market Players |
|---|
| Kuwait Institute for Scientific Research (KISR) |
| Kuwait Oil Company |
| Alternative Energy Projects Co. (AEPCo) |
| Kuwait National Petroleum Company |
| Solarity |
| JinkoSolar Holding Co. Ltd. |
| ACWA Power |
| Masdar |
| Kharafi National |
| Others |
Pricing and Supply Chain Analysis
Bifacial module adoption with single-axis tracking is compressing levelized cost thresholds while concentrating procurement leverage among sovereign buyers with multi-hundred-megawatt tendering authority. This technology transition simultaneously reshapes supplier margins and hardens buyer concentration around Kuwait's Ministry of Electricity and Water consolidated procurement mandates.
Pricing Analysis
Capacity additions in China and Southeast Asia are reshaping price floors for crystalline silicon modules serving Kuwaiti utility-scale projects. Three-tier pricing structure across premium, standard, and economy levels differentiates bids based on conversion efficiency guarantees and local content compliance. Cost compression in standard-tier modules is intensifying because polysilicon feedstock prices fluctuate with hydrocarbon markets. Industrial offtakers in Al-Ahmadi's petrochemical corridor demonstrate highest price sensitivity due to energy cost hedging mandates, while government procurement through the Central Tendering Committee prioritizes technical qualification over unit cost minimization.
Supply Chain Analysis
Module refurbishment and warranty claim flows from early Kuwaiti installations are creating secondary supply channels for replacement components and asset management services. Manufacturing concentrates in China, Vietnam, and Malaysia for cell and module assembly, while inverter production centers on Germany, China, and the USA. Polysilicon, aluminum framing, and lithium-ion cells constitute critical input dependencies with exposure to commodity price volatility. Single-source vulnerability from concentrated polysilicon refining in specific geographies threatens EPC margin stability. Distribution runs through Kuwaiti EPC contractors with sovereign project execution experience, who intermediate between international suppliers and Ministry of Electricity and Water procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's solar market compounds steadily as sovereign renewable energy procurement mandates institutionalize demand visibility across project development cycles. The Ministry of Electricity and Water's consolidated tendering authority creates predictable offtake volumes that anchor supplier investment decisions.
For Market Incumbents: To counter emerging competition from Chinese module manufacturers with integrated financing capabilities, deepen technology transfer commitments with Kuwaiti construction partners and secure captive polysilicon supply through backward integration into upstream refining. Prioritize certification investment for bifacial-plus-tracking configurations to satisfy Shagaya expansion technical benchmarks and defend evaluation scoring against lower-cost standard module bids. For New Entrants and Emerging Players: Launch via industrial self-generation power purchase agreements targeting Kuwait Oil Company and petrochemical complex operators in Al-Ahmadi Governorate. This segment offers fastest penetration through bilateral negotiation outside Central Tendering Committee competitive bidding, with multi-site portfolio contracting enabling scale without sovereign procurement qualification barriers. Prioritize battery-integrated solution architectures that address firm power supply requirements for desalination and process heat loads. For Investors and Strategic Acquirers: Valuations sit cheapest among regional EPC contractors with established Ministry of Electricity and Water relationships but limited balance sheet capacity for independent power producer transitions. Long-term viability over the next decade hinges on successful pivot from construction-only models toward development and asset ownership. Monitor Central Tendering Committee qualification scoring revisions for early signals of preferred developer archetype shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Execution | Long-term offtake structures with Kuwait Oil Company secure revenue visibility for project financing. |
| Backward Integration into Polysilicon | Captive feedstock supply insulates module margins from hydrocarbon-linked input cost volatility. |
| Technology Licensing Partnership | Bifacial tracking system transfers satisfy Central Tendering Committee local content evaluation criteria. |
| Battery Storage Convergence | Lithium-ion integration addresses grid operator intermittency management requirements for summer peak loads. |
| Green Certification Program | Carbon intensity disclosures align with Kuwait sovereign wealth fund domestic infrastructure investment mandates. |
Research Methodology
Coverage spans Kuwait, Saudi Arabia, and the United Arab Emirates, with primary inputs from each market informing cross-border demand pattern analysis. The research combines structured interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators with secondary validation from EIA data, IEA renewable energy reports, FERC-equivalent regulatory filings in Gulf Cooperation Council jurisdictions, and project development databases tracking Shagaya Renewable Energy Park expansion phases. Bottom-up installation volume estimates triangulate against top-down Ministry of Electricity and Water procurement target assessments.
Segmentation modeling operates at technology type, installation configuration, and end-user category granularity. The analytical framework projects crystalline silicon module, battery storage, and inverter demand across the analysis window, with CAGRs derived from regression analysis of historical procurement cycles and policy implementation timelines. Forecast inputs incorporate solar irradiance resource assessments for Al-Jahra and Al-Ahmadi governorates, grid interconnection queue data, and building code solar readiness mandate adoption curves administered by the Public Authority for Housing Welfare.
Forecast precision tightens around the base case; tail outcomes carry wider variance under grid infrastructure investment delays or sovereign wealth fund deployment redirection into non-energy sectors. Practitioners should monitor Central Tendering Committee competitive bidding cycle duration and local content requirement stringency revisions for early signals of developer access conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Solar Power Tracker Market
Solar Power Systems
Solar Mirror Market
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Canada Distributed Solar Power Generation Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
On-Grid Solar Inverter Market
Solar Power Systems
Floating Solar Panels Market