
 United Kingdom Diagnostic Imaging Equipment Market | 2026-2036
United Kingdom Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Diagnostic Imaging Equipment Market Analytics
CE marking under the EU Medical Device Regulation is rotating toward UKCA marking as the gatekeeping qualification for market access, forcing manufacturers to revalidate quality management systems. Siemens Healthineers leverages its established installed base across NHS trusts to sustain service contract renewals. GE HealthCare anchors its position through backward integration into helium-free MRI magnet technology, reducing supply chain exposure. Canon Medical Systems differentiates via detector manufacturing scale that controls cost structures in digital X-ray.
Diagnostic imaging equipment encompasses systems that generate visual representations of internal body structures for clinical diagnosis, utilizing electromagnetic radiation, acoustic energy, or magnetic fields with spatial resolution parameters typically ranging from sub-millimetre to centimetre scale depending on modality. These systems serve primarily to enable non-invasive detection, monitoring, and treatment planning for pathological conditions across acute and chronic care pathways. CT scan platforms retain the largest revenue share among product types due to emergency department throughput requirements and trauma protocol standardisation, while ultrasound experiences the fastest structural expansion driven by point-of-care deployment in community diagnostic hubs. Digital technology dominates the installed base as NHS England phases out analog cassette systems through its imaging modernisation programmes.
The Medicines and Healthcare products Regulatory Agency enforces UKCA conformity assessment for all new device placements, while the Care Quality Commission inspects imaging service compliance against Ionising Radiation Regulations. NHS England's procurement frameworks further shape demand by mandating interoperability with electronic patient record systems and standardised DICOM connectivity. Stakeholders must monitor how the UKCA recognition route divergence from EU MDR mutual recognition agreements reshapes supplier qualification timelines and service parts availability.
Market Dynamics
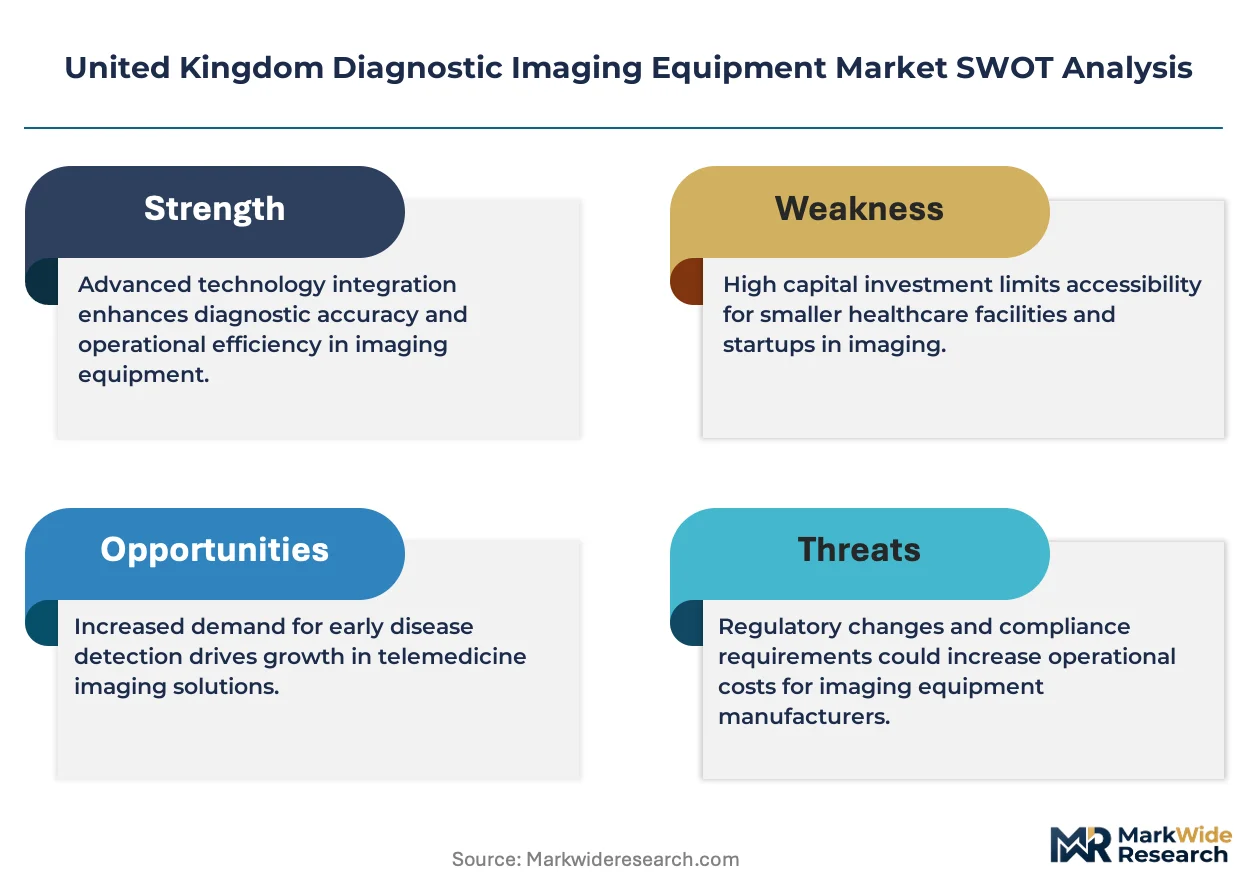
The transition from EU CE marking to UKCA conformity assessment under the UK Medical Device Regulations is forcing manufacturers to revalidate quality management systems and restructure supply chains specifically for the British market.
Growth Catalysts
- NHS Imaging Modernisation Programmes:NHS England's phased elimination of analog cassette systems through dedicated capital funding is accelerating digital radiography procurement across acute trusts.
- Community Diagnostic Centre Expansion:The UK government's commitment to establishing 160 community diagnostic hubs by 2025 is pulling point-of-care ultrasound and mobile X-ray systems into primary care networks.
- Helium Conservation Mandates:European F-Gas Regulation alignment and NHS supply chain resilience directives are incentivizing adoption of helium-free MRI magnet technologies that reduce import dependency.
Market Restraints
- UKCA Recognition Route Divergence:The Medicines and Healthcare products Regulatory Agency's non-recognition of EU MDR mutual recognition agreements is extending supplier qualification timelines by 12-18 months for continental European manufacturers.
- Specialist Radiographer Shortages:The Health Education England workforce census identifies persistent vacancies in diagnostic radiography that constrain equipment utilization rates across NHS trusts.
- Capital Budget Cyclicality:NHS capital expenditure freezes during fiscal consolidation periods create lumpy demand patterns that destabilize equipment replacement cycles.
Strategic Opportunities
- AI-Enabled Workflow Integration:The UKCA software-as-a-medical-device pathway for AI diagnostic platforms creates first-mover advantage for vendors validating clinical decision support algorithms against NICE evidence standards.
- Interoperability Mandate Compliance:NHS England's procurement frameworks requiring DICOM connectivity and electronic patient record integration position vendors with open-architecture systems to capture trust-wide enterprise contracts.
- Academic Health Science Network Concentration:England's seven AHSN clusters around London, Manchester, and Birmingham concentrate early-adopter demand for experimental imaging modalities and hybrid diagnostic-therapeutic systems.
Industry Challenges
- Dual Certification Burden:Manufacturers must maintain parallel quality management system audits for UKCA and residual CE marking requirements, doubling compliance overhead for the British market relative to pre-2021 access.
- Legacy System Integration Complexity:NHS trusts operate heterogeneous installed bases spanning three decades of equipment generations, complicating vendor transitions and data migration protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Diagnostic Imaging Equipment Market |
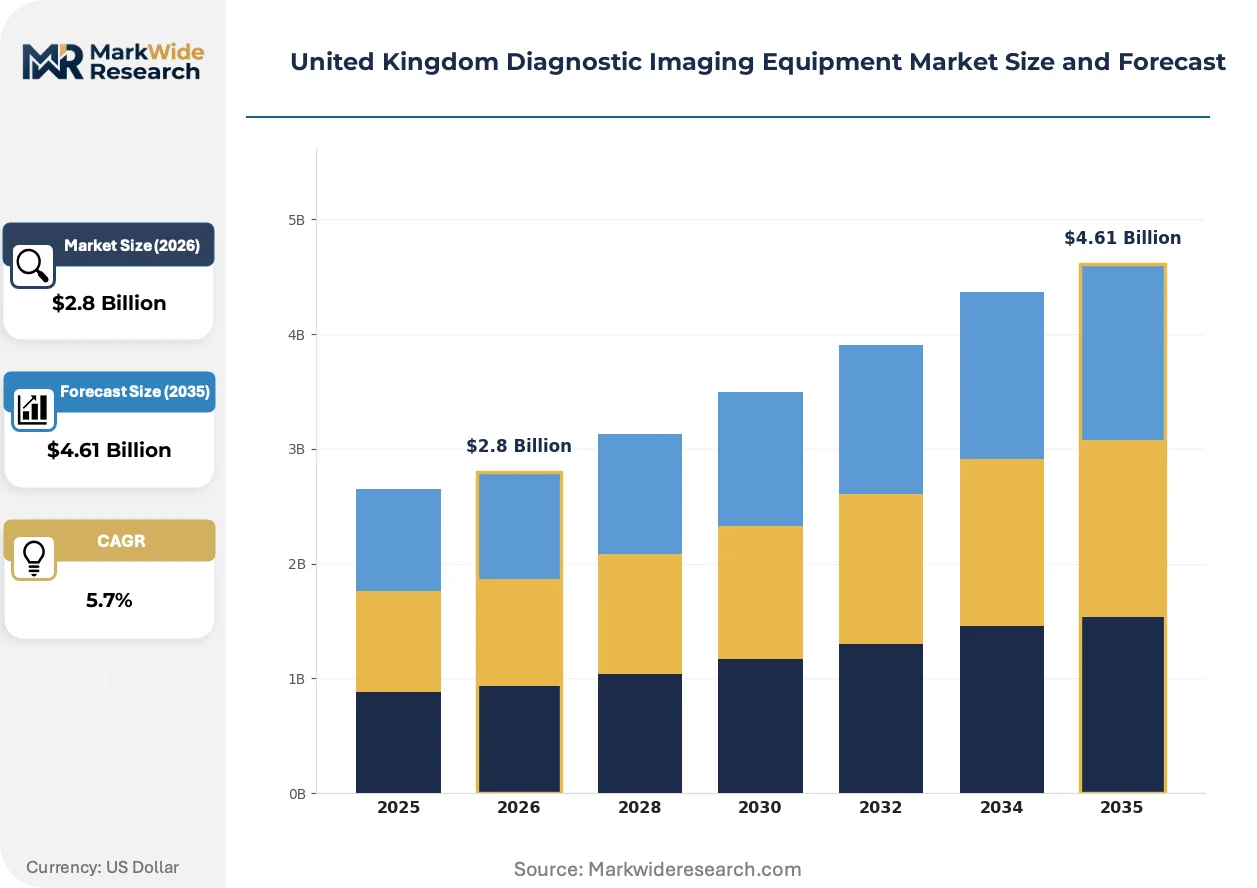
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, MRI, CT Scan, X-Ray End User: Hospitals, Clinics, Imaging Centers, Research Institutions Technology: Analog, Digital, Hybrid, 3D Imaging Delivery Mode: Portable, Stationary, Mobile Units, Others |
| Companies Covered | Koninklijke Philips N.V., Siemens Healthineers AG, GE HealthCare, Canon Medical Systems Corporation, Fujifilm Holdings Corp., United Imaging Healthcare Co. Ltd., Mindray Medical Intl. Ltd., Carestream Health, Hologic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Diagnostic Imaging Equipment Market Evolving Landscape
Digital detector technology and artificial intelligence integration are restructuring competitive positioning in British diagnostic imaging, while procurement centralization through NHS frameworks is compressing vendor margins and service contract structures.
Photon-counting CT detector arrays are displacing conventional energy-integrating detectors in premium system configurations. NHS teaching hospitals in London and Oxford are piloting installations ahead of national procurement frameworks. This displacement is compressing upgrade cycles for installed base systems and forcing incumbent vendors to accelerate detector platform refreshes.
The UK Medicines and Healthcare products Regulatory Agency's tightened software-as-a-medical-device requirements for AI-enabled imaging platforms are mandating clinical validation datasets specific to British patient populations. Algorithm developers must now submit performance evidence against UK Biobank-representative demographics. Radiology AI vendors are responding by establishing UK-based clinical investigation sites and partnerships with Academic Health Science Networks.
Trust-level procurement consolidation through NHS England's national commercial frameworks is aggregating purchasing power previously dispersed across individual hospital procurement departments. Framework compliance now mandates total cost of ownership modeling over ten-year horizons rather than capital expenditure alone. This behavioral shift is most visible in England's Integrated Care Systems, where equipment standardization across constituent trusts is becoming a board-level priority.
United Kingdom Diagnostic Imaging Equipment Market Segmentation
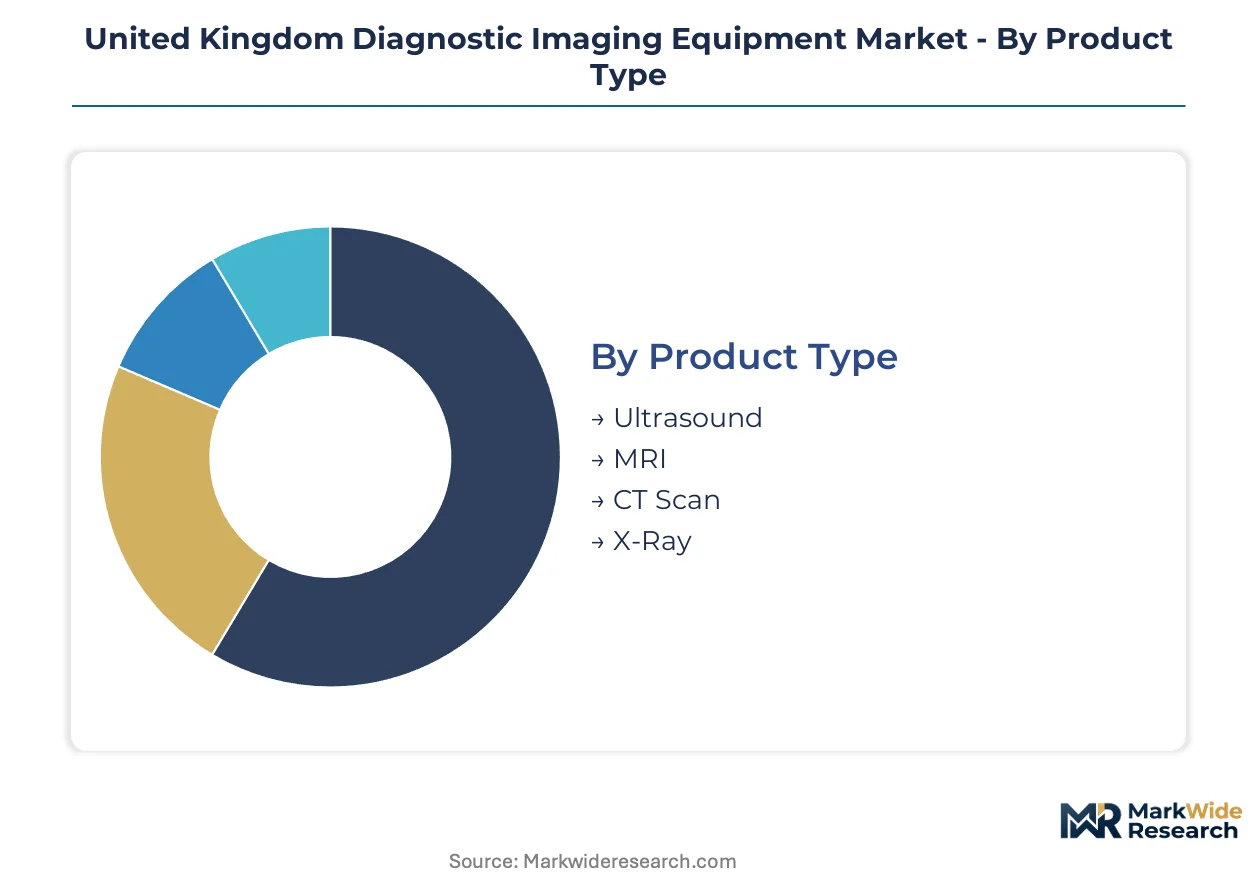
Segmentation in the United Kingdom diagnostic imaging equipment market reveals how procurement channels, clinical workflows, and technology lifecycles intersect. NHS England's capital allocation frameworks and the transition to UKCA marking reshape which segments capture investment priority across acute and community care pathways.
Product Type:
CT scan systems flow through NHS national procurement frameworks to acute trusts, while ultrasound platforms distribute via primary care networks and community diagnostic hubs. MRI contracts concentrate through teaching hospital capital programmes and specialist neuroscience centers.
- CT Scan:Energy-integrating detector arrays and emerging photon-counting configurations deliver sub-millimetre spatial resolution for trauma protocols. NHS emergency departments in London, Manchester, and Birmingham anchor replacement demand as throughput requirements intensify. The Medicines and Healthcare products Regulatory Agency's UKCA pathway governs all new system placements.
- Ultrasound:Acoustic energy systems span cart-based hospital configurations to handheld point-of-care devices. Community diagnostic hubs across England's Integrated Care Systems drive the steepest volume expansion, supported by NHS England's 160-hub deployment target. Point-of-care deployment reduces referral-to-diagnosis intervals in primary care networks.
- MRI:Magnetic resonance platforms utilizing superconducting magnets or emerging helium-free alternatives serve neurological, oncological, and musculoskeletal pathways. Supply chain resilience directives favor helium-free magnet adoption.
- X-Ray:Digital radiography systems with flat-panel detectors replace analog cassette installations through NHS imaging modernisation programmes.
By volume, X-Ray leads through phased analog replacement. By growth pace, ultrasound is ahead.
End User:
Capital intensity and clinical throughput requirements separate high-acuity hospital deployments from distributed community settings. Procurement authorization thresholds and UKCA compliance timelines further stratify access.
- Hospitals:Acute NHS trusts operate comprehensive imaging suites across radiology departments, emergency units, and surgical planning workflows. Teaching hospitals in Academic Health Science Networks pilot experimental modalities ahead of national frameworks. Ionising Radiation Regulations compliance and Care Quality Commission inspections govern operational licensing.
- Imaging Centers:Independent diagnostic facilities and NHS-affiliated standalone units handle elective procedure backlogs and outsourced NHS contract volumes. These centers concentrate in urban corridors with established radiographer labor pools.
- Clinics:General practice networks and specialist outpatient facilities deploy portable ultrasound and basic X-ray for immediate diagnostic triage.
- Research Institutions:University hospitals and biomedical research centers operate preclinical imaging systems and experimental hybrid diagnostic-therapeutic platforms.
Hospitals command the largest capital allocation. Imaging centers are expanding most quickly through NHS outsourcing contracts.
Technology:
Digital platforms dominate NHS procurement specifications, while residual analog installations face mandatory phase-out. Cost tier and interoperability requirements separate premium configurations from standard deployments.
- Digital:Direct radiography with flat-panel detectors, digital ultrasound with software beamforming, and fully digital MRI/CT acquisition chains constitute the NHS installed base standard. DICOM connectivity and electronic patient record integration are mandatory under NHS England procurement frameworks. Digital systems command premium pricing but reduce consumable costs and enable AI-enabled workflow integration.
- 3D Imaging:Tomosynthesis, volumetric ultrasound, and 3D reconstruction CT serve orthopedic planning, breast imaging, and interventional guidance applications. Academic Health Science Networks in Oxford and London pilot advanced 3D configurations.
- Hybrid:Combined modality systems such as PET-CT and PET-MRI integrate functional and anatomical imaging for oncology and neurology pathways.
- Analog:Cassette-based film systems persist in limited legacy installations facing NHS England-mandated replacement deadlines.
Digital platforms dominate current procurement. 3D imaging is gaining share fastest through specialized application expansion.
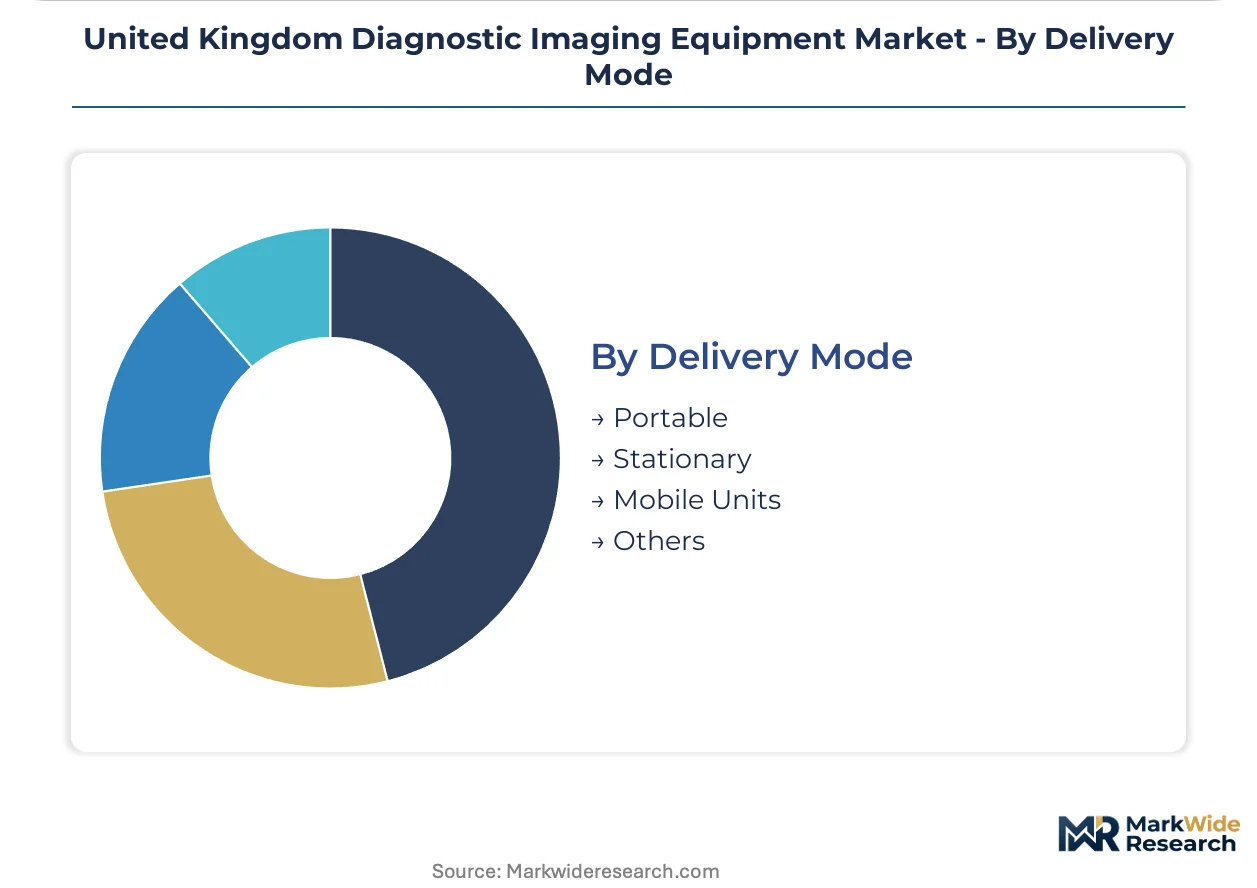
Delivery Mode:
Physical mobility requirements and site infrastructure constraints determine deployment configuration. Community diagnostic hub expansion favors portable and mobile formats over fixed-room installations.
- Portable:Handheld ultrasound probes, battery-powered X-ray units, and compact CT scanners enable bedside and domiciliary diagnostics. These configurations serve community diagnostic hubs and reduce patient transport requirements.
- Mobile Units:Truck-mounted MRI, CT, and mammography systems deliver screening services to underserved geographies and temporary capacity augmentation. NHS cancer screening programmes utilize mobile mammography fleets.
- Stationary:Fixed-room installations with dedicated power, cooling, and shielding infrastructure serve high-throughput hospital radiology departments.
- Others:Containerized and modular imaging suites address temporary demand surges and construction-period replacement needs.
Stationary systems retain the largest installed base. Portable configurations are climbing the fastest through community diagnostic hub deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHS England's capital allocation frameworks and UKCA marking requirements concentrate procurement authority within Integrated Care Systems. Regional demand clusters around Academic Health Science Networks where teaching hospitals pilot experimental modalities ahead of national framework adoption.
London and the Southeast
Imperial College Healthcare NHS Trust and Guy's and St Thomas' NHS Foundation Trust anchor premium CT and MRI procurement through specialist neuroscience and cancer center designations. The Medicines and Healthcare products Regulatory Agency's London headquarters accelerates UKCA conformity assessment for vendors establishing UK clinical investigation sites. King's Health Partners AHSN concentrates early-adopter demand for photon-counting CT configurations.
Midlands
University Hospitals Birmingham NHS Foundation Trust operates one of England's highest-throughput emergency departments, driving CT replacement cycles for trauma protocol compliance. NHS England's Midlands regional team coordinates capital planning across seven Integrated Care Systems. The Birmingham Health Partners AHSN supports clinical validation partnerships for AI-enabled diagnostic platforms seeking UKCA software-as-a-medical-device clearance.
North England
Manchester University NHS Foundation Trust anchors MRI procurement for specialist cardiovascular and musculoskeletal pathways across Greater Manchester Integrated Care System. Health Education England's northern workforce programs address radiographer vacancy rates constraining equipment utilization. The Northern Health Science Alliance coordinates research partnerships between teaching hospitals and imaging technology developers.
Scotland
NHS Scotland's national procurement framework aggregates equipment purchasing across fourteen territorial health boards, compressing vendor margins through consolidated tendering. NHS Greater Glasgow and Clyde operates Scotland's largest radiology department with dedicated interventional imaging suites. The Scottish Imaging Network provides teleradiology infrastructure connecting remote highlands hospitals to specialist reporting centers in Aberdeen and Edinburgh.
Wales
Velindre University NHS Trust coordinates cancer imaging service planning across Wales through the Single Cancer Pathway program. Cardiff and Vale University Health Board anchors MRI and PET-CT capacity for south Wales populations. Health Technology Wales conducts rapid evidence assessments that inform National Institute for Health and Care Excellence-aligned procurement decisions for novel imaging modalities.
United Kingdom Diagnostic Imaging Equipment Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with established NHS service infrastructure. Siemens Healthineers, GE HealthCare, and Philips collectively dominate installed base maintenance through multi-year managed equipment service contracts. Three archetypes define competitive positioning: European-headquartered full-line suppliers with UK manufacturing presence, Japanese imaging specialists leveraging detector manufacturing scale, and emerging Chinese vendors competing on capital cost. Consolidation pressure intensifies through NHS framework aggregation, while technology differentiation shifts toward AI workflow integration and helium-free magnet architectures.
Among European-headquartered suppliers, Siemens Healthineers AG and Koninklijke Philips N.V. exemplify the full-line service contract model that anchors long-term revenue stability across NHS trusts. Canon Medical Systems Corporation represents the Japanese specialist archetype with detector manufacturing integration. These three occupy positions where installed base scale and service network density create defensive moats against capital-cost competition from United Imaging Healthcare Co. Ltd. and other emerging entrants.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Siemens Healthineers AG |
| GE HealthCare |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corp. |
| United Imaging Healthcare Co. Ltd. |
| Mindray Medical Intl. Ltd. |
| Carestream Health |
| Hologic |
| Others |
Value Network & Pricing Analysis
Six-to-nine month UKCA conformity assessment timelines concentrate procurement authority within NHS England's national frameworks, compressing vendor margins while amplifying price leverage for teaching hospital trusts with multi-year managed equipment service contracts. This lead-time band shapes how manufacturers structure total cost of ownership models against pure capital expenditure bids.
Pricing Analysis
Certification level creates the primary spread between premium UKCA-validated systems and transitional CE-marked inventory liquidated ahead of regulatory deadlines. Three-tier pricing structure across premium, standard, and economy levels reflects detector generation, helium-free magnet architecture, and AI workflow bundling. Cost compression in standard-tier digital radiography intensifies because NHS framework aggregation pools demand across Integrated Care Systems. Community diagnostic hubs exhibit highest price sensitivity due to capital allocation constraints, while London teaching hospitals prioritize throughput specifications over unit economics.
Supply Chain Analysis
Port congestion at Felixstowe and Rotterdam-Antwerp corridors extends inbound component lead times for superconducting magnet cryostats and flat-panel detector arrays manufactured in Germany, Japan, and the United States. UK assembly operations draw from rare earth magnet suppliers in China, semiconductor foundries in Taiwan, and precision machining clusters in Switzerland. Single-source vulnerability concentrates in helium supply chains tethered to Qatar and Algeria export terminals. Distribution runs through NHS Supply Chain central warehousing with final-mile installation managed by manufacturer-authorized service engineers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from AI-enabled workflow subscriptions and predictive maintenance contracts expands faster than hardware replacement cycles, repositioning vendor economics toward recurring revenue capture across decade-long equipment lifespans.
For Market Incumbents: Compound defensive moats by deepening backward integration into detector manufacturing and securing exclusive service contracts across NHS trust installed bases. Emerging Chinese vendors with capital-cost positioning threaten standard-tier market share. Vertical integration into helium-free magnet production reduces supply chain exposure and sustains margin structures against low-cost entrants. For New Entrants and Emerging Players: UKCA software-as-a-medical-device fast-track pathways enable first-mover positioning in radiology AI clinical decision support. White-space concentrates in community diagnostic hub ultrasound deployment and portable X-ray configurations for primary care networks. Go-to-market through Academic Health Science Network clinical validation partnerships accelerates trust-level procurement access. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized imaging detector divisions or legacy analog equipment portfolios requiring digital transition capital. Long-term viability hinges on AI algorithm validation infrastructure and NHS framework compliance capabilities. Watch NHS capital allocation announcements as inflection indicators for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Software-as-a-Medical-Device Pathway | Accelerates market access for AI diagnostic platforms validated against NICE evidence standards. |
| Helium-Free Magnet Technology Licensing | Reduces import dependency exposure under European F-Gas Regulation alignment mandates. |
| Academic Health Science Network Partnership | Concentrates early-adopter demand for experimental photon-counting CT configurations in Oxford and London. |
| Managed Equipment Service Contract Expansion | Captures decade-long revenue streams through NHS trust total cost of ownership procurement frameworks. |
| Community Diagnostic Hub Distribution Agreement | Positions portable ultrasound and mobile X-ray systems across England's 160-hub deployment target. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with NHS trust procurement directors, biomedical engineering leads, radiology department heads, and GPO contracts managers; and secondary validation against MHRA device registration databases, NHS Supply Chain tender records, and Care Quality Commission inspection reports. Bottom-up equipment shipment tracking triangulated against top-down capital expenditure allocation models.
Across the analysis window, forecasts incorporate modality-specific replacement cycles, UKCA transition timelines, and helium supply chain resilience scenarios. Segmentation dimensions span product type, end-user setting, technology tier, and delivery mode. CAGRs derive from installed base evolution, procurement framework award patterns, and point-of-care expansion trajectories. Forecast inputs include Health Education England workforce census projections and NHS England imaging modernisation programme capital release schedules.
The analysis sits within stated boundaries; outcomes outside sustained NHS capital funding, UKCA-EU MDR divergence acceleration, or radiographer workforce stabilization would require recalibration. Forecasts reflect documented assumptions regarding procurement centralization, AI regulatory clarity, and supply chain restructuring. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global CT Scanners Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Europe Digital Radiology Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
Carotid Ultrasound Imaging Market
Medical Imaging
Pediatric Imaging Market
Medical Imaging
US Medical Imaging Market
Medical Imaging
France Digital Radiology Market
Medical Imaging
Medical Holography Market
Medical Imaging
New Born Eye Imaging Systems Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Neurophotonics Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
Americas Interventional Radiology Market
Medical Imaging
Radiology Positioning Aids Market