
 Global Sugar Free Beverages Market | 2026-2036
Global Sugar Free Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sugar Free Beverages Market Outlook
The capital-intensity divergence between bottling infrastructure and digital-native brand building is rotating competitive advantage toward players with flexible manufacturing networks. The Coca-Cola Company leverages its global bottling partnerships to sustain cost-efficient distribution across multiple continents. Red Bull GmbH anchors its premium positioning through event marketing and controlled retail pricing. Celsius Holdings Inc. competes by specializing in metabolism-enhancing formulations that target fitness-oriented consumers.
Sugar free beverages are non-alcoholic drinks formulated without sucrose, fructose, or added caloric sweeteners, typically using stevia, aspartame, sucralose, or erythritol to achieve palatability while maintaining near-zero caloric content; they serve industrial and commercial purposes by enabling beverage producers to comply with health regulations and capture consumers managing diabetes, weight, or metabolic conditions. Functional beverages lead value generation through probiotic, adaptogenic, and nootropic ingredient premiums that command shelf-space priority in supermarkets and online retailers. Sports drinks represent the fastest-growing consumption pool as athlete and weekend-warrior segments expand hydration routines beyond traditional glucose-based formulations.
FDA labeling requirements for added sugars and WHO sugar intake guidelines shape formulation decisions across North American and European manufacturing, while EFSA novel food approvals determine which alternative sweeteners gain market access in EU territories. The EU Green Deal packaging directives and state-level bottle-deposit programs in Germany and California are forcing material transitions from conventional PET toward recycled-content and aluminum alternatives. Stakeholders must monitor evolving sweetener safety assessments and packaging compliance timelines to anticipate reformulation costs and channel redistribution requirements.
Market Dynamics
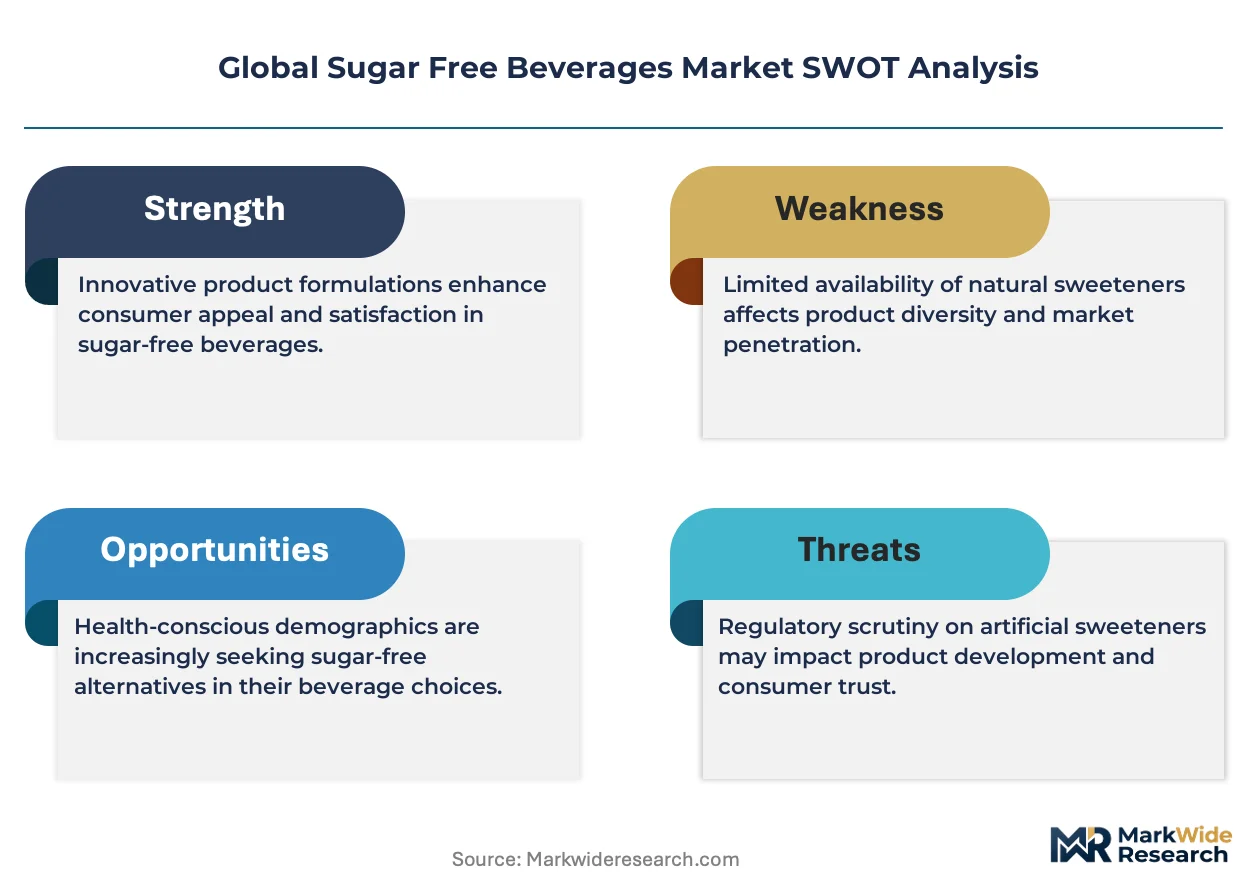
The sugar free beverages sector is undergoing a fundamental restructuring as WHO sugar reduction guidelines force multinational reformulation cycles across legacy portfolios. Capital allocation now favors flexible contract manufacturing networks over fixed bottling assets.
Growth Catalysts
- Metabolic Health Awareness:Diabetes prevalence in Mexico and India is accelerating consumer migration from sucrose-sweetened carbonates to stevia-based alternatives. Retailers in São Paulo and Mumbai are expanding dedicated shelf facings for zero-calorie functional lines.
- FDA Added Sugars Labeling:The 2016 Nutrition Facts overhaul mandates gram-level disclosure of added sugars, compelling US beverage producers to reformulate or face competitive disadvantage in supermarket channel negotiations.
- Stevia-Erythritol Blending:Advanced enzymatic processing is reducing aftertaste profiles in plant-derived sweetener systems, enabling cleaner sensory matches to conventional sugar across cola and citrus flavor architectures.
Market Restraints
- Input Cost Volatility:Erythritol supply concentrates in Chinese fermentation facilities, exposing formulators to freight and energy cost swings that compress margin structures during contract renegotiations.
- EFSA Novel Food Timelines:European approvals for emerging sweeteners like allulose and brazzein extend 18-36 months, blocking market entry for innovators ahead of US FDA determinations.
- Technical Limitation:Aspartame thermal degradation above 85°C restricts hot-fill processing applications, excluding the ingredient from aseptic tea and coffee formulations where sucralose dominates.
Strategic Opportunities
- Indonesia Underpenetration:Per-capita zero-calorie beverage consumption remains 12% of Japanese levels, creating whitespace for localized flavor development targeting tropical fruit profiles and halal certification requirements.
- Direct-to-Consumer Subscription:Fitness-oriented brands are bypassing traditional retail slotting fees through personalized replenishment models, capturing lifetime value data that informs rapid SKU iteration.
- EU Green Deal Packaging:Mandatory recycled content thresholds for PET bottles by 2030 are accelerating aluminum can conversion investments, favoring producers with existing metal packaging partnerships.
Industry Challenges
- Flavor Chemist Scarcity:The specialized expertise required to mask alternative sweetener off-notes in complex botanical formulations commands premium compensation, constraining mid-tier brand R&D throughput.
- Legacy System Integration:Existing ERP and quality management platforms at major bottlers require multimillion-dollar upgrades to trace batch-level sweetener provenance for evolving EU digital product passport mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sugar Free Beverages Market |
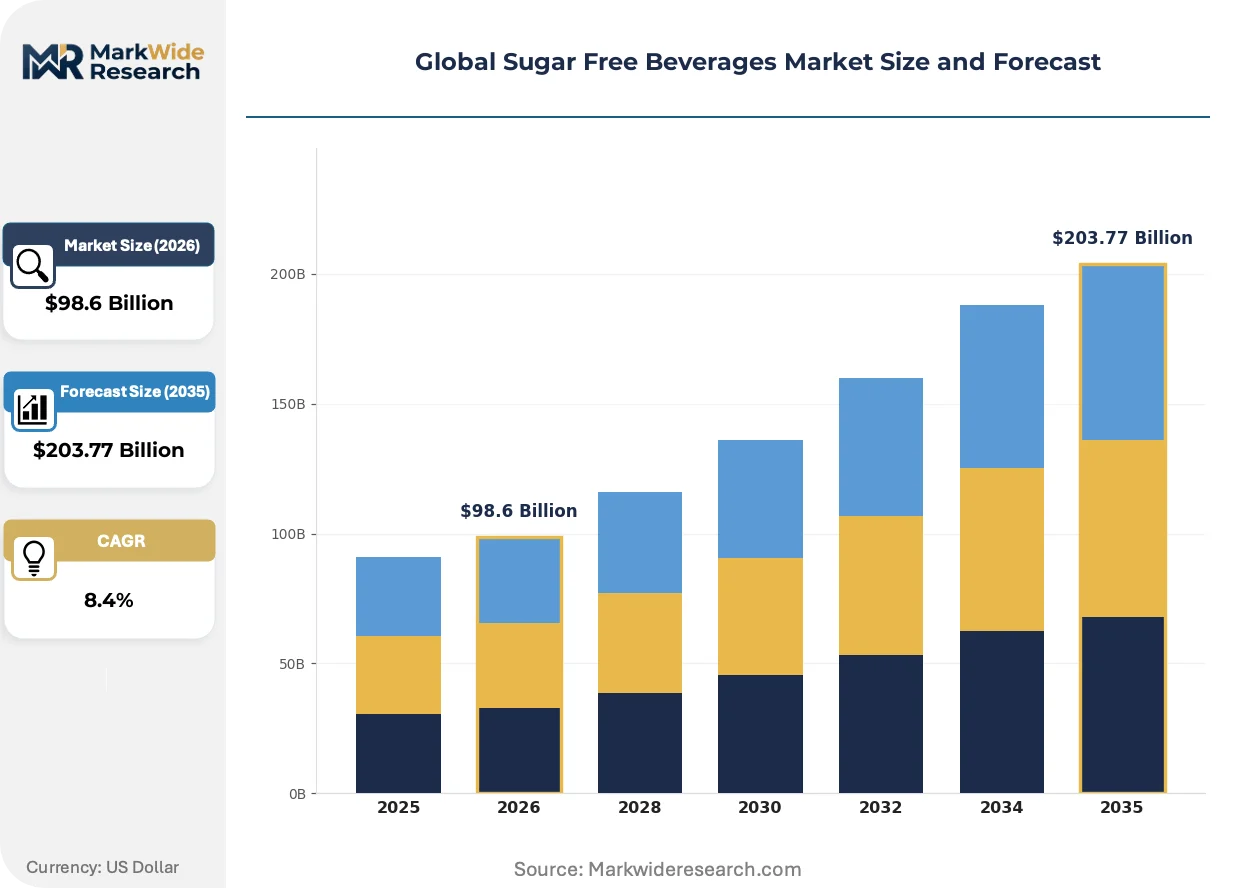
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $203.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodas, Sports Drinks, Functional Beverages, Iced Teas End User: Health-Conscious Consumers, Diabetics, Athletes, Weight Watchers Distribution Channel: Online Retailers, Supermarkets, Convenience Stores, Wholesale Distributors Packaging Type: RTD Cans, Tetra Packs, Glass Bottles, PET Bottles |
| Companies Covered | Monster Beverage Corporation, Red Bull GmbH, The Coca-Cola Company, Suntory Holdings Limited, Celsius Holdings Inc., PepsiCo, Inc., Keurig Dr Pepper Inc., The Kraft Heinz Company, Nestlé Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sugar Free Beverages Market Strategic Shifts
Reformulation science is converging with precision fermentation and AI-driven sensory mapping to compress development cycles. Three developments are restructuring competitive advantage.
Precision fermentation-derived sweeteners are displacing agricultural extraction methods for steviol glycosides and rare sugars. Biotech suppliers in California and Singapore are scaling tank-based production that eliminates crop yield dependency and pesticide residue concerns. Major beverage formulators in Germany and Japan are qualifying these inputs for 2025-2027 product launches, compressing traditional agrifood supply chain margins.
EU F-Gas Regulation phase-down schedules are accelerating cold-chain infrastructure transitions toward natural refrigerant systems. Supermarket retailers in France and Italy face compliance deadlines that favor ambient-stable beverage formats over chilled distribution, reshaping shelf-stable functional drink development priorities. Bottlers with heat-tolerant formulation capabilities are capturing expanded private-label contracts.
Consumer pantry consolidation is compressing purchase decision cycles from habitual brand loyalty toward trial-driven discovery. Subscription box services and TikTok-native discovery algorithms in Brazil and South Korea are displacing traditional television advertising as the primary awareness driver for emerging zero-calorie brands. Weekend athletes in these markets now source hydration products through influencer-curated bundles rather than supermarket aisle browsing.
Global Sugar Free Beverages Market Segmentation
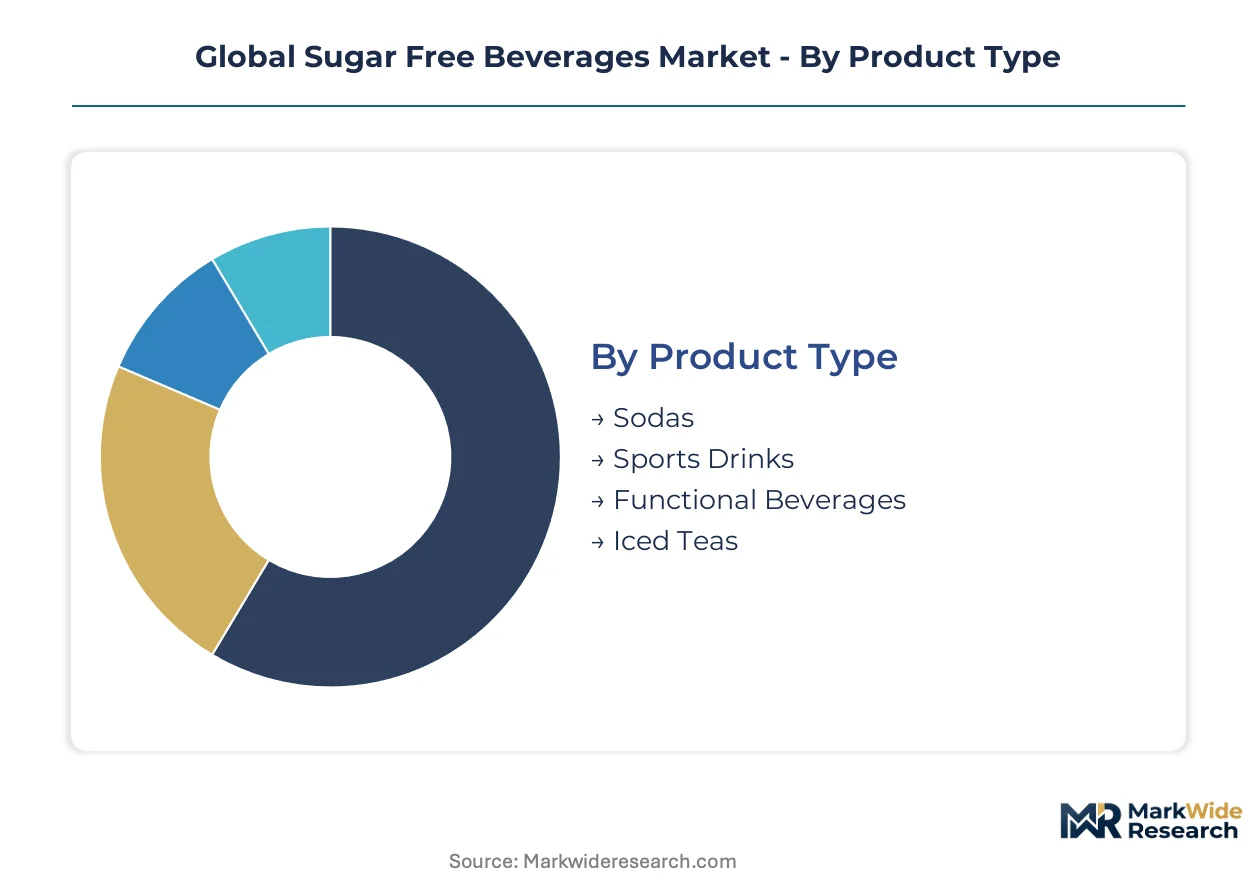
Sugar free beverage producers configure manufacturing assets and marketing spend around distinct consumption occasions and physiological needs. Segment boundaries determine sweetener selection, packaging format, and channel prioritization.
Product Type:
Premium ingredient costs and functional claims concentrate margin pools in formulations targeting metabolic performance rather than simple refreshment.
- Functional Beverages:Probiotic, adaptogenic, and nootropic formulations command shelf-space priority through ingredient premiums. Demand concentrates in Germany and Japan as WHO sugar guidelines tighten formulation standards for health-positioned products.
- Sports Drinks:Electrolyte-enhanced zero-calorie formulations serve athlete and weekend-warrior hydration routines beyond traditional glucose-based products. Weekend athletes in Brazil and South Korea now source these through influencer-curated bundles rather than supermarket aisles.
- Sodas:Stevia-erythritol blended colas and citrus profiles replicate conventional carbonates without caloric load. Reformulation cycles accelerate under FDA added sugars labeling mandates.
- Iced Teas:Aseptic-processed unsweetened and alternative-sweetened teas leverage heat-tolerant sucralose systems where aspartame degrades.
The dominant share belongs to Functional Beverages, while Sports Drinks is closing the gap fastest.
End User:
Physiological need states drive pricing tolerance, with medical necessity and athletic performance commanding steepest premiums over general wellness positioning.
- Athletes:Weekend warriors and competitive performers require rapid hydration with electrolyte balance and metabolic support. Fitness-oriented consumers in São Paulo and Mumbai expand dedicated shelf facings for zero-calorie functional lines.
- Diabetics:Medically necessary glucose management creates inelastic demand for verified zero-glycemic formulations. Diabetes prevalence in Mexico and India accelerates consumer migration from sucrose-sweetened alternatives.
- Health-Conscious Consumers:General wellness seekers prioritize clean-label sweeteners and functional ingredient transparency. Purchase decisions compress from habitual loyalty toward trial-driven discovery through TikTok-native algorithms.
- Weight Watchers:Caloric deficit maintenance drives selection of near-zero formulations with satiety-signaling ingredients.
Athletes capture the steepest pricing premium, while Diabetics provide the most stable volume baseline.
Distribution Channel:
Channel economics separate high-frequency replenishment models from discovery-driven trial formats, with data capture value tilting investment toward direct relationships.
- Online Retailers:Subscription-based replenishment bypasses traditional slotting fees while capturing lifetime value data for rapid SKU iteration. Personalized bundles displace television advertising as primary awareness drivers in Brazil and South Korea.
- Supermarkets:Dedicated shelf facings for zero-calorie lines expand in São Paulo and Mumbai as retailers respond to health-conscious migration. EU Green Deal packaging directives reshape private-label contract priorities toward recycled-content formats.
- Convenience Stores:Impulse-oriented single-serve purchases favor RTD cans and smaller PET formats for immediate consumption occasions.
- Wholesale Distributors:Bulk procurement for foodservice and institutional accounts concentrates volume in standardized SKUs with extended shelf stability.
Supermarkets retain volume leadership, though Online Retailers is expanding most quickly through subscription model economics.
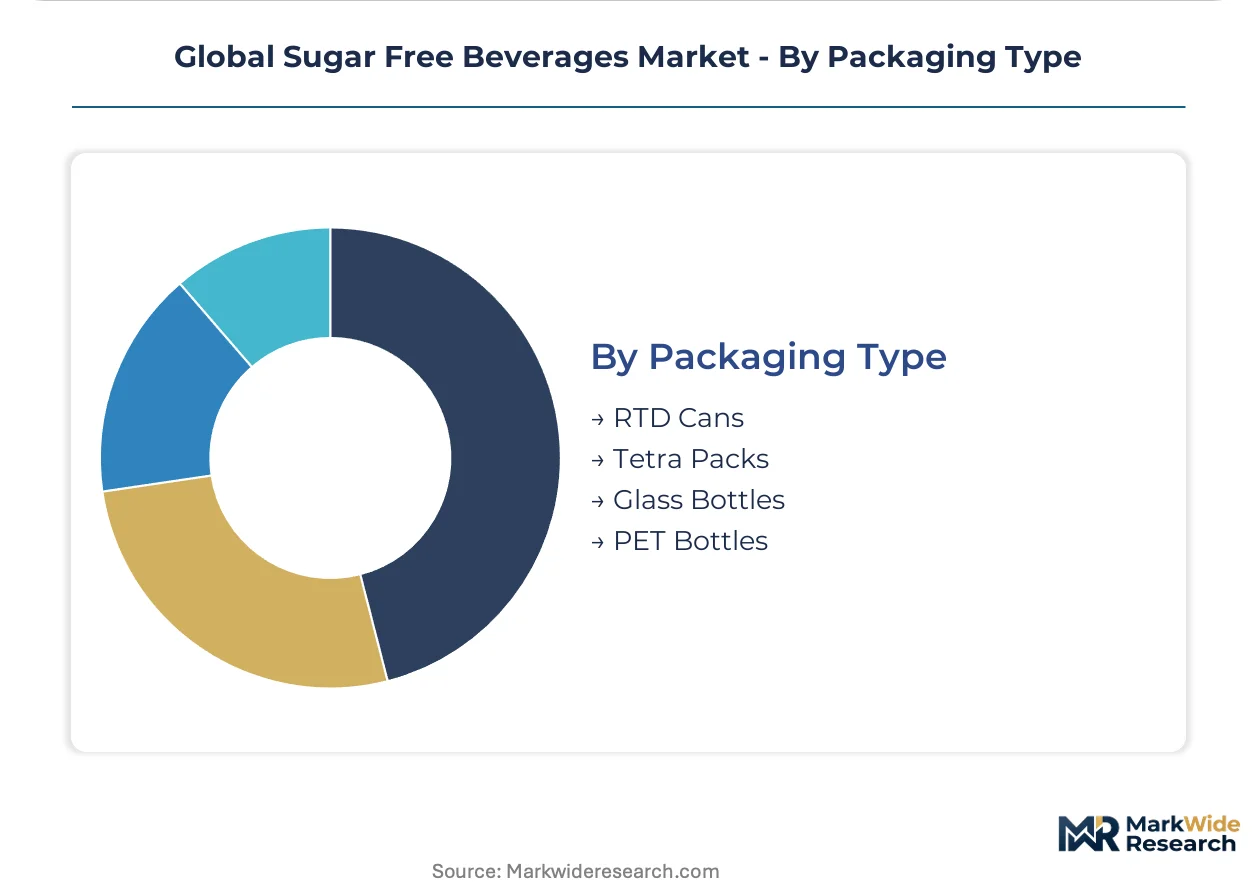
Packaging Type:
Material transitions under EU Green Deal mandates and state-level deposit programs are rotating advantage toward aluminum and recycled-content PET capabilities.
- RTD Cans:Aluminum formats bypass recycled-content PET threshold requirements while enabling thermal processing compatibility. Mandatory recycled content thresholds for PET bottles by 2030 accelerate aluminum conversion investments.
- PET Bottles:Lightweight conventional and recycled-content formats dominate volume through existing bottling infrastructure. Germany and California state-level bottle-deposit programs force material transitions toward recycled alternatives.
- Tetra Packs:Aseptic carton systems enable ambient-stable distribution for functional beverages without cold-chain dependency.
- Glass Bottles:Premium positioning and reusability cycles serve on-premise and deposit-system markets with higher per-unit economics.
PET Bottles hold installed base dominance, yet RTD Cans is gaining share fastest through regulatory-driven material transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Japan where WHO-compliant formulation standards command shelf-space premiums, while cost-sensitive markets in Brazil and India compress margin structures through localized sourcing requirements.
United States
FDA added sugars labeling mandates drive reformulation cycles across legacy carbonates and functional lines. State-level bottle deposit programs in California and New York force material transitions toward recycled-content PET. The Pacific Northwest cluster anchors precision fermentation R&D for next-generation steviol glycoside production.
Germany
Health-conscious consumers in Berlin and Munich expand zero-calorie functional beverage purchases as EFSA novel food approvals tighten ingredient standards. The EU Green Deal packaging directives mandate recycled content thresholds for PET bottles by 2030. The North Rhine-Westphalia industrial corridor concentrates contract manufacturing capacity for aluminum can conversion.
Japan
Aging demographics and metabolic health awareness accelerate demand for diabetes-compatible formulations in Tokyo and Osaka. METI guidelines on functional food claims shape probiotic and adaptogenic ingredient positioning. The Kanto region hosts advanced enzymatic processing facilities for stevia-erythritol blending systems.
Brazil
Weekend athlete segments in São Paulo and Rio de Janeiro drive sports drink consumption through influencer-curated subscription bundles. ANVISA labeling requirements for alternative sweeteners lag FDA and EFSA timelines, creating formulation complexity for multinational portfolios. The Southeast industrial belt concentrates flexible contract manufacturing for tropical fruit flavor development.
India
Diabetes prevalence in Mumbai and Delhi accelerates consumer migration from sucrose-sweetened carbonates to stevia-based alternatives. FSSAI standards on artificial sweetener maximum limits constrain formulation flexibility versus Western markets. The Maharashtra-Gujarat pharmaceutical corridor supplies fermentation-derived erythritol to domestic bottlers.
Global Sugar Free Beverages Market Competitive Environment
Concentration sits with multinational beverage conglomerates possessing global bottling partnerships and event marketing infrastructure. The competitive structure divides into three strategic archetypes: legacy carbonates with reformulation capabilities, premium energy specialists with controlled distribution, and digital-native functional brands with direct-to-consumer subscription models. Dominant competitive moves include aluminum can conversion investments under EU packaging mandates and precision fermentation partnerships for novel sweetener supply security.
Within the multinational conglomerate tier, The Coca-Cola Company and PepsiCo, Inc. occupy positions defined by bottling network scale and supermarket channel leverage. Red Bull GmbH exemplifies the premium energy archetype through event marketing anchoring and retail pricing discipline. Celsius Holdings Inc. represents the digital-native functional specialist segment with metabolism-positioned formulations targeting fitness-oriented consumers through subscription replenishment models.
| Leading Market Players |
|---|
| Monster Beverage Corporation |
| Red Bull GmbH |
| The Coca-Cola Company |
| Suntory Holdings Limited |
| Celsius Holdings Inc. |
| PepsiCo, Inc. |
| Keurig Dr Pepper Inc. |
| The Kraft Heinz Company |
| Nestlé Inc. |
| Others |
Value Chain & Pricing Dynamics
Stevia-erythritol blending replacing legacy aspartame-sucralose systems simultaneously redraws procurement geography toward Chinese fermentation hubs and compresses formulation premiums as enzymatic processing achieves cost parity. Buyers now arbitrage between established high-intensity sweeteners and plant-derived alternatives based on thermal stability requirements and clean-label positioning.
Pricing Analysis
The customization-premium spread separates configured-to-order functional beverage formulations from standard carbonated SKUs. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with WHO-compliant formulations commanding shelf-space premiums in German and Japanese supermarkets. Pricing pressure stems from erythritol freight cost volatility out of Chinese ports, compressing margin structures during contract renegotiations. Health-conscious consumers in Tokyo and Berlin show lowest price sensitivity, while cost-driven buyers in São Paulo and Mumbai gravitate toward economy-tier stevia-sweetened carbonates.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo port congestion and Red Sea routing disruptions are elevating landed costs for erythritol and precision fermentation inputs. Supply concentrates in China for fermentation-derived sweeteners, India for pharmaceutical-grade excipients, and Germany for enzymatic processing equipment. Raw material dependencies span stevia leaf extraction, corn-derived erythritol feedstock, and allulose precursor chemicals. Single-source vulnerability around Chinese erythritol fermentation capacity exposes formulators to energy cost swings. Distribution runs through supermarket retail networks for volume, with direct-to-consumer subscription models capturing premium functional segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are restructuring competitive advantage as TikTok-native discovery algorithms and subscription replenishment models displace traditional slotting-fee gatekeeping, creating interoperability between influencer ecosystems and direct-to-consumer fulfillment infrastructure.
For Market Incumbents: Compound aluminum can conversion investments under EU Green Deal mandates to defend manufacturing flexibility against contract manufacturing networks. Lock in precision fermentation partnerships for steviol glycoside supply security as biotech suppliers scale tank-based production. Prioritize ERP upgrades for EU digital product passport traceability requirements.
For New Entrants and Emerging Players: Fitness-oriented subscription service gaps where incumbents under-serve weekend warriors in São Paulo and Mumbai offer the most penetrable whitespace. Target tropical fruit flavor localization for Indonesian halal certification requirements. Deploy influencer-curated bundle discovery as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing networks possessing flexible bottling infrastructure and aluminum can partnerships. Five-to-ten year viability hinges on sweetener supply diversification and packaging compliance capabilities. Watch EFSA novel food approval timelines for allulose and brazzein as inflection indicators for European market entry economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Biotech suppliers in California and Singapore displace agricultural extraction for steviol glycoside supply security. |
| Aluminum Can Conversion Investment | Mandatory EU recycled-content thresholds by 2030 favor metal packaging partnerships over PET infrastructure. |
| Direct-to-Consumer Subscription Launch | Fitness-oriented brands bypass supermarket slotting fees while capturing lifetime value data for SKU iteration. |
| ERP Traceability Upgrade | Batch-level sweetener provenance systems satisfy evolving EU digital product passport mandates. |
| Tropical Flavor Localization | Halal-certified formulations targeting Indonesian underpenetration capture whitespace at 12% of Japanese per-capita consumption. |
Study Parameters
Cross-validation between primary interviews with beverage formulation scientists, contract manufacturing executives, supermarket category buyers, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA GRAS notifications, EFSA novel food opinions, WHO sugar guideline publications, and customs trade data for erythritol and stevia extract shipments. Bottom-up SKU-level volume builds triangulate against top-down category expenditure estimates.
Sensitivity analysis around sweetener cost volatility and packaging compliance timelines shapes the analytical framework across the analysis window. Segmentation dimensions span product type, end-user physiological need state, distribution channel economics, and packaging material format. CAGRs derive from normalized growth rate convergence across modeled scenarios, with inputs including diabetes prevalence trajectories in Mexico and India, FDA labeling enforcement intensity, and EU Green Deal implementation schedules.
Material uncertainties — EFSA approval delays for emerging sweeteners, Red Sea logistics disruptions, and Indonesian regulatory harmonization — sit outside the modeled envelope. Forecasts reflect documented assumptions about reformulation cost pass-through and channel migration velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Pearl Milk Tea Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Non-Dairy Beverages Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market