
 Carbonated Ready-To-Drink Tea Market | 2026-2036
Carbonated Ready-To-Drink Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Carbonated Ready-To-Drink Tea Market Analysis
Asset-light co-manufacturing partnerships is reconfiguring competitive entry barriers for emerging brands in carbonated ready-to-drink tea. PepsiCo leverages its bottler network and fountain infrastructure to sustain shelf dominance across mass retail. Coca-Cola anchors its position through captive cold-chain distribution and cross-category placement with sparkling water portfolios. Unilever competes via tea-origin credibility and botanical sourcing relationships that predate the RTD format.
Carbonated ready-to-drink tea denotes tea extract-based beverages infused with carbon dioxide, typically containing brewed tea solids, acidulants, and flavoring systems at pH levels between 2.5 and 4.0, manufactured through hot-fill or aseptic cold-fill processes to preserve volatile aromatic compounds. The category serves refreshment occasions previously captured by conventional soft drinks while offering perceived functional benefits associated with tea polyphenols. Green tea formulations command premium positioning in specialty shops and online retail channels where antioxidant claims support higher price realization. Cans represent the fastest-growing packaging type due to aluminum recycling credentials and portability for convenience store consumption. Supermarkets remain the volume anchor but face margin compression from private-label entrants.
FDA governs nutrition labeling and health claim substantiation for products sold in the United States, while EFSA and national regulators across Europe enforce additive permissions and botanical safety assessments under evolving Novel Food frameworks. China's SAMR mandates GB standards compliance for carbonated beverages including microbiological limits and additive maximums that affect formulation flexibility. Stakeholders must monitor how divergent sugar taxation regimes and packaging extended producer responsibility laws reshape cost structures and regional product portfolios.
Market Dynamics
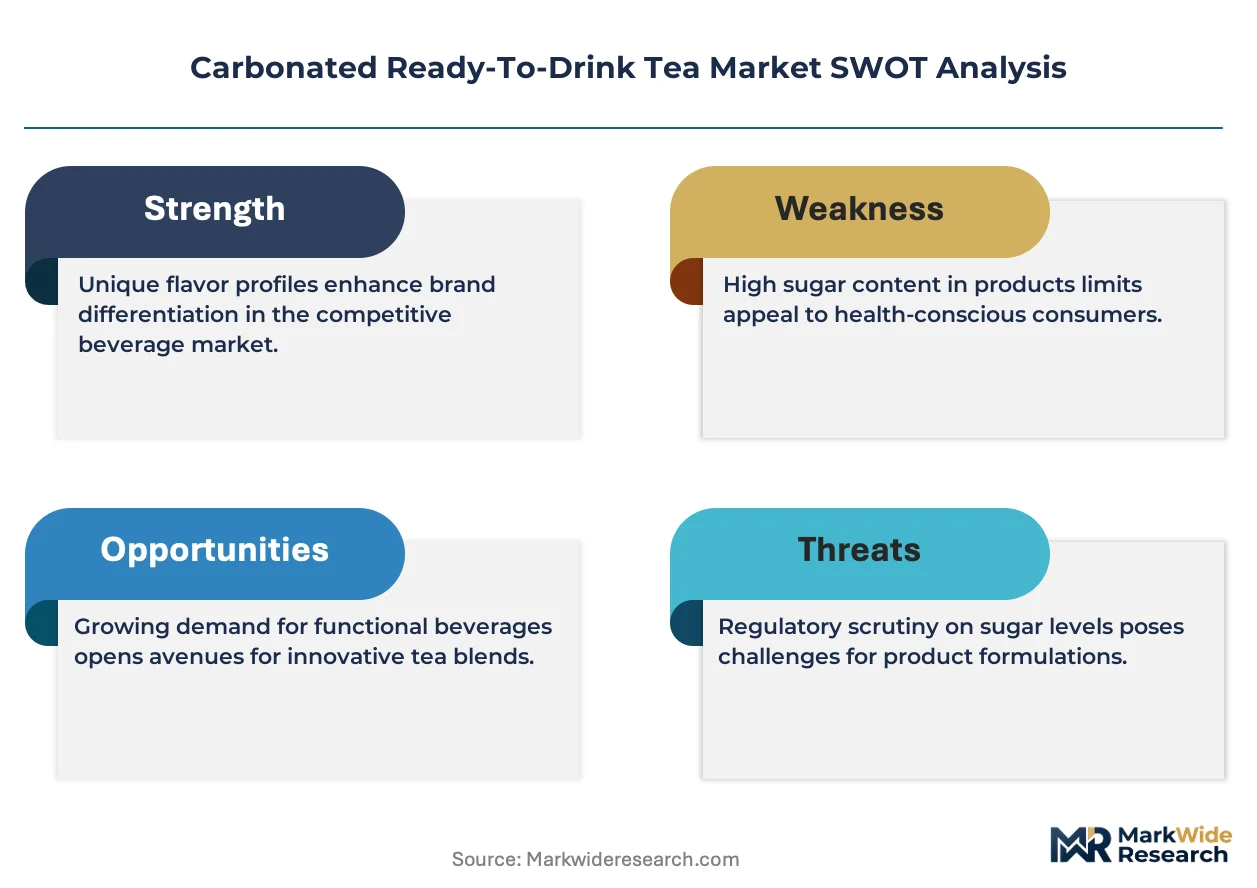
Reformulation pressure from sugar taxation regimes and FDA labeling mandates is compressing margins while forcing rapid portfolio pivots toward reduced-sugar and clean-label profiles across the carbonated ready-to-drink tea category.
Growth Catalysts
- Dual carbon goals in China:SAMR's streamlined GB standards approval for low-sugar carbonated beverages accelerates product registration timelines for reformulated SKUs entering convenience channels.
- Aluminum recycling infrastructure:Extended producer responsibility laws in the European Union drive can format adoption as brands seek packaging with verified circular credentials.
- Botanical sourcing protocols:Tea-origin traceability systems leveraging blockchain verification satisfy antioxidant claim substantiation requirements under EFSA health claim frameworks.
Market Restraints
- Tea extract supply concentration:Premium green tea solids sourcing clusters in specific prefectures of Japan and provinces of China, exposing brands to climate-driven harvest volatility.
- Aseptic cold-fill capex barriers:Equipment for preserving volatile aromatic compounds requires substantial upfront investment, limiting co-manufacturing partner availability for emerging entrants.
- Acidulant cost volatility:Citric and malic acid prices fluctuate with bio-based feedstock competition from other food and industrial applications.
Strategic Opportunities
- Convenience channel penetration in India:Modern trade expansion and FSSAI's clarified additive permissions for carbonated beverages create whitespace for RTD tea formats in Tier-2 cities.
- Functional ingredient convergence:Adaptogen and nootropic botanical infusions paired with carbonated tea bases target wellness-oriented young adult consumption occasions.
- Deposit-return scheme alignment:EU Green Deal packaging mandates reward early can-format adopters with reduced compliance fees and preferential retail placement.
Industry Challenges
- pH stability formulation expertise:Maintaining tea polyphenol bioactivity across shelf life at 2.5-4.0 pH requires specialized food chemistry talent scarce in emerging brand R&D teams.
- Multi-regulatory registration timelines:Simultaneous FDA, EFSA, and SAMR compliance submissions for global SKUs create bottlenecks in product launch calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbonated Ready-To-Drink Tea Market |
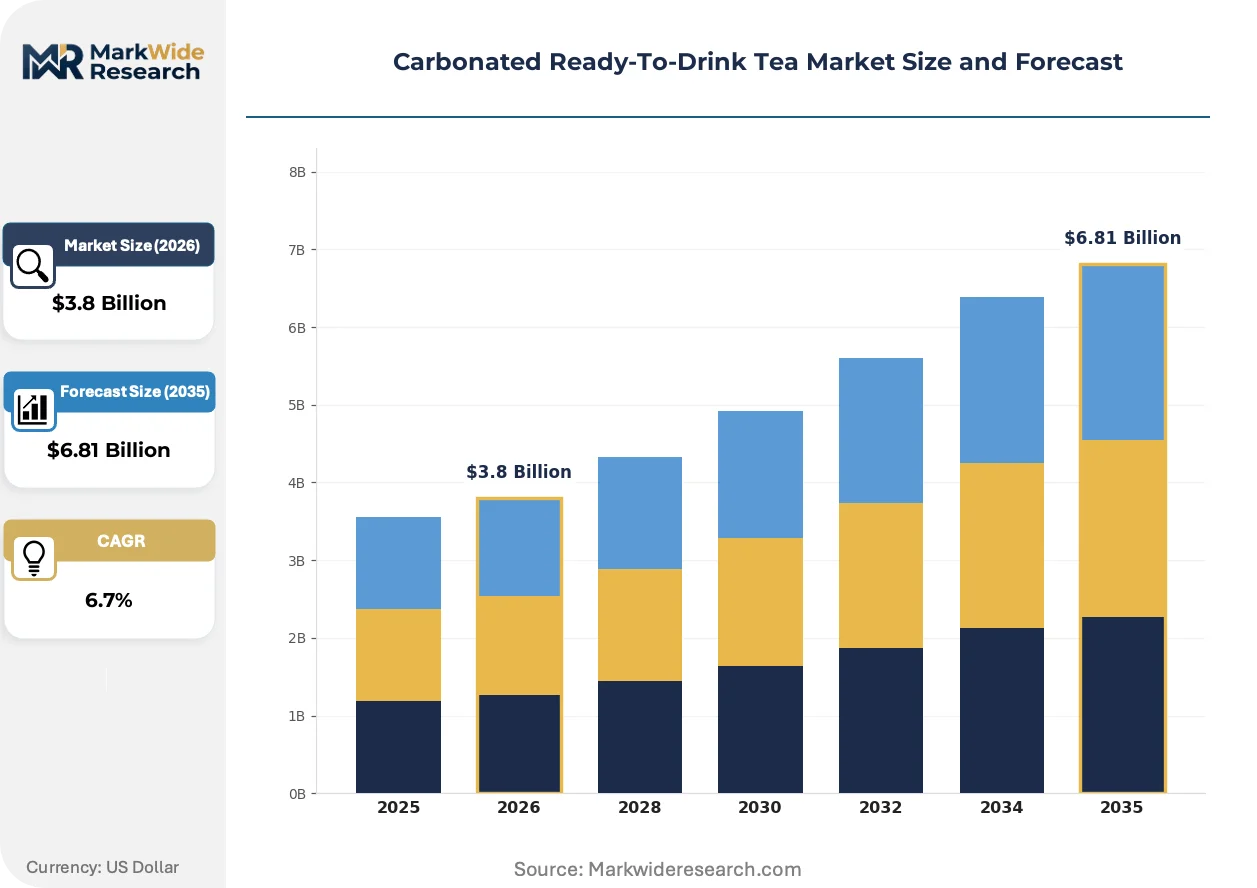
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal, Black Tea, Green Tea, Fruit Infusions Flavor Profile: Lemon, Peach, Mango, Berry Packaging Type: Pet Bottles, Cans, Glass Bottles, Tetra Packs Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops |
| Companies Covered | Talking Rain, Sunny Delight Beverages Co., TeaZazz, PepsiCo, Suja Juice, Unilever, Coca-Cola, Lactalis, Starbucks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbonated Ready-To-Drink Tea Market Emerging Trajectories
Digital formulation platforms and precision fermentation are compressing development cycles while regulatory divergence between major markets forces parallel track compliance strategies.
Aseptic nitrogen dosing technology is virtualizing traditional hot-fill preservation methods by enabling ambient-stable carbonated tea production without thermal degradation of catechin compounds. Mid-size brands in the United States adopt this equipment to bypass captive cold-chain dependencies of established distributors. The technology is virtualizing shelf-life extension economics, allowing regional players to compete on freshness claims previously reserved for fountain and chilled formats.
EFSA's evolving Novel Food framework for botanical extracts is tightening safety assessment requirements for non-traditional tea varieties and functional additives in carbonated RTD formulations. Manufacturers must now submit comprehensive toxicological dossiers for ingredients previously grandfathered under general food safety provisions. Carbonated green tea lines with added adaptogens face the steepest compliance burden, with several SKUs delayed in German and French market entry pending novel food status determination.
Young adult buyers in convenience channels now prioritize antioxidant transparency and sugar content visibility over brand heritage when making impulse purchases. Specialty retailers and direct-to-commerce platforms capture this shift through front-of-pack certification callouts and subscription models with personalized flavor profiling. Japan's kombini chains and China's unmanned refrigerated cabinets represent the most advanced deployment of this behavioral data, with dynamic pricing tied to real-time inventory and demographic foot traffic analysis.
Carbonated Ready-To-Drink Tea Market Segmentation
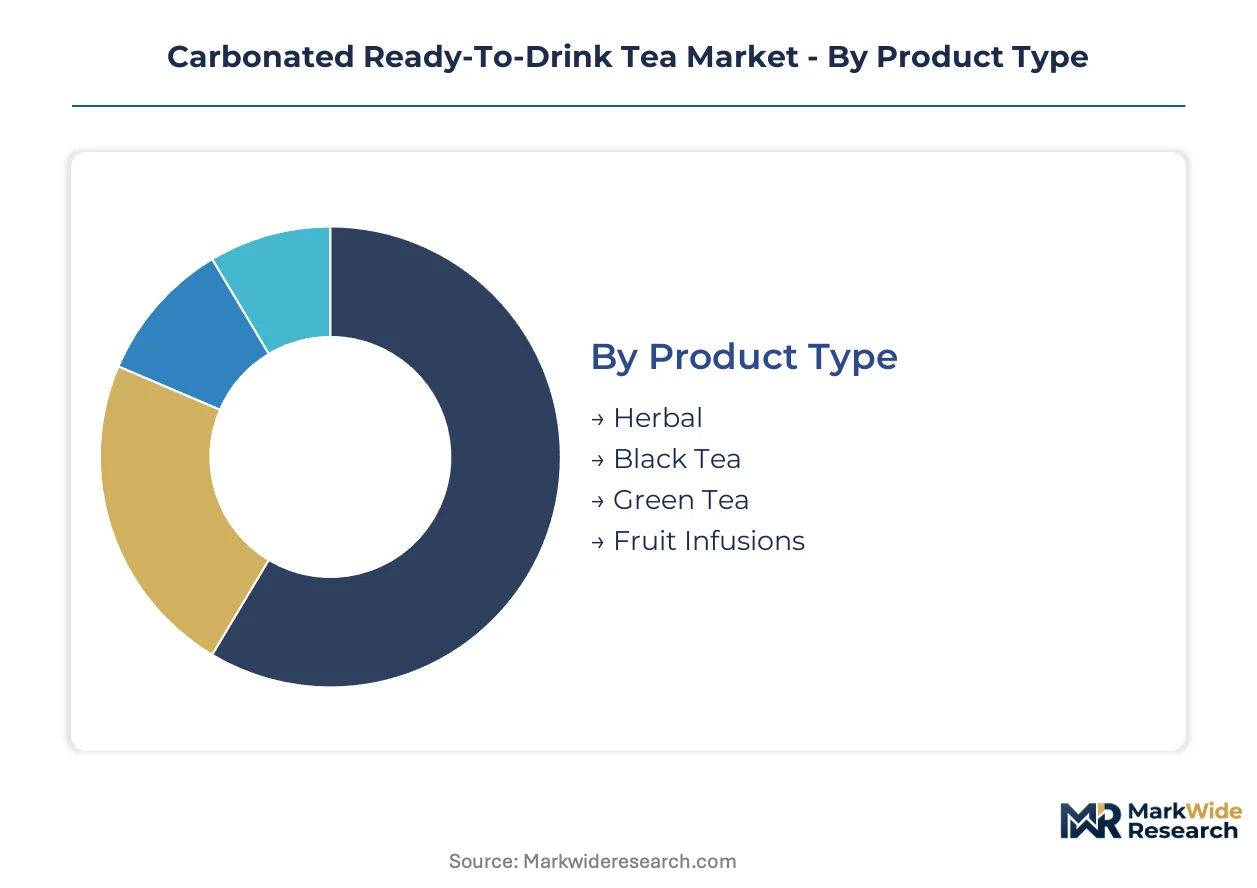
Carbonated ready-to-drink tea segmentation reveals distinct velocity profiles across product cycles. Green tea SKUs rotate fastest in convenience channels while glass formats linger in specialty retail. Understanding these turnover differentials shapes inventory deployment and margin capture strategies.
Product Type:
Green tea formulations command the shortest production-to-purchase cycle in the category, driven by antioxidant positioning and seasonal harvest freshness windows. Herbal variants exhibit the longest shelf residency due to broader flavor tolerance thresholds and lower perishability concerns.
- Green Tea:Catechin-rich extracts from Japanese prefectures and Chinese provinces undergo rapid formulation-to-market cycles to preserve volatile aromatic compounds. Young adult buyers in China's unmanned refrigerated cabinets and Japan's kombini chains drive velocity through wellness-oriented impulse purchasing.
- Black Tea:Oxidized tea solids deliver bolder flavor profiles that withstand longer distribution timelines without sensory degradation. Demand clusters in the United States where traditional tea consumption patterns merge with carbonated refreshment occasions.
- Herbal:Botanical infusions including rooibos and chamomile base materials offer caffeine-free alternatives with extended stability windows.
- Fruit Infusions:Hybrid formulations combining tea extracts with fruit purees target flavor novelty seekers in direct-to-commerce channels.
Black tea anchors the volume base while green tea gains share at the steepest rate.
Flavor Profile:
Cost-tier stratification separates commodity citrus positioning from premium tropical variants. Lemon formulations occupy economy shelf placements while mango commands price premiums in specialty channels.
- Lemon:Citric acid compatibility with tea tannins creates stable, low-cost flavor systems dominating mass retail. United States supermarkets favor this profile for private-label carbonated RTD tea lines seeking parity with mainstream soft drinks.
- Mango:Tropical positioning supports antioxidant claim stacking and premium pricing in online retail and specialty shops. Supply volatility in Alphonso puree sourcing from Indian growing regions constrains formulation flexibility.
- Peach:Stone fruit essences balance accessibility with perceived sophistication across convenience store and supermarket placements.
- Berry:Anthocyanin-rich coloration supports clean-label positioning despite higher raw material costs from concentrated extract sourcing.
Lemon flavoring captures the broadest geographic penetration while mango climbs fastest in revenue contribution per liter.
Packaging Type:
Aluminum can adoption accelerates most quickly among formats, displacing PET dominance in convenience channels. Glass retains niche positioning where premium perception justifies weight and fragility tradeoffs.
- Cans:Aluminum recycling credentials align with EU Green Deal packaging mandates and deposit-return scheme incentives. European brands leverage circular economy verification for preferential retail placement and reduced compliance fees.
- PET Bottles:Lightweight, shatter-resistant formats maintain volume leadership in supermarket and online retail channels where shipping economics favor reduced breakage rates.
- Glass Bottles:Premium positioning in specialty shops and on-premise accounts leverages tactile quality signals despite higher logistics costs.
- Tetra Packs:Aseptic carton formats serve ambient-stable distribution needs in emerging markets with underdeveloped cold-chain infrastructure.
PET bottles sustain the volume foundation while cans expand most quickly across regional portfolios.
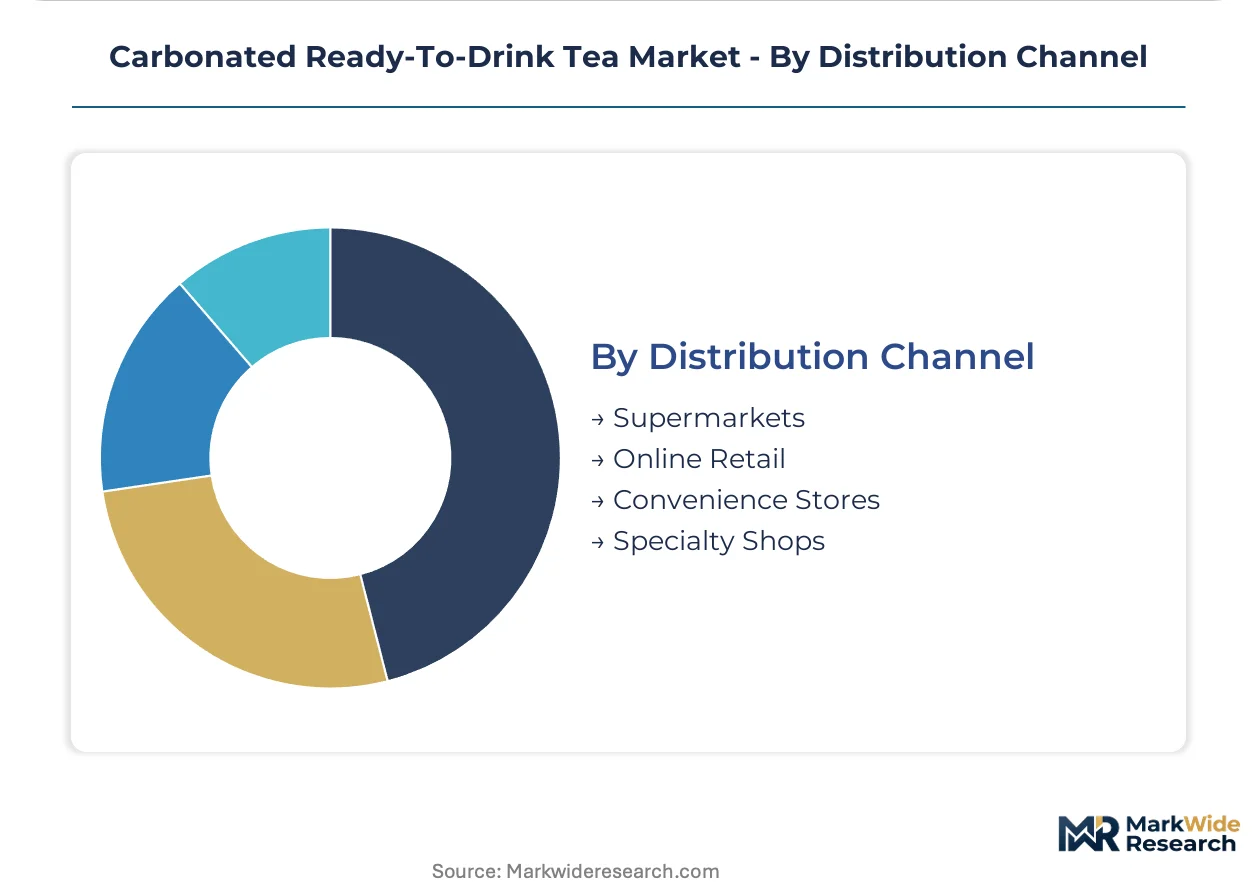
Distribution Channel:
Customer-type divergence separates planned pantry-loading behavior from impulse refreshment purchasing. Supermarket buyers stock for home consumption while convenience store traffic captures immediate consumption occasions.
- Convenience Stores:Refrigerated cabinet placement and dynamic pricing tied to foot traffic analytics maximize impulse conversion among young adult demographics. China's Tier-2 city expansion and India's modern trade growth create whitespace for RTD tea format penetration.
- Supermarkets:Cross-category placement with sparkling water and functional beverage sets drives basket expansion in planned shopping trips. Private-label entrants compress margins through shelf-space competition.
- Online Retail:Subscription models with personalized flavor profiling capture antioxidant transparency preferences among wellness-oriented segments.
- Specialty Shops:Curated assortments emphasizing tea-origin traceability and blockchain-verified botanical sourcing support premium price realization.
Supermarkets retain the volume anchor while convenience stores demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling mandates and China's dual carbon goals are reshaping formulation requirements across major consumption clusters. Convenience channel expansion in emerging economies creates whitespace for carbonated RTD tea penetration.
United States
Young adult consumers in convenience stores drive impulse purchasing through refrigerated cabinet placement. FDA nutrition labeling requirements force rapid portfolio pivots toward reduced-sugar profiles. California and New York metro areas anchor specialty retail channels where antioxidant transparency commands premium pricing.
China
Unmanned refrigerated cabinets in Tier-2 cities capture wellness-oriented impulse buying among young demographics. SAMR's streamlined GB standards approval accelerates product registration timelines for low-sugar reformulations. Yangtze River Delta manufacturing clusters concentrate aseptic cold-fill capacity for volatile aromatic preservation.
Japan
Kombini chains deploy dynamic pricing tied to real-time foot traffic analytics for maximum conversion. METI oversees food additive permissions affecting carbonated beverage formulation flexibility. Kanto region production facilities specialize in catechin-rich green tea extract processing for premium positioning.
Germany
Deposit-return scheme alignment under EU Green Deal packaging mandates rewards aluminum can adoption with reduced compliance fees. EFSA's Novel Food framework tightens safety assessments for adaptogen-infused carbonated tea lines. Bavaria-based bottling partnerships serve central European distribution networks.
India
Modern trade expansion in Tier-2 cities creates penetration opportunities for RTD tea formats previously confined to metropolitan markets. FSSAI clarified additive permissions for carbonated beverages reduce regulatory uncertainty for new entrants. Maharashtra and Gujarat manufacturing corridors develop co-manufacturing capacity for emerging brands.
Carbonated Ready-To-Drink Tea Market Vendor Landscape
On the supply side, the industry is consolidating around beverage conglomerates with captive distribution infrastructure and captive cold-chain networks. Three strategic archetypes dominate: multinational soft drink giants leveraging bottler relationships, tea-origin specialists with botanical sourcing credibility, and emerging wellness brands pursuing direct-to-commerce channels. Competitive moves center on co-manufacturing partnerships for asset-light entry and aluminum can format transitions for circular economy compliance.
Within the multinational tier, PepsiCo and Coca-Cola exemplify scale-driven positioning through bottler network control and cross-category placement strategies. Unilever occupies a distinct archetype as a tea-origin specialist with pre-existing botanical sourcing relationships. Among emerging entrants, Talking Rain represents the wellness-oriented direct-to-commerce vector targeting young adult demographics through antioxidant transparency claims.
| Leading Market Players |
|---|
| Talking Rain |
| Sunny Delight Beverages Co. |
| TeaZazz |
| PepsiCo |
| Suja Juice |
| Unilever |
| Coca-Cola |
| Lactalis |
| Starbucks |
| Others |
Supply Flow & Price Mechanics
Climate-driven harvest volatility in Japanese prefectures and Chinese provinces determines both pricing tier spreads and supply chain shape across the carbonated ready-to-drink tea category. Premium green tea extract sourcing clusters expose brands to simultaneous cost inflation and margin compression.
Pricing Analysis
Tea-origin certification level creates the primary spread between premium and economy tiers in this market. Three-tier pricing structure across premium, standard, and economy levels reflects catechin concentration, antioxidant claim substantiation, and blockchain-verified botanical traceability. Cost compression in the standard tier is intensifying because private-label entrants in United States supermarkets force parity pricing with mainstream soft drinks. Mass retail buyers exhibit the highest price sensitivity, while specialty shop consumers accept premiums for tea-origin credibility.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for global SKU portfolios. Premium green tea solids sourcing draws from specific prefectures in Japan, provinces in China, and emerging cultivation regions in India. Single-source vulnerability concentrates in Kanto region catechin processing facilities and Yangtze River Delta aseptic cold-fill capacity. Distribution runs through captive bottler networks for multinational incumbents and co-manufacturing partnerships for emerging brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbonated ready-to-drink tea functions as a platform-economics inflection where dynamic pricing algorithms in unmanned refrigerated cabinets reshape traditional refreshment distribution. Interoperability between real-time inventory systems and demographic foot traffic analytics creates new competitive moats.
For Market Incumbents: Build captive cold-chain infrastructure as the primary moat against asset-light challengers. PepsiCo and Coca-Cola should deepen bottler network control in convenience channels to block emerging wellness brands from refrigerated cabinet placement. Certification investment in EFSA Novel Food compliance creates regulatory barriers for adaptogen-infused line extensions. For New Entrants and Emerging Players: India's Tier-2 city modern trade expansion offers the most penetrable whitespace for carbonated RTD tea formats. Direct-to-commerce subscription models with personalized flavor profiling capture antioxidant transparency preferences among wellness-oriented young adults. FSSAI clarified additive permissions reduce regulatory uncertainty for new market entrants. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors tea-origin specialists with pre-existing botanical sourcing relationships. Long-term viability over the next decade hinges on aluminum can format transitions for EU Green Deal compliance. Watch EFSA Novel Food framework determinations for adaptogen-infused SKUs as the inflection signal for premium segment growth.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Capacity Expansion | Yangtze River Delta manufacturing clusters preserve volatile aromatic compounds for premium green tea formulations. |
| Aluminum Can Format Transition | EU deposit-return scheme alignment reduces compliance fees and secures preferential retail placement. |
| Blockchain Botanical Traceability | Tea-origin verification systems satisfy EFSA antioxidant claim substantiation requirements. |
| Reduced-Sugar Reformulation | FDA labeling mandates and sugar taxation regimes force rapid portfolio pivots toward clean-label profiles. |
| Convenience Channel Penetration | China's unmanned refrigerated cabinets and India's modern trade expansion capture impulse refreshment occasions. |
Methodological Framework
A spread of perspectives from brand managers, category buyers at retailers, co-manufacturing partners, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interviews with supply planners and channel sales heads combined with secondary validation from FDA filings, SAMR GB standards documentation, EFSA Novel Food registers, and Nielsen retail audit data. Bottom-up SKU velocity modeling and top-down category sizing triangulated market estimates.
Demand-supply balance across the analysis window anchored the forecast framework, with segmentation dimensions spanning tea type, flavor profile, packaging format, and distribution channel. CAGRs derived from historical velocity trends and projected channel expansion rates incorporated aseptic nitrogen dosing technology adoption curves and aluminum recycling infrastructure buildout timelines.
Practitioners should monitor climate-driven harvest volatility, divergent sugar taxation regime implementations, and EFSA Novel Food determination timelines for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Pearl Milk Tea Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
Non-Dairy Beverages Market
Non-Alcoholic Beverages
Soy Beverage Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Global Nonalcoholic Beverage Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market