
 Fruit-Infused Water Market | 2026-2036
Fruit-Infused Water Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit-Infused Water Market Analysis
Natural sweeteners and botanical extracts is realigning cost structures across the fruit-infused water category. Nestle Group leverages its bottled water infrastructure to secure shelf placement in premium retail channels. PepsiCo anchors volume through convenience store distribution networks. Hint Water differentiates via zero-calorie positioning and minimalist ingredient panels.
Fruit-infused water denotes still or carbonated water products containing fruit essences, extracts, or infusions without added sugars or artificial colorants, typically manufactured through cold-infusion or vacuum-extraction processes at temperatures below 40 degrees Celsius to preserve volatile aromatic compounds. The primary commercial purpose centers on delivering flavored hydration alternatives to sugar-sweetened beverages for health-oriented consumers. Sparkling variants command premium price positioning in urban markets, while organic certification creates margin pools through supply chain traceability requirements. Citrus-based formulations dominate volume given year-round raw material availability, though berries segments attract higher per-unit pricing in specialty health shops.
The FDA governs bottled water safety under 21 CFR 165.110, while EPA standards for source water quality establish baseline treatment protocols; both frameworks elevate compliance costs for new entrants. USDA organic certification and state-level bottle deposit legislation in California, New York, and Oregon shape regional distribution economics and packaging format decisions. Stakeholders must monitor evolving sugar-tax proposals at municipal levels and assess captive sourcing of organic fruit extracts to secure margin stability.
Market Dynamics
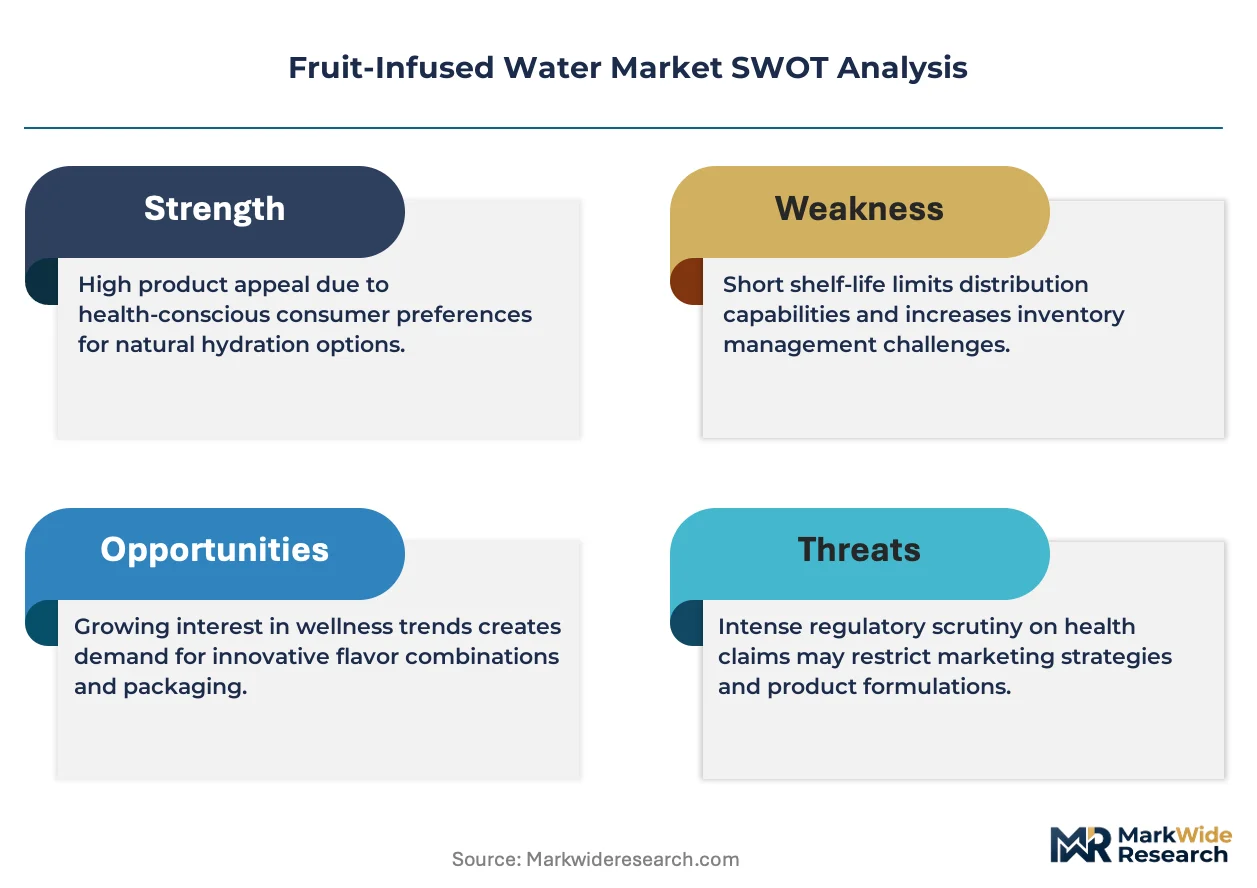
The FDA's updated Nutrition Facts labeling requirements for added sugars are forcing reformulation across the fruit-infused water category, compressing margins for manufacturers dependent on natural sweetener workarounds while rewarding zero-calorie positioning.
Growth Catalysts
- California and New York metropolitan clusters:Health-conscious millennials and Gen Z consumers in fitness and wellness programs drive concentrated adoption in these urban density centers.
- USDA organic certification:Supply chain traceability requirements create premium margin pools through verified sourcing protocols that command shelf price premiums.
- Cold-infusion processing:Vacuum-extraction below 40 degrees Celsius preserves volatile aromatic compounds, enabling clean-label positioning that satisfies FDA labeling scrutiny.
Market Restraints
- Organic fruit extract sourcing:Year-round citrus availability masks berry supply volatility, with organic certification adding 15-20% raw material cost premiums.
- State-level bottle deposit legislation:California, New York, and Oregon deposit schemes impose packaging format constraints and reverse logistics costs that disadvantage regional entrants.
- Sugar-sweetened beverage substitution:Zero-calorie carbonated waters and unsweetened teas compete for identical shelf space and consumer occasions.
Strategic Opportunities
- Sparkling variant expansion:Carbonated fruit-infused water commands urban premium pricing in specialty health shops and fitness channel placements.
- Municipal sugar-tax proposals:Pending legislation in progressive cities creates regulatory tailwinds for zero-added-sugar formulations that preempt taxation exposure.
- Botanical extract convergence:Adaptogenic and nootropic ingredient pairing with fruit essences opens functional hydration positioning beyond basic flavoring.
Industry Challenges
- Volatile aromatic compound retention:Cold-infusion process engineering requires specialized equipment and temperature control expertise that constrains scale-up velocity.
- Organic certification timeline:USDA organic approval cycles extend 12-18 months, delaying product launches and locking working capital in pre-certified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit-Infused Water Market |
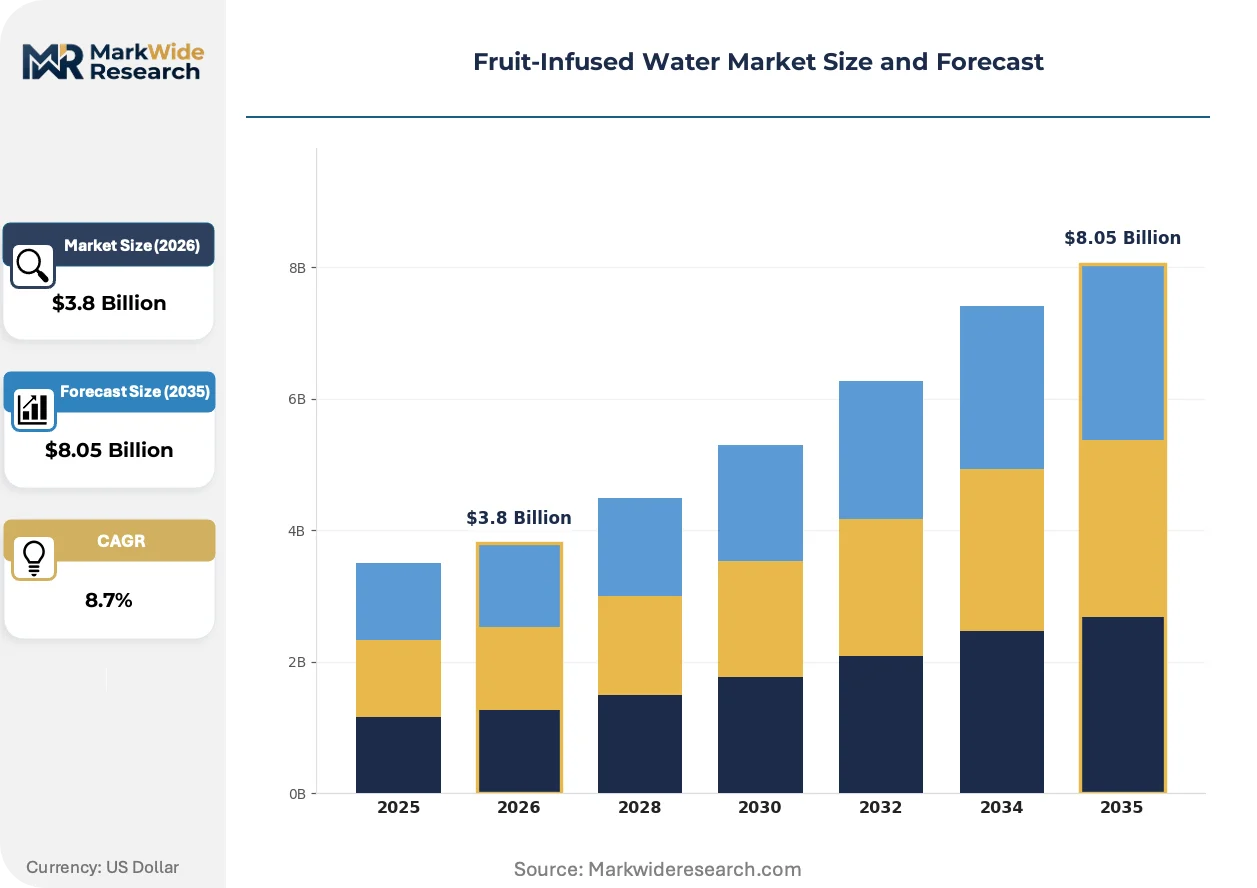
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Sparkling, Organic, Flavored Ingredients: Citrus, Berries, Herbs, Vegetables Packaging Type: Bottles, Pouches, Cartons, Jugs Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Shops |
| Companies Covered | Keurig Dr Pepper, Treo Brands, Nestle Group, Propel Water, Core Nutrition, PepsiCo, Hint Water, True Citrus, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit-Infused Water Market Emerging Trajectories
Formulation science and packaging engineering are converging to redefine competitive differentiation in fruit-infused water, with preservation technology and regulatory compliance emerging as the primary battlegrounds for margin defense.
High-pressure processing equipment is modularizing production economics for mid-scale manufacturers. Regional bottlers in Texas and Florida are adopting modular HPP units to bypass centralized co-packing dependencies. This technology is modularizing capital deployment, enabling 10,000-unit-batch production that previously required million-dollar line investments.
EPA source water quality standards under 40 CFR Part 141 are tightening pretreatment requirements for municipal water sourcing. Bottlers must now document multi-barrier treatment protocols that elevate baseline compliance costs. Sparkling variants face disproportionate impact due to carbonation equipment sterilization mandates.
Direct-to-subscription models are displacing traditional grocery channel dependence for premium positioning. Health-focused consumers in Seattle and Austin are migrating toward scheduled delivery platforms that guarantee cold-chain integrity. Fitness studios and corporate wellness programs represent the fastest-growing B2B subscription vertical.
Fruit-Infused Water Market Segmentation
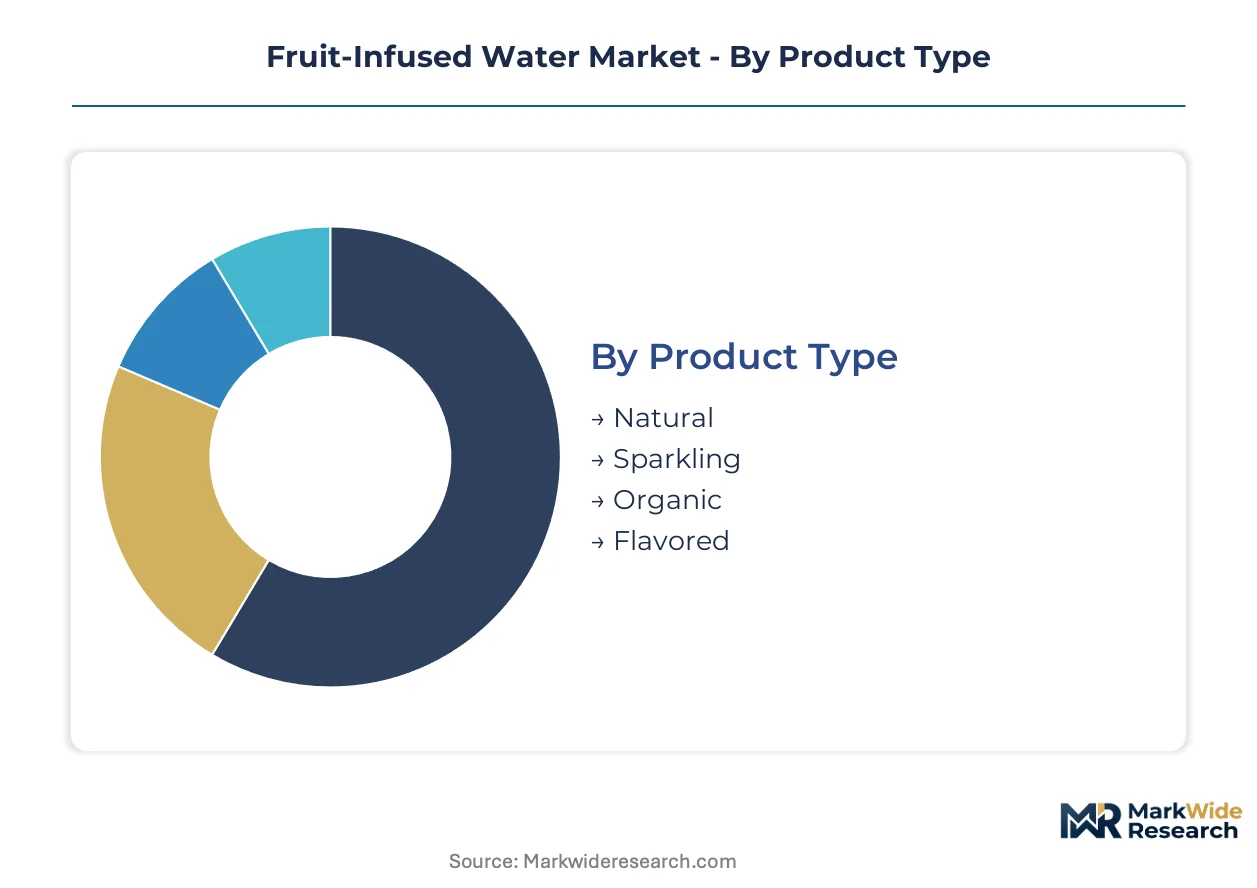
Segmentation in fruit-infused water reveals how certification burdens, processing complexity, and channel economics fragment addressable markets. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer positioning strategies.
Product Type:
USDA organic certification and FDA labeling requirements create divergent compliance timelines across product type segments, with cold-processed variants demanding specialized equipment validation and sparkling categories facing carbonation safety protocols.
- Natural:Still water with fruit essences extracted through vacuum or cold-infusion methods below 40 degrees Celsius, preserving volatile aromatic compounds without thermal degradation. Demand concentrates in California and New York metropolitan fitness studios where clean-label positioning commands shelf premiums.
- Sparkling:Carbonated water infused with fruit extracts requiring pressurized processing equipment and sterilization protocols under EPA source water standards. Urban specialty health shops in Seattle and Austin drive premium pricing for this segment.
- Organic:Formulations meeting USDA organic certification with 12-18 month approval cycles and supply chain traceability documentation. Verified sourcing protocols create margin pools through shelf price premiums.
- Flavored:Broader category encompassing natural and artificial flavoring systems with variable regulatory scrutiny depending on sweetener content and label claims.
Natural sits at the top of the volume ranking, with Sparkling climbing the fastest.
Ingredients:
Raw material availability and organic certification premiums drive cost tier differentiation across ingredient segments, with year-round sourcing capabilities separating volume leaders from specialty positioning.
- Citrus:Lemon, lime, orange, and grapefruit essences with established year-round supply chains from Florida, California, and Mediterranean growing regions. Bulk procurement scales constrain cost structures for mid-tier manufacturers.
- Berries:Strawberry, raspberry, blueberry, and blackberry extracts with pronounced seasonal volatility and 15-20% organic certification cost premiums. Supply concentration in Pacific Northwest and Chilean growing regions creates geographic sourcing risk.
- Herbs:Mint, basil, rosemary, and lavender botanical pairings enabling functional hydration positioning with adaptogenic claims. Emerging demand in corporate wellness programs drives B2B subscription growth.
- Vegetables:Cucumber, celery, and beet infusions targeting detox and wellness positioning with narrower consumer acceptance curves.
Citrus dominates absolute volume, with Herbs expanding most quickly through botanical convergence trends.
Packaging Type:
State-level bottle deposit legislation and reverse logistics economics reshape packaging format decisions, with California, New York, and Oregon deposit schemes imposing distinct cost structures on rigid versus flexible formats.
- Bottles:PET and glass formats with established recycling infrastructure but elevated deposit compliance costs in regulated states. Premium glass positioning in specialty health shops offsets logistics burden.
- Pouches:Flexible film formats with lower shipping cube and reduced reverse logistics exposure. Convenience store distribution networks favor this format for shelf-space efficiency.
- Cartons:Paper-based aseptic packaging with emerging adoption in subscription delivery platforms guaranteeing cold-chain integrity.
- Jugs:Bulk formats targeting fitness studios and corporate wellness programs with fountain dispenser compatibility.
Bottles retain the largest volume share, though Pouches are gaining share fastest through convenience channel expansion.
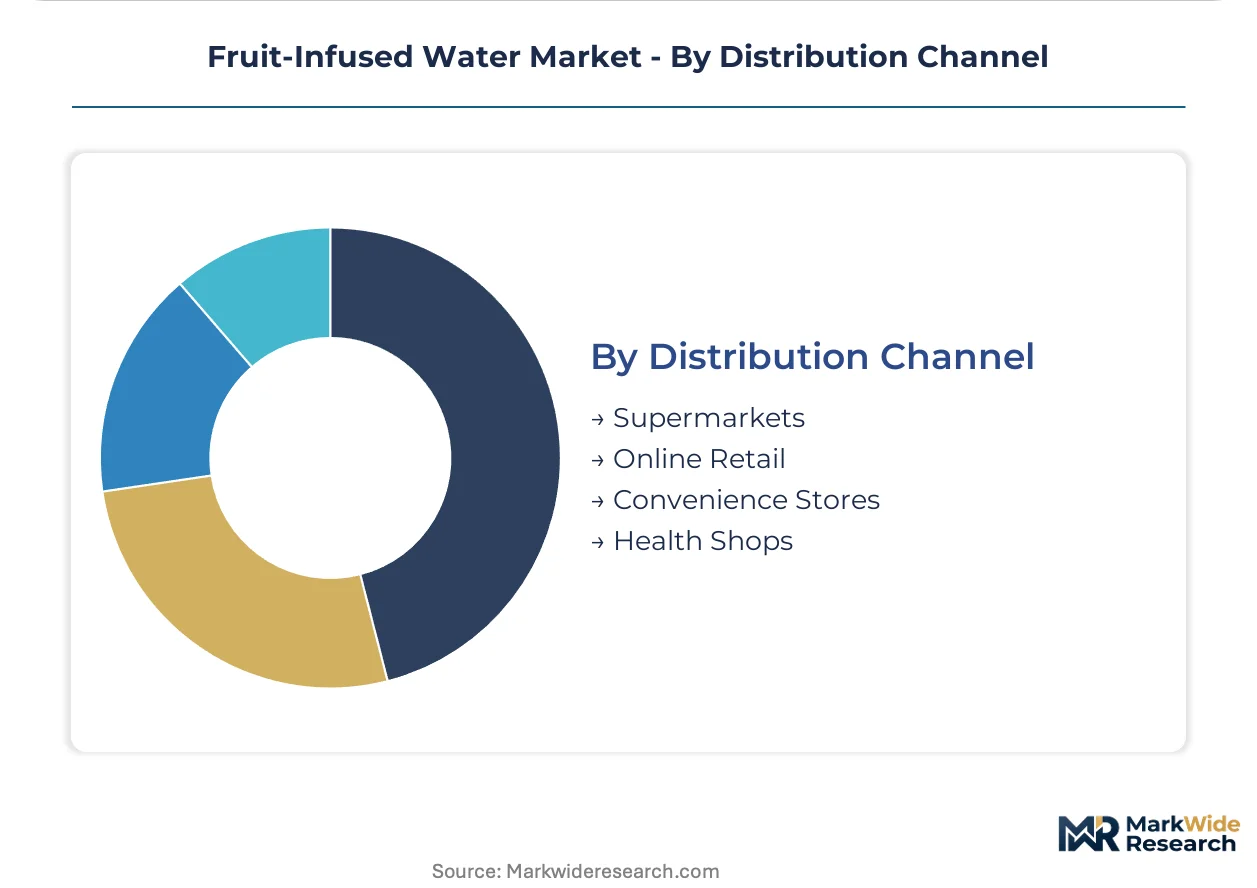
Distribution Channel:
Channel selection determines margin capture and consumer data access, with direct-to-subscription models displacing traditional grocery dependence for premium positioning while mass retail anchors volume scale.
- Supermarkets:Conventional grocery with slotting fee structures and promotional intensity compressing margins for emerging brands. Nestle and PepsiCo leverage existing bottled water infrastructure for shelf placement.
- Online Retail:E-commerce platforms and direct-to-subscription models enabling scheduled delivery with cold-chain guarantees. Seattle and Austin consumers migrate toward this channel for premium assortment access.
- Convenience Stores:Impulse-oriented channel with limited SKU count favoring established brands with distribution network density. Volume anchoring through grab-and-go positioning.
- Health Shops:Specialty retail with curated assortments and educated staff enabling premium pricing for organic and functional formulations.
Supermarkets maintain volume leadership, with Online Retail showing the steepest expansion trajectory through subscription platform growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California and New York metropolitan clusters anchor demand concentration for fruit-infused water, with health-conscious millennials and Gen Z consumers in fitness and wellness programs driving adoption. FDA labeling requirements and state-level bottle deposit legislation reshape regional distribution economics across multiple markets.
United States
Fitness studios and corporate wellness programs in California and New York metropolitan areas drive concentrated adoption. FDA's updated Nutrition Facts labeling requirements for added sugars force reformulation across domestic manufacturers. Cold-infusion processing facilities cluster in Pacific Northwest and Northeast corridor cities to preserve volatile aromatic compounds.
Germany
Sparkling fruit-infused water commands premium positioning in Berlin and Munich specialty health shops. EFSA clean-label standards and EU organic certification requirements elevate compliance timelines for imported formulations. Bavarian bottlers leverage established mineral water infrastructure to secure shelf placement in premium retail channels.
United Kingdom
Subscription delivery platforms in London and Southeast England guarantee cold-chain integrity for direct-to-consumer brands. UK Food Standards Agency labeling requirements for natural flavor claims constrain formulation flexibility. Manchester and Birmingham distribution hubs service expanding convenience store networks.
Japan
Functional hydration positioning with adaptogenic ingredients attracts health-focused consumers in Tokyo and Osaka metropolitan areas. Ministry of Health, Labour and Welfare standards for food with nutrient function claims create regulatory pathways for botanical extract pairings. Nagoya-based co-packers specialize in high-pressure processing equipment for mid-scale production.
Australia
Organic certification demand concentrates in Sydney and Melbourne wellness retail corridors. Food Standards Australia New Zealand requirements for natural sweetener labeling compress margins for reformulated products. Queensland citrus growers supply year-round raw material availability to domestic bottlers.
Fruit-Infused Water Market Vendor Landscape
Global majors compete with regional champions across distribution network density and clean-label positioning. The vendor base stratifies into three tiers: multinational beverage conglomerates with bottled water infrastructure, mid-scale organic specialists with USDA certification, and emerging subscription-native brands. Consolidation pressures concentrate around M&A activity targeting regional co-packing capabilities and portfolio diversification into functional hydration extensions.
Within the multinational tier, Nestle Group and PepsiCo exemplify scale-driven positioning through existing bottled water infrastructure and convenience store distribution networks. Among specialist players, Hint Water occupies a position defined by zero-calorie positioning and minimalist ingredient panels. The Coca-Cola Company anchors the premium sparkling segment through Propel Water and Core Nutrition brand extensions.
| Leading Market Players |
|---|
| Keurig Dr Pepper |
| Treo Brands |
| Nestle Group |
| Propel Water |
| Core Nutrition |
| PepsiCo |
| Hint Water |
| True Citrus |
| The Coca-Cola Company |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up mid-scale bottlers in Texas and Florida are consolidating regional co-packing capacity, tightening supply discipline while anchoring pricing power through captive sourcing of organic fruit extracts and modular high-pressure processing equipment deployment.
Pricing Analysis
Organic certification cost premiums pass through to shelf prices with 15-20% markups over conventional formulations, while sparkling variants command urban premium positioning in Seattle and Austin specialty channels. Price differentiation hinges on USDA certification tier and cold-infusion processing validation, with convenience store buyers showing highest price sensitivity and fitness studio procurement committees least sensitive due to wellness program budgets. Pricing pressure intensifies in the flavored segment as zero-calorie carbonated waters and unsweetened teas compete for identical shelf space.
Supply Chain Analysis
Freight cost exposure concentrates in reverse logistics for bottle deposit compliance across California, New York, and Oregon, driving pouch format adoption in convenience networks. Raw material sourcing draws from Florida and California citrus belts, Pacific Northwest berry growers, and Chilean counter-seasonal suppliers, with organic certification adding traceability documentation burdens. Single-source vulnerability sits with vacuum-extraction equipment manufacturers in Germany and Japan. Distribution runs through three-tier structures anchored by Nestle and PepsiCo bottled water infrastructure, with direct-to-subscription platforms displacing traditional grocery dependence in premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between FDA labeling jurisdictions and EU EFSA clean-label standards creates formulation cost differentials, with domestic manufacturers facing compressed margins from added-sugar disclosure requirements while European imports capture premium positioning through regulatory halo effects.
For Market Incumbents: Anchor shelf placement through existing bottled water infrastructure while consolidating regional co-packing capacity in Texas and Florida to defend against subscription-native entrants. Deepen backward integration into organic citrus sourcing from Florida growers to secure margin stability against berry supply volatility. For New Entrants and Emerging Players: Direct-to-subscription platforms with cold-chain guarantees represent the most penetrable route, targeting Seattle and Austin fitness studios with botanical-infused functional hydration lines. Corporate wellness B2B procurement offers faster scaling than crowded supermarket slotting contests. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale organic specialists with pending USDA certification and modular HPP equipment. Long-term viability hinges on adaptogenic ingredient convergence beyond basic flavoring. Watch municipal sugar-tax proposal momentum in progressive cities as inflection signal for zero-added-sugar formulation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Scheduled delivery platforms bypass slotting fees while capturing consumer data in Seattle and Austin corridors. |
| USDA Organic Certification Investment | Twelve-to-eighteen-month approval cycles lock working capital but command shelf price premiums in specialty health shops. |
| Botanical Extract Convergence | Adaptogenic pairings with fruit essences open functional hydration positioning beyond commodity flavoring. |
| Modular HPP Equipment Deployment | Regional bottlers bypass centralized co-packing dependencies through 10,000-unit-batch production economics. |
| Corporate Wellness B2B Partnership | Fitness studios and employer programs represent fastest-growing subscription vertical with guaranteed volume offtake. |
Methodological Framework
Multiple input streams — executive interviews with bottled water category managers, procurement leads at fitness studio chains, and regulatory affairs directors — were reconciled against FDA 21 CFR 165.110 filings, USDA organic certification databases, and Nielsen retail audit data. Primary fieldwork with co-packing facility operators in Texas and Florida supplemented secondary validation through EPA source water quality reports and state-level bottle deposit legislation records. Bottom-up volume modeling across product type, ingredient, packaging, and channel segments triangulated against top-down market sizing.
Data-stream reconciliation anchored forecast construction across the analysis window, with segmentation modeling spanning natural versus sparkling versus organic product tiers, citrus versus berry versus herb ingredient categories, and supermarket versus online retail versus convenience store channel dynamics. CAGRs were derived from trend extrapolation of health-conscious millennial and Gen Z adoption curves in California and New York metropolitan clusters, cross-referenced with cold-infusion processing capacity expansion timelines and municipal sugar-tax proposal tracking.
Regulatory enforcement variance, organic certification approval delays, and raw material supply shocks are the dominant revision risks to modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Lemonade Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Low- and No-Calorie Soda Market
Non-Alcoholic Beverages
Non-Dairy Beverages Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
US NFC Lemon Juice Market
Non-Alcoholic Beverages
United States Energy Drink Market