
 Underwater Exploration Robots Market | 2026-2036
Underwater Exploration Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Exploration Robots Market Outlook
ISO 13628-8 qualification for subsea production systems is collapsing the supplier base to a handful of certified integrators. Oceaneering International leverages its vertical integration across umbilical manufacturing and ROV services to dominate North Sea contracting. Soil Machine Dynamics Ltd. anchors its position through proprietary hydraulic manipulator technology purpose-built for ultra-deepwater intervention. ECA Group competes by sustaining dual capability in both military mine-countermeasure AUVs and commercial seabed survey platforms.
Underwater exploration robots are tethered or untethered electromechanical vehicles engineered to operate at depths exceeding 6,000 meters, utilizing pressure-resistant hulls, thruster arrays, and sensor payloads for seabed intervention and data collection. Their primary purpose is to execute tasks in environments where human divers cannot survive, including pipeline inspection, geological sampling, and wreck documentation. ROV systems still occupy the largest revenue share due to persistent demand from offshore oil and gas operators requiring real-time operator control for critical infrastructure work. AUV platforms represent the fastest-expanding category as autonomous navigation technology enables longer-duration missions without surface vessel support, particularly for marine research and environmental monitoring applications where labor cost reduction drives procurement.
The International Maritime Organization's Polar Code and the EPA's National Pollutant Discharge Elimination System shape vessel-based robot deployment standards, while the EU Green Deal's marine biodiversity targets redirect public research funding toward environmental monitoring end uses. China's MEE enforces seabed environmental impact assessments that mandate pre- and post-construction surveys, creating recurring demand for mapping and inspection technologies. Stakeholders must weigh capital intensity against mission flexibility when selecting between tethered and autonomous architectures.
Market Dynamics
ISO 13628-8 qualification requirements for subsea production systems are concentrating the supplier base to certified integrators, reshaping competitive positioning around proven deployment records rather than component innovation alone.
Growth Catalysts
- Offshore decommissioning mandates:Norway's Petroleum Safety Authority and the UK's Oil and Gas Authority impose strict asset-end-of-life protocols, requiring robotic inspection of aging subsea infrastructure before platform removal.
- Deep-water field development:Brazil's pre-salt basin and Guyana's Stabroek block drive sustained procurement of ultra-deepwater intervention systems capable of operating below 3,000 meters.
- Autonomous navigation maturation:Simultaneous localization and mapping algorithms enable AUVs to execute multi-day missions without surface vessel tethering, reducing operational expenditure for seabed survey operators.
Market Restraints
- Titanium alloy cost volatility:Pressure-resistant hull fabrication depends on Grade 5 titanium supply concentrated in Russian and Chinese smelters, exposing integrators to input price swings and export control risk.
- Subsea connector oligopoly:Hydraulic and electrical wet-mate connector supply concentrates among three European manufacturers, creating single-source vulnerability for ROV umbilical assemblies.
- Battery energy density ceiling:Lithium-sulfur and solid-state chemistries remain unproven at full ocean depth, limiting AUV mission endurance to 48-72 hours against operator demand for week-long deployments.
Strategic Opportunities
- Marine mineral extraction frontier:The International Seabed Authority's draft exploitation regulations for polymetallic nodule collection create first-mover positioning for mining contractors in the Clarion-Clipperton Zone.
- Offshore wind foundation inspection:Fixed-bottom and floating turbine installations in the North Sea and Taiwan Strait require repetitive subsea structural monitoring, opening recurring service contracts outside oil and gas.
- Convergence of optical and acoustic sensing:Hybrid lidar-multibeam sonar payloads enable centimeter-scale seabed mapping at operational depths previously requiring separate survey passes.
Industry Challenges
- Subsea robotics engineering talent scarcity:Cross-disciplinary expertise combining hydrodynamics, pressure vessel design, and real-time control systems concentrates among a handful of academic programs and incumbent employers.
- ISO 13628-8 certification timelines:Qualification testing for subsea production system integration extends 18-24 months, delaying revenue recognition for new platform entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Exploration Robots Market |
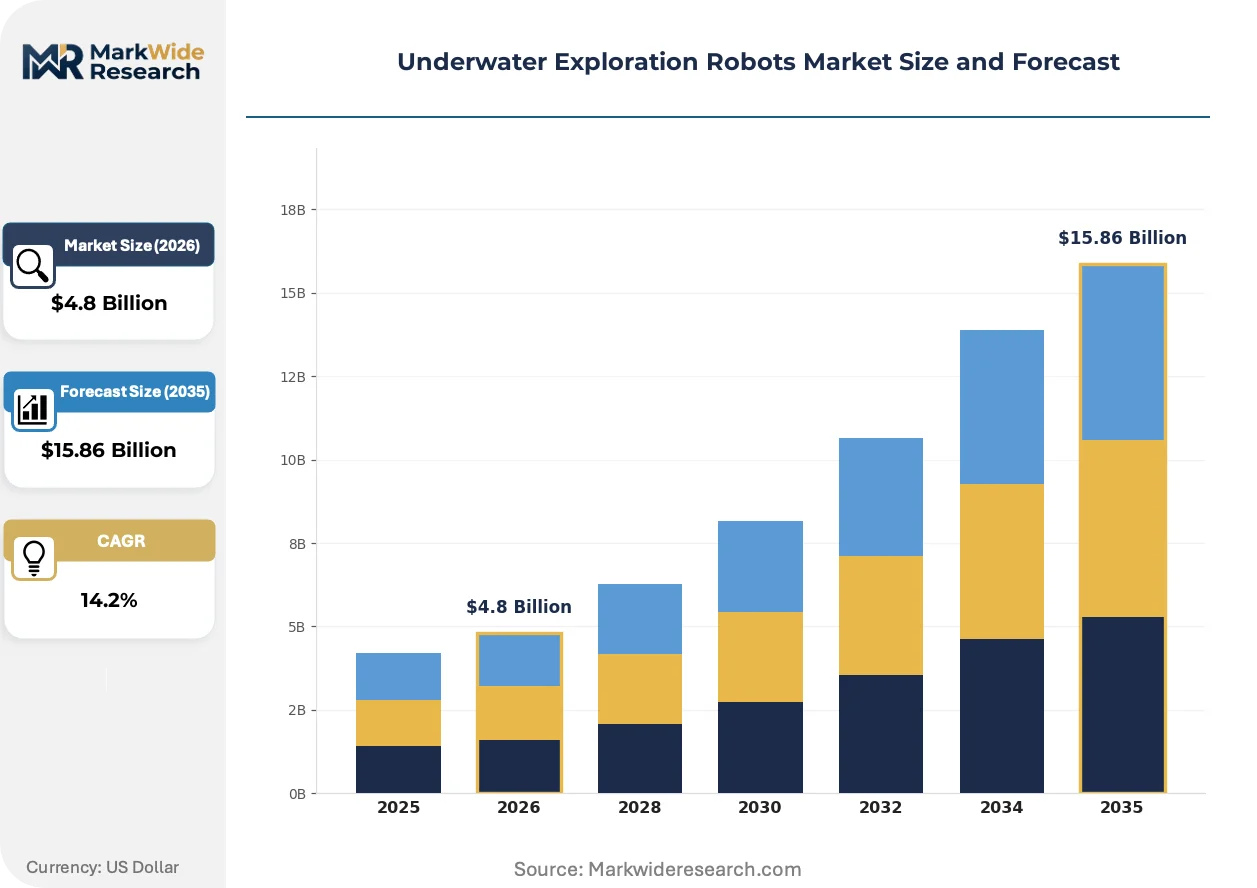
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AUV, ROV, Hybrid, Unmanned Surface Vehicle End User: Marine Research, Oil & Gas, Defense, Environmental Monitoring Application: Surveying, Inspection, Mapping, Deep-sea Exploration Technology: Autonomous Navigation, Sonar Systems, Communication Tools, Imaging Systems |
| Companies Covered | Oceaneering International Inc., Deep Ocean Engineering Inc., ECA Group, International Submarine Engineering, Soil Machine Dynamics Ltd., ATLAS MARIDAN ApS, General Dynamics Mission Systems Inc., Saab AB, TechnipFMC plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Exploration Robots Market Strategic Shifts
Electrification of subsea hydraulic functions and convergence of autonomous navigation with resident deployment models are compressing the traditional surface-vessel dependency that has structured offshore robotics economics for decades.
Modular payload architectures are fragmenting the historically integrated ROV supply chain. Standardized mechanical and electrical interfaces allow end-users to swap sensor packages, manipulator arms, and tooling skids between missions without returning units to shore-based service centers. Offshore wind operators in the North Sea and oil majors in the Gulf of Mexico are adopting this configurability to reduce vessel standby costs. The shift is fragmenting maintenance revenue away from original equipment manufacturers toward third-party service depots and in-house engineering teams.
The EU Green Deal's marine biodiversity targets redirect public research funding toward environmental monitoring end uses. National oceanographic institutes in France, Germany, and Norway are reallocating vessel budgets toward persistent AUV networks for water-column and benthic ecosystem observation. Commercial survey contractors are responding by certifying platforms for dual-use military and scientific payloads. Environmental monitoring now represents the fastest-expanding procurement category outside hydrocarbon applications.
Long-term resident deployment contracts are displacing call-out service models for production field support. Major operators in Norway's North Sea corridor are installing permanently stationed ROV systems on subsea docking stations, connected via seafiber to onshore control centers. This eliminates surface vessel day-rates for routine inspection and intervention. The contracting shift compresses traditional ROV service company margins while favoring integrators with software and connectivity competencies over those dependent on marine crew deployment.
Underwater Exploration Robots Market Segmentation
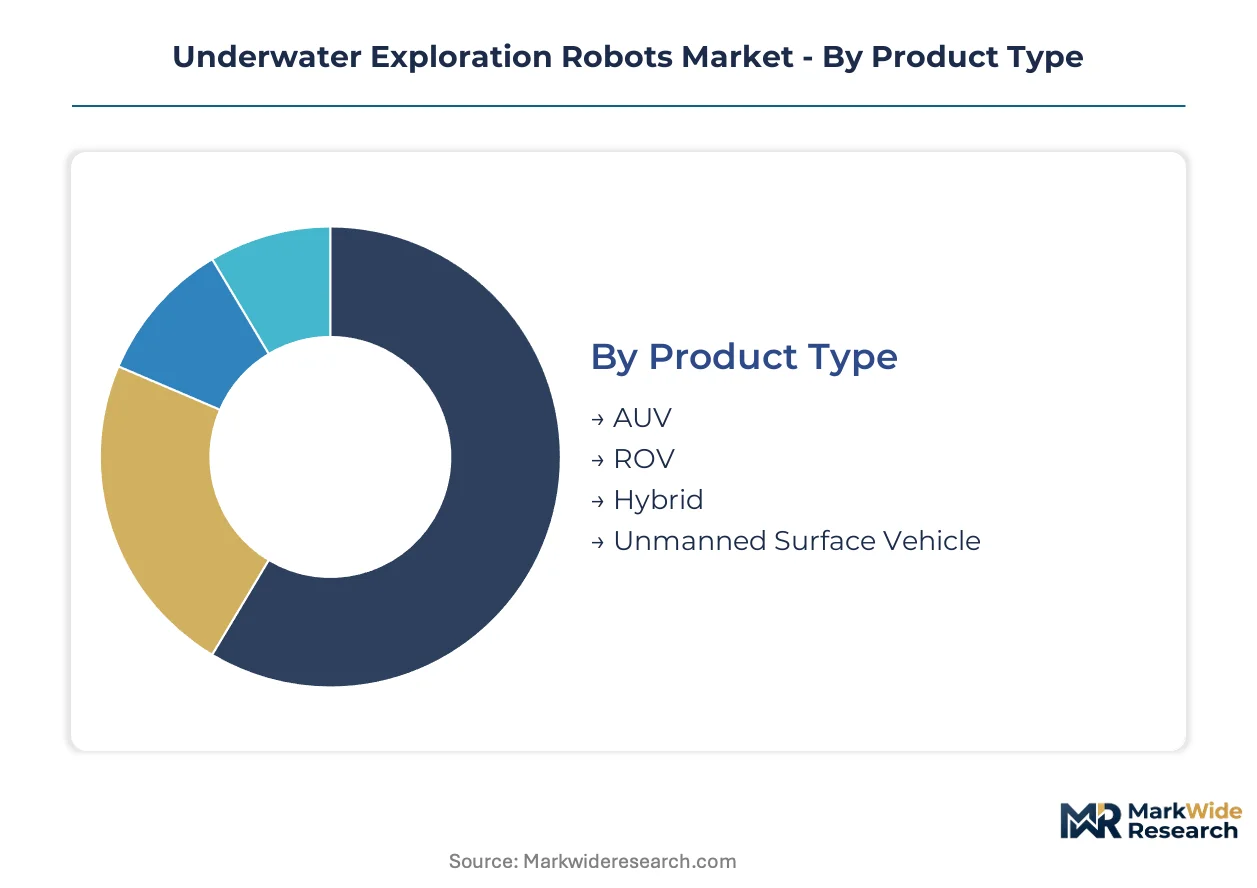
Underwater exploration robots segment across product architecture, end-use sector, mission application, and enabling technology. Procurement patterns diverge sharply between hydrocarbon-driven demand and emerging environmental monitoring contracts, reshaping supplier priorities across certification tiers.
Product Type:
ROV systems anchor domestic procurement in offshore oil and gas corridors, while AUV platforms drive export-led growth through marine research institutes and defense ministries seeking autonomous capability.
- AUV:Untethered platforms execute multi-day missions using simultaneous localization and mapping algorithms. Demand concentrates among Norway's oceanographic institutes and Australia's Commonwealth Scientific and Industrial Research Organisation for persistent seabed observation networks, constrained by lithium-sulfur battery energy density ceilings at full ocean depth.
- ROV:Tethered systems maintain real-time operator control through umbilical connections for critical infrastructure intervention. Procurement clusters around Brazil's pre-salt basin and Guyana's Stabroek block where ultra-deepwater field development requires human-in-the-loop decision making below 3,000 meters.
- Hybrid:Dual-mode architectures switch between autonomous transit and tethered intervention, serving offshore wind operators in the North Sea seeking reduced vessel day-rates for foundation inspection.
- Unmanned Surface Vehicle:Wave-gliding and powered hulls deploy AUV launch-and-recovery functions, gaining traction among Taiwan Strait survey contractors for repetitive turbine array monitoring.
ROV systems command the established base. The steepest expansion runs through AUV platforms.
End User:
Cost tier stratification separates capital-intensive oil and gas deployments from publicly funded research and environmental monitoring programs operating on fixed vessel budgets.
- Oil & Gas:Offshore operators in Norway's North Sea corridor and Brazil's Santos Basin drive sustained procurement of ISO 13628-8 certified systems for subsea production system intervention. Decommissioning mandates from Norway's Petroleum Safety Authority and the UK's Oil and Gas Authority accelerate inspection of aging infrastructure.
- Environmental Monitoring:EU Green Deal marine biodiversity targets redirect French, German, and Norwegian oceanographic institute budgets toward persistent AUV networks. China's MEE enforces pre- and post-construction seabed surveys, creating recurring demand for mapping platforms.
- Marine Research:Academic and governmental institutes prioritize long-duration autonomous missions for water-column and benthic ecosystem observation, constrained by funding cycles tied to national vessel replacement programs.
- Defense:Naval mine-countermeasure programs in France and the United Kingdom sustain dual-use platform certification, bridging commercial survey and military seabed clearance requirements.
Oil and Gas anchors revenue concentration. Environmental Monitoring climbs fastest as regulatory mandates expand survey obligations.
Application:
Mission duration and sensor payload complexity stratify procurement, with repetitive inspection contracts favoring resident deployment models and deep-sea exploration requiring maximum pressure-rated hull specifications.
- Inspection:Pipeline integrity assessment and subsea infrastructure monitoring dominate operator spending, particularly for pre-decommissioning surveys mandated by North Sea regulators.
- Surveying:Commercial seabed mapping for route planning and site characterization sustains vessel-based AUV operations across the Gulf of Mexico and West African offshore concessions.
- Mapping:High-resolution bathymetric data collection for International Seabed Authority compliance in the Clarion-Clipperton Zone drives hybrid lidar-multibeam sonar payload integration.
- Deep-sea Exploration:Hadal zone missions below 6,000 meters require titanium alloy hull fabrication and specialized sampling manipulators, limiting procurement to national research programs and mineral extraction pilots.
Inspection commands recurring contract volume. Deep-sea Exploration gains share as polymetallic nodule exploitation regulations advance.
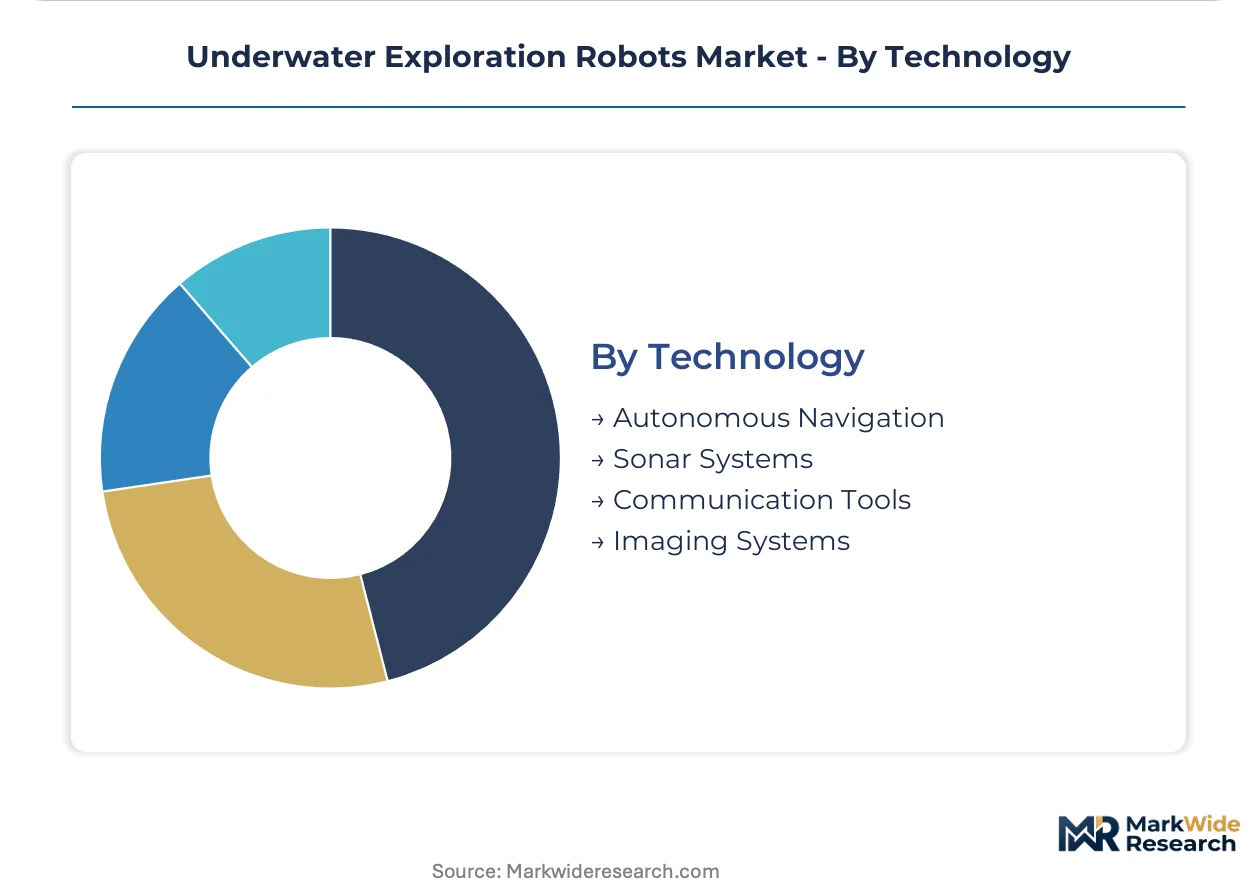
Technology:
Supply concentration in wet-mate connectors and pressure-rated imaging components shapes technology adoption curves, with autonomous navigation software emerging as the primary differentiation vector.
- Autonomous Navigation:SLAM algorithms and acoustic positioning systems enable untethered mission execution, reducing operational expenditure for survey operators seeking multi-day deployments without surface vessel support.
- Sonar Systems:Multibeam and synthetic aperture sonar payloads provide centimeter-scale seabed resolution, with Kongsberg Maritime and Teledyne Marine dominating transducer supply.
- Imaging Systems:Low-light cameras and laser line scanners document subsea infrastructure condition, constrained by optical attenuation at operational depths requiring artificial illumination.
- Communication Tools:Acoustic modems and seafiber connections enable real-time data transmission and resident ROV control from onshore centers, compressing traditional marine crew deployment models.
Sonar Systems anchor platform specification. Autonomous Navigation delivers the steepest capability expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's Petroleum Safety Authority mandates decommissioning protocols that accelerate robotic inspection procurement. Brazil's pre-salt licensing rounds and China's MEE seabed assessment requirements are redirecting fleet deployment patterns across three continents.
Norway
Deep-water field development in the North Sea corridor sustains demand for ultra-deepwater intervention systems. The Petroleum Safety Authority enforces strict asset-end-of-life inspection protocols before platform removal. Stavanger anchors subsea robotics engineering talent concentration where resident ROV deployment contracts are displacing traditional call-out service models.
Brazil
Pre-salt basin development below 3,000 meters drives procurement of human-in-the-loop ROV systems for critical infrastructure work. The national petroleum regulator mandates continuous subsea production system monitoring for offshore concession holders. Rio de Janeiro hosts the primary contracting cluster where Petrobras and international majors coordinate fleet deployment schedules.
China
MEE seabed environmental impact assessments create recurring demand for pre- and post-construction survey platforms. The Ministry of Ecology and Environment enforces mapping obligations for offshore wind and hydrocarbon development. Qingdao and Shanghai concentrate domestic AUV manufacturing capacity where state research institutes prioritize long-duration autonomous missions.
United Kingdom
The Oil and Gas Authority decommissioning mandates accelerate inspection of aging North Sea infrastructure. Offshore wind foundation installation in Scottish waters requires repetitive subsea structural monitoring contracts. Aberdeen maintains the primary service depot network where third-party maintenance revenue is fragmenting away from original equipment manufacturers.
United States
Gulf of Mexico ultra-deepwater lease obligations sustain ROV procurement for real-time operator control below 3,000 meters. The EPA National Pollutant Discharge Elimination System shapes vessel-based robot deployment standards for environmental compliance. Houston anchors the primary contracting hub where modular payload architectures are reducing vessel standby costs for major operators.
Underwater Exploration Robots Market Competitive Environment
Player mix skews toward vertically integrated service providers and specialized component fabricators. The supplier base concentrates around certified integrators meeting ISO 13628-8 qualification timelines. Strategic archetypes include full-service contractors controlling umbilical manufacturing through captive supply, hydraulic manipulator specialists commanding ultra-deepwater intervention niches, and dual-use platform developers bridging commercial survey with defense seabed clearance. Dominant competitive moves involve backward integration into pressure-resistant hull fabrication and technology licensing for autonomous navigation software.
Within the full-service contractor tier, Oceaneering International Inc. and TechnipFMC plc represent vertically integrated positions spanning subsea production system integration. Among specialized fabricators, Soil Machine Dynamics Ltd. occupies a hydraulic manipulator technology position purpose-built for ultra-deepwater environments. ECA Group exemplifies the dual-use archetype sustaining capability across both military mine-countermeasure and commercial seabed survey segments.
| Leading Market Players |
|---|
| Oceaneering International Inc. |
| Deep Ocean Engineering Inc. |
| ECA Group |
| International Submarine Engineering |
| Soil Machine Dynamics Ltd. |
| ATLAS MARIDAN ApS |
| General Dynamics Mission Systems Inc. |
| Saab AB |
| TechnipFMC plc |
| Others |
Value Chain & Pricing Dynamics
Grade 5 titanium substitution for aluminum-lithium alloys in pressure hull fabrication is simultaneously relocating forging capacity toward Russian and Chinese smelters while amplifying cost volatility exposure for North Sea integrators. This input shift concentrates pricing power among a handful of metallurgical suppliers capable of meeting full ocean depth specifications.
Pricing Analysis
Certification level creates the primary spread between ISO 13628-8 qualified systems and uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects qualification investment recovery timelines and deployment record premiums. Cost compression in the standard tier is intensifying because Brazilian pre-salt operators are consolidating procurement volumes around proven integrators. Offshore wind developers exhibit highest price sensitivity due to fixed vessel budget constraints, while Norway's Petroleum Safety Authority mandates leave oil majors least elastic.
Supply Chain Analysis
Strait of Hormuz transit vulnerability for titanium sponge feedstock underwrites supply security premiums in contract negotiations. Hull fabrication draws from Russian VSMPO-AVISMA and Chinese Baoji Titanium, while wet-mate connector supply rests on three European manufacturers. Single-source vulnerability in umbilical assemblies exposes integrators to 18-24 month qualification delays. Distribution runs through Stavanger and Houston service depots where third-party maintenance fragmentation is eroding OEM capture rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Offshore decommissioning cycles are driving a cyclical recovery as Norway and the UK accelerate aging infrastructure inspection mandates ahead of platform removal deadlines.
For Market Incumbents: Fortify resident deployment capabilities through seafiber connectivity investments that compress traditional marine crew economics. Deepen backward integration into pressure-resistant hull fabrication to offset titanium supply concentration risk. ISO 13628-8 certification timelines protect against emerging modular payload competitors by locking in operator preference for proven deployment records.
For New Entrants and Emerging Players: Fast-track ISO 13628-8 qualification through partnership with established North Sea service depots accelerates market access without full integration burden. Offshore wind foundation inspection presents the most penetrable white space given repetitive contract structures and lower certification barriers. Lead with hybrid AUV-ROV architectures that reduce vessel day-rates for Taiwan Strait turbine operators.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors software-centric integrators over marine crew-dependent service models. Long-term viability across the next decade hinges on autonomous navigation competency and resident deployment infrastructure ownership. Watch International Seabed Authority exploitation regulation finalization as the signal for polymetallic nodule mining contract inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Resident ROV Deployment Infrastructure | Seafiber-connected docking stations eliminate surface vessel dependency for Norway's North Sea operators. |
| Autonomous Navigation Software Licensing | SLAM algorithm commercialization enables multi-day AUV missions without Petrobras vessel support. |
| Modular Payload Architecture Adoption | Standardized interfaces allow Gulf of Mexico operators to swap sensors without shore-based service returns. |
| Dual-Use Military-Commercial Certification | Mine-countermeasure pedigree from France's naval programs bridges into seabed survey contracts. |
| Titanium Supply Security Partnerships | Long-term offtake agreements with VSMPO-AVISMA hedge Grade 5 alloy price volatility for hull fabricators. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with subsea robotics engineering directors, offshore wind procurement leads, and oil major fleet managers; and secondary validation through SEC filings from listed integrators, Norwegian Petroleum Safety Authority decommissioning registers, and International Seabed Authority contract databases. Bottom-up vessel deployment tallies triangulated against top-down OEM revenue segmentation across the analysis window.
Across the modeling period, forecasts incorporate product architecture splits between tethered and autonomous platforms, end-use sector differentiation across hydrocarbon and environmental monitoring applications, and enabling technology adoption curves for sonar and navigation systems. CAGRs derive from regression against offshore capital expenditure cycles and regulatory mandate implementation timelines. Battery energy density ceilings and titanium supply concentration factor as binding constraints.
Underlying assumptions cover sustained offshore decommissioning enforcement and autonomous navigation maturation, with deviation risk concentrated in export control expansion for titanium alloys and lithium-sulfur chemistry breakthroughs. Practitioners should keep alternative scenarios live as International Seabed Authority exploitation regulations and EU Green Deal funding allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Canada Cloud Robotics Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
Robotic Lawn Mower Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Global Automated Parcel Delivery Terminals Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Europe Robotics and Automation Actuators Market
Robotics and Automation
Robotics Software Platforms Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Micro Robots Market
Robotics and Automation
Automated Plate Handlers Market
Robotics and Automation
Global Enterprise Robotic Process Automation Market
Robotics and Automation
China Cloud Robotics Market
Robotics and Automation
Household Robots Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market