
 China Cloud Robotics Market | 2026-2036
China Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
China Cloud Robotics Market Insights
Capital-intensity divergence between cloud-native robotics firms and legacy automation vendors is redrawing competitive boundaries in the China Cloud Robotics Market. Siasun Robot & Automation leverages its manufacturing scale to dominate industrial robot deployments. Unitree Robotics anchors its position through specialized quadruped platforms that extend into inspection and logistics use cases.
Cloud robotics fuses distributed computing architectures with physical automation systems, enabling real-time task offloading, fleet learning, and centralized AI model updates across robot populations. The technology relies on sub-50ms latency thresholds and edge-cloud orchestration to coordinate multi-robot workflows in dynamic environments. Service robots and collaborative robots represent the fastest-expanding product categories, with margin pools concentrating in hybrid cloud deployment models that balance data sovereignty with computational elasticity. Manufacturing end users currently absorb the largest volume share, though logistics applications are gaining traction as warehouse operators pursue cloud-coordinated fleet optimization.
MIIT's cloud computing standards, SAMR's data security regulations, and GB standards for industrial robot safety collectively shape product certification pathways and data architecture requirements for market participants. Compliance with these frameworks determines market access for both domestic vendors and foreign technology suppliers. Stakeholders must monitor regulatory evolution around cross-border data flows and AI algorithm disclosure mandates to anticipate compliance cost trajectories.
Market Dynamics
Guangdong Province's factory automation push is compressing deployment cycles for cloud-connected robotic systems as manufacturers chase real-time fleet coordination and centralized AI model updates.
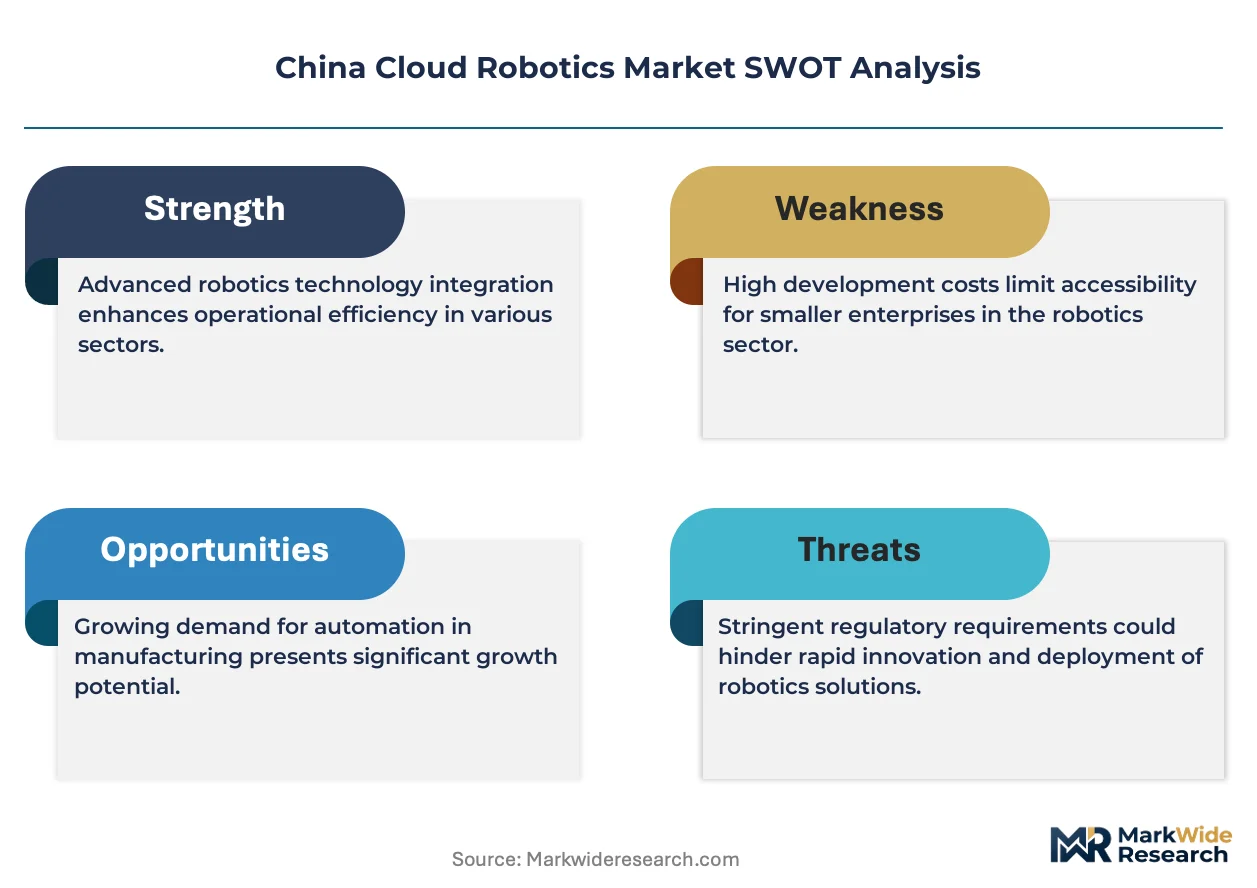
Growth Catalysts
- MIIT Cloud Computing Standards:Tightened data residency requirements for industrial platforms are accelerating domestic infrastructure investment and creating captive demand for locally-hosted cloud robotics architectures.
- Shenzhen Robotics Corridor:Supply chain density combined with comprehensive 5G coverage generates clustering effects that reduce integration costs and shorten procurement lead times for cloud-native deployments.
- Edge-Cloud Orchestration:Sub-50ms latency thresholds now enable multi-robot workflow coordination in dynamic manufacturing environments, expanding addressable use cases beyond static automation lines.
Market Restraints
- Semiconductor Input Volatility:GPU and specialized AI accelerator supply concentration creates margin pressure for cloud robotics vendors dependent on high-throughput edge computing hardware.
- Cross-Border Data Flow Friction:SAMR data security regulations impose architectural constraints on multinational manufacturers seeking centralized cloud control over Chinese operational fleets.
- Legacy Brownfield Inertia:Existing programmable logic controller installations and proprietary industrial networks resist seamless cloud integration, extending replacement cycles.
Strategic Opportunities
- Logistics Fleet Optimization:Warehouse operators in the Yangtze River Delta are pursuing cloud-coordinated autonomous mobile robot fleets to compress fulfillment costs and enable dynamic slotting.
- Dual Carbon Policy Alignment:Beijing's emissions reduction mandates create regulatory tailwinds for energy-efficient cloud robotics architectures that optimize motor control through centralized AI load balancing.
- 5G-Advanced Convergence:Integration of time-sensitive networking with edge computing nodes enables deterministic control loops previously requiring wired connections, opening mobile manipulation applications.
Industry Challenges
- Edge-AI Talent Scarcity:Shortage of engineers proficient in distributed systems, real-time control, and machine learning operations constrains deployment velocity for complex cloud-robotics integrations.
- GB Standard Certification Timelines:Industrial robot safety compliance and MIIT platform certification processes extend product launch schedules and increase pre-revenue development burn.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cloud Robotics Market |
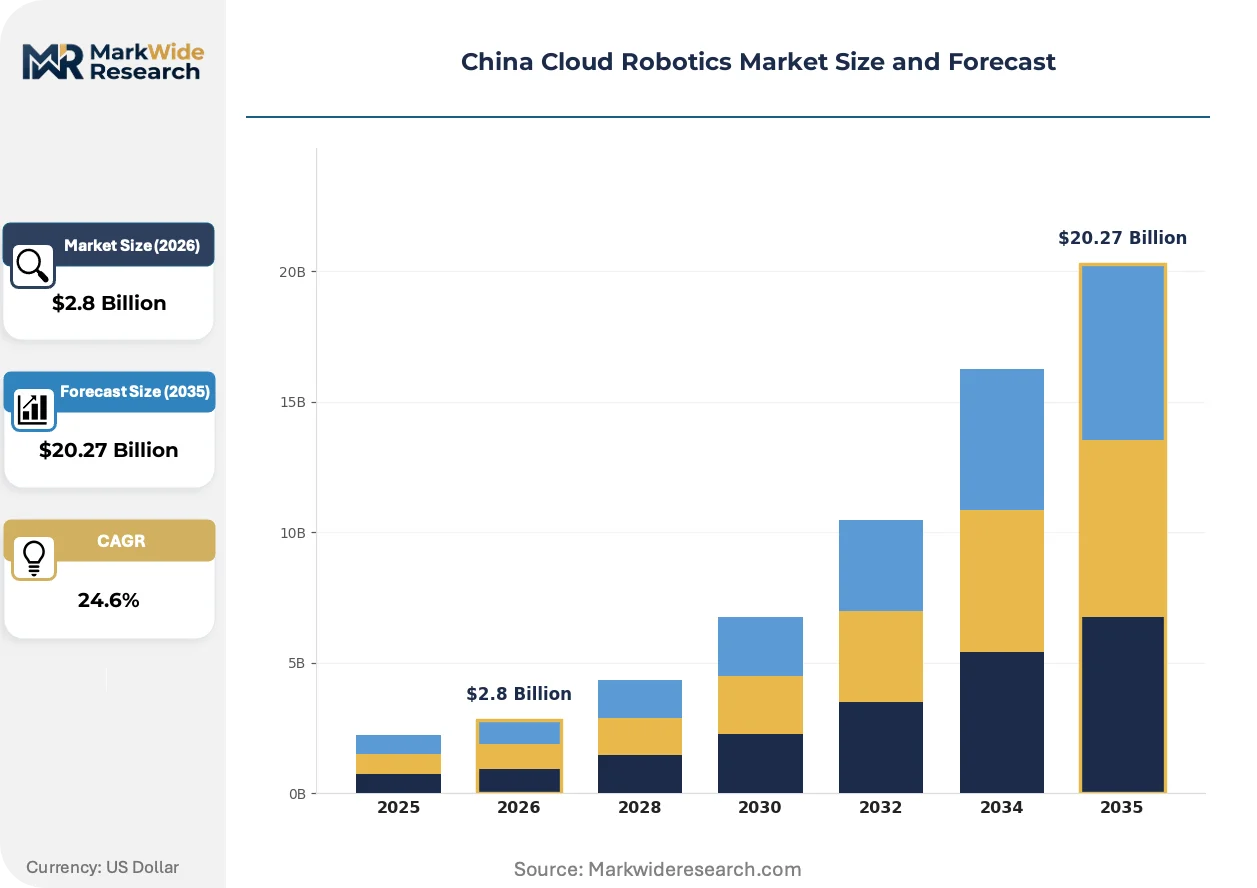
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Service Robots, Industrial Robots, Personal Robots, Collaborative Robots Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing End User: Healthcare, Manufacturing, Retail, Logistics Technology: AI, Machine Learning, IoT, Automation |
| Companies Covered | Siasun Robot & Automation, Unitree Robotics, Deep Robotics, Astribot Robotics, RobotEra, Beijing Kingsoft Cloud Network Technology Co., Ltd., Sichuan Jiuyuan Yinhai Software Co., Ltd., Shenzhen 1011 Communication Technology Co., Ltd., Beijing Ruiying Zhituo Technology Development Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cloud Robotics Market Trends and Innovations
Cloud-native control architectures are supplanting on-premise programmable automation controllers across Chinese manufacturing floors, compressing the traditional seven-year capital equipment replacement cycle.
Distributed computing frameworks with containerized robot operating system deployments are supplanting monolithic industrial software stacks. Electronics manufacturers in Dongguan and Foshan are adopting these architectures at twelve-to-eighteen-month refresh intervals. The shift is compressing vendor lock-in duration and enabling rapid algorithm iteration without hardware replacement.
MIIT's tightening cloud computing infrastructure standards are mandating domestic data center hosting for industrial platforms with cross-fleet learning capabilities. This regulatory pressure is fragmenting previously centralized global architectures and forcing multinational automation vendors to establish sovereign Chinese cloud instances. Manufacturing end users in Guangdong and Jiangsu provinces are prioritizing vendors with certified domestic edge node deployments.
Buyer procurement patterns are migrating from capital equipment purchases toward operational expenditure models with uptime guarantees. Automotive tier-one suppliers and consumer electronics contract manufacturers are leading this transition, negotiating fleet availability contracts rather than robot unit acquisitions. The shift is most pronounced in Shenzhen's precision manufacturing cluster, where balance sheet optimization priorities favor subscription-based cloud robotics service agreements.
China Cloud Robotics Market Segmentation
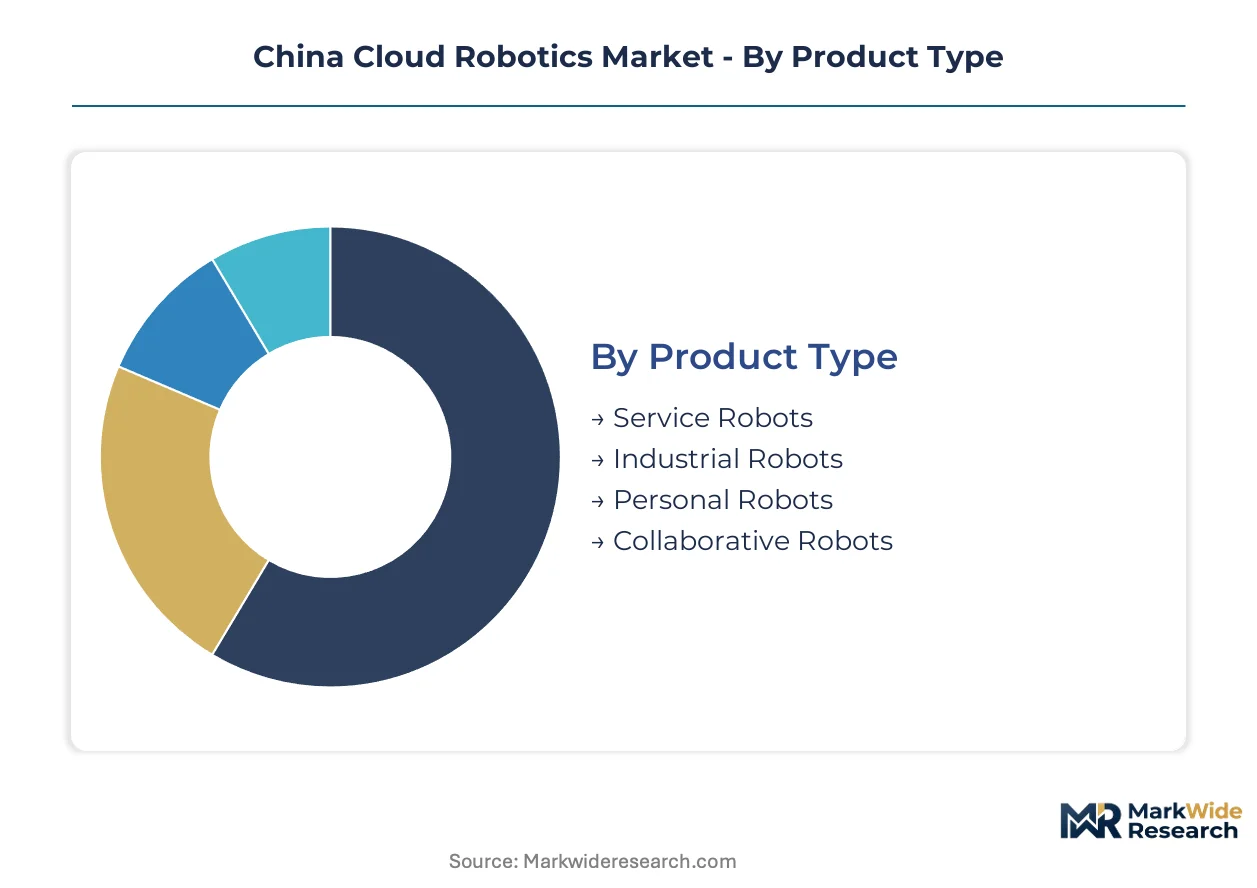
Cloud robotics architectures fragment across multiple technical and commercial dimensions, each carrying distinct margin profiles and regulatory exposure. Segmentation clarity enables vendors to target procurement patterns that favor operational expenditure models over capital equipment cycles.
Product Type:
Domestic demand concentrates on industrial and collaborative variants, while service robot development targets export markets through Shenzhen's hardware ecosystem.
- Service Robots:Cloud-connected units integrate natural language processing and computer vision for hospitality and eldercare applications. Guangdong manufacturers absorb the largest procurement volumes as municipal governments deploy sanitation and guidance units across transport hubs.
- Industrial Robots:Six-axis articulated arms with edge-cloud orchestration dominate factory floors in Dongguan and Foshan. MIIT's data residency requirements force architectural redesigns for fleet learning capabilities, extending certification timelines for foreign vendors.
- Personal Robots:Consumer-facing units with companion and educational functions face price compression from white-label Shenzhen producers.
- Collaborative Robots:Force-limited arms with sub-50ms cloud feedback loops enable human-robot workcell integration without safety cages.
Industrial robots hold the largest share; momentum sits with collaborative robots as automotive tier-one suppliers reconfigure assembly lines.
Deployment:
Cost tier differentiation separates sovereign infrastructure investments from elastic public cloud consumption, with hybrid architectures capturing the widest customer base.
- Public Cloud:Shared infrastructure delivers computational elasticity for seasonal demand spikes in logistics applications. Multinational manufacturers face SAMR data security constraints that limit cross-border fleet control, compressing addressable use cases.
- Private Cloud:Dedicated on-premise stacks satisfy GB standard certification requirements for safety-critical industrial deployments. Jiangsu province's precision electronics manufacturers prioritize this architecture to isolate proprietary process data.
- Hybrid Cloud:Edge-cloud orchestration balances latency-sensitive control loops with centralized model training. This architecture is climbing the fastest as warehouse operators pursue dynamic fleet optimization without full infrastructure replacement.
- Edge Computing:Containerized ROS deployments on factory-floor nodes enable deterministic response times for manipulation tasks.
Hybrid cloud deployments command the widest adoption; private cloud infrastructure is expanding most quickly under regulatory pressure.
End User:
Volume concentration in manufacturing creates supply chain pull-through effects that reshape component sourcing for adjacent sectors.
- Healthcare:Cloud-connected surgical assistance and disinfection robots face NMPA medical device classification requirements. Shanghai's tertiary hospitals pilot teleoperation platforms with 5G-Advanced latency guarantees.
- Manufacturing:Electronics contract manufacturers in the Pearl River Delta drive fleet-scale procurement with twelve-to-eighteen-month refresh cycles. Dual carbon policy alignment favors energy-efficient motor control through centralized AI load balancing.
- Retail:Inventory scanning and customer service robots deploy through operational expenditure contracts with uptime guarantees.
- Logistics:Yangtze River Delta warehouse operators pursue cloud-coordinated autonomous mobile robot fleets to compress fulfillment costs.
Manufacturing absorbs the greatest volume; logistics applications are gaining share fastest as e-commerce fulfillment networks scale.
Technology:
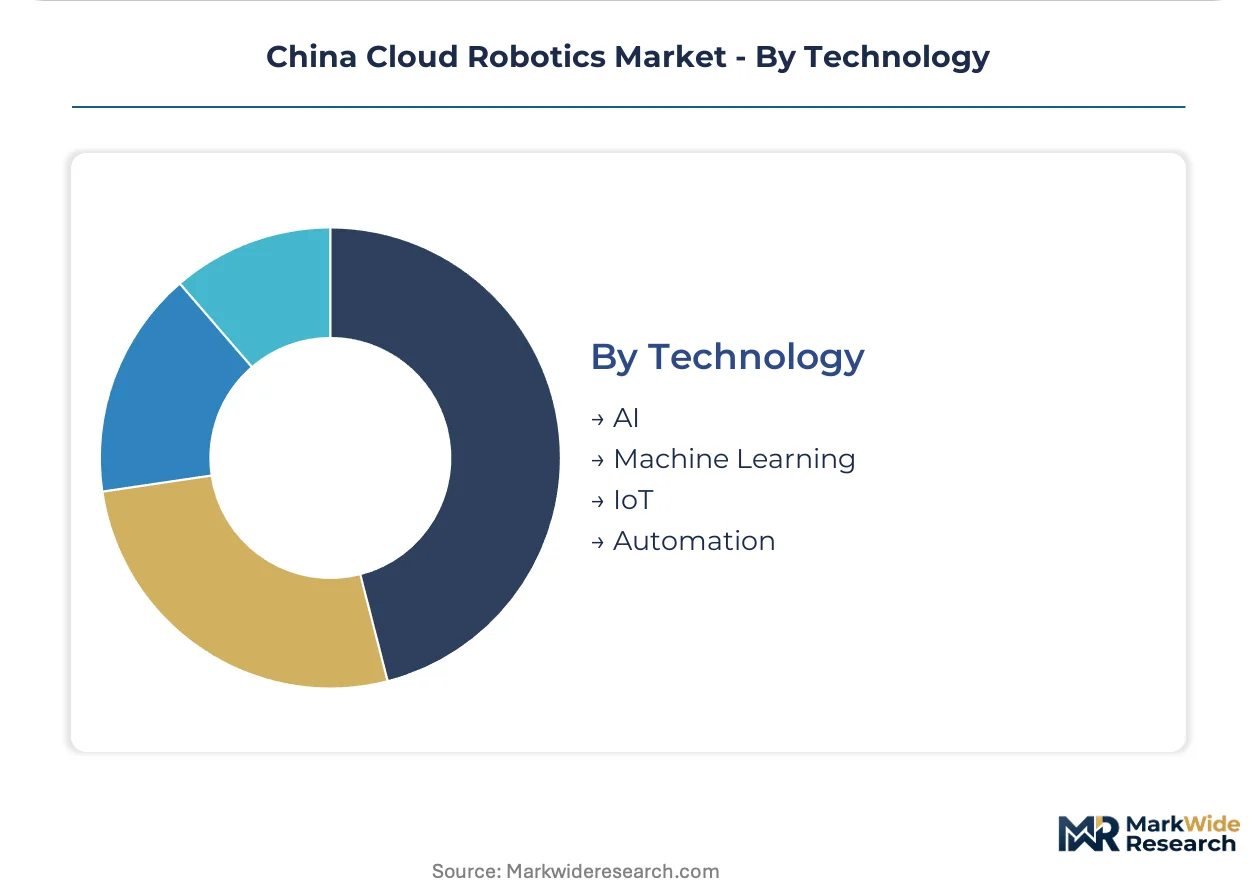
Customer type stratification separates deep-tech integrators from component assemblers, with AI capabilities determining margin capture.
- AI:Distributed model training across robot populations enables fleet learning without individual unit reprogramming. Edge-AI talent scarcity in Shenzhen and Beijing constrains deployment velocity for complex integrations.
- Machine Learning:Reinforcement learning pipelines optimize path planning and grasp strategies through centralized cloud computation.
- IoT:Sensor fusion architectures feed operational data streams into predictive maintenance algorithms.
- Automation:Traditional control logic layers interface with cloud-native orchestration through API gateways.
AI capabilities anchor premium pricing; machine learning pipelines are expanding most quickly as training infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Guangdong Province exhibit the lowest price elasticity as factory automation mandates compress procurement cycles, while inland western provinces remain highly sensitive to upfront infrastructure costs. Coastal manufacturing clusters absorb premium pricing for sub-50ms latency guarantees. Interior logistics hubs prioritize cost-optimized edge computing configurations over sovereign cloud architectures.
Guangdong Province
Electronics contract manufacturers in Dongguan and Shenzhen drive fleet-scale procurement with twelve-to-eighteen-month refresh cycles. MIIT's cloud computing infrastructure standards mandate domestic data center hosting for cross-fleet learning capabilities. The Shenzhen robotics corridor concentrates supply chain density and comprehensive 5G coverage that generates clustering effects for cloud-native deployments.
Jiangsu Province
Precision electronics manufacturers in Suzhou and Wuxi prioritize private cloud architectures to isolate proprietary process data from shared infrastructure. GB standard certification requirements for industrial robot safety extend product launch schedules for foreign vendors establishing domestic edge nodes. The Yangtze River Delta warehouse operators pursue cloud-coordinated autonomous mobile robot fleets to compress fulfillment costs.
Beijing-Tianjin-Hebei
Automotive tier-one suppliers in Beijing reconfigure assembly lines with collaborative robots featuring sub-50ms cloud feedback loops. SAMR data security regulations impose architectural constraints on multinational manufacturers seeking centralized control over Chinese operational fleets. The capital region's tertiary hospitals pilot teleoperation platforms with 5G-Advanced latency guarantees for surgical assistance applications.
Sichuan-Chongqing
Western logistics hubs in Chengdu exhibit high price sensitivity toward upfront edge infrastructure investments compared to coastal counterparts. Dual carbon policy alignment creates regulatory tailwinds for energy-efficient cloud robotics architectures that optimize motor control through centralized AI load balancing. The Chongqing manufacturing base adopts hybrid cloud deployments to balance latency-sensitive control with centralized model training.
Shandong Peninsula
Heavy machinery producers in Qingdao and Yantai retrofit brownfield installations with API gateway interfaces to cloud-native orchestration layers. Legacy programmable logic controller networks resist seamless integration, extending replacement cycles for full cloud migration. The province's port logistics operators test containerized robot operating system deployments on factory-floor nodes for deterministic response times.
China Cloud Robotics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the China Cloud Robotics Market. Industrial robot manufacturers with captive manufacturing scale dominate volume deployments in factory automation. Specialized quadruped and humanoid developers anchor premium positioning through task-specific platform architectures. Cloud infrastructure providers and industrial software integrators occupy intermediate positions linking hardware fleets to centralized AI orchestration. Dominant competitive moves include backward integration into edge computing hardware and strategic partnerships with 5G network operators to guarantee latency thresholds.
Within the industrial automation tier, Siasun Robot & Automation represents manufacturing-scale archetypes with captive production capabilities. Unitree Robotics occupies a specialist position anchored by quadruped platform development extending into inspection and logistics use cases. Beijing Kingsoft Cloud Network Technology Co., Ltd. exemplifies the infrastructure-provider archetype bridging hardware fleets to distributed computing architectures. These three player types collectively illustrate the market's tripartite structure separating hardware fabrication, specialized robotics, and cloud orchestration layers.
| Leading Market Players |
|---|
| Siasun Robot & Automation |
| Unitree Robotics |
| Deep Robotics |
| Astribot Robotics |
| RobotEra |
| Beijing Kingsoft Cloud Network Technology Co., Ltd. |
| Sichuan Jiuyuan Yinhai Software Co., Ltd. |
| Shenzhen 1011 Communication Technology Co., Ltd. |
| Beijing Ruiying Zhituo Technology Development Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term fleet availability contracts with uptime guarantees lock in supply access and price visibility for Guangdong electronics manufacturers pursuing cloud-connected robotic deployments. These arrangements compress vendor switching costs while anchoring procurement budgets against GPU and AI accelerator input volatility.
Pricing Analysis
After-sales service revenue tiers—spanning predictive maintenance subscriptions, edge node refreshes, and algorithm update packages—drive lifetime value capture for cloud robotics vendors. Subscription-based fleet availability contracts dominate procurement patterns across Shenzhen's precision manufacturing cluster, with three-tier pricing structure across premium, standard, and economy levels differentiating by latency guarantees and data sovereignty compliance. Pricing pressure stems from semiconductor input concentration as GPU supply constraints tighten margins for edge computing hardware. Automotive tier-one suppliers exhibit lowest price sensitivity due to balance sheet optimization priorities, while western logistics hubs in Sichuan-Chongqing remain highly sensitive to upfront infrastructure investments.
Supply Chain Analysis
Taiwan Strait transit corridors for advanced semiconductor lithography equipment constitute a critical chokepoint for cloud robotics edge computing hardware. Component sourcing draws from Taiwan for GPU fabrication, South Korea for memory modules, and domestic Chinese foundries for mid-tier AI accelerators. Raw material dependencies span rare earth elements for motor magnets, high-purity silicon for sensor arrays, and specialized copper alloys for power distribution. Single-source vulnerability concentrates in NVIDIA GPU supply for high-throughput fleet learning workloads. Distribution runs through Shenzhen's robotics corridor for domestic deployment, with Jiangsu province precision electronics manufacturers receiving direct edge node integration support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's cloud robotics market is cycling through a capital equipment replacement wave as factory automation mandates compress traditional seven-year refresh intervals. Guangdong Province's manufacturing upgrade policies provide the cyclical impetus.
For Market Incumbents: Fortify domestic edge node certification portfolios to preempt MIIT data residency enforcement expansion. Siasun Robot & Automation and comparable manufacturing-scale players should deepen backward integration into AI accelerator supply chains to offset GPU procurement volatility. Captive production of edge computing hardware reduces exposure to Taiwan Strait logistics disruptions. For New Entrants and Emerging Players: Cloud-native orchestration software for brownfield PLC retrofit represents an underserved service layer where established vendors under-serve legacy manufacturing bases. Target Shandong Peninsula heavy machinery producers with API gateway integration packages that bridge proprietary industrial networks to containerized ROS deployments. Pursue outcome-based contracting with uptime guarantees rather than capital equipment sales to align procurement patterns with automotive tier-one supplier preferences. For Investors and Strategic Acquirers: Edge-AI engineering boutiques with distributed systems and real-time control expertise constitute the priority acquisition target archetype. These capabilities anchor premium pricing in hybrid cloud deployments while talent scarcity constrains deployment velocity for complex integrations. Monitor GB standard certification timeline compression as an inflection signal—accelerated MIIT platform approval processes would unlock pre-revenue development burn for portfolio companies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Edge Computing Hardware | Captive GPU and AI accelerator supply reduces Taiwan Strait transit exposure for Guangdong deployments. |
| MIIT Platform Certification Acceleration | Compressed approval timelines unlock fleet learning capabilities for foreign vendors establishing domestic cloud instances. |
| 5G-Advanced Network Partnership | Time-sensitive networking integration enables deterministic control loops for mobile manipulation applications. |
| Hybrid Cloud Orchestration Platform Launch | Edge-cloud balance attracts Yangtze River Delta warehouse operators pursuing dynamic fleet optimization. |
| Edge-AI Engineering Talent Acquisition | Distributed systems expertise alleviates deployment velocity constraints for complex cloud-robotics integrations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with robotics fleet managers, MIIT certification specialists, edge computing procurement leads, and cloud infrastructure architects. Secondary validation drew from MIIT cloud computing infrastructure standards documentation, SAMR data security regulation filings, GB industrial robot safety standard revisions, and hyperscaler capex disclosures for Chinese data center expansion. Bottom-up unit deployment estimates across Guangdong, Jiangsu, and Sichuan-Chongqing manufacturing bases were triangulated against top-down infrastructure investment forecasts.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type (industrial, collaborative, service), deployment architecture (public, private, hybrid, edge), end-use vertical (manufacturing, logistics, healthcare, retail), and technology layer (AI, machine learning, IoT, automation). CAGRs were derived from installed base growth trajectories and refresh cycle compression patterns. Industry-specific inputs included 5G coverage density metrics, MIIT certification pipeline velocity, and dual carbon policy compliance timelines for energy-efficient motor control systems.
Forecasts assume regulatory continuity in MIIT cloud computing standards and SAMR data security frameworks; material policy shifts around cross-border data flows or AI algorithm disclosure mandates would require re-modeling. Edge-AI talent availability, semiconductor supply concentration, and GB standard certification timeline variability constitute specific revision triggers. Practitioners should keep alternative scenarios live as MIIT enforcement priorities and 5G-Advanced network deployment schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Mobile Robotics Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Global Enterprise Robotic Process Automation Market
Robotics and Automation
Mobile Robot Charging Station Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
Wearable Robots and Exoskeletons Market
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Africa Cloud Robotics Market
Robotics and Automation
Handheld Robotics Market
Robotics and Automation
APAC Service Robots Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Quadruped Robot Market
Robotics and Automation
Latin America Cloud Robotics Market