
 Robotic Lawn Mower Market | 2026-2036
Robotic Lawn Mower Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Lawn Mower Market Analysis
Li-ion cell chemistry is shifting toward higher energy density formats that extend runtime per charge cycle while reducing unit weight. Husqvarna leverages its Nordic manufacturing footprint to sustain premium positioning in GPS-enabled systems. Bosch anchors its European market presence through industrial-grade sensor integration and channel control across commercial landscaping networks. Mammotion competes aggressively on price-performance in the autonomous navigation sub-category.
A robotic lawn mower is an autonomous or semi-autonomous mobile machine equipped with rotary blades, boundary detection sensors, and rechargeable battery packs, designed to cut grass surfaces without continuous human operation. These machines typically operate within defined perimeter zones using buried wire, GPS geofencing, or LiDAR-based obstacle recognition, serving residential, commercial, and municipal turf maintenance applications where labor reduction and scheduling consistency carry operational value. The residential segment dominates unit shipments across most developed economies, though commercial deployments to landscaping companies generate disproportionate margin pools due to higher duty-cycle requirements and service-contract attach rates. GPS-enabled technology leads replacement demand as precision mapping reduces missed strips and boundary overshoot, while sensor-based platforms occupy the value-tier entry point where cost sensitivity limits feature adoption.
The EPA regulates small-engine emissions standards that constrain gasoline-powered mower legality in the United States, while the EU Green Deal and REACH frameworks restrict hazardous substances in battery manufacturing and mandate circularity in end-of-life electronics across European markets. CE marking and FCC certification create dual compliance burdens for vendors selling transatlantically, effectively filtering out smaller hardware producers lacking dedicated regulatory affairs capacity. Stakeholders must monitor evolving battery recycling mandates and autonomous-vehicle liability frameworks as these rules will reshape warranty structures and aftermarket service economics.
Market Dynamics
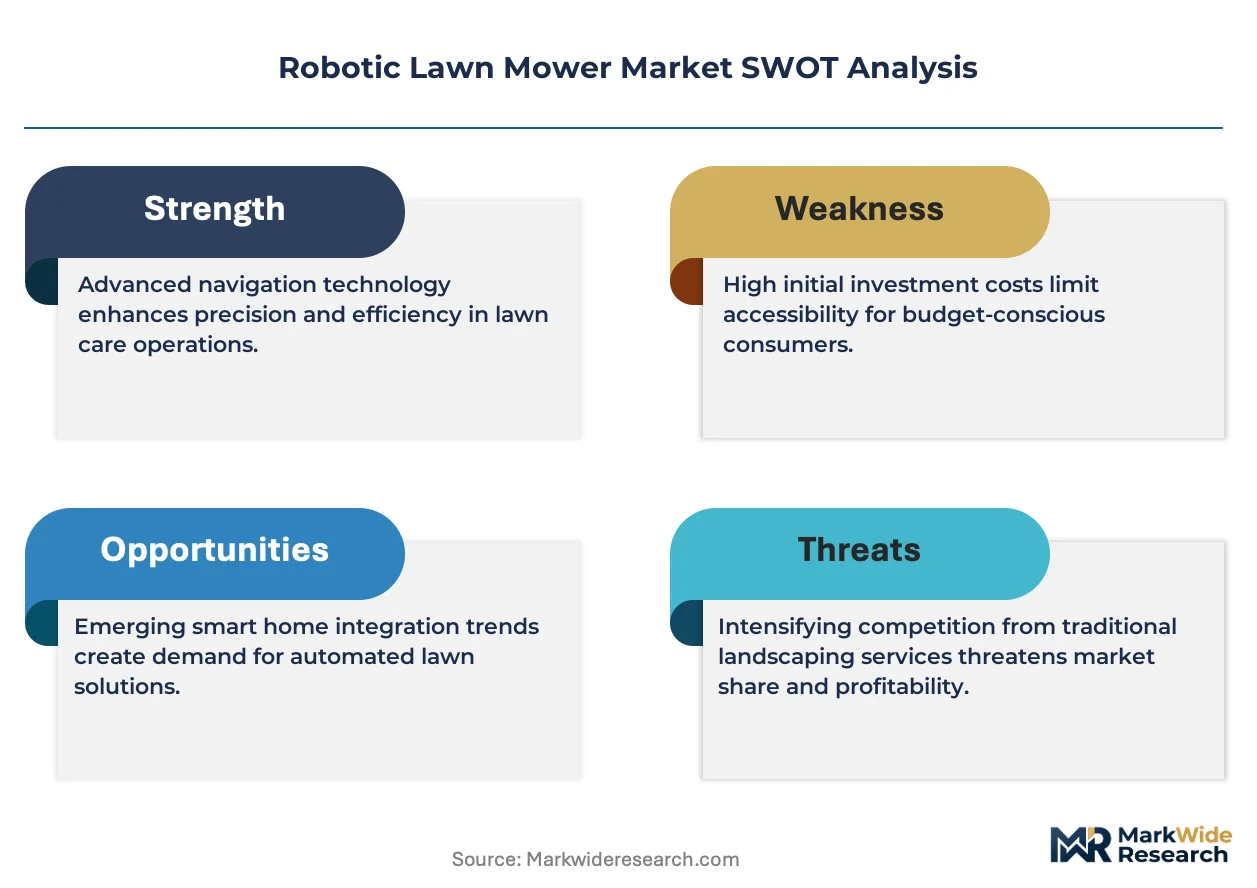
Labor cost inflation across developed economies is compressing maintenance budgets for landscaping operations, while EU machinery efficiency mandates under the Green Deal are accelerating the phase-out of gasoline-powered alternatives and forcing battery-platform investment.
Growth Catalysts
- EU Green Deal machinery mandates:Binding efficiency targets for outdoor power equipment are eliminating internal combustion engine eligibility and redirecting R&D spending toward battery-electric architectures.
- Landscaping company labor economics:Rising wage pressure in Germany, France, and the Netherlands is converting commercial turf maintenance fleets to autonomous systems that reduce crew-hour requirements.
- GPS geofencing maturation:Precision boundary mapping is reducing perimeter wire installation costs and expanding addressable property profiles to irregular terrain.
Market Restraints
- Li-ion cell supply concentration:Cathode active material processing clusters in China create single-source dependency risks for European and North American mower assemblers.
- REACH substance restrictions:ECHA authorization requirements for nickel and cobalt compounds are extending qualification timelines for new battery chemistries.
- Manual reel mower substitution:Low-cost mechanical alternatives retain cost advantage in sub-200 square meter residential plots across Southern Europe.
Strategic Opportunities
- Municipal turf contracts:Parks departments in Sweden and Denmark are piloting fleet-scale autonomous deployments with multi-year service agreements.
- Solar-integrated charging stations:Off-grid power infrastructure is expanding addressable markets to remote commercial sites without reliable grid access.
- CE marking harmonization:Mutual recognition agreements with Switzerland and Norway are simplifying cross-border distribution logistics for compliant manufacturers.
Industry Challenges
- Autonomous navigation algorithm talent:Shortage of computer vision specialists with outdoor robotics experience is delaying product roadmap execution for mid-tier vendors.
- FCC and CE dual certification:Transatlantic radio frequency compliance testing adds six-to-nine month delays to product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Lawn Mower Market |
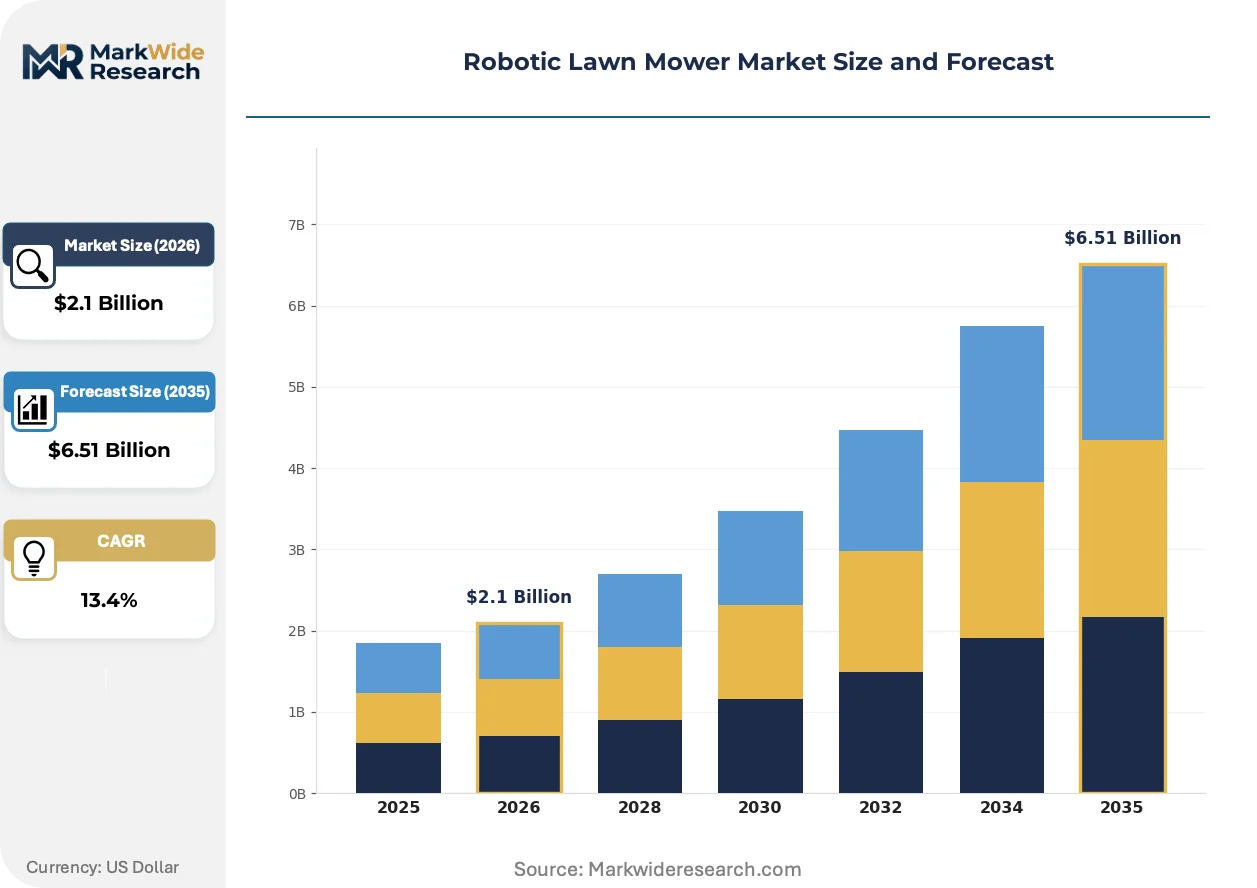
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.51 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential, Commercial, Hybrid, Industrial End User: Homeowners, Landscaping Companies, Golf Courses, Municipalities Technology: Autonomous, GPS-enabled, Smart Control, Sensor-based Power Source: Batteries, Solar, Gasoline, Electric |
| Companies Covered | Worx, Dreame, Husqvarna, Ecovacs, Greenworks, Mammotion, Roborock, Bosch, Segway-Ninebot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Lawn Mower Market Emerging Trajectories
Battery-electric powertrains are crossing performance thresholds that enable full substitution of gasoline systems, while regulatory pressure and buyer procurement evolution are reshaping competitive requirements across the value chain.
Swappable battery pack architecture is modularizing field service economics for commercial landscaping operators. Fleet managers in Germany and the Netherlands are adopting hot-swap systems that eliminate charging downtime during peak season. This configuration is modularizing the traditional unit-replacement cycle into component-level refresh programs.
The EU Green Deal's F-Gas Regulation and machinery efficiency directives are tightening emission thresholds for small engines. Gasoline-powered equipment faces progressive market exclusion in EU member states. Commercial landscaping procurement in Germany now specifies battery-electric platforms as default requirements.
Service contract unbundling is separating hardware ownership from maintenance responsibility. Landscaping companies in Scandinavia are shifting toward operational expenditure models where vendors retain asset ownership. This pattern concentrates most visibly in Denmark's municipal groundskeeping sector.
Robotic Lawn Mower Market Segmentation
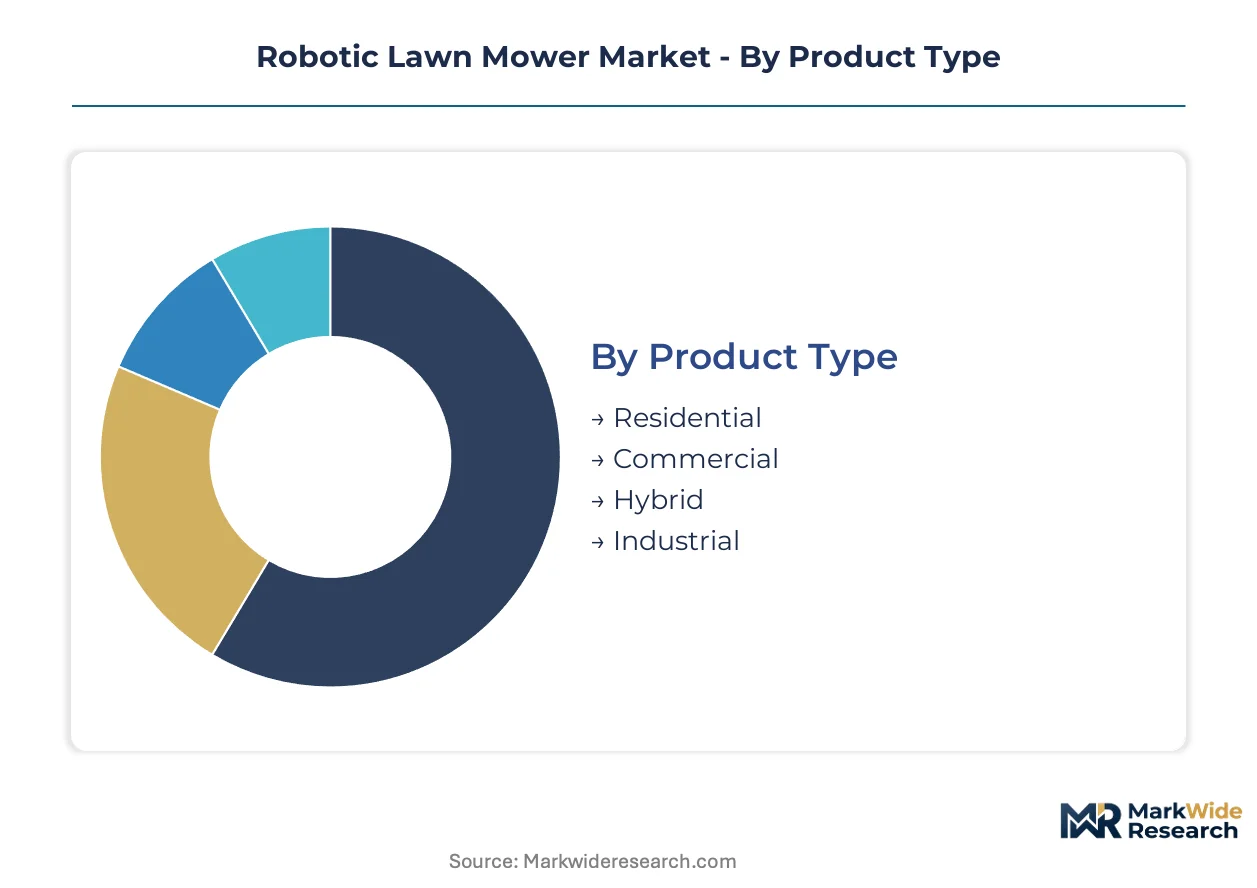
Segmentation in robotic lawn mowers reveals how technical specifications align with duty-cycle intensity and buyer procurement sophistication. Equipment specifications diverge sharply between occasional residential trimming and continuous commercial fleet deployment.
Product Type:
Standardization dominates entry-level units while commercial-grade systems require extensive customization for terrain mapping and fleet management integration.
- Residential:Compact deck sizes under 20 inches address sub-acre properties with simplified boundary-wire installation. Demand clusters in German suburban developments where environmental regulation and lawn ownership rates intersect.
- Commercial:Reinforced cutting decks and swappable battery architectures sustain 12-hour daily operation cycles. Landscaping companies in the Netherlands and Denmark are converting maintenance fleets to reduce crew-hour requirements amid wage inflation.
- Hybrid:Dual-power systems combine battery-electric primary drive with gasoline range extension for irregular terrain. Municipalities in remote Swedish counties evaluate these for park maintenance without reliable grid access.
- Industrial:Heavy-duty chassis rated for slopes exceeding 30 degrees serve golf course roughs and highway embankments. German golf resorts in Bavaria pilot these for labor reduction on contoured fairway margins.
Leading the category by volume: Residential. Expanding most quickly: Commercial.
End User:
Procurement sophistication separates price-sensitive individual buyers from institutional purchasers demanding service-contract integration and multi-year total-cost-of-ownership analysis.
- Homeowners:Individual purchasers prioritize plug-and-play installation and smartphone scheduling interfaces. German and French residential markets show strongest uptake where single-family home density and environmental awareness align.
- Landscaping Companies:Fleet operators require centralized monitoring platforms and rapid field-service turnaround. Danish and Swedish contractors are adopting operational-expenditure models where vendors retain asset ownership.
- Golf Courses:Turf managers demand precision cutting height control and minimal soil compaction for playability. Bavarian and Baden-Württemberg clubs represent early adoption clusters in Germany.
- Municipalities:Parks departments evaluate fleet-scale deployments with multi-year service agreements. Copenhagen and Stockholm pilot programs are establishing procurement templates for Scandinavian public groundskeeping.
Highest procurement sophistication: Landscaping Companies. Steepest adoption trajectory: Municipalities.
Technology:
Navigation architecture determines both unit economics and addressable terrain complexity, with boundary-definition methods creating distinct price-performance tiers.
- Autonomous:Self-directed operation with obstacle recognition and path optimization algorithms enables unattended multi-zone coverage. Commercial landscaping fleets in Germany prioritize these for crew reduction.
- GPS-enabled:Satellite geofencing eliminates perimeter wire installation and accommodates irregular property boundaries. Precision mapping reduces missed strips and boundary overshoot, driving replacement demand in premium residential segments.
- Smart Control:Cloud-connected platforms enable remote scheduling, theft tracking, and predictive maintenance alerts. Integration with smart home ecosystems appeals to tech-forward homeowners in Nordic markets.
- Sensor-based:Ultrasonic and bump-detection systems provide entry-level automation at reduced cost. Price-sensitive buyers in Southern European markets accept navigation limitations for lower acquisition outlay.
Dominant by installed base: Sensor-based. Gaining share fastest: GPS-enabled.
Power Source:
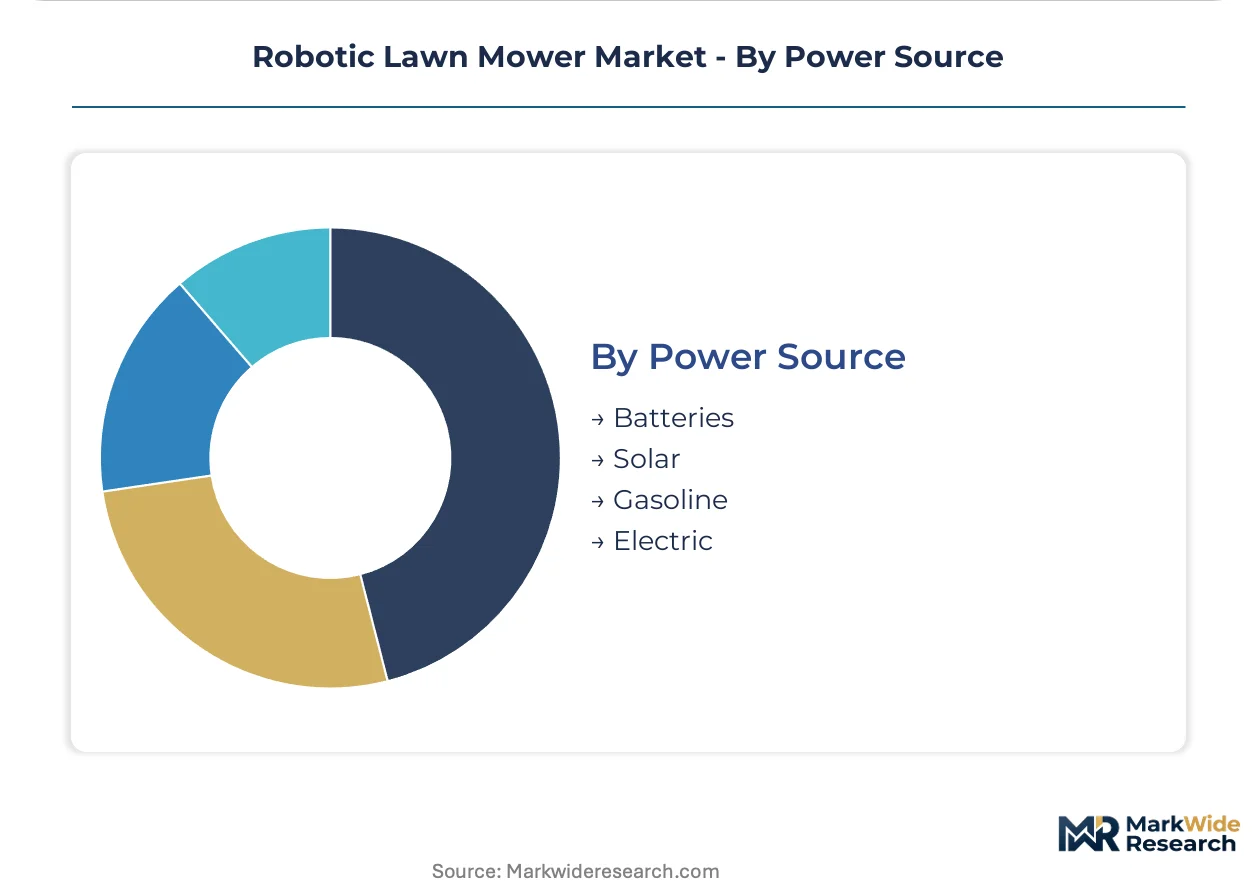
Regulatory phase-out timelines and charging infrastructure availability are concentrating investment toward battery-electric architectures across all duty-cycle categories.
- Batteries:Lithium-ion packs with energy density improvements now enable full gasoline substitution for properties under five acres. EU Green Deal machinery mandates are accelerating platform conversion in German and Dutch commercial fleets.
- Solar:Integrated photovoltaic charging stations extend addressable markets to off-grid commercial sites and remote municipal facilities. Swedish parks departments evaluate solar-integrated deployments for island and coastal maintenance.
- Gasoline:Internal combustion engines face progressive market exclusion under EU F-Gas Regulation and machinery efficiency directives. Remaining demand concentrates in legacy fleet replacement and non-EU export markets.
- Electric:Corded systems tethered to fixed power sources serve small enclosed properties with reliable grid access. Limited mobility constrains adoption to compact urban gardens in dense European city centers.
Platform commanding investment: Batteries. Facing regulatory displacement: Gasoline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German residential lawn ownership and Dutch commercial landscaping economics concentrate current demand. EU Green Deal machinery mandates redirect investment toward battery-electric platforms. Municipal procurement pilots in Scandinavia signal fleet-scale expansion.
Germany
High single-family home density and environmental awareness drive residential uptake. The EU Green Deal's machinery efficiency directives accelerate gasoline phase-out timelines. Bavarian golf resorts pilot industrial-grade units for fairway margin maintenance.
Netherlands
Landscaping companies face acute wage pressure converting fleets to autonomous systems. ECHA REACH substance restrictions extend battery chemistry qualification timelines. Randstad contractors adopt operational-expenditure models with vendor-retained asset ownership.
Sweden
Municipal parks departments evaluate fleet-scale deployments with multi-year service agreements. The EU F-Gas Regulation excludes internal combustion engines from public procurement eligibility. Stockholm pilot programs establish templates for Scandinavian public groundskeeping.
United States
EPA small-engine emissions standards constrain gasoline-powered mower legality in multiple states. FCC certification requirements create compliance burdens for transatlantic vendors. Suburban developments in the Northeast and Pacific Northwest show strongest residential adoption clusters.
Denmark
Copenhagen municipal procurement specifies battery-electric platforms as default requirements. CE marking harmonization with Norway simplifies cross-border distribution logistics. Danish landscaping contractors lead operational-expenditure model adoption in commercial segments.
Robotic Lawn Mower Market Vendor Landscape
Capacity expansion dominates the current landscape as vendors scale battery-platform production to meet EU machinery mandate deadlines. The vendor base organizes around three archetypes: Nordic precision-engineering specialists, Chinese price-performance manufacturers, and European industrial conglomerates with sensor integration depth. Strategic partnerships for LiDAR component sourcing and geographic expansion into municipal procurement channels represent the dominant competitive moves.
Within the precision-engineering tier, Husqvarna leverages its Nordic manufacturing footprint for GPS-enabled system positioning. Bosch anchors European market presence through industrial-grade sensor integration. Mammotion competes aggressively on price-performance in autonomous navigation sub-categories, representing the Chinese manufacturing archetype's market entry pattern.
| Leading Market Players |
|---|
| Worx |
| Dreame |
| Husqvarna |
| Ecovacs |
| Greenworks |
| Mammotion |
| Roborock |
| Bosch |
| Segway-Ninebot |
| Others |
Supply Flow & Price Mechanics
Landscaping company fleet operators concentrate procurement volume and negotiate operational-expenditure contracts that shift pricing power toward vendors with swappable battery architectures and centralized monitoring platforms. This buyer concentration rewards modular service economics over unit-transaction models.
Pricing Analysis
Volume concentrates in sensor-based entry-tier units while margin pools accrue to GPS-enabled commercial systems with fleet-management integration. Price differentiation rests on navigation precision tier and battery chemistry certification under REACH substance restrictions. Cost compression in the residential segment intensifies as Chinese manufacturers expand autonomous navigation capabilities. Homeowners in Southern European markets exhibit highest price sensitivity, while Danish municipal procurement shows lowest sensitivity due to total-cost-of-ownership framing.
Supply Chain Analysis
Reverse-logistics flows for battery pack refurbishment and end-of-life recycling are emerging as cost centers under EU circularity mandates for electronics. Cathode active material processing clusters in China, South Korea, and Japan anchor upstream supply for Li-ion cells. The supply chain draws from cobalt and nickel feedstocks subject to ECHA authorization delays. Single-source vulnerability in cathode precursor processing creates qualification timeline risk for European assemblers. Distribution runs through commercial landscaping networks in Germany and the Netherlands, with direct-to-consumer channels serving Nordic residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robotic lawn mower market sits in a technology-transition phase where battery-electric architectures are displacing gasoline powertrains under regulatory pressure from the EU Green Deal machinery efficiency directives.
For Market Incumbents: Deploy swappable battery platform standardization to lock in fleet operator switching costs and defend against emerging Chinese autonomous navigation specialists. Accelerate CE marking harmonization with Norway and Switzerland to simplify cross-border distribution logistics. Invest in predictive maintenance algorithm development to differentiate service-contract economics. For New Entrants and Emerging Players: The mid-tier price-point gap between Husqvarna's GPS-enabled premium systems and entry-level sensor-based units offers white-space opportunity for autonomous navigation capabilities at reduced cost. Municipal procurement pilots in Sweden and Denmark represent the most penetrable institutional segment. A go-to-market angle through operational-expenditure fleet leasing bypasses capital-budget constraints at commercial landscaping contractors. For Investors and Strategic Acquirers: The window for entry favors component specialists with LiDAR or computer vision capabilities that can plug into existing OEM platform architectures. Long-term viability hinges on regulatory compliance capacity and battery chemistry qualification speed. The signal to watch is ECHA substance restriction expansion to additional cathode materials, which would reshape competitive positioning for vendors with alternative chemistry pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Swappable Battery Architecture Deployment | Modular field service economics reduce downtime for German landscaping fleet operators during peak season. |
| CE Marking Harmonization Expansion | Mutual recognition agreements with Switzerland and Norway streamline distribution for compliant manufacturers. |
| LiDAR Component Sourcing Partnership | Precision mapping capabilities differentiate GPS-enabled systems from sensor-based entry-tier alternatives. |
| Municipal Fleet Pilot Conversion | Copenhagen and Stockholm procurement templates establish scalable templates for Scandinavian public groundskeeping. |
| Solar-Integrated Charging Infrastructure | Off-grid power expansion addresses remote Swedish municipal sites without reliable grid access. |
Methodological Framework
Trade association filings, EU regulatory databases, and customs import records formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with commercial landscaping fleet managers, municipal parks procurement officers, battery supply chain specialists, and robotic navigation engineers validated demand assumptions and technology adoption timelines. Bottom-up unit shipment estimates and top-down spending allocation analysis were triangulated against OEM production disclosures and channel inventory data.
Bottom-up modeling tracked unit shipments by product tier, end-user segment, and navigation technology type across the projection horizon. Top-down validation assessed aggregate spending patterns in commercial turf maintenance and municipal groundskeeping budgets. CAGRs were derived from segmented growth trajectory analysis incorporating EU machinery mandate phase-out timelines and battery chemistry substitution curves. Forecast inputs included landscaping wage inflation indices and REACH substance restriction implementation schedules.
Inputs from municipal procurement databases and commercial fleet operator surveys were available through the study window; gaps in real-time battery chemistry cost data introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding regulatory implementation pace and technology substitution thresholds. Practitioners should monitor ECHA authorization timeline announcements and Li-ion cell capacity expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Articulated Robots for Injection Molding Machine Market
Robotics and Automation
AGV & AMR in Logistics Market
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Self-Driving Delivery Robot Market
Robotics and Automation
Robot Fleet Management Software Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Rotary Gripper Module Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Global Rescue Robot Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Waste Sorting Robots Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Robotic Flexible Washer Market
Robotics and Automation
Consumer and Office Robot Market
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market