
 Global Autonomous Mobile Robot Market | 2026-2036
Global Autonomous Mobile Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autonomous Mobile Robot Market Analysis
Third-party logistics providers are unwinding their historical reliance on fixed automation, redirecting capital toward flexible mobile platforms that adapt to seasonal volume swings. Geekplus Technology Co., Ltd. leverages its manufacturing scale to dominate warehouse automation deployments across Asia-Pacific. ABB anchors European demand through its integration of autonomous forklifts with existing plant control systems. KUKA AG competes on sensor fusion depth, sustaining R&D intensity in machine learning-driven path planning.
Autonomous mobile robots are self-navigating vehicles equipped with LiDAR, cameras, and inertial measurement units that execute material transport without fixed infrastructure or human drivers, primarily serving manufacturing floors and distribution centers where throughput velocity determines operational economics. Warehouse automation absorbs the largest share of deployed units, though delivery robots represent the fastest-expanding margin pool as last-mile operators seek labor cost containment. Service robots occupy a mature niche in healthcare corridors, while exploration robots attract specialized defense and subterranean mining budgets.
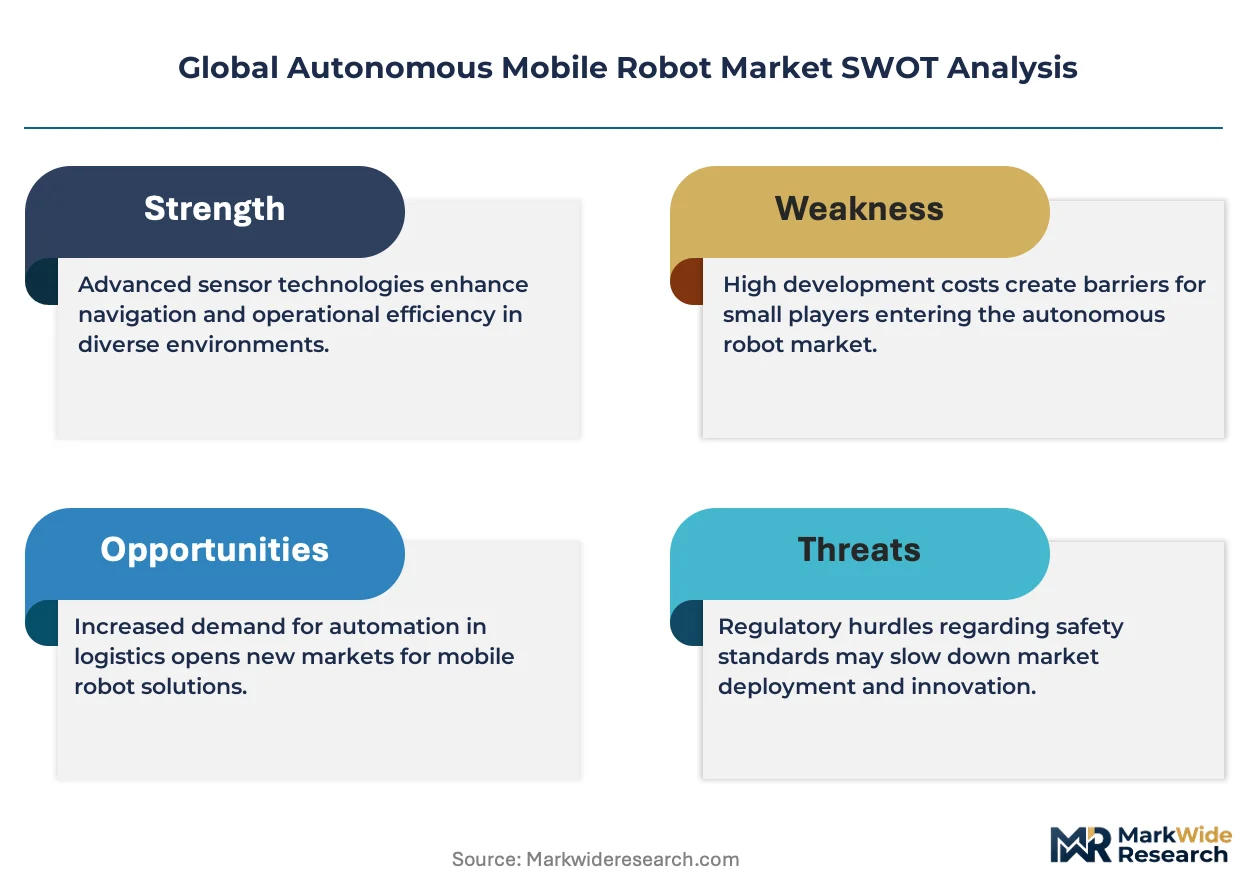
The EU AI Act, ISO 3691-4 safety standards, and China's MIIT navigation certification framework collectively elevate compliance costs for cross-border suppliers while creating barriers for uncertified entrants. OSHA in the United States and Japan's METI issue complementary workplace safety directives that mandate collision avoidance thresholds and human-robot collaboration protocols. Stakeholders must monitor divergence between regional certification timelines to avoid stranded development investments.
Market Dynamics
E-commerce fulfillment networks are forcing a capital reallocation from fixed conveyor systems toward autonomous mobile platforms that reconfigure within hours rather than weeks. This structural shift compresses deployment timelines and rewards vendors with software-native fleet orchestration capabilities.
Growth Catalysts
- Labor scarcity in logistics:Warehouse operators in Germany and the United States face persistent forklift operator shortages, accelerating autonomous forklift procurement.
- EU AI Act certification pathways:The regulation's risk-based classification creates clarity for high-risk autonomous navigation systems, reducing regulatory uncertainty for compliant vendors.
- LiDAR cost curves:Solid-state LiDAR manufacturing scale is collapsing sensor costs, enabling mid-tier warehouse operators to justify AMR deployments.
Market Restraints
- ISO 3691-4 compliance costs:Safety certification for collaborative mobile robots requires extensive third-party testing, adding six-figure expenses per platform variant.
- Concentrated LiDAR supply:High-performance sensor production concentrates among Asian component suppliers, creating input vulnerability for European and North American integrators.
- Legacy WMS integration friction:Proprietary warehouse management system architectures in established distribution centers resist API-based fleet management overlays.
Strategic Opportunities
- Healthcare corridor automation:Hospital pharmacy and linen delivery applications remain underpenetrated in Japan and South Korea, offering first-mover positioning for navigation-hardened platforms.
- MIIT navigation certification:China's streamlined type-approval process for industrial autonomous vehicles accelerates market entry for compliant foreign suppliers.
- 5G private network convergence:Ultra-reliable low-latency connectivity is enabling cloud-based path planning that offloads compute from edge hardware, reducing unit costs.
Industry Challenges
- Multi-fleet orchestration talent:Scarcity of robotics engineers with simultaneous expertise in machine learning, safety systems, and operational technology integration constrains deployment velocity.
- Site-specific commissioning:Each facility requires weeks of SLAM mapping and safety zone validation, compressing vendor margins and extending customer payback periods.
- Cross-jurisdiction certification divergence:OSHA workplace safety directives, EU machinery directives, and Japan's METI collaborative robot guidelines create fragmented compliance roadmaps for multinational customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autonomous Mobile Robot Market |
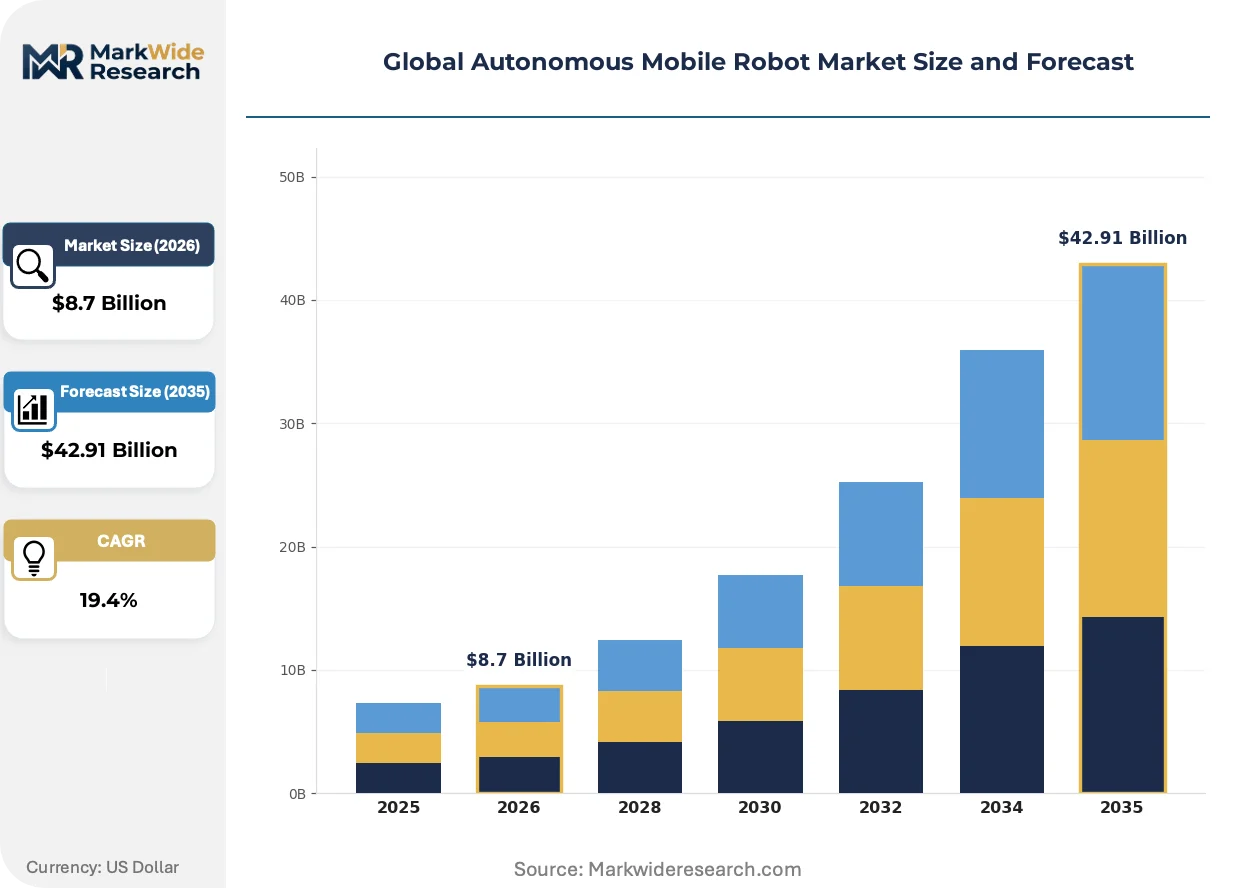
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Warehouse Automation, Delivery Services, Robotics Process Automation, Inventory Management End User: Retail, Healthcare, Manufacturing, Logistics Technology: Navigation Systems, Sensor Fusion, Machine Learning, AI Algorithms Product Type: Autonomous Forklifts, Service Robots, Delivery Robots, Exploration Robots |
| Companies Covered | ABB, KUKA AG, Omron Corporation, Mobile Industrial Robots, Geekplus Technology Co., Ltd., Zebra Technologies, Locus Robotics, GreyOrange, Boston Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autonomous Mobile Robot Market Emerging Trajectories
Navigation autonomy is migrating from hardware-heavy sensor stacks toward software-defined perception, compressing bill-of-materials costs while elevating fleet intelligence. This transition rewards compute-centric vendors and challenges legacy sensor manufacturers.
Vision-only navigation systems leveraging neural radiance fields are displacing LiDAR-dominant architectures in controlled indoor environments. Third-party logistics providers in the United States are piloting camera-first platforms for pallet transport. The shift is compressing hardware costs by thirty to fifty percent while demanding greater edge compute investment.
The EU AI Act's high-risk system requirements are mandating explainable path-planning algorithms and human oversight protocols for autonomous industrial vehicles. Manufacturers must document decision logic and maintain audit trails. German automotive suppliers are responding by embedding compliance documentation tools directly into fleet management software.
Third-party logistics contracts are fragmenting from multi-year automation leases toward short-term fleet rentals with performance-based pricing. Retail peak seasons now drive spot demand for mobile robot capacity rather than permanent installation. This pattern is most visible in the United Kingdom and Netherlands, where e-commerce volatility has normalized flexible procurement terms.
Global Autonomous Mobile Robot Market Segmentation
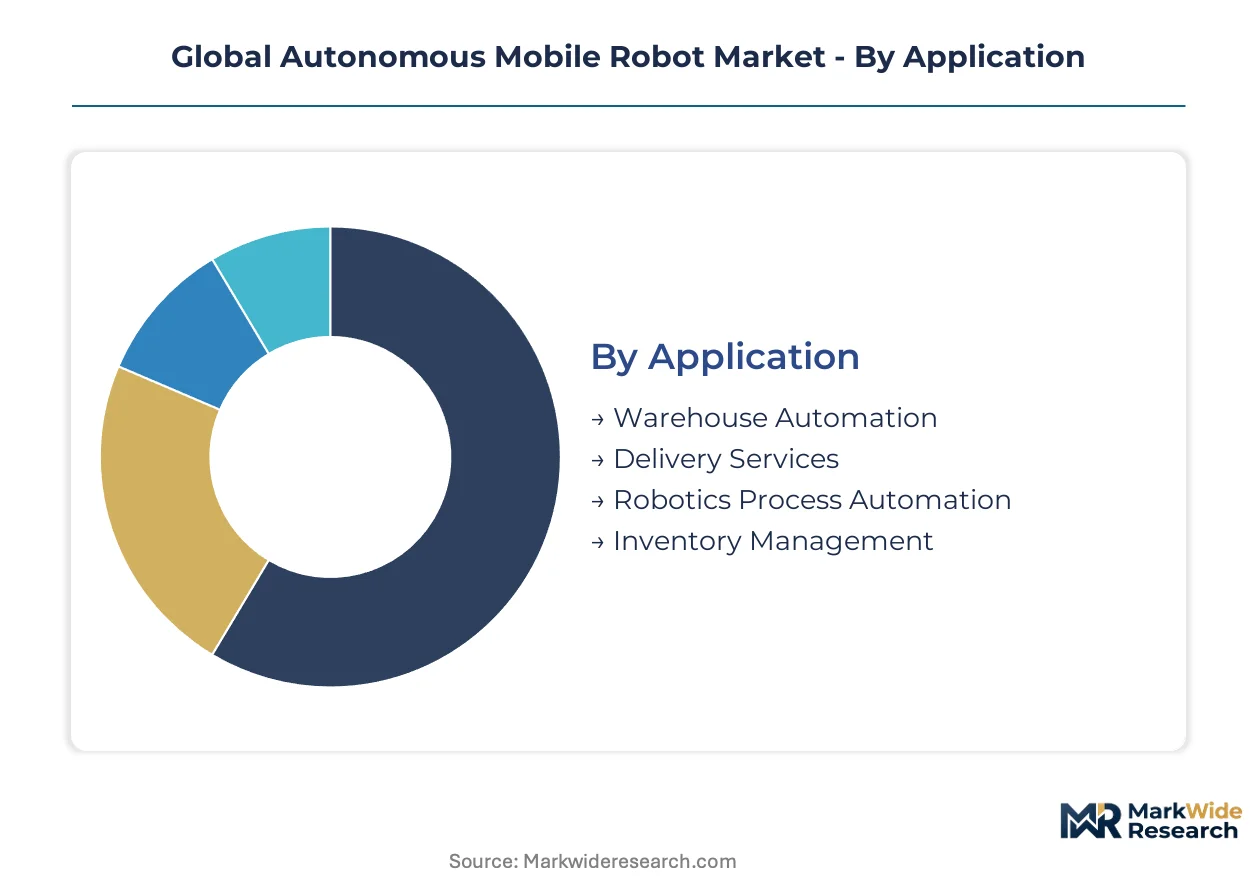
Segmentation reveals where capital allocation pressures differ most sharply across the autonomous mobile robot value chain. Procurement patterns diverge significantly between fixed-infrastructure replacements and greenfield autonomous deployments.
Application:
Substitution pressure from fixed automation systems weighs heaviest on segments serving established distribution networks.
- Warehouse Automation:Autonomous mobile robots replace conveyor belts and fixed-sortation infrastructure in fulfillment centers. Demand concentrates in Germany and the United States where e-commerce operators face acute forklift operator shortages and seasonal volume volatility.
- Delivery Services:Last-mile autonomous vehicles navigate sidewalks and curbside environments for parcel and food delivery. Operators in the United Kingdom and Netherlands are piloting short-term fleet rentals rather than permanent installation to match retail peak seasonality.
- Robotics Process Automation:Software-driven workflow automation complements physical AMR deployments in administrative and operational coordination layers.
- Inventory Management:Cycle-counting robots traverse aisles to verify stock levels and locations without warehouse shutdowns.
Warehouse Automation retains volume leadership; Delivery Services holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive manufacturing deployments from rental-flexible logistics contracts.
- Logistics:Third-party logistics providers redirect capital from fixed automation toward mobile platforms that reconfigure within hours. Procurement in the Netherlands and United Kingdom has normalized short-term fleet rentals with performance-based pricing.
- Manufacturing:Automotive and electronics producers integrate autonomous forklifts with plant control systems for just-in-time material flow. German automotive suppliers embed EU AI Act compliance documentation directly into fleet management software.
- Retail:E-commerce fulfillment networks force structural shifts from conveyor systems to autonomous platforms.
- Healthcare:Hospital pharmacy and linen delivery applications remain underpenetrated in Japan and South Korea.
Logistics commands the largest installed base; Healthcare offers the most underpenetrated addressable market.
Technology:
Supply concentration in Asian component manufacturers creates input vulnerability for European and North American integrators.
- Navigation Systems:SLAM-based localization and path-planning software defines fleet intelligence. Vision-only architectures leveraging neural radiance fields are displacing LiDAR-dominant stacks in controlled indoor environments.
- Sensor Fusion:Integration of LiDAR, cameras, and inertial measurement units enables robust environmental perception. Solid-state LiDAR manufacturing scale is collapsing sensor costs and enabling mid-tier warehouse operators to justify deployments.
- Machine Learning:Edge compute investment demands rise as software-defined perception replaces hardware-heavy sensor stacks.
- AI Algorithms:Explainable path-planning and human oversight protocols are mandated under EU AI Act high-risk system requirements.
Navigation Systems anchor current bill-of-materials; Sensor Fusion is gaining share fastest as hardware costs compress.
Product Type:
Margin structure separates industrial-grade certified platforms from consumer-facing delivery units with lighter regulatory burdens.
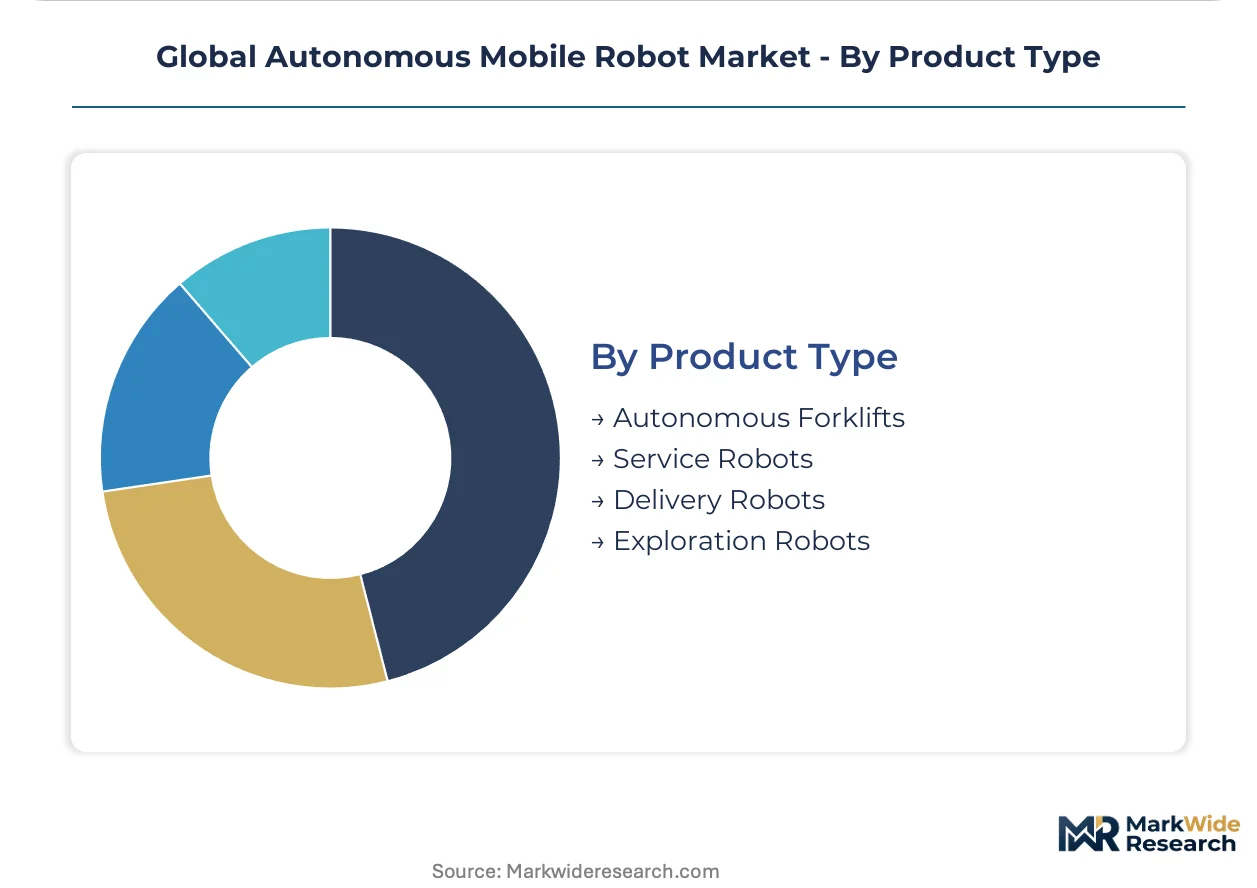
- Autonomous Forklifts:Industrial vehicles equipped with pallet handling mechanisms navigate manufacturing floors and distribution centers. ISO 3691-4 safety certification requires extensive third-party testing, adding six-figure expenses per platform variant.
- Delivery Robots:Compact sidewalk vehicles execute last-mile parcel transport. Pilots in the United States are testing camera-first platforms that compress hardware costs while demanding greater edge compute investment.
- Service Robots:Healthcare corridor and hospitality applications occupy a mature niche with established safety protocols.
- Exploration Robots:Subterranean mining and defense applications attract specialized budgets with extreme environment hardening requirements.
Autonomous Forklifts dominate current revenue; Delivery Robots are climbing the fastest as last-mile labor costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in China and South Korea dominate sensor supply, while demand concentration tracks e-commerce fulfillment buildouts in Germany and the United States. Regulatory divergence across OSHA, EU AI Act, and MIIT frameworks fragments vendor certification roadmaps.
United States
Fulfillment center construction in Dallas-Fort Worth and Indianapolis drives autonomous forklift procurement. OSHA workplace safety directives mandate collision avoidance thresholds for human-robot collaboration zones. Michigan automotive suppliers integrate AMRs with plant control systems for just-in-time material flow.
Germany
Automotive producers in Stuttgart and Wolfsburg anchor industrial AMR demand for assembly line feeding. EU AI Act high-risk system requirements mandate explainable path-planning algorithms with audit trail documentation. Bavarian logistics hubs near Munich deploy vision-only navigation pilots to compress hardware costs.
China
MIIT navigation certification streamlines type-approval for industrial autonomous vehicles, accelerating foreign supplier market entry. Yangtze River Delta fulfillment centers absorb the largest warehouse automation volumes. Shenzhen-based component manufacturers dominate solid-state LiDAR production scale.
Japan
METI collaborative robot guidelines establish human-robot interaction protocols for manufacturing floors. Hospital pharmacy automation remains underpenetrated in Tokyo and Osaka corridors. Nagoya automotive clusters test 5G private networks for cloud-based path planning offload.
Netherlands
Rotterdam port logistics operators pilot short-term fleet rentals rather than permanent AMR installation. E-commerce volatility has normalized flexible procurement terms with performance-based pricing. Randstad distribution hubs reconfigure mobile platforms within hours to match seasonal volume swings.
Global Autonomous Mobile Robot Market Vendor Landscape
Concentration sits with diversified industrial automation conglomerates and software-native fleet orchestration specialists. The vendor base splits between established European industrial equipment manufacturers and Asia-Pacific scale players. Three archetypes dominate: integrated automation platforms, pure-play AMR software vendors, and sensor-to-fleet vertical specialists. Competitive moves center on strategic partnerships for WMS integration and geographic expansion through local certification compliance.
Among diversified industrial conglomerates, ABB and KUKA AG exemplify the integrated platform archetype, anchoring European demand through plant control system compatibility. Geekplus Technology Co., Ltd. occupies a position within the Asia-Pacific scale-driven tier, representing manufacturing-scale deployment capabilities. These three entities collectively illustrate the geographic and strategic bifurcation shaping vendor positioning.
| Leading Market Players |
|---|
| ABB |
| KUKA AG |
| Omron Corporation |
| Mobile Industrial Robots |
| Geekplus Technology Co., Ltd. |
| Zebra Technologies |
| Locus Robotics |
| GreyOrange |
| Boston Dynamics |
| Others |
Supply Flow & Price Mechanics
Long-term fleet rental contracts with performance-based pricing clauses lock in both LiDAR sensor access and cost visibility for third-party logistics operators navigating EU AI Act compliance timelines. These agreements compress margin volatility for warehouse automation vendors while binding buyers to specific certification tiers.
Pricing Analysis
EU AI Act high-risk system requirements dictate the pricing tier structure across the autonomous mobile robot market. Three-tier pricing structure across premium, standard, and economy levels separates ISO 3691-4 certified platforms from uncertified alternatives and from vision-only navigation systems. Price differentiation rests on certification level and sensor fusion depth. Cost compression in mid-tier warehouse segments is intensifying because solid-state LiDAR manufacturing scale is collapsing input costs. E-commerce fulfillment operators show highest price sensitivity, while automotive manufacturers absorbing AMRs into plant control systems demonstrate lowest.
Supply Chain Analysis
Strategic stockpile preferences dominate sensor procurement as warehouse operators buffer against concentrated Asian component supply. Solid-state LiDAR production centers on China and South Korea, with inertial measurement unit fabrication anchored in Japan and Taiwan. Raw material dependencies include rare earth elements for motor magnets, silicon carbide substrates for power electronics, and specialized optical glass for camera lenses. Single-source vulnerability in high-performance LiDAR emitters creates procurement risk for European and North American integrators. Distribution runs through direct OEM relationships with fulfillment center operators and systems integrators serving manufacturing floors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification regimes and fleet orchestration capabilities creates niche entry points for specialized vendors. E-commerce fulfillment networks are forcing procurement pattern shifts from permanent installation toward flexible capacity contracts.
For Market Incumbents: Compound certification breadth across OSHA, EU AI Act, and MIIT frameworks to lock out emerging competitors lacking compliance infrastructure. Prioritize backward integration into solid-state LiDAR supply through strategic component partnerships, defending against sensor cost compression that erodes hardware margins. Threat substitution comes from vision-only navigation platforms displacing sensor-heavy architectures in controlled indoor environments. For New Entrants and Emerging Players: Differentiate on software-native fleet orchestration capabilities that compress site-specific commissioning timelines from weeks to days. White-space targets include hospital pharmacy automation in Japan and South Korea, plus 5G private network convergence for cloud-based path planning offload. Go-to-market angle: short-term rental contracts with performance-based pricing aligned to retail peak seasonality. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet management software vendors with embedded compliance documentation tools. Long-term viability favors compute-centric platforms over sensor-dependent hardware manufacturers as navigation autonomy migrates toward software-defined perception. Acquisition target archetype: pure-play AMR software vendors with proven WMS integration capabilities. Signal to watch: divergence between regional certification timelines creating stranded development investments.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Establishes market access for high-risk autonomous navigation systems in German automotive corridors. |
| 5G Private Network Deployment | Enables cloud-based path planning offload for Nagoya manufacturing clusters testing ultra-reliable connectivity. |
| Vision-Only Navigation Pilot Programs | Compresses hardware costs thirty to fifty percent for United States third-party logistics pallet transport trials. |
| Strategic LiDAR Component Partnership | Secures solid-state sensor supply for European integrators facing concentrated Asian manufacturer dependency. |
| WMS Integration Platform Development | Resolves API friction with proprietary warehouse management architectures in established distribution centers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and hyperscaler capex disclosures. Primary interviews engaged fleet operations directors at third-party logistics providers, plant engineers at German automotive suppliers, procurement leads at e-commerce fulfillment networks, and robotics integration specialists. Secondary validation drew from OSHA workplace safety directives, EU AI Act implementation guidance, MIIT type-approval databases, and SEC filings from industrial automation conglomerates. Bottom-up unit deployment estimates triangulate against top-down market sizing across the analysis window.
Segmentation dimensions modeled include application type, end-user industry, navigation technology architecture, and product certification tier. CAGRs derive from installed base growth rates applied to average selling price trajectories. Industry-specific forecast inputs incorporate LiDAR cost curve assumptions and e-commerce fulfillment center construction pipelines.
Material uncertainties — regulatory timeline slippage, sensor supply disruption, WMS integration friction — sit outside the modeled envelope. Forecasts reflect assumptions about certification harmonization progress and fleet rental contract normalization. Revision becomes warranted when cross-jurisdiction certification divergence exceeds eighteen-month implementation gaps.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Exoskeleton Systems Market
Robotics and Automation
Japan Articulated Robot Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Robotic Desktop Automation (RDA) Market
Robotics and Automation
Claytronics Market
Robotics and Automation
North America Cloud Robotics Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Humanoids Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
Canada Cloud Robotics Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Global Exoskeleton Market
Robotics and Automation
United States Agricultural Robots Market
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
Lab Robotics Market