
 Industrial Robot Controllers Market | 2026-2036
Industrial Robot Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Robot Controllers Market Outlook
The divergence between premium and commodity tiers is repositioning how vendors allocate engineering resources, as high-mix manufacturers demand adaptive control architectures while cost-sensitive buyers prioritize basic point-to-point motion. FANUC Corporation leverages its captive servo motor and drive production to sustain margin control across integrated controller-robot bundles. ABB Ltd competes through its OmniCore platform, which anchors software-defined motion planning for collaborative cells. KUKA AG differentiates via deep automotive line integration, occupying the premium tier where cycle-time guarantees command pricing power.
Industrial robot controllers are embedded computing systems that execute real-time trajectory generation, servo loop closure, and safety interlocking for multi-axis manipulators, typically operating with cycle times below one millisecond and supporting fieldbus protocols such as EtherCAT and PROFINET. Their primary purpose is to translate high-level task commands into precise motor torque and position instructions while enforcing functional safety boundaries. Programmable controllers lead unit shipments due to their flexibility across welding and material handling workflows, though PC-based controllers represent the fastest-expanding category as open-architecture systems enable AI-driven path optimization. Modular controllers concentrate margin pools in aerospace and electronics end users where certification traceability and rapid reconfiguration justify premium positioning.
The EU Machinery Directive, ISO 10218 safety standards, and China's GB robot standards collectively shape product design by mandating force-limiting behaviors, emergency-stop response latencies, and electromagnetic compatibility testing for controller hardware sold into regulated environments. FDA oversight of robotic surgical systems and NHTSA guidance on autonomous manufacturing transport extend compliance burdens to controllers deployed in medical and mobility-adjacent applications. Stakeholders must monitor how fragmented national certification regimes affect platform standardization decisions and whether software update obligations shift liability upstream to controller vendors.
Market Dynamics
The Industrial Robot Controllers Market is experiencing structural pressure from software-defined motion architectures that separate hardware from algorithmic control, forcing incumbents to reallocate engineering resources toward open-platform development while defending proprietary fieldbus ecosystems.
Growth Catalysts
- EU Machinery Directive compliance mandates:Force-limiting controller behaviors and emergency-stop latency requirements are accelerating replacement cycles in collaborative robot deployments across German automotive assembly plants.
- Electric vehicle battery assembly investments:Gigafactory construction in China and Germany is generating concentrated demand for multi-axis synchronized controllers capable of sub-millimeter positioning repeatability in cell stacking operations.
- EtherCAT industrial Ethernet adoption:Real-time deterministic communication protocols are displacing legacy fieldbus networks in high-speed packaging lines, enabling distributed controller architectures that reduce cabinet wiring complexity.
Market Restraints
- Semiconductor supply concentration:FPGA and high-speed ADC sourcing from Taiwanese foundries creates vulnerability in controller production schedules, with lead times extending beyond 26 weeks for safety-critical processing modules.
- ISO 10218-2 certification complexity:Human-robot collaboration interface validation requires third-party testing that adds 8-14 months to product launch timelines, compressing effective revenue windows for new controller generations.
- PC-based open architecture substitution:Industrial PC platforms running real-time Linux or hypervisor-based systems are capturing mid-range applications previously served by dedicated robot controllers, eroding hardware margin pools.
Strategic Opportunities
- India precision manufacturing expansion:PLI scheme incentives for electronics and automotive component production are creating first-mover advantage for controller vendors establishing localized technical support and spare parts logistics.
- AI-driven predictive maintenance convergence:Controller-embedded vibration analysis and motor signature monitoring are enabling outcome-based service contracts that extend customer lifetime value beyond hardware shipment margins.
- GB standard harmonization in China:Alignment between Chinese national robot safety standards and ISO frameworks is reducing dual-certification burdens, streamlining market entry for controllers already validated to European norms.
Industry Challenges
- Real-time systems engineering talent scarcity:Controller firmware development requires expertise in deterministic scheduling and safety-critical coding practices that command premium compensation and extend recruitment cycles.
- Legacy robot fleet integration friction:Retrofitting 15-20 year old manipulators with modern safety-certified controllers demands custom kinematic parameter extraction and mechanical interface adaptation that erodes project profitability.
- Functional safety documentation burden:IEC 61508 SIL certification requires exhaustive failure mode analysis and fault injection testing that consumes 30-40% of total product development engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Robot Controllers Market |
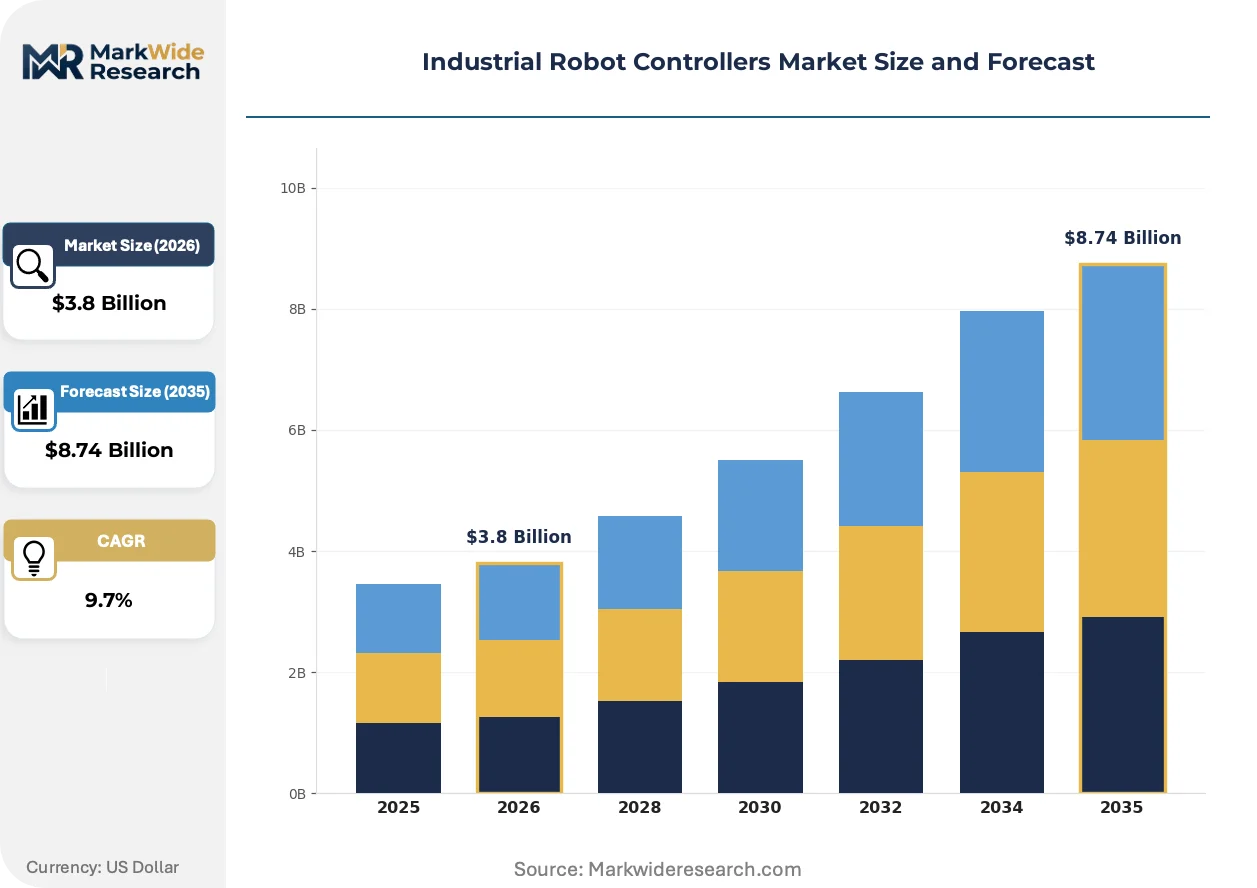
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Controllers, Modular Controllers, PC-Based Controllers, Motion Controllers Technology: Analog Control, Digital Control, Pneumatic Control, Hydraulic Control End User: Manufacturing, Automotive, Electronics, Aerospace Application: Welding, Material Handling, Assembly, Packaging |
| Companies Covered | Yaskawa Electric Corporation, Mitsubishi Electric Corporation, KUKA AG, ABB Ltd, FANUC Corporation, OMRON Corporation, DENSO Corporation, Stäubli International AG, Kawasaki Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Robot Controllers Market Strategic Shifts
Software-defined control architectures are decoupling motion planning from servo execution, enabling algorithmic updates without hardware replacement and compressing the traditional 7-10 year controller lifecycle.
Edge AI accelerators are integrating into robot controller backplanes to execute neural network inference for collision-free path planning directly at the motion control layer. Automotive OEMs in Germany and Japan are piloting these configurations in welding cells where environmental variability exceeds rule-based trajectory capabilities. This capability is integrating adaptive motion generation that reduces teach-point programming time by eliminating fixed-path constraints.
REACH substance restrictions on lead-bearing solder and halogenated flame retardants are forcing controller PCB redesigns with tin-silver-copper alloys and phosphorus-based alternatives that alter thermal cycling reliability profiles. European industrial automation suppliers are absorbing 12-18 month requalification costs ahead of 2026 enforcement deadlines. Medical device manufacturers face compounded compliance burdens as FDA electromagnetic compatibility requirements intersect with EU material restrictions.
After-sales service unbundling is separating hardware warranty from software maintenance and field engineering support, with battery manufacturers in China and South Korea negotiating à-la-carte technical assistance contracts. Distributors are losing attach-rate leverage as direct vendor relationships capture recurring revenue streams. This restructuring is most pronounced in electric vehicle supply chain deployments where production line uptime guarantees dominate purchasing criteria.
Industrial Robot Controllers Market Segmentation
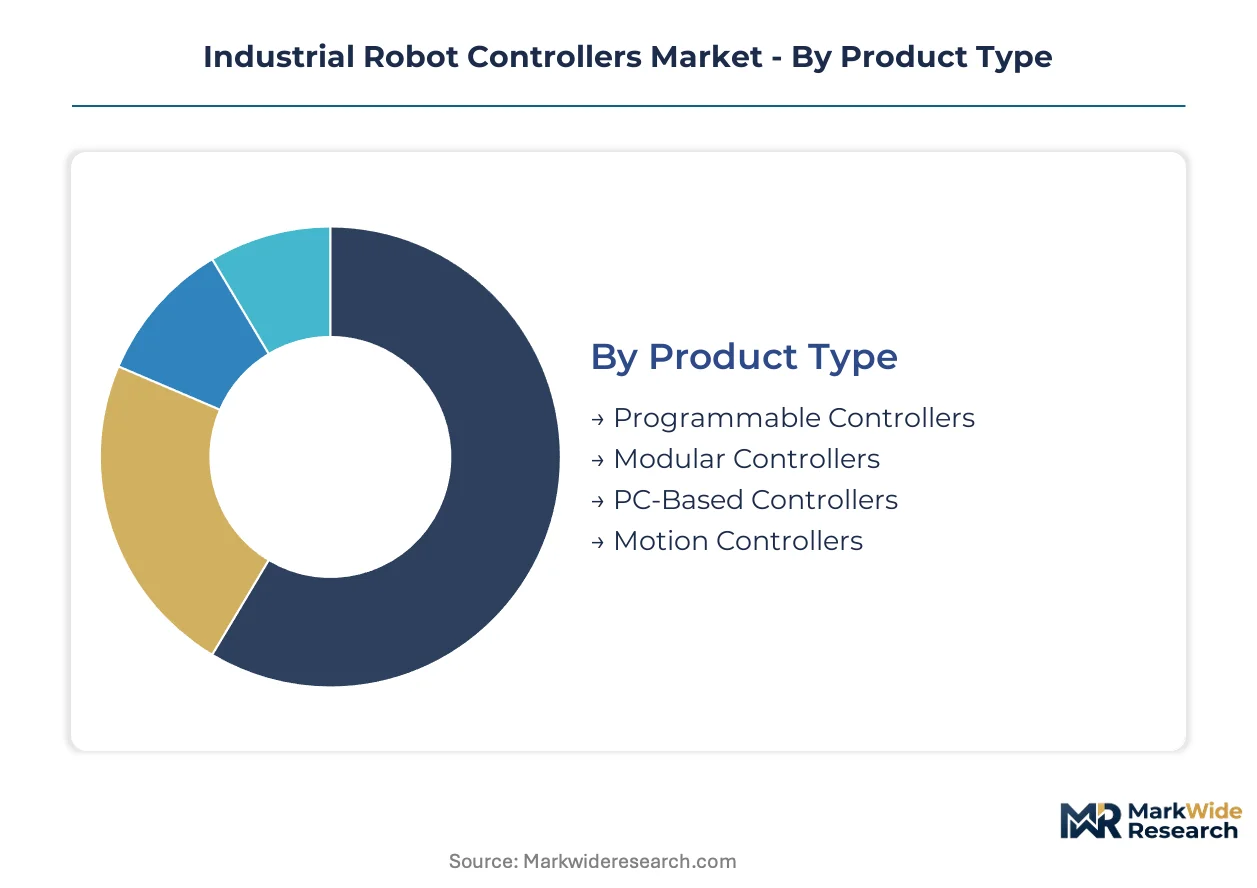
Controller architectures diverge sharply between high-volume standardized deployments and precision-engineered custom integrations. Segmentation reveals how vendor engineering resources allocate across these competing imperatives, with software-defined platforms eroding traditional hardware boundaries.
Product Type:
Programmable controllers dominate unit shipments while modular and PC-based systems capture expanding premium pools, with cost tier determining feature depth and reconfiguration flexibility.
- Programmable Controllers:Fixed-architecture systems execute stored motion sequences through proprietary firmware with deterministic cycle times below one millisecond. Automotive welding lines in Germany and Japan standardize on these units for throughput guarantees in high-volume chassis assembly operations.
- Modular Controllers:Distributed I/O architectures separate motion planning from servo execution, enabling field-replaceable safety modules and custom kinematic configurations. Aerospace manufacturers in Toulouse and Hamburg pay premium positioning for certification traceability and rapid cell reconfiguration between airframe programs.
- PC-Based Controllers:Industrial PC platforms running real-time Linux or hypervisor-based systems enable open-architecture algorithm development. Electronics assembly in Shenzhen and Seoul favors these for AI-driven path optimization in high-mix surface-mount production.
- Motion Controllers:Dedicated multi-axis synchronization units manage coordinated servo loops for gantry and SCARA configurations. Battery cell stacking operations in Chinese gigafactories deploy these for sub-millimeter repeatability in electrode positioning.
Mature deployment sits with programmable controllers in established automotive body shops. Newer deployment is concentrated in PC-based systems for adaptive manufacturing cells.
Technology:
Digital architectures have displaced analog dominance, though pneumatic and hydraulic actuation retain defensible positions in hazardous environments where electrical spark risks prohibit standard servo deployment.
- Analog Control:Continuous voltage signal processing for servo loop closure persists in legacy installations where electromagnetic interference resilience outweighs precision requirements. Foundry operations in Pittsburgh and Essen maintain these systems for molten metal handling where digital component failure modes present unacceptable thermal risks.
- Digital Control:Discrete signal processing with FPGA-based trajectory generation enables nanosecond-level synchronization across distributed axes. EV battery assembly in Ningbo and Stuttgart mandates these systems for force-controlled cell insertion and tab welding sequences.
- Pneumatic Control:Compressed air actuation with proportional valve positioning serves explosive atmospheres in chemical processing and paint finishing. Pharmaceutical packaging in Basel and Singapore deploys these for solvent-rich coating operations.
- Hydraulic Control:Fluid power systems deliver force densities exceeding electromechanical alternatives for heavy-payload forging and press tending. Aerospace titanium forming in Seattle and Toulouse requires these for 500+ kilonewton clamping forces.
Volume concentration favors digital control in precision manufacturing. Niche durability requirements sustain pneumatic and hydraulic alternatives in process industries.
End User:
Application complexity and certification burden determine customer tiering, with automotive and aerospace commanding dedicated engineering support while electronics buyers prioritize cost-optimized standard platforms.
- Manufacturing:General industrial automation spans material handling, machine tending, and quality inspection across discrete production. Tier-one suppliers in Mexico and Poland deploy standardized controller configurations for 24/7 operational continuity in contract machining operations.
- Automotive:OEM and tier-assembly operations demand cycle-time guarantees, safety-certified collaborative interfaces, and line-integration protocols. German and Japanese manufacturers specify controllers with guaranteed mean-time-between-failures exceeding 60,000 hours for body-in-white welding cells.
- Electronics:High-mix, low-volume surface-mount and test operations require rapid program changeover and vision-guided calibration. Taiwanese and South Korean contract manufacturers favor compact controllers with embedded vision processing for smartphone component assembly.
- Aerospace:Airframe and engine production mandates full certification traceability, custom kinematic configurations, and extended temperature operating ranges. Airbus and Boeing supply chains in Toulouse, Hamburg, and Charleston specify controllers with DO-178C software assurance for flight-critical adjacent operations.
Procurement sophistication peaks in aerospace with multi-year qualification cycles. Electronics procurement moves fastest with compressed vendor selection timelines.
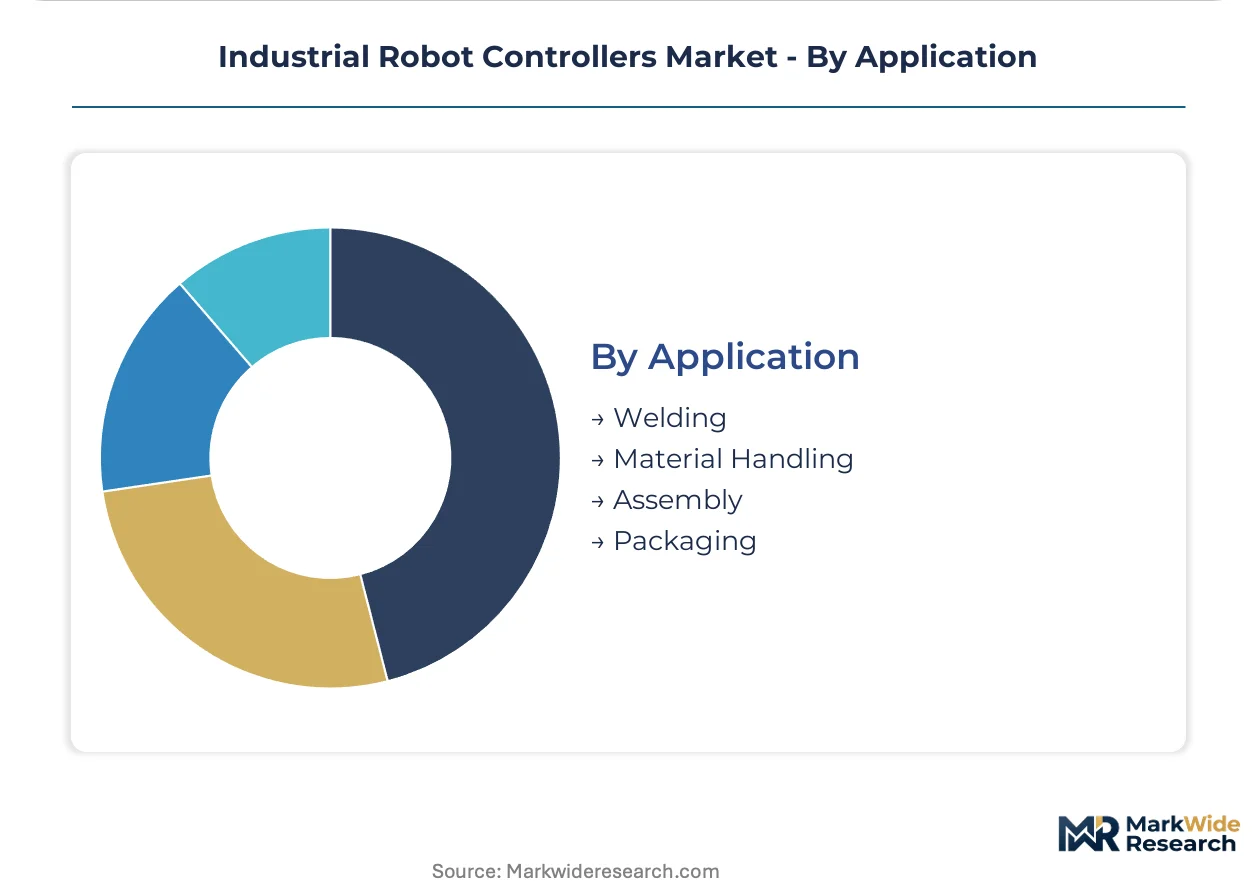
Application:
Motion complexity and environmental exposure differentiate application requirements, with welding demanding robust arc interference immunity and material handling prioritizing speed over precision.
- Welding:Arc welding controllers integrate seam tracking, weave pattern generation, and spatter compensation with electromagnetic noise rejection. Automotive plants in Wolfsburg and Toyota City specify these with integrated fume extraction interlocks and touch-sensing capabilities.
- Material Handling:Pick-and-place and palletizing operations emphasize throughput optimization and collision avoidance in constrained workspaces. E-commerce fulfillment centers in Leipzig and Rotterdam deploy these with AI-optimized path planning for mixed-SKU tote handling.
- Assembly:Precision insertion and fastening operations require force-torque sensing and compliant motion control. Medical device manufacturing in Minneapolis and Warsaw specifies these for sterile component assembly with full batch traceability.
- Packaging:High-speed carton forming, filling, and sealing demands synchronized multi-axis motion with quick format changeover. Food processing in Parma and Copenhagen deploys these with IP69K washdown ratings and allergen containment protocols.
Force-controlled assembly applications are expanding most quickly with collaborative robot integration. Material handling retains the largest installed base across logistics and manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors precision manufacturing demand for industrial robot controllers, with German automotive OEMs specifying sub-millisecond cycle time guarantees for body-in-white welding cells. Controller vendors concentrate technical support and spare parts logistics around this industrial corridor to capture replacement cycles driven by EU Machinery Directive compliance mandates.
China
Gigafactory construction in Ningbo and Shenzhen generates concentrated demand for multi-axis synchronized controllers capable of sub-millimeter positioning repeatability in battery cell stacking operations. GB standard harmonization with ISO frameworks is reducing dual-certification burdens for controllers already validated to European norms. Yangtze River Delta electronics assemblers favor PC-based open architecture systems for AI-driven path optimization in high-mix surface-mount production.
Germany
Automotive manufacturers in Wolfsburg and Munich are accelerating replacement cycles for collaborative robot deployments to meet EU Machinery Directive force-limiting and emergency-stop latency requirements. REACH substance restrictions on lead-bearing solder are forcing 12-18 month PCB requalification timelines ahead of 2026 enforcement deadlines. Bavarian automation suppliers absorb these compliance costs to defend premium positioning in aerospace line integration.
Japan
Tokyo and Nagoya industrial clusters sustain demand for programmable controllers with guaranteed mean-time-between-failures exceeding 60,000 hours in high-volume chassis assembly. METI industrial policy supports captive servo motor and drive production integration to sustain margin control across controller-robot bundles. Kansai-region electronics contract manufacturers deploy compact controllers with embedded vision processing for smartphone component assembly.
United States
FDA oversight of robotic surgical systems extends compliance burdens to controllers deployed in medical device manufacturing clusters around Minneapolis and Boston. NHTSA guidance on autonomous manufacturing transport creates additional certification requirements for mobility-adjacent controller applications. Pittsburgh foundry operations maintain analog control systems for molten metal handling where digital component failure modes present unacceptable thermal risks.
India
PLI scheme incentives for electronics and automotive component production are creating first-mover advantage for controller vendors establishing localized technical support in Maharashtra and Gujarat. Pune and Chennai precision manufacturing expansion demands adaptive control architectures for high-mix production workflows. BIS certification alignment with IEC standards is streamlining market entry for controllers validated to European safety norms.
Industrial Robot Controllers Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and line-integration capability, with tiered engineering resource allocation separating safety-certified collaborative interfaces from basic point-to-point motion systems. The vendor base concentrates around integrated hardware-software bundles and open-platform development paths, with incumbents defending proprietary fieldbus ecosystems while reallocating toward software-defined architectures. Three strategic archetypes dominate: captive component producers controlling servo supply chains, platform specialists anchoring software-defined motion planning, and automotive line integrators commanding cycle-time guarantee pricing. Competitive moves center on strategic partnerships for AI-driven path optimization and geographic expansion into India precision manufacturing corridors.
Among Japanese electrical conglomerates, Yaskawa Electric Corporation and Mitsubishi Electric Corporation exemplify the captive production archetype through in-house servo motor and drive manufacturing that sustains margin control across integrated controller-robot bundles. Within the European automation tier, ABB Ltd and KUKA AG occupy differentiated positioning—ABB anchors software-defined motion planning for collaborative cells through its OmniCore platform, while KUKA commands premium pricing power in automotive line integration where cycle-time guarantees dominate procurement criteria. FANUC Corporation represents the integrated hardware-software bundle model with proprietary controller-robot configurations standardized in German and Japanese automotive welding lines.
| Leading Market Players |
|---|
| Yaskawa Electric Corporation |
| Mitsubishi Electric Corporation |
| KUKA AG |
| ABB Ltd |
| FANUC Corporation |
| OMRON Corporation |
| DENSO Corporation |
| Stäubli International AG |
| Kawasaki Robotics |
| Others |
Value Chain & Pricing Dynamics
German automotive OEMs and Chinese battery manufacturers concentrate procurement authority for industrial robot controllers, anchoring value-based pricing models tied to production line uptime guarantees and cycle-time performance rather than hardware unit costs.
Pricing Analysis
Uptime-guarantee contracts in automotive body-in-white welding anchor value-based pricing, with German and Japanese OEMs paying premium positioning for controllers certified to ISO 10218-2 with sub-millisecond emergency-stop latency. Price differentiation separates safety-certified collaborative interfaces from basic point-to-point motion systems, with aerospace line integration commanding the highest tier. Cost compression in mid-range programmable controllers is intensifying because PC-based open architectures running real-time Linux are eroding dedicated hardware margins. Electronics contract manufacturers in Taiwan and South Korea exhibit the sharpest price sensitivity, while aerospace integrators in Toulouse and Hamburg show minimal elasticity due to multi-year qualification lock-in.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Shanghai anchor hub-and-spoke logistics patterns for spare parts and technical support, with controllers shipping from final assembly plants in Germany, Japan, and China. FPGA and high-speed ADC sourcing draws from Taiwanese foundries and Japanese semiconductor houses, while servo motor production rests on captive manufacturing in Yaskawa and Mitsubishi facilities. Single-source vulnerability in safety-critical processing modules creates scheduling risk when lead times extend beyond standard procurement windows. Distribution runs through direct vendor relationships with automotive OEMs and tier-one system integrators, bypassing traditional distributor attach-rate leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial robot controller vendors face a vertical-integration race, with captive servo motor production and safety-certified firmware development emerging as the decisive upstream levers for margin defense.
For Market Incumbents: Deepen backward integration into safety-critical semiconductor sourcing to reduce exposure to Taiwanese foundry concentration, while accelerating IEC 61508 SIL certification pipelines to defend against PC-based open architecture substitution in mid-range applications. Prioritize software-defined platform development to capture recurring revenue from algorithmic updates without hardware replacement cycles. For New Entrants and Emerging Players: India's PLI scheme for electronics and automotive component production opens a window for establishing localized technical support and spare parts logistics in Maharashtra and Gujarat before incumbent distribution networks solidify. Target high-mix electronics assembly in Pune and Chennai with PC-based controllers offering AI-driven path optimization, leveraging compressed vendor selection timelines in this segment to bypass lengthy automotive qualification barriers. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive servo supply chains and established safety certification portfolios, as these assets compound defensibility against software-defined disruption. Monitor GB standard harmonization progress in China as an inflection indicator for reduced dual-certification burdens that would streamline market entry for European-validated controllers.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Platform Development | Enables algorithmic updates without hardware replacement, compressing traditional controller lifecycles. |
| Captive Servo Motor Integration | Yaskawa and Mitsubishi sustain margin control across bundled controller-robot configurations. |
| Safety Certification Pipeline Investment | IEC 61508 SIL validation defends premium positioning against open-architecture erosion. |
| Localized Technical Support Expansion | India PLI scheme incentives create first-mover advantage in Pune and Chennai corridors. |
| AI-Driven Path Optimization Partnerships | Edge AI accelerator integration enables collision-free planning in welding cells. |
Study Parameters
Document review covered regulatory filings with FDA, ECHA, and METI, complemented by interviews with plant engineers at German automotive OEMs, procurement leads at Chinese battery manufacturers, aftermarket service heads at Japanese robotics firms, and technical R&D directors at European automation suppliers. Secondary validation drew from SEC 10-K disclosures, EU Machinery Directive implementation guidance, customs and trade data for industrial automation equipment, and production statistics from vehicle and battery manufacturing databases. Bottom-up unit shipment estimates and top-down market value triangulation anchored the analytical framework.
Historical shipment trajectories were cross-referenced against panel input from industry stakeholders to model growth across the projection horizon. Segmentation dimensions included controller architecture type, end-use vertical, application complexity, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for technology substitution effects and compliance-driven replacement cycles, with specific inputs from EtherCAT adoption rates and EV battery assembly capacity expansion.
The model assumes a particular technology adoption path; alternative pathways for software-defined control architectures would alter the outlook if open-platform development outpaces proprietary ecosystem defense. Forecasts reflect assumptions regarding regulatory harmonization timelines, semiconductor supply normalization, and real-time systems engineering talent availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robot Controller, Integrator and Software Market
Robotics and Automation
Robotic Desktop Automation (RDA) Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Household Cleaning Robotics Market
Robotics and Automation
Disinfectant Robot Market
Robotics and Automation
South Korea Cloud Robotics Market
Robotics and Automation
Japan Agricultural Robot Market
Robotics and Automation
Middle East and Africa Warehouse Robotics Market
Robotics and Automation
AGV Dispatch Management Platforms Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Marine Robots Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
Articulated Robots for Injection Molding Machine Market
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Italy Cloud Robotics Market