
 Global Enterprise Robotic Process Automation Market | 2026-2036
Global Enterprise Robotic Process Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Robotic Process Automation Market Foresight
North American software engineering capacity is recalibrating around cloud-native orchestration layers. UiPath leverages extensive partner training networks to sustain platform stickiness across mid-market accounts. Automation Anywhere competes aggressively on pricing for attended bot licenses in emerging markets. Microsoft anchors enterprise trust through native integration with Azure Active Directory and Office 365 pipelines.
Enterprise Robotic Process Automation denotes software that emulates human interactions with digital systems through scripted UI manipulations, API calls, and increasingly, AI-powered cognitive parsing of unstructured documents. Cloud deployment architectures now dominate new installations, though on-premises configurations persist in European banking and defense contexts where data sovereignty requirements block public cloud tenancy. Integrated RPA solutions that embed process mining and intelligent document processing capture disproportionate margin pools compared to standalone attended bots. Finance & accounting use cases remain the most mature segment, while compliance management applications are expanding fastest under intensifying regulatory scrutiny.
The EU AI Act classifies certain RPA-driven credit decisions as high-risk, forcing vendors to maintain audit trails and human-in-the-loop checkpoints. The US SEC has signaled closer examination of algorithmic trading workflows built on unattended automation chains. India's TRAI data localization guidelines and the RBI's cybersecurity framework for IT service providers shape how global banks architect bot governance. Stakeholders must weigh sovereign cloud requirements against the latency and cost advantages of centralized orchestration platforms.
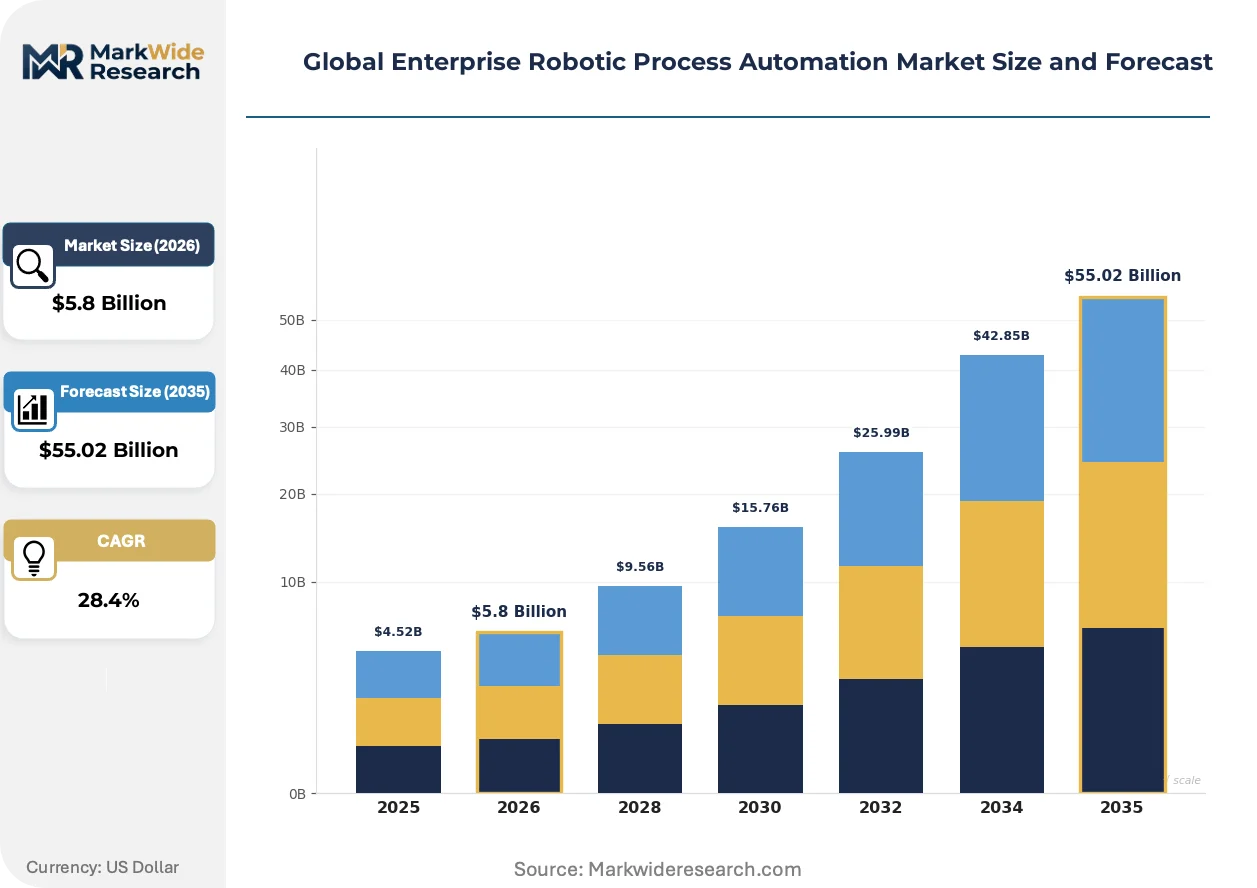
Market Dynamics
Cloud-native orchestration layers are compressing deployment cycles from months to weeks, while the EU AI Act forces vendors to rebuild audit architectures for high-risk automated decision workflows.
Growth Catalysts
- EU AI Act compliance mandates:Banking institutions in Germany and France must retrofit unattended bots with human-in-the-loop checkpoints, creating replacement demand for governance-enabled platforms.
- API-first integration patterns:Healthcare providers in the United States are replacing screen-scraping bots with headless automation chains that interface directly with EHR systems via FHIR protocols.
- Captive center buildouts:IT services firms in India are constructing dedicated automation campuses in Bangalore and Hyderabad to serve North American insurance underwriting workflows.
Market Restraints
- Data sovereignty requirements:European defense contractors and Swiss private banks maintain on-premises orchestration nodes, blocking cloud-native margin capture.
- Specialized talent scarcity:Process mining engineers and bot governance architects command compensation premiums that inflate total cost of ownership for mid-market deployments.
- Screen-scraping fragility:Legacy attended bots break when target applications release UI updates, forcing maintenance cycles that erode unattended automation economics.
Strategic Opportunities
- Intelligent document processing convergence:Vendors bundling IDP with RPA capture margin pools in US mortgage processing and Japanese trade finance documentation.
- PLI scheme tailwinds:India's production-linked incentive framework for IT hardware is attracting automation software firms to establish local development centers.
- Compliance-as-a-service models:Regulated industries in Singapore and the UAE are procuring bot governance layers as managed services rather than licensed software.
Industry Challenges
- Legacy system integration friction:Mainframe-dependent banks in Italy and core banking systems in Brazil require custom connector development that extends implementation timelines.
- Bot credential management complexity:Cybersecurity teams struggle to rotate service account passwords across hundreds of unattended automations without breaking dependent workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Robotic Process Automation Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $55.02 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Hosted Solution/Offering: Standalone RPA, Integrated RPA, Cognitive Automation, Intelligent Document Processing, Process Mining Use Case: Finance & Accounting, Customer Service, Supply Chain Management, Human Resources, IT Operations, Compliance Management Industry Vertical: Banking, Insurance, Telecommunications, Manufacturing, Government, Education |
| Companies Covered | UiPath, Automation Anywhere, SS&C Blue Prism, Pegasystems, IBM Corporation, NICE, Kofax, Microsoft, Appian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Robotic Process Automation Market Shifts & Advancements
Process mining engines are embedding directly into orchestration platforms, collapsing the discovery-to-deployment pipeline and eliminating standalone vendor relationships.
Agentic AI architectures that chain multiple specialized models through reasoning loops are expanding into compliance management and exception handling workflows. Financial services firms in London and New York are piloting these systems for anti-money laundering alert triage, compressing analyst review queues by enabling autonomous investigation paths subject to audit logging.
The EU AI Act's high-risk system classification is forcing RPA vendors to maintain technical documentation and conformity assessments for credit decisioning bots. German automotive lenders and Dutch mortgage providers must now demonstrate human oversight mechanisms before deploying unattended workflows, shifting competitive advantage toward platforms with native governance tooling.
Buyers are unbundling implementation services from software licenses and contracting directly with systems integrators for bot development. This pattern is most visible in Australia's banking sector and Canada's insurance vertical, where procurement teams separate platform selection from delivery partner appointments to drive down total contract values.
Global Enterprise Robotic Process Automation Market Segmentation
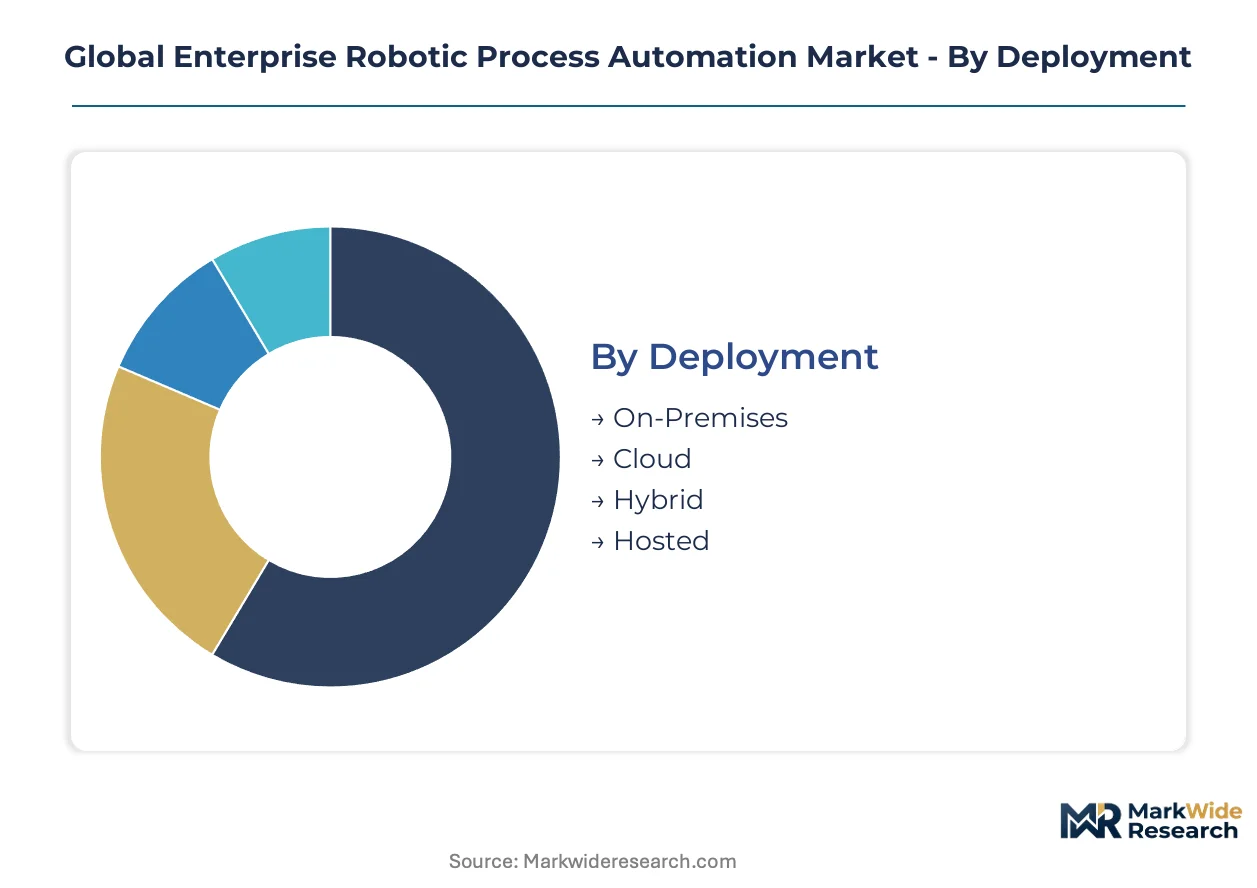
Deployment architecture determines governance complexity and total cost of ownership for enterprise automation programs. Solution bundling strategies separate margin-capturing integrated platforms from commoditized standalone licenses. Use case maturity and industry regulatory intensity shape vendor selection criteria across procurement cycles.
Deployment:
Cloud-native orchestration layers compress provisioning timelines while sovereign data requirements sustain on-premises alternatives in regulated sectors.
- On-Premises:Infrastructure resides within client-controlled data centers with dedicated orchestration nodes. Swiss private banks and Italian defense contractors maintain these configurations to satisfy data sovereignty mandates that block public cloud tenancy.
- Cloud:Multi-tenant SaaS platforms deliver elastic bot capacity with centralized governance dashboards. Healthcare providers in the United States are migrating here to leverage FHIR-native EHR integrations without infrastructure overhead.
- Hybrid:Sensitive workloads run on-premises while scalable processing bursts to cloud nodes. German automotive lenders deploy this architecture to keep credit decisioning data local while outsourcing document parsing.
- Hosted:Single-tenant dedicated instances managed by vendors in regional facilities. UAE government entities procure these to satisfy data localization without operating their own data centers.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud.
Solution/Offering:
Standalone tools face margin compression as buyers demand bundled intelligence layers.
- Integrated RPA:Platforms embed process mining, IDP, and governance tooling within unified orchestration layers. North American insurance carriers are consolidating vendor relationships here to eliminate integration tax.
- Intelligent Document Processing:Cognitive extraction engines parse unstructured trade finance documentation and mortgage packets. Japanese banks and US mortgage servicers are expanding procurement of these capabilities.
- Standalone RPA:Screen-scraping and API-based automation without adjacent intelligence modules. Attended bot licenses in emerging markets compete primarily on price.
- Cognitive Automation:AI-powered decisioning for exception handling and pattern recognition. AML alert triage in London and New York represents early adoption.
- Process Mining:Discovery engines that map actual process flows before automation deployment. These are embedding directly into orchestration platforms, collapsing standalone vendor relationships.
Margin capture concentrates in Integrated RPA. Fastest capability expansion is occurring in Intelligent Document Processing.
Use Case:
Finance operations deliver proven ROI while compliance applications face steepest regulatory tailwinds.
- Finance & Accounting:Invoice processing, reconciliation, and period-end close automation. This remains the most mature segment with established playbook libraries and trained implementer pools.
- Compliance Management:Regulatory reporting, audit trail maintenance, and risk monitoring workflows. EU AI Act mandates for human-in-the-loop checkpoints are forcing platform replacements across German and French banking.
- Customer Service:Ticket routing, data retrieval, and response drafting in contact centers. Attended bots here augment rather than replace human agents.
- IT Operations:Password resets, provisioning, and incident response automation. These deployments face credential rotation complexity that strains cybersecurity teams.
- Human Resources:Onboarding, payroll verification, and benefits administration. Mid-market adoption lags due to process variability across organizations.
- Supply Chain Management:Order processing, inventory updates, and vendor communication. Fragile screen-scraping bots here break when supplier portals update.
Proven returns sit with Finance & Accounting. Steepest expansion trajectory belongs to Compliance Management.
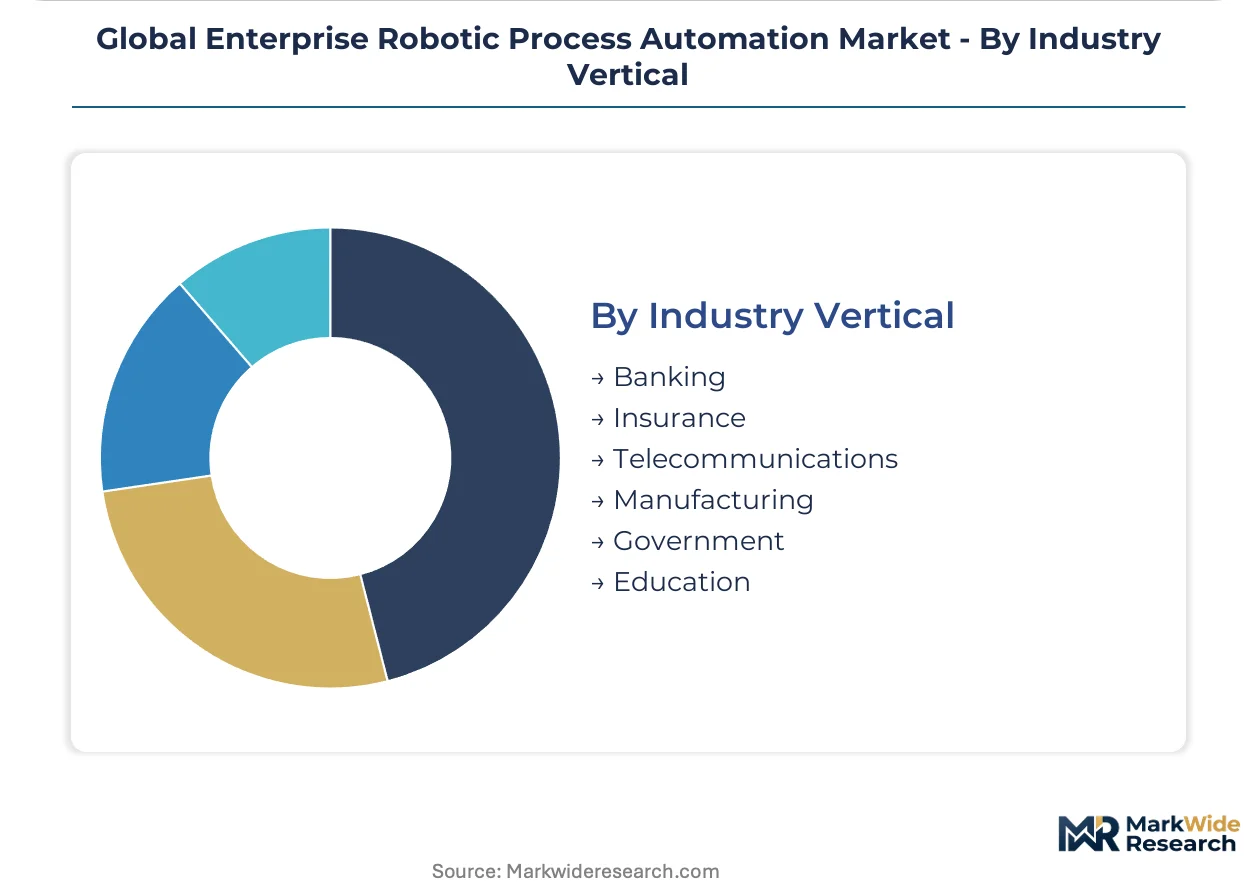
Industry Vertical:
Banking and insurance carry automation spending density while government verticals face procurement friction.
- Banking:AML workflows, loan processing, and regulatory reporting dominate bot portfolios. US institutions are expanding deployments while retrofitting for SEC algorithmic trading scrutiny.
- Insurance:Claims processing, underwriting support, and policy administration drive demand. Australian carriers and Canadian insurers are unbundling implementation from platform licenses.
- Telecommunications:Customer provisioning, billing reconciliation, and network operations. These firms operate at scale that justifies dedicated automation centers.
- Manufacturing:Purchase order management and supplier communication. ERP integration complexity slows deployment relative to service industries.
- Government:Citizen service delivery and internal administrative workflows. Procurement cycles extend timelines versus private sector.
- Education:Student onboarding and financial aid processing. Budget constraints limit deployment to attended bot models.
Deployment maturity sits with Banking. Emerging procurement volume is concentrating in Insurance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent pools in Bangalore and Hyderabad anchor automation delivery capacity for North American and European banking clients. Cloud infrastructure investments in Frankfurt and Singapore shape data residency architectures for regulated workloads.
United States
Banking institutions in New York and Charlotte are expanding bot deployments for anti-money laundering workflows. The SEC is examining algorithmic trading automation chains more closely. Healthcare providers in Boston are migrating to FHIR-native EHR integrations that eliminate screen-scraping fragility.
Germany
Automotive lenders in Munich and Stuttgart must retrofit unattended bots with human-in-the-loop checkpoints under EU AI Act high-risk system classifications. The BaFin is enforcing audit trail requirements for credit decisioning workflows. Process mining engineers command compensation premiums in the Frankfurt Rhine-Main cluster.
India
IT services firms in Bangalore and Hyderabad are constructing dedicated automation campuses to serve North American insurance underwriting workflows. The RBI's cybersecurity framework for IT service providers shapes bot governance architecture. The PLI scheme for IT hardware is attracting automation software firms to establish local development centers.
United Kingdom
Financial services firms in London are piloting agentic AI architectures for AML alert triage. The FCA is scrutinizing automated decision systems in retail banking. Lloyd's of London syndicates are unbundling implementation services from platform licenses to drive down total contract values.
Switzerland
Private banks in Zurich and Geneva maintain on-premises orchestration nodes to satisfy data sovereignty mandates that block public cloud tenancy. Swissmedic-aligned documentation requirements influence validation protocols for life sciences automation. The Zug crypto valley cluster is emerging as a testbed for blockchain-anchored bot audit trails.
Global Enterprise Robotic Process Automation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent intelligent document processing and agentic AI capabilities. The vendor base stratifies across platform orchestration specialists, legacy enterprise software incumbents, and cloud-native challengers. Three archetypes dominate: full-stack integrated platforms, API-first automation engines, and governance-layer specialists. Competitive moves center on bundling adjacent intelligence modules and unbundling implementation services to capture margin pools.
Among platform-native specialists, UiPath and Automation Anywhere occupy positions as archetypal orchestration-layer providers, while Microsoft anchors enterprise trust through native Azure integration. These three exemplify distinct competitive vectors: extensive partner training networks, aggressive attended-bot pricing in emerging markets, and cloud-identity pipeline embedding respectively.
| Leading Market Players |
|---|
| UiPath |
| Automation Anywhere |
| SS&C Blue Prism |
| Pegasystems |
| IBM Corporation |
| NICE |
| Kofax |
| Microsoft |
| Appian |
| Others |
Supply & Pricing Matrix
The EU AI Act's high-risk system classification gates qualified supply for banking-grade automation platforms, restricting premium-tier pricing access to vendors with native audit-trail architectures and human-in-the-loop tooling. Compliance infrastructure investments compress margins for mid-market entrants while concentrating pricing power among governance-certified incumbents serving German automotive lenders and Dutch mortgage providers.
Pricing Analysis
Warranty and implementation service bundling separates premium integrated platforms from unbundled attended-bot licenses in emerging markets. Pricing stratifies across enterprise governance tiers, standard SaaS subscriptions, and economy attended-bot licenses, with differentiation driven by EU AI Act certification status and embedded process mining depth. Cost compression in standalone screen-scraping tiers intensifies as UiPath and Automation Anywhere compete aggressively on per-seat pricing. Mid-market procurement teams in Australian banking and Canadian insurance demonstrate highest price sensitivity, unbundling implementation services to drive down total contract values.
Supply Chain Analysis
Process mining engineer scarcity in Bangalore and Hyderabad constrains delivery capacity for North American insurance underwriting workflows. Software engineering talent concentrates in India, Poland, and Romania, while cloud infrastructure provisioning rests on hyperscaler data center investments in Frankfurt, Singapore, and Virginia. Single-source vulnerability in specialized bot governance architect pools extends implementation timelines for German automotive lenders. Distribution runs through direct vendor sales for enterprise accounts and systems integrator partnerships for mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's conformity assessment requirements erect a cost-of-compliance moat that favors incumbent platforms with pre-built audit architectures, forcing subscale competitors into expensive retrofit cycles or market exit.
For Market Incumbents: Deepen vertical integration into intelligent document processing engines to capture margin pools in US mortgage processing and Japanese trade finance documentation. Fortify partner training networks against emerging API-first automation challengers by embedding process mining directly into orchestration layers, eliminating standalone vendor relationships.
For New Entrants and Emerging Players: The pricing gap between premium governance-certified platforms and economy attended-bot licenses opens white-space in compliance-as-a-service models for Singapore and UAE regulated industries. Target mid-market healthcare providers in the United States migrating from screen-scraping fragility to FHIR-native EHR integrations. Lead with managed bot governance offerings rather than licensed software to bypass incumbent channel control.
For Investors and Strategic Acquirers: BaFin enforcement actions against German automotive lenders lacking human-in-the-loop checkpoints are the leading indicator that governance-layer specialists face accelerated consolidation pressure. Five-to-ten year viability favors platforms with embedded process mining and IDP convergence. Target acquisition archetypes include agentic AI architecture pilots in London AML workflows. Watch for SEC algorithmic trading scrutiny expanding to unattended automation chains as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding process mining into orchestration layers collapses standalone vendor relationships at North American insurance carriers. |
| Acquisition of Specialist Firm | IDP engine purchases capture margin pools in US mortgage processing and Japanese trade finance documentation. |
| Geographic Expansion | Captive center buildouts in Bangalore and Hyderabad anchor delivery capacity for North American underwriting workflows. |
| Strategic Partnership | Systems integrator alliances bypass direct procurement friction in Australian banking and Canadian insurance unbundling trends. |
| Product Launch | Agentic AI architectures for AML alert triage compress analyst review queues at London and New York financial services firms. |
Research Methodology
Document review covered SEC filings, EU regulatory submissions, and hyperscaler capex disclosures, complemented by interviews with RPA platform executives, enterprise IT procurement officers, bot governance architects, and systems integrator delivery leads. Secondary validation drew from trade data, RBI cybersecurity framework circulars, and PLI scheme documentation. Bottom-up deployment sizing and top-down vendor revenue triangulation anchored market estimates.
Cross-referencing historical adoption curves against panel input from automation center heads shaped the analytical framework across deployment models, solution bundling tiers, use case maturity levels, and regional regulatory clusters. CAGRs derived from segment-level growth rate reconciliation. Forecast inputs incorporated EU AI Act implementation timelines and FHIR protocol migration patterns in US healthcare.
Inputs from BaFin enforcement records and SEC examination priorities were available through the study window; gaps in private bot deployment counts at Swiss private banks and Italian defense contractors introduce uncertainty bands around on-premises market sizing. Forecasts reflect documented assumptions about regulatory rollout sequencing and cloud migration velocity. Material deviation in EU AI Act enforcement intensity or RBI data localization rulings warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Security Robots Market
Robotics and Automation
Japan Articulated Robot Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
Waste Sorting Robots Market
Robotics and Automation
AI Powered Robot Market
Robotics and Automation
Europe Cloud Robotics Market
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Medical Robotics Market
Robotics and Automation
Global Delivery Robots Market
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
Medical Rehabilitation Robotics Market
Robotics and Automation
Humanoids Market
Robotics and Automation
Disinfectant Robot Market