
 Pharmaceutical Collaborative Robots Market | 2026-2036
Pharmaceutical Collaborative Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Collaborative Robots Market Analytics
Aftermarket service revenue is tilting from hardware replacement toward predictive maintenance software and remote diagnostics platforms. Universal Robots leverages its open-architecture software ecosystem to capture recurring platform licensing income across pharmaceutical installations. ABB sustains competitive positioning through deep integration with its own SCARA and delta robot portfolios for hybrid automation cells. Fanuc dominates high-reliability cleanroom-certified installations where ISO 14644 compliance anchors long-term service contracts.
Pharmaceutical collaborative robots are force-limited articulated manipulators designed for direct human interaction without protective guarding, typically operating at speeds below 1.5 m/s with payload capacities from 3 kg to 20 kg for aseptic processing, precision dispensing, and quality inspection tasks. Cobots lead the product type landscape due to their plug-and-play deployment in validated environments, while mobile robots represent the fastest-growing category as autonomous material transport displaces fixed conveyor infrastructure in multi-suite facilities. Manufacturing automation commands the largest application share, though laboratory automation segments attract premium pricing for AI-powered liquid handling and high-throughput screening workflows.
FDA's 21 CFR Part 11 electronic records requirements and EU MDR device traceability mandates compel pharmaceutical manufacturers to select cobots with embedded audit trail capabilities and encrypted data logging. Japan's PMDA enforces GMP Annex 15 qualification standards that directly influence robot vendor selection for export-oriented drug production. Switzerland's Swissmedic coordinates with ISO 13485 quality frameworks to harmonize validation protocols across cross-border supply chains. Stakeholders must weigh regulatory divergence against platform standardization when consolidating multi-site cobot fleets.
Market Dynamics
Contract manufacturing organizations are consolidating cobot deployments to meet FDA validation requirements while KBA-equivalent machinery safety standards in Germany and PMDA GMP guidelines in Japan tighten human-robot collaboration protocols across sterile filling and packaging lines.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates compel pharmaceutical manufacturers to select cobots with embedded audit trail capabilities and encrypted data logging for validated environments.
- Aseptic processing automation:Force-limited articulated manipulators enable direct human interaction without protective guarding, accelerating deployment in sterile filling operations.
- Basel manufacturing corridor:Roche and Novartis suppliers in Switzerland concentrate demand for cleanroom-certified installations with ISO 14644 compliance.
Market Restraints
- Cleanroom certification costs:ISO 14644 compliance anchors long-term service contracts but creates substantial upfront capital barriers for mid-tier manufacturers.
- Regulatory divergence:EU MDR device traceability mandates conflict with Japan's PMDA GMP Annex 15 qualification standards, complicating multi-site fleet consolidation.
- Technical speed limitations:Cobots operating below 1.5 m/s cannot match throughput of traditional industrial robots in high-volume packaging applications.
Strategic Opportunities
- Mobile robot category:Autonomous material transport displaces fixed conveyor infrastructure in multi-suite facilities, representing the fastest-growing product segment.
- AI-powered laboratory workflows:Premium pricing for liquid handling and high-throughput screening creates margin expansion in pharmaceutical R&D automation.
- Predictive maintenance platforms:Aftermarket revenue tilts from hardware replacement toward remote diagnostics software and recurring licensing income.
Industry Challenges
- Validation engineering talent:Scarcity of professionals capable of executing IQ/OQ/PQ protocols for collaborative robot installations delays deployment timelines.
- Legacy system integration:Hybrid automation cells combining cobots with existing SCARA and delta robot portfolios require complex control architecture reconfiguration.
- Cross-border qualification:Swissmedic coordination with ISO 13485 frameworks demands redundant documentation for Basel-region suppliers serving multiple regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Collaborative Robots Market |
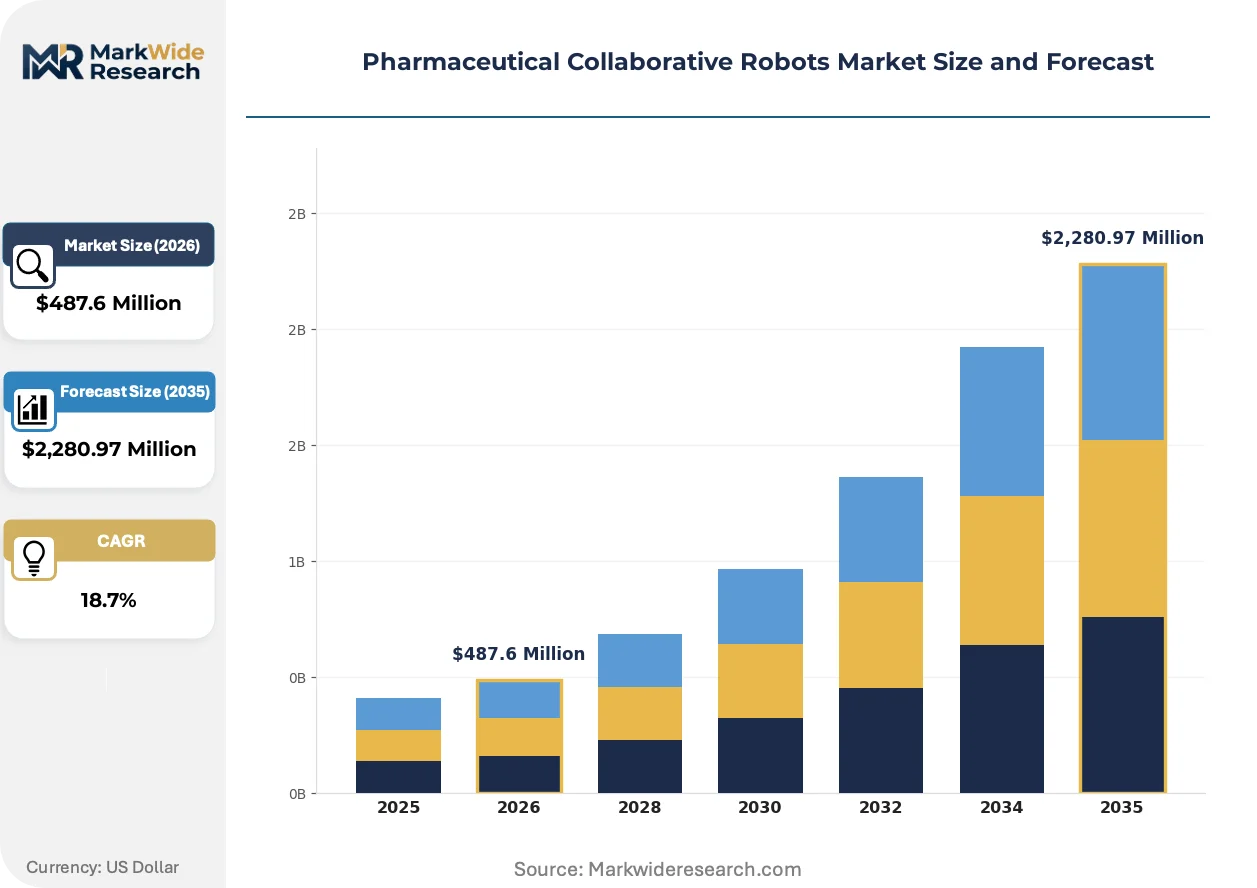
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,280.97 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, Cobots, Mobile Robots, Vision Robots Application: Drug Discovery, Manufacturing Automation, Laboratory Automation, Clinical Trials End User: Pharmaceutical Companies, Research Laboratories, Contract Manufacturing Organizations, Hospitals Technology: AI-Powered, Sensor-Based, Software-Integrated, Machine Learning |
| Companies Covered | Yaskawa, Mitsubishi Electric, Universal Robots, Omron, Denso Robotics, ABB, KUKA, Staubli, Fanuc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Collaborative Robots Market Evolving Landscape
Open-architecture software ecosystems are reshaping competitive positioning as vendors capture recurring platform licensing income and predictive maintenance revenue displaces traditional hardware replacement cycles.
Force-torque sensing with adaptive impedance control is collapsing the boundary between human-occupied and robot-only zones in cleanroom environments. Contract manufacturers in Switzerland's pharmaceutical corridor are adopting these systems at accelerated pace to eliminate fixed guarding infrastructure. This convergence is collapsing facility layout constraints and enabling reconfigurable production lines that shift between small-batch personalized medicine and high-volume generics within single shifts.
EU MDR device traceability mandates now require serialized component tracking across automated production equipment. The regulation compels cobot vendors to embed cryptographic data logging and tamper-evident audit trails at the controller level. High-reliability cleanroom installations face the steepest compliance burden, with Swissmedic-validated facilities in Basel restructuring supplier qualification protocols to accommodate these requirements.
Service unbundling is fragmenting traditional robot procurement as pharmaceutical manufacturers separate hardware acquisition from software licensing and predictive maintenance subscriptions. End-users in Japan's export-oriented drug production sector increasingly source validation engineering and remote diagnostics from specialized third-party integrators rather than OEM service organizations. This pattern concentrates most visibly among PMDA-regulated facilities seeking to compress total cost of ownership across ten-year equipment lifecycles.
Pharmaceutical Collaborative Robots Market Segmentation
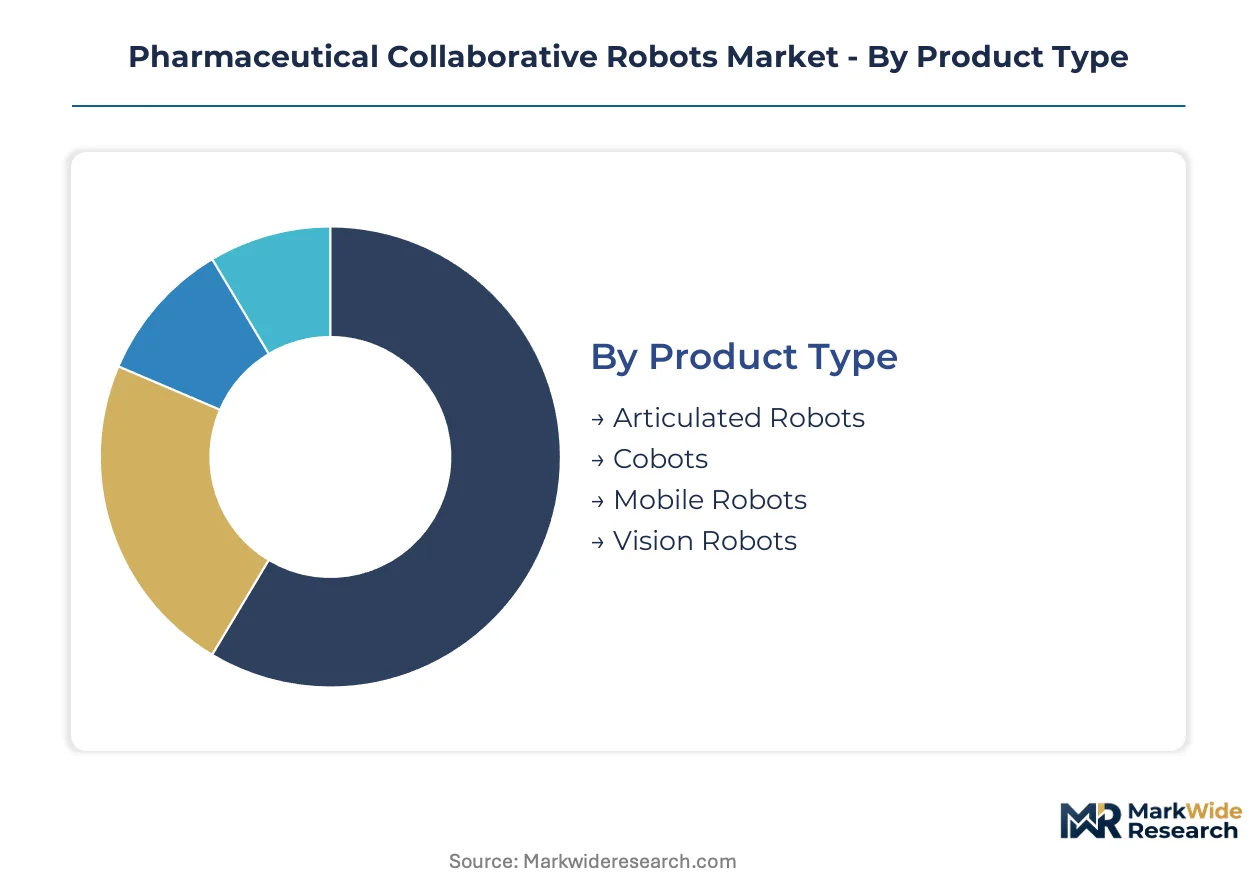
Pharmaceutical collaborative robots segment across four critical dimensions that determine validation pathways, procurement budgets, and deployment complexity. Each category reflects distinct technical requirements and regulatory constraints that shape vendor selection and integration architecture.
Product Type:
The use-case spectrum spans fixed-mount precision manipulation to autonomous material transport across multi-suite facilities.
- Cobots:Force-limited articulated manipulators operate below 1.5 m/s with payload capacities from 3 kg to 20 kg, enabling direct human interaction without protective guarding in aseptic processing environments. FDA 21 CFR Part 11 compliance requirements concentrate demand among contract manufacturing organizations scaling sterile filling lines.
- Mobile Robots:Autonomous transport systems displace fixed conveyor infrastructure in multi-suite facilities, with demand accelerating in Switzerland's Basel manufacturing corridor where Roche and Novartis suppliers operate reconfigurable production lines. ISO 14644 cleanroom certification anchors long-term service contracts for these installations.
- Articulated Robots:Traditional six-axis configurations handle heavier payloads in packaging applications where speed exceeds collaborative safety thresholds.
- Vision Robots:Camera-integrated systems perform quality inspection and traceability verification under EU MDR device serialization mandates.
The dominant share belongs to Cobots, while Mobile Robots is closing the gap fastest.
Application:
Cost tier differentiation separates high-volume manufacturing from premium-priced R&D automation workflows.
- Manufacturing Automation:Sterile filling, packaging, and aseptic processing command the largest revenue concentration due to scale deployment across validated production lines. KBA-equivalent machinery safety standards in Germany and PMDA GMP guidelines in Japan tighten human-robot collaboration protocols for these installations.
- Laboratory Automation:AI-powered liquid handling and high-throughput screening workflows attract premium pricing from pharmaceutical R&D budgets. Demand concentrates in research clusters requiring ISO 13485 quality framework coordination across Swissmedic-validated facilities.
- Drug Discovery:Early-stage compound screening and target identification utilize adaptive impedance control for flexible protocol execution.
- Clinical Trials:Sample processing and biomarker analysis require embedded audit trail capabilities for regulatory submission documentation.
Manufacturing Automation retains the largest footprint, though Laboratory Automation commands the steepest margin expansion.
End User:
Customer type determines procurement authority, validation expertise depth, and equipment lifecycle expectations.
- Contract Manufacturing Organizations:Scalable cobot deployments across sterile filling and packaging lines dominate procurement volume as CMOs consolidate multi-site fleets to meet FDA validation requirements. Predictive maintenance software subscriptions increasingly unbundle from hardware acquisition in this segment.
- Pharmaceutical Companies:In-house production facilities prioritize deep integration with existing SCARA and delta robot portfolios for hybrid automation cells.
- Research Laboratories:Academic and institutional settings emphasize open-architecture software ecosystems for protocol flexibility.
- Hospitals:Clinical pharmacy and compounding applications require compact footprints for space-constrained installations.
Contract Manufacturing Organizations drive the majority of current installations, while Pharmaceutical Companies are deepening vertical integration fastest.
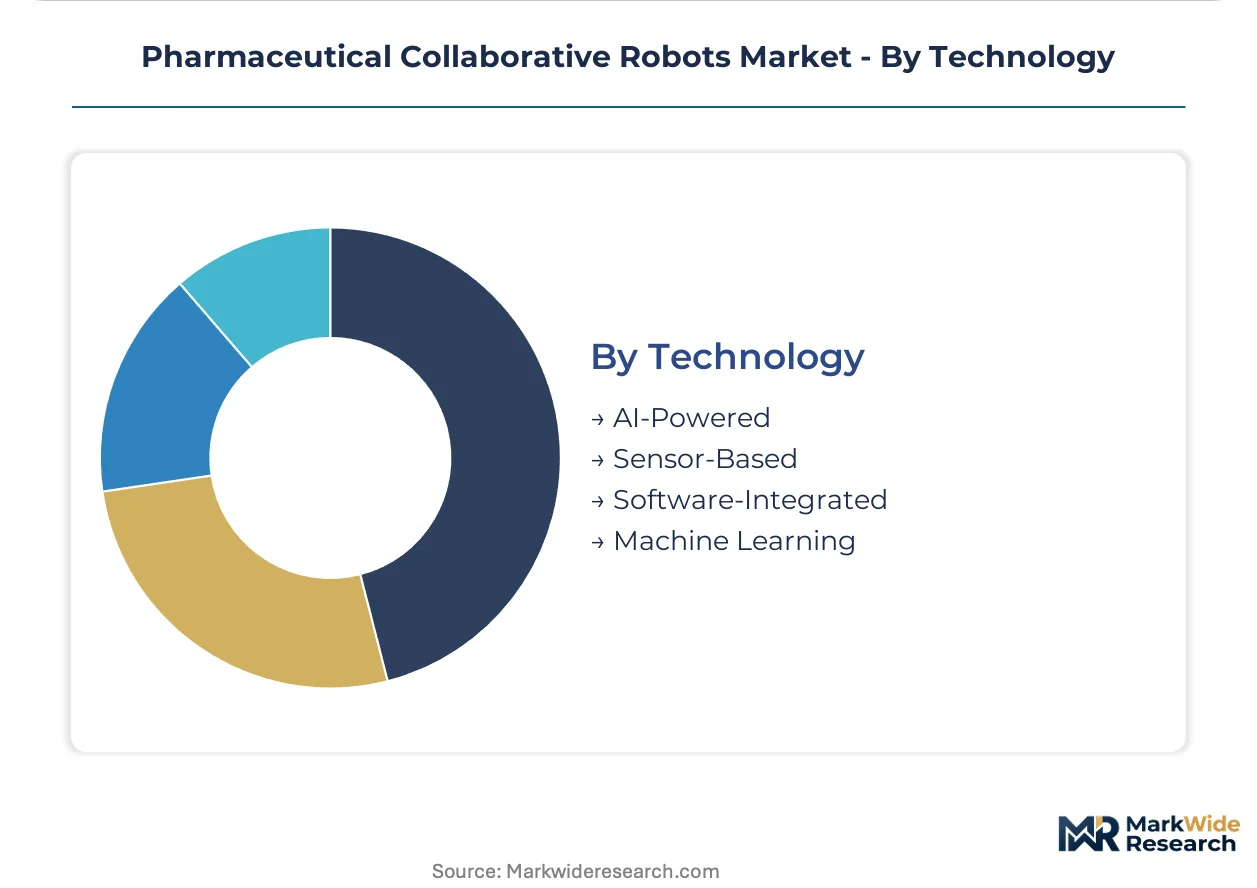
Technology:
Maturity gradients separate established sensor architectures from emerging AI-native control systems.
- AI-Powered:Machine vision and adaptive control algorithms enable real-time process optimization in high-throughput screening workflows. Japan's PMDA export-oriented drug production sector sources these capabilities through specialized third-party integrators rather than OEM service organizations.
- Sensor-Based:Force-torque sensing with adaptive impedance control collapses boundaries between human-occupied and robot-only zones in cleanroom environments, eliminating fixed guarding infrastructure in Basel-region facilities.
- Software-Integrated:Open-architecture platforms capture recurring licensing income through embedded audit trails and encrypted data logging.
- Machine Learning:Predictive maintenance models shift aftermarket revenue from hardware replacement toward remote diagnostics platforms.
Sensor-Based systems anchor current deployment, yet AI-Powered configurations are scaling most aggressively in R&D environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Switzerland's pharmaceutical manufacturing corridor around Basel, where Roche and Novartis suppliers anchor cleanroom-certified cobot demand. FDA validation requirements and Japan's PMDA GMP guidelines are reshaping deployment patterns across export-oriented drug production hubs.
United States
FDA 21 CFR Part 11 mandates drive cobot selection with embedded audit trails and encrypted data logging. The regulation compels contract manufacturing organizations to prioritize validated installations. The Greater Boston biotech cluster sees accelerated sterile filling automation as CMOs consolidate multi-site fleets.
Germany
KBA-equivalent machinery safety standards tighten human-robot collaboration protocols across pharmaceutical packaging lines. The country's industrial automation heritage supports hybrid cell integration with existing SCARA and delta robot portfolios. Baden-Württemberg's precision engineering suppliers serve export-oriented drug manufacturers.
Switzerland
Swissmedic coordinates ISO 13485 quality frameworks to harmonize validation protocols across cross-border supply chains. The Basel manufacturing corridor concentrates demand for ISO 14644 cleanroom-certified installations. Local suppliers face redundant documentation requirements when serving multiple regulatory jurisdictions.
Japan
PMDA enforces GMP Annex 15 qualification standards that directly influence robot vendor selection for export-oriented drug production. METI industrial policy supports AI-powered control systems in pharmaceutical R&D environments. The Kansai pharmaceutical cluster adopts adaptive impedance control for flexible protocol execution.
India
CDSCO regulatory alignment with international GMP standards accelerates cobot deployment in contract manufacturing facilities. The country's cost-competitive production base attracts sterile filling automation investments. Maharashtra's pharmaceutical manufacturing belt sees predictive maintenance software subscriptions unbundle from hardware acquisition.
Pharmaceutical Collaborative Robots Market Competitive Landscape
European precision-engineering specialists and Japanese industrial automation conglomerates split the market between cleanroom-certified installations and open-architecture software ecosystems. The vendor base organizes around three strategic archetypes: force-limited cobot pure-plays, diversified robotics conglomerates with pharmaceutical-certified portfolios, and specialized cleanroom integrators. Dominant competitive moves include predictive maintenance platform development and validation engineering service bundling.
Among diversified industrial automation groups, ABB, Fanuc, and KUKA exemplify scale-driven positioning across hybrid automation cells. ABB represents the archetype of deep portfolio integration spanning cobots, SCARA, and delta configurations. Fanuc anchors the high-reliability cleanroom installation segment where long-term service contracts follow ISO 14644 certification. KUKA occupies a position within the pharmaceutical-certified articulated robot tier serving packaging applications beyond collaborative speed thresholds.
| Leading Market Players |
|---|
| Yaskawa |
| Mitsubishi Electric |
| Universal Robots |
| Omron |
| Denso Robotics |
| ABB |
| KUKA |
| Staubli |
| Fanuc |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's cost dynamics compress margins for component suppliers concentrated in Germany's precision engineering belt while amplifying price differentiation between ISO 14644-certified cleanroom installations and standard pharmaceutical automation systems. This logistics chokepoint forces Basel-region contract manufacturers to absorb premium freight costs or shift sourcing toward Swissmedic-validated local suppliers, tightening the feedback loop between supply concentration and downstream pricing power.
Pricing Analysis
Predictive maintenance software subscriptions and remote diagnostics platforms now generate the majority of lifetime customer value, displacing traditional hardware replacement cycles as the profit center. Three-tier pricing structure across premium cleanroom-certified, standard validated, and economy non-certified levels separates Fanuc's high-reliability installations from Universal Robots' open-architecture deployments. Pricing pressure stems from mid-tier contract manufacturing organizations demanding unbundled service contracts to compress total cost of ownership. Small-batch personalized medicine producers exhibit highest price sensitivity, while Roche and Novartis suppliers in Switzerland's Basel corridor accept premium positioning for regulatory certainty.
Supply Chain Analysis
Export-control restrictions on force-torque sensors and adaptive impedance control modules limit technology flows from Japanese METI-regulated suppliers to European pharmaceutical automation integrators. Component sourcing concentrates in Germany for precision gearboxes, Japan for servo motors and motion controllers, and Switzerland for cleanroom-certified controller assemblies. Raw material dependencies include rare-earth magnets for motor assemblies, high-purity aluminum for lightweight arm construction, and specialized cable harnesses for EMI shielding. Single-source vulnerability around Japanese force-sensing technology creates supply chain risk given PMDA GMP Annex 15 qualification requirements. Distribution runs through authorized system integrators rather than direct OEM sales for validated pharmaceutical environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates prohibitive switching costs for validated pharmaceutical installations. FDA 21 CFR Part 11 and EU MDR device traceability mandates lock end-users into multi-year service relationships with incumbent vendors.
For Market Incumbents: Pre-empt emerging AI-native control system threats by embedding machine learning capabilities directly into existing sensor-based architectures rather than relying on third-party software layers. Deepen backward integration into force-torque sensor production to reduce exposure to Japanese supply constraints. Expand validation engineering service capacity in Switzerland's Basel corridor to capture redundant documentation demand from cross-border suppliers. For New Entrants and Emerging Players: Mid-market contract manufacturing organizations in India's Maharashtra pharmaceutical belt represent the most penetrable entry point, as CDSCO regulatory alignment with international GMP standards lowers qualification barriers relative to FDA or PMDA jurisdictions. AI-powered laboratory automation for high-throughput screening workflows offers premium pricing headroom with less entrenched incumbent presence. Target specialized third-party integrator partnerships rather than direct OEM channel competition to bypass established service relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial automation conglomerates seeking to divest non-core pharmaceutical-certified robot portfolios amid broader portfolio restructuring. Long-term viability hinges on recurring software licensing income displacing hardware transaction revenue across ten-year equipment lifecycles. Watch for PMDA harmonization with EU MDR traceability standards as the inflection signal for accelerated fleet consolidation among export-oriented Japanese drug manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Audit Trail Development | FDA 21 CFR Part 11 compliance anchors vendor selection for contract manufacturing organizations scaling sterile filling lines. |
| Predictive Maintenance Platform Launch | Remote diagnostics subscriptions capture recurring revenue from Basel-region Roche and Novartis supplier installations. |
| Cleanroom Certification Investment | ISO 14644 compliance creates service contract lock-in for high-reliability pharmaceutical automation deployments. |
| Open-Architecture Ecosystem Expansion | Software licensing income scales across multi-site cobot fleets without proportional hardware manufacturing cost. |
| Validation Engineering Service Buildout | IQ/OQ/PQ protocol execution scarcity delays competitor deployment timelines and extends incumbent customer tenure. |
Research Methodology
Operator-level perspectives from validation engineering directors, sterile filling line managers, pharmaceutical procurement leads, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation across FDA 510(k) filings, PMDA GMP inspection reports, Swissmedic device registration databases, and ISO 13485 certification records. Bottom-up installation tracking across Switzerland's Basel manufacturing corridor, Germany's Baden-Württemberg precision engineering cluster, and Japan's Kansai pharmaceutical belt triangulated against top-down vendor revenue segmentation.
Scenario-bracketing around regulatory harmonization timelines and AI control system adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application workflow, end-user procurement authority, and technology maturity tier alongside regional regulatory cluster differentiation. CAGRs derived from installation base growth rates, average selling price trajectories for software-integrated versus sensor-based systems, and service revenue mix shifts. Forecast inputs incorporated PMDA GMP Annex 15 qualification standard evolution and EU MDR device traceability mandate enforcement intensity.
Practitioners should monitor regulatory divergence between FDA electronic records requirements and Japan's PMDA export-oriented drug production standards for early signals of multi-site fleet consolidation acceleration. Forecasts reflect assumptions regarding validation engineering talent availability and cleanroom certification capacity expansion. Material shifts in METI industrial policy regarding AI-powered control system export classifications or Swissmedic coordination with ISO 13485 framework revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Mobile Stabilizer Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Robotics-Ready Fulfillment Center Design and Integration Services Market
Robotics and Automation
Global K-12 Robotic Toolkits Market
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
North America Robotics and Automation Actuators Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Asia-Pacific Robotics Technology Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
South America Agricultural Robots and Mechatronics Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Robot Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
AGV & AMR in Logistics Market
Robotics and Automation
Cleanroom Robots in Healthcare Market