
 Europe Robotics and Automation Actuators Market | 2026-2036
Europe Robotics and Automation Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Robotics and Automation Actuators Market Analytics
Germany's industrial actuator capacity build-out is fragmenting as regional supply networks diversify beyond traditional Stuttgart and Munich hubs. Festo leverages its pneumatic heritage to sustain dominance in clean-room automation for semiconductor clients. Bosch Rexroth anchors heavy-duty hydraulic actuator production for automotive press lines across Bavaria and Baden-Württemberg. Siemens competes through integrated motion control platforms that combine servo drives with linear positioning modules.
Europe robotics and automation actuators are electromechanical, fluid-power, or mechanical devices that convert energy into controlled physical motion, typically achieving positioning accuracy within micrometers through servo-feedback loops or proportional valve control. Their primary purpose is to deliver precise force, torque, or displacement in automated manufacturing cells, robotic arms, and process machinery where human operation is impractical or unsafe. Electric actuators lead value generation in electronics and food packaging lines where contamination risks exclude hydraulic fluids. Pneumatic actuators retain cost advantages in high-speed material handling across Automotive end-user facilities. Servo technology commands premium positioning in Aerospace component machining where rotary motion accuracy dictates airworthiness certification.
The EU Machinery Directive and CE marking framework mandate functional safety ratings and electromagnetic compatibility testing before market access, compelling actuator suppliers to embed redundant position sensors and fail-safe braking. ECHA REACH compliance restricts certain seal and lubricant chemistries, pushing manufacturers toward bio-based hydraulic fluids and fluoropolymer alternatives. Germany's KBA and France's ANSM coordinate type-approval pathways for actuators deployed in autonomous mobile robots traversing public industrial zones. Stakeholders must monitor how the EU AI Act's risk-classification rules will recalibrate liability for actuators operating in self-learning robotic systems.
Market Dynamics
The EU Machinery Directive's tightened functional safety mandates are compressing certification timelines while forcing actuator suppliers to embed redundant sensor architectures before CE marking approval.
Growth Catalysts
- REACH compliance evolution:ECHA's expanding restricted substance list accelerates bio-based hydraulic fluid R&D across German automotive press lines.
- France's aerospace machining:Toulouse-based airframe builders specify servo-electric actuators for tighter rotary positioning in titanium wing component fabrication.
- Semiconductor clean-room demand:Dutch lithography equipment OEMs drive specification intensity for particle-free pneumatic positioning modules in wafer handling systems.
Market Restraints
- Rare-earth magnet dependency:Neodymium price volatility constrains permanent-magnet servo motor cost structures for mid-tier actuator suppliers.
- Seal chemistry restrictions:ECHA REACH Annex XVII limitations on fluoropolymer compounds extend qualification cycles for high-temperature hydraulic cylinder applications.
- Regional supply concentration:Precision ball screw manufacturing clusters in southern Germany create single-source vulnerability for linear positioning module producers.
Strategic Opportunities
- Poland's industrial corridor:Wrocław and Poznań manufacturing zones remain underpenetrated for integrated motion control platforms serving automotive tier-one suppliers.
- EU AI Act risk classification:Self-learning robotic system mandates create liability-driven demand for actuators with embedded force-torque sensing and programmable safety limits.
- Remanufacturing channel emergence:Circular economy directives position refurbished hydraulic actuators as cost-competitive alternatives for non-safety-critical material handling in Spanish logistics hubs.
Industry Challenges
- Mechatronics talent scarcity:Cross-functional engineering roles combining servo tuning, fluid dynamics, and embedded software command 40% wage premiums in Bavaria's automation cluster.
- Legacy system integration friction:Fieldbus protocol fragmentation between PROFINET, EtherCAT, and Modbus TCP extends commissioning timelines for brownfield automotive assembly retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Robotics and Automation Actuators Market |
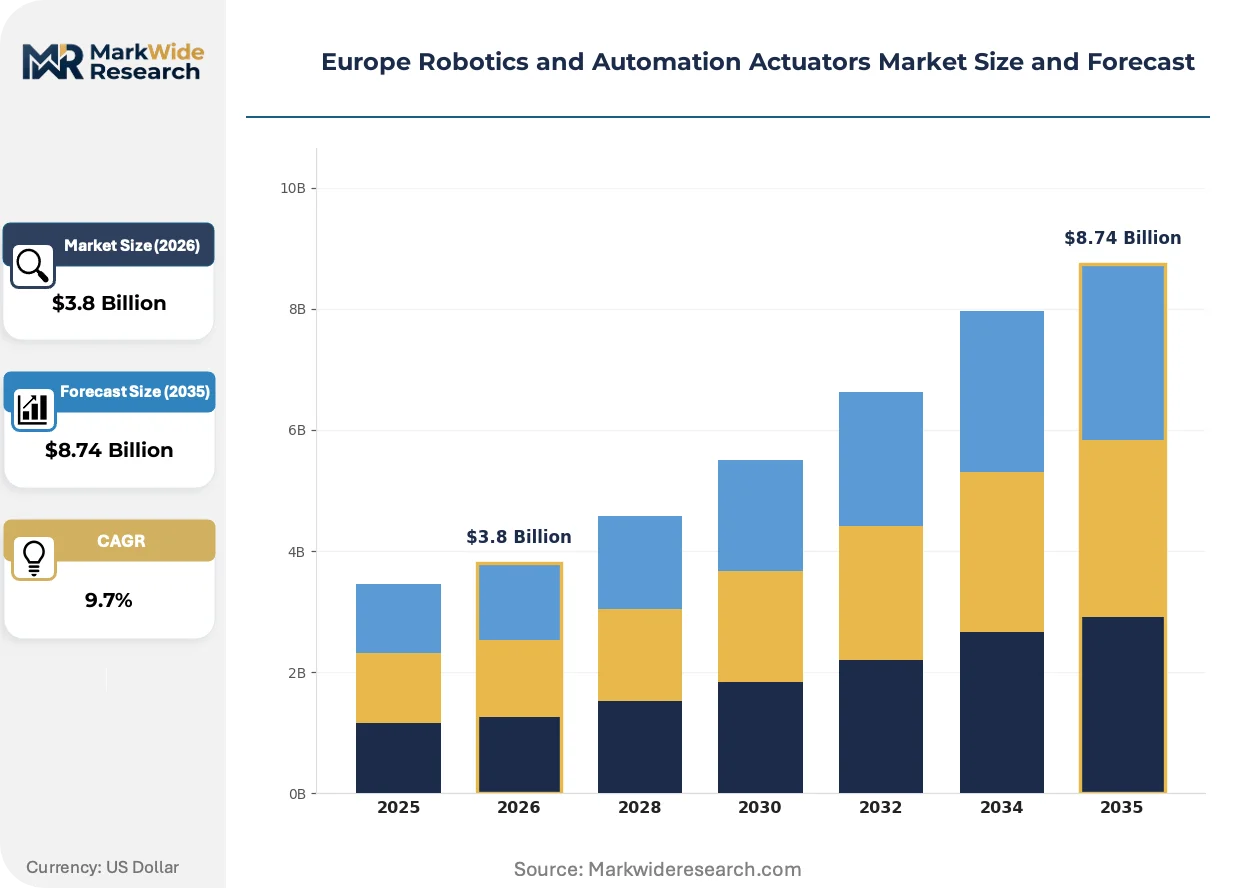
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Hydraulic Actuators, Pneumatic Actuators, Mechanical Actuators Application: Manufacturing, Packaging, Material Handling, Robotics End User: Automotive, Aerospace, Electronics, Food & Beverage Technology: Linear Motion, Rotary Motion, Servo Technology, Motion Control |
| Companies Covered | ABB, Festo, Bosch Rexroth, Rockwell Automation, Siemens, Moog, SMC, Parker Hannifin, Schneider Electric, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Robotics and Automation Actuators Market Evolving Landscape
Actuator architecture is converging around electrification and intelligence, with energy recovery mechanisms and embedded diagnostics displacing purely mechanical positioning across European manufacturing.
Integrated servo-actuator systems with hollow-shaft torque motors and absolute encoders are migrating from high-end aerospace machining into mid-tier automotive body-in-white applications. Tier-one suppliers in Stuttgart's industrial belt now specify these units for robotic spot-welding cells where cycle-time precision dictates line throughput. The technology is compressing mechanical transmission component demand while elevating motion controller software value capture.
The EU AI Act's risk-based classification framework mandates documented safety validation for actuators deployed in collaborative robotic cells. Industrial OEMs must now submit technical files demonstrating fail-safe braking response times and force-limiting accuracy before CE marking. German KBA type-approval pathways for autonomous mobile robots traversing public factory zones are extending lead times for servo-drive suppliers serving intralogistics integrators.
Buying committees at French automotive OEMs now unbundle actuator hardware from multi-year service contracts, compressing supplier switching costs. Equipment finance houses in Milan and Frankfurt offer operating-lease structures for electric linear positioning systems, transferring residual-value risk from end-users to lessors. This shift is most visible in Italy's packaging machinery sector where SME manufacturers prioritize OPEX flexibility over capital ownership.
Europe Robotics and Automation Actuators Market Segmentation
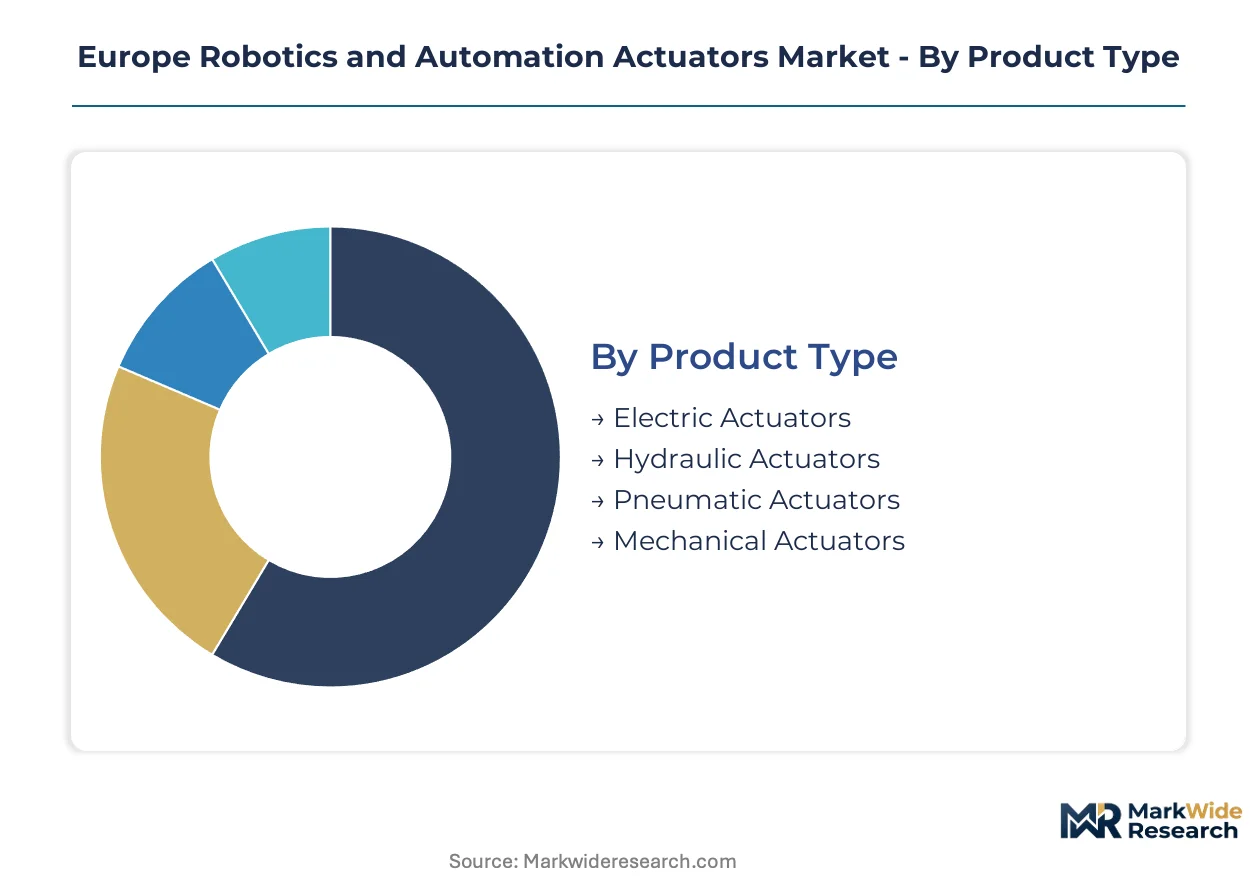
Actuator procurement cycles vary dramatically across Europe's automation landscape. Electric servo systems for semiconductor clean-rooms turn over every 3-4 years while hydraulic press-line cylinders operate for 15+ years, fragmenting supplier revenue recognition and service contract structures.
Product Type:
Cycle-time disparities between replacement intervals create portfolio management challenges for distributors serving mixed manufacturing bases.
- Electric Actuators:Brushless DC motors with integrated ball screws deliver positioning accuracy within micrometers. Dutch lithography equipment OEMs in Eindhoven specify these for wafer handling systems where particle contamination risks exclude fluid power. REACH compliance on seal materials accelerates R&D spending on dry-running linear guides.
- Hydraulic Actuators:Proportional valve-controlled cylinders generate force densities exceeding 350 bar for automotive press lines. Bavarian stamping plants anchor regional demand though bio-based fluid adoption extends qualification cycles. ECHA's expanding restricted substance list pressures seal compound reformulation.
- Pneumatic Actuators:Compressed air systems dominate high-speed pick-and-place operations in French food packaging facilities.
- Mechanical Actuators:Screw-jack and cam-based systems persist in legacy conveyor adjustments across Spanish logistics hubs.
Electric actuators anchor the volume base while servo-electric configurations gain share at the steepest rate.
Application:
Margin structures diverge sharply between specification-heavy aerospace machining and price-sensitive material handling corridors.
- Manufacturing:CNC machine tool feed drives and robotic welding cells demand sub-micron repeatability. Stuttgart's automotive body-in-white lines specify integrated servo-actuator systems where cycle-time precision dictates throughput. CE marking functional safety mandates compress supplier certification timelines.
- Robotics:Collaborative robot joints require force-torque sensing and programmable safety limits under EU AI Act risk classification rules. German KBA type-approval pathways for autonomous mobile robots extend lead times for intralogistics integrators serving public factory zones.
- Packaging:High-speed carton erecting and palletizing operations concentrate in Italy's Emilia-Romagna machinery cluster.
- Material Handling:Overhead crane and conveyor positioning systems prioritize mean-time-between-failure metrics over absolute accuracy.
Manufacturing commands the largest revenue pool while robotics applications expand most quickly.
End User:
Customer concentration patterns map directly onto Europe's industrial geography with aerospace and automotive anchoring premium specification demand.
- Automotive:Electric vehicle battery assembly lines and electric motor production cells drive specification intensity for clean-room compatible actuators. German OEMs unbundle hardware from multi-year service contracts, compressing supplier switching costs. Operating-lease structures from Milan and Frankfurt finance houses transfer residual-value risk to lessors.
- Aerospace:Titanium wing component machining in Toulouse demands rotary positioning accuracy for airworthiness certification. Servo-electric actuators with hollow-shaft torque motors and absolute encoders command premium pricing. EU Machinery Directive fail-safe braking requirements elevate embedded sensor architecture costs.
- Electronics:Semiconductor wafer handling and PCB assembly operations concentrate in Dutch and German clean-room corridors.
- Food & Beverage:Washdown-compatible pneumatic systems dominate dairy and beverage packaging lines across Denmark and Ireland.
Automotive anchors the volume base while aerospace specifications drive margin expansion at the steepest rate.
Technology:
Architecture convergence toward integrated intelligence elevates software value capture while compressing mechanical component demand.
- Servo Technology:Closed-loop position control with encoder feedback enables dynamic trajectory planning. French automotive OEMs now specify these for robotic spot-welding cells previously served by pneumatic positioning. Embedded diagnostics and predictive maintenance algorithms differentiate supplier offerings.
- Motion Control:Multi-axis coordination platforms combine servo drives with linear positioning modules. Siemens competes through integrated offerings spanning controller hardware to commissioning software. Fieldbus protocol fragmentation between PROFINET, EtherCAT, and Modbus TCP extends brownfield retrofit timelines.
- Linear Motion:Ball screw and belt-driven positioning stages concentrate procurement in southern German manufacturing clusters.
- Rotary Motion:Direct-drive torque motors and harmonic gearboxes serve robotic joint applications requiring compact form factors.
Linear motion systems anchor the installed base while servo technology climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision manufacturing clusters across Germany, France, and the Netherlands concentrate actuator specification authority, with regulatory enforcement through CE marking and the EU Machinery Directive shaping deployment patterns. Southern Germany's ball screw manufacturing networks and Toulouse's aerospace machining corridors anchor premium demand segments.
Germany
Automotive press lines in Bavaria and Baden-Württemberg drive heavy-duty hydraulic actuator procurement, while Stuttgart's body-in-white facilities specify integrated servo-actuator systems for robotic welding cells. KBA type-approval pathways for autonomous mobile robots extend lead times for intralogistics integrators. Munich's industrial belt hosts precision engineering clusters where Festo and Siemens compete for clean-room automation contracts.
France
Toulouse-based airframe builders specify servo-electric actuators with hollow-shaft torque motors for titanium wing component machining requiring airworthiness certification. ANSM coordinates with EU Machinery Directive enforcement on functional safety ratings for collaborative robotic cells. The Île-de-France region concentrates packaging machinery OEMs deploying high-speed pneumatic pick-and-place systems.
Netherlands
Eindhoven's lithography equipment OEMs drive specification intensity for particle-free pneumatic positioning modules in semiconductor wafer handling systems. REACH compliance on seal materials accelerates R&D spending on dry-running linear guides among Dutch automation suppliers. The Randstad manufacturing corridor anchors electronics assembly automation demand.
Italy
Emilia-Romagna's packaging machinery cluster prioritizes operating-lease structures for electric linear positioning systems, transferring residual-value risk to Milan-based equipment finance houses. SME manufacturers in Bologna and Modena favor OPEX flexibility over capital ownership for carton erecting and palletizing operations. CE marking timelines compress supplier certification cycles for export-oriented machinery builders.
Poland
Wrocław and Poznań manufacturing zones remain underpenetrated for integrated motion control platforms serving automotive tier-one suppliers. EU structural funds accelerate industrial corridor development, attracting actuator distributors from German supply networks. The country's machinery sector concentrates in Lower Silesia where brownfield retrofit demand outpaces greenfield automation investment.
Europe Robotics and Automation Actuators Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision mechanical elements. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with motion control portfolios, pneumatic heritage specialists leveraging clean-room expertise, and focused servo-drive technology providers. Competitive moves concentrate on embedded intelligence integration and geographic expansion into underpenetrated Central European manufacturing corridors.
Among Germany-based industrial technology groups, Bosch Rexroth, Festo, and Siemens occupy distinct positioning vectors. Bosch Rexroth anchors heavy-duty hydraulic production for automotive press applications. Festo exemplifies the pneumatic heritage specialist archetype with semiconductor clean-room penetration. Siemens represents the platform integrator model combining controller hardware through commissioning software into unified motion control offerings.
| Leading Market Players |
|---|
| ABB |
| Festo |
| Bosch Rexroth |
| Rockwell Automation |
| Siemens |
| Moog |
| SMC |
| Parker Hannifin |
| Schneider Electric |
| Others |
Value Network & Pricing Analysis
Rhine-Alpine freight corridor cost dynamics compress margins for actuator suppliers sourcing precision ball screws from southern German clusters while amplifying price differentiation between CE-marked premium tiers and standard economy configurations serving Polish automotive tier-one facilities.
Pricing Analysis
EU Machinery Directive functional safety mandates dictate the pricing tier structure across European robotics and automation actuators. Three-tier pricing stratifies across premium servo-electric systems with redundant sensor architectures, standard integrated motion platforms, and economy pneumatic configurations for material handling. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier intensifies as French automotive OEMs unbundle hardware from multi-year contracts. Packaging machinery SMEs in Italy's Emilia-Romagna cluster exhibit highest price sensitivity, while aerospace machining facilities in Toulouse demonstrate lowest sensitivity due to airworthiness certification requirements.
Supply Chain Analysis
Contract manufacturing capacity for precision linear motion components concentrates with specialized German mechanical engineering firms and Taiwanese electronics manufacturing services serving servo-drive production. Geographic supply concentration centers on Germany, Taiwan, and Japan for ball screws, encoders, and rare-earth magnet processing. Raw material dependencies draw from neodymium magnet supply chains, high-grade steel alloys, and fluoropolymer seal compounds. Single-source vulnerability in southern German ball screw manufacturing clusters poses structural supply chain risk. Distribution runs through authorized distributor networks serving automotive OEM procurement teams and machinery builder specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification substitution threatens pneumatic actuator incumbents as servo-electric systems penetrate mid-tier automotive applications previously served by compressed air technology.
For Market Incumbents: Harden defensive positions by deepening backward integration into precision ball screw manufacturing and accelerating bio-based hydraulic fluid R&D ahead of ECHA REACH expansion. Secure KBA type-approval pathways for autonomous mobile robot servo-drives before lead times extend further. Embed predictive maintenance algorithms to elevate software value capture against hardware commoditization pressure. For New Entrants and Emerging Players: Build out integrated motion control platforms targeting Poland's underpenetrated Wrocław and Poznań manufacturing corridors where EU structural funds accelerate industrial development. Prioritize collaborative robot joint applications requiring EU AI Act-compliant force-torque sensing and programmable safety limits. Pursue operating-lease financing partnerships with Milan-based equipment finance houses to transfer residual-value risk from SME end-users. For Investors and Strategic Acquirers: EU AI Act risk-classification implementation reshapes the acquisition landscape toward actuators with embedded diagnostics and documented safety validation. Long-term viability favors platform integrators combining controller hardware through commissioning software over pure component suppliers. Target acquisition archetypes include pneumatic heritage specialists with clean-room automation expertise and servo-drive technology providers with hollow-shaft torque motor capabilities. Monitor ECHA REACH substance restriction announcements as inflection signals for seal chemistry reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Ball Screw Manufacturing | Captive supply of linear motion components reduces single-source vulnerability in southern German clusters. |
| Bio-Based Hydraulic Fluid R&D Investment | ECHA REACH compliance acceleration positions suppliers ahead of seal chemistry restrictions in Bavarian press lines. |
| Embedded Diagnostics Platform Development | Predictive maintenance algorithms differentiate servo-actuator offerings in Stuttgart body-in-white applications. |
| Polish Industrial Corridor Expansion | Wrocław and Poznań manufacturing zones remain underpenetrated for integrated motion control platforms. |
| EU AI Act Safety Validation Documentation | Technical file preparation for collaborative robotic cells extends lead times and elevates compliance barriers. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at automotive OEMs, procurement leads at Tier 1 suppliers, aftermarket service heads, and R&D directors at automation technology firms and refined through secondary validation. Bottom-up and top-down triangulation combined trade data from Eurostat and national customs authorities, SEC filings and annual reports from diversified industrial conglomerates, ECHA regulatory documentation, and EU Machinery Directive implementation guidance. Primary fieldwork captured specification intensity patterns across German precision engineering clusters and French aerospace machining corridors.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include actuator product type, application intensity, end-user industry concentration, and technology architecture convergence. CAGRs were derived from installed base turnover analysis, replacement cycle compression in semiconductor clean-rooms, and electrification substitution rates in automotive body-in-white lines. Industry-specific forecast inputs incorporated EU structural fund disbursement patterns in Central European manufacturing corridors and ECHA REACH substance restriction timelines.
Stress conditions across neodymium price volatility, ECHA regulatory acceleration, and EU AI Act implementation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding electrification penetration rates and pneumatic system displacement curves. Quarterly review of ECHA restricted substance announcements, KBA type-approval queue lengths, and Polish industrial zone FDI inflows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global All Terrain Robots Market
Robotics and Automation
Asia-Pacific Cloud Robotics Market
Robotics and Automation
Case and Box Handling Robots Market
Robotics and Automation
Mobile Stabilizer Market
Robotics and Automation
Robotics End of Arm Tooling Market
Robotics and Automation
Airport Robots Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Robotic Welding Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Smart Remote Control Market
Robotics and Automation
AGV Dispatch Management Platforms Market
Robotics and Automation
Indonesia Robotics Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
United Kingdom Cloud Robotics Market