
 Robotics Software Platforms Market | 2026-2036
Robotics Software Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Robotics Software Platforms Market Analytics
Multi-source procurement of robotics middleware is decoupling hardware vendors from exclusive software ecosystems. Nvidia leverages its GPU-accelerated simulation stack to anchor high-fidelity digital twin deployments. ABB Robotics sustains broad compatibility across third-party controllers, while Boston Dynamics specializes in locomotion-specific control algorithms for dynamic terrain navigation.
Robotics software platforms are modular middleware layers that abstract hardware interfaces through real-time operating system kernels and standardized communication protocols such as DDS or ROS 2, enabling coordinated perception-planning-execution loops across heterogeneous machine fleets. Cloud-based deployment leads in total addressable reach by eliminating on-site server capital, though edge computing segments capture the fastest expansion as latency-sensitive applications in computer vision and closed-loop process automation outgrow centralized architectures. API-based integration levels command premium pricing by reducing custom engineering hours, while standalone deployments retain share in legacy manufacturing retrofits.
The EU AI Act imposes conformity assessment obligations on autonomous decision systems, compelling platform vendors to embed traceable logging and human oversight hooks. The FDA in the United States maintains separate software-as-medical-device pathways for surgical robotics, creating divergent compliance cost structures across healthcare end users. ISO 10218 and ISO/TS 15066 define collaborative robot safety parameters that directly constrain motion planning algorithms and workspace arbitration logic. Stakeholders must monitor whether emerging national AI sovereignty frameworks fragment cross-border software licensing terms before committing to single-tenant cloud architectures.
Market Dynamics
The EU AI Act's conformity assessment mandate is forcing platform vendors to rearchitect logging architectures and human-in-the-loop interfaces, while warehouse operators in Germany accelerate collaborative robot deployments that require interoperable middleware stacks.
Growth Catalysts
- Algorithmic Transparency Mandates:The EU AI Act creates procurement preference for platforms with embedded audit trails, driving replacement cycles in autonomous logistics fleets.
- Automotive OEM Scale Deployment:German manufacturers are standardizing on open programming environments for human-robot collaboration cells, expanding addressable middleware volume.
- ROS 2 Migration:Real-time DDS-based communication protocols are displacing legacy ROS 1 installations in perception-heavy applications.
Market Restraints
- GPU Supply Concentration:Nvidia's dominance in simulation-accelerated hardware creates single-source risk for high-fidelity digital twin deployments.
- Cross-Border Licensing Fragmentation:Emerging national AI sovereignty frameworks threaten to partition cloud-based platform architectures.
- Safety Certification Burden:ISO 10218 and ISO/TS 15066 compliance timelines extend 14-18 months for collaborative motion planning modules.
Strategic Opportunities
- Edge Computing Expansion:Latency-sensitive computer vision applications in semiconductor fabrication are outpacing centralized cloud architectures.
- API-First Integration Models:Premium-priced middleware layers reduce custom engineering hours for system integrators serving automotive tier-1 suppliers.
- Healthcare Pathway Divergence:The FDA's software-as-medical-device framework creates specialized compliance tooling demand for surgical robotics vendors.
Industry Challenges
- Real-Time Systems Talent Scarcity:Shortage of engineers proficient in ROS 2, DDS, and deterministic scheduling kernels constrains deployment velocity.
- Legacy Controller Integration:Retrofitting proprietary industrial automation stacks with standardized middleware requires custom protocol bridges.
- Multi-Tenant Security Architecture:Cloud-based fleet management platforms face hardened requirements for data residency and cross-tenant isolation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotics Software Platforms Market |
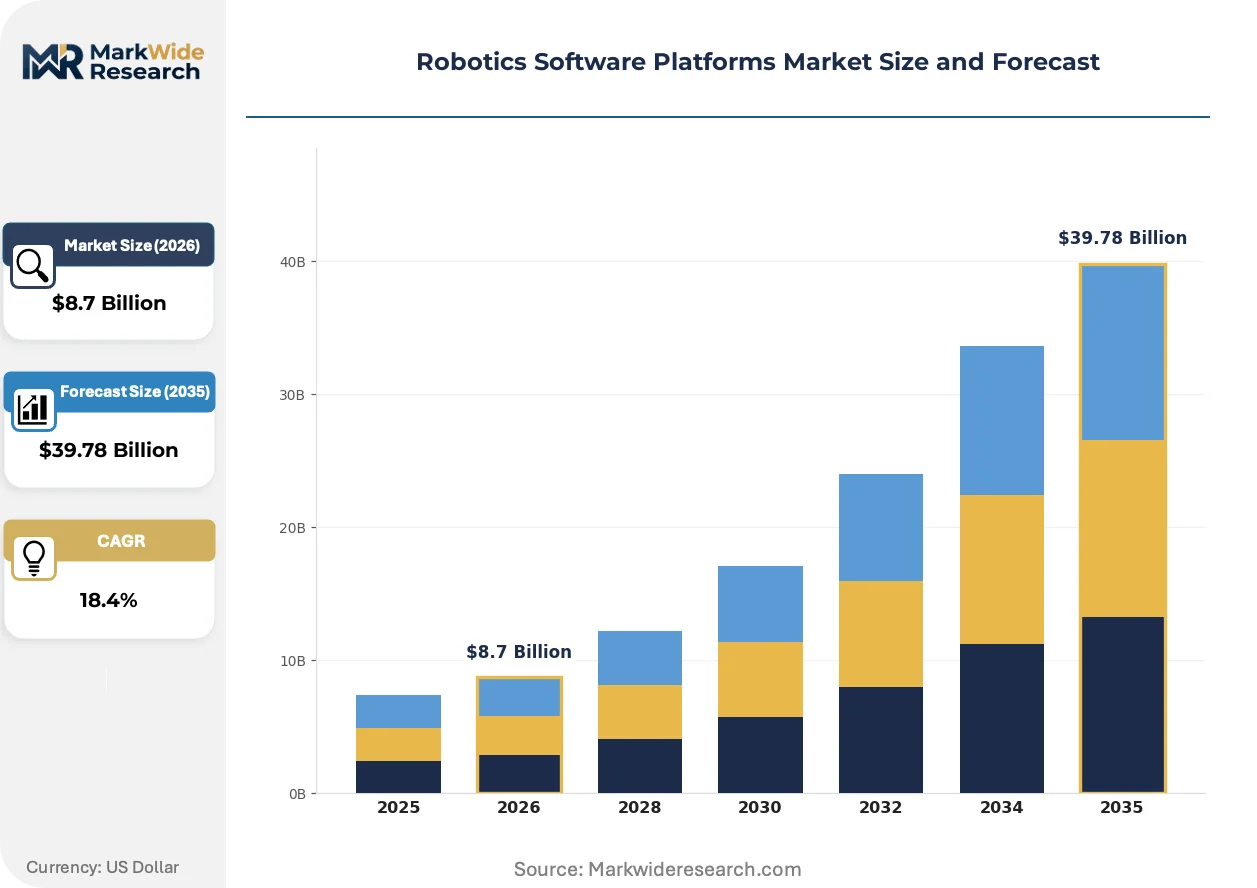
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Manufacturing, Healthcare, Logistics, Agriculture Functionality: Process Automation, Data Analytics, Machine Learning, Computer Vision Integration Level: Standalone, API-Based, Platform-Integrated, Middleware |
| Companies Covered | FANUC, Geek+, Clearpath Robotics, Boston Dynamics, GreyOrange, KUKA, Universal Robots, Nvidia, ABB Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotics Software Platforms Market Evolving Landscape
Simulation-first development workflows are compressing hardware-in-the-loop testing cycles, while regulatory pressure on algorithmic accountability reshapes platform architecture roadmaps across automotive and logistics end uses.
Digital twin environments are unifying physics-based simulation with production sensor feeds, enabling predictive maintenance models for dynamic terrain navigation systems. Mining operators in Australia and construction firms in Japan are deploying these unified stacks to reduce physical prototyping cycles by half. The technology is compressing vendor competitive differentiation around fidelity benchmarks rather than hardware compatibility alone.
The EU AI Act's conformity assessment obligations are mandating traceable decision logging for autonomous systems deployed in public logistics infrastructure. Platform vendors must now embed immutable audit trails and human override hooks directly into perception-planning-execution loops. Healthcare robotics manufacturers face the steepest compliance cost escalation, as surgical systems require dual certification under both the EU framework and the FDA's software-as-medical-device pathway.
System integrators are consolidating procurement around vertically specialized middleware vendors rather than generalist platform suites. Automotive OEMs in Germany now specify collaborative robot programming environments with pre-certified safety modules, displacing custom integration projects. This concentration is most visible in Bavaria's automotive supplier corridor, where tier-1 manufacturers demand API-native fleet orchestration tools with guaranteed ISO/TS 15066 compliance documentation.
Robotics Software Platforms Market Segmentation
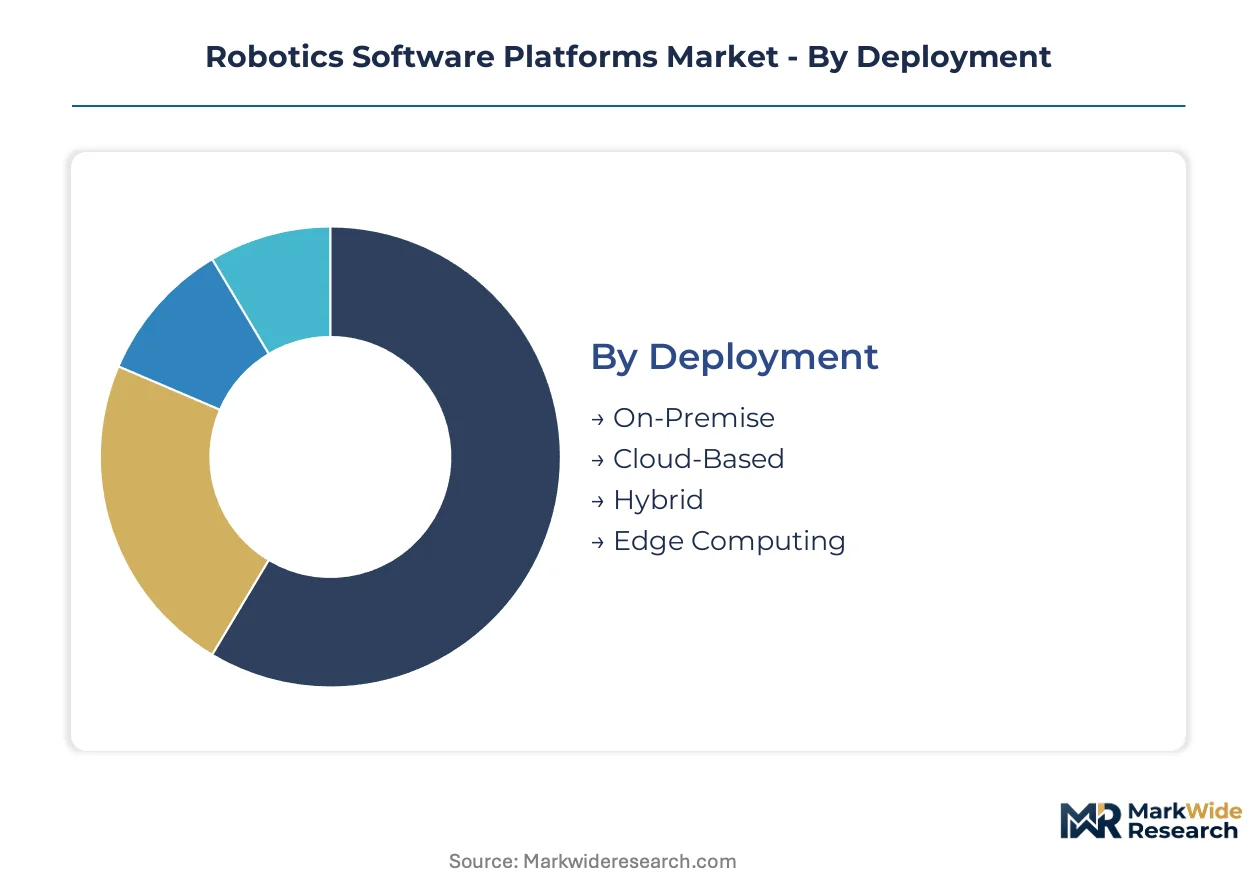
Robotics software platforms fragment across four orthogonal dimensions that determine procurement economics and integration complexity. Deployment architecture dictates capital intensity and latency performance. End-user verticals impose divergent safety certifications and workflow constraints.
Deployment:
Cloud-based architectures dominate total addressable reach through elimination of on-site server capital, while edge computing segments capture premium expansion rates as latency-sensitive applications outgrow centralized infrastructure.
- Cloud-Based:Multi-tenant SaaS delivery eliminates upfront infrastructure spend for warehouse operators scaling robot fleet management. German automotive OEMs favor this model for collaborative robot programming environments that require centralized model training and remote diagnostics access.
- Edge Computing:Deterministic real-time kernels process perception-planning-execution loops locally, slashing round-trip latency for semiconductor fabrication vision systems. Australian mining operators deploy these stacks for dynamic terrain navigation where connectivity gaps render cloud dependency untenable.
- On-Premise:Single-tenant installations retain share in defense and nuclear applications with air-gapped security mandates.
- Hybrid:Workload-splitting architectures federate training to cloud while keeping inference at edge, common in FDA-regulated surgical robotics requiring local decision sovereignty with remote oversight capability.
Today's leader: Cloud-Based. Tomorrow's challenger: Edge Computing.
End User:
Manufacturing commands the deepest installed base through automotive and electronics assembly automation, though healthcare segments extract the highest per-seat pricing through regulatory compliance tooling.
- Manufacturing:Automotive tier-1 suppliers in Bavaria standardize on open programming environments for human-robot collaboration cells. ISO/TS 15066 safety modules are now procurement prerequisites rather than optional add-ons.
- Healthcare:Surgical robotics manufacturers face dual certification burdens under FDA software-as-medical-device pathways and EU AI Act conformity assessments. Traceable logging and human override hooks add 30-40% to platform development costs.
- Logistics:Warehouse operators scale fleet orchestration tools for autonomous mobile robots in last-mile distribution centers.
- Agriculture:Precision farming deployments leverage computer vision for crop monitoring and autonomous harvesting in Japanese greenhouse operations.
Manufacturing retains volume leadership. Healthcare climbs the fastest on compliance-driven replacement cycles.
Functionality:
Process automation modules generate the most recurring revenue through deterministic control loops, while machine learning layers command implementation premiums for perception-heavy applications.
- Computer Vision:GPU-accelerated inference stacks enable real-time object detection and pose estimation for bin-picking and quality inspection. Japanese construction firms deploy these modules for predictive maintenance on heavy equipment fleets.
- Machine Learning:Model training pipelines and MLOps tooling support adaptive motion planning for collaborative robots in German automotive supplier corridors. EU AI Act traceability requirements are reshaping logging architectures here.
- Process Automation:Deterministic sequencing engines coordinate multi-robot workflows in electronics assembly lines.
- Data Analytics:Fleet telemetry aggregation supports predictive maintenance and operational optimization for logistics operators.
Process automation anchors current spend. Machine learning gains share fastest on generative simulation and adaptive control demand.
Integration Level:
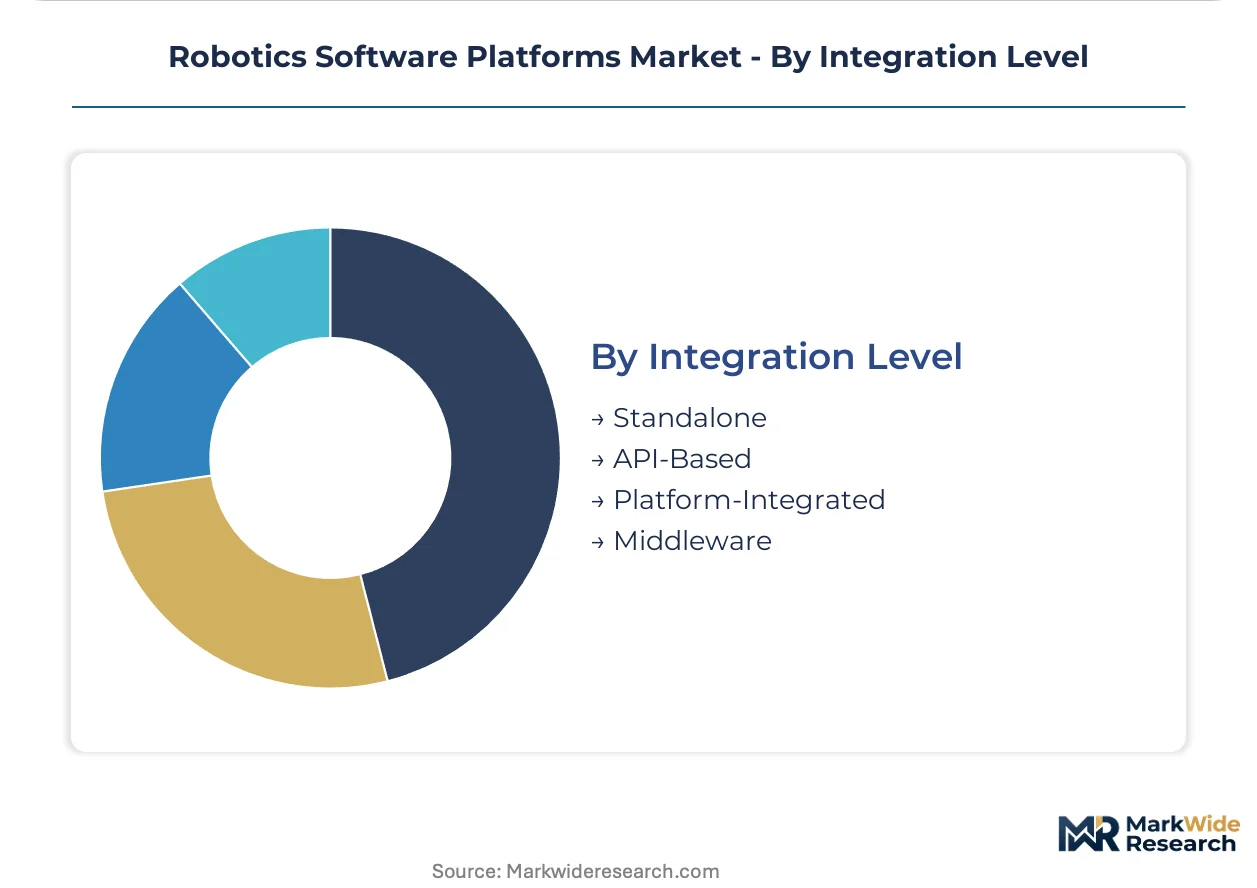
API-based integration levels extract premium pricing by reducing custom engineering hours for system integrators, while standalone deployments persist in legacy manufacturing retrofits with proprietary controller stacks.
- API-Based:Standardized REST and gRPC interfaces enable rapid orchestration across heterogeneous robot fleets without protocol bridge development. System integrators serving automotive OEMs specify these layers to compress deployment timelines.
- Middleware:ROS 2 and DDS-based communication abstraction layers decouple hardware vendors from exclusive software ecosystems. ABB Robotics sustains broad compatibility here, while Nvidia anchors high-fidelity digital twin deployments.
- Standalone:Monolithic control systems persist in brownfield installations where retrofitting standardized middleware exceeds replacement economics.
- Platform-Integrated:Vendor-locked suites bundle perception, planning, and execution in closed environments common in early-generation collaborative robot installations.
API-Based integration leads on new procurement. Middleware climbs fastest on multi-vendor fleet standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence is redistributing platform development investment toward jurisdictions with clearer compliance pathways. The EU AI Act's conformity assessment timeline has compressed procurement decisions in member states, while the United States maintains separate FDA software-as-medical-device tracks that fragment vendor resource allocation.
United States
FDA software-as-medical-device pathways for surgical robotics create specialized compliance tooling demand. The agency maintains distinct premarket submission tracks that extend platform certification timelines. Boston and Pittsburgh robotics clusters concentrate venture deployment in autonomous mobile robot middleware.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg standardize on open programming environments for human-robot collaboration cells. The EU AI Act imposes conformity assessment obligations that favor vendors with pre-certified safety modules. Stuttgart's supplier corridor demands API-native fleet orchestration with guaranteed ISO/TS 15066 documentation.
China
MIIT industrial internet policies accelerate domestic middleware standardization for smart manufacturing. National AI sovereignty frameworks threaten to partition cross-border software licensing terms. Shenzhen and Shanghai robotics parks concentrate deployment of cloud-based fleet management for electronics assembly.
Japan
METI robotics roadmaps prioritize edge computing architectures for latency-sensitive semiconductor fabrication. JIS standards harmonization with ISO 10218 reduces certification friction for collaborative motion planning. Nagoya's automotive belt deploys deterministic real-time kernels for multi-robot welding cells.
Australia
TGA medical device regulations create parallel compliance tracks for surgical robotics software. Mining operators in Western Australia deploy edge-native stacks for dynamic terrain navigation where connectivity gaps render cloud dependency untenable. Perth's resources technology cluster compresses physical prototyping cycles through unified digital twin environments.
Robotics Software Platforms Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized vertical integration and API-first monetization models. The vendor base stratifies across three maturity tiers: industrial automation incumbents with captive controller ecosystems, GPU-accelerated simulation specialists, and collaborative robot pure-plays. Dominant competitive moves include strategic partnerships for ROS 2 middleware compatibility and geographic expansion into German automotive supplier corridors.
Within the industrial automation tier, FANUC and KUKA exemplify hardware-anchored platform strategies. Nvidia occupies a distinct position as the simulation-accelerated specialist. Among collaborative robot pure-plays, Universal Robots represents the open-ecosystem archetype. ABB Robotics and Boston Dynamics anchor divergent specialization vectors—broad controller compatibility versus locomotion-specific control algorithms.
| Leading Market Players |
|---|
| FANUC |
| Geek+ |
| Clearpath Robotics |
| Boston Dynamics |
| GreyOrange |
| KUKA |
| Universal Robots |
| Nvidia |
| ABB Robotics |
| Others |
Value Network & Pricing Analysis
Captive GPU supply from Nvidia anchors both the cost structure and the pricing power of high-fidelity simulation stacks, forcing platform vendors to absorb silicon scarcity through tiered service bundling or pass-through surcharges to German automotive OEMs and Australian mining operators.
Pricing Analysis
Distributor margins on middleware licenses compress as direct-to-OEM API subscriptions displace channel-heavy perpetual sales. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated surgical stacks from uncertified logistics modules, with ISO/TS 15066 documentation and EU AI Act traceability commanding tier premiums. Cost compression in edge computing tiers is intensifying because semiconductor foundry capacity constraints inflate deterministic kernel costs. Automotive tier-1 suppliers in Bavaria show lowest price sensitivity due to bundled safety certification requirements, while warehouse operators in logistics segments resist per-seat escalations.
Supply Chain Analysis
Engineering talent scarcity in Germany, Japan, and the United States constrains deployment velocity for ROS 2 and DDS-proficient teams, elongating implementation timelines. GPU silicon from Taiwan, South Korea, and the United States feeds simulation-accelerated digital twin development, while rare earth processing for servo motor magnets centers on China. Single-source vulnerability in Nvidia's CUDA ecosystem threatens high-fidelity deployment roadmaps. Distribution runs through system integrator networks serving automotive supplier corridors, with API-native vendors bypassing traditional channel markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotics software platforms function as a stable compounder, with regulatory mandates for algorithmic transparency in the EU and FDA pathways in the United States driving sustained replacement cycles across automotive and healthcare verticals.
For Market Incumbents: Lock in collaborative robot programming environments through pre-certified ISO/TS 15066 safety modules that German automotive OEMs now mandate. Deepen backward integration into deterministic real-time kernels to reduce dependency on third-party ROS 2 distributions. Absorb GPU supply volatility through long-term allocation agreements with foundry partners, defending margin position against emerging entrants lacking silicon leverage.
For New Entrants and Emerging Players: The gap between premium FDA-validated surgical stacks and economy-tier logistics middleware creates entry space for mid-market API-first vendors. Target Australian mining operators and Japanese semiconductor fabricators with edge-native stacks where connectivity gaps exclude cloud incumbents. Lead with deterministic latency guarantees and local deployment sovereignty, bypassing the certification burden that slows healthcare penetration.
For Investors and Strategic Acquirers: Roll-up economics work for vertically specialized middleware vendors because automotive OEM consolidation around open programming environments fragments addressable share among narrow specialists. Focus acquisition screens on edge computing pure-plays with JIS or ISO 10218 documentation assets and established relationships with tier-1 system integrators. Watch for inflection when EU AI Act enforcement triggers replacement waves in autonomous logistics fleets, signaling volume acceleration for traceable logging architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ROS 2 middleware compatibility decouples hardware vendors from captive ecosystems. |
| Acquisition of Specialist Firm | Edge computing pure-plays add deterministic kernel capabilities for semiconductor fabrication. |
| Geographic Expansion | API-native fleet orchestration penetrates Bavaria's automotive supplier corridor. |
| Strategic Partnership | GPU allocation agreements secure simulation-accelerated digital twin roadmaps. |
| Product Launch | Pre-certified safety modules capture EU AI Act procurement preferences in logistics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with robotics platform engineers, system integrator technical leads, automotive OEM procurement officers, and healthcare regulatory affairs specialists with secondary validation against SEC filings, EU AI Act implementation guidance, ISO certification registries, and semiconductor foundry capex disclosures. Bottom-up deployment estimates triangulated against top-down market sizing across cloud, edge, and on-premise architectures.
Segment-weighting approaches distributed value across deployment models, end-user verticals, functionality layers, and integration levels, with growth trajectories derived from adoption curve analysis and replacement cycle timing across the projection horizon. Modeled inputs included ROS 2 migration velocity, EU AI Act compliance cost pass-through rates, and GPU supply elasticity for simulation workloads.
Caveats apply where MIIT industrial internet policies in China or emerging national AI sovereignty frameworks could materially shift cross-border licensing terms and cloud architecture viability. Material deviation in FDA software-as-medical-device pathway timelines or Nvidia foundry allocation priorities warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
North America Agricultural Robots and Mechatronics Market
Robotics and Automation
Soft Exoskeleton Market
Robotics and Automation
Motion Control Software in Robotics Market
Robotics and Automation
Bot Services Market
Robotics and Automation
Gantry Industrial Robots Market
Robotics and Automation
Asia Pacific Automated Guided Vehicle (AGV) Market
Robotics and Automation
Mobile Robotics Market
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
Asia-Pacific AUV and ROV Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Europe Service Robotics Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
Smart Exoskeleton Market
Robotics and Automation
Intelligent Parcel Delivery Lockers Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Electric Power Intelligent Inspection Robot Market