
 Gasoline As a Fuel Market | 2026-2036
Gasoline As a Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Gasoline As a Fuel Market Analysis
Retail station networks across suburban corridors is reshaping how gasoline reaches end consumers in fragmented demand pockets. Exxon Mobil Corp. controls extensive downstream infrastructure that locks in supply security for branded outlets. Shell plc differentiates through loyalty-integrated mobility services that extend beyond commodity fuel sales. Chevron Corp. anchors its position in premium gasoline grades through additive technology leadership.
Gasoline as a fuel denotes a volatile, refined petroleum distillate composed primarily of C4-C12 hydrocarbons with a typical research octane number ranging from 87 to 94, formulated for spark-ignition internal combustion engines. Its primary commercial purpose centers on energy delivery for transportation and small-scale power applications requiring portable, high-energy-density fuel. The regular and premium fuel type categories dominate volume, while ethanol blends capture regulatory-driven growth corridors in markets with biofuel mandates. Marine and equipment applications in the application dimension retain stable offtake despite electrification headwinds in vehicle fueling.
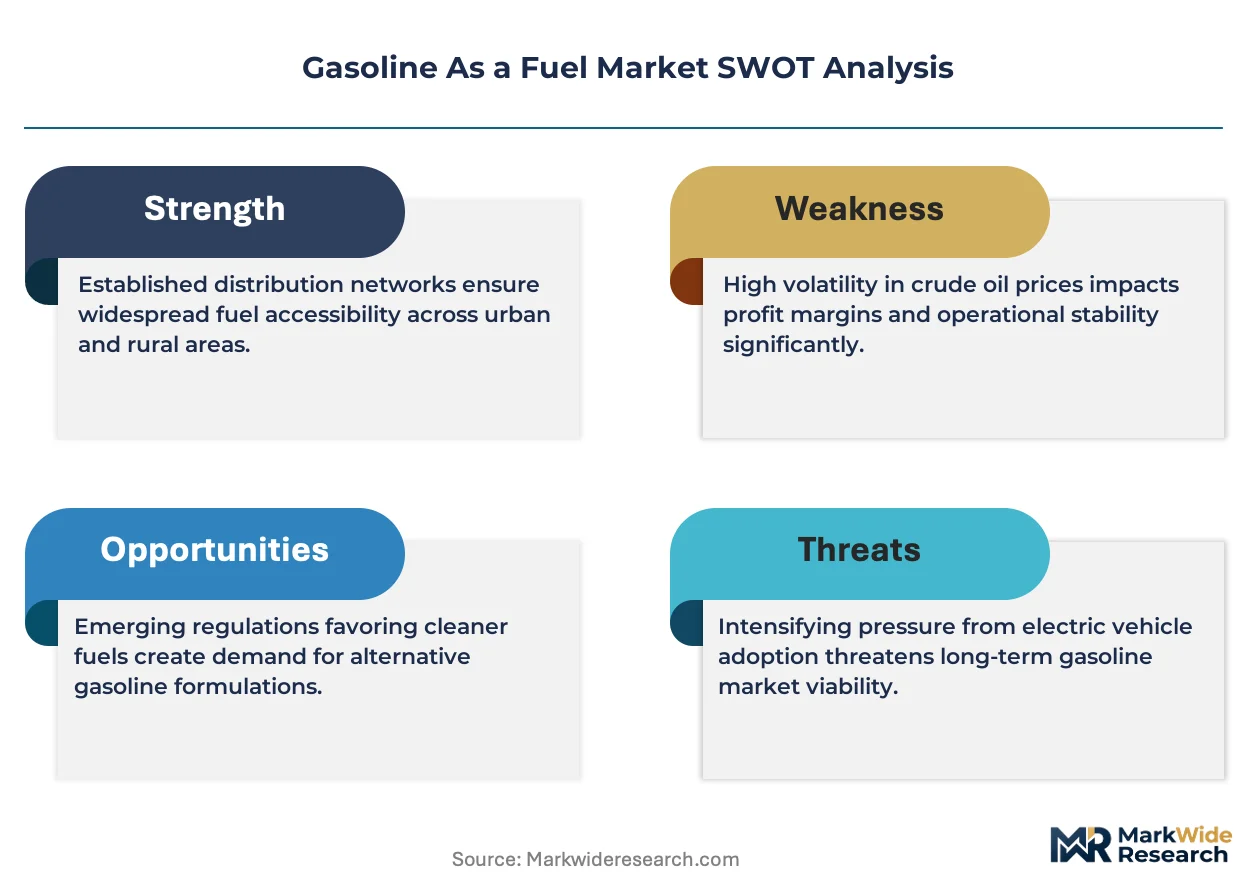
EPA, Euro 6 emission frameworks, and India's BIS fuel quality standards collectively tighten sulfur content and octane specifications, forcing refinery upgrades and blendstock reconfiguration. These regulations raise compliance costs for market access while advantaging integrated refiners with hydrocracker and alkylation capacity. Stakeholders must monitor biofuel blending mandates and carbon border adjustments as these mechanisms increasingly determine gasoline's competitive position against electrified alternatives.
Market Dynamics
Refinery configuration decisions now hinge on sulfur-content mandates that force capital reallocation toward hydrotreating and alkylation units. EPA Tier 3 and Euro 6 specifications compress the viable crude slate while raising the cost floor for market participation.
Growth Catalysts
- Motorization in emerging economies:First-time vehicle ownership in India, Brazil, and Indonesia sustains incremental gasoline demand as household income thresholds cross two-wheeler-to-car transition points.
- Biofuel blending mandates:Regulatory floors for ethanol content in transportation fuels create captive offtake for agricultural feedstock processors and shield gasoline from direct displacement in compliant jurisdictions.
- Alkylation unit investments:Refiners with existing hydrocracker capacity capture margin expansion as octane specifications tighten and high-octane blendstock scarcity intensifies.
Market Restraints
- Crude price volatility:Feedstock cost swings compress crack spreads and erode planning certainty for independent refiners without integrated upstream positions.
- Electrification substitution:Battery electric vehicle penetration in passenger transport segments directly displaces gasoline volume in markets with charging infrastructure density.
- Refinery concentration risk:Gulf Coast and Singapore hub dependence creates supply vulnerability to weather events and geopolitical disruptions affecting maritime transit routes.
Strategic Opportunities
- Retail network digitization:Mobile-integrated fueling apps and loyalty platforms capture consumer data and reduce price elasticity for branded station operators.
- Marine and equipment segments:Small-engine and coastal vessel applications retain stable offtake as electrification economics prove unworkable for high-utilization commercial equipment.
- Carbon border adjustment positioning:Low-carbon intensity gasoline production pathways qualify for preferential treatment under emerging EU and UK import frameworks.
Industry Challenges
- Alkylation catalyst supply constraints:Hydrofluoric and sulfuric acid catalyst procurement faces extended lead times and environmental permitting delays.
- Legacy terminal infrastructure:Underground storage tank replacement cycles strain capital budgets for independent distributors facing ethanol compatibility mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gasoline As a Fuel Market |
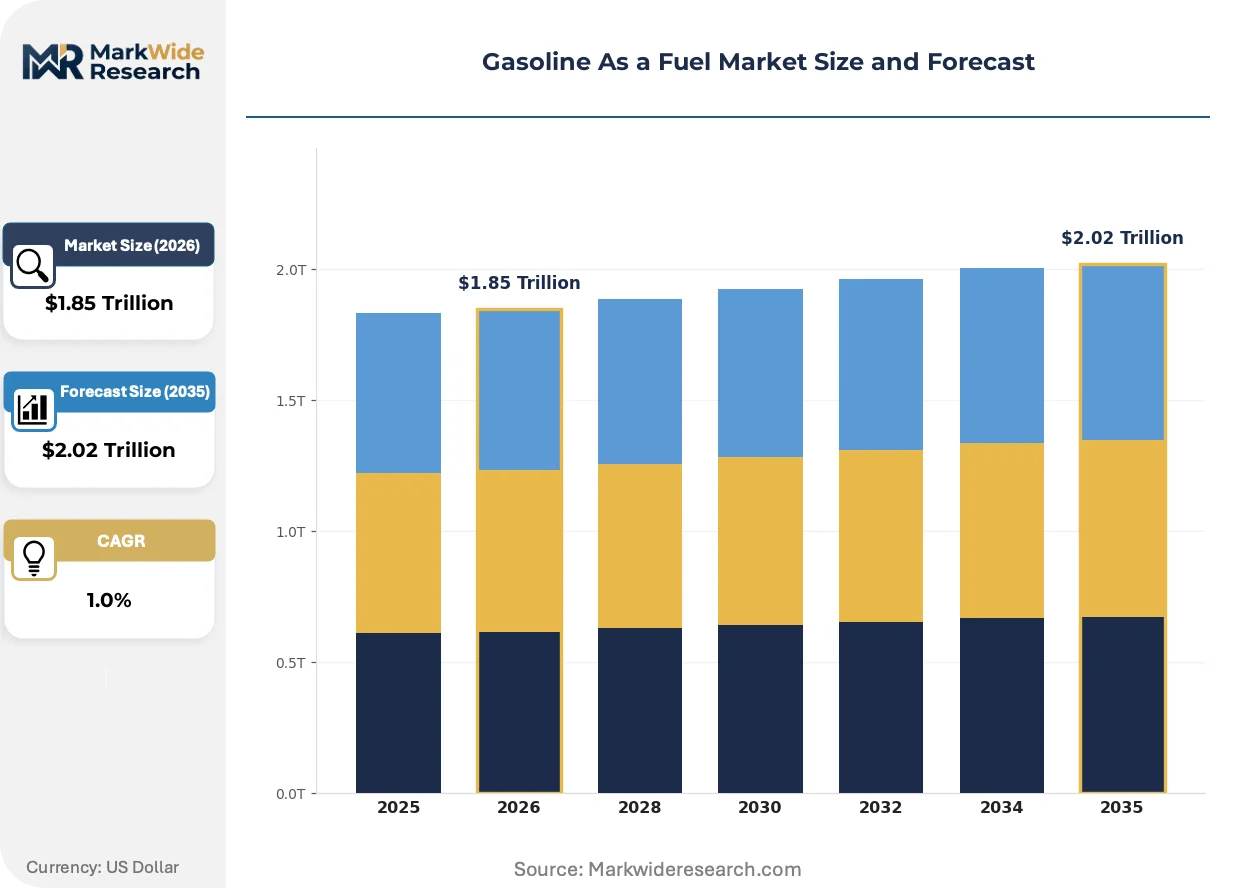
| Market Size in 2026 | $1.85 Trillion |
| Market Size in 2035 | $2.02 Trillion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Regular, Premium, Ethanol, Blend Application: Vehicle Fueling, Marine, Power Generation, Equipment Distribution Channel: Retail Stations, Wholesalers, Distributors, Online Sales Storage Type: Above Ground Tanks, Underground Tanks, Drums, Tanker Trucks |
| Companies Covered | Exxon Mobil Corp., Chevron Corp., BP Plc, Shell plc, Phillips 66 Company, Valero Energy Corp., Marathon Petroleum Corp., PBF Energy Inc., Saudi Arabian Oil Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gasoline As a Fuel Market Emerging Trajectories
Operational technology deployment is digitizing refinery yield optimization and retail demand forecasting. These capabilities compress decision latency and reconfigure competitive advantage around data velocity rather than scale alone.
Artificial intelligence-driven predictive maintenance is digitizing refinery turnaround scheduling and catalyst replacement cycles. Mid-scale operators with constrained technical staffing adopt cloud-based diagnostic platforms to extend run lengths and reduce unplanned outages. This technology is digitizing maintenance cost structures and compressing the performance gap between integrated majors and independent processors.
EPA's Tier 3 sulfur standards and California's LCFS framework impose sub-10 ppm gasoline specifications and carbon intensity scoring. Refiners without deep hydroprocessing capability face product exclusion from premium coastal markets. West Coast and Northeast distribution systems absorb the highest compliance costs while Gulf Coast exporters redirect lower-specification product to less regulated destinations.
Fleet procurement centralization is consolidating gasoline purchasing into contracted fuel card programs and direct refinery relationships. Independent retail stations lose volume to corporate fleet accounts with negotiated rack-price access. This concentration is most visible in last-mile delivery and ride-hail vehicle pools across metropolitan India and Southeast Asian logistics corridors.
Gasoline As a Fuel Market Segmentation
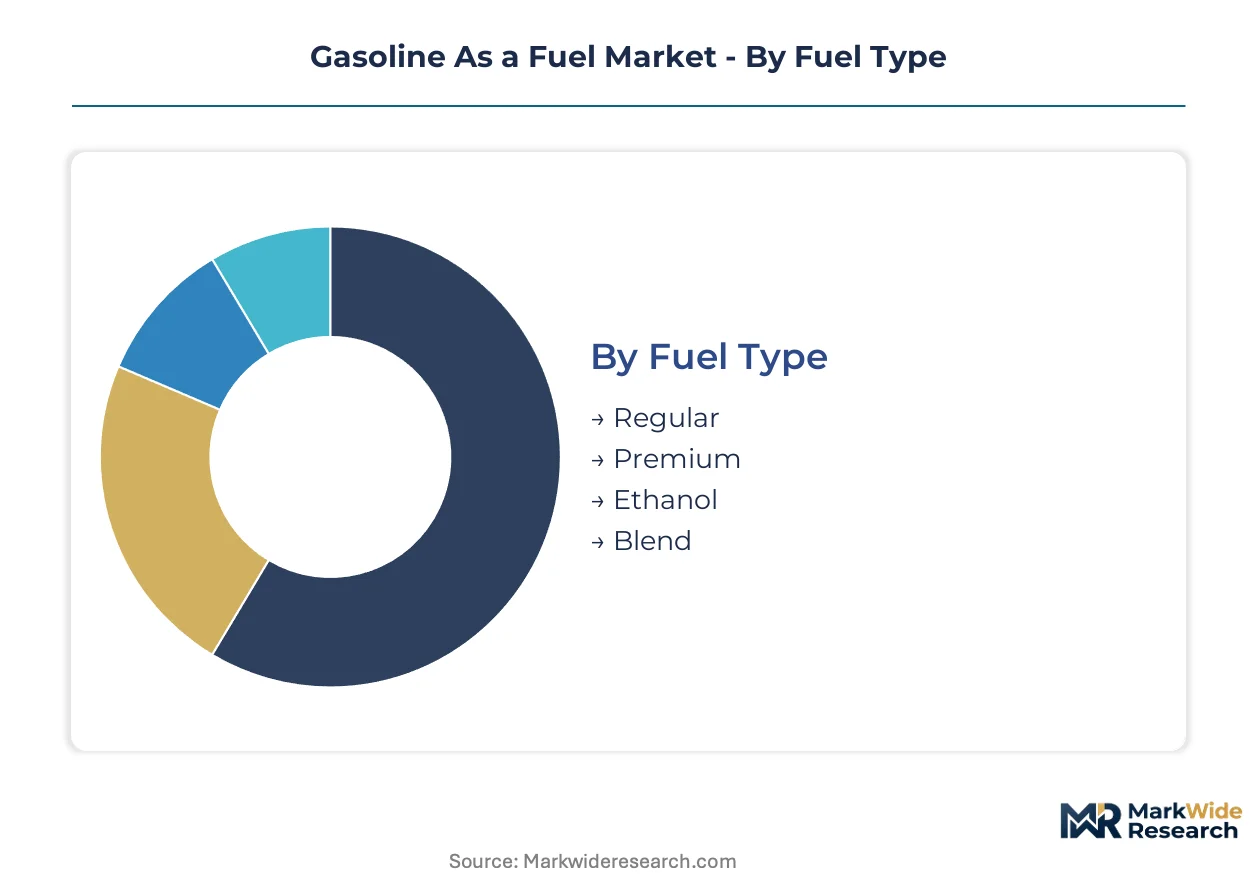
Gasoline segmentation determines refinery configuration priorities, margin capture potential, and regulatory compliance pathways. Distinct fuel grades, application requirements, and distribution architectures create divergent investment returns across the value chain.
Fuel Type:
Octane ratings and biofuel content define the use-case spectrum from mass-market vehicle propulsion to specialized high-performance engines.
- Regular:87-octane formulation serves price-sensitive vehicle owners and fleet operators across India, Brazil, and Indonesia. EPA Tier 3 sulfur limits force hydrotreater investments that compress margins on this volume-heavy grade.
- Premium:91-94 octane ratings command pricing premiums in markets with turbocharged engine penetration and manufacturer warranty requirements. Chevron's additive technology leadership anchors branded differentiation in this segment.
- Ethanol:E10-E85 blends capture regulatory-mandated volume in jurisdictions with biofuel floors. Agricultural feedstock processors lock in captive offtake through blending obligations.
- Blend:Intermediate ethanol-gasoline mixtures balance octane enhancement with infrastructure compatibility constraints.
Established volume favors Regular; emerging adoption favors Ethanol.
Application:
End-use concentration determines sulfur tolerance, volatility specifications, and delivery infrastructure requirements.
- Vehicle Fueling:Light-duty passenger and commercial fleets absorb the majority of gasoline throughput. Motorization rate climbs in emerging economies sustain incremental demand despite electrification headwinds in developed markets.
- Marine:Coastal vessels and recreational craft require specialized low-volatility formulations. This segment retains stable offtake as battery economics prove unworkable for high-utilization commercial watercraft.
- Power Generation:Portable generators and remote installations demand high-energy-density fuel with extended storage stability.
- Equipment:Landscaping, construction, and agricultural machinery maintain consistent consumption patterns resistant to electrification substitution.
Vehicle Fueling dominates volume contribution; Marine offers the most defensible position against displacement.
Distribution Channel:
Channel selection shapes working capital intensity, price transparency, and customer relationship durability.
- Retail Stations:Branded networks across suburban corridors capture fragmented demand pockets. Exxon Mobil's downstream infrastructure locks in supply security for outlet operators.
- Wholesalers:Rack-price access serves fleet procurement centralization and fuel card program consolidation.
- Distributors:Independent terminal operators bridge refinery output and end-user access in secondary markets.
- Online Sales:Mobile-integrated platforms and loyalty apps compress price elasticity for digitally enabled operators.
Retail Stations anchor revenue stability; Online Sales climbs the fastest in metropolitan corridors.
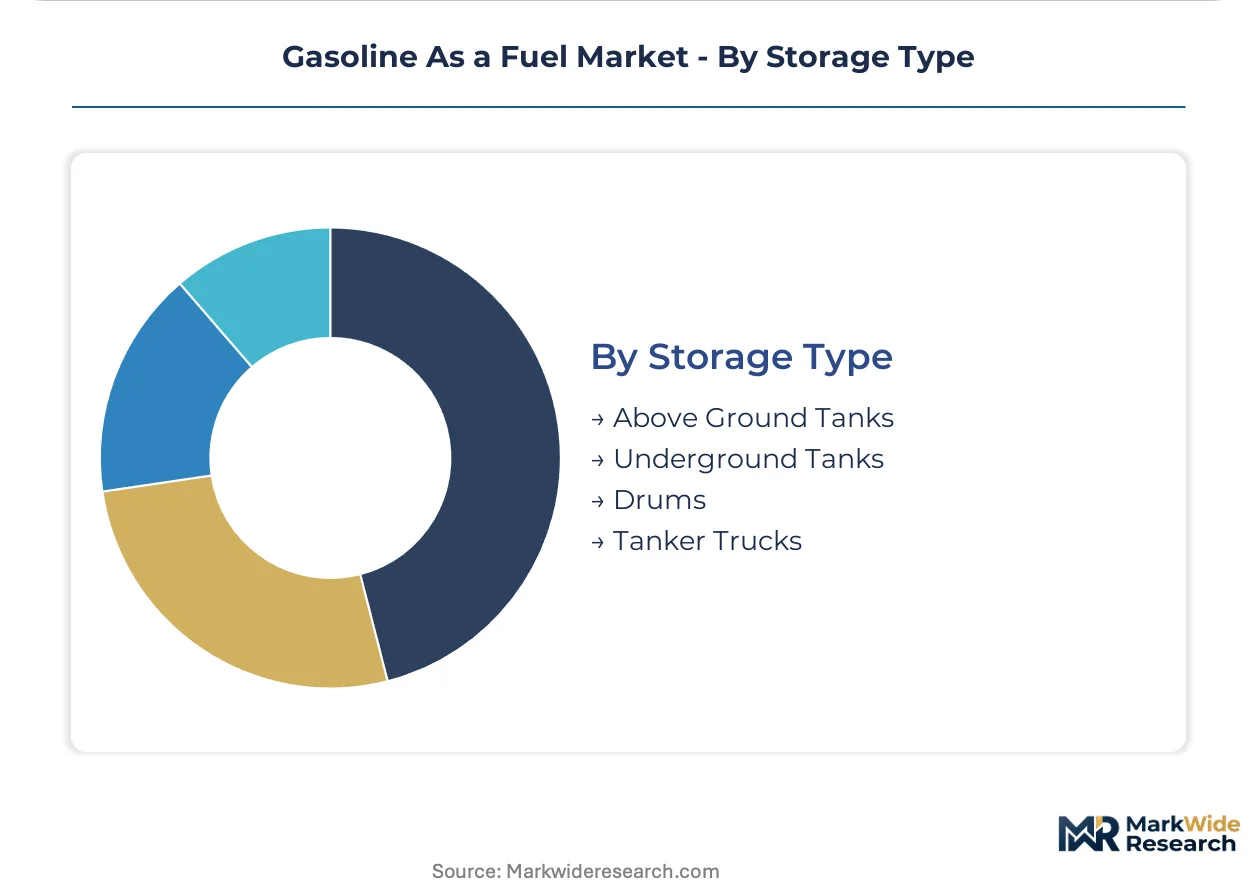
Storage Type:
Physical containment specifications respond to ethanol compatibility mandates, environmental permitting, and throughput velocity.
- Above Ground Tanks:Terminal and bulk storage facilities enable rapid turnover and inspection access. Gulf Coast and Singapore hub operators concentrate capacity in this configuration.
- Underground Tanks:Retail station infrastructure faces replacement cycles driven by ethanol degradation concerns and leak detection regulations.
- Drums:Small-volume packaging serves equipment and marine applications requiring portable fuel access.
- Tanker Trucks:Last-mile delivery fleets connect terminals to retail and commercial end-users.
Underground Tanks represent the largest installed base; Above Ground Tanks attract new investment in export-oriented hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS fuel quality standards and Brazil's RenovaBio program are accelerating refinery upgrades across major consumption corridors. Regulatory tightening in Indonesia and sulfur-content mandates in the United States are compressing the viable crude slate for gasoline producers. These policy drivers are redistributing competitive advantage toward integrated refiners with deep hydroprocessing capability.
United States
EPA Tier 3 sulfur specifications enforce sub-10 ppm gasoline standards that exclude refiners lacking hydrotreater investments. The Gulf Coast refining hub concentrates alkylation capacity and export-oriented production, with Houston-area terminals redirecting lower-specification product to less regulated destinations. West Coast and Northeast distribution systems absorb the highest compliance costs under California's LCFS framework.
India
Motorization rate climbs in tier-2 and tier-3 cities sustain incremental gasoline demand as household incomes cross two-wheeler-to-car transition points. BIS fuel quality standards mandate cleaner-burning specifications that force refinery upgrades at Mathura and Panipat facilities. The Delhi-Mumbai Industrial Corridor anchors branded retail network expansion as suburban vehicle ownership accelerates.
Brazil
RenovaBio carbon intensity targets and ANP blending regulations create captive offtake for ethanol-gasoline mixtures in the flex-fuel vehicle fleet. São Paulo state concentrates sugarcane processing infrastructure that feeds the hydrous ethanol supply chain. The Southeast region's refinery complex at Paulínia captures margin advantages from integrated biofuel production.
Indonesia
Pertamina's fuel quality roadmaps and the national B30 biodiesel program extend to gasoline specifications as motorization accelerates across Java and Sumatra. The Cilacap and Balikpapan refining hubs face capital reallocation demands to meet emerging sulfur and octane mandates. Jakarta's suburban corridor expansion drives retail station network densification.
Saudi Arabia
Saudi Aramco's downstream integration strategy positions the Kingdom as a residual fuel oil exporter while gasoline specifications tighten in target markets. The Jubail and Yanbu industrial cities concentrate refining and petrochemical capacity with export-oriented configuration. Domestic demand growth in Riyadh and Jeddah sustains incremental product offtake for the local vehicle fleet.
Gasoline As a Fuel Market Vendor Landscape
On the supply side, the industry is consolidating around integrated majors with captive upstream positions and independent refiners with specialized hydroprocessing assets. The competitive terrain stratifies into three archetypes: global integrated oil companies controlling downstream infrastructure, independent pure-play refiners optimizing crack spreads, and national oil companies leveraging state-backed feedstock access. Dominant competitive moves include alkylation unit investments to capture octane specification premiums and retail network digitization to reduce price elasticity.
Among North American integrated majors, Exxon Mobil Corp., Chevron Corp., and Marathon Petroleum Corp. occupy positions spanning refinery ownership through branded retail distribution. These entities exemplify the infrastructure-anchored archetype where downstream control locks in supply security across suburban corridor networks. Their market presence represents the scale-driven tier where integrated operations compress cost structures against independent processors.
| Leading Market Players |
|---|
| Exxon Mobil Corp. |
| Chevron Corp. |
| BP Plc |
| Shell plc |
| Phillips 66 Company |
| Valero Energy Corp. |
| Marathon Petroleum Corp. |
| PBF Energy Inc. |
| Saudi Arabian Oil Co. |
| Others |
Supply Flow & Price Mechanics
Gulf Coast refinery concentration in the United States anchors global gasoline supply and funnels margin capture toward integrated operators with hydrocracker and alkylation assets. This upstream consolidation directly determines where pricing power accrues downstream, as independent distributors without captive refining face compressed rack-price spreads.
Pricing Analysis
Volume-discount tiering structures separate branded premium formulations from unbranded standard grades and economy spot markets. Price differentiation rests on octane certification tiers, additive technology licensing, and geographic delivery cost differentials. Pricing pressure intensifies in the standard tier as ethanol blend mandates compress margins for non-integrated blenders. Fleet procurement centralization renders corporate fuel card holders least price-sensitive, while independent retail stations exhibit highest elasticity.
Supply Chain Analysis
Export-control regimes on hydrofluoric acid alkylation catalysts constrain refinery upgrade timelines and extend procurement lead times for independent processors. Geographic supply concentrates in the United States, Saudi Arabia, and Singapore, with crude feedstock dependencies on Middle Eastern sour grades and North American tight oil. Single-source vulnerability in catalyst supply chains threatens turnaround scheduling. Distribution runs through terminal-rack-retail networks with Gulf Coast hubs feeding Atlantic and Pacific basin markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gasoline market presents a defensive-moat story anchored in regulatory entrenchment. EPA Tier 3 and Euro 6 sulfur specifications create insurmountable compliance barriers that lock out new refining capacity and protect incumbent asset values.
For Market Incumbents: Insulate margin structures by accelerating alkylation unit investments ahead of octane specification tightening. Deepen backward integration into ethanol supply chains to capture RenovaBio and LCFS credit revenue streams. Battery electric vehicle penetration in passenger segments represents the primary substitution threat requiring marine and equipment segment diversification.
For New Entrants and Emerging Players: Retail network digitization in tier-2 Indian cities represents the most penetrable entry point, as suburban motorization outpaces branded station coverage. Marine fueling infrastructure in Southeast Asian archipelagos offers second-mover advantages where electrification economics fail. A fuel-card-integrated loyalty platform provides the necessary go-to-market angle to bypass incumbent supply security advantages.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed independent terminal operators facing ethanol compatibility replacement cycles. Long-term viability hinges on hydroprocessing capability positioning for carbon border adjustment regimes. The signal to watch is EU carbon intensity scoring implementation timelines for import gasoline.
| Strategic Initiative | Industry Significance |
|---|---|
| Alkylation Capacity Expansion | Captures octane premium margins as Euro 6 and EPA Tier 3 specifications tighten blendstock scarcity. |
| Retail Network Digitization | Mobile-integrated platforms reduce price elasticity for branded operators competing against unbranded independents. |
| Backward Integration into Ethanol | Sugarcane processing assets in Brazil lock in RenovaBio credit revenue and shield gasoline from direct displacement. |
| Marine Segment Diversification | Coastal vessel applications retain stable offtake as battery economics prove unworkable for high-utilization commercial watercraft. |
| Carbon Intensity Certification | Low-carbon pathway documentation qualifies for preferential treatment under emerging EU and UK import frameworks. |
Methodological Framework
The analysis maps regular, premium, ethanol-blend, and marine gasoline segments, each validated through refinery operations managers, retail network operators, fuel procurement officers at fleet centralization platforms, and terminal infrastructure engineers. Primary interviews combined with secondary validation from EPA regulatory filings, EIA throughput statistics, ANP blending reports, and BIS fuel quality notifications. Bottom-up refinery capacity modeling and top-down consumption elasticity estimates were triangulated to anchor volume projections.
Assumption sets held crude slate composition and regulatory enforcement timelines fixed while varying motorization rate trajectories and electrification penetration curves across the projection horizon. Segmentation dimensions modeled include fuel grade tier, end-use application, distribution channel architecture, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity utilization forecasts. Industry-specific inputs encompassed ethanol blend mandate floors and alkylation unit commissioning schedules.
Stress conditions across crude price volatility bands, catalyst supply disruption scenarios, and carbon border adjustment implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to biofuel mandate revisions and maritime transit route disruptions. Material shifts in battery electric vehicle adoption curves or refinery carbon intensity thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Smart Gas Market
Fuels
United States LNG Bunkering Market
Fuels
Fuel Conditioning System Market
Fuels
Hydrogen Tube Trailer Market
Fuels
LNG Filling Station Market
Fuels
Smart Gas Solutions Market
Fuels
Gasoline Octane Improvers Market
Fuels
Mobile Gas Pumping System Market
Fuels
Briquette Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
Global Charcoal Market
Fuels
North America Bunker Fuel Market
Fuels
City Gas Distribution Market
Fuels
Bituminous Coal Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
Anthracite Coal Mining Market