
 Industrial Radiography Equipment Market | 2026-2036
Industrial Radiography Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Radiography Equipment Market Outlook
Specialized industrial distributor networks is reshaping how radiography equipment reaches end users across heavy manufacturing clusters. General Electric Company leverages its turbine inspection heritage to dominate energy sector deployments. Fujifilm Holdings Corporation anchors digital detector supply through captive sensor fabrication. Baker Hughes Company specializes in pipeline integrity systems for oil and gas operators.
Industrial radiography equipment encompasses X-ray and gamma-ray systems engineered to detect subsurface defects in metallic and composite structures, typically operating at tube voltages from 10 kV to 450 kV with focal spot sizes below 3.0 mm for high-resolution imaging. Digital Radiography segments command premium positioning through real-time imaging capabilities that eliminate chemical processing, while Computed Radiography sustains mid-market penetration where legacy film workflows persist. Aerospace applications generate the fastest growth trajectory as airframe manufacturers enforce stricter porosity detection standards on additive-manufactured titanium components.
The U.S. Nuclear Regulatory Commission governs radioactive source licensing for gamma radiography operations, while OSHA enforces exposure limits that accelerate substitution toward electronic X-ray sources. The EU's F-Gas Regulation and CE marking under the Machinery Directive constrain equipment import and retrofit pathways across member states. Stakeholders must monitor evolving harmonization between ISO 17636 weld inspection standards and emerging AI-assisted defect recognition protocols.
Market Dynamics
The transition from film-based to digital detector architectures constitutes the dominant structural force reshaping competitive positioning, compressing inspection cycle times while eliminating chemical processing infrastructure and darkroom facilities from manufacturing sites.
Growth Catalysts
- Aerospace Porosity Mandates:Airframe manufacturers enforce stricter defect detection thresholds on additive-manufactured titanium structures, necessitating high-resolution digital radiography deployment across production lines.
- F-Gas Regulation:The European Union's phasedown of hydrofluorocarbon coolants accelerates replacement of legacy film processors with solid-state detector systems that eliminate refrigerant-dependent chemical baths.
- Pipeline Integrity Requirements:Oil and gas operators in the Permian Basin and North Sea expand inline inspection programs, driving gamma radiography procurement for corrosion mapping in subsea and buried infrastructure.
Market Restraints
- Isotope Supply Concentration:Cobalt-60 and Iridium-192 source production concentrates in Canadian and Russian irradiation facilities, exposing gamma radiography operators to geopolitical supply interruptions.
- Detector Material Cost Volatility:Selenium and cesium iodide crystal prices fluctuate with photovoltaic and medical imaging demand, compressing margins for flat-panel detector manufacturers.
- OSHA Exposure Limits:The U.S. Occupational Safety and Health Administration's stringent personnel dose thresholds restrict gamma source deployment in congested fabrication yards, favoring electronic X-ray alternatives.
Strategic Opportunities
- AI-Assisted Defect Recognition:Machine learning algorithms trained on ISO 17636 weld image libraries enable automated porosity and crack classification, reducing interpreter certification burdens.
- India Manufacturing Corridor:Reliance Industries and Tata Steel expand specialty alloy production in Hazira and Jamshedpur, creating greenfield demand for in-process radiography systems.
- Drone-Mounted Crawlers:Magnetic adhesion robots carrying miniaturized X-ray sources access storage tank shells and wind turbine towers without scaffolding, opening inspection services to asset operators directly.
Industry Challenges
- Level II Radiographer Certification Bottlenecks:The American Society for Nondestructive Testing and BINDT in the United Kingdom report twelve-month backlogs for practical examination slots, constraining field crew scaling.
- Legacy Film Archive Migration:Decades of radiographic film records require digitization for regulatory retention compliance, burdening operators with capital-intensive scanning infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Radiography Equipment Market |
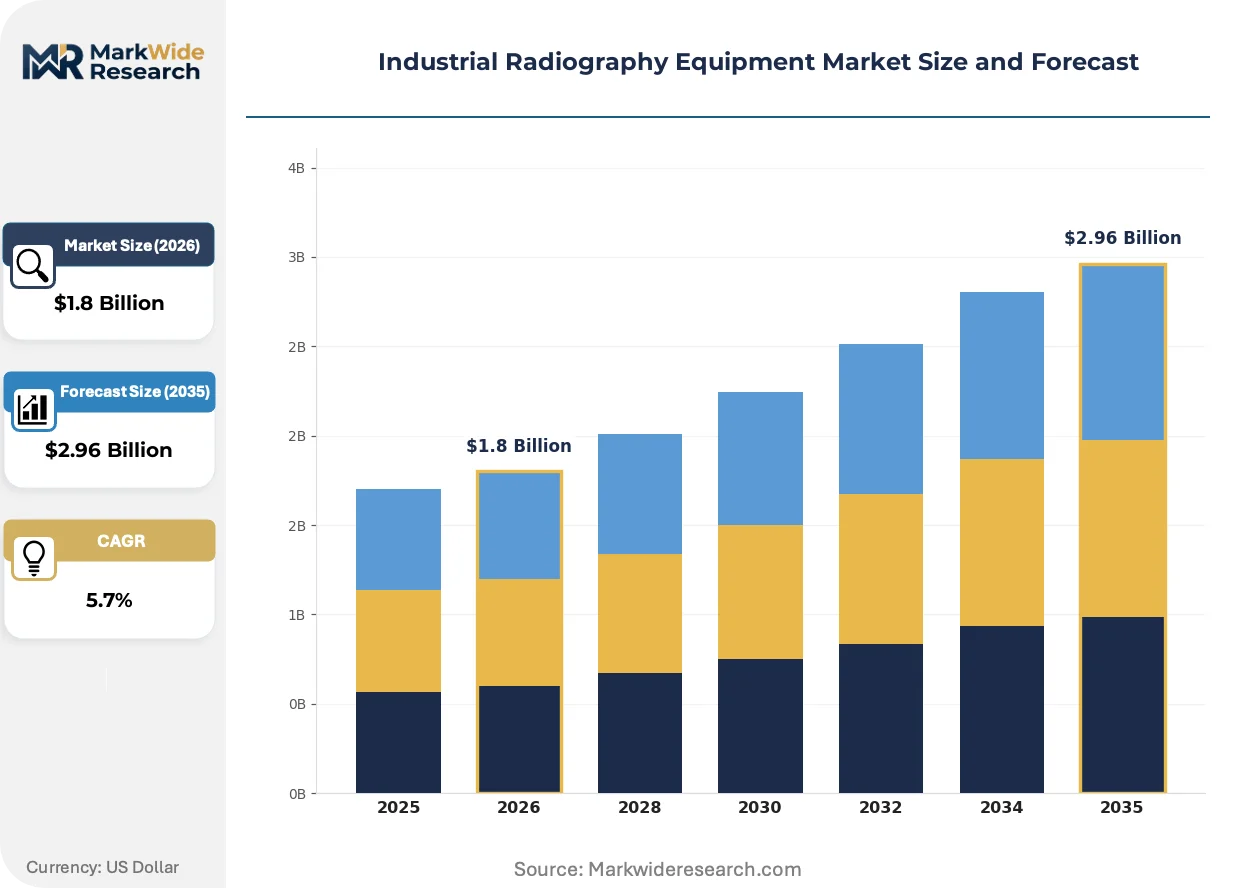
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Detectors, Radiographic Systems, Mobile Radiography Units, Accessories Technology: Digital Radiography, Computed Radiography, Film Radiography, Non-Destructive Testing Application: Aerospace, Automotive, Oil & Gas, Manufacturing End User: Inspection Agencies, Energy Sector, Manufacturing Companies, Service Providers |
| Companies Covered | General Electric Company, Fujifilm Holdings Corporation, Baker Hughes Company, Nikon Corporation, Shimadzu Corporation, Comet Holding AG, Waygate Technologies GmbH, Mettler-Toledo International, Inc., Rigaku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Radiography Equipment Market Strategic Shifts
Digital detector architectures are collapsing the traditional tradeoff between image resolution and inspection throughput, enabling real-time feedback loops that integrate directly with manufacturing execution systems.
Photon-counting CdTe sensors are collapsing the distinction between radiography and computed tomography by delivering energy-resolved imaging in single exposures. Aerospace NDT departments at Boeing and Airbus facilities adopt these detectors for simultaneous porosity and density mapping in titanium additive builds. The technology is collapsing equipment consolidation timelines as single platforms replace separate film, CR scanner, and CT system investments.
The EU F-Gas Regulation mandates refrigerant phase-down schedules that directly impact film processor cooling systems, forcing processors toward thermal management redesigns or abandonment. Equipment lessors in Germany and France now bundle detector upgrades with chemical processing decommissioning services. The regulation most acutely affects small-to-mid fabrication shops in Poland and Czechia where legacy film workflows persist.
Service unbundling now separates equipment ownership from certified interpreter labor, with specialized NDE contractors deploying their own personnel to operate customer-owned systems. This model displaces full-service radiography providers in the Gulf Coast petrochemical corridor, where operators prefer capital-light inspection partnerships. The shift is most visible in Texas and Louisiana, where turnaround maintenance cycles compress and specialized crews rotate between facilities.
Industrial Radiography Equipment Market Segmentation
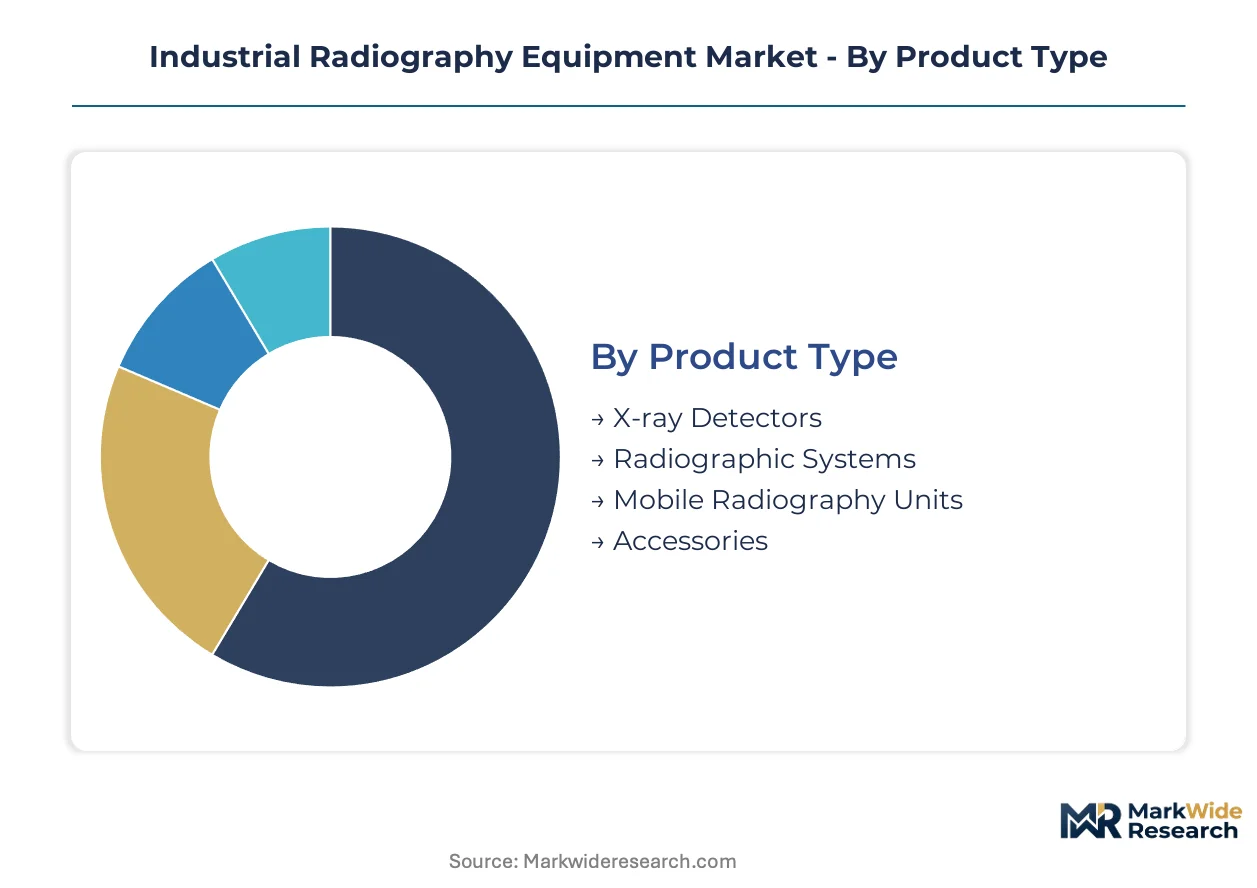
Equipment configurations vary sharply across inspection environments, from fixed gantry systems in aerospace production lines to portable gamma crawlers accessing subsea pipelines. Understanding these segment boundaries clarifies why technology choices diverge between high-volume manufacturing and asset integrity services.
Product Type:
Use-case spectrum spans precision laboratory benches through explosion-proof field crawlers, with mobility requirements dictating hardware architecture decisions.
- X-ray Detectors:Flat-panel amorphous selenium arrays and CMOS photodiode matrices convert ionizing radiation directly into digital signals. Demand concentrates in Germany's industrial corridor spanning Munich, Stuttgart, and Hamburg, where automotive OEMs mandate real-time weld verification.
- Radiographic Systems:Integrated source-detector platforms with automated positioning stages enable repeatable inspection protocols. Aerospace manufacturers in Toulouse and Hamburg drive procurement for gantry-mounted systems inspecting additive-manufactured titanium structures.
- Mobile Radiography Units:Battery-powered X-ray sources on crawler chassis access pipeline segments without excavation.
- Accessories:Collimators, calibration phantoms, and radiation shielding enclosures complete operational readiness.
The dominant share belongs to Radiographic Systems, while Mobile Radiography Units are closing the gap fastest.
Technology:
Cost tier differentiation separates capital-intensive solid-state platforms from legacy chemical processing workflows.
- Digital Radiography:Direct-readout flat panels eliminate intermediate conversion steps, delivering 16-bit grayscale resolution at frame rates exceeding 30 fps. Oil and gas operators in the Permian Basin and North Sea expand procurement for corrosion mapping applications.
- Computed Radiography:Photostimulable phosphor plates bridge analog exposure and digital workflow, sustaining mid-market penetration where legacy film infrastructure persists.
- Film Radiography:Silver halide emulsions on polyester substrates retain regulatory acceptance in pressure vessel certification.
- Non-Destructive Testing:Ultrasonic and eddy-current modalities complement radiographic methods in multi-technique inspection protocols.
Digital Radiography commands the premium tier, while Computed Radiography maintains installed base loyalty.
Application:
Customer type concentration shapes equipment specification priorities across sector-specific defect tolerance thresholds.
- Aerospace:Porosity detection in electron-beam-melted titanium demands sub-100-micron spatial resolution. Boeing and Airbus facilities adopt photon-counting CdTe sensors for simultaneous density mapping.
- Automotive:High-throughput chassis weld inspection favors linear detector arrays with automated part handling.
- Oil & Gas:Subsea pipeline integrity programs require gamma radiography for corrosion wall-thickness measurement in flooded environments.
- Manufacturing:General fabrication shops balance equipment versatility across mixed alloy portfolios.
Aerospace generates the steepest expansion trajectory, while Oil & Gas sustains replacement cycle volume.
End User:
Volume concentration clusters around third-party inspection contractors serving asset operators directly.
- Inspection Agencies:Certified NDE contractors deploy portable equipment across multiple client sites, with Level II radiographer certification backlogs constraining crew scaling in Texas and Louisiana.
- Energy Sector:Utility operators and pipeline owners favor capital-light service partnerships over in-house radiography departments.
- Manufacturing Companies:In-process quality control integration drives fixed-system investment in specialty alloy production.
- Service Providers:Equipment lessors in Germany and France bundle detector upgrades with chemical processing decommissioning services.
Inspection Agencies hold the dominant share, while Service Providers are gaining share fastest through unbundled ownership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial corridor while procurement costs in India's Hazira-Jamshedpur belt run 15-20% below Western benchmarks for equivalent detector specifications. This asymmetry shapes equipment sourcing strategies across multinational inspection contractors.
United States
OSHA's stringent personnel dose thresholds restrict gamma source deployment in congested Gulf Coast fabrication yards, accelerating substitution toward electronic X-ray alternatives. The U.S. Nuclear Regulatory Commission governs radioactive source licensing for gamma radiography operations. Inspection demand clusters in Texas and Louisiana, where turnaround maintenance cycles compress and specialized crews rotate between petrochemical facilities.
Germany
Automotive OEMs in Munich, Stuttgart, and Hamburg mandate real-time weld verification, driving concentrated procurement of flat-panel detector systems. The EU's F-Gas Regulation mandates refrigerant phase-down schedules that directly impact film processor cooling systems, forcing processors toward thermal management redesigns. Equipment lessors now bundle detector upgrades with chemical processing decommissioning services across the industrial corridor.
China
Specialty alloy production expansion in the Yangtze River Delta and Pearl River Delta generates greenfield demand for in-process radiography systems. The country's national industrial safety regulator enforces exposure limits that mirror OSHA thresholds, favoring digital detector adoption. Manufacturing execution system integration accelerates in Shanghai-Suzhou industrial parks, where real-time quality feedback loops collapse inspection cycle times.
India
Reliance Industries and Tata Steel expand specialty alloy production in Hazira and Jamshedpur, creating demand for radiography systems in steel and petrochemical fabrication. The Bureau of Indian Standards enforces weld inspection protocols aligned with ISO 17636. Procurement concentrates in Gujarat and Jharkhand, where greenfield capacity additions outpace legacy equipment replacement cycles in mature manufacturing regions.
United Kingdom
BINDT reports twelve-month backlogs for Level II radiographer practical examination slots, constraining field crew scaling across North Sea oil and gas operations. The Health and Safety Executive enforces exposure limits comparable to OSHA thresholds. Inspection demand clusters in Aberdeen and the Humber estuary, where subsea pipeline integrity programs require gamma radiography for corrosion wall-thickness measurement.
Industrial Radiography Equipment Market Competitive Environment
Integrated industrial conglomerates and specialized detector fabricators split the market along technology-integration fault lines. The vendor base concentrates around three strategic archetypes: diversified multinationals leveraging turbine and aerospace heritage, captive sensor manufacturers with in-house crystal growth capabilities, and pure-play NDE contractors unbundling equipment ownership from certified labor. Dominant competitive moves include strategic partnerships between detector OEMs and inspection service platforms, plus geographic expansion through equipment leasing models that displace full-service radiography providers.
Among diversified industrial conglomerates, General Electric Company and Baker Hughes Company exemplify the integrated-systems archetype, with the former representing turbine-inspection heritage and the latter anchoring pipeline-integrity specialization. Fujifilm Holdings Corporation occupies a distinct position as a captive sensor fabricator with direct control over phosphor plate and flat-panel production. These three entities collectively illustrate how technology integration depth separates premium-tier positioning from mid-market equipment supply.
| Leading Market Players |
|---|
| General Electric Company |
| Fujifilm Holdings Corporation |
| Baker Hughes Company |
| Nikon Corporation |
| Shimadzu Corporation |
| Comet Holding AG |
| Waygate Technologies GmbH |
| Mettler-Toledo International, Inc. |
| Rigaku Corporation |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Antwerp chemical corridor's freight cost volatility amplifies price spreads between configured-to-order digital detector systems and standard flat-panel arrays, compressing margins for European distributors while rewarding German manufacturers with captive sensor fabrication.
Pricing Analysis
The customization-premium spread between configured-to-order gantry systems and standard portable units reaches three-to-one multiples, with aerospace-specified photon-counting CdTe sensors commanding certification-grade premiums over amorphous selenium alternatives. Price differentiation hinges on ISO 17636 compliance tier and detector resolution specification, with flat-panel manufacturers absorbing selenium crystal cost volatility rather than passing through to automotive OEMs. Pricing pressure stems from detector material cost swings in photovoltaic-linked supply chains, squeezing mid-tier CR scanner vendors most acutely while premium digital radiography holds firm.
Supply Chain Analysis
Contract manufacturing for flat-panel detector assemblies concentrates in South Korean and Taiwanese electronics foundries, with Japanese crystal growers supplying cesium iodide scintillator inputs. Raw material dependencies center on selenium ingots, rare-earth phosphors, and high-purity silicon substrates. Single-source vulnerability runs through Russian and Canadian irradiation facilities producing Cobalt-60 and Iridium-192 gamma sources. Distribution runs through specialized industrial distributor networks anchored in Germany's Munich-Stuttgart-Hamburg corridor and the US Gulf Coast petrochemical belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where AI-assisted defect recognition protocols threaten to unbundle interpreter expertise from equipment ownership, rewarding vendors who control both sensor fabrication and algorithm training data.
For Market Incumbents: Pre-empt service unbundling by integrating certified interpreter labor into equipment lease bundles, mirroring the German lessor model that couples detector upgrades with chemical processing decommissioning. Deepen backward integration into phosphor plate and flat-panel production to defend against selenium cost volatility, while accelerating photon-counting CdTe roadmaps before aerospace mandates harden. For New Entrants and Emerging Players: Establish a beachhead in India's Hazira-Jamshedpur manufacturing corridor where Reliance Industries and Tata Steel greenfield investments outpace legacy equipment replacement cycles. Target drone-mounted crawler inspection services for wind turbine and storage tank applications, bypassing the Level II radiographer certification bottlenecks that constrain incumbent scaling in Texas and Louisiana. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors captive sensor fabricators with direct crystal growth capabilities over pure-play system integrators, as detector material cost volatility and F-Gas regulatory compliance deepen competitive moats. The signal to watch is BINDT and ASNT certification backlogs—prolonged examination delays indicate sustained pricing power for interpreter-integrated service models.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Defect Recognition Development | Machine learning algorithms trained on ISO 17636 weld libraries collapse interpreter certification burdens for aerospace NDT departments. |
| Detector Upgrade Bundling with Decommissioning Services | German and French equipment lessors capture recurring revenue from F-Gas-driven film processor replacement cycles. |
| Drone-Mounted Crawler Platform Launch | Magnetic adhesion robots accessing wind turbine towers displace scaffolding-dependent inspection providers in North Sea operations. |
| Backward Integration into Crystal Growth | Fujifilm's captive cesium iodide production insulates margins from photovoltaic demand swings in selenium markets. |
| India Manufacturing Corridor Expansion | Greenfield radiography system deployment at Hazira and Jamshedpur specialty alloy plants outpaces legacy replacement in mature regions. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of NRC licensing records, EU F-Gas Regulation implementation reports, and ISO 17636 technical committee documentation, with bottom-up equipment shipment data triangulated against top-down end-user procurement surveys. Primary interviews engaged Level II radiographer certification directors at ASNT and BINDT, maintenance directors at Permian Basin pipeline operators, and procurement leads at Toulouse and Hamburg aerospace facilities. Secondary sources included OSHA exposure limit enforcement data, customs records for selenium and cesium iodide trade flows, and hospital radiography department capital expenditure disclosures.
Forecast inputs span tube voltage configuration, detector technology tier, mobility classification, and end-use sector concentration across the projection horizon. Segmentation modeling incorporates product type, technology architecture, application severity, and customer ownership structure. CAGRs derive from equipment replacement cycle analysis, regulatory compliance deadline mapping, and greenfield capacity addition tracking in specialty alloy production corridors.
Stress conditions across isotope supply interruption, selenium price spikes, and OSHA exposure limit tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of ASNT examination slot availability, F-Gas refrigerant phase-down schedules, and aerospace additive manufacturing capacity buildouts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Medical Imaging Outsourcing Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market
Medical Imaging
Germany Nuclear Imaging Market
Medical Imaging
Intravascular Imaging Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
US Medical Imaging Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
Brazil Diagnostic Imaging Equipment Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market