
 Computed Tomography (CT) Scanners Market | 2026-2036
Computed Tomography (CT) Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Computed Tomography (CT) Scanners Market Analysis
Japanese component manufacturing is decoupling from legacy Western supply chains as domestic producers expand detector fabrication capacity. Siemens Healthineers leverages its Erlangen engineering base to sustain dual-energy CT development. GE Healthcare anchors North American service contracts through predictive maintenance platforms. Canon Medical Systems differentiates via detector integration that reduces scan acquisition times.
Computed tomography scanners generate cross-sectional anatomical images through rotating X-ray tube-detector assemblies, with modern systems achieving sub-millimeter spatial resolution at reduced radiation exposure through iterative reconstruction algorithms. Helical CT technology dominates installed bases due to continuous patient table translation during gantry rotation, while dual-energy CT captures fastest-growing interest among academic medical centers seeking material decomposition for lesion characterization. Flat panel CT occupies emerging niches in intraoperative imaging where cone-beam geometry enables compact system design.
The FDA regulates CT device premarket clearance through 510(k) and PMA pathways, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for new system approvals. ISO 13485 quality management standards govern manufacturing processes across all major production sites. Stakeholders must monitor reimbursement code revisions for cardiac CT angiography, as these determine hospital capital allocation priorities for scanner replacement cycles.
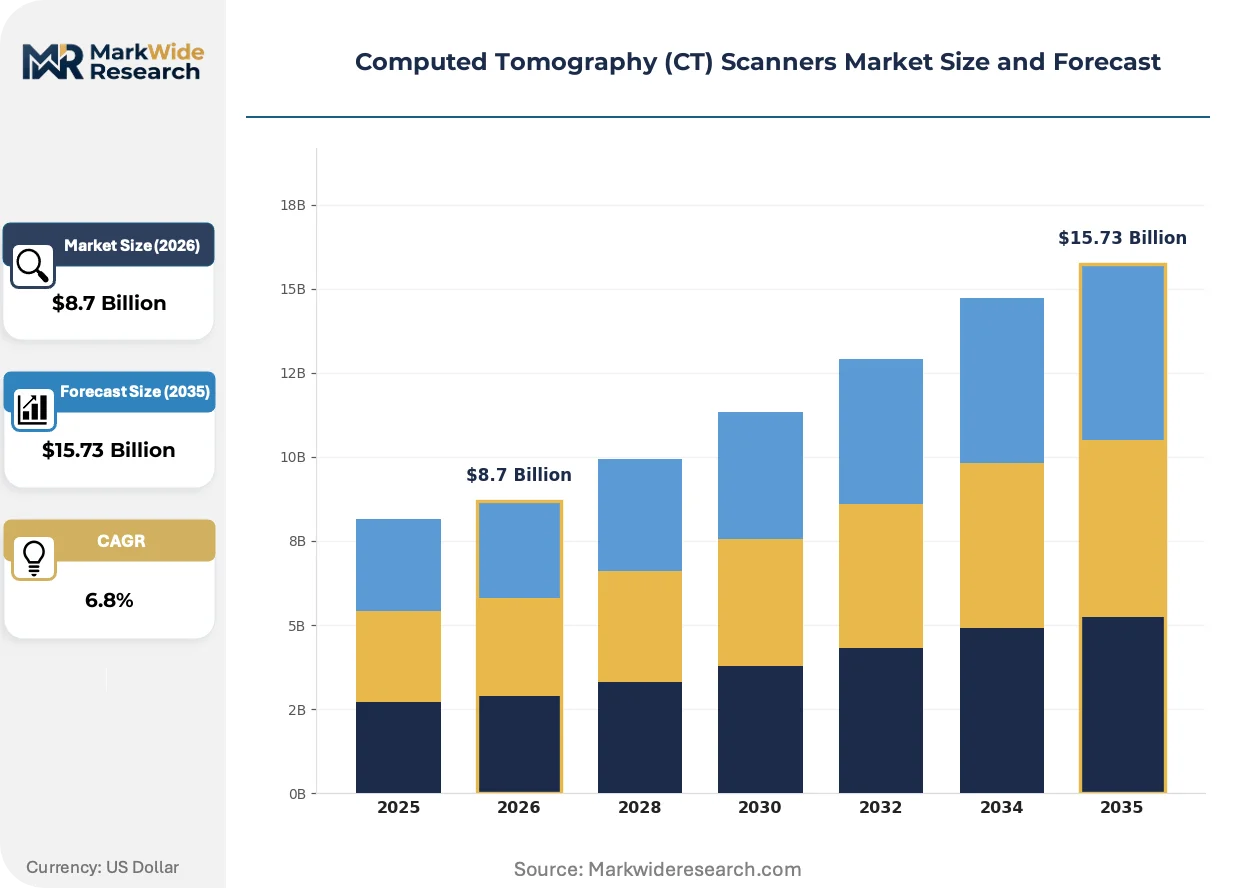
Market Dynamics
Dual-energy CT is absorbing capital allocation as academic medical centers prioritize material decomposition capabilities for lesion characterization, while FDA radiation dose guidelines force equipment replacement cycles ahead of natural depreciation schedules.
Growth Catalysts
- Oncology Screening Protocols:Hospital systems are expanding CT fleet capacity to meet rising cancer detection mandates. Radiology departments prioritize helical systems for throughput efficiency.
- EU Medical Device Regulation:Stricter clinical evidence requirements for new system approvals are accelerating R&D investment in iterative reconstruction algorithms. Manufacturers pursue PMA-equivalent pathways to capture premium positioning.
- Intraoperative Imaging Demand:Flat panel CT with cone-beam geometry is penetrating surgical suites for real-time anatomical guidance. Compact system design enables installation in space-constrained hybrid operating rooms.
Market Restraints
- Detector Supply Concentration:Japanese component manufacturers dominate scintillator crystal fabrication, creating vulnerability to export restrictions or capacity constraints. Western OEMs face extended lead times for dual-energy detector arrays.
- Capital Intensity Barriers:Helical CT systems require substantial infrastructure investment including shielded suite construction and power conditioning. Community hospitals delay replacement cycles due to financing constraints.
- Substitution from MRI:Magnetic resonance imaging captures soft-tissue applications previously assigned to CT, particularly in neurovascular and musculoskeletal diagnostics. Radiation exposure concerns accelerate this displacement in pediatric populations.
Strategic Opportunities
- German University Hospital Networks:Modernization programs across Bavaria and Baden-Württemberg create replacement demand for 256-slice systems. Procurement frameworks favor vendors with local service infrastructure.
- Predictive Maintenance Platforms:AI-driven remote monitoring enables unbundling of service contracts from hardware sales. Independent service organizations capture margin from legacy installed bases.
- Photon-Counting Detector Convergence:Direct conversion technology integrated with dual-energy acquisition protocols promises dose reduction below iterative reconstruction thresholds. Early adopters in Switzerland and Austria are validating clinical protocols.
Industry Challenges
- Iterative Reconstruction Expertise Gap:Clinical engineers lack training in algorithm parameter optimization for dose reduction protocols. Manufacturers must embed automated tuning to prevent image quality degradation.
- ISO 13485 Certification Timelines:Quality management system audits for detector fabrication facilities extend 18-24 months. Startups face capital depletion before first commercial shipment.
- Legacy PACS Integration Complexity:New CT systems must interface with decade-old picture archiving infrastructure. Hospital IT departments resist middleware investments that delay go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computed Tomography (CT) Scanners Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone CT, Mobile CT, Computed Tomography Angiography, Cone Beam CT Technology: Helical CT, Flat Panel CT, Dual Energy CT, High-Performance CT End User: Hospitals, Diagnostic Imaging Centers, Academic Institutions, Research Facilities Application: Oncology, Neurology, Cardiology, Orthopedics |
| Companies Covered | Philips Healthcare, Hitachi Healthcare, Siemens Healthineers, Shimadzu Corporation, United Imaging Healthcare, GE Healthcare, NeuroLogica Corp., Neusoft Medical Systems, Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computed Tomography (CT) Scanners Market Emerging Trajectories
Photon-counting detector technology is absorbing engineering resources as manufacturers race to commercialize direct conversion architectures before competitors lock in hospital procurement decisions for the next replacement cycle.
Photon-counting CT is absorbing development priority across all major engineering centers. The technology eliminates electronic noise through direct X-ray photon measurement, enabling spectral imaging at diagnostic dose levels below one millisievert. Siemens Healthineers leverages its Erlangen base to accelerate clinical validation, while academic centers in Germany and Switzerland establish reference protocols. The structural consequence is compression of conventional energy-integrating detector margins as premium pricing migrates to photon-counting platforms.
FDA updated radiation dose guidelines are reshaping procurement criteria for United States hospital systems. The regulatory framework mandates diagnostic reference levels and requires dose reporting infrastructure as a 510(k) clearance condition. Community hospitals face accelerated obsolescence of pre-2020 installed bases, while vendors redesign gantry architectures to meet new technical standards. Cardiac CT angiography reimbursement code revisions determine capital allocation timing across integrated delivery networks.
Service contract unbundling is disrupting traditional vendor-captive revenue models in North American and Western European markets. Independent service organizations now capture preventive maintenance for helical CT systems beyond warranty periods, using third-party detector calibration tools. GE Healthcare responds with predictive analytics platforms that demonstrate uptime guarantees, while hospital procurement committees evaluate total cost of ownership over seven-year depreciation schedules. This behavioral shift concentrates in Germany and the United States where installed base density supports third-party technician networks.
Computed Tomography (CT) Scanners Market Segmentation
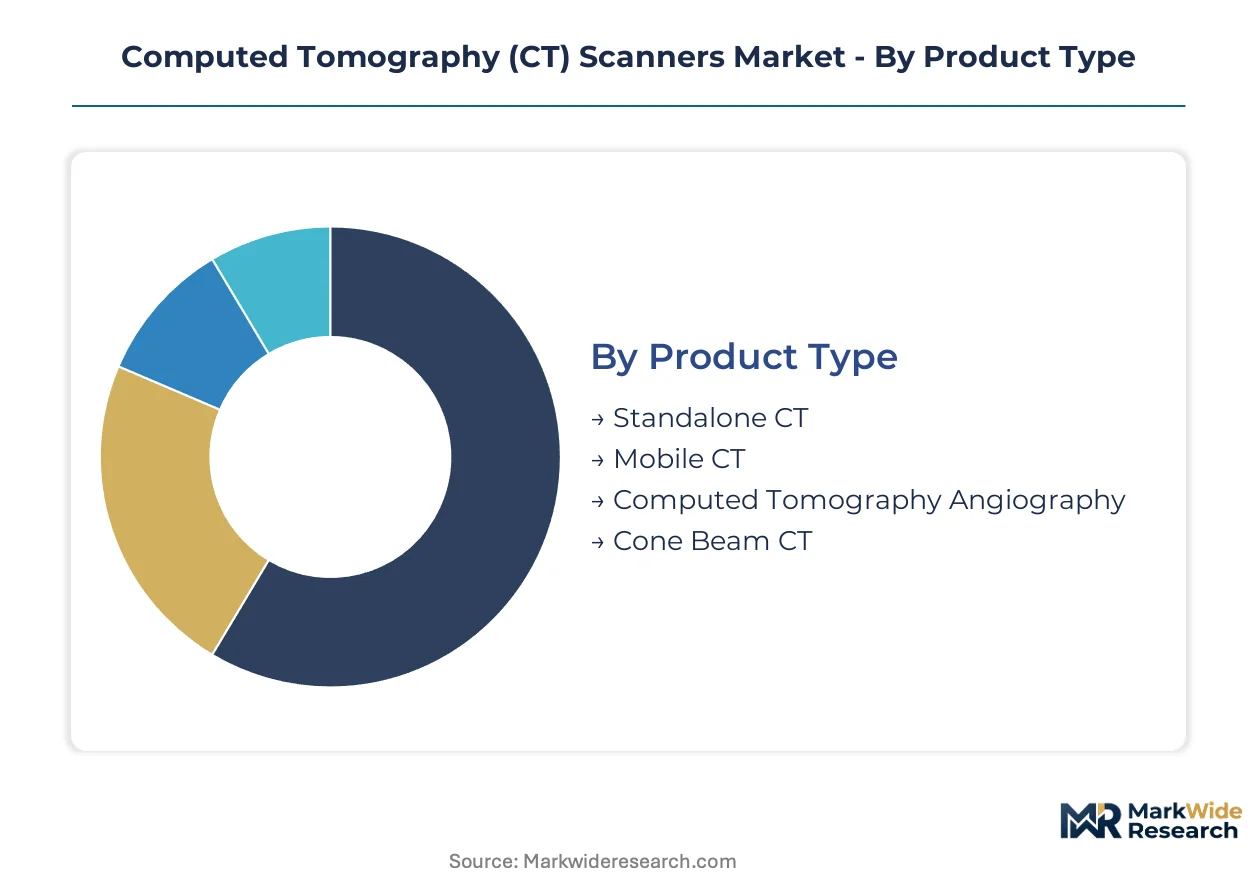
CT scanner procurement decisions cluster around upgrade cycles driven by detector technology transitions and radiation dose compliance mandates. Hospital capital committees evaluate segment choices against replacement timelines that compress from traditional ten-year cycles toward seven-year intervals.
Product Type:
Replacement cycles vary sharply across product formats as shielded suite requirements and mobility needs reshape capital allocation priorities.
- Standalone CT:Fixed-room installations with full gantry enclosures dominate hospital infrastructure planning. German university hospital networks prioritize 256-slice configurations for throughput optimization.
- Mobile CT:Trailer-mounted or self-propelled units enable temporary deployment to satellite clinics and emergency surge capacity. Demand concentrates in rural United States health systems seeking to extend screening access without permanent construction.
- Computed Tomography Angiography:Cardiac-optimized protocols with ECG-gated acquisition. Reimbursement code revisions determine hospital investment timing for coronary imaging programs.
- Cone Beam CT:Compact C-arm geometry for intraoperative three-dimensional guidance. Flat panel detector integration enables installation in space-constrained hybrid operating rooms.
Standalone CT sits at the top of the volume ranking, with Mobile CT climbing the fastest as rural access mandates expand.
Technology:
Detector architecture choices determine dose efficiency thresholds and spectral imaging capabilities that differentiate procurement tiers.
- Helical CT:Continuous patient table translation during gantry rotation enables volumetric acquisition without interscan delays. Installed base concentration in community hospitals sustains service contract revenue for legacy energy-integrating detectors.
- Dual Energy CT:Simultaneous high-low kVp acquisition enables material decomposition for lesion characterization. Academic medical centers in Switzerland and Austria validate photon-counting convergence protocols.
- Flat Panel CT:Cone-beam geometry with large-area digital detectors for intraoperative imaging. Surgical suite integration demands compact footprint design and rapid reconstruction pipelines.
- High-Performance CT:Sub-millisecond temporal resolution for cardiac and pediatric applications. FDA radiation dose guidelines accelerate displacement of pre-2020 installed bases.
Helical CT maintains the largest installed footprint, though Dual Energy CT expands most quickly among academic procurement frameworks.
End User:
Capital intensity and clinical volume thresholds segment customers into distinct purchasing behaviors and service contract structures.
- Hospitals:Integrated delivery networks with dedicated radiology departments and shielded suite infrastructure. Oncology screening protocol expansion drives fleet capacity decisions.
- Diagnostic Imaging Centers:Outpatient-focused facilities with high throughput requirements and lean technical staffing. Independent service organizations capture preventive maintenance beyond warranty periods.
- Academic Institutions:University-affiliated medical centers prioritizing research protocols and spectral imaging capabilities. Dual-energy and photon-counting validation programs concentrate here.
- Research Facilities:Preclinical and translational imaging centers with small-animal or specimen-focused systems. Custom reconstruction algorithm development supports grant-funded procurement.
Hospitals command the greatest absolute unit demand, while Diagnostic Imaging Centers gain share fastest through outpatient volume migration.
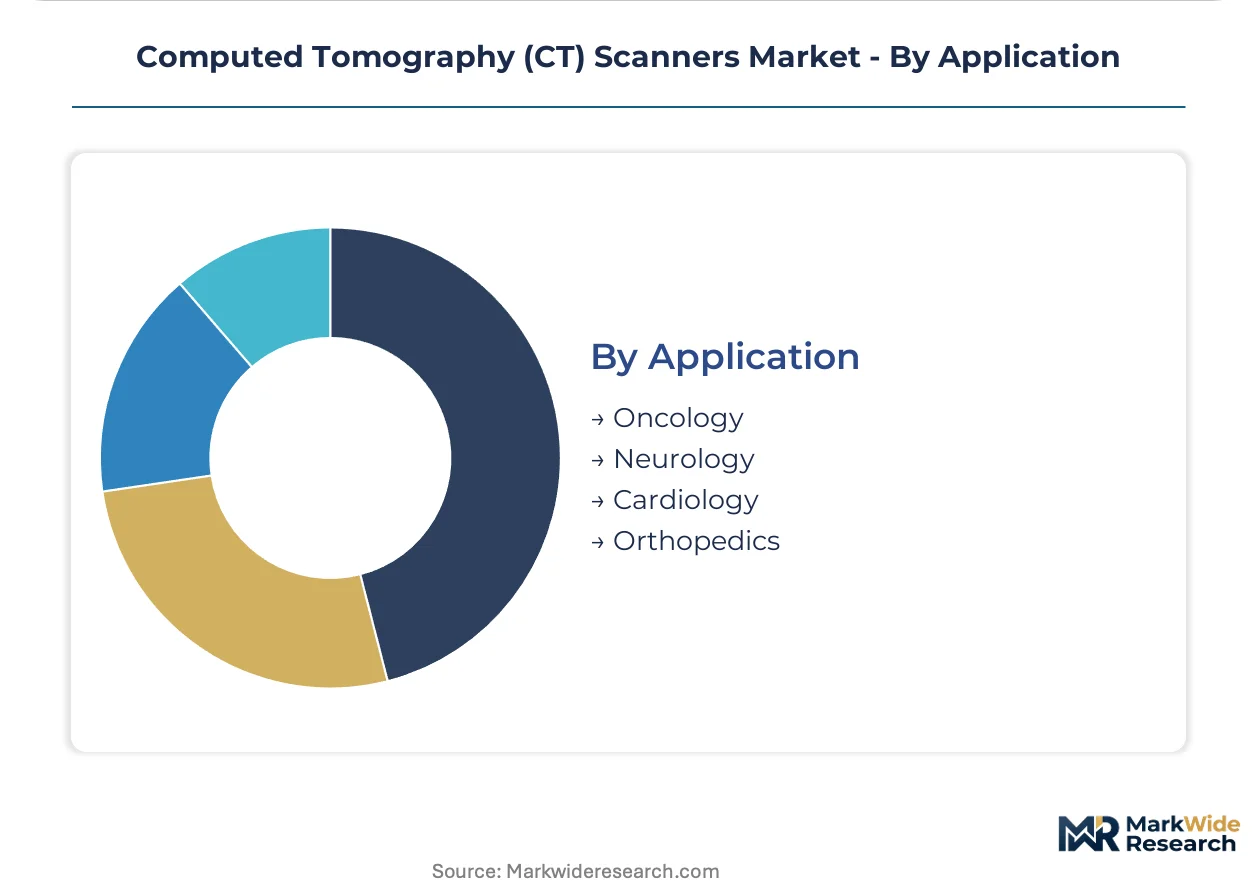
Application:
Clinical indication specialization determines slice count requirements, contrast protocols, and reimbursement pathways that shape equipment specification.
- Oncology:Low-dose lung cancer screening and staging protocols with iterative reconstruction algorithms. Rising detection mandates expand CT fleet capacity across hospital systems.
- Neurology:Perfusion imaging and stroke protocol optimization with sub-minute acquisition windows. MRI substitution pressure concentrates in pediatric populations.
- Cardiology:Coronary CT angiography with ECG-gated dose modulation. Reimbursement code stability determines capital allocation timing.
- Orthopedics:Weight-bearing extremity imaging and preoperative planning for joint replacement. Flat panel CT penetration in surgical suites supports intraoperative guidance.
Oncology leads application-specific procurement volume, with Cardiology showing steepest expansion trajectory as coronary imaging protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's university hospital networks modernize imaging infrastructure at faster replacement cycles than Japan's concentrated detector fabrication hubs, where domestic producers expand capacity to serve regional OEM demand.
United States
Hospital systems expand CT fleet capacity to meet rising oncology screening mandates across integrated delivery networks. The FDA's updated radiation dose guidelines reshape procurement criteria and accelerate obsolescence of pre-2020 installed bases. Boston and Cleveland medical clusters prioritize 256-slice helical configurations for throughput optimization.
Germany
Bavaria and Baden-Württemberg university hospital networks drive replacement demand for dual-energy and photon-counting systems. The EU Medical Device Regulation imposes stricter clinical evidence requirements that accelerate R&D investment in iterative reconstruction algorithms. Erlangen anchors Siemens Healthineers engineering operations for spectral imaging development.
Japan
Domestic component manufacturers decouple from legacy Western supply chains as scintillator crystal fabrication capacity expands. The PMDA governs premarket approval pathways for new detector architectures. Tokyo and Kyoto production clusters concentrate flat panel detector integration for intraoperative imaging systems.
Switzerland
Academic medical centers in Zurich and Bern validate photon-counting convergence protocols for material decomposition applications. Swissmedic regulates clinical evidence standards for premium-tier system approvals. Basel-region procurement frameworks favor vendors with predictive maintenance infrastructure.
China
Domestic OEMs capture share in diagnostic imaging centers through localized service networks and cost-optimized helical platforms. The NMPA streamlines 510(k)-equivalent clearance pathways for iterative reconstruction algorithms. Shanghai and Shenzhen manufacturing clusters scale detector assembly for regional hospital procurement.
Computed Tomography (CT) Scanners Market Vendor Landscape
German and Japanese producers anchor one tier; United States and Chinese specialists hold differentiated positions through service infrastructure and cost engineering. The vendor base concentrates around engineering-intensive detector development and predictive maintenance platform deployment. Three archetypes dominate: diversified healthcare conglomerates with captive imaging divisions, pure-play diagnostic equipment manufacturers, and component-integrated regional challengers. Capacity expansion in photon-counting detector fabrication and strategic partnerships for AI-driven reconstruction algorithms represent the dominant competitive vectors.
Within the diversified healthcare conglomerate tier, Siemens Healthineers and GE Healthcare exemplify integrated engineering and service scale. Philips Healthcare occupies a position emphasizing diagnostic workflow integration across hospital systems. Among Asia-Pacific specialists, Canon Medical Systems and Hitachi Healthcare represent detector technology and compact system design archetypes respectively. Shimadzu Corporation anchors the precision instrumentation segment with concentrated focus on flat panel CT for surgical applications.
| Leading Market Players |
|---|
| Philips Healthcare |
| Hitachi Healthcare |
| Siemens Healthineers |
| Shimadzu Corporation |
| United Imaging Healthcare |
| GE Healthcare |
| NeuroLogica Corp. |
| Neusoft Medical Systems |
| Canon Medical Systems Corporation |
| Others |
Supply Flow & Price Mechanics
Captive integration of scintillator crystal fabrication in Japan anchors both supply security and premium pricing power for dual-energy detector arrays. Western OEMs face extended lead times and compressed margins as domestic Japanese producers prioritize regional hospital procurement frameworks over export commitments.
Pricing Analysis
Capacity additions in Japan are reshaping price floors for energy-integrating detectors as domestic fabrication scales to serve regional OEM demand. Three-tier pricing structure across photon-counting premium, dual-energy standard, and helical economy levels stratifies procurement tiers. Cost compression in economy helical systems is intensifying because Chinese manufacturers capture share through localized service networks. Community hospitals exhibit highest price sensitivity, while academic medical centers prioritize spectral imaging capabilities over unit cost.
Supply Chain Analysis
Regional distribution centers in Erlangen, Tokyo, and Milwaukee coordinate hub-and-spoke patterns for gantry assemblies and detector modules. Manufacturing concentrates in Germany, Japan, and China, with scintillator crystal growth and flat panel detector integration as critical inputs. Single-source vulnerability in scintillator supply creates exposure to export licensing shifts. Distribution runs through hospital GPO contracts and direct OEM service agreements that bundle preventive maintenance with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CT scanner market compounds steadily as oncology screening mandates drive replacement cycles across hospital networks. Detector technology transitions and radiation dose compliance compress depreciation schedules toward seven-year intervals.
For Market Incumbents: Hedge against photon-counting convergence by accelerating clinical validation partnerships with Swiss and Austrian academic centers. Secure backward integration into detector fabrication through strategic alliances with Japanese component manufacturers. MRI substitution in pediatric neurovascular applications threatens helical system volumes in community hospitals.
For New Entrants and Emerging Players: Enter via mobile CT trailer deployments in rural United States health systems seeking screening access without permanent infrastructure investment. Target diagnostic imaging centers with lean technical staffing and high throughput requirements. Unbundle service contracts using third-party detector calibration tools and AI-driven remote monitoring platforms.
For Investors and Strategic Acquirers: Roll-up economics work for independent service organizations because installed base density in Germany and the United States supports technician network scalability. Five-to-ten year viability hinges on predictive maintenance platform deployment and legacy system parts harvesting. Monitor FDA reimbursement code revisions for cardiac CT angiography as capital allocation timing signal across integrated delivery networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Commercialization | Siemens Healthineers leverages Erlangen engineering to validate direct conversion architectures below one millisievert diagnostic dose. |
| Predictive Maintenance Platform Deployment | GE Healthcare anchors North American service contracts through AI-driven uptime guarantees and remote gantry monitoring. |
| Hospital System Partnership | Canon Medical Systems secures Bavaria procurement frameworks via detector integration reducing scan acquisition times. |
| CE Marking Pathway Investment | EU Medical Device Regulation imposes stricter clinical evidence requirements accelerating iterative reconstruction R&D spend. |
| Reimbursement Strategy Development | Cardiac CT angiography code revisions determine capital allocation timing across United States integrated delivery networks. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and radiology department heads. Secondary validation draws from FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up unit demand modeling triangulates against top-down capital expenditure estimates from integrated delivery network disclosures.
Granularity-level modeling disaggregates volume and value across product type, technology architecture, end-user facility class, and clinical application indication throughout the forecast period. CAGRs derive from replacement cycle compression analysis and detector technology transition curves. Forecast inputs incorporate radiation dose guideline revision impacts and photon-counting adoption thresholds validated through academic medical center protocol development.
Inputs from regulatory filing databases and hospital capital budget disclosures were available through the study window; gaps in real-time procurement pipeline visibility introduce uncertainty bands around near-term unit shipment estimates. Forecasts reflect documented assumptions regarding reimbursement stability and detector fabrication capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
AI Radiology Worklist Orchestration Market
Medical Imaging
Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
Urology Imaging Systems Market
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market
Medical Imaging
Industrial X-Ray Machine Market
Medical Imaging
Global AI for Radiology Market
Medical Imaging
Fluorescence Microscopy Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
India Computed Tomography Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market