
 North America Surgical Microscopes Market | 2026-2036
North America Surgical Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Surgical Microscopes Market Insights
Ambulatory surgery centers is consolidating as a procurement channel for surgical microscopes across North America, overtaking traditional hospital capital expenditure cycles in velocity. Carl Zeiss Meditec AG leverages its longstanding optical heritage to dominate premium neurosurgical installations in major academic medical centers. Leica Microsystems competes through specialized fluorescence imaging modules that anchor its position in oncologic resection workflows. Olympus Corporation sustains broad channel control across mid-tier hospital systems through diversified endoscopy and microscopy distribution networks.
North America surgical microscopes are precision optical instruments engineered with apochromatic objectives, motorized zoom systems, and integrated illumination delivering magnification ranges from 4x to 40x for real-time tissue visualization during invasive procedures. Their primary commercial purpose centers on enabling surgeons to discriminate anatomical structures at submillimeter resolution while maintaining ergonomic positioning over prolonged operative durations. Optical microscopes retain the largest installed base across neurosurgery and ophthalmic procedures, though digital microscopes are capturing accelerated replacement cycles as hospitals prioritize 4K and 3D visualization outputs for resident training and remote proctoring. Robotic microscopes command concentrated margin pools in plastic surgery and complex oncologic applications where tremor filtration and submicron positioning justify premium capital outlays.
FDA premarket notification and quality system regulation frameworks govern device commercialization, while ISO 13485 certification shapes supplier qualification criteria for North American purchasers. Health Canada and PMRA oversight in Canadian provinces adds a secondary compliance layer that manufacturers must navigate for cross-border market access. Stakeholders should monitor evolving reimbursement codes for robotic-assisted procedures and digital surgical documentation as these directly influence capital allocation timelines across hospital systems and ambulatory networks.
Market Dynamics
Outpatient procedural migration is compressing capital equipment replacement cycles across North American surgical facilities, forcing manufacturers to reconfigure service models around ambulatory deployment rather than traditional hospital enterprise sales.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited premarket notification reviews for digital surgical microscopes with predicate device claims are reducing time-to-market by 4-6 months for optical system upgrades.
- Ambulatory surgery center expansion:Freestanding ASCs in Texas and California are procuring advanced visualization systems as spinal and ophthalmic outpatient volumes accelerate beyond inpatient capacity.
- Fluorescence-guided resection protocols:Near-infrared imaging integration into surgical microscopes is becoming standard-of-care for glioblastoma margin delineation across major academic neurosurgical programs.
Market Restraints
- Precision optical component concentration:German and Japanese suppliers dominate apochromatic objective lens manufacturing, creating single-source vulnerability for North American microscope assemblers.
- Capital intensity barriers:Robotic surgical microscope platforms require $2-4 million installed costs that ASCs cannot amortize without joint venture structures with hospital systems.
- ISO 13485 certification friction:Small optical component vendors struggle with quality management system documentation requirements, constraining supplier base diversification for North American OEMs.
Strategic Opportunities
- Canadian provincial health authority consolidation:Health Canada's streamlined device licensing under the Medical Devices Regulations creates unified procurement channels across Ontario and Quebec health networks.
- Remote proctoring infrastructure:4K and 3D digital microscopy outputs are enabling real-time surgical education platforms that ASCs can monetize through academic affiliate subscriptions.
- Reimbursement code evolution:Emerging CPT codes for robotic-assisted microsurgical procedures are creating coverage precedents that justify premium capital allocation in plastic and reconstructive surgery.
Industry Challenges
- Biomedical engineering talent scarcity:Optical system integration specialists with surgical workflow expertise command compensation premiums that strain mid-tier manufacturer R&D budgets.
- Legacy hospital IT infrastructure:Digital microscope connectivity requires HL7 FHIR compliance and PACS integration that conflicts with decades-old radiology archiving systems in community hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Surgical Microscopes Market |
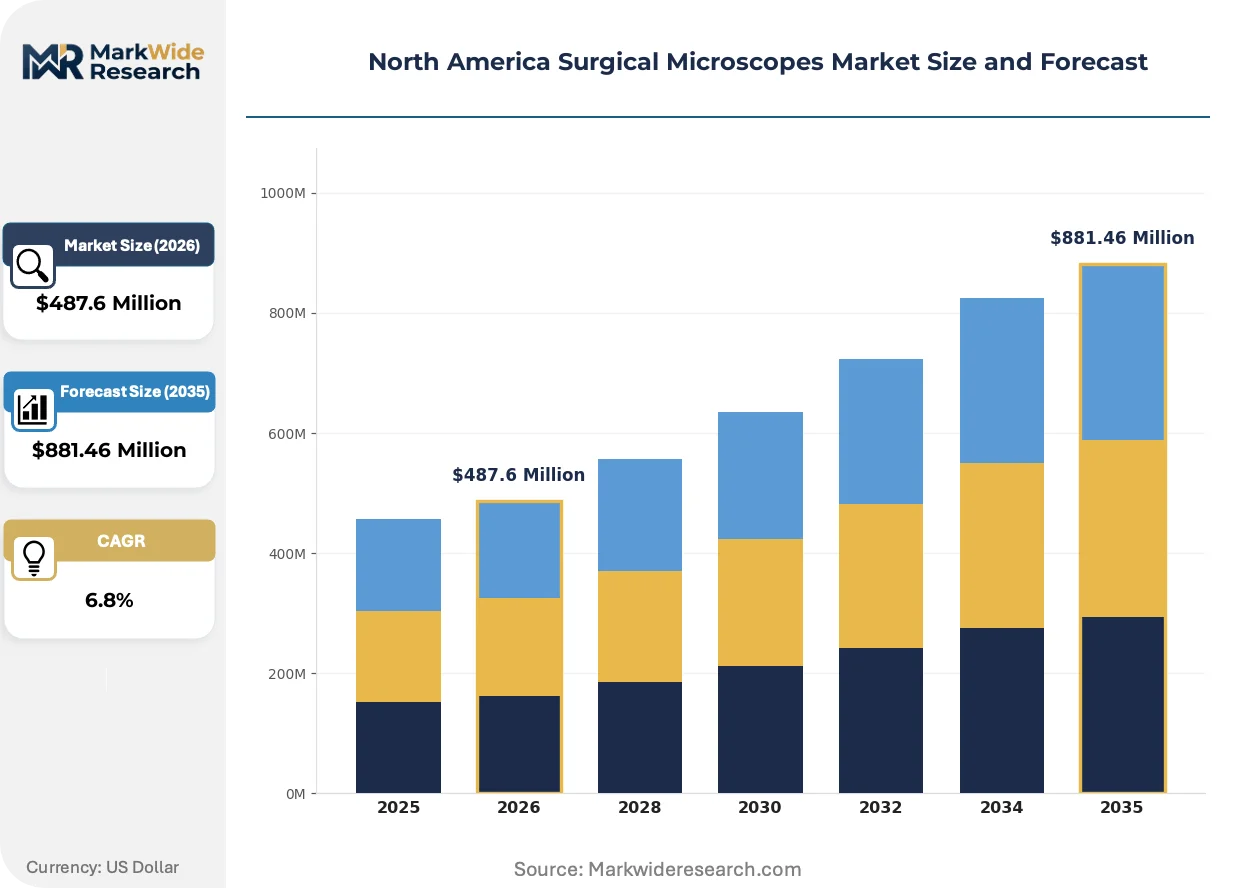
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Microscopes, Digital Microscopes, Optical Microscopes, Video Microscopes End User: Hospitals, Clinics, Ambulatory Surgery Centers, Academic Institutions Technology: 3D Visualization, Integrated Imaging, Laser Technology, Micro-manipulation Application: Neurosurgery, Ophthalmic Procedures, Oncology, Plastic Surgery |
| Companies Covered | Carl Zeiss Meditec AG, Leica Microsystems, Olympus Corporation, Alcon Inc., Topcon Corporation, Synaptive Medical Inc., Seiler Instrument Inc., Haag-Streit, Takagi Seiko Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Surgical Microscopes Market Trends and Innovations
Digital visualization architectures are displacing purely optical systems across North American surgical suites, with fluorescence imaging and augmented reality overlay capabilities becoming procurement differentiators rather than premium options.
Modular microscope platforms with swappable illumination engines and objective turrets are modularizing capital deployment for ASCs. Texas-based outpatient networks are adopting lease-to-own structures for these configurable systems. The approach is modularizing how manufacturers structure service contracts around upgradeable subsystems rather than monolithic device replacement.
FDA's evolving guidance on artificial intelligence-enabled surgical devices is reshaping validation requirements for image analysis algorithms embedded in digital microscopes. Manufacturers must now submit standalone software documentation for fluorescence pattern recognition modules. Neurosurgical device sponsors are responding by segregating AI components into detachable processing units that can be updated independently of base hardware.
Consolidated buying groups representing multi-state ASC chains are extracting volume-based pricing commitments that override traditional distributor markups. These procurement collectives in California and New York are mandating standardized service response time guarantees across their networks. The shift is most visible in ophthalmology, where cataract surgery volume concentration gives purchasing coalitions leverage over microscope OEMs previously accustomed to hospital-centric negotiation dynamics.
North America Surgical Microscopes Market Segmentation
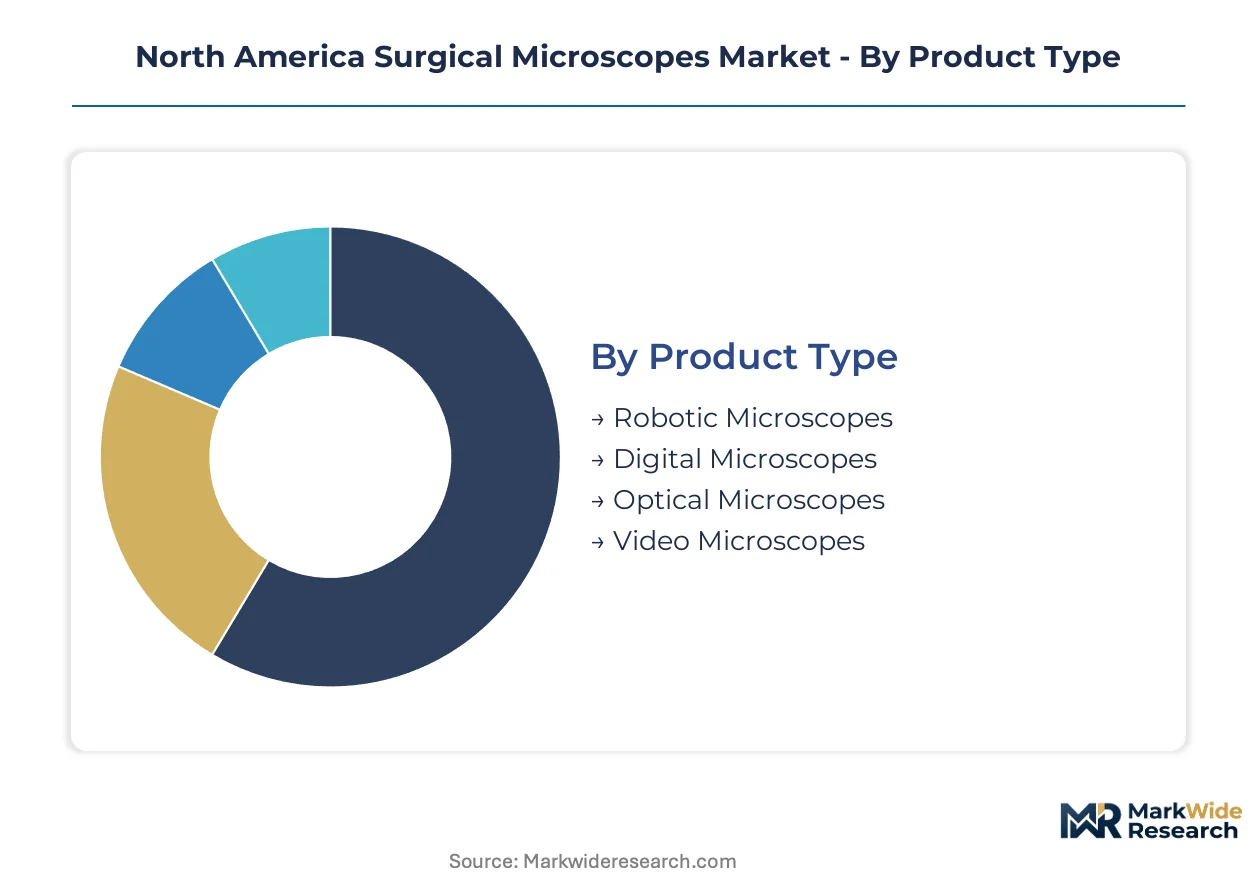
Surgical microscope procurement in North America stratifies sharply across facility type and technical sophistication. Certification burdens from FDA 510(k) pathways and Health Canada licensing create divergent compliance costs that reshape competitive positioning within each segment cluster.
Product Type:
FDA 510(k) premarket notification requirements vary substantially across optical, digital, and robotic platforms, with predicate device availability determining review timelines for each category.
- Robotic Microscopes:Electromechanical platforms integrate submicron positioning engines with tremor filtration algorithms for plastic and oncologic applications. Demand concentrates in Texas and California academic medical centers where complex reconstructive volumes justify $2-4 million capital outlays.
- Digital Microscopes:4K and 3D visualization architectures with integrated image processing replace legacy optical systems. ASCs in New York and Florida prioritize these for resident training and remote proctoring monetization.
- Optical Microscopes:Apochromatic objective systems with motorized zoom retain installed base dominance in neurosurgery and ophthalmology.
- Video Microscopes:Entry-level documentation systems serve cost-constrained community hospital settings.
Optical microscopes sit at the top of the volume ranking, with digital microscopes climbing the fastest.
End User:
Capital deployment cycles diverge dramatically between institutional purchasers, with procurement velocity inversely correlated with organizational scale and approval hierarchy complexity.
- Hospitals:Enterprise capital committees govern multi-year replacement cycles for neurosurgical suites. Major metropolitan clusters in Texas, California, and New York concentrate premium robotic installations through academic affiliate networks.
- Ambulatory Surgery Centers:Freestanding facilities in Texas and California compress procurement timelines through lease-to-own structures and consolidated buying group negotiations. Spinal and ophthalmic outpatient volume acceleration drives visualization system upgrades.
- Clinics:Smaller-scale purchasers prioritize refurbished optical systems and mid-tier digital platforms.
- Academic Institutions:Training programs mandate 4K and 3D outputs for surgical education curricula.
Hospitals dominate absolute spending, though ambulatory surgery centers are expanding most quickly.
Technology:
Margin profiles stratify across visualization and manipulation capabilities, with integrated systems commanding premium pricing against standalone functional modules.
- Integrated Imaging:Near-infrared fluorescence modules for glioblastoma margin delineation anchor oncologic resection workflows. Academic neurosurgical programs in New York and California have standardized these protocols.
- 3D Visualization:Stereoscopic display architectures enable depth perception for complex microsurgical procedures. Plastic surgery applications in California and Texas drive adoption for reconstructive precision.
- Laser Technology:Integrated cutting and coagulation beams reduce instrument exchange frequency in ophthalmic procedures.
- Micro-manipulation:Submillimeter positioning interfaces serve specialized research and training applications.
Integrated imaging leads current revenue concentration, with 3D visualization gaining share fastest.
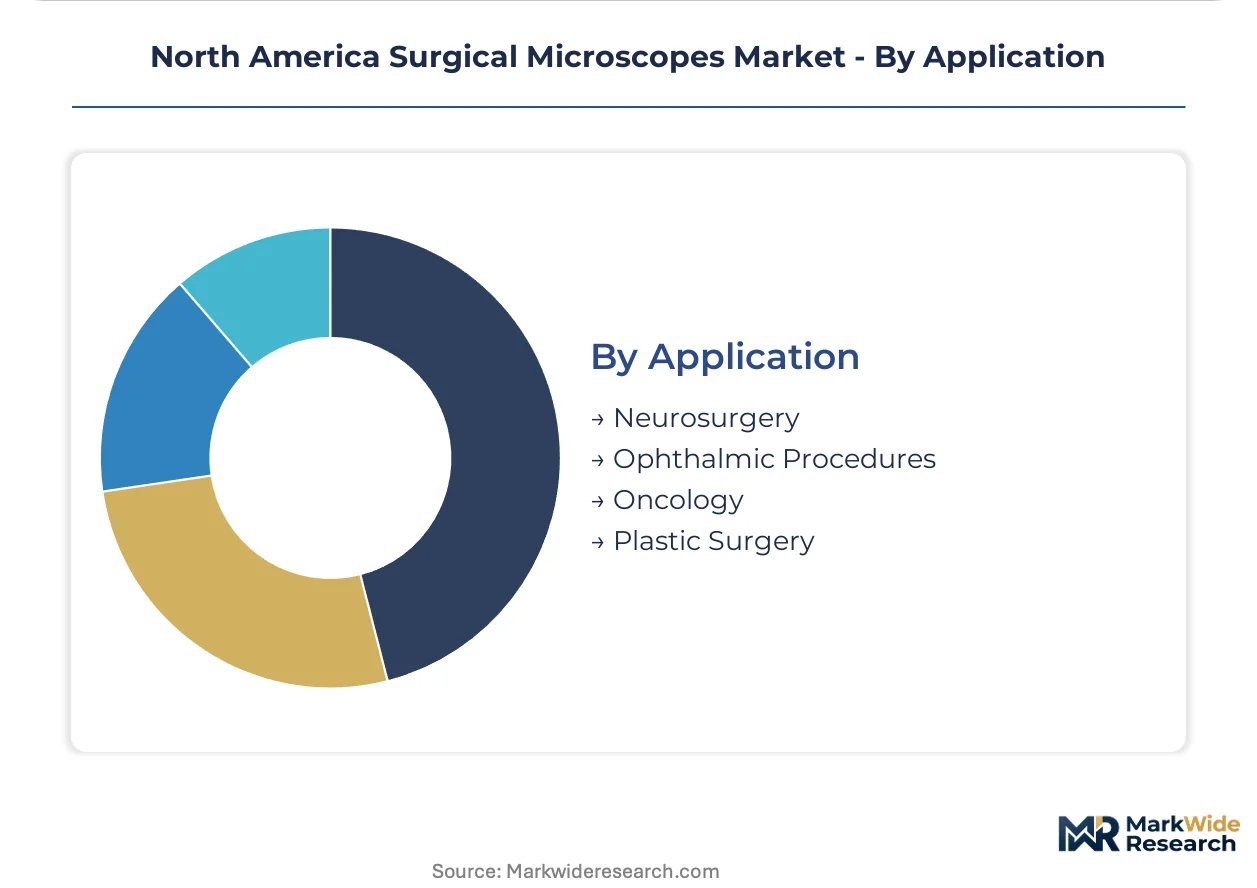
Application:
Procedure reimbursement codes directly influence capital allocation priority, with coverage precedents for robotic-assisted techniques reshaping investment sequencing across surgical disciplines.
- Neurosurgery:Glioblastoma resection and cerebrovascular procedures demand fluorescence-guided visualization with submillimeter resolution. Major academic centers in California, New York, and Texas anchor demand for premium optical and robotic platforms.
- Ophthalmic Procedures:Cataract surgery volume concentration in ASC networks creates procurement leverage over OEMs. Consolidated buying groups in California and New York extract standardized service guarantees.
- Oncology:Margin delineation protocols drive near-infrared imaging integration across resection workflows.
- Plastic Surgery:Reconstructive microsurgery applications justify robotic platform capital intensity through tremor filtration requirements.
Neurosurgery commands the highest average selling prices, with ophthalmic procedures showing the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement flows as manufacturers navigate divergent FDA 510(k) timelines against Health Canada's streamlined Medical Devices Regulations. Cost-of-compliance gaps between jurisdictions are concentrating premium robotic platform deployments in specific metropolitan clusters while mid-tier digital systems diffuse through cross-border ASC networks.
United States
Texas and California academic medical centers anchor demand for $2-4 million robotic microscope installations through tremor filtration requirements in complex reconstructive workflows. FDA premarket notification pathways compress time-to-market for predicate device claims, accelerating digital upgrade cycles. Major hospital clusters in New York metropolitan areas concentrate fluorescence-guided neurosurgical protocol standardization.
Canada
Ontario and Quebec health networks leverage Health Canada's unified device licensing to consolidate procurement across provincial boundaries. PMRA oversight adds secondary compliance verification for cross-border supply chains serving ASC expansion in Toronto and Vancouver corridors. Near-infrared imaging integration is becoming standard-of-care for glioblastoma margin delineation at academic centers in Montreal and Calgary.
Mexico
Medical device manufacturing zones in Baja California and Chihuahua supply precision optical components to North American OEMs under maquiladora cost structures. COFEPRIS regulatory alignment with FDA quality system frameworks enables component vendor qualification for cross-border purchasers. Guadalajara medical device clusters are expanding capacity for apochromatic objective lens assembly.
North America Surgical Microscopes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium neurosurgical installations consolidating around heritage optical houses while mid-tier digital platforms fragment across diversified instrument suppliers. The vendor base stratifies into three tiers: integrated imaging conglomerates, precision optical specialists, and regional fabrication houses serving cost-constrained community hospitals. Dominant competitive moves center on fluorescence module portfolio diversification and lease-to-own service model restructuring for ASC procurement velocity.
Within the heritage optical tier, Carl Zeiss Meditec AG and Leica Microsystems occupy positions defined by academic medical center anchoring and specialized imaging protocol integration. Olympus Corporation exemplifies the diversified conglomerate archetype with broad channel control across mid-tier hospital systems. These three entities collectively represent the competitive spectrum from premium robotic platforms to standardized digital documentation systems.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Leica Microsystems |
| Olympus Corporation |
| Alcon Inc. |
| Topcon Corporation |
| Synaptive Medical Inc. |
| Seiler Instrument Inc. |
| Haag-Streit |
| Takagi Seiko Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Consolidated buying groups representing multi-state ASC chains in California and New York are mandating standardized service response guarantees and volume-based pricing commitments that override traditional distributor markups, forcing manufacturers to restructure channel economics and compress margin layers across mid-tier digital platforms.
Pricing Analysis
Distributor margins in the North America surgical microscopes market typically absorb 15-25% of final installed costs before reaching hospital procurement committees or ASC administrators. Three-tier pricing structure across premium, standard, and economy levels stratifies by fluorescence module integration and robotic positioning capability, with academic medical centers showing lowest price sensitivity and community clinics demanding refurbished optical systems. Pricing pressure stems from lease-to-own structures proliferating in Texas and California outpatient networks, compressing upfront revenue recognition for OEMs while extending service contract durations.
Supply Chain Analysis
Regional distribution centers in Illinois and Ohio anchor hub-and-spoke patterns serving hospital clusters across the Midwest and Northeast, with cross-border flows from Ontario warehouses supplying Toronto and Vancouver corridors. Precision optical component manufacturing concentrates in Germany and Japan for apochromatic objective lenses, while Mexico's Baja California and Chihuahua maquiladora zones supply machined housings and illumination engines. Single-source vulnerability in German and Japanese lens suppliers creates tariff exposure risk for North American microscope assemblers. Distribution runs through specialized medical device distributors with ISO 13485 certification rather than general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America surgical microscopes market represents a late-cycle quality story where ASC procurement velocity and fluorescence-guided protocol standardization are shifting demand toward premium visualization specifications with integrated imaging capabilities.
For Market Incumbents: Deepen backward integration into apochromatic objective lens supply through captive manufacturing partnerships or long-term offtake agreements with German and Japanese optical houses, insulating margin structures from single-source concentration risk. Fortify channel control by embedding service engineers directly within Texas and California ASC networks, converting lease-to-own contracts into recurring revenue streams that resist price erosion from consolidated buying groups. For New Entrants and Emerging Players: Begin with mid-tier digital microscope platforms targeting cost-constrained community hospitals in Florida and the Mountain West, where legacy IT infrastructure gaps and limited fluorescence protocol adoption create whitespace below premium robotic installations. Pursue Health Canada streamlined licensing pathways to access Ontario and Quebec provincial procurement networks with unified device registrations, leveraging regulatory arbitrage against FDA 510(k) timeline compression for predicate-dependent optical upgrades. For Investors and Strategic Acquirers: Asymmetric upside sits with modular platform specialists offering swappable illumination engines and objective turrets that align with ASC lease-to-own procurement preferences. Long-term viability hinges on software-enabled revenue expansion through AI-embedded fluorescence pattern recognition modules that command recurring update fees independent of base hardware replacement cycles. Watch for CPT code finalization for robotic-assisted microsurgical procedures as the inflection signal justifying premium capital allocation in plastic and reconstructive surgery segments.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Streamlined Submission | Expedited predicate device claims reduce time-to-market for digital optical upgrades by compressing premarket notification reviews. |
| Health Canada Unified Licensing | Provincial consolidation across Ontario and Quebec creates cross-border procurement channels with reduced compliance friction. |
| Hospital System Partnership | Academic affiliate networks in Texas and California anchor demand for tremor filtration platforms through complex reconstructive volumes. |
| Software Companion Development | Detachable AI processing units for fluorescence pattern recognition enable independent update cycles beyond base hardware refresh. |
| Reimbursement Strategy | Emerging CPT codes for robotic-assisted procedures create coverage precedents that justify premium capital allocation timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, ASC operations directors, biomedical engineering specialists, and GPO contracts managers with secondary validation against FDA 510(k) filings, Health Canada Medical Devices Regulations submissions, hospital procurement databases, and CMS Medicare reimbursement code updates. Bottom-up installation base modeling and top-down market sizing triangulated volume estimates across the analysis window.
Historical reference periods anchored the projection horizon through surgical procedure volume trajectories and capital equipment replacement cycle analysis. Segmentation dimensions modeled include product type, end user facility category, technology integration level, application specialty, and metropolitan cluster concentration. CAGRs derived from weighted average procedure growth assumptions and equipment penetration elasticity coefficients, with fluorescence-guided protocol adoption curves and ASC expansion rates serving as primary forecast inputs.
Several conditions sit outside the modeled scope, including macroeconomic recession impacts on hospital capital budgets, sudden regulatory pathway modifications by FDA or Health Canada, and disruptive optical technology shifts rendering current platform architectures obsolete. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Arthroscopic Shaver Market
Medical Devices
Global Tracheostomy Products Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
North America Laser Hair Removal Market
Medical Devices
Epilepsy Devices Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Medical Cyclotron Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Global Microelectronic Medical Implants Market
Medical Devices
Neurofeedback Systems Market