
 Asia-Pacific Medical Aesthetic Devices Market | 2026-2036
Asia-Pacific Medical Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Aesthetic Devices Market Outlook
South Korean aesthetic device manufacturing capacity is hardening as domestic producers scale output of radiofrequency and ultrasound platforms. AbbVie leverages its cross-border distribution infrastructure to sustain premium injector product flows across Japan and Australia. Lumenis anchors its regional position through specialized laser systems for skin rejuvenation applications. Alma Lasers competes aggressively on diode laser hair removal technology, particularly within Southeast Asian clinic networks.
Medical aesthetic devices encompass electromechanical and energy-based systems engineered to deliver controlled thermal, optical, or mechanical energy to cutaneous or subcutaneous tissue, typically operating at wavelengths between 600 nm and 10,600 nm or frequencies between 1 MHz and 40 MHz for therapeutic remodeling or cosmetic enhancement. These systems serve commercial purposes across dermatology centers, medical spas, and hospitals where practitioners perform procedures requiring precise dose modulation and real-time tissue feedback. Laser devices command established margin pools given their capital intensity and recurring consumable revenue streams, while facial injectables represent the fastest-growing product category as biostimulatory fillers gain protocol adoption. Radiofrequency technology leads the energy-based segment due to its versatility across skin tightening and body contouring indications, with ultrasound platforms gaining traction for focal adipose disruption.
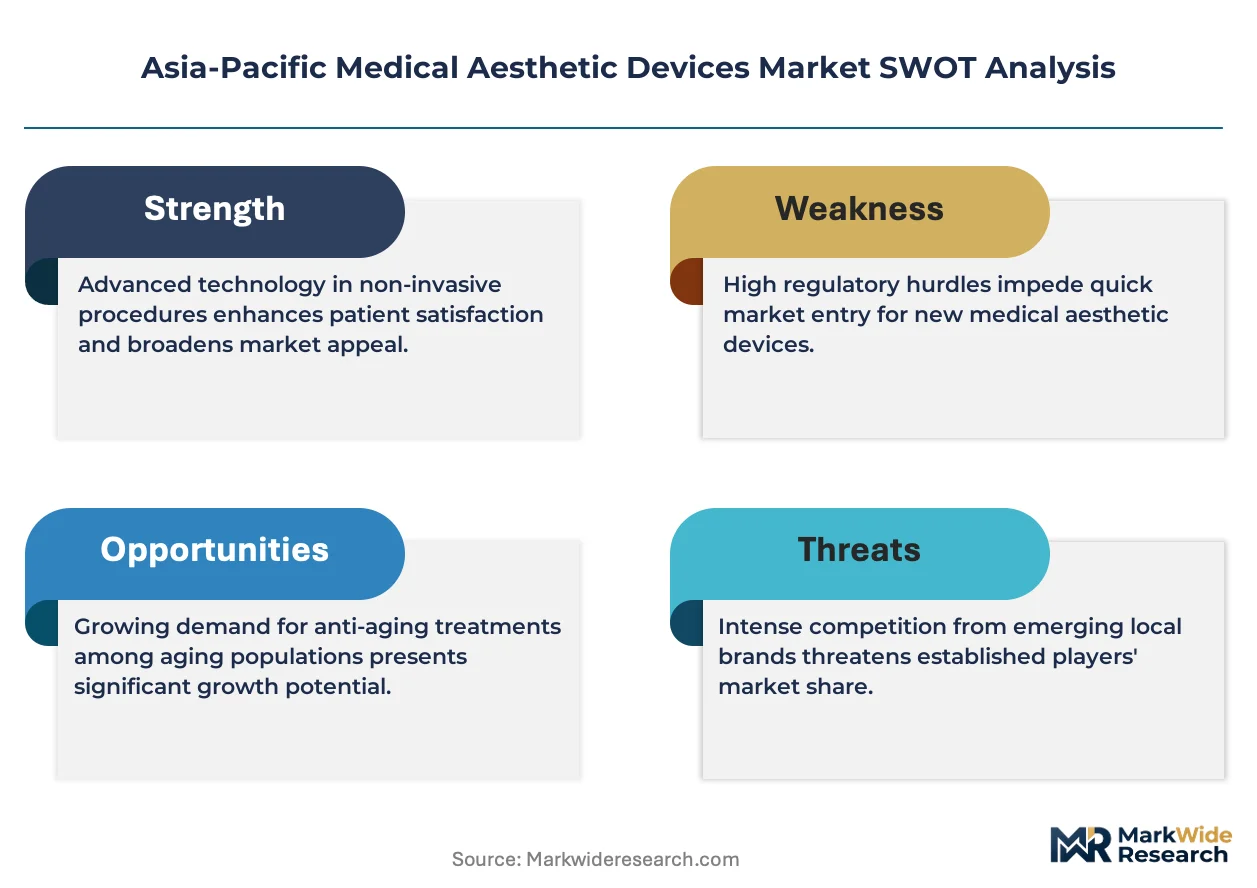
MFDS in South Korea, PMDA in Japan, and TGA in Australia collectively enforce escalating clinical evidence requirements for energy-based device registrations, lengthening approval timelines but elevating barriers against lower-tier competitors. China's NMPA has aligned its technical review standards more closely with international electromagnetic compatibility and biological safety benchmarks, reshaping import access for European and Israeli manufacturers. Stakeholders must monitor evolving reimbursement classifications for aesthetic procedures in Australia's private health framework, as coverage shifts could redirect patient out-of-pocket spending toward device-intensive treatments or away from them entirely.
Market Dynamics
MFDS tightening of radiofrequency and ultrasound platform approval pathways is forcing South Korean manufacturers toward heavier clinical trial investments and longer development cycles, compressing margins for mid-tier device producers while elevating barriers against new entrants.
Growth Catalysts
- Biostimulatory filler protocol adoption:Dermatology centers across China tier-one cities are integrating collagen-stimulating injectables into premium service portfolios, expanding procedure volumes per patient visit.
- NMPA electromagnetic compatibility alignment:China's technical review standard convergence with international benchmarks is streamlining import access for European and Israeli energy-based device manufacturers.
- Medical spa chain consolidation:Southeast Asian clinic networks are centralizing procurement of diode laser hair removal systems, creating volume-driven purchasing power previously absent in fragmented independent practices.
Market Restraints
- Capital equipment depreciation cycles:Laser platform capital intensity and five-to-seven-year replacement timelines constrain clinic cash flow flexibility, particularly in Australian private practice settings.
- Consumable supply concentration:Premium injector cartridge production clusters heavily in select European manufacturing hubs, exposing Asia-Pacific distributors to currency and logistics volatility.
- Clinical evidence cost inflation:PMDA and TGA escalating requirements for energy-based device registrations extend approval timelines to 18-24 months, freezing product pipeline velocity.
Strategic Opportunities
- Second-tier Chinese city penetration:Medical aesthetic device density in Chengdu, Hangzhou, and Wuhan remains substantially below Shanghai and Beijing levels, creating whitespace for scaled service rollouts.
- Radiofrequency-ultrasound combination platforms:Convergent multi-modal systems addressing simultaneous skin tightening and focal adipose disruption are capturing protocol preference in South Korean dermatology centers.
- Direct-to-clinic digital distribution:Bypassing traditional medical device distributor layers through specialized e-procurement platforms is compressing landed cost structures for Southeast Asian independent practitioners.
Industry Challenges
- Practitioner certification bottlenecks:Energy-based device operation licensing requirements are expanding faster than accredited training program capacity across Australia and Japan, constraining qualified user supply.
- Legacy system integration friction:New radiofrequency platforms face interoperability barriers with established clinic management software and patient record systems, complicating technology refresh decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Aesthetic Devices Market |
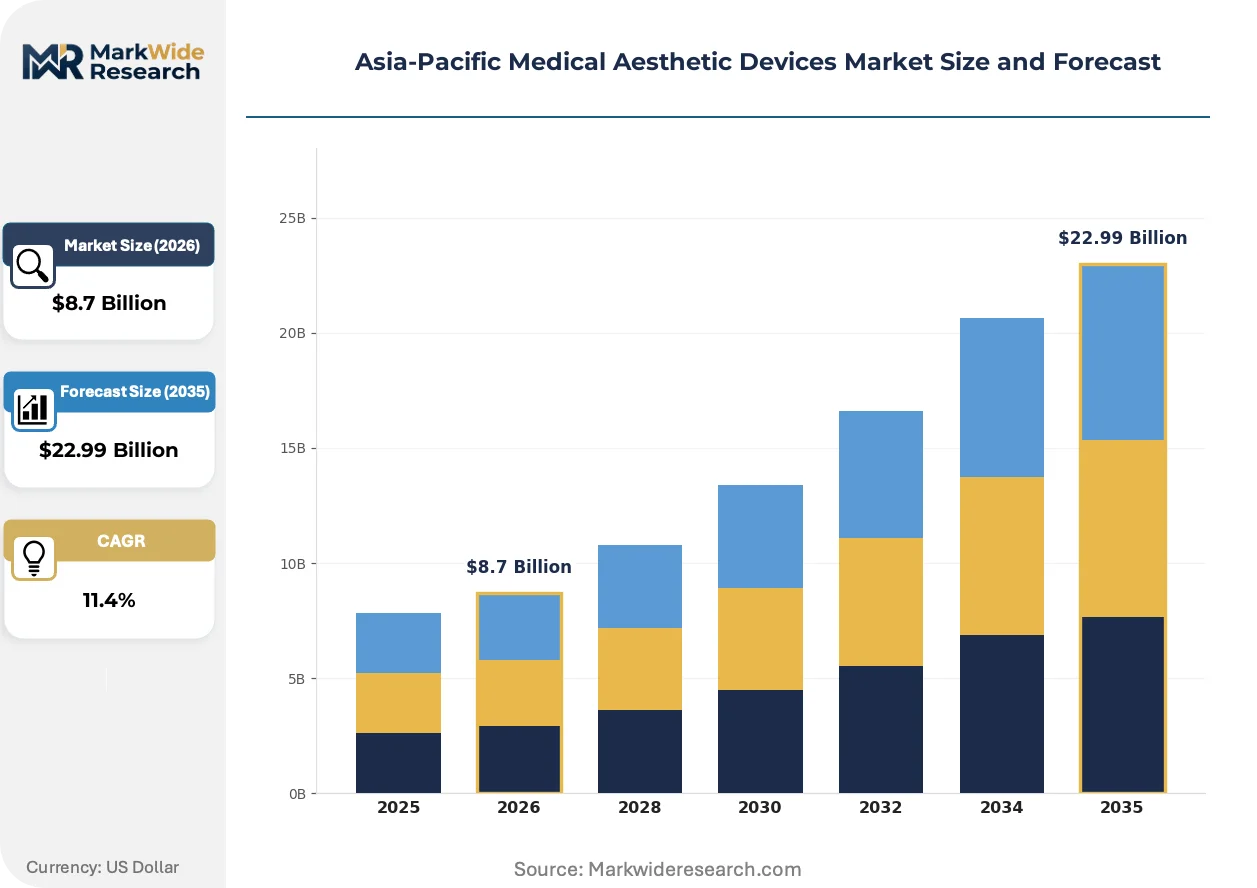
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Dermal Fillers, Microdermabrasion Equipment, Facial Injectables End User: Clinics, Hospitals, Medical Spas, Dermatology Centers Technology: Radiofrequency, Ultrasound, LED, Chemical Peels Application: Anti-Aging, Skin Rejuvenation, Hair Removal, Body Contouring |
| Companies Covered | AbbVie, Cutera, Lumenis, Cynosure, Johnson & Johnson, Candela Medical, Alma Lasers, Lutronic, Classys, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Aesthetic Devices Market Strategic Shifts
Real-time tissue feedback mechanisms and AI-assisted dose modulation are displacing operator-dependent parameter selection across energy-based aesthetic platforms, compressing training requirements while elevating treatment consistency benchmarks.
Fractional radiofrequency microneedling technology is automating depth-controlled thermal delivery to dermal layers previously requiring manual cannula techniques. Dermatology centers in Seoul and Tokyo are adopting these platforms at replacement-cycle pace, compressing demand for standalone microneedling devices while expanding addressable indications to acne scarring and stretch mark protocols.
PMDA's 2024 guidance on software-as-a-medical-device classification for aesthetic platform control systems is mandating cybersecurity documentation and update validation protocols. Japanese manufacturers are restructuring quality management systems to accommodate continuous software deployment, while importers face extended technical file preparation timelines for laser and ultrasound platforms with embedded AI modules.
Subscription-based equipment access models are displacing outright capital purchase arrangements across Australian medical spa chains. Clinics in Sydney and Melbourne are transitioning to per-procedure leasing structures with bundled maintenance and consumable supply, compressing upfront cash requirements while locking in multi-year vendor relationships and reducing switching flexibility.
Asia-Pacific Medical Aesthetic Devices Market Segmentation
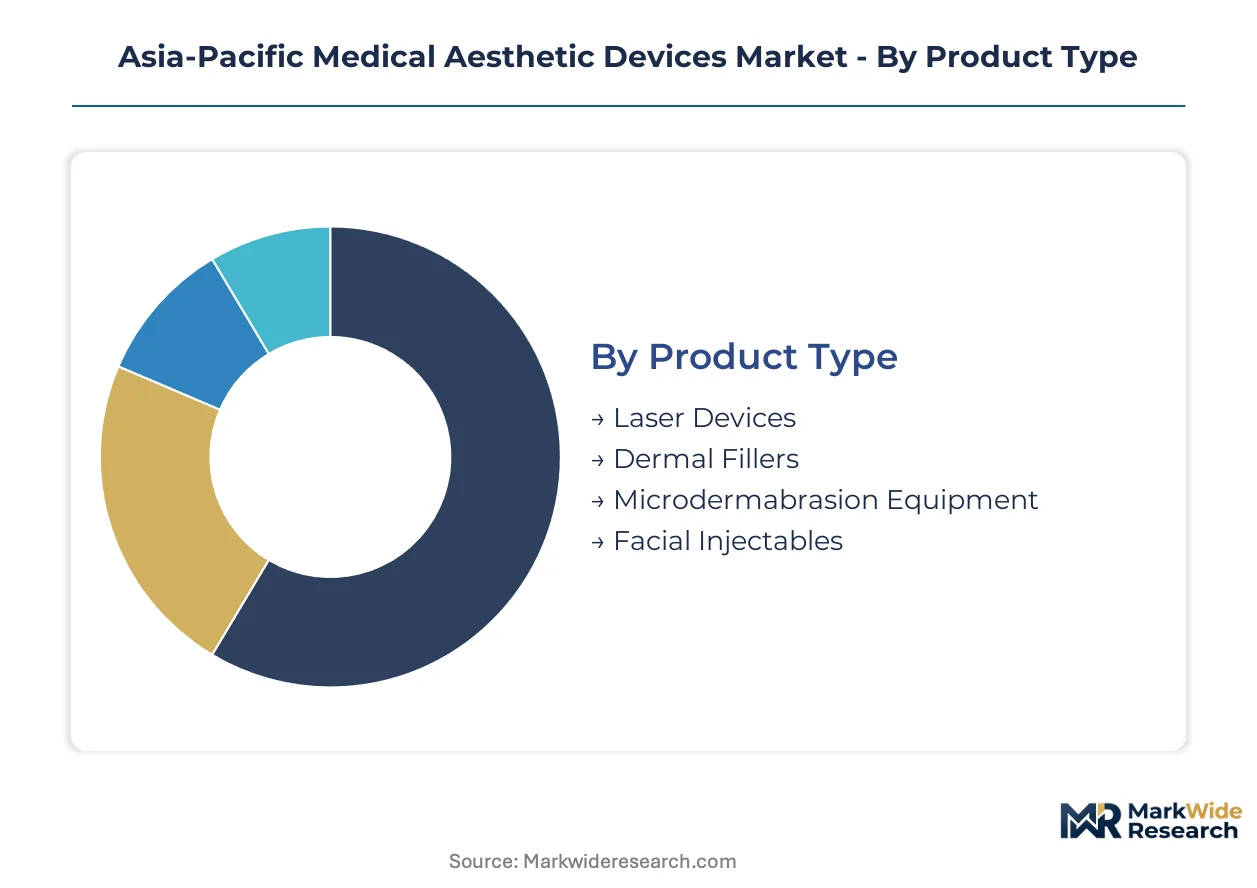
Technology differentiation and procedure specialization define competitive positioning across Asia-Pacific aesthetic device procurement. Segmentation reveals how capital intensity, regulatory pathways, and clinical protocol adoption concentrate revenue across distinct equipment categories and service settings.
Product Type:
Product architecture determines capital deployment cycles and recurring revenue potential across aesthetic practice business models.
- Laser Devices:These systems deliver controlled optical energy across wavelengths from 600 nm to 10,600 nm for precise tissue interaction. Dermatology centers in Seoul and Tokyo prioritize fractional CO2 and erbium platforms for resurfacing protocols given established reimbursement codes and predictable patient throughput. Capital intensity and five-to-seven-year replacement timelines constrain independent clinic purchasing flexibility.
- Facial Injectables:Biostimulatory formulations including poly-L-lactic acid and calcium hydroxylapatite stimulate neocollagenesis for gradual volumetric correction. Tier-one Chinese medical spas are integrating these into premium membership tiers, expanding procedure volumes per patient visit beyond traditional hyaluronic acid touch-ups.
- Dermal Fillers:Cross-linked hyaluronic acid gels dominate immediate volumization applications across Southeast Asian clinic networks.
- Microdermabrasion Equipment:Mechanical exfoliation systems serve entry-level service tiers in Australian private practices with lower regulatory barriers.
Laser Devices leads on scale; Facial Injectables leads on momentum.
End User:
Facility type shapes procurement authority, patient volume economics, and technology refresh cadence across the region.
- Dermatology Centers:Physician-directed facilities in South Korea and Japan command highest equipment utilization rates with dedicated procedure rooms and trained nursing support. These centers drive adoption of combination radiofrequency-ultrasound platforms for simultaneous skin tightening and adipose disruption, compressing demand for standalone devices.
- Medical Spas:Corporate chains across China's Yangtze River Delta are centralizing procurement through specialized e-procurement platforms, creating volume-driven purchasing power absent in fragmented independent practices. Subscription-based equipment access models are displacing outright capital purchases in Australian metro markets.
- Clinics:Independent practitioners in Southeast Asia face working capital constraints limiting technology refresh frequency.
- Hospitals:Academic medical centers in Japan prioritize platforms with embedded AI modules for resident training protocols.
Medical Spas leads on scale; Dermatology Centers leads on momentum.
Technology:
Energy delivery mechanisms determine clinical indication breadth and regulatory classification complexity across approval pathways.
- Radiofrequency:Electromagnetic energy at 1-40 MHz generates controlled dermal heating for collagen remodeling without epidermal damage. South Korean manufacturers are scaling output of fractional microneedling platforms that automate depth-controlled thermal delivery, compressing demand for standalone microneedling devices while expanding indications to acne scarring protocols.
- Ultrasound:High-intensity focused acoustic energy enables focal adipose disruption at precise tissue depths. MFDS tightening of approval pathways is forcing heavier clinical trial investments for new platform registrations, elevating barriers against lower-tier competitors while extending development cycles.
- LED:Photobiomodulation systems serve maintenance protocols and post-procedure recovery applications with minimal regulatory burden.
- Chemical Peels:Acid-based exfoliation represents lowest capital threshold for service line expansion in emerging Chinese tier-two cities.
Radiofrequency leads on scale; Ultrasound leads on momentum.
Application:
Clinical indication drives device selection, pricing power, and patient retention economics across service portfolios.
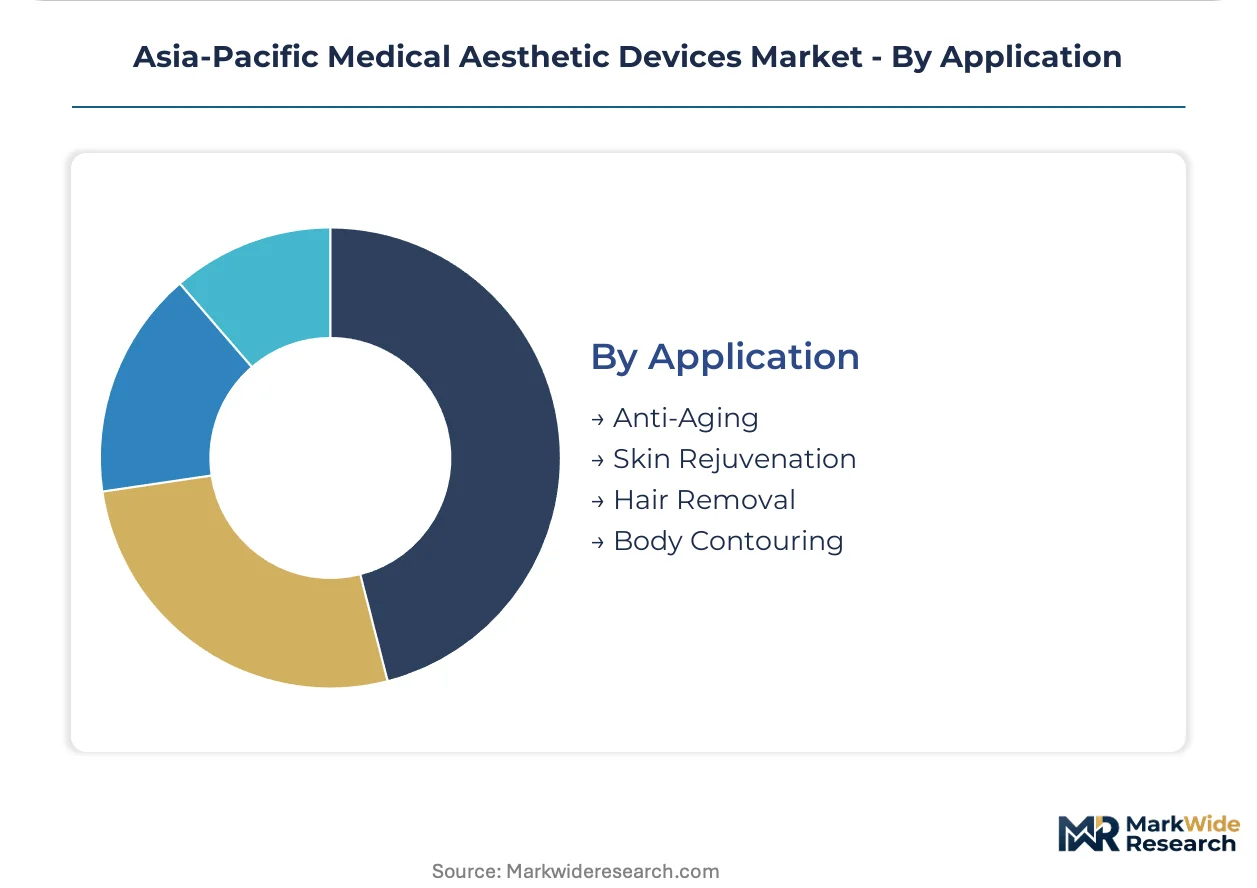
- Anti-Aging:Comprehensive protocols combining neuromodulators, biostimulatory fillers, and energy-based tightening command highest lifetime patient value. Australian private health framework reimbursement shifts could redirect out-of-pocket spending toward device-intensive treatments or away from them entirely, reshaping clinic capital allocation priorities.
- Skin Rejuvenation:Laser resurfacing and fractional radiofrequency address photodamage, texture irregularities, and dyschromia. PMDA escalating clinical evidence requirements for energy-based device registrations extend approval timelines to 18-24 months, freezing product pipeline velocity for novel rejuvenation platforms.
- Hair Removal:Diode laser systems dominate Southeast Asian clinic network procurement with established protocol efficiency.
- Body Contouring:Cryolipolysis and ultrasound platforms capture patient preference for non-invasive adipose reduction in South Korean and Australian metro markets.
Anti-Aging leads on scale; Skin Rejuvenation leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's dermatology center density exceeds Japan's by a factor of three, yet China's procedural volume growth outpaces both markets combined. Regulatory divergence across these three markets is reshaping manufacturer compliance investments and approval sequencing strategies.
China
Tier-one cities Shanghai and Beijing concentrate premium medical spa chain expansion, with Chengdu and Hangzhou emerging as whitespace targets for device-intensive service rollouts. NMPA electromagnetic compatibility alignment with international benchmarks is streamlining import access for European and Israeli energy-based device manufacturers. Yangtze River Delta medical spa chains are centralizing procurement through specialized e-procurement platforms, creating volume-driven purchasing power.
South Korea
Domestic manufacturers are scaling output of radiofrequency and ultrasound platforms as dermatology centers expand device procurement budgets. MFDS tightening of approval pathways is forcing heavier clinical trial investments and longer development cycles, elevating barriers against lower-tier competitors. Seoul dermatology centers are adopting combination radiofrequency-ultrasound platforms at replacement-cycle pace, compressing demand for standalone devices.
Japan
PMDA escalating clinical evidence requirements for energy-based device registrations extend approval timelines to 18-24 months, freezing product pipeline velocity for novel rejuvenation platforms. Academic medical centers in Tokyo prioritize platforms with embedded AI modules for resident training protocols. Kansai region clinics face practitioner certification bottlenecks as energy-based device operation licensing requirements expand faster than accredited training program capacity.
Australia
Subscription-based equipment access models are displacing outright capital purchases across Sydney and Melbourne medical spa chains, compressing upfront cash requirements while locking in multi-year vendor relationships. TGA requirements for energy-based device registrations parallel PMDA escalation patterns. Private health framework reimbursement shifts could redirect patient out-of-pocket spending toward device-intensive treatments or away from them entirely.
Southeast Asia
Clinic networks in Singapore and Thailand are consolidating procurement of diode laser hair removal systems, creating volume-driven purchasing power previously absent in fragmented independent practices. Independent practitioners across Indonesia and Vietnam face working capital constraints limiting technology refresh frequency. Direct-to-clinic digital distribution is compressing landed cost structures through bypass of traditional medical device distributor layers.
Asia-Pacific Medical Aesthetic Devices Market Competitive Environment
South Korean producers anchor one tier; Israeli and European specialists hold premium positioning in laser and energy-based platforms. The vendor base structures across three tiers: multinational conglomerates with cross-border distribution infrastructure, mid-cap regional manufacturers with domestic regulatory expertise, and emerging specialists targeting single-modality dominance. Strategic archetypes include capital-intensive platform developers, consumable-centric injector specialists, and combination-technology integrators. Competitive moves concentrate on M&A for regulatory footprint expansion and strategic partnerships for localized clinical trial execution.
Within the multinational tier, AbbVie leverages cross-border distribution infrastructure to sustain premium injector product flows across Japan and Australia. Lumenis anchors regional positioning through specialized laser systems for skin rejuvenation applications, while Alma Lasers occupies a position competing aggressively on diode laser hair removal technology within Southeast Asian clinic networks. These three exemplify divergent archetype strategies: pharmaceutical-backed injectable platforms, established laser capital equipment, and aggressive price-positioned specialty systems.
| Leading Market Players |
|---|
| AbbVie |
| Cutera |
| Lumenis |
| Cynosure |
| Johnson & Johnson |
| Candela Medical |
| Alma Lasers |
| Lutronic |
| Classys |
| Others |
Value Chain & Pricing Dynamics
Fractional radiofrequency microneedling automation is compressing production costs for South Korean manufacturers while concentrating procurement power among dermatology center chains across Seoul and Tokyo. This technology transition simultaneously elevates quality benchmarks and reduces per-unit manufacturing overhead, reshaping margin structures across the radiofrequency device tier.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for radiofrequency platforms as domestic manufacturers scale fractional microneedling output. Three-tier pricing structure across premium, standard, and economy levels stratifies by MFDS certification tier and bundled software modules. Pricing pressure stems from subscription-based equipment access models displacing outright capital purchases across Australian medical spa chains. Independent practitioners in Southeast Asia exhibit highest price sensitivity; corporate dermatology center chains in Seoul and Shanghai demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates in China's NMPA technical review standards are reshaping sourcing patterns for European and Israeli energy-based device manufacturers seeking import access. Manufacturing concentrates in South Korea, Israel, and Germany for radiofrequency and laser platforms. Supply chains draw from specialized optical component foundries, medical-grade aluminum housing suppliers, and embedded AI processor distributors. Single-source vulnerability concentrates in premium injector cartridge production clusters across select European manufacturing hubs. Distribution runs through specialized medical device distributors with regulatory compliance expertise, though direct-to-clinic digital platforms are compressing traditional channel layers across Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific medical aesthetic devices market reads as a late-cycle quality story, with demand shifting decisively toward biostimulatory filler protocols and combination radiofrequency-ultrasound platforms that command premium specifications.
For Market Incumbents: To counter subscription-based equipment access models compressing upfront capital purchase volumes, AbbVie and Lumenis should deepen backward integration into consumable cartridge production to capture recurring revenue streams. Prioritize MFDS and PMDA certification investments for embedded AI module platforms, as regulatory evidence requirements are extending approval timelines and freezing pipeline velocity for unprepared competitors.
For New Entrants and Emerging Players: Direct-to-clinic e-procurement platforms represent the most penetrable channel wedge, bypassing traditional distributor markups that constrain independent practitioner access in Indonesia and Vietnam. Target second-tier Chinese cities—Chengdu, Hangzhou, Wuhan—where device density remains substantially below Shanghai and Beijing levels. Lead with diode laser hair removal systems for Southeast Asian clinic network consolidation, as procurement centralization creates volume-driven purchasing power absent in fragmented independent practices.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap regional manufacturers with domestic regulatory expertise but limited cross-border distribution infrastructure. Long-term viability hinges on 5-10 year regulatory alignment trajectories across MFDS, PMDA, and NMPA, as technical review standard convergence accelerates. Target acquisition archetype: South Korean radiofrequency specialists with fractional microneedling automation capabilities. Signal to monitor: reimbursement classification shifts in Australia's private health framework, which could redirect patient out-of-pocket spending toward device-intensive treatments or away from them entirely.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Certification Investment | Accelerates market access for radiofrequency platforms amid tightening clinical evidence requirements in Seoul. |
| Combination Technology Integration | Captures protocol preference in South Korean dermatology centers for simultaneous skin tightening and adipose disruption. |
| Direct-to-Clinic Digital Distribution | Compresses landed cost structures for Southeast Asian independent practitioners bypassing traditional distributor layers. |
| Biostimulatory Filler Portfolio Expansion | Aligns with tier-one Chinese medical spa premium membership tier integration and expanded procedure volumes. |
| Embedded AI Module Development | Addresses PMDA software-as-a-medical-device classification mandates for aesthetic platform control systems in Tokyo. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dermatology center procurement directors, biomedical engineers at academic medical centers, medical spa chain operations executives, and GPO contracts managers with secondary validation against MFDS registration databases, PMDA approval filings, NMPA electromagnetic compatibility technical standards, hospital procurement records, and trade customs data for optical component imports. Bottom-up equipment shipment tracking and top-down procedural volume estimates were triangulated to anchor market sizing.
Comparable-period anchoring established historical reference baselines against which projection assumptions were stress-tested across the modeling period. Segmentation dimensions modeled include product architecture, energy delivery mechanism, clinical indication, facility type, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis, procedure volume elasticity estimates, and technology adoption curve positioning. Industry-specific forecast inputs encompassed dermatology center density ratios, medical spa chain consolidation rates, and biostimulatory filler protocol penetration trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to reimbursement classification shifts, regulatory evidence requirement escalations, and supply chain concentration in premium injector cartridge manufacturing. Forecasts reflect documented assumptions regarding technology refresh cadences and practitioner certification capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Graft Delivery Devices Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
Global Vascular Access Devices Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Acne Treatment Devices Market
Medical Devices
Intravaginal Device Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Pocket Otoscope Market
Medical Devices
Ocular Adhesive Market
Medical Devices
Global Hemostasis Valves Market