
 Insurance Protection Products Market | 2026-2036
Insurance Protection Products Market Size, Share, and Industry Trends Forecast 2026-2036
Insurance Protection Products Market Analysis
Asia-Pacific's regulatory harmonization is narrowing the compliance gap between developed and emerging insurance markets. Allianz leverages its captive reinsurance capabilities to sustain pricing power across European property lines. AXA anchors its growth strategy in digital health ecosystems, while MetLife competes through workplace benefit distribution networks in North America.
Insurance protection products encompass risk-transfer instruments that indemnify policyholders against mortality, morbidity, property damage, or income loss through contractual premium-for-benefit exchanges. These instruments pool collective risk through actuarial pricing models, delivering financial restoration to individuals and commercial entities upon the occurrence of specified contingent events. Life insurance and health insurance command the largest premium pools, with health insurance recording accelerated growth due to aging demographics and medical cost inflation. Online platforms represent the fastest-expanding distribution channel, compressing acquisition costs while expanding addressable customer bases beyond traditional agent territories.
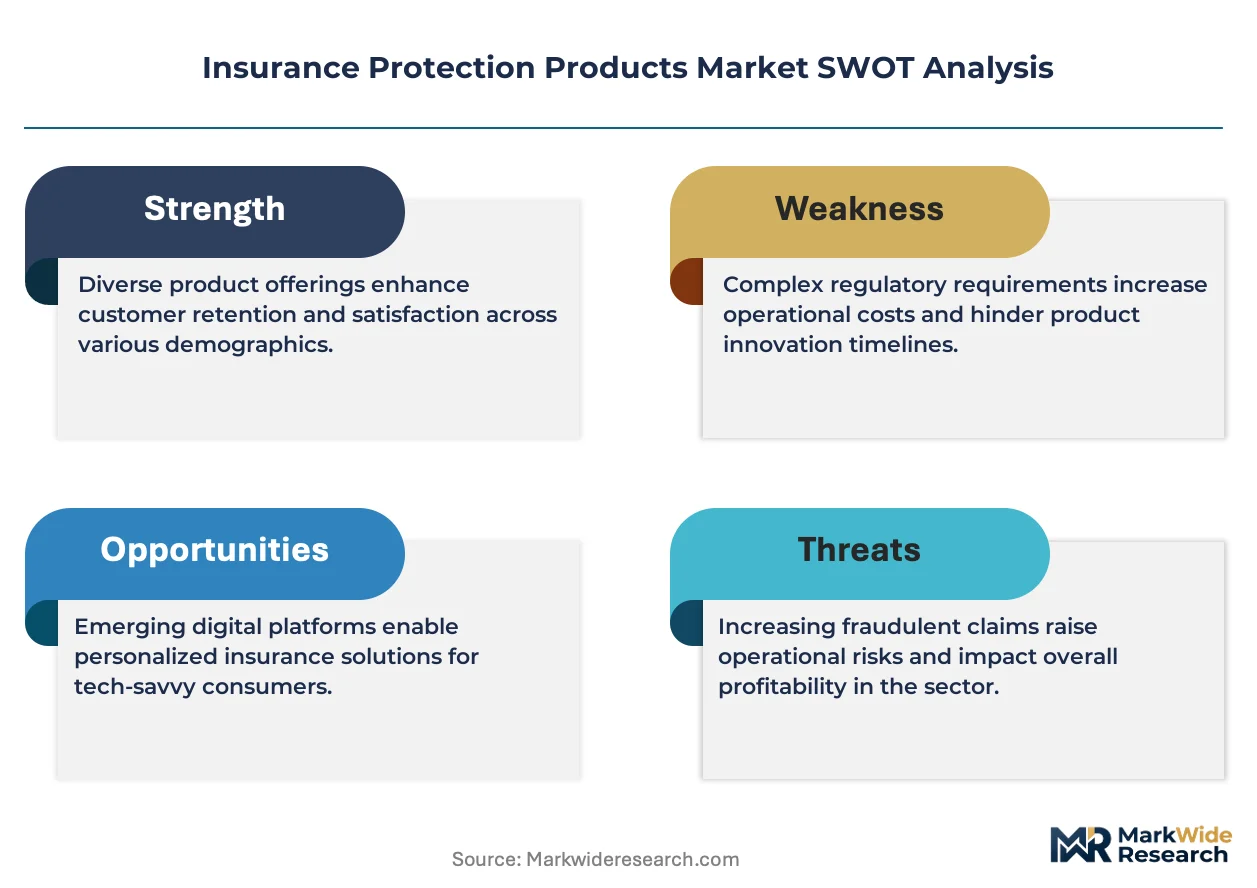
FDA oversight of wearable-integrated underwriting data, HIPAA privacy constraints on health information utilization, and EIOPA's Solvency II capital requirements collectively determine product design feasibility and market entry pathways across jurisdictions. The EU AI Act introduces additional algorithmic transparency mandates for automated claims and pricing systems. Stakeholders must evaluate which regulatory perimeter—US state-based, EU harmonized, or emerging market adaptive—offers the most favorable innovation-to-compliance ratio for their capital allocation decisions.
Market Dynamics
Embedded insurance APIs are compressing distribution layers, enabling carriers to embed protection products directly into e-commerce checkout flows and banking apps without traditional agent intermediation.
Growth Catalysts
- EU Digital Operational Resilience Act (DORA):Mandatory ICT risk management frameworks for insurers operating across member states are accelerating cyber insurance product development and operational investment.
- Workplace benefit platforms:Employers in North America are consolidating employee protection offerings through integrated digital portals, expanding group life and disability coverage penetration.
- Parametric triggers:Satellite data and IoT sensors enable automatic payouts based on predefined weather or seismic events, reducing claims processing friction in catastrophe-exposed property lines.
Market Restraints
- Long-duration liability risk:Life insurers face asset-liability duration mismatches as low-yield environments persist, compressing investment income that subsidizes guaranteed product pricing.
- Reinsurance capacity concentration:Bermuda and London market reinsurers control critical catastrophe capacity, creating pricing volatility when modelled loss estimates shift.
- Legacy core system dependency:Mainframe policy administration platforms constrain real-time data integration for usage-based or on-demand product variants.
Strategic Opportunities
- Germany corporate pension reform:Riester and Rürup scheme adjustments are expanding defined contribution adoption, creating group annuity product demand among mid-size employers.
- Wearable-integrated underwriting:Continuous health data streams from FDA-cleared devices enable dynamic premium adjustment for individual life and health policies.
- Bancassurance digitization:European banks are white-labeling protection products through open banking APIs, creating embedded distribution partnerships without branch infrastructure.
Industry Challenges
- Actuarial talent scarcity:Predictive modeling and machine learning deployment require hybrid skill sets combining traditional reserving expertise with data science capabilities that remain scarce.
- EU AI Act compliance timelines:Automated underwriting and claims systems face mandatory algorithmic transparency documentation, extending product development cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insurance Protection Products Market |
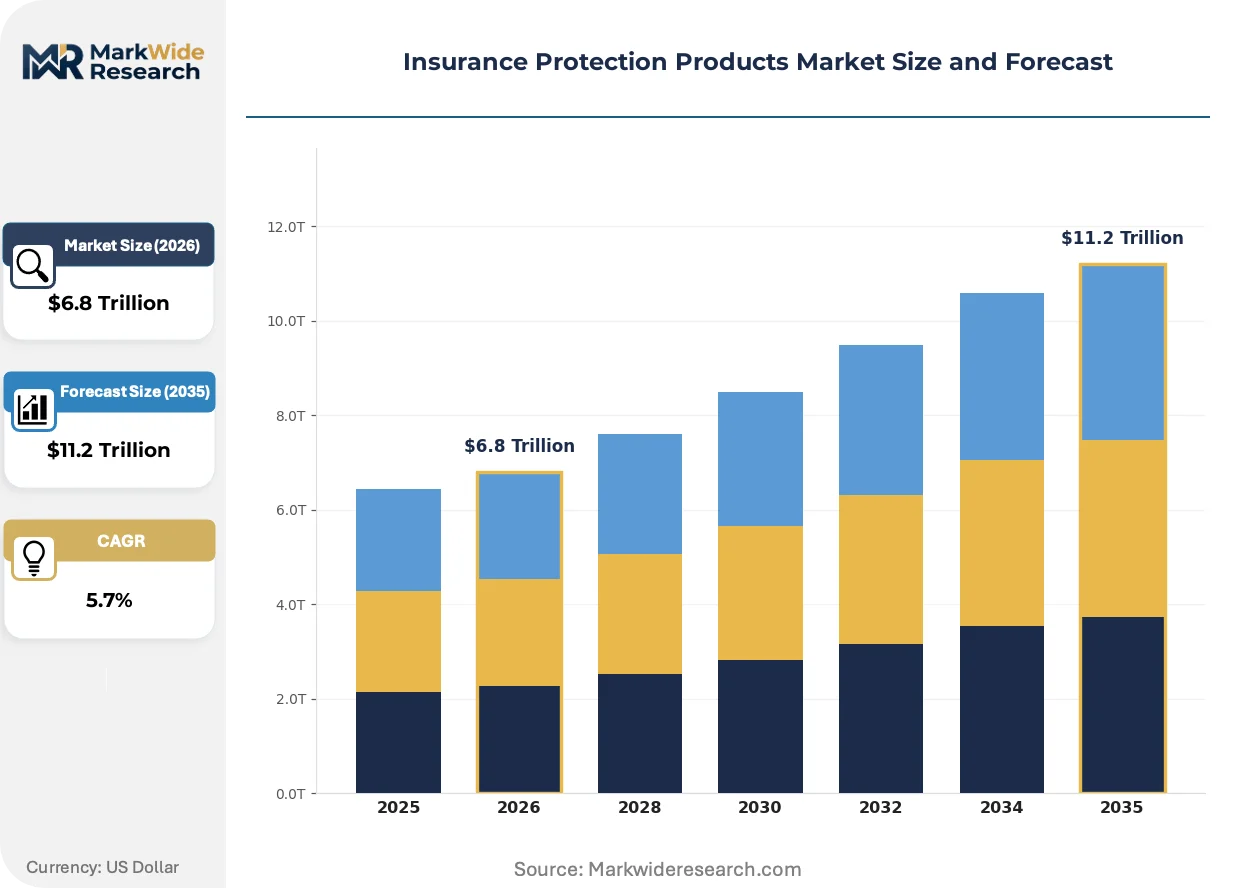
| Market Size in 2026 | $6.8 Trillion |
| Market Size in 2035 | $11.2 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Health Insurance, Disability Insurance, Property Insurance Distribution Channel: Direct Sales, Brokers, Agents, Online Platforms Customer Type: Individuals, Families, Small Businesses, Corporations Coverage Type: Whole Life, Term Life, Critical Illness, Accident Insurance |
| Companies Covered | Allianz, AXA, MetLife, Prudential, UnitedHealth Group, Chubb, Zurich, AIG, China Life Insurance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insurance Protection Products Market Emerging Trajectories
Telematics and behavioral data streams are reconstructing risk assessment from static demographic pooling to dynamic individual monitoring, compressing the information asymmetry that has historically defined insurance economics.
Blockchain-enabled smart contracts are digitizing policy administration and claims settlement for parametric products, eliminating manual loss adjustment for predefined trigger events. Agricultural cooperatives in climate-vulnerable regions are adopting these instruments fastest, drawn by immediate liquidity post-disaster. The technology is digitizing back-office functions that previously consumed 15-20% of gross written premium in administrative overhead.
The EU AI Act introduces mandatory conformity assessments for automated decision systems used in pricing and claims, requiring insurers to document training data provenance and algorithmic logic. Product development teams must now embed technical documentation workflows from inception rather than retrofitting compliance. German and French regulators are conducting parallel supervisory examinations, creating fragmented implementation timelines across the bloc's largest markets.
Small commercial buyers are migrating from annual packaged policies to modular, subscription-based coverage activated by business activity metrics. Digital brokers in the United Kingdom and Netherlands are capturing this demand through API-connected platforms that quote and bind coverage in under ten minutes. The shift is most pronounced among gig economy platforms and micro-enterprises with volatile revenue streams that resist traditional fixed-premium structures.
Insurance Protection Products Market Segmentation
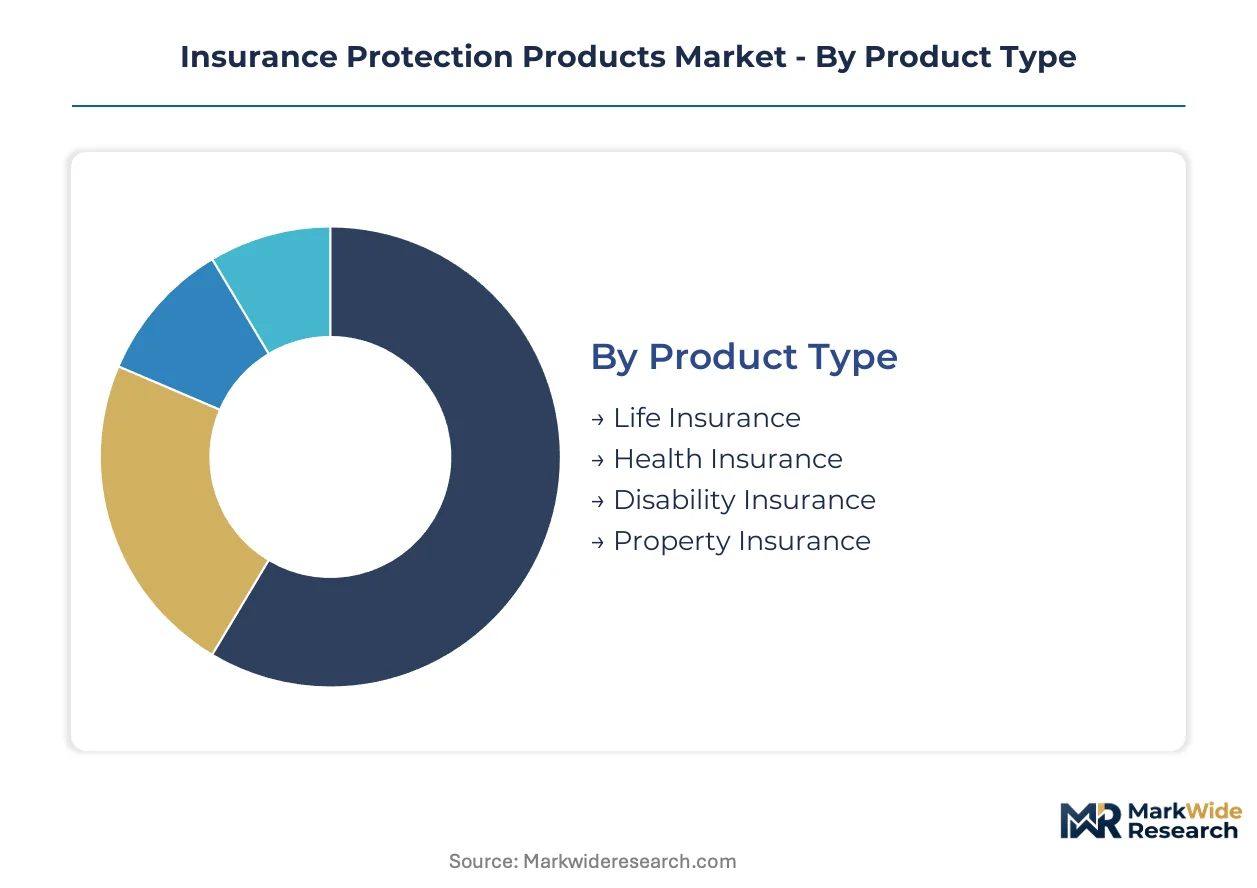
Segmentation in insurance protection products reveals distinct risk-transfer economics across product architectures, distribution economics, and buyer sophistication levels. Each dimension shapes capital allocation, pricing models, and regulatory compliance requirements differently.
Product Type:
Cost tier differentiation separates guaranteed-benefit products from contingent-payout structures, with capital intensity and duration risk varying substantially across the spectrum.
- Life Insurance:Long-duration contracts pool mortality risk through actuarial pricing, with whole life and term variants demanding distinct asset-liability management strategies. German corporate pension schemes and North American workplace benefit platforms drive group life adoption, though low-yield environments compress investment income margins.
- Health Insurance:Medical cost inflation and aging demographics accelerate premium growth in this segment. Wearable-integrated underwriting from FDA-cleared devices enables dynamic pricing adjustments, while HIPAA constraints limit data utilization scope.
- Disability Insurance:Income replacement contracts face adverse selection challenges in individual markets. Group distribution through employers dominates volume, with occupational classification determining pricing tiers.
- Property Insurance:Catastrophe-exposed lines rely on Bermuda and London reinsurance markets for capacity. Parametric triggers using satellite data reduce claims friction for agricultural and climate-vulnerable risks.
Life Insurance holds installed capacity. Health Insurance is rotating up the share rankings.
Distribution Channel:
Channel economics determine customer acquisition costs and addressable market reach, with digital infrastructure displacing traditional intermediary layers.
- Direct Sales:Carrier-owned channels capture full margin but require substantial brand investment and digital infrastructure. Telematics and behavioral data integration enable personalized pricing without intermediary interpretation.
- Brokers:Independent intermediaries serve commercial buyers with complex, multi-line coverage needs. Small commercial migration to modular, subscription-based products threatens traditional packaged policy commissions.
- Agents:Captive and independent agent networks retain strength in relationship-driven life insurance sales. Legacy core system dependencies constrain real-time quoting capabilities for many carrier-agent partnerships.
- Online Platforms:API-connected distribution compresses quote-to-bind cycles to under ten minutes. Embedded insurance integrations through e-commerce checkout flows and banking apps expand addressable bases beyond traditional territories.
Online Platforms are climbing the fastest. Agents retain relationship-driven permanence.
Customer Type:
Buyer sophistication and purchasing power concentration shape product design, with institutional buyers demanding customization unavailable to retail segments.
- Individuals:Single-policy buyers prioritize simplicity and price transparency. Digital health ecosystems from carriers like AXA target this segment with integrated wellness and protection offerings.
- Families:Multi-life coverage decisions involve intergenerational risk pooling considerations. Term life and critical illness combinations address breadwinner protection needs.
- Small Businesses:Commercial coverage portfolios expand as owners recognize operational risk exposure. DORA-mandated ICT risk management frameworks accelerate cyber insurance adoption among this buyer class.
- Corporations:Large employers consolidate employee protection through integrated digital portals. Group annuity demand in Germany concentrates among mid-size employers adjusting to Riester and Rürup scheme reforms.
Corporations command premium pricing power. Small Businesses are gaining share fastest.
Coverage Type:
Maturity and margin profiles diverge across coverage architectures, with guaranteed products facing duration risk that contingent-payout structures avoid.
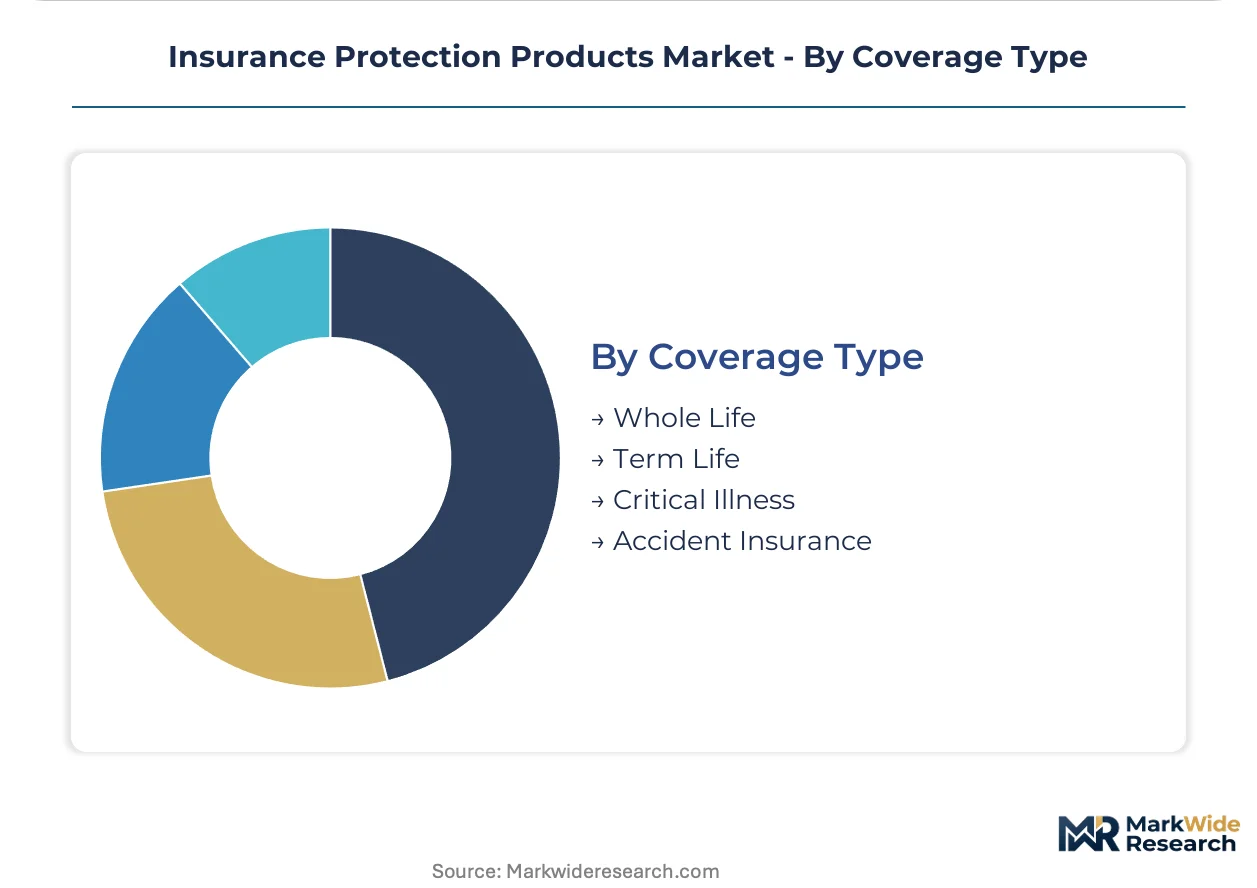
- Whole Life:Permanent coverage with cash value accumulation demands long-duration asset portfolios. Low-yield environments strain investment income subsidies for guaranteed pricing.
- Term Life:Pure mortality protection without cash value offers lower premiums and simpler underwriting. Workplace benefit platforms drive group term penetration in North America.
- Critical Illness:Lump-sum payouts upon diagnosis of specified conditions address medical cost exposure gaps. Product development faces EU AI Act algorithmic transparency documentation requirements.
- Accident Insurance:Contingent payouts for injury events utilize simpler underwriting than morbidity-based products. Bancassurance digitization through open banking APIs expands distribution reach.
Term Life holds installed capacity. Critical Illness is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lloyd's of London insurance marketplace anchors European risk-transfer capacity, while Singapore's financial district infrastructure underwrites Asia-Pacific distribution reach for multinational carriers.
United States
Workplace benefit platforms and employer-sponsored group life coverage drive volume concentration. HIPAA privacy constraints shape health information utilization in underwriting workflows. Hartford, Connecticut maintains its historical position as a domestic insurance cluster, with carriers digitizing policy administration to reduce legacy system dependencies.
Germany
Riester and Rürup pension scheme reforms accelerate defined contribution adoption among mid-size employers. EIOPA's Solvency II capital requirements determine product design feasibility across property and life lines. Munich and Frankfurt host the headquarters of major carriers leveraging captive reinsurance capabilities to sustain pricing power.
China
Aging demographics and medical cost inflation expand health insurance penetration in urban centers. NMPA oversight of wearable-integrated devices influences dynamic underwriting product development. Shanghai's Pudong financial district concentrates bancassurance distribution partnerships between domestic insurers and state-owned banks.
United Kingdom
Digital brokers capture small commercial demand through API-connected platforms quoting coverage in under ten minutes. FCA conduct regulations govern embedded insurance integrations through e-commerce and banking channels. London's Square Mile retains catastrophe reinsurance brokerage concentration despite Bermuda capacity competition.
Japan
Corporate pension scheme structures sustain group annuity product demand among established enterprises. METI guidelines on algorithmic transparency affect automated claims system deployment timelines. Tokyo's Marunouchi district hosts the headquarters of carriers integrating telematics into property risk assessment for commercial lines.
Insurance Protection Products Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in risk assessment and data provision. The market structure consolidates around diversified financial conglomerates with captive reinsurance capabilities and regional specialists with distribution depth. Three archetypes dominate: pan-Asian life insurers with bancassurance networks, European property-casualty carriers with commercial risk expertise, and North American workplace benefit platforms with employer channel control. Competitive moves concentrate on embedded insurance API partnerships and parametric product development using satellite and IoT trigger mechanisms.
Among the named carriers, Allianz and AXA exemplify the diversified conglomerate archetype with multi-line portfolios spanning life, health, and property operations across European and Asian markets. MetLife occupies a position within the workplace benefit specialization tier, leveraging employer distribution networks in North America. These three represent distinct strategic positioning vectors: reinsurance-integrated pricing power, digital health ecosystem anchoring, and group benefit platform consolidation respectively.
| Leading Market Players |
|---|
| Allianz |
| AXA |
| MetLife |
| Prudential |
| UnitedHealth Group |
| Chubb |
| Zurich |
| AIG |
| China Life Insurance |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European property-casualty lines is compressing reinsurance pricing power while forcing primary carriers into captive retention structures. This utilization dynamic reshapes both supplier consolidation patterns and front-book pricing posture across the value chain.
Pricing Analysis
EIOPA's Solvency II capital requirements dictate the pricing tier structure across European protection products, separating fully collateralized guaranteed-benefit offerings from capital-light contingent-payout structures. Three-tier pricing stratifies across premium whole-life, standard term-life, and economy direct-to-consumer digital products, with brand premium and distribution channel cost serving as primary differentiation drivers. Pricing pressure stems from sustained low-yield environments compressing investment income margins on long-duration liabilities. Small commercial buyers exhibit highest price sensitivity, migrating toward modular subscription products, while corporate group annuity purchasers prioritize benefit customization over premium minimization.
Supply Chain Analysis
Extended payment terms from Bermuda and London market reinsurers are tightening working capital requirements for primary carriers writing catastrophe-exposed property lines. Risk capacity concentrates in Bermuda, London, and Zurich, with satellite data providers and IoT sensor manufacturers serving as critical technology inputs. Single-source vulnerability in catastrophe reinsurance capacity creates pricing volatility when modeled loss estimates shift. Distribution runs through embedded insurance APIs, direct carrier platforms, and traditional broker networks serving commercial buyers with complex multi-line needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded insurance adoption represents an early-cycle expansion story, with API-connected distribution compressing acquisition costs while expanding addressable customer bases beyond traditional agent territories.
For Market Incumbents: Pre-empt disintermediation by captive reinsurance specialists through accelerated bancassurance digitization partnerships. Defensive consolidation should prioritize open banking API infrastructure in Germany and the Netherlands, while algorithmic transparency documentation capabilities address EU AI Act compliance timelines extending product development cycles.
For New Entrants and Emerging Players: Mid-size employer segments in Germany's Riester and Rürup pension reform environment offer underpenetration white-space for group annuity products. Target modular subscription-based coverage for gig economy platforms and micro-enterprises with volatile revenue streams. Go-to-market execution should leverage white-label partnerships with European banks eliminating branch infrastructure requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital health ecosystem platforms, reducing barrier-to-entry thresholds for wellness-integrated underwriting capabilities. Long-term viability across the projection horizon favors carriers with captive reinsurance pricing power or workplace benefit platform consolidation. Acquisition targets should demonstrate FDA-cleared wearable integration or parametric trigger technology using satellite data. The signal to monitor is reinsurance capacity pricing volatility in catastrophe-exposed lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Insurance API Development | E-commerce checkout integrations through banking apps eliminate traditional agent intermediation layers. |
| Parametric Product Expansion | Satellite-triggered automatic payouts reduce claims friction for agricultural and climate-vulnerable risks. |
| Wearable-Integrated Underwriting | FDA-cleared devices enable dynamic premium adjustment for individual life and health policies. |
| Bancassurance Digitization | Open banking partnerships create embedded distribution without physical branch infrastructure investment. |
| Cyber Insurance Product Development | DORA-mandated ICT risk frameworks accelerate operational investment across EU member states. |
Methodological Framework
Cross-validation between primary interviews with insurance executives and secondary regulatory filings anchors the qualitative findings. Actuarial directors, digital distribution heads, reinsurance placement specialists, and compliance officers across European and North American carriers provided operational perspective. Secondary sources include EIOPA Solvency II disclosures, FDA device clearance databases, HIPAA enforcement actions, and EU AI Act implementation guidance. Bottom-up premium pool estimates triangulate against top-down macroeconomic demographic projections.
Calibration against historical loss ratio patterns and investment yield trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, distribution channel economics, buyer sophistication tier, and coverage maturity profile. CAGRs derive from actuarial mortality improvement assumptions, medical cost inflation trajectories, and embedded insurance penetration curves. Forecast inputs incorporate reinsurance capacity pricing cycles and regulatory compliance timeline shifts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by insurtech platform specialists or hyperscaler banking entrants would shift outcomes. Macroeconomic deviation in interest rate environments, regulatory acceleration in algorithmic transparency mandates, or technological breakthroughs in predictive health modeling would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Global Healthcare Claims Management Market
Insurance
Asia-Pacific Liability Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
US Homeowner's Insurance Market
Insurance
Canada Home Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Property Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
India Dental Insurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
Global Sports Insurance Market
Insurance
Medical Claims Processing Services Market
Insurance
Canada House Insurance Market
Insurance
Japan Property and Casualty Insurance Market