
 Europe Parametric Insurance Market | 2026-2036
Europe Parametric Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Parametric Insurance Market Analytics
Modular policy bundling is shifting buyer choice across the Europe parametric insurance landscape. Zurich Insurance Group leverages its climate risk analytics platform to anchor multi-trigger offerings for corporate clients. Descartes Underwriting competes through specialized natural catastrophe products that bypass traditional loss adjustment.
Parametric insurance deploys pre-defined triggers—such as wind speed thresholds, rainfall indices, or seismic magnitude—to execute automatic payouts without conventional claims assessment. IoT sensor networks and satellite data feeds enable real-time trigger verification, reducing settlement cycles from months to days. Natural disaster insurance leads product type penetration as insurers seek alternatives to conventional indemnity models in flood-prone regions. Multi-trigger policy structures command premium positioning by stacking correlated perils into single contracts.
Solvency II capital requirements from EIOPA shape product design by mandating transparent risk transfer mechanics and standardized trigger documentation. The EU Green Deal's climate adaptation targets direct national regulators in Germany, France, and the Netherlands to embed parametric instruments into public disaster relief frameworks. Stakeholders must monitor how EIOPA's evolving catastrophe reserve standards redistribute capital between traditional reinsurance and algorithmic trigger structures.
Market Dynamics
EIOPA's evolving catastrophe reserve standards under Solvency II are compressing capital allocation timelines and forcing insurers to restructure risk transfer mechanics around algorithmic trigger verification rather than traditional loss adjustment protocols.
Growth Catalysts
- EU Green Deal climate adaptation mandates:National regulators in Germany, France, and the Netherlands embed parametric instruments into public disaster relief frameworks, creating institutional demand for standardized trigger products.
- IoT sensor network deployment:Real-time data feeds from ground-based sensors and satellite constellations enable instantaneous trigger verification, collapsing settlement cycles from months to days for agricultural cooperatives.
- Agricultural cooperative expansion:French and German farming collectives are scaling drought and flood coverage procurement, driving volume concentration in climate-vulnerable rural districts.
Market Restraints
- Basis risk in trigger design:Mismatches between parametric payouts and actual economic losses limit buyer confidence in single-index contracts, particularly for complex commercial property portfolios.
- Data infrastructure concentration:Satellite imagery and meteorological data feeds rely on a narrow supplier base concentrated in North American and European aerospace clusters, creating single-point-of-failure exposure.
- Solvency II capital charges:EIOPA's risk margin requirements for non-proportional reinsurance elevate holding costs for algorithmic trigger structures versus traditional indemnity reserves.
Strategic Opportunities
- Underpenetrated Southern European markets:Spain, Italy, and Portugal exhibit minimal parametric penetration despite elevated flood and wildfire exposure, presenting first-mover positioning for specialized underwriters.
- Multi-trigger policy bundling:Stacking correlated perils—wind, flood, and business interruption—into single contracts commands premium positioning and reduces buyer administrative burden.
- CSRD climate disclosure alignment:Corporate sustainability reporting mandates drive treasuries to adopt parametric solutions as demonstrable risk transfer instruments for stakeholder transparency.
Industry Challenges
- Actuarial talent scarcity:Shortages of professionals skilled in index-based pricing and climate data modeling constrain product development velocity across European underwriting hubs.
- Legacy system integration friction:Incumbent insurers face technical debt when embedding real-time trigger APIs into core policy administration platforms built on batch-processing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Parametric Insurance Market |
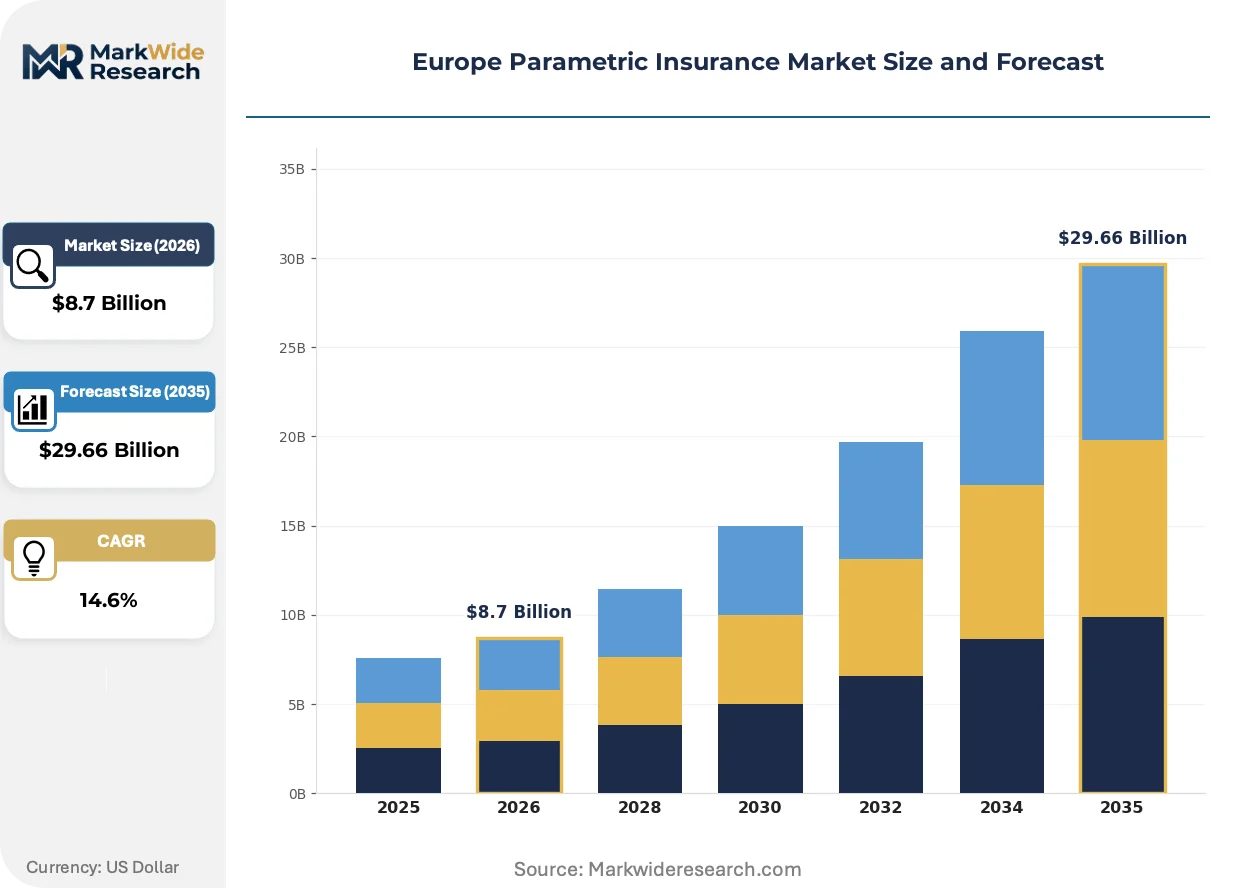
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weather Insurance, Flight Delay Insurance, Crop Insurance, Natural Disaster Insurance End User: Farmers, Corporations, Travelers, Small Businesses Distribution Channel: Online Platforms, Brokers, Direct Sales, Agents Policy Structure: Single Trigger, Multi-Trigger, Indexed, Customized |
| Companies Covered | Zurich Insurance Group, Hannover Re Group, Allianz SE, Descartes Underwriting, Lloyd's of London, Munich Re, Swiss Re, FloodFlash, AXA Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Parametric Insurance Market Evolving Landscape
Parametric insurance is automating core insurance functions through embedded data infrastructure, regulatory pressure is standardizing product documentation, and corporate risk managers are compressing procurement cycles toward faster-settling alternatives.
Blockchain-enabled smart contracts are automating payout execution upon satellite-verified trigger events. Mid-sized corporate risk managers in the United Kingdom and Germany are piloting these instruments for supply chain disruption coverage. The technology is automating claims settlement entirely, eliminating loss adjusters from the value chain and collapsing administrative overhead.
The EU Green Deal's climate adaptation targets are mandating parametric inclusion in national disaster relief frameworks. EIOPA is requiring transparent trigger documentation and standardized index methodologies. Agricultural cooperatives in France face the strictest compliance timelines, accelerating their shift from conventional indemnity to index-based structures.
Corporate treasury departments are unbundling risk transfer from traditional broker relationships. Direct placement platforms and insurer-hosted client portals are displacing intermediary-dependent procurement in the United Kingdom and Netherlands. Large manufacturing conglomerates in Germany's industrial belt exhibit the most aggressive channel migration, seeking price transparency and faster contract execution.
Europe Parametric Insurance Market Segmentation
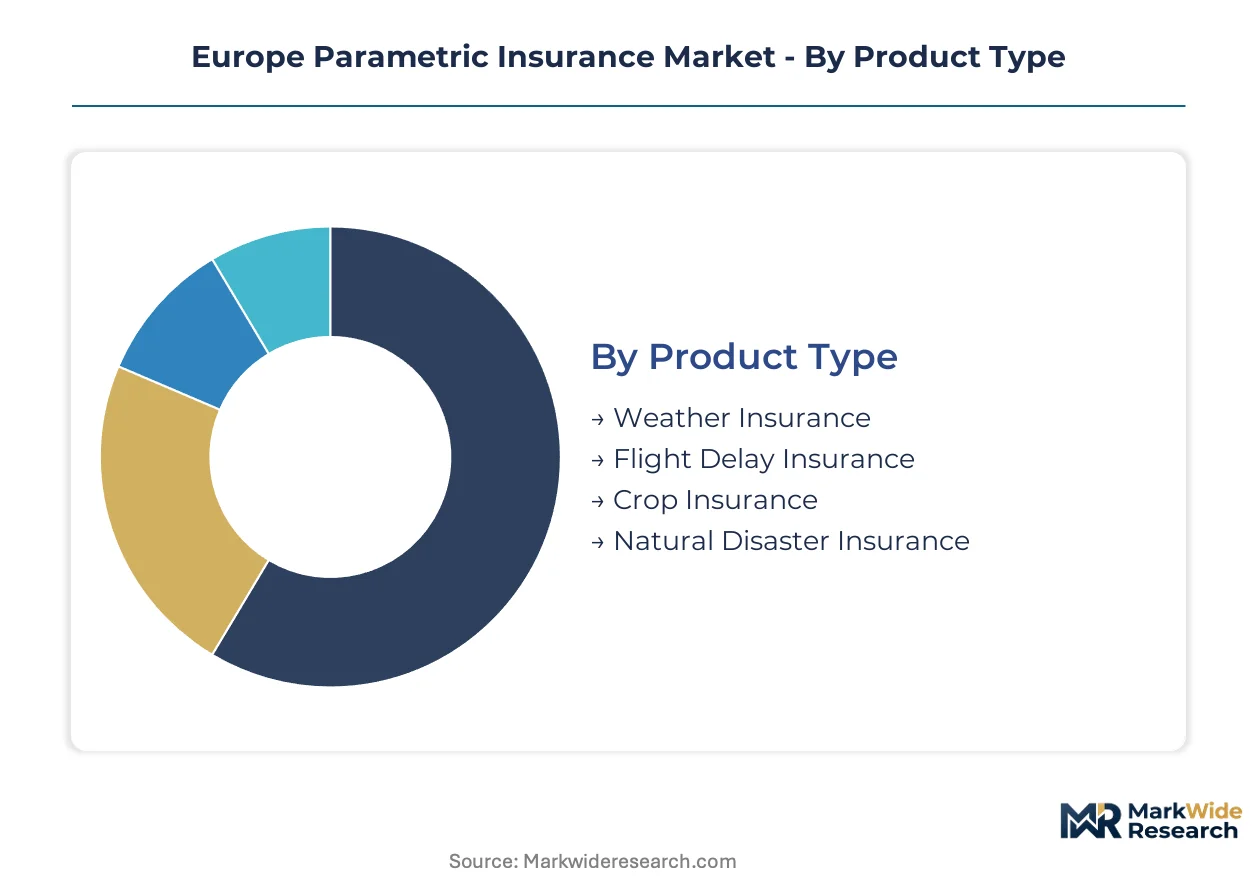
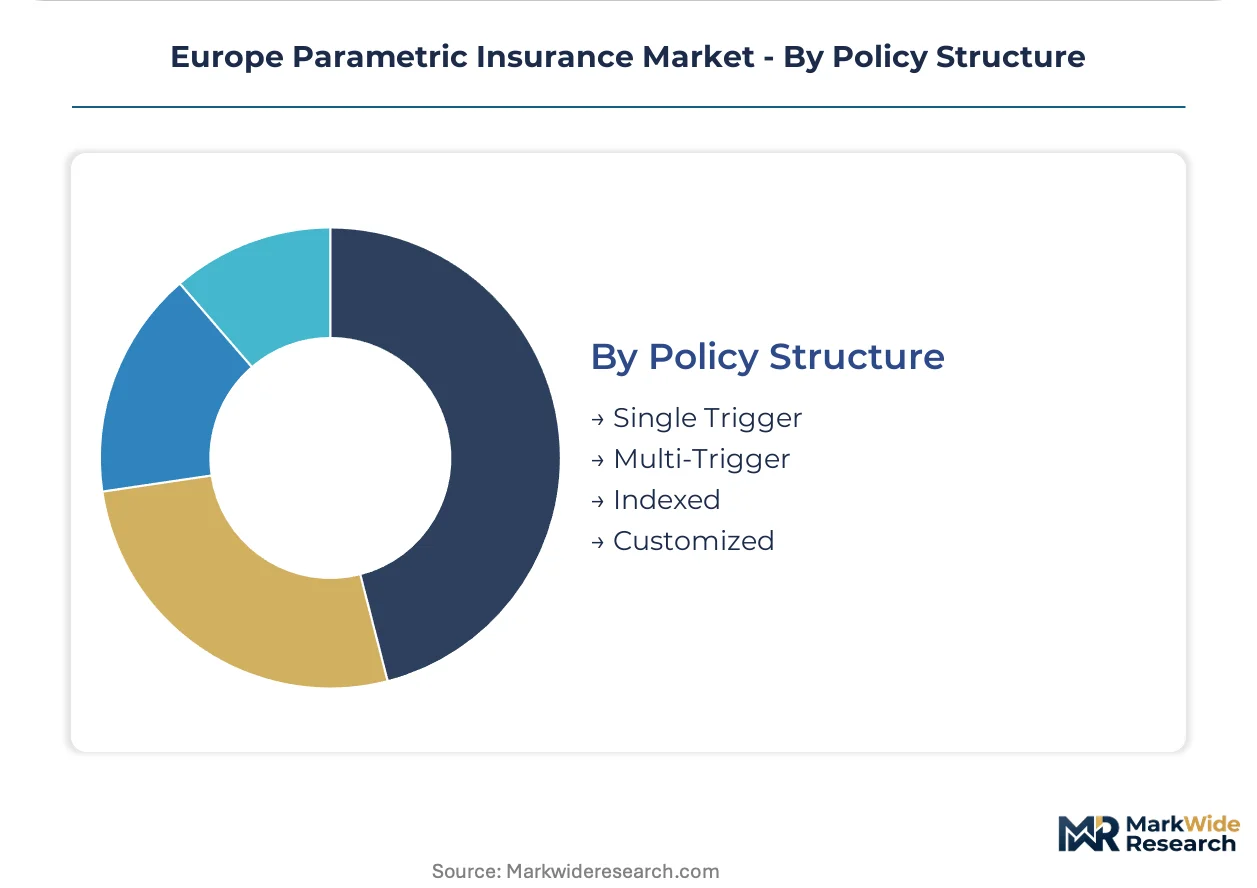
Parametric insurance segments diverge sharply by buyer sophistication and data infrastructure requirements. Corporate risk managers prioritize multi-trigger structures with embedded IoT verification, while agricultural cooperatives favor standardized weather indices with satellite-based settlement.
Product Type:
Corporate buyers select products based on peril specificity and settlement speed rather than premium cost alone.
- Natural Disaster Insurance:Covers seismic, flood, and wind events through magnitude or intensity triggers verified by satellite and ground sensor networks. German industrial conglomerates in the Rhine-Ruhr corridor are consolidating coverage here as EIOPA catastrophe reserve standards compress traditional reinsurance capacity.
- Crop Insurance:Deploys rainfall indices and temperature thresholds to automate payouts for drought and frost damage. French agricultural cooperatives in the Île-de-France and Grand Est regions are expanding procurement fastest as EU Green Deal adaptation mandates harden disclosure requirements.
- Weather Insurance:Protects against temperature and precipitation deviations for energy traders and event organizers. Construction firms in the Netherlands use these instruments to hedge project delays.
- Flight Delay Insurance:Automates payouts when aircraft departure thresholds are breached, verified through aviation data feeds. UK corporate travel managers are piloting these for executive mobility programs.
Natural disaster insurance leads on scale; crop insurance leads on momentum.
End User:
Volume concentrates where regulatory pressure intersects with climate exposure and balance sheet sophistication.
- Corporations:Multinational risk managers procure multi-trigger policies covering supply chain disruption across multiple geographies. German automotive suppliers and Dutch logistics operators are the most active adopters of blockchain-enabled smart contract settlement.
- Farmers:Agricultural cooperatives in France and Germany are shifting from indemnity to index-based structures as national regulators embed parametric instruments into disaster relief frameworks. Settlement speed matters more than basis risk mitigation for this cohort.
- Small Businesses:Retail and hospitality operators in flood-prone UK regions use single-trigger products for business interruption coverage with minimal underwriting friction.
- Travelers:Individual and corporate travel managers purchase flight delay and weather-linked policies through digital distribution platforms with instant payout execution.
Corporations dominate premium volume; farmers are expanding most quickly.
Distribution Channel:
Channel selection reflects buyer scale and tolerance for intermediary involvement in contract structuring.
- Brokers:Intermediate complex multi-trigger policies for large corporate buyers requiring customized peril stacking and basis risk analysis. London and Frankfurt brokerages retain dominance in catastrophe-linked placements.
- Online Platforms:Enable direct procurement of standardized single-trigger products with transparent pricing and instant quote generation. UK and Netherlands corporate treasuries are migrating fastest to disintermediated channels.
- Direct Sales:Insurer-hosted client portals serve multinational accounts with dedicated underwriters and API-embedded trigger verification. Zurich Insurance Group and Descartes Underwriting compete aggressively here.
- Agents:Distribute agricultural and small business products in rural districts where relationship-based selling persists. French mutual insurers deploy agent networks in Brittany and Normandy farming communities.
Brokers retain the largest transaction value; online platforms are gaining share fastest.
Policy Structure:
Structural complexity escalates with buyer sophistication and the need for correlated peril coverage.
- Multi-Trigger:Stacks wind, flood, and business interruption indices into single contracts with premium positioning. German manufacturers in flood-exposed river basins favor these for comprehensive asset protection without multiple policy administration.
- Single Trigger:Executes payout upon one verified parameter breach—rainfall below threshold, wind speed above limit. French viticulture cooperatives use these for frost protection with minimal contract complexity.
- Indexed:Ties payout magnitude to continuous index values rather than binary thresholds. Energy traders in the UK and Netherlands hedge temperature-driven demand fluctuations.
- Customized:Bespoke trigger design for unique asset portfolios or non-standard perils. Infrastructure funds financing North Sea offshore wind deploy these for combined weather and grid outage protection.
Multi-trigger structures command premium positioning; single-trigger products show the steepest expansion trajectory in agricultural segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parametric insurance first scaled commercially through Lloyd's of London catastrophe bonds in the 1990s, then migrated to continental Europe as Solvency II standardized capital treatment for index-based structures. The current landscape reflects divergent national regulatory timelines and climate exposure profiles.
Germany
Industrial conglomerates in the Rhine-Ruhr corridor consolidate multi-trigger policies covering flood and business interruption risks. BaFin enforces EIOPA catastrophe reserve standards that compress traditional reinsurance capacity, accelerating algorithmic trigger adoption. Munich anchors underwriting innovation for automotive suppliers seeking supply chain disruption coverage.
France
Agricultural cooperatives in Île-de-France and Grand Est scale drought and frost index procurement fastest. The Autorité de Contrôle Prudentiel et de Résolution embeds EU Green Deal adaptation mandates into national disaster relief frameworks. Brittany and Normandy farming communities shift from indemnity to satellite-verified settlement through mutual insurer agent networks.
United Kingdom
Corporate treasuries in London and Southeast England pilot blockchain-enabled smart contracts for flight delay and supply chain coverage. The Prudential Regulation Authority supervises Lloyd's syndicate capacity allocation toward parametric catastrophe instruments. Midlands manufacturing firms disintermediate brokers through direct placement platforms.
Netherlands
Construction firms and logistics operators in the Randstad region hedge project delays through temperature and precipitation indices. De Nederlandsche Bank aligns with EIOPA transparency requirements for trigger documentation. Rotterdam port operators test combined weather and grid outage protection for infrastructure financing.
Spain
Underpenetrated markets in Catalonia and Andalusia present first-mover positioning despite elevated flood and wildfire exposure. The Dirección General de Seguros y Fondos de Pensiones lags Northern European counterparts in parametric standardization. Madrid-based energy traders pilot temperature-driven demand hedging through indexed structures.
Europe Parametric Insurance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across data infrastructure sophistication and trigger verification speed. The market structures around three tiers: global reinsurance groups with captive climate analytics platforms, specialized parametric underwriters with satellite-native operations, and incumbent insurers retrofitting legacy systems. Consolidation pressures favor algorithmic trigger verification over traditional loss adjustment protocols. Strategic moves concentrate on multi-trigger product bundling and direct-to-corporate channel expansion.
Among Swiss-based reinsurance groups, Zurich Insurance Group and Swiss Re anchor the premium tier through climate risk analytics platforms and corporate client portals. Descartes Underwriting occupies a position among specialized underwriters competing through natural catastrophe products that bypass conventional claims assessment. Lloyd's of London exemplifies the market-maker archetype, hosting syndicate capacity that structures catastrophe-linked placements for European corporate buyers.
| Leading Market Players |
|---|
| Zurich Insurance Group |
| Hannover Re Group |
| Allianz SE |
| Descartes Underwriting |
| Lloyd's of London |
| Munich Re |
| Swiss Re |
| FloodFlash |
| AXA Group |
| Others |
Value Network & Pricing Analysis
Corporate risk managers in Germany's Rhine-Ruhr corridor anchor pricing power through multi-trigger policy consolidation, compressing supplier margins while rewarding algorithmic trigger verification speed over traditional loss adjustment overhead.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Zurich Insurance Group's climate analytics platform from Descartes Underwriting's satellite-native operations and agent-distributed agricultural products. Price differentiation rests on trigger verification speed and data infrastructure sophistication. Pricing pressure stems from EIOPA's catastrophe reserve standards elevating holding costs for algorithmic structures. Agricultural cooperatives in France exhibit highest price sensitivity; German automotive suppliers prioritize settlement speed over premium cost.
Supply Chain Analysis
Dual-sourcing requirements from BaFin and the Autorité de Contrôle Prudentiel et de Résolution mandate qualified alternative data feed providers, forcing underwriters to maintain parallel satellite imagery and ground sensor network relationships. Geographic supply concentration centers on France, Germany, and the United Kingdom for underwriting capacity, with meteorological data feeds anchored in European aerospace clusters. Raw material dependencies include satellite constellation access, IoT sensor hardware, and climate data modeling software. Single-point-of-failure exposure concentrates in North American and European aerospace data suppliers. Distribution runs through broker intermediaries for complex multi-trigger policies and direct insurer portals for standardized products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market is accelerating as blockchain-enabled smart contracts eliminate loss adjuster overhead and compress administrative costs toward algorithmic verification economics.
For Market Incumbents: Deploy captive climate analytics platforms to defend against specialized parametric underwriters. Zurich Insurance Group's multi-trigger bundling strategy and API-embedded trigger verification illustrate how legacy carriers consolidate corporate accounts. Incumbents must backward integrate into satellite data partnerships or cede premium positioning to satellite-native competitors.
For New Entrants and Emerging Players: The 40-60% premium gap between Lloyd's syndicate catastrophe placements and agent-distributed agricultural products creates entry space for mid-tier underwriters. Spain and Italy present the most penetrable geographies despite elevated flood and wildfire exposure. New entrants should target construction firms in the Netherlands with temperature-indexed project delay products through direct digital channels.
For Investors and Strategic Acquirers: Reinsurance groups with captive climate analytics platforms are the most active acquirers in this space, consolidating specialized parametric underwriters to fill capability gaps. Long-term viability favors algorithmic trigger verification over traditional loss adjustment protocols. Acquisition targets with satellite-native operations and EIOPA-compliant documentation frameworks command strategic premiums. Watch EIOPA's evolving catastrophe reserve standards as the inflection signal redistributing capital between traditional reinsurance and algorithmic structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Climate Analytics Platform Development | Zurich Insurance Group anchors multi-trigger corporate offerings through proprietary risk modeling infrastructure. |
| Blockchain Smart Contract Integration | UK corporate treasuries pilot automated payout execution eliminating loss adjusters from settlement chains. |
| Satellite-Native Operations Buildout | Descartes Underwriting competes through specialized natural catastrophe products bypassing conventional claims assessment. |
| Direct-to-Corporate Channel Expansion | German automotive suppliers disintermediate brokers through insurer-hosted client portals with API-embedded verification. |
| EIOPA Compliance Documentation Investment | French agricultural cooperatives accelerate index-based shifts as national regulators embed parametric instruments into relief frameworks. |
Research Methodology
Coverage spans Germany, France, the United Kingdom, the Netherlands, and Spain, with primary inputs from each national regulatory cluster. The analysis combines primary interviews with risk managers at German automotive suppliers, French agricultural cooperative directors, UK corporate treasury officers, Dutch construction firm procurement leads, and Spanish energy traders with secondary validation. Secondary sources include EIOPA regulatory filings, BaFin solvency reports, EU Green Deal implementation documents, and national disaster relief framework guidelines. Bottom-up policy volume aggregation and top-down premium market sizing were triangulated to derive segment-level outputs.
Rate-of-change decomposition across the analysis window isolates volume drivers from price effects in parametric insurance expansion. The forecast framework models product type, end user, distribution channel, and policy structure segmentation alongside regulatory compliance tier and data infrastructure sophistication. CAGRs were derived through trend extrapolation of historical adoption curves adjusted for EIOPA capital requirement phase-ins and EU Green Deal mandate timelines. Climate exposure indices and corporate sustainability reporting adoption rates served as industry-specific forecast inputs.
Caveats apply where EIOPA catastrophe reserve standard revisions or EU Green Deal timeline accelerations could materially shift the outlook. Forecasts reflect assumptions about regulatory implementation consistency, satellite data feed reliability, and corporate treasury risk management practice evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Japan Property and Casualty Insurance Market
Insurance
Medical Professional Liability Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
Disability Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
Digital Monetary Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Fire Insurance Market
Insurance
Green Insurance Market
Insurance
Greece Property and Casualty Insurance Market
Insurance
MENA Health and Medical Insurance Market
Insurance
Drone Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
Asia-Pacific EV Insurance Market
Insurance
Agriculture Insurance Market