
 France Property and Casualty Insurance Market | 2026-2036
France Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
France Property and Casualty Insurance Market Foresight
Project finance and asset-light reinsurance structures is tilting competitive dynamics toward carriers with superior capital flexibility. AXA France leverages its bancassurance network to sustain premium flow across retail segments. Covéa anchors its position through mutual ownership structures that reduce cost-of-capital pressure. Crédit Agricole Assurances competes by integrating property coverage with agricultural lending relationships.
Property and casualty insurance constitutes risk transfer contracts indemnifying policyholders against physical damage, legal liability, and income interruption, with technical pricing grounded in actuarial loss modeling, reinsurance treaty structures, and statutory solvency margin requirements. Its primary commercial purpose is stabilizing corporate and household balance sheets against unpredictable loss events. Auto Insurance and Commercial Property Insurance command the largest premium pools, while Liability Insurance generates superior underwriting margins amid rising litigation frequency. Bancassurance and Insurance Brokers dominate distribution, though Online Platforms are capturing younger policyholder cohorts through embedded purchasing journeys.
ACPR, the French prudential supervisor, enforces Solvency II capital adequacy rules that shape product pricing and reserve requirements across the sector. EU Green Deal disclosure obligations and France's ORSEC natural catastrophe framework are redirecting coverage design toward climate resilience parameters. Stakeholders must monitor how DORA implementation redefines cyber coverage standards and intermediary accountability before committing to multi-year distribution partnerships.
Market Dynamics
Digital Operational Resilience Act (DORA) implementation is restructuring capital allocation and product design across French property and casualty carriers, forcing simultaneous upgrades to policyholder cyber coverage standards and internal operational risk frameworks.
Growth Catalysts
- Cyber Risk Exposure Widening:French small business owners are expanding coverage purchases as ransomware incidents and supply chain vulnerabilities multiply across manufacturing and professional services verticals.
- EU Green Deal Disclosure Obligations:Climate resilience parameters are redirecting commercial property coverage design toward flood-resistant construction standards and renewable energy asset protection.
- Île-de-France Commercial Density:Fleet concentrations and property density in the Paris metropolitan corridor sustain premium flow for auto and commercial multi-peril lines.
Market Restraints
- Reinsurance Cost Volatility:Natural catastrophe treaty renewals are absorbing elevated capital charges following consecutive storm seasons in Atlantic and Mediterranean coastal zones.
- Solvency II Capital Adequacy Pressure:ACPR reserve requirements compress underwriting capacity for long-tail liability exposures, particularly environmental and construction defect risks.
- Legacy Core System Dependencies:Mainframe policy administration platforms constrain real-time data integration for usage-based auto and parametric property products.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur Agricultural Expansion:Viticulture and specialized crop operations in southeastern France remain underpenetrated for revenue protection and parametric weather coverage.
- Bancassurance Channel Convergence:Embedded purchasing journeys through retail banking apps capture younger policyholder cohorts before traditional broker relationships form.
- ORSEC Framework Alignment:France's natural catastrophe response coordination system creates demand for business interruption products with civil authority trigger clauses.
Industry Challenges
- Actuarial Talent Scarcity:Shortages in cyber risk modeling and climate scenario analysis expertise delay product development cycles for emerging peril categories.
- Intermediary Accountability Reconfiguration:DORA's operational resilience standards require distribution partners to maintain equivalent cybersecurity postures, fragmenting traditional broker networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Property and Casualty Insurance Market |
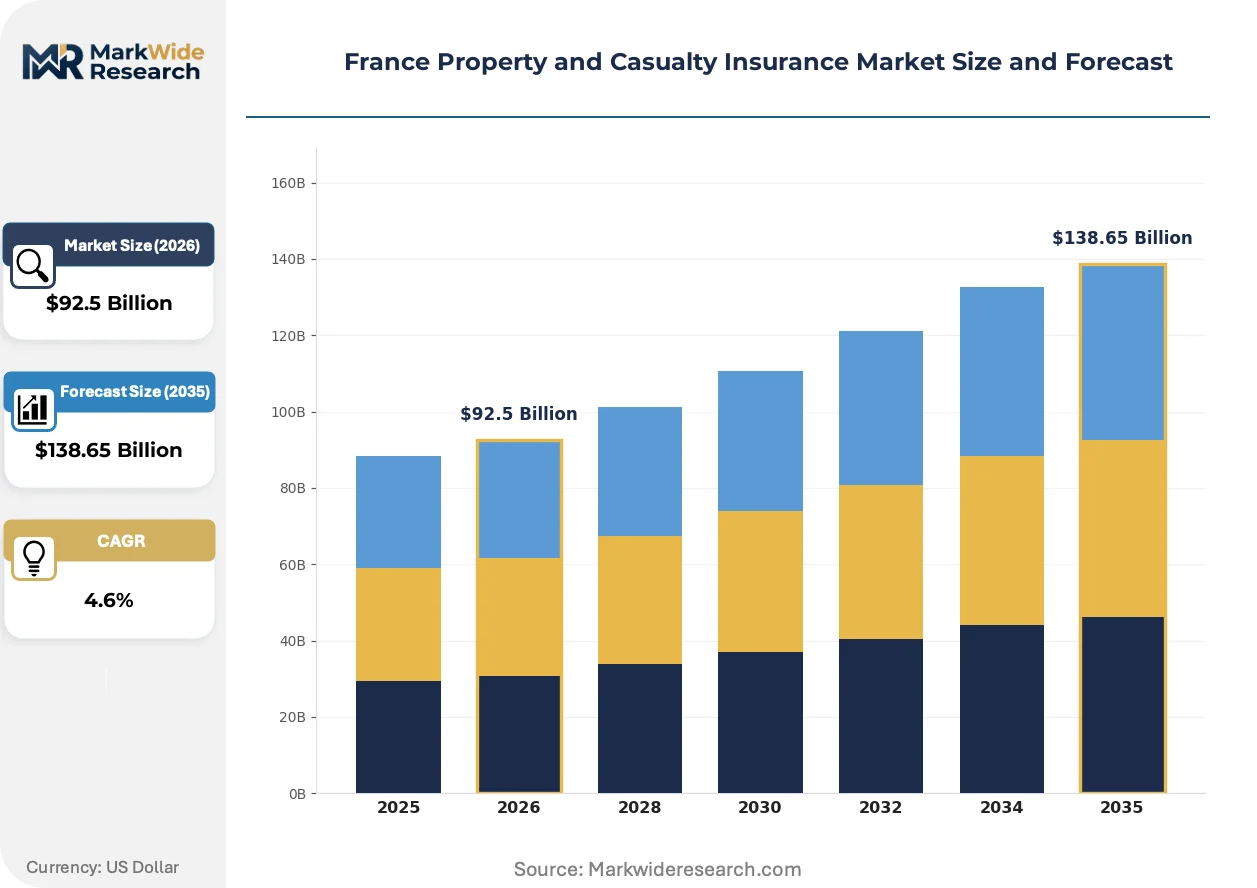
| Market Size in 2026 | $92.5 Billion |
| Market Size in 2035 | $138.65 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homeowners Insurance, Auto Insurance, Liability Insurance, Commercial Property Insurance, Workers Compensation, Marine Insurance Distribution Channel: Direct Sales, Insurance Brokers, Bancassurance, Online Platforms, Agents, Affinity Groups Policyholder Type: Individual Policyholders, Small Business Owners, Corporate Clients, Nonprofit Entities, Public Sector Organizations, Freelancers Coverage Type: Fire and Theft, Natural Disaster, Liability Protection, Vehicle Damage, Personal Accident, Legal Assistance |
| Companies Covered | Allianz France, Macif, AXA France, BNP Paribas Cardif, Generali France, Covéa, Crédit Agricole Assurances, CNP Assurances, Groupama, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Property and Casualty Insurance Market Shifts & Advancements
Telematics integration and parametric triggers are compressing traditional indemnity structures, while regulatory disclosure mandates accelerate climate risk transparency across underwriting portfolios.
Usage-based auto insurance platforms are virtualizing traditional mileage and behavior rating factors through smartphone-enabled data capture. Younger policyholder cohorts in Île-de-France and Rhône-Alpes are adopting these programs at triple the rate of conventional annual policies. This shift is virtualizing actuarial risk pools from geographic aggregation toward individual driving behavior granularity.
France's ORSEC natural catastrophe framework is mandating standardized exposure data formats for commercial property submissions to national emergency planning databases. Industrial facilities in flood-prone Seine and Rhône corridors must now pre-file business continuity protocols to qualify for premium discounts. Manufacturing and logistics operations are responding by procuring contingent business interruption riders with civil authority coverage triggers.
Embedded insurance purchasing through automotive and real estate transaction platforms is displacing traditional annual renewal cycles. French auto dealerships and property notaries are integrating coverage selection into closing workflows, capturing policyholders at point of asset acquisition. This pattern concentrates in urban property markets and fleet leasing channels where transaction velocity supports seamless coverage activation.
France Property and Casualty Insurance Market Segmentation
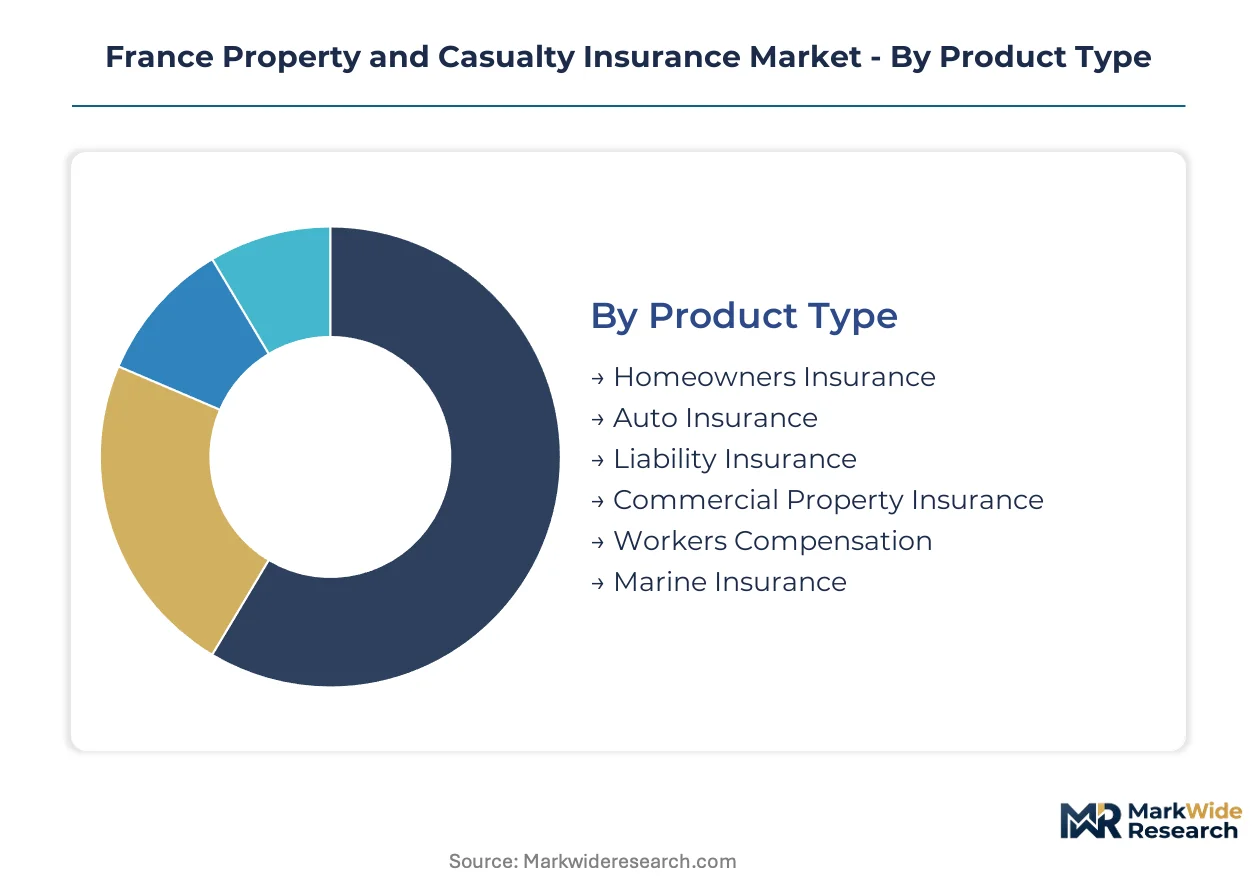
Segmentation in French property and casualty insurance determines capital allocation, distribution investment, and regulatory compliance intensity. Each dimension—product, channel, policyholder, and coverage—carries distinct Solvency II capital requirements and ACPR reporting obligations that shape carrier strategy.
Product Type:
Cost tier differentiation separates mass-market personal lines from capital-intensive commercial portfolios requiring reinsurance treaty support.
- Auto Insurance:Technical pricing integrates telematics data streams from smartphone-enabled platforms for usage-based rating in Île-de-France and Rhône-Alpes. Younger policyholder cohorts adopt these programs at triple the rate of conventional annual policies, compressing traditional geographic risk pools toward individual behavior granularity.
- Commercial Property Insurance:ORSEC framework compliance mandates standardized exposure data formats for flood-prone Seine and Rhône corridor submissions. Industrial facilities must pre-file business continuity protocols to qualify for premium discounts, driving demand for contingent business interruption riders with civil authority triggers.
- Homeowners Insurance:Natural catastrophe coverage dominates premium considerations in Atlantic and Mediterranean coastal zones.
- Liability Insurance:Rising litigation frequency generates superior underwriting margins amid ACPR reserve pressure on long-tail exposures.
- Workers Compensation:Statutory coverage requirements sustain stable premium flow across manufacturing and construction verticals.
- Marine Insurance:Port of Marseille activity and Channel shipping lanes anchor cargo and hull coverage demand.
Auto Insurance commands the established base. The steepest expansion runs through Commercial Property Insurance.
Distribution Channel:
Application integration determines customer acquisition cost and policyholder lifetime value across traditional and digital pathways.
- Bancassurance:Embedded purchasing journeys through Crédit Agricole and BPCE retail banking apps capture younger policyholder cohorts before traditional broker relationships form. AXA France leverages this channel to sustain premium flow across retail segments with reduced acquisition friction.
- Insurance Brokers:Commercial mid-market and corporate placement depends on intermediary expertise for complex multi-peril structuring and reinsurance placement. DORA operational resilience standards now require distribution partners to maintain equivalent cybersecurity postures, fragmenting traditional networks.
- Direct Sales:Carrier-owned channels concentrate on simple personal lines with standardized underwriting.
- Online Platforms:Comparison engines and embedded insurance purchasing displace annual renewal cycles in auto and property transactions.
- Agents:Territorial representation persists in rural départements with limited digital infrastructure penetration.
- Affinity Groups:Professional associations and trade federations negotiate collective coverage terms for member businesses.
Bancassurance anchors the established base. The steepest expansion runs through Online Platforms.
Policyholder Type:
Customer type segmentation aligns capital intensity with service model requirements from standardized retail to bespoke corporate placement.
- Corporate Clients:Multi-national programs require centralized policy administration across EU subsidiaries with Solvency II cross-border compliance. Risk managers prioritize captives and fronting arrangements for environmental and construction defect exposures where ACPR reserve requirements compress standard market capacity.
- Small Business Owners:Cyber risk exposure widening drives coverage expansion as ransomware incidents multiply across manufacturing and professional services verticals. EU DORA implementation tightens compliance requirements for this cohort simultaneously with carrier operational framework upgrades.
- Individual Policyholders:Mass-market personal lines dominate premium volume through bancassurance and direct channels.
- Nonprofit Entities:Social economy organizations require specialized directors and officers coverage.
- Public Sector Organizations:State-owned enterprises and local authorities procure through centralized purchasing frameworks.
- Freelancers:Professional indemnity and portable equipment coverage gaps persist in creative and consulting sectors.
Individual Policyholders command the established base. The steepest expansion runs through Small Business Owners.
Coverage Type:
Maturity differentiation separates commoditized standard covers from emerging peril categories requiring actuarial innovation.
- Natural Disaster:Caisse Centrale de Réassurance backstop mechanism and ORSEC framework alignment create standardized exposure protocols. Flood-resistant construction standards and renewable energy asset protection redirect commercial property coverage design under EU Green Deal disclosure obligations.
- Liability Protection:Construction defect and environmental impairment exposures face Solvency II capital adequacy pressure from ACPR reserve requirements. Covéa anchors market position through mutual ownership structures that reduce cost-of-capital pressure on these long-tail lines.
- Fire and Theft:Traditional property damage coverage retains stable demand across residential and commercial portfolios.
- Vehicle Damage:Telematics-enabled claims assessment reduces indemnity leakage in auto physical damage.
- Personal Accident:Supplementary health coverage integration varies by bancassurance partnership structure.
- Legal Assistance:Access to justice coverage expands as litigation funding mechanisms mature in French courts.
Fire and Theft commands the established base. The steepest expansion runs through Natural Disaster.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU DORA implementation and ORSEC natural catastrophe protocols are redirecting capital allocation toward cyber resilience and climate-adaptive coverage across French metropolitan corridors.
Île-de-France
Commercial property density and fleet concentrations sustain premium flow for auto and commercial multi-peril lines. ACPR enforces Solvency II capital adequacy rules that compress underwriting capacity for long-tail exposures. Paris metropolitan corridor manufacturing and logistics operations procure contingent business interruption riders with civil authority coverage triggers.
Auvergne-Rhône-Alpes
Telematics-enabled usage-based auto insurance platforms capture younger policyholder cohorts at triple the rate of conventional annual policies. EU Green Deal disclosure obligations redirect commercial property coverage design toward flood-resistant construction standards. Lyon and Grenoble industrial clusters drive demand for renewable energy asset protection and parametric weather coverage.
Provence-Alpes-Côte d'Azur
Viticulture and specialized crop operations remain underpenetrated for revenue protection and parametric weather coverage. ORSEC framework alignment creates standardized exposure protocols for natural catastrophe submissions. Marseille port activity anchors cargo and hull coverage demand across Mediterranean shipping lanes.
Hauts-de-France
Manufacturing verticals expand cyber coverage purchases as ransomware incidents multiply across supply chain networks. DORA operational resilience standards require distribution partners to maintain equivalent cybersecurity postures. Lille metropolitan logistics corridors concentrate fleet leasing channels where embedded insurance purchasing displaces traditional annual renewal cycles.
Nouvelle-Aquitaine
Atlantic coastal zones absorb elevated natural catastrophe treaty renewal costs following consecutive storm seasons. Caisse Centrale de Réassurance backstop mechanism stabilizes coverage availability for flood-prone residential portfolios. Bordeaux wine production and specialized agriculture drive demand for climate resilience parameter integration in commercial property submissions.
France Property and Casualty Insurance Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent capital intensity requirements. Bancassurance networks and mutual ownership structures concentrate retail premium flow, while reinsurance-dependent commercial lines fragment among capacity-constrained underwriters. Three archetypes dominate: integrated financial conglomerates with banking distribution, mutual insurers with reduced cost-of-capital pressure, and specialized liability carriers with long-tail expertise. Competitive moves center on embedded purchasing journey integration and operational resilience framework upgrades.
Within the mutual tier, Covéa anchors positioning through ownership structures that reduce Solvency II capital pressure on environmental and construction defect exposures. AXA France and Crédit Agricole Assurances represent the bancassurance archetype, leveraging retail banking app integration to capture policyholder relationships before traditional broker networks form. These three entities exemplify how distribution control and capital structure flexibility determine competitive positioning amid DORA compliance requirements.
| Leading Market Players |
|---|
| Allianz France |
| Macif |
| AXA France |
| BNP Paribas Cardif |
| Generali France |
| Covéa |
| Crédit Agricole Assurances |
| CNP Assurances |
| Groupama |
| Others |
Supply & Pricing Matrix
Undercapacity in cyber risk modeling expertise across French actuarial labor markets compresses product development timelines while elevating technical pricing premiums for emerging coverage categories. This utilization squeeze simultaneously constrains carrier underwriting capacity and hardens rates for small business cyber policies in Île-de-France manufacturing corridors.
Pricing Analysis
Solvency II capital tier creates the primary spread between mutual and stock carrier rate filings, with Covéa's ownership structure enabling softer pricing on long-tail environmental exposures than AXA France's bancassurance-dependent cost base. Three-tier pricing structure across premium, standard, and economy levels stratifies by distribution channel friction, with broker-placed corporate programs commanding rate adequacy advantages over direct personal lines. Pricing pressure stems from reinsurance treaty cost volatility following Atlantic storm seasons, compressing margins on natural catastrophe-exposed commercial property in Nouvelle-Aquitaine. Small business owners in Hauts-de-France manufacturing verticals exhibit highest price sensitivity, while corporate risk managers prioritize coverage breadth over rate competition.
Supply Chain Analysis
Reinsurance capacity feeds from Munich, London, and Bermuda treaty markets, with European mutual pools and Lloyd's syndicates anchoring catastrophe excess-of-layers placement for French carriers. Retrocession capacity, collateralized reinsurance instruments, and specialty cyber quota-shares constitute critical inputs. Single-source vulnerability concentrates in Mediterranean windstorm modeling vendors, where three firms dominate scenario generation for Caisse Centrale de Réassurance submissions. Distribution runs through bancassurance networks for retail lines and broker-led placement for commercial risks, with embedded insurance partnerships emerging in automotive and real estate transaction platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parametric insurance and captive self-insurance structures threaten traditional indemnity market share as corporate risk managers seek balance sheet alternatives to volatile treaty renewals. Incumbents must defend substitution encroachment through product innovation and distribution lock-in.
For Market Incumbents: Entrench bancassurance channel control through API-level integration with Crédit Agricole and BPCE retail banking platforms, preempting fintech distribution disintermediation. Deepen operational resilience certifications under DORA implementation to fragment non-compliant broker networks and capture orphaned commercial mid-market accounts. Prioritize backward integration into telematics data infrastructure for usage-based auto pricing granularity in Rhône-Alpes. For New Entrants and Emerging Players: Build out parametric weather coverage for viticulture operations in Provence-Alpes-Côte d'Azur, where revenue protection penetration remains below commercial property density would suggest. Target agricultural cooperative distribution partnerships before established carriers extend mutual ownership structures into specialized crop lines. Pursue embedded insurance integration with Provence wine consortium transaction platforms as primary go-to-market pathway. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bancassurance-integrated carriers with retail banking exclusivity arrangements, offering superior visibility through economic cycles than reinsurance-dependent commercial specialists. Acquisition focus should center on mutual insurers with untapped cyber coverage development capacity and existing ORSEC framework compliance infrastructure. Monitor DORA implementation enforcement intensity as inflection indicator for intermediary network consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cyber Coverage Product Launch | DORA compliance mandates create first-mover advantage for operational resilience-certified carriers in SME segment. |
| Bancassurance Platform Integration | Embedded purchasing journeys through BPCE and Crédit Agricole apps capture policyholder relationships before broker formation. |
| Parametric Weather Coverage Expansion | ORSEC framework alignment enables standardized exposure protocols for viticulture revenue protection in Provence. |
| Reinsurance Treaty Restructuring | Collateralized capacity from Bermuda markets reduces Atlantic storm season volatility absorption for Nouvelle-Aquitaine portfolios. |
| Telematics Data Partnership | Smartphone-enabled usage-based auto platforms compress geographic risk pools toward individual behavior granularity in Île-de-France. |
Research Methodology
Operator-level perspectives from chief underwriting officers, reinsurance placement brokers, ACPR supervisory staff, and SME risk managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through Solvency II public disclosure filings, Caisse Centrale de Réassurance annual reports, and EU DORA regulatory impact assessments. Bottom-up premium volume estimates by product line triangulated against top-down macroeconomic exposure modeling.
Scenario-bracketing around natural catastrophe frequency, cyber loss development patterns, and interest rate trajectories bounded the projection range across the analysis window. Segmentation dimensions modeled include product type, distribution channel, policyholder category, and regional exposure cluster, with specific weighting for ORSEC framework compliance intensity and bancassurance channel penetration. CAGRs derived from actuarial loss cost trend analysis combined with regulatory capital requirement projections, incorporating reinsurance treaty renewal pricing assumptions and telematics adoption curve estimates for usage-based auto lines.
Sensitivities concentrate around Atlantic storm season severity, DORA enforcement calibration by ACPR, and actuarial talent migration patterns affecting cyber product development velocity. Forecasts embed assumptions regarding mutual ownership structure persistence and bancassurance exclusivity renewal negotiations. Cross-checking against Caisse Centrale de Réassurance exposure database submissions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Telematics-Based Auto Insurance Market
Insurance
Parametric Insurance Market
Insurance
Global Fine Art Insurance Market
Insurance
Saudi Arabia Property and Casualty Insurance Market
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Asia-Pacific Liability Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
Takaful Insurance Market
Insurance
Agriculture Insurance Market
Insurance
US Electronic Gadgets Insurance Market
Insurance
Germany Car Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Usage-Based Insurance (UBI) Market
Insurance
GCC Health Insurance Market