
 Factory and Warehouse Insurance Market | 2026-2036
Factory and Warehouse Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Factory and Warehouse Insurance Market Analysis
OSHA's process safety management standards are expanding the baseline coverage threshold for chemical and heavy manufacturing facilities. Allianz SE leverages its engineering risk consulting arm to pre-qualify industrial clients before policy issuance. Chubb Limited anchors its factory underwriting with specialized valuation services that reduce claims disputes. Tokio Marine Holdings competes through captive insurance structures for Japanese automotive manufacturers with US operations.
Factory and warehouse insurance protects physical structures, inventory, machinery, and operational continuity against fire, natural catastrophe, equipment failure, and third-party liability, with policies typically specifying replacement-cost valuation methods and business interruption indemnity periods of 12 to 24 months. Property insurance dominates premium volume across manufacturing and logistics verticals, where asset concentration and supply chain interdependency inflate maximum probable loss calculations. Business interruption coverage is growing fastest among food processing clients, as temperature-controlled supply chains multiply contingent business income exposures from single-point refrigeration failures.
OSHA, the EPA, and state-level building codes collectively determine minimum safety infrastructure that insurers mandate before binding coverage on aging industrial facilities. The National Fire Protection Association's updated ammonium nitrate storage standards are reshaping underwriting questionnaires for fertilizer and chemical warehouses. Stakeholders must monitor how parametric climate risk models recalibrate deductible structures and capacity allocation across catastrophe-exposed industrial corridors.
Market Dynamics
Climate risk modeling is electrifying underwriting methodologies across factory and warehouse portfolios, forcing carriers to rebuild rating engines around parametric triggers and satellite-based loss verification rather than traditional indemnity structures.
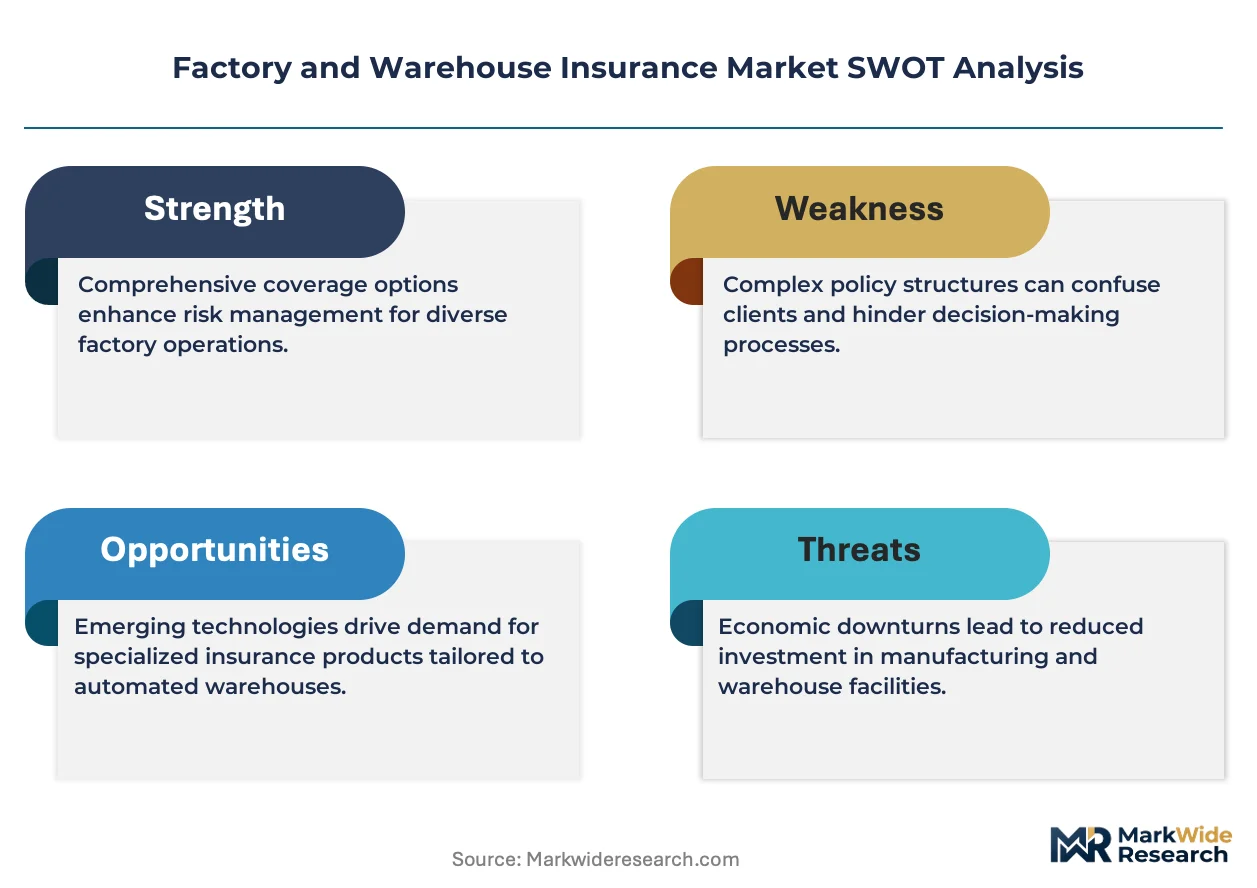
Growth Catalysts
- E-commerce fulfillment density:Temperature-controlled last-mile facilities in Germany and the Netherlands are expanding coverage limits to address spoilage exposure from single-point refrigeration failures.
- EU Green Deal building mandates:Energy efficiency retrofit requirements are triggering policy endorsements that bundle property coverage with performance guarantees for industrial envelope upgrades.
- OSHA process safety expansion:Chemical and heavy manufacturing facilities face elevated baseline coverage thresholds as federal inspection protocols tighten around ammonium nitrate and combustible dust hazards.
Market Restraints
- Reinsurance capacity contraction:Catastrophe bond spreads for industrial property risks have widened as climate loss experience deteriorates in US Gulf Coast and Florida corridors.
- Aging electrical infrastructure:Pre-1980 factory panels in the US Midwest and UK Midlands carry elevated fire ignition rates that standard deductibles fail to price adequately.
- Parametric basis risk:Index-triggered policies for flood and wind exposure leave policyholders exposed when physical damage exceeds satellite-derived loss estimates.
Strategic Opportunities
- Captive insurance expansion:Japanese automotive manufacturers with US assembly operations are establishing Vermont and Bermuda domiciled captives to retain predictable property layers.
- Supply chain contingent BI:Food processing clients are purchasing 24-month indemnity periods covering revenue loss from critical supplier refrigeration failures.
- Engineering risk pre-qualification:Carriers are embedding loss control inspections into binding authority workflows, creating fee-based consulting revenue streams separate from premium income.
Industry Challenges
- Valuation methodology disputes:Replacement cost clauses for specialized manufacturing equipment generate claims litigation when functional obsolescence accelerates depreciation schedules.
- Interdependent supply chain mapping:Tier-three supplier concentration in single industrial zones creates correlated loss scenarios that exceed traditional maximum probable loss calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Factory and Warehouse Insurance Market |
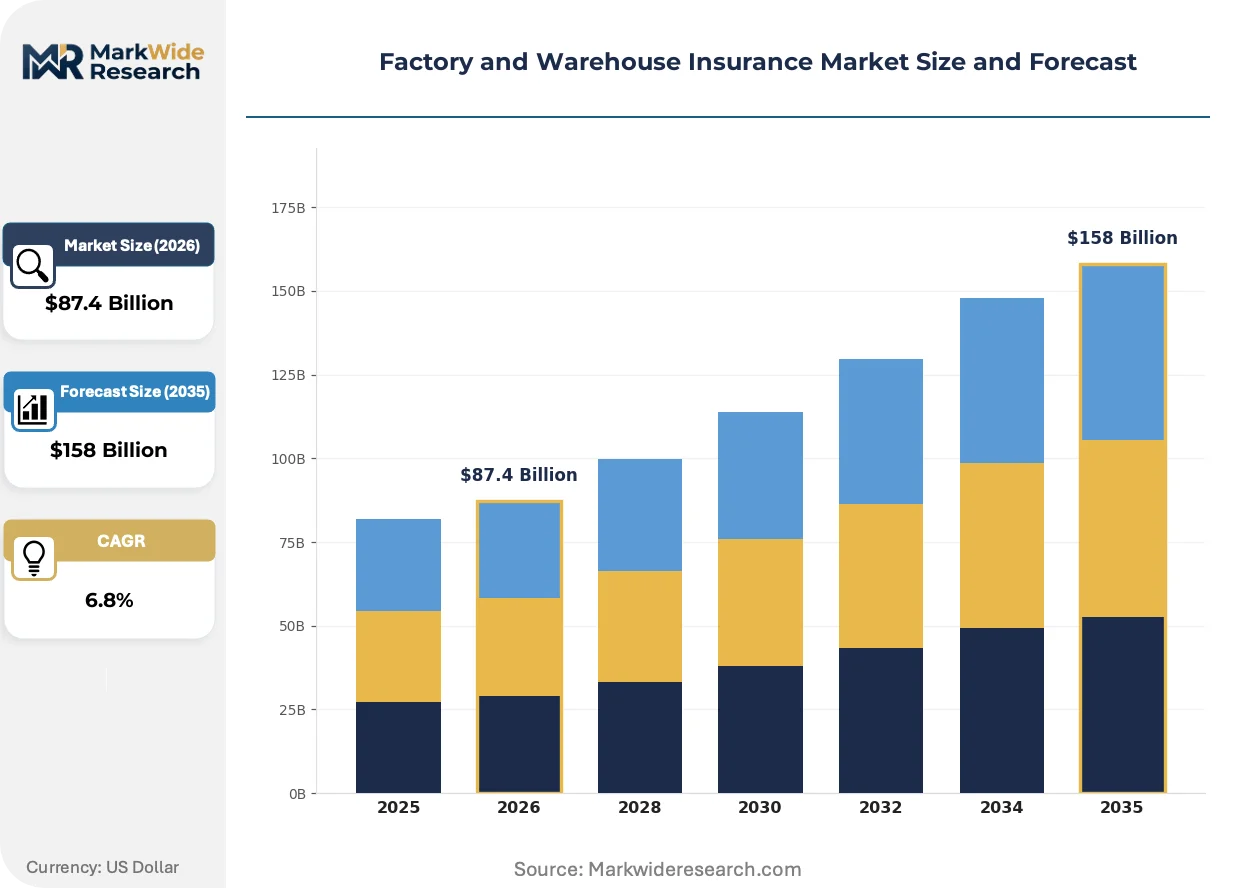
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Property Insurance, Liability Insurance, Business Interruption, Equipment Breakdown Industry Vertical: Manufacturing, Logistics, Food Processing, Retail Policy Type: Comprehensive, Specific, Named Peril, All Risk Client Type: Small Enterprises, Medium Enterprises, Large Corporations, Non-profits |
| Companies Covered | AXA SA, Zurich Insurance Group, Allianz SE, Chubb Limited, AIG, The Hartford, Tokio Marine Holdings, Liberty Mutual Insurance, Travelers Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Factory and Warehouse Insurance Market Emerging Trajectories
Digital twin technology is compressing the interval between risk assessment and policy issuance, enabling real-time monitoring of structural integrity and inventory fluctuations across distributed warehouse networks.
Parametric climate risk models are electrifying deductible structures across catastrophe-exposed industrial corridors. These satellite-verified triggers enable immediate liquidity post-event without traditional loss adjustment. German chemical manufacturers operating Rhine floodplains are piloting index-linked coverage that settles within 72 hours of water level thresholds being breached.
The National Fire Protection Association's updated ammonium nitrate storage standards are reshaping underwriting questionnaires for fertilizer and chemical warehouses throughout the US Corn Belt. Carriers now mandate passive fire protection systems and blast-resistant construction for facilities above threshold tonnages. State-level enforcement variations between Texas and Illinois are creating compliance complexity for multi-site operators.
Buyer concentration among third-party logistics providers is compressing placement cycles and unbundling traditional package policies. Large warehousing clients in the Netherlands and Belgium are procuring property and business interruption coverage through centralized procurement functions, stripping out broker intermediation. This disintermediation favors carriers with direct engineering risk consulting capabilities and captive fronting expertise.
Factory and Warehouse Insurance Market Segmentation
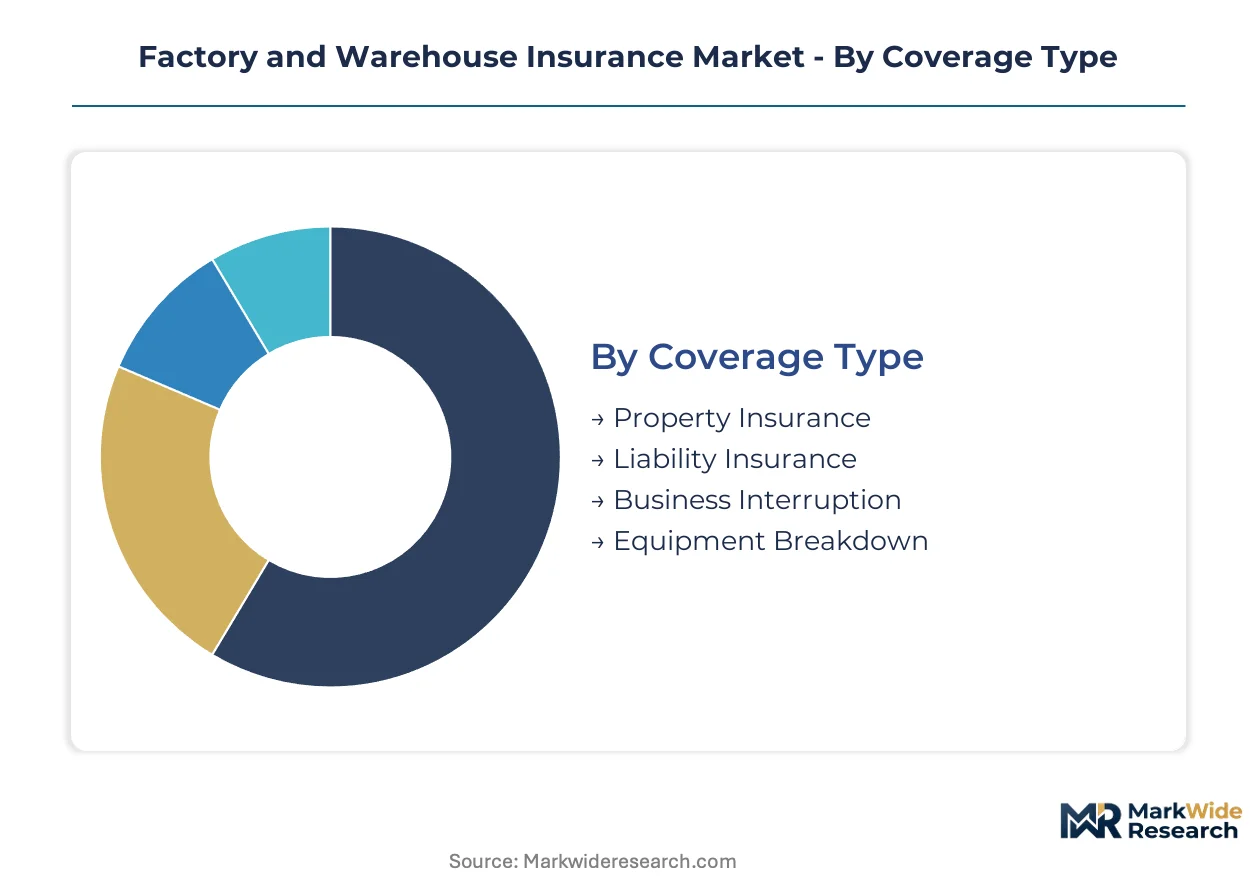
Factory and warehouse insurance segmentation reveals how risk concentration patterns shape carrier capacity allocation and pricing granularity. Coverage structures vary sharply across client scale and operational complexity, with specialized endorsements multiplying as industrial automation deepens asset interdependency.
Coverage Type:
Supply concentration in catastrophe-exposed industrial corridors is forcing carriers to tier coverage limits and deductible structures around parametric triggers.
- Property Insurance:Protects physical structures, inventory, and fixed assets against fire, flood, wind, and seismic perils. Replacement-cost valuation clauses dominate manufacturing placements in Germany's North Rhine-Westphalia corridor, where industrial density inflates maximum probable loss calculations for clustered chemical facilities.
- Business Interruption:Indemnifies revenue loss from operational suspension following insured physical damage. Food processing clients in the Netherlands are purchasing 24-month indemnity periods covering contingent exposures from single-point refrigeration failures in temperature-controlled supply chains.
- Liability Insurance:Covers third-party bodily injury and property damage arising from premises operations or completed operations.
- Equipment Breakdown:Protects against mechanical and electrical failure of production machinery, boilers, and pressure vessels.
Property Insurance absorbs the bulk of installed capacity; Business Interruption is expanding most quickly.
Industry Vertical:
Cost tier differentiation separates standardized package policies from engineered coverage for complex manufacturing exposures.
- Manufacturing:Encompasses chemical, automotive, electronics, and heavy industrial production facilities requiring specialized machinery valuation and process safety endorsements. German automotive manufacturers operating US assembly plants are establishing Vermont-domiciled captives to retain predictable property layers and reduce premium volatility.
- Logistics:Covers third-party warehousing, distribution centers, and fulfillment networks. E-commerce density in Belgium and the Netherlands is compressing placement cycles as large clients centralize procurement and strip broker intermediation from traditional package structures.
- Food Processing:Addresses temperature-controlled production, cold storage, and perishable inventory with heightened spoilage and contamination exposures.
- Retail:Protects distribution facilities and back-of-house storage for consumer goods chains with seasonal inventory fluctuations.
Manufacturing commands the deepest premium pools; Logistics is gaining share fastest as fulfillment infrastructure scales.
Policy Type:
Application complexity determines whether clients accept broad all-risk protection or negotiate named-peril structures with explicit exclusion carve-outs.
- All Risk:Provides blanket coverage against all perils except those explicitly excluded, requiring granular underwriting of moral hazard and maintenance protocols. German chemical manufacturers piloting Rhine floodplain coverage favor this structure for seamless integration with parametric water-level triggers.
- Named Peril:Specifies enumerated risks—typically fire, explosion, windstorm, and hail—with narrower scope but lower premium outlays. Aging US Midwest factories with pre-1980 electrical panels gravitate here as standard deductibles fail to price elevated ignition rates.
- Comprehensive:Bundles property, liability, and business interruption into unified coverage with coordinated limits.
- Specific:Targets isolated assets or single operational locations with tailored endorsement schedules.
All Risk structures dominate large-account placements; Named Peril policies are climbing fastest among mid-market clients managing cost pressures.
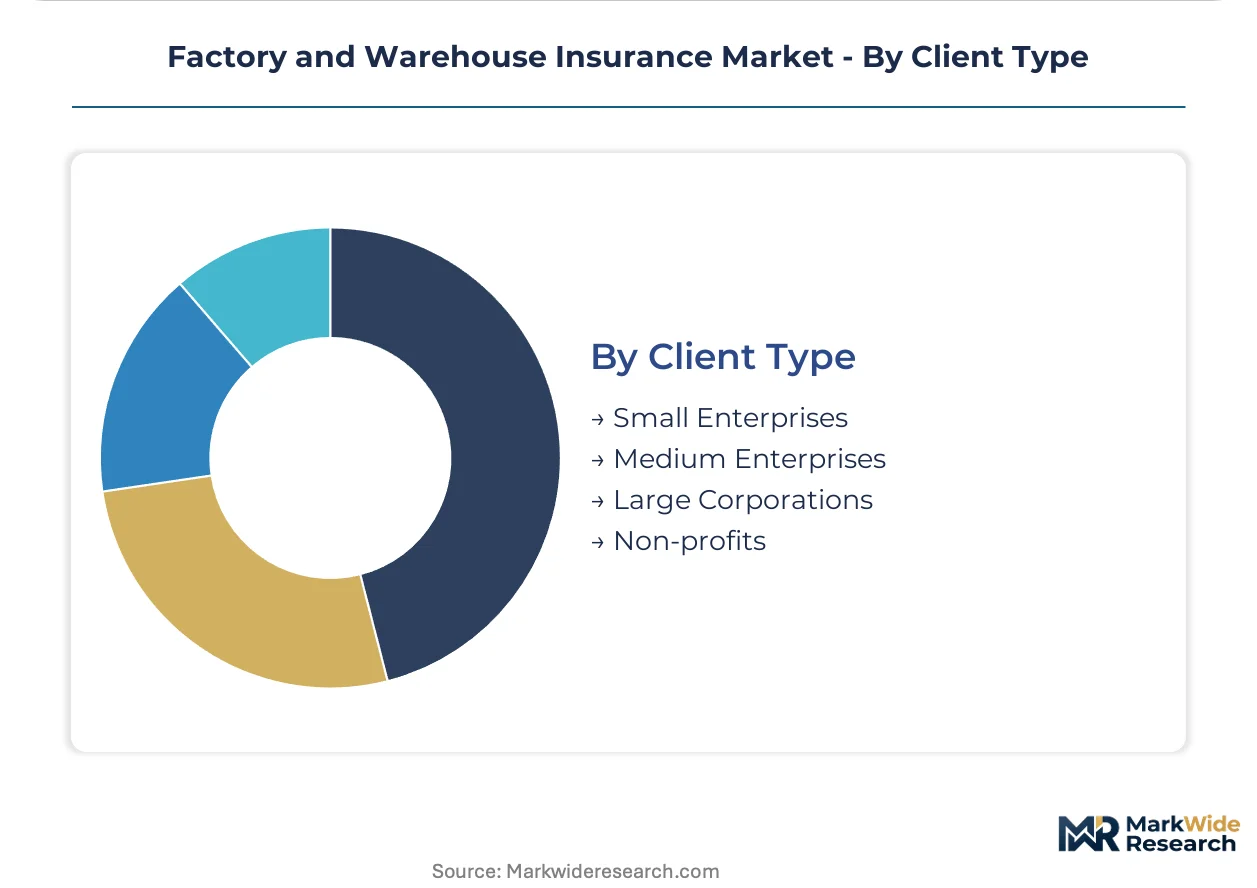
Client Type:
Customer scale dictates whether risk transfer occurs through commercial markets, captive structures, or self-insured retention programs.
- Large Corporations:Maintain dedicated risk management functions negotiating manuscript policies with capacity from multiple carriers. Japanese automotive manufacturers with US operations leverage Bermuda and Vermont captives to front retained layers and access reinsurance markets directly.
- Medium Enterprises:Purchase through broker channels with packaged coverage and standard ISO forms, supplemented by engineering inspections for premium credits.
- Small Enterprises:Rely on simplified business owner policies with basic property and liability limits, minimal customization, and rapid binding authority.
- Non-profits:Access specialized programs through trade associations and group purchasing arrangements with modified coverage triggers.
Large Corporations deploy the most sophisticated risk financing structures; Medium Enterprises represent the steepest expansion trajectory as industrial automation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the Netherlands and Belgium concentrate e-commerce fulfillment infrastructure, compressing insurance placement cycles as centralized procurement functions strip traditional broker intermediation from package policies.
Germany
Industrial clusters in Bavaria and North Rhine-Westphalia drive concentrated large-account placements for chemical and automotive manufacturing facilities. The EU Green Deal tightens building efficiency mandates that directly reshape property underwriting criteria for retrofitting industrial envelopes. Munich and Düsseldorf anchor engineering risk consulting demand as carriers pre-qualify clients before policy issuance.
United States
OSHA process safety management standards expand baseline coverage thresholds for Gulf Coast chemical facilities and Midwest heavy manufacturing plants. The EPA coordinates with state building codes to mandate minimum safety infrastructure before binding coverage on aging electrical infrastructure. Houston and Chicago concentrate maximum probable loss calculations where pre-1980 factory panels carry elevated fire ignition rates.
Japan
Automotive manufacturers with US assembly operations establish Vermont and Bermuda domiciled captives to retain predictable property layers and reduce premium volatility. METI guidelines influence risk retention strategies for multinational industrial portfolios. Toyota City and Nagoya anchor captive insurance expansion as Tokio Marine Holdings structures fronting arrangements.
Netherlands
Temperature-controlled last-mile facilities expand coverage limits to address spoilage exposure from single-point refrigeration failures in food processing and pharmaceutical distribution. EU Green Deal retrofit requirements trigger policy endorsements bundling property coverage with performance guarantees. Rotterdam and Eindhoven concentrate logistics procurement centralization that disintermediates traditional broker channels.
United Kingdom
Aging electrical infrastructure in the Midlands carries elevated fire ignition rates that standard deductibles fail to price adequately for pre-1980 industrial facilities. The National Fire Protection Association ammonium nitrate storage standards reshape underwriting questionnaires for fertilizer warehouses serving agricultural supply chains. Birmingham and Manchester anchor contingent business interruption demand as food processing clients extend indemnity periods.
Factory and Warehouse Insurance Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market segments. The landscape consolidates around carriers with captive fronting expertise and engineering risk consulting capabilities. Three archetypes dominate: global multi-line insurers with integrated loss control divisions, regional specialists leveraging geographic proximity to industrial clusters, and captive managers serving multinational manufacturing clients. Competitive moves center on embedding pre-qualification inspections into binding authority workflows and expanding parametric climate coverage with satellite-verified triggers.
Within the integrated consulting tier, Allianz SE and Chubb Limited exemplify carriers bundling engineering risk pre-qualification with policy issuance. Tokio Marine Holdings occupies a distinct position structuring captive insurance arrangements for Japanese automotive manufacturers with US operations. These three anchors demonstrate how specialized capabilities separate premium-tier positioning from commoditized placement channels.
| Leading Market Players |
|---|
| AXA SA |
| Zurich Insurance Group |
| Allianz SE |
| Chubb Limited |
| AIG |
| The Hartford |
| Tokio Marine Holdings |
| Liberty Mutual Insurance |
| Travelers Companies |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up insurance intermediaries in the US and UK are compressing broker commissions and forcing carriers to absorb front-end acquisition costs, tightening pricing discipline while accelerating consolidation among distribution channels serving mid-market industrial clients.
Pricing Analysis
Short lead-time placements command premium rate loads as carriers deploy accelerated underwriting workflows for time-sensitive factory startups and warehouse expansions. Three-tier pricing structure across premium, standard, and economy levels separates large-account manuscript policies with engineering pre-qualification from packaged ISO forms and stripped-down business owner policies. Pricing pressure stems from reinsurance capacity contraction in US Gulf Coast corridors, where catastrophe bond spreads have widened. Small enterprises exhibit highest price sensitivity, while large corporations with captive structures demonstrate inelastic demand for fronting and consulting services.
Supply Chain Analysis
Single-source vulnerability sits with Bermuda and Vermont captive domiciles, where regulatory capacity constraints limit fronting carrier options for Japanese automotive manufacturers retaining US property layers. Insurance capacity draws from Germany, the United States, and Bermuda as primary underwriting hubs. Raw material dependencies include catastrophe modeling software, satellite imagery verification systems, and specialized engineering inspection labor. Tariff exposure runs through cross-border reinsurance treaty arrangements. Distribution runs through centralized procurement functions at third-party logistics providers that strip traditional broker intermediation from package policies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where carriers must capture engineering risk consulting capabilities upstream of policy issuance to defend placement margins against disintermediation.
For Market Incumbents: Hedge parametric climate risk exposure by diversifying capacity allocation across multiple catastrophe modeling vendors and satellite verification providers. Lock in multi-year engineering inspection contracts with German industrial clusters before EU Green Deal retrofit mandates accelerate competitive bidding for pre-qualification services. For New Entrants and Emerging Players: Capture white-space in supply chain contingent business interruption for food processing clients extending indemnity periods to 24 months. Target Netherlands and Belgium logistics procurement centralization with direct carrier platforms that bundle parametric spoilage coverage for temperature-controlled facilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor captive management specialists with Vermont regulatory licenses and Japanese automotive relationships. Long-term viability hinges on climate risk modeling IP and fronting infrastructure rather than traditional underwriting balance sheets. Watch catastrophe bond spread movements as inflection indicators for reinsurance capacity availability.| Strategic Initiative | Industry Significance |
|---|---|
| Engineering Risk Pre-Qualification Integration | Allianz SE embeds loss control inspections into binding authority workflows, creating fee-based consulting revenue separate from premium income. |
| Parametric Climate Coverage Expansion | Chubb Limited deploys satellite-verified triggers for Rhine floodplain chemical manufacturers, enabling 72-hour settlement post-water-level breach. |
| Captive Fronting Infrastructure Buildout | Tokio Marine Holdings structures Vermont and Bermuda domiciled captives for Toyota and Honda US assembly operations. |
| Supply Chain Contingent BI Product Development | Food processing clients in the Netherlands purchase extended indemnity periods covering revenue loss from critical supplier refrigeration failures. |
| Digital Twin Technology Deployment | Real-time structural integrity monitoring compresses risk assessment intervals and enables dynamic premium adjustment for distributed warehouse networks. |
Methodological Framework
Independent corroboration across carrier underwriting executives, risk management consultants, and captive insurance managers underwrites the qualitative findings. Primary interviews engaged chief underwriting officers at multi-line insurers, directors of engineering risk consulting divisions, and risk managers at German automotive and chemical manufacturers. Secondary validation drew from National Association of Insurance Commissioners filings, Bermuda Monetary Authority regulatory disclosures, and EU Green Deal implementation progress reports. Bottom-up premium volume estimates triangulated against top-down market sizing from reinsurance treaty disclosures.
Comparable-period anchoring calibrated the projection horizon against historical loss experience from 2017-2023 catastrophe events and subsequent rate hardening cycles. The analytical framework modeled segmentation across coverage type, industry vertical, policy structure, and client scale. CAGRs derived from carrier premium growth disclosures and reinsurance pricing trend indices. Forecast inputs incorporated OSHA inspection frequency data and EU building efficiency mandate implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to climate loss experience deterioration and reinsurance capacity withdrawal. Forecasts reflect documented assumptions about parametric trigger adoption rates and captive formation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Cloud Computing in Insurance Market
Insurance
China Online Insurance Market
Insurance
India Life and Non-Life Insurance Market
Insurance
China Parametric Insurance Market
Insurance
Commercial Insurance Market
Insurance
Asia-Pacific Family Floater Health Insurance Market
Insurance
Asia-Pacific Liability Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
United States Commercial Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
India Parametric Insurance Market
Insurance
Cyber Insurance Market
Insurance
Indonesia Private Health Insurance Market
Insurance
Canada Parametric Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Dental Insurance Market