
 US Travel Insurance Market | 2026-2036
US Travel Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
US Travel Insurance Market Outlook
The Affordable Care Act's narrow extraterritorial medical coverage is consolidating demand around comprehensive travel medical policies. Allianz leverages its airline partnership network to dominate embedded distribution at booking checkpoints. Berkshire Hathaway Travel Protection sustains brand recognition through direct-to-consumer digital channels that bypass traditional broker intermediaries. Seven Corners specializes in niche adventure and high-risk activity coverage that standard carriers exclude from base policies.
Travel insurance constitutes a short-term indemnity contract that transfers financial risk associated with trip-related losses from the policyholder to the underwriter, typically specifying per-occurrence limits, deductible thresholds, and named peril schedules. Its primary commercial purpose is to restore prepaid travel expenditures and emergency medical costs that standard health or property policies exclude during temporary absences from the policyholder's home domicile. Trip cancellation coverage anchors the largest premium pool due to its attachment to high-value cruise and tour deposits, while medical emergency coverage generates the fastest premium expansion as aging demographics confront Medicare's foreign care limitations. Distribution through online travel agencies captures disproportionate volume growth because booking platforms embed insurance at the point of sale before consumer comparison shopping occurs.
The National Association of Insurance Commissioners coordinates state-level reserving standards and policy form approvals that shape product availability across jurisdictions. The US Department of Transportation enforces refund regulations for flight cancellations that indirectly define the boundary between carrier liability and insurable trip interruption risk. State insurance commissioners in New York and California maintain the most stringent rate filing requirements that delay product launches and elevate compliance costs. Stakeholders must monitor how the NAIC's evolving model laws on travel insurance disclosures reshape competitive transparency obligations.
Market Dynamics
Embedded distribution through airline and cruise booking platforms is consolidating purchase pathways before consumers reach comparison shopping stages, compressing traditional broker intermediation.
Growth Catalysts
- Medicare's foreign care exclusions:Retirees facing coverage gaps abroad are accelerating purchases of supplemental travel medical policies. This demographic shift expands the addressable base for comprehensive emergency coverage.
- Post-pandemic corporate mobility normalization:Business travel volume rebound is restoring employer-sponsored group policies. Duty-of-care obligations are mandating broader protection for traveling employees.
- Florida and California gateway concentration:Cruise departure clusters and international airport hubs in these states concentrate policy origination. Geographic density reduces customer acquisition costs for carriers with localized distribution.
Market Restraints
- State-by-state rate filing heterogeneity:New York and California maintain the most stringent approval timelines, delaying product launches and elevating compliance overhead. Multi-state carriers face fragmented regulatory navigation.
- Medical cost inflation in destination markets:Emergency treatment pricing volatility in popular travel corridors creates reserving uncertainty. Underwriters must price for claims severity dispersion that standard health inflation indices poorly capture.
- Airline refund obligation boundaries:US Department of Transportation cancellation regulations overlap with insurable trip interruption coverage, creating consumer confusion and claim dispute friction.
Strategic Opportunities
- Adventure and high-risk activity white space:Standard carriers exclude base coverage for extreme sports, creating niche specialization potential. Custom underwriting for climbing, diving, and backcountry segments commands premium pricing.
- Online travel agency channel expansion:Booking platform partnerships enable point-of-sale embedding before consumer comparison. This distribution innovation captures impulse purchases at transaction momentum peaks.
- Affordable Care Act gap exploitation:Limited extraterritorial medical provisions create regulatory tailwind for supplemental products. Educational marketing around coverage boundaries drives incremental policy attachment.
Industry Challenges
- Actuarial talent scarcity in short-duration specialty lines:Pricing travel risks requires modeling expertise distinct from standard property-casualty. Competition for qualified underwriters elevates compensation costs.
- Legacy policy administration system integration:Carriers acquiring digital distribution capabilities face middleware complexity connecting modern front-ends to established claims platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Travel Insurance Market |
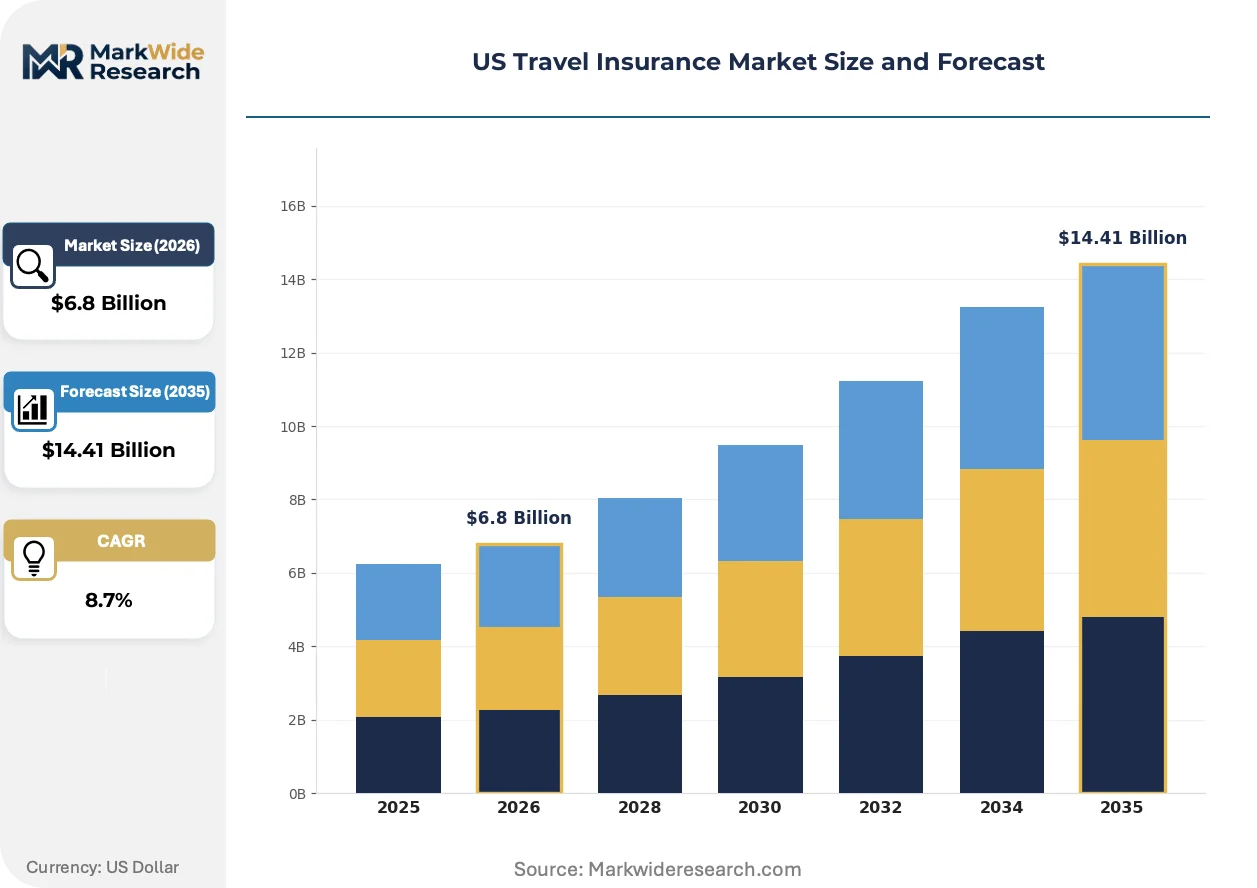
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Trip Cancellation, Medical Emergency, Baggage Loss, Travel Interruption Customer Type: Family Travelers, Business Travelers, Solo Travelers, Group Travelers Distribution Channel: Online Travel Agencies, Insurance Brokers, Direct Sales, Mobile Apps Duration of Coverage: Single Trip, Annual Multi-Trip, Long-Term, Short-Term |
| Companies Covered | Allianz, American International Group, AXA Assistance USA, USI Insurance Services, Seven Corners, Travel Insured International, Zurich Insurance Group, Battleface, Berkshire Hathaway Travel Protection, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Travel Insurance Market Strategic Shifts
Real-time data integration is compressing underwriting cycles and enabling dynamic pricing adjustments that static annual policies cannot match. This technological infusion is reshaping how carriers assess and price transient risk exposures.
Parametric claim triggers is unifying weather and disruption data streams with automatic payout mechanisms. Cruise lines and tour operators are adopting these instruments to secure balance sheet protection against itinerary failures. This convergence is enabling capital markets to participate in travel risk transfer through catastrophe bond structures.
The National Association of Insurance Commissioners is coordinating enhanced disclosure model laws that mandate clearer coverage limitation presentations. State insurance commissioners are implementing these standards through revised policy form approval requirements. Smaller carriers with constrained compliance resources are experiencing product launch delays as they adapt to transparency obligations.
Consumer research behavior is fragmenting across mobile booking applications and aggregator platforms before reaching carrier direct channels. Millennials and Gen Z travelers are purchasing coverage through airline app interfaces rather than standalone insurance websites. This channel migration is most pronounced in California and Florida departure markets where digital-native demographics concentrate.
US Travel Insurance Market Segmentation
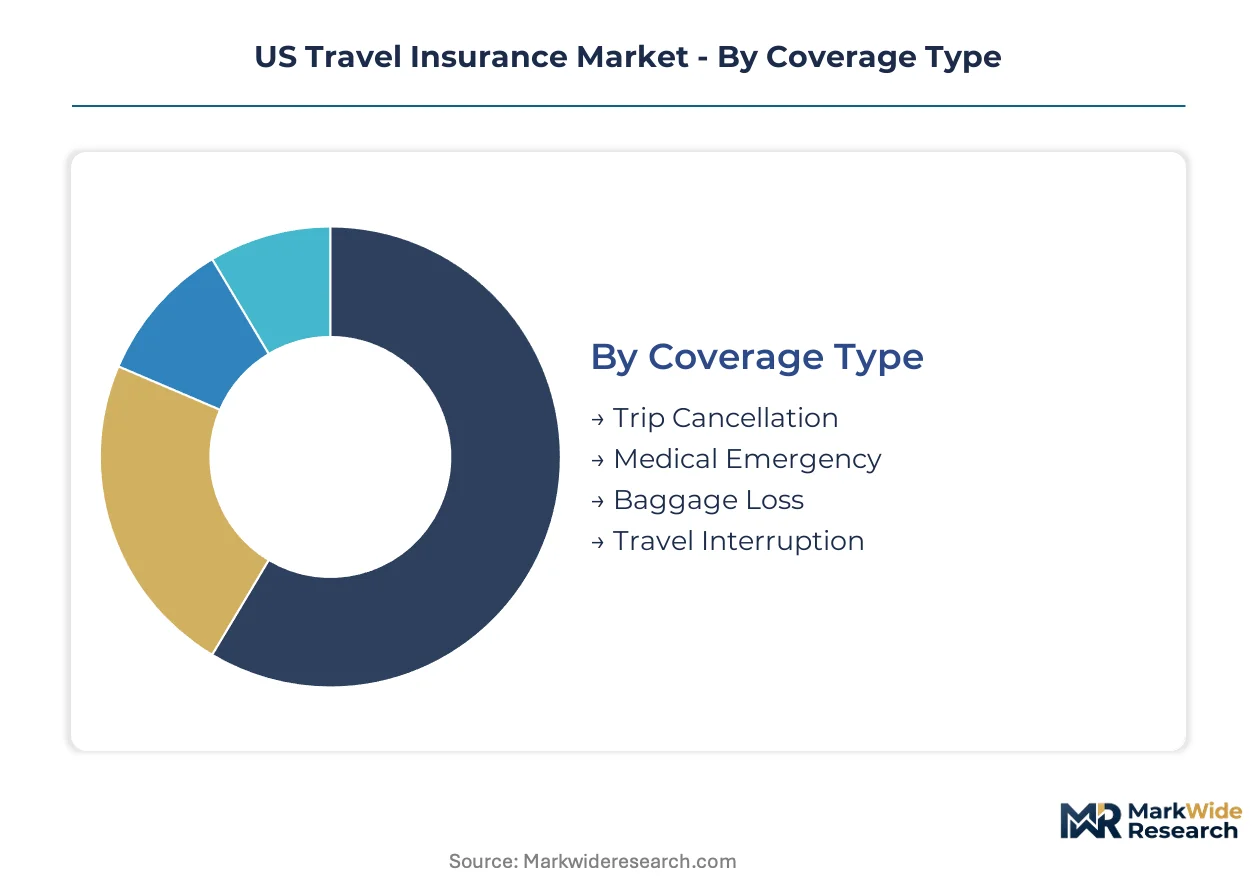
Travel insurance products fragment across coverage scope, buyer profiles, and purchase pathways that determine underwriting complexity and distribution economics. Each segmentation dimension reveals distinct pricing power, claims frequency patterns, and customer lifetime value profiles that carriers must align against operational capabilities.
Coverage Type:
Trip cancellation products operate as standalone purchase decisions at booking checkpoints, while medical emergency coverage often embeds within comprehensive packages or employer-sponsored group arrangements.
- Trip Cancellation:Indemnifies prepaid non-refundable deposits against named peril triggers including illness, weather, or supplier default. Florida cruise departure corridors concentrate the highest attachment rates as deposit values escalate. The segment anchors premium volume due to integration with high-value tour and cruise bookings.
- Medical Emergency:Covers emergency treatment, evacuation, and repatriation costs excluded by domestic health policies. California gateway airports and retiree-heavy departure markets drive disproportionate demand as Medicare's foreign care limitations create coverage gaps. This segment is expanding most quickly as aging demographics confront overseas medical cost exposure.
- Baggage Loss:Reimburses personal property damage or delay during transit. Airlines' contractual liability limitations create demand concentration among international route passengers.
- Travel Interruption:Covers incremental costs when trips terminate early due to covered events. Business traveler segments in corporate mobility programs generate the bulk of commercial placements.
Volume placements concentrate in Trip Cancellation; the faster expansion belongs to Medical Emergency.
Customer Type:
Family and business traveler segments command premium pricing through comprehensive coverage requirements, while solo and group buyers present divergent risk pooling and administrative cost structures.
- Family Travelers:Multi-generational units purchasing bundled coverage for dependent members. Theme park destination clusters in Orlando and Anaheim drive seasonal concentration.
- Business Travelers:Corporate account placements with duty-of-care compliance requirements. Post-pandemic employer liability concerns are restoring group policy volumes.
- Solo Travelers:Individual purchasers seeking flexible single-trip products. Digital-native demographics in urban coastal markets favor mobile-first distribution.
- Group Travelers:Affinity organizations and tour operators arranging collective coverage. Educational institutions and religious organizations constitute the core origination base.
Premium concentration sits with Business Travelers; steepest expansion trajectory is occurring among Solo Travelers.
Distribution Channel:
Online travel agencies capture transaction-momentum purchases before comparison shopping, while broker and direct channels serve deliberative buyers with complex coverage needs.
- Online Travel Agencies:Embedded checkout integration with airline and cruise booking platforms. California and Florida departure markets exhibit the highest penetration rates.
- Insurance Brokers:Intermediary counsel for commercial accounts and high-net-worth individuals. Complex multi-trip annual policies require advisory placement.
- Direct Sales:Carrier-controlled websites and call centers bypassing intermediaries. Berkshire Hathaway Travel Protection maintains recognition through this channel.
- Mobile Apps:Airline and travel service applications with one-tap coverage attachment. Millennial and Gen Z adoption is reshaping purchase behavior.
Transaction volume concentrates in Online Travel Agencies; Mobile Apps are gaining share fastest.
Duration of Coverage:
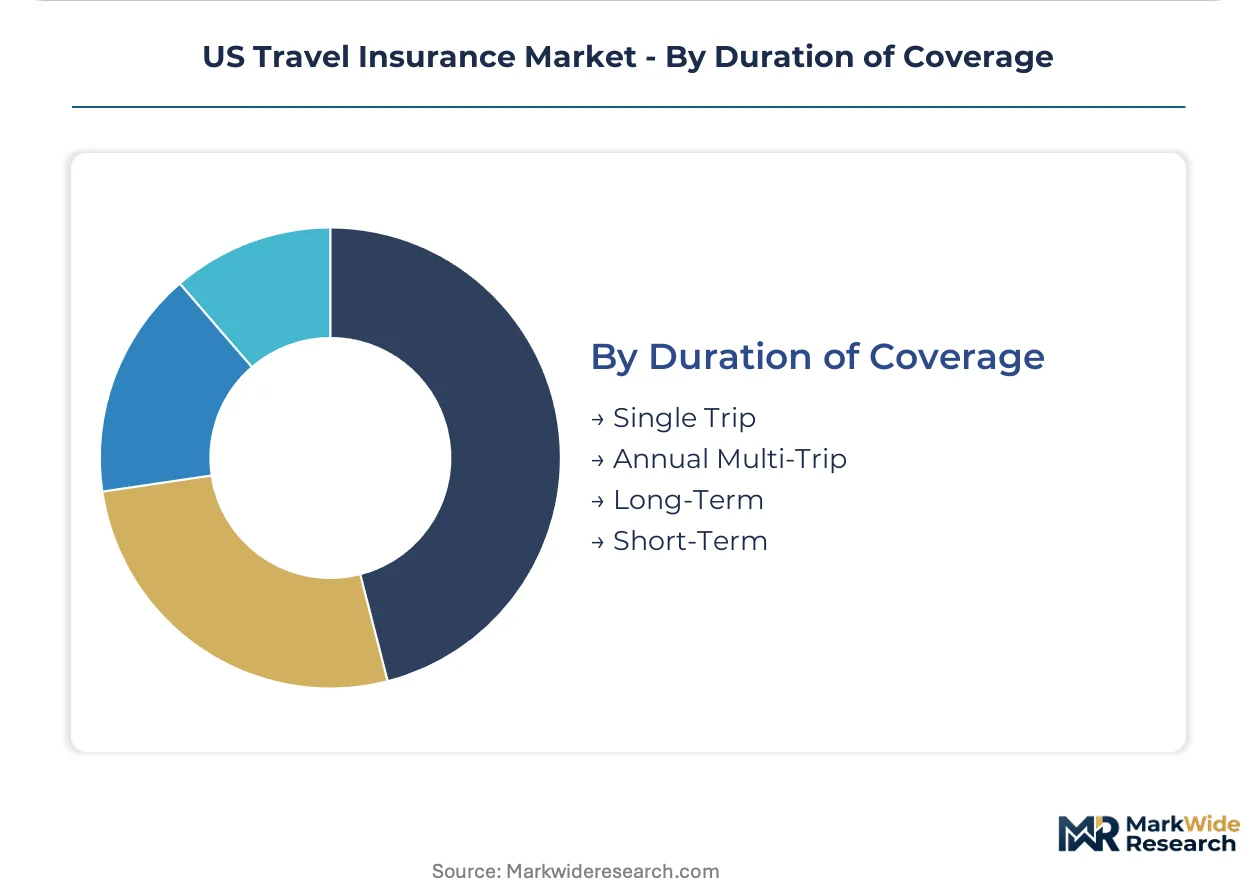
Single-trip products dominate leisure purchase occasions, while annual multi-trip arrangements align with frequent business travel patterns and retiree snowbird mobility.
- Single Trip:Discrete coverage aligned with specific departure and return dates. Cruise and tour deposit protection drives the majority of policy origination.
- Annual Multi-Trip:Year-round protection for unlimited journeys within duration limits. Corporate travel managers and frequent leisure travelers constitute the addressable base.
- Long-Term:Extended coverage exceeding standard trip limits for expatriate assignments or educational programs. International student mobility supports niche demand.
- Short-Term:Brief-duration protection for domestic weekend or regional travel. Price-sensitive segments favor stripped-down medical-only configurations.
Policy count concentrates in Single Trip; Annual Multi-Trip is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Miami and Fort Lauderdale anchor the nation's densest travel insurance origination corridor, with cruise departure volumes and international gateway traffic concentrating policy sales in South Florida metropolitan clusters.
Florida
Cruise line embarkation ports in Miami, Fort Lauderdale, and Port Canaveral generate the highest single-trip cancellation attachment rates nationally. The Florida Office of Insurance Regulation maintains streamlined rate filing procedures that accelerate product launches compared to northeastern states. Orlando's theme park destination cluster drives seasonal family policy spikes, while Tampa's expanding international airport footprint captures growing Latin America route demand.
California
Los Angeles International and San Francisco International serve as primary Pacific gateway hubs for Asia-Pacific route insurance origination. The California Department of Insurance enforces the nation's most stringent policy form disclosure requirements, elevating compliance costs for multi-state carriers. San Diego's cruise terminal expansion and Silicon Valley's business traveler density create dual demand streams for leisure and corporate coverage products.
New York
John F. Kennedy International and Newark Liberty International concentrate northeast corridor international departure volume. The New York State Department of Financial Services imposes extended rate filing review timelines that delay product introductions by quarters versus Florida timelines. Manhattan's corporate headquarters density sustains employer-sponsored group policy placements for financial services and consulting sector travel.
Texas
Dallas-Fort Worth International and George Bush Intercontinental rank among the nation's busiest international connection hubs, generating substantial transit passenger coverage sales. The Texas Department of Insurance operates a competitive filing environment with faster approval cycles than coastal regulatory regimes. Austin's technology sector expansion is restoring business travel volumes and associated duty-of-care policy demand post-pandemic.
Illinois
Chicago O'Hare International serves as the primary midwest gateway for European and Asian route origination. The Illinois Department of Insurance coordinates with the National Association of Insurance Commissioners on model law implementations affecting disclosure standards. The city's corporate headquarters concentration in insurance, manufacturing, and professional services sustains mid-market group policy placements.
US Travel Insurance Market Competitive Environment
The competitive structure tilts toward embedded distribution specialists with airline and cruise platform partnerships. Three to five national carriers dominate premium volume through direct-to-consumer channels and online travel agency integrations. Strategic archetypes include legacy multi-line insurers with travel divisions, travel-specialist underwriters with niche risk expertise, and digital-native distributors with booking platform integrations. Capacity expansion through technology licensing agreements and strategic partnerships with online travel agencies represent the dominant competitive moves.
Among the embedded distribution specialists, Allianz and Berkshire Hathaway Travel Protection occupy positions representing divergent channel strategies. Allianz exemplifies the airline partnership archetype with checkpoint embedding at booking stages. Berkshire Hathaway Travel Protection represents the direct-to-consumer digital channel approach that bypasses traditional intermediaries. Seven Corners anchors the niche specialization tier with high-risk activity coverage that standard carriers exclude.
| Leading Market Players |
|---|
| Allianz |
| American International Group |
| AXA Assistance USA |
| USI Insurance Services |
| Seven Corners |
| Travel Insured International |
| Zurich Insurance Group |
| Battleface |
| Berkshire Hathaway Travel Protection |
| Others |
Value Chain & Pricing Dynamics
Medical cost inflation indices in destination corridors cascade through underwriting reserves into premium tiers, compressing margins for standard coverage while amplifying pricing power for specialty medical emergency products. Cost volatility in emergency treatment markets forces carriers to stratify offerings across comprehensive, limited-benefit, and catastrophic-only configurations.
Pricing Analysis
Value-based pricing anchors on trip deposit protection outcomes, with trip cancellation premiums scaling to non-refundable expenditure exposure. Price differentiation rests on medical benefit ceilings and evacuation service tiers, while pricing pressure intensifies in standard leisure segments due to embedded distribution commission compression. Corporate group buyers exhibit lowest price sensitivity; solo leisure purchasers through mobile channels show highest elasticity.
Supply Chain Analysis
NAIC model law compliance certification gates product launches, with Florida and Texas regulatory approvals moving fastest while California and New York filings lag. Underwriting capacity concentrates in domestic carriers with admitted status, reinsurance treaties, and claims infrastructure. Raw material dependencies span emergency medical networks, air ambulance operators, and assistance service platforms. Single-source vulnerability sits with specialized evacuation providers. Distribution runs through online travel agency integrations, airline checkpoint embedding, and direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
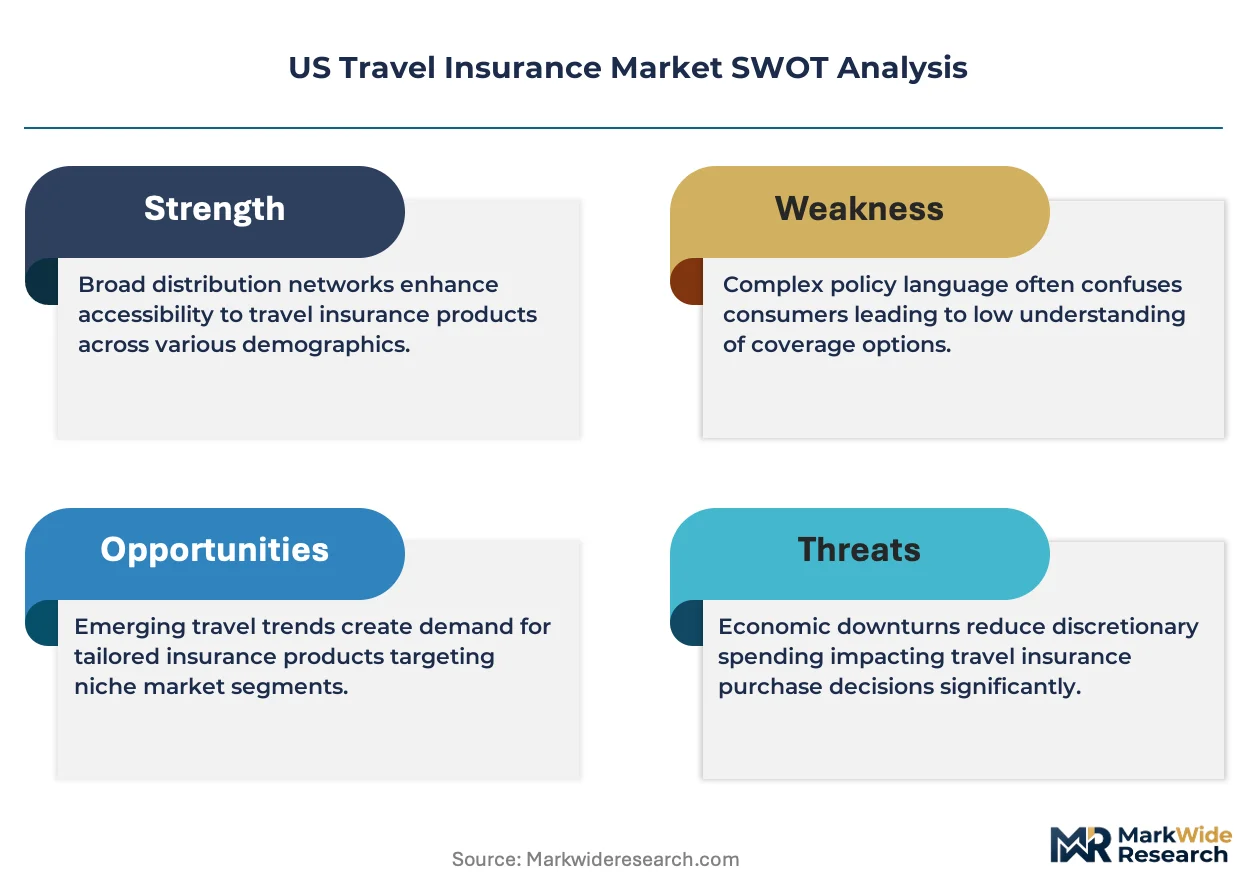
This market operates as a cost-of-compliance story where NAIC disclosure model law adherence erects barrier-to-entry moats favoring carriers with established state filing capabilities and regulatory affairs infrastructure.
For Market Incumbents: Deepen vertical integration into claims assistance networks to capture emergency medical service margins currently leaking to third-party providers. Fortify rate filing capabilities in California and New York to accelerate product launch velocity against regulatory lag. Channel control through exclusive airline partnerships represents the critical defensive lever against digital-native distributors. For New Entrants and Emerging Players: Capture adventure and high-risk activity white space where standard carriers exclude coverage and specialty underwriting commands premium positioning. Mobile-first distribution through airline application interfaces offers the most penetrable pathway, particularly among Millennial and Gen Z demographics in Florida and California departure markets. Niche focus on climbing, diving, and backcountry segments enables differentiated go-to-market positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor digital-native distributors with established online travel agency integrations in Texas and Florida regulatory environments. Long-term viability over the extended horizon hinges on embedded distribution lock-in and regulatory filing scale. Monitor NAIC model law adoption velocity across state insurance departments as the primary inflection signal for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Online Travel Agency Partnership Expansion | Point-of-sale embedding at booking checkpoints captures transaction-momentum purchases before comparison shopping. |
| Regulatory Filing Capability Investment | Accelerated product launches in Florida and Texas create first-mover advantage against compliance-constrained competitors. |
| Adventure Coverage Product Development | Specialized underwriting for excluded high-risk activities commands premium pricing in underserved niche segments. |
| Mobile Application Distribution Integration | One-tap coverage attachment through airline apps reshapes purchase behavior among digital-native demographics. |
| Assistance Network Vertical Integration | In-house emergency medical and evacuation services capture margins currently flowing to third-party providers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with insurance product managers, state regulatory affairs directors, airline partnership executives, and online travel agency integration specialists. NAIC model law documentation, state insurance department rate filing databases, and carrier statutory financial statements provided foundational validation. Bottom-up policy origination modeling and top-down premium pool estimation were cross-referenced for triangulation.
Data-stream reconciliation across distribution channel volumes, demographic penetration rates, and regulatory approval timelines informed the analytical framework. Segmentation dimensions modeled encompass coverage type, customer archetype, distribution pathway, and policy duration across the projection horizon. CAGRs were derived from historical premium growth patterns and forward-looking demographic and travel volume assumptions. Medicare foreign care exclusion penetration and corporate mobility normalization served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to medical cost inflation volatility, state regulatory harmonization progress, and airline refund obligation boundary shifts. Forecasts reflect documented assumptions regarding travel volume recovery trajectories and demographic aging patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Umbrella Insurance Market
Insurance
Medical Professional Liability Insurance Market
Insurance
US Homeowner's Insurance Market
Insurance
Aviation Insurance Market
Insurance
Japan Parametric Insurance Market
Insurance
Germany Health and Medical Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
India Life and Non-Life Insurance Market
Insurance
Denmark Property and Casualty Insurance Market
Insurance
Digital Transformation in Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
Africa Insurance Market
Insurance
Aerial Imaging in Insurance Service Market
Insurance
Asia-Pacific Mobile Phone Insurance Market