
 Vietnam Private Health Insurance Market | 2026-2036
Vietnam Private Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Private Health Insurance Market Analytics
Market Context
MOH Circular 54/2017/TT-BYT agent licensing requirements is redrawing competitive boundaries for new entrants. Bao Viet Holdings leverages its state-affiliated heritage and captive agency network to dominate rural provinces. AIA Group Limited anchors its position through bancassurance partnerships with Vietcombank and Techcombank. Prudential Vietnam differentiates via digital-first onboarding and telemedicine bundled policies.
Technical Definition and Segment Structure
Vietnam Private Health Insurance comprises voluntary, non-state medical expense indemnity contracts underwritten by licensed domestic and foreign-invested insurers, typically featuring annual renewable terms, deductible tiers, and provider network restrictions tied to accredited private hospitals such as Vinmec and Hoan My. Its primary commercial purpose is to fill reimbursement gaps left by Vietnam's compulsory social health insurance scheme, which caps payouts and excludes advanced procedures at private facilities. Individual Plans command the deepest margin pools among product types due to persistency bonuses and cross-sell potential into critical illness riders. Group Plans sustain volume leadership as foreign-invested enterprises expand mandatory supplemental coverage for expatriate and local management tiers. Inpatient Care coverage anchors policy design, while Outpatient Care represents the fastest-growing attachment as private clinic chains proliferate in Da Nang and Can Tho.
Regulatory Framework and Outlook
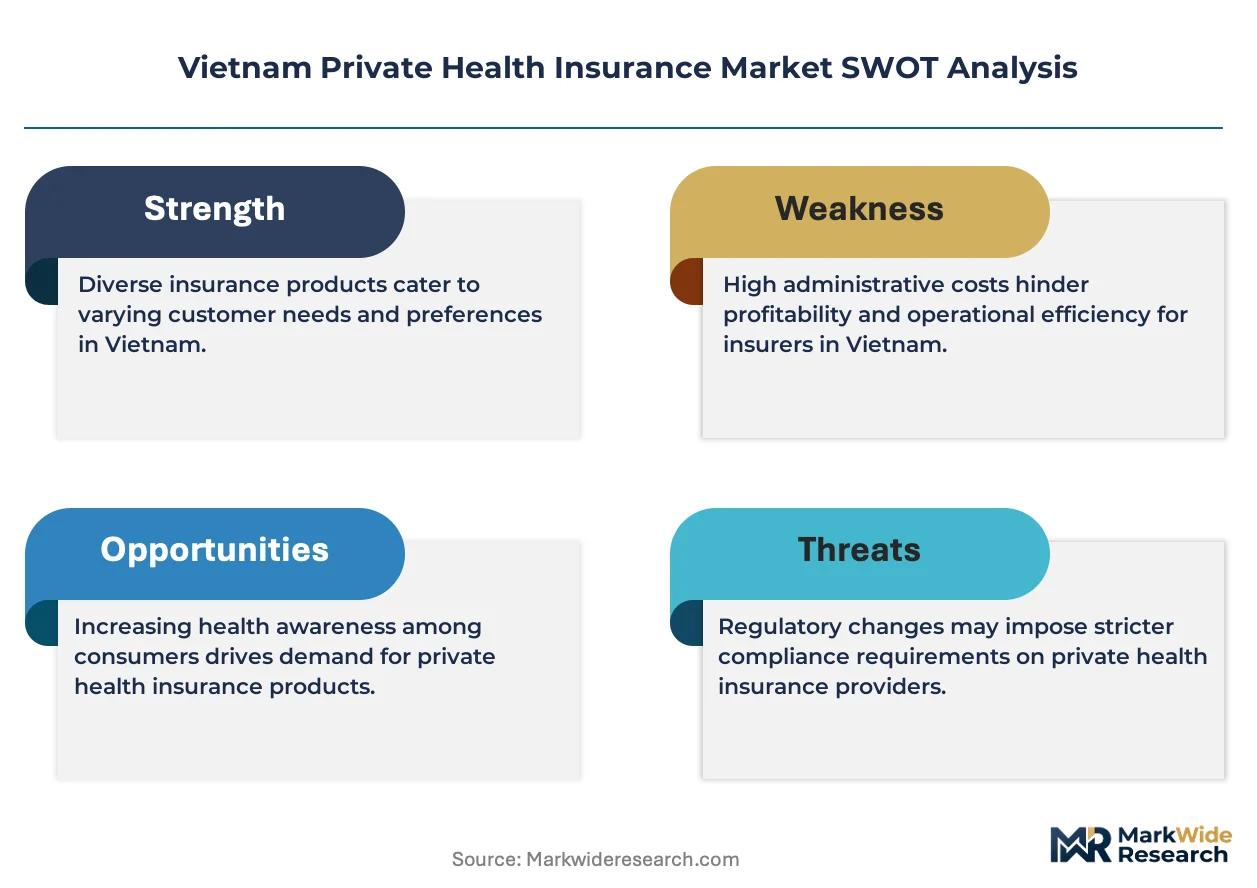
The Ministry of Finance's Insurance Supervisory Authority enforces solvency margin requirements and product filing approvals, while the Ministry of Health coordinates provider accreditation standards that directly constrain network breadth. Vietnam's Law on Insurance Business amendments and draft decrees on foreign ownership limits shape capital commitments from Allianz SE and Chubb Group Holdings Inc. Stakeholders must monitor whether MOF implements risk-based capital frameworks aligned with IAIS standards, as this would elevate reserving costs for smaller domestic underwriters and accelerate consolidation toward insurers with diversified product portfolios and reinsurance access.
Market Dynamics
Circular 54/2017/TT-BYT is compressing distribution capacity by mandating agent licensing exams and capital thresholds, forcing unlicensed intermediaries out of Ho Chi Minh City and Hanoi while concentrating volume among bancassurance partnerships and captive agency networks.
Growth Catalysts
- Employer Mandate Expansion:Foreign-invested manufacturing and technology firms in Binh Duong and Bac Ninh provinces are extending supplemental health benefits to local management tiers, creating group policy volume.
- MOH Hospital Accreditation:Private hospital chains achieving Ministry of Health tier-1 status expand insurable network breadth, reducing out-of-pocket exposure for policyholders seeking Vinmec or Hoan My facilities.
- Telemedicine Integration:Video consultation platforms bundled with outpatient riders are reducing claim leakage from unnecessary emergency department visits.
Market Restraints
- Social Health Insurance Saturation:Vietnam's compulsory VSS scheme covers 92% of citizens with capped reimbursement, limiting perceived value of supplemental private products among price-sensitive rural populations.
- Reinsurance Capacity Concentration:Catastrophic risk coverage depends on Singapore-based reinsurers, exposing domestic underwriters to hardening treaty terms and collateral requirements.
- Provider Reimbursement Friction:Cashless claim settlement delays at non-accredited clinics persist due to incomplete electronic health record interoperability between insurers and provincial hospitals.
Strategic Opportunities
- Da Nang-Central Coast Corridor:Underpenetrated manufacturing zones in Quang Nam and Thua Thien-Hue provinces lack dedicated private hospital networks, creating first-mover advantage for insurers building exclusive provider contracts.
- Critical Illness Rider Bundling:Cancer and cardiovascular treatment cost inflation at private oncology centers is driving attach rates for lump-sum payout supplements to base inpatient policies.
- Digital-First Distribution:Mobile app-based policy issuance and AI-assisted underwriting are reducing acquisition costs for individual plans among millennial professionals in Can Tho and Hai Phong.
Industry Challenges
- Licensed Actuarial Talent Scarcity:Vietnam's actuarial association counts fewer than 200 fully qualified members, constraining product development velocity for complex rider structures.
- Legacy Core System Migration:Domestic insurers operating on 1990s-era policy administration platforms face integration friction with telemedicine APIs and real-time claims adjudication engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Private Health Insurance Market |
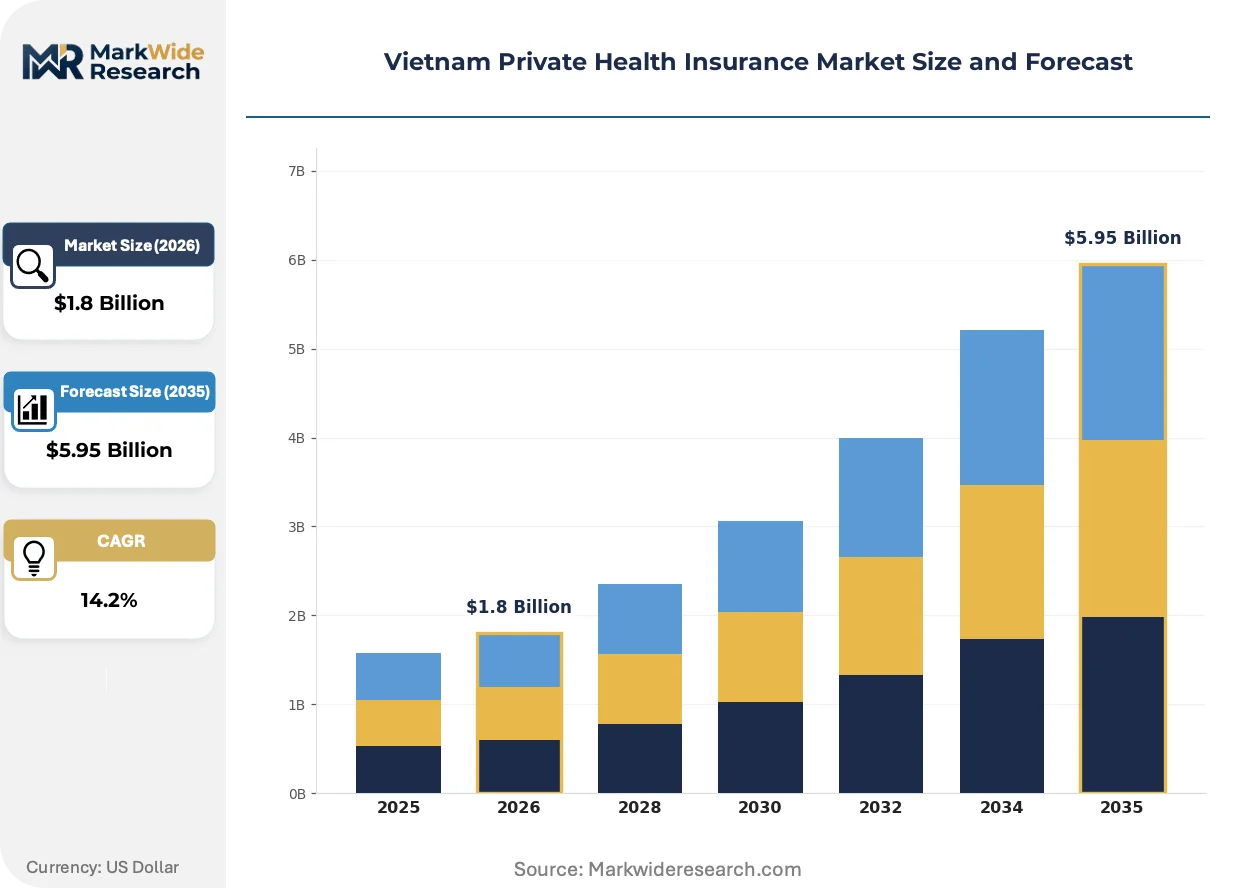
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Individual Plans, Family Plans, Group Plans, Critical Illness Plans End User: Employees, Self-Employed, Retirees, Students Coverage Type: Inpatient Care, Outpatient Care, Dental Coverage, Maternity Coverage Premium Range: Low, Medium, High, Customized |
| Companies Covered | Bao Viet Holdings, AXA Global Healthcare, AIA Group Limited, Allianz SE, Generali Vietnam, Manulife (Vietnam) Company Limited, Chubb Group Holdings Inc., Cigna Corporation, Prudential Vietnam, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Private Health Insurance Market Evolving Landscape
Technology-enabled care delivery models and regulatory digitization are restructuring how policies are distributed, underwritten, and serviced across Vietnam's urban centers.
Embedded telehealth platforms are supplanting traditional nurse hotlines as the primary first-touch triage mechanism. Technology sector employers in District 7 of Ho Chi Minh City are mandating these modules for expatriate staff. This shift is compressing per-member-per-month costs while elevating outpatient rider attach rates.
MOF Insurance Supervisory Authority's sandbox framework for digital-only insurers is lowering capital entry barriers. Foreign-invested entrants are testing direct-to-consumer models without branch networks. Individual plan segments in Hanoi are responding with price-transparent, no-commission product designs.
Subscription-style wellness programs are displacing annual renewable contracts among urban professionals. Fitness tracker data and preventive screening compliance now determine premium discounts. Da Nang's white-collar workforce exhibits the highest enrollment velocity for these behavior-linked structures.
Vietnam Private Health Insurance Market Segmentation
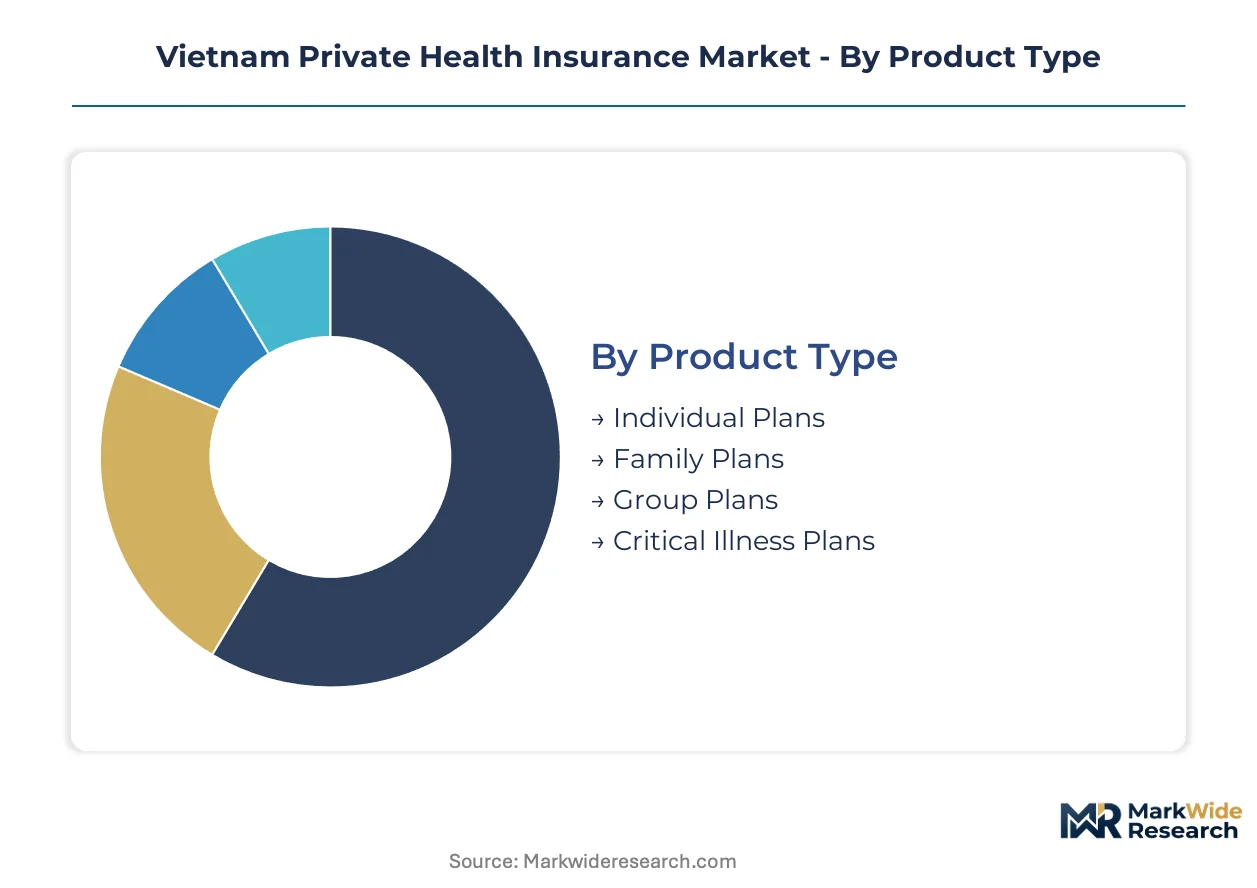
Vietnam's private health insurance market fragments across product design, beneficiary profiles, and benefit structures that determine pricing elasticity and distribution channel selection. Understanding these segment boundaries clarifies where compulsory social health insurance creates coverage gaps versus direct substitution pressure.
Product Type:
Group Plans face the strongest substitution threat from Vietnam's expanding compulsory social health insurance mandate, while Individual Plans operate in a protected niche above reimbursement caps.
- Individual Plans:Single-life annual renewable contracts featuring tiered deductibles and network restrictions tied to accredited private hospitals. Demand concentrates among expatriate professionals in Ho Chi Minh City's District 2 and District 7, driven by employer cash allowances that replace group coverage for senior hires.
- Group Plans:Master policies covering employee cohorts with standardized benefits and experience-rated renewals. Volume clusters at foreign-invested manufacturing facilities in Binh Duong and Bac Ninh provinces, where supplemental coverage has become mandatory for local management tiers.
- Family Plans:Multi-life structures bundling primary insured, spouse, and dependent coverage with shared deductibles.
- Critical Illness Plans:Lump-sum payout riders attaching to base medical expense policies, triggered by cancer or cardiovascular diagnosis.
Group Plans retain volume leadership; Critical Illness Plans hold the steepest expansion curve.
End User:
Cost tier stratification separates price-sensitive student segments from premium-tolerant corporate tiers, with retirees occupying an underserved middle band.
- Employees:Salaried workers accessing coverage through employer-sponsored schemes or voluntary individual purchase. Demand concentrates in technology and manufacturing sectors where foreign ownership drives benefits standardization, constrained by social health insurance's 92% population coverage that suppresses perceived supplemental value.
- Self-Employed:Independent professionals and business owners purchasing coverage without group purchasing leverage.
- Retirees:Post-employment individuals seeking coverage beyond social health insurance caps, typically facing age-rated premiums or exclusion periods.
- Students:Young adults in tertiary education programs, often covered by institutional arrangements or family plans.
Employees dominate policy-in-force counts; Self-Employed categories are gaining share fastest among digital distribution channels.
Coverage Type:
Application-driven design separates acute intervention from preventive and elective services, with outpatient benefits expanding as private clinic networks proliferate.
- Inpatient Care:Hospitalization benefits covering room charges, surgical procedures, and physician fees during confinement. Policy design anchors on this category across all product types, with network restrictions tied to Vinmec and Hoan My accreditation status.
- Outpatient Care:Clinic visits, diagnostic testing, and prescription coverage without overnight stay. Attachment rates are climbing fastest in Da Nang and Can Tho where private clinic chains reduce emergency department leakage.
- Dental Coverage:Preventive and restorative oral health benefits, typically sub-limited within comprehensive policies.
- Maternity Coverage:Prenatal, delivery, and postnatal benefits subject to waiting periods and benefit caps.
Inpatient Care remains the mandatory core; Outpatient Care demonstrates the sharpest attach rate acceleration.
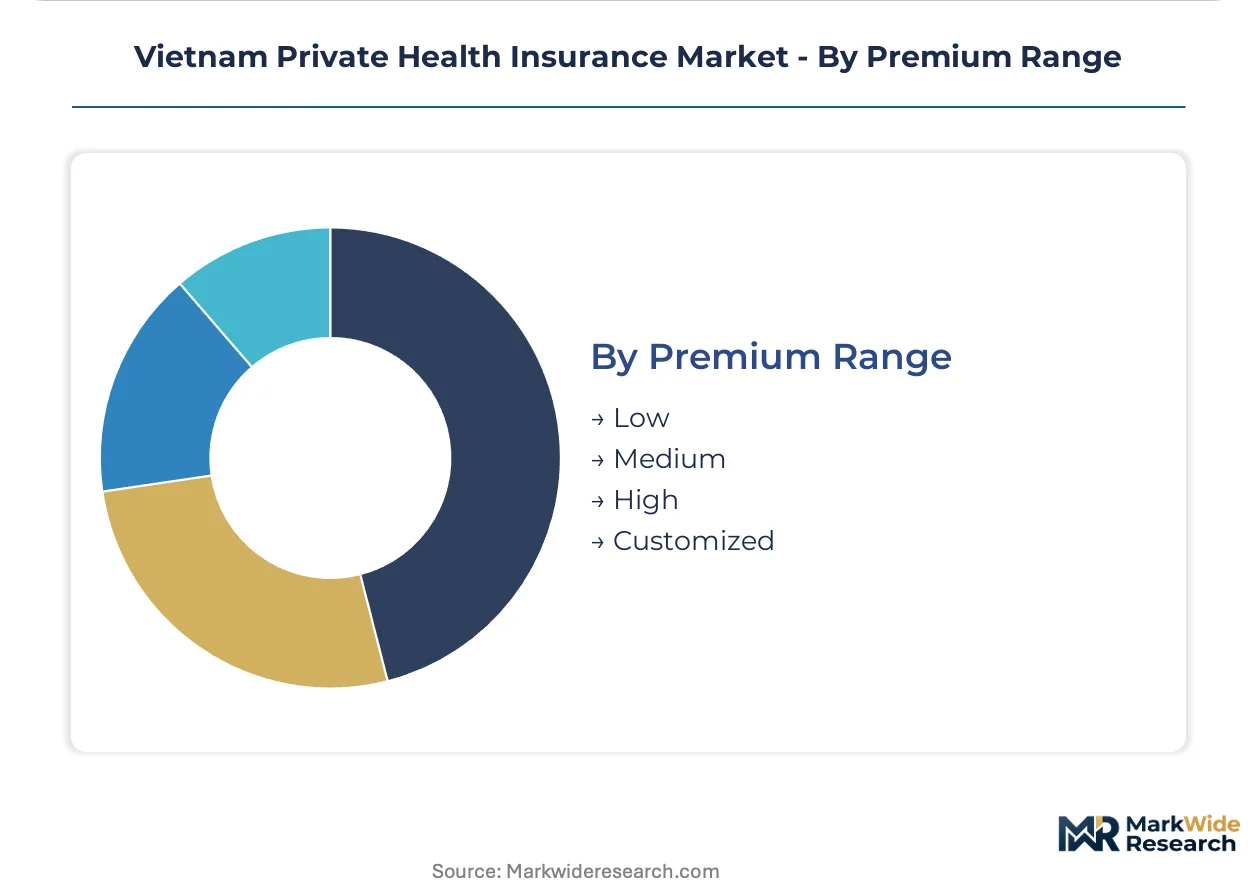
Premium Range:
Customer type stratification aligns with income distribution and provider network breadth, with customized tiers emerging for high-net-worth segments.
- High:Comprehensive coverage with minimal deductibles, international evacuation benefits, and unrestricted provider choice. Demand localizes to Hanoi and Ho Chi Minh City expatriate enclaves.
- Medium:Balanced cost-sharing structures with moderate deductibles and tier-1 private hospital networks.
- Low:Catastrophic coverage with high deductibles and restricted networks, targeting price-sensitive first-time buyers.
- Customized:Bespoke structures for ultra-high-net-worth individuals with specific provider preferences or international portability requirements.
Medium premium tiers sustain the broadest enrollment base; Customized segments are expanding most quickly among family office referrals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate employees in foreign-invested manufacturing and technology sectors concentrate demand in Vietnam's two primary economic poles, with emerging clusters in secondary cities reshaping distribution priorities.
Ho Chi Minh City
Expatriate professionals in District 2 and District 7 drive individual plan purchases through employer cash allowances. The Ministry of Health's Circular 54/2017/TT-BYT licensing requirements are compressing unlicensed intermediary activity in Thu Duc City and adjacent manufacturing zones.
Hanoi
Technology sector employers in Cau Giay and Nam Tu Liem districts are mandating telemedicine-integrated outpatient riders for management tiers. The Ministry of Finance's Insurance Supervisory Authority sandbox framework is enabling digital-only distribution pilots in the capital's urban core.
Binh Duong Province
Foreign-invested electronics and automotive component manufacturers in Thuan An and Di An cities are extending group supplemental coverage to local management. Provincial labor regulations are aligning with national social health insurance mandates while creating carve-outs for private hospital network access.
Bac Ninh Province
Samsung Electronics Vietnam and supplier ecosystems in Yen Phong Industrial Park are standardizing group health benefits for engineering staff. The provincial Department of Health is coordinating with private hospital chains to expand tier-1 accreditation coverage.
Da Nang
White-collar professionals in the central coast's largest city exhibit the fastest enrollment velocity for subscription-style wellness programs linked to fitness tracker data. Underpenetrated manufacturing zones in neighboring Quang Nam and Thua Thien-Hue provinces lack dedicated private hospital networks.
Vietnam Private Health Insurance Market Competitive Landscape
Player mix skews toward state-affiliated incumbents with captive agency networks and foreign-invested insurers with bancassurance partnerships. The competitive structure concentrates volume among three archetypes: domestic conglomerates leveraging rural distribution, regional Asian insurers with bank channel dominance, and global carriers with digital-first capabilities. Consolidation pressure is mounting through agent licensing threshold increases and risk-based capital framework discussions. Strategic moves center on exclusive provider contracts with accredited hospital chains and telemedicine platform integration.
Within the state-affiliated tier, Bao Viet Holdings occupies a position reflecting heritage advantages in provincial penetration. Among foreign-invested regional players, AIA Group Limited and Prudential Vietnam exemplify divergent channel strategies—one anchored in banking partnerships, the other in digital onboarding and bundled telemedicine policies. These three represent the competitive archetypes reshaping market boundaries.
| Leading Market Players |
|---|
| Bao Viet Holdings |
| AXA Global Healthcare |
| AIA Group Limited |
| Allianz SE |
| Generali Vietnam |
| Manulife (Vietnam) Company Limited |
| Chubb Group Holdings Inc. |
| Cigna Corporation |
| Prudential Vietnam |
| Others |
Value Network & Pricing Analysis
Telemedicine platform integration is displacing traditional nurse hotlines as the primary first-touch triage mechanism, simultaneously compressing per-member-per-month costs for insurers in Ho Chi Minh City and Hanoi while elevating outpatient rider attach rates across tier-1 private hospital networks. This substitution dynamic redraws supply geography toward Singapore-based reinsurance capacity and digital health infrastructure providers, while pricing economics shift toward behavior-linked premium discounts anchored on fitness tracker data compliance.
Pricing Analysis
Cost-plus reinsurance treaties with Singapore-based carriers index to medical inflation benchmarks and catastrophe loss development patterns. Three-tier pricing structure across premium, standard, and economy levels separates expatriate professionals with unrestricted provider choice from manufacturing employees with tier-1 network restrictions and price-sensitive first-time buyers with high deductibles. Price differentiation rests on accreditation status with Vinmec and Hoan My chains versus non-accredited provincial facilities. Cost compression in the economy tier is intensifying because social health insurance's 92% population coverage suppresses perceived supplemental value among rural populations. Self-employed professionals in Can Tho and Hai Phong exhibit highest price sensitivity; expatriate enclaves in District 2 and District 7 demonstrate lowest elasticity.
Supply Chain Analysis
Reinsurance capacity concentration in Singapore underwrites catastrophic risk coverage for domestic underwriters, exposing the market to hardening treaty terms and collateral requirements. Geographic supply concentration draws from Singapore, Thailand, and domestic Vietnamese capital pools for risk-bearing capacity. Raw material dependencies hinge on licensed actuarial talent, telemedicine API infrastructure, and electronic health record interoperability platforms. Supply chain risk centers on single-source vulnerability to Singapore-based reinsurers withdrawing capacity during hard market cycles. Distribution runs through bancassurance partnerships with Vietcombank and Techcombank, captive agency networks anchored by Bao Viet Holdings, and emerging digital-only direct-to-consumer channels testing the Ministry of Finance sandbox framework.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from employer mandate expansion creating distinct coverage tiers for expatriate, local management, and general employee populations. This demand-side shift fragments the historically monolithic group plan segment into niche structures requiring tailored network design and rider bundling.
For Market Incumbents: Secure exclusive provider contracts with tier-1 accredited hospital chains before foreign-invested digital entrants establish network breadth. Consolidate actuarial talent through targeted recruitment from regional hubs given Vietnam's association counts fewer than 200 fully qualified members. Backward integration into telemedicine platform development reduces per-member acquisition costs and locks in outpatient rider attach rates against bancassurance competitors. For New Entrants and Emerging Players: Anchor in the Da Nang-Central Coast Corridor where underpenetrated manufacturing zones in Quang Nam and Thua Thien-Hue provinces lack dedicated private hospital networks. Target self-employed professionals through mobile app-based policy issuance with AI-assisted underwriting, as this segment gains share fastest among digital distribution channels. Pursue first-mover advantage by building exclusive provider contracts before provincial Department of Health accreditation expands tier-1 coverage. For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional Asian insurers operating legacy core systems from the 1990s facing integration friction with telemedicine APIs and real-time claims adjudication engines. Long-term viability over a five-to-ten-year window favors acquisition targets with diversified product portfolios beyond pure health coverage and established reinsurance treaty access. Monitor Ministry of Finance implementation of risk-based capital frameworks aligned with IAIS standards as the inflection indicator for consolidation acceleration toward insurers with captive agency networks or bancassurance dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Provider Contracting | Locking tier-1 Vinmec and Hoan My accreditation status blocks competitor network breadth expansion in Hanoi and Ho Chi Minh City. |
| Telemedicine Platform Integration | Bundling video consultation modules with outpatient riders reduces emergency department claim leakage for District 7 technology employers. |
| Digital-Only Distribution Pilot | Testing direct-to-consumer models through Ministry of Finance sandbox framework bypasses Circular 54 licensing compression for unlicensed intermediaries. |
| Critical Illness Rider Development | Cancer and cardiovascular lump-sum supplements attach to base inpatient policies as oncology cost inflation accelerates at private centers. |
| Actuarial Talent Acquisition | Recruiting from regional hubs addresses product development velocity constraints for complex rider structures in a sub-200-member association. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with insurance product development executives, regulatory affairs specialists at the Ministry of Health, hospital procurement managers at Vinmec and Hoan My chains, and reinsurance treaty negotiators; alongside secondary validation through Ministry of Finance Insurance Supervisory Authority filings, Vietnam Social Security reimbursement databases, hospital accreditation registries, and customs records on medical equipment imports. Bottom-up policy-in-force estimates triangulated against top-down premium volume disclosures from licensed domestic and foreign-invested insurers.
Across the analysis window, forecasts reflect analytical framework segmentation by product type, end user category, coverage design, and premium tier, with additional modeling of provincial penetration rates and network accreditation status. CAGRs were derived from historical premium growth patterns, employer mandate expansion trajectories, and telemedicine adoption curves. Key inputs included social health insurance reimbursement cap adjustments, foreign direct investment flows into manufacturing zones, and tier-1 hospital accreditation timelines coordinated by provincial Departments of Health.
Decision-makers should treat outputs as directional under assumptions of continued employer mandate expansion and stable reinsurance treaty access from Singapore-based carriers; material deviation in Circular 54 enforcement intensity or foreign ownership limit liberalization would warrant model refresh. Practitioners should keep alternative scenarios live as risk-based capital framework implementation timelines and social health insurance benefit expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
China Business Income Insurance Market
Insurance
Europe Entertainment Insurance Market
Insurance
UAE Property and Casualty Insurance Market
Insurance
Europe Embedded Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Indonesia Private Health Insurance Market
Insurance
Canada House Insurance Market
Insurance
Crime Insurance Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Germany Travel Insurance Market
Insurance
France Property and Casualty Insurance Market
Insurance
Cyber Insurance Market