
 Insurance BPO Services Market | 2026-2036
Insurance BPO Services Market Size, Share, and Industry Trends Forecast 2026-2036
Insurance BPO Services Market Analysis
SLA-grade performance tiering is unwinding the traditional cost-plus contracting model in insurance outsourcing. Accenture leverages its cloud-native platforms to anchor large-scale policy administration mandates for North American carriers. Genpact specializes in AI-infused claims processing, differentiating its offering through proprietary data analytics layers. WNS Global Services competes aggressively in the London reinsurance segment, where its underwriting support desks occupy a narrow but defensible niche.
Insurance BPO services encompass the delegation of policy lifecycle functions—claims adjudication, premium collection, beneficiary verification, and regulatory reporting—to third-party operators executing under strict turnaround-time and accuracy-rate parameters. These arrangements reduce fixed-cost intensity for carriers while introducing variable-cost scalability aligned to premium volume fluctuations. Claims processing leads the service-type dimension, though robotic process automation is displacing manual intake fastest in policy administration. Cloud computing underpins the delivery-model shift, with hybrid structures capturing margin pools as carriers demand data-sovereignty compliance alongside cost arbitrage.
FDA guidelines on algorithmic decision-support systems intersect with state-level NAIC model regulations to shape AI deployment standards in US insurance BPO contracts. The EU AI Act imposes conformity-assessment obligations on European carriers, forcing providers to re-architect their risk-scoring engines for auditability. India's BIS data-localization standards and TRAI telecom-quality mandates add compliance layers for offshore delivery centers serving domestic insurers. Stakeholders must weigh regulatory fragmentation against automation returns when selecting delivery geography and technology stack.
Market Dynamics
SLA-grade performance tiering is unwinding the traditional cost-plus contracting model as property and casualty insurers demand outcome-linked pricing tied to claims accuracy rates and turnaround-time guarantees. Cloud-native delivery platforms are compressing deployment cycles while introducing new data-sovereignty compliance obligations across offshore delivery centers.
Growth Catalysts
- EU AI Act conformity mandates:European carriers now require algorithmic auditability from BPO partners, creating premium service tiers for providers with certified risk-scoring engines and explainable AI frameworks.
- Robotic process automation in policy administration:RPA tools are eliminating manual intake bottlenecks, allowing carriers to scale premium volume without proportional headcount expansion in back-office functions.
- India's delivery hub concentration:Mumbai and Bangalore have consolidated underwriting support and customer service operations, offering carriers variable-cost scalability aligned to cyclical premium fluctuations.
Market Restraints
- Data-localization compliance costs:India's BIS standards and EU GDPR requirements force providers to maintain redundant infrastructure across jurisdictions, eroding labor arbitrage margins.
- Talent scarcity in actuarial analytics:Specialized underwriting support desks in London and Bermuda face recruitment bottlenecks for professionals combining domain expertise with AI tool proficiency.
- Legacy system integration friction:Carriers running on decades-old policy administration cores impose costly middleware requirements that delay cloud-migration timelines and inflate implementation budgets.
Strategic Opportunities
- Underpenetrated Latin American markets:Brazilian and Mexican carriers show accelerating appetite for outsourced claims adjudication as regulatory complexity outpaces internal capability building.
- Climate risk modeling convergence:Integration of satellite imagery analytics with traditional actuarial methods creates new service lines for catastrophe-exposed property underwriting support.
- Outcome-based contracting expansion:North American carriers are piloting contracts where BPO fees tie directly to claims closure rates and customer satisfaction scores rather than input volumes.
Industry Challenges
- AI model explainability requirements:EU AI Act conformity assessments demand documentation trails that many offshore delivery centers lack, forcing expensive re-architecture of automated decision systems.
- Attrition in specialized underwriting desks:London-market reinsurance support teams face turnover rates exceeding industry norms as competitors poach talent with equity-linked compensation packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insurance BPO Services Market |
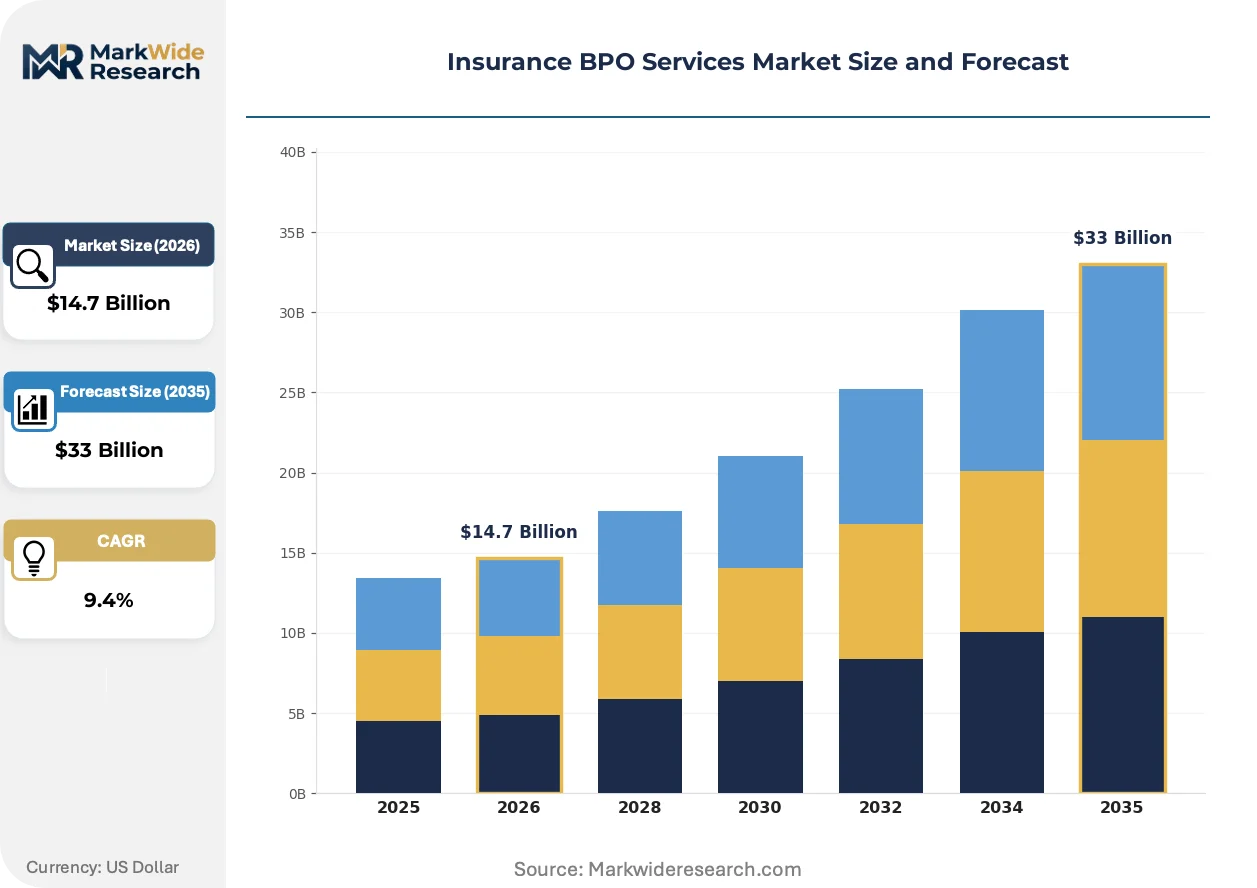
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $33 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Claims Processing, Policy Administration, Underwriting Support, Customer Service Delivery Model: Onshore, Offshore, Nearshore, Hybrid End User: Life Insurance, Property & Casualty, Health Insurance, Reinsurance Technology: AI Solutions, Cloud Computing, Robotic Process Automation, Data Analytics |
| Companies Covered | Wipro, Concentrix, Accenture, WNS Global Services, Crawford & Company, Cognizant, Capgemini, EXL Service, Genpact, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insurance BPO Services Market Emerging Trajectories
Intelligent automation is compressing the boundary between routine transactional processing and judgment-intensive underwriting support. Carriers now expect BPO partners to deliver predictive analytics layers rather than pure labor arbitrage.
Generative AI tools for claims narrative analysis are supplanting manual adjuster review in first-notice-of-loss intake. Mid-tier US property carriers are deploying these systems across auto and homeowners lines within eighteen-month rollout cycles. The technology is enabling same-day claim resolution for straightforward cases while reserving human expertise for complex liability disputes.
The EU AI Act's risk-based classification system imposes conformity-assessment obligations on automated claims decision engines used by European carriers. Providers must re-architect their algorithms to generate auditable decision trails and human-override protocols. Life and health insurers in Germany and France are most affected, with several carriers pausing AI deployments pending vendor certification.
Subscription-based service models are displacing traditional per-transaction pricing in policy administration outsourcing. US regional carriers are consolidating vendor relationships under multi-year platform agreements that bundle software, processing capacity, and regulatory reporting. This shift is most visible in the Midwest and Southeast states where mid-market insurers lack scale to justify captive operations.
Insurance BPO Services Market Segmentation
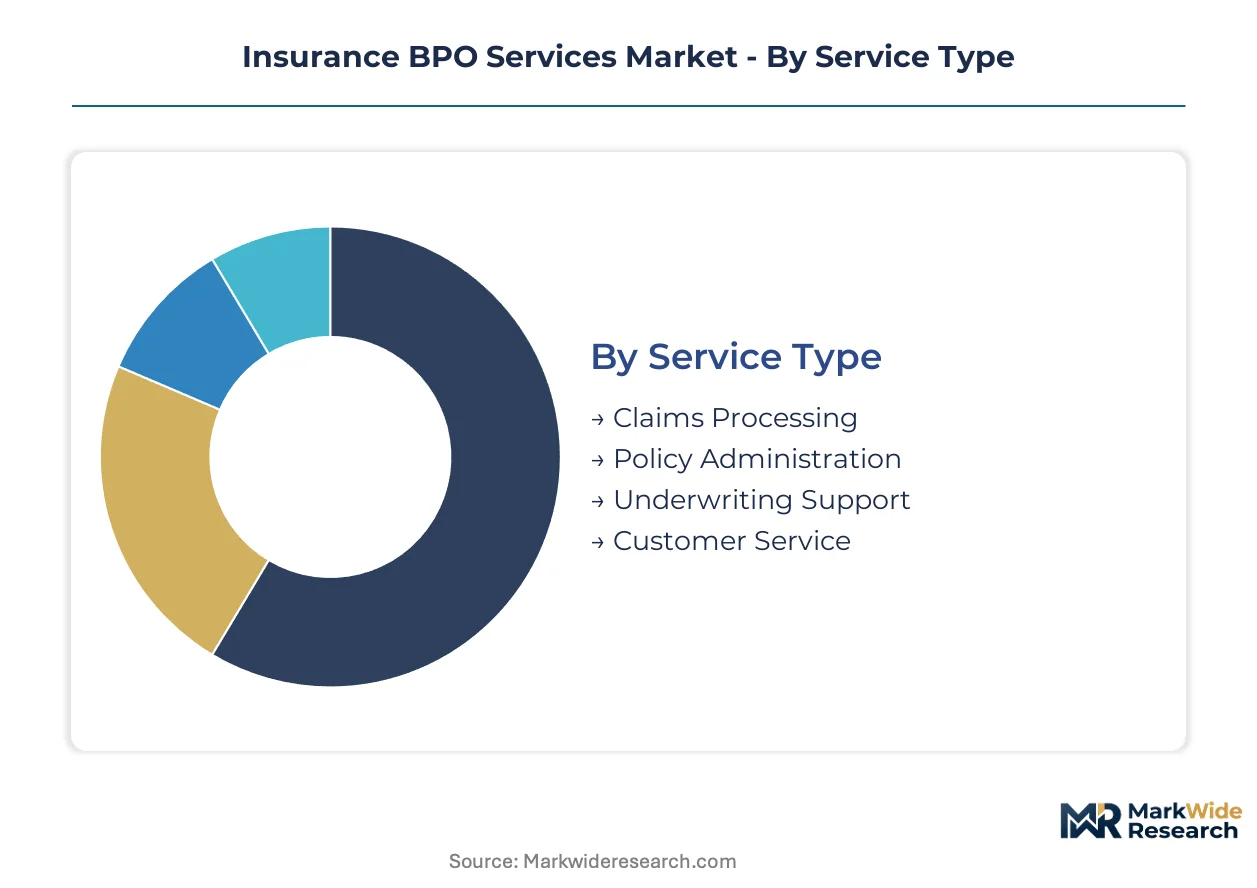
Segmentation in insurance BPO services reveals how carriers align outsourcing architecture to regulatory exposure, cost arbitrage targets, and automation maturity. Each dimension carries distinct margin profiles and compliance obligations that reshape vendor selection criteria.
Service Type:
EU AI Act auditability requirements and FDA algorithmic guidance in the US create divergent compliance burdens across service categories, forcing carriers to tier their outsourcing portfolios by regulatory risk.
- Claims Processing:Automated adjudication engines handle first-notice-of-loss intake, medical bill review, and settlement authorization. Property carriers in Florida and Texas concentrate demand here as catastrophe volume strains internal capacity.
- Policy Administration:Premium collection, beneficiary updates, and regulatory reporting execution. Life insurers in Germany and France are migrating these functions to certified providers to satisfy EU AI Act conformity assessments.
- Underwriting Support:Risk scoring, actuarial data preparation, and submission triage. Bermuda reinsurance desks and London-market syndicates drive premium pricing for specialized expertise.
- Customer Service:Policyholder inquiry resolution and claims status communication. Indian delivery centers in Mumbai and Bangalore capture volume through 24/7 multilingual capacity.
Claims Processing handles the majority of throughput; Policy Administration is the fastest mover on share as RPA deployment accelerates.
Delivery Model:
Cost tier differentiation separates captive-scale operations from variable-cost arrangements, with hybrid structures capturing margin pools as data-sovereignty requirements harden.
- Onshore:Domestic delivery centers executing under direct carrier supervision. US regional insurers in the Midwest favor this model for Medicare Advantage compliance and HIPAA audit trails.
- Offshore:India-based processing hubs leveraging labor arbitrage for high-volume transactional work. TRAI telecom-quality mandates and BIS data-localization standards add compliance layers that erode margin advantages.
- Nearshore:Mexico and Poland delivery centers serving US and EU carriers respectively. Time-zone alignment and cultural proximity command 15-25% premiums over offshore rates.
- Hybrid:Split architecture with sensitive functions onshore and volume processing offshore. European carriers facing GDPR and EU AI Act obligations are expanding this configuration fastest.
Offshore delivery retains the largest volume footprint; Hybrid models are expanding most quickly as regulatory fragmentation deepens.
End User:
Application-specific requirements reshape service specifications, with property catastrophe exposure and health data privacy creating the widest divergence in vendor capabilities.
- Life Insurance:Long-duration policy administration, beneficiary verification, and mortality-based claims adjudication. Japanese carriers under METI guidance and German insurers face the strictest reserving-documentation demands.
- Property & Casualty:Short-tail claims processing and catastrophe response operations. US Gulf Coast and Australian east coast carriers drive seasonal capacity spikes that favor variable-cost outsourcing.
- Health Insurance:Medical claims coding, pre-authorization management, and HIPAA-compliant data handling. US payers dominate demand as CMS audit intensity escalates.
- Reinsurance:Treaty administration, loss portfolio transfer support, and retrocession processing. London, Bermuda, and Zurich concentration creates specialized talent scarcity.
Property & Casualty generates the highest transaction velocity; Health Insurance is gaining share fastest as Medicare Advantage expansion outpaces other lines.
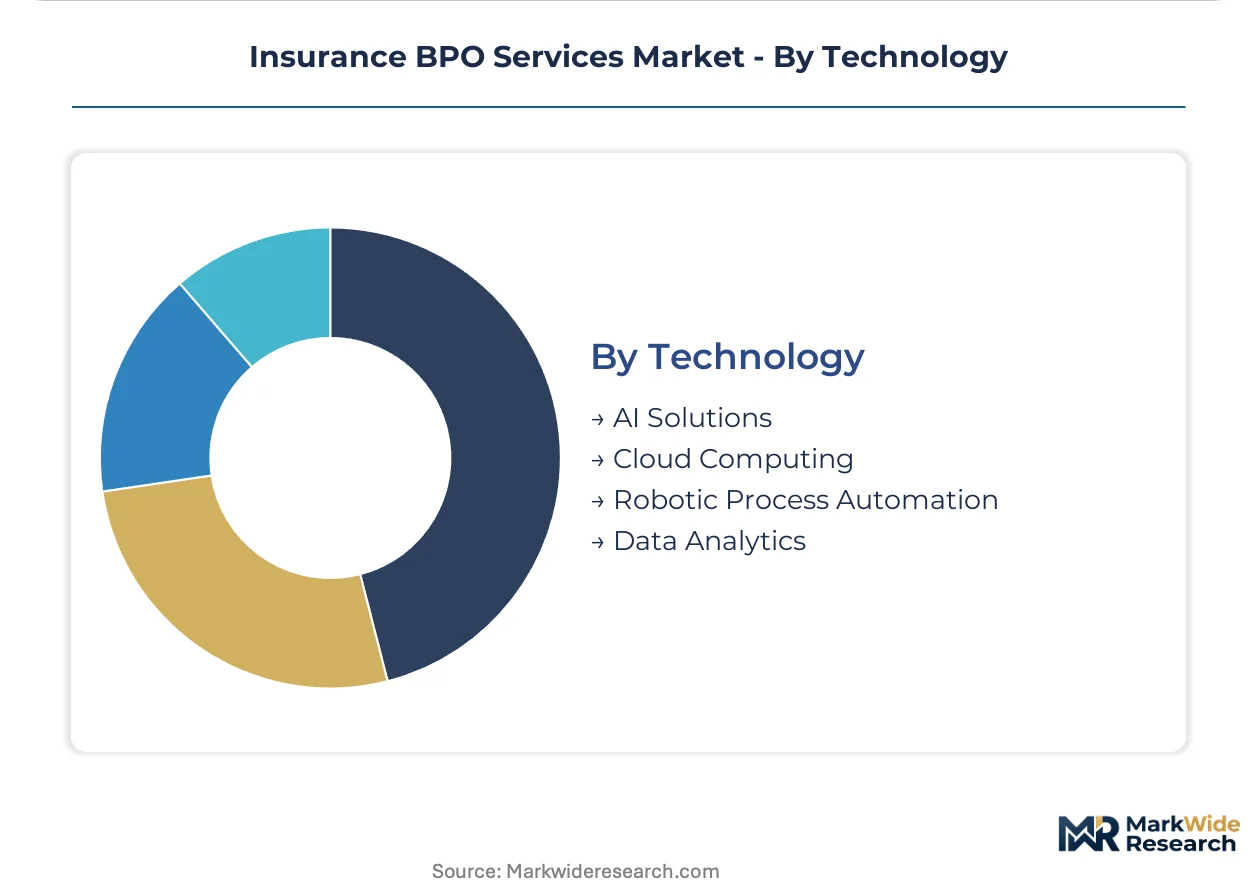
Technology:
Margin structure follows automation maturity, with cloud-native platforms and explainable AI frameworks commanding premium positioning against legacy toolsets.
- AI Solutions:Machine learning models for fraud detection, risk scoring, and claims prediction. EU AI Act conformity assessments and FDA algorithmic guidance impose documentation burdens that favor established providers.
- Cloud Computing:Scalable infrastructure for policy administration platforms and data lakes. India's BIS localization standards and EU GDPR requirements force multi-jurisdiction redundancy.
- Robotic Process Automation:Rule-based bots for data entry, document classification, and system reconciliation. Mid-tier US carriers deploy these fastest in policy administration.
- Data Analytics:Predictive modeling for underwriting profitability and customer retention. Satellite imagery integration for climate risk assessment represents the newest service line.
Cloud Computing underpins the largest installed base; AI Solutions are climbing the fastest as carrier procurement shifts from labor arbitrage to outcome-linked capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Services trade flows in insurance BPO tilt heavily toward export-oriented delivery hubs, with India generating substantial service exports to North American and European carriers while the United States remains the largest net importer of outsourced policy administration functions.
United States
Property and casualty carriers in Florida and Texas drive concentrated demand for catastrophe claims processing capacity. HIPAA and state-level NAIC model regulations govern data handling standards for health insurance BPO contracts. Delivery concentration spans Midwest policy administration centers and Southeast customer service hubs.
India
Mumbai and Bangalore anchor underwriting support and 24/7 customer service operations for international carriers seeking labor arbitrage. BIS data-localization standards and TRAI telecom-quality mandates impose compliance infrastructure requirements on delivery centers. Karnataka and Maharashtra host the densest clusters of insurance-specific BPO facilities.
Germany
Life insurers under METI guidance face strict reserving-documentation demands that favor specialized policy administration partners. EU AI Act conformity assessments force re-architecture of automated claims decision engines. Frankfurt and Munich concentrate domestic delivery capacity for regulatory-sensitive functions.
United Kingdom
London-market reinsurance syndicates generate premium pricing for specialized underwriting support desks. GDPR requirements intersect with Lloyd's regulatory frameworks to shape data governance in BPO arrangements. The City of London and Bermuda-linked operations dominate high-value actuarial service lines.
Brazil
Carriers in São Paulo and Rio de Janeiro show accelerating appetite for outsourced claims adjudication as regulatory complexity outpaces internal capability building. ANVISA and SUSEP frameworks govern health and general insurance outsourcing standards. Southeast regional delivery centers are expanding to capture Latin American market growth.
Insurance BPO Services Market Vendor Landscape
Listed leaders compete with private specialists across service-type and delivery-model dimensions, producing a tiered structure where scale-driven platforms coexist with niche underwriting expertise providers. The vendor base separates into three strategic archetypes: cloud-native platform operators, AI-infused claims specialists, and regional reinsurance support boutiques. Consolidation pressures favor acquisition of mid-tier policy administration providers by larger consultancies, while talent scarcity in London and Bermuda drives equity-linked compensation wars for actuarial professionals.
Within the scale-driven tier, Accenture and Cognizant occupy positions anchored by cloud-native infrastructure and large-scale carrier mandates. Genpact exemplifies the AI-specialist archetype through its claims processing differentiation. WNS Global Services represents the regional boutique model with concentrated presence in London-market reinsurance support. These three patterns illustrate how competitive positioning separates across technology investment intensity versus domain expertise depth.
| Leading Market Players |
|---|
| Wipro |
| Concentrix |
| Accenture |
| WNS Global Services |
| Crawford & Company |
| Cognizant |
| Capgemini |
| EXL Service |
| Genpact |
| Others |
Supply Flow & Price Mechanics
EU AI Act conformity assessments gate both vendor qualification and price tiering simultaneously, forcing carriers to pay premiums for certified algorithmic auditability while squeezing uncertified providers into commodity transactional rates. This regulatory filter reshapes how BPO contracts price risk-scoring engine transparency against labor arbitrage savings.
Pricing Analysis
Property and casualty carriers anchor pricing stratification across premium, standard, and economy tiers tied to claims accuracy guarantees and turnaround-time SLAs. Certification under EU AI Act and FDA algorithmic guidance commands 15-25% premiums over uncertified competitors. Cost compression in the offshore tier intensifies as India's BIS data-localization requirements erode traditional labor arbitrage margins. Mid-market US regional insurers show highest price sensitivity, while London-market reinsurance syndicates prioritize domain expertise over unit cost.
Supply Chain Analysis
Just-in-time capacity scaling dominates as carriers demand variable-cost alignment to premium volume fluctuations rather than fixed infrastructure commitments. Supply concentrates in India, Poland, and Mexico, with Mumbai and Bangalore anchoring high-volume transactional processing while nearshore centers capture regulatory-sensitive functions. Talent pipelines draw from actuarial programs in the UK, India, and the US, with specialized underwriting desks in London and Bermuda facing acute recruitment bottlenecks. Single-source vulnerability runs through India's concentrated delivery hub architecture. Distribution feeds from platform-based vendor relationships consolidating software, processing capacity, and compliance reporting into multi-year agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as cloud-native policy administration systems displace fragmented point solutions, with interoperability mandates from EU AI Act and HIPAA driving carrier consolidation around integrated vendor ecosystems.
For Market Incumbents: Shield core policy administration mandates through certification investments in EU AI Act conformity and FDA algorithmic guidance compliance. Accenture and Cognizant anchor positions via cloud-native infrastructure; smaller providers face displacement without comparable platform scale. Vertical integration into proprietary AI layers for claims prediction offers defensive differentiation against pure labor arbitrage competitors. For New Entrants and Emerging Players: Lead with climate risk modeling convergence as the most penetrable white space, integrating satellite imagery analytics with traditional actuarial methods for catastrophe-exposed property underwriting. Brazilian and Mexican carriers present underpenetrated demand as regulatory complexity outpaces internal capability building. A partnership-first go-to-market angle with regional reinsurance brokers accelerates credibility in London-market syndicates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-infused claims processing as explainable model development demands specialized engineering talent and compliance infrastructure. Long-term viability favors acquisition targets with certified algorithmic auditability and existing carrier platform relationships. The signal to watch is EU AI Act enforcement intensity, which would accelerate carrier migration toward certified providers and strand uncertified assets.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Establishes algorithmic auditability credentials required by German and French life insurers under conformity mandates. |
| Climate Risk Modeling Integration | Creates new service lines combining satellite imagery with actuarial methods for Florida and Texas property carriers. |
| Platform Consolidation Partnership | Bundles software, processing capacity, and regulatory reporting into multi-year agreements for Midwest regional insurers. |
| Nearshore Delivery Expansion | Captures GDPR and EU AI Act-sensitive functions through Poland and Mexico centers commanding time-zone premiums. |
| Specialized Talent Acquisition | Addresses actuarial analytics scarcity in London and Bermuda through equity-linked compensation structures. |
Methodological Framework
Initial hypotheses were tested against primary input from insurance carrier procurement officers, BPO delivery center operations heads, regulatory compliance leads, and reinsurance broker executives and refined through secondary validation. Primary interviews combined with carrier RFP documentation, EU AI Act conformity assessment records, FDA algorithmic guidance filings, and Indian BIS localization compliance reports. SEC filings from listed BPO providers and Lloyd's market underwriting data provided additional triangulation. Bottom-up service-type demand modeling and top-down carrier IT spending analysis were reconciled across approaches.
Variance decomposition across service type, delivery model, end user, and technology dimensions structured the analytical framework over the projection horizon. CAGRs derived from carrier outsourcing penetration rates, automation adoption curves, and regulatory compliance cost trajectories. Segmentation modeling incorporated policy lifecycle function, geographic delivery configuration, insurance line-specific requirements, and automation maturity tier. Cloud infrastructure capex disclosures and carrier premium volume cyclicality informed capacity scaling assumptions.
The analysis sits within stated boundaries; outcomes outside sustained carrier cost reduction mandates and regulatory enforcement continuity would require recalibration. Forecasts reflect assumptions regarding EU AI Act implementation timelines, India delivery hub labor cost trajectories, and legacy system integration friction persistence. Revision becomes warranted when algorithmic explainability requirements cross enforcement thresholds or data-localization compliance costs exceed labor arbitrage savings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
US Long-Term Care Private Insurance Market
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
Employee Benefit Broker Market
Insurance
Aircraft Insurance Market
Insurance
Global SME Insurance Market
Insurance
Telematics-Based Auto Insurance Market
Insurance
B2B2C Insurance Market
Insurance
Travel Insurance Market
Insurance
Cargo Insurance Market
Insurance
Property Insurance Market
Insurance
Business Income Insurance Market
Insurance
Intellectual Property Liability Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
Canada Parametric Insurance Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Europe Online Insurance Market