
 Saudi Arabia Health & Medical Insurance Market | 2026-2036
Saudi Arabia Health & Medical Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Health & Medical Insurance Market Insights
Comprehensive family takaful coverage is redrawing competitive boundaries in the Saudi insurance landscape. Bupa Arabia for Cooperative Insurance leverages its hospital network density to sustain premium positioning in major cities. Tawuniya anchors the corporate segment through direct employer relationships and scale. Al Rajhi Takaful differentiates via Shariah-compliant product structures that appeal to conservative buyer segments.
Health and medical insurance in Saudi Arabia constitutes risk-pooled financing mechanisms covering diagnostic, therapeutic, and preventive healthcare expenditures against premium contributions, with takaful models operating on cooperative principles and surplus-sharing rather than conventional interest-based underwriting. The primary purpose centers on reducing out-of-pocket medical costs while ensuring regulated access to private healthcare providers under CCHI-mandated schemes. Corporate group policies dominate premium volume due to compulsory employer-sponsored coverage for expatriate workers, while family plans capture faster policy growth as Saudi nationals expand dependent coverage under evolving social protection frameworks. Inpatient care services generate the largest claim outlays, though preventive services segments attract insurer investment as risk-adjusted pricing models mature.
CCHI mandates, SAMR licensing requirements, and SFDA pharmaceutical reimbursement protocols collectively structure product design and provider network obligations for market participants. These frameworks enforce minimum benefit standards, capital adequacy ratios, and claims settlement timelines that elevate operational barriers for smaller underwriters. Stakeholders must monitor regulatory convergence between takaful accounting standards and conventional solency benchmarks as the authority consolidates sector oversight.
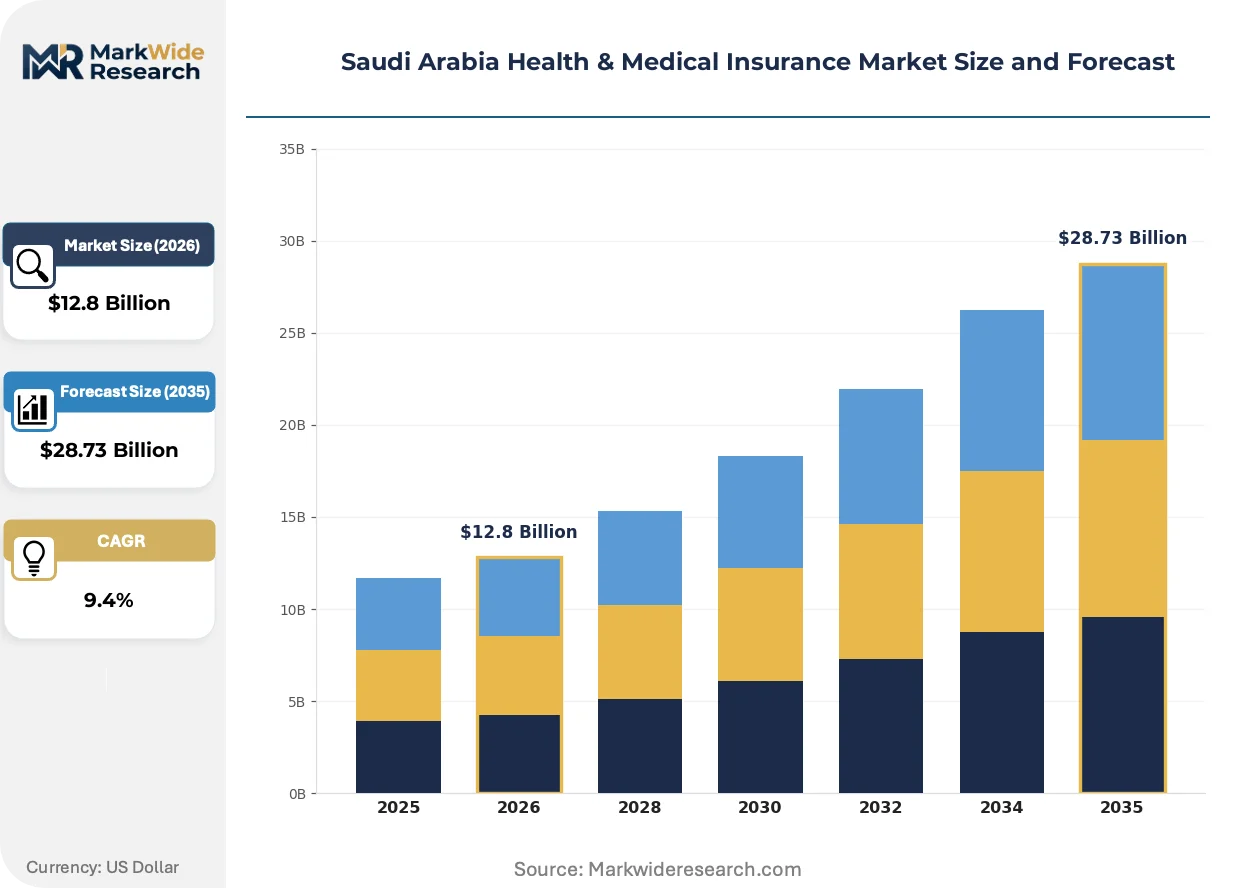
Market Dynamics
The Saudi Arabia health insurance sector is undergoing structural recalibration as CCHI enforcement tightens benefit minimums and SAMR capital requirements compress the carrier base, forcing consolidation among undercapitalized takaful operators.
Growth Catalysts
- Expatriate workforce mandates:CCHI compulsory employer coverage for foreign workers sustains premium inflows across construction, hospitality, and domestic services sectors.
- Nitaqat program incentives:Saudization quotas push employers toward comprehensive family coverage to attract and retain national talent in competitive labor pools.
- Telemedicine infrastructure:SFDA-approved remote diagnostic platforms expand network reach into secondary cities without proportional hospital capex.
Market Restraints
- Reinsurance capacity concentration:Retrocession markets in London and Singapore impose capacity limits on catastrophe coverage, elevating retention ratios for Saudi primary carriers.
- Medical inflation differentials:Pharmaceutical reimbursement under SFDA protocols lags actual provider pricing, creating margin compression on high-cost therapeutic categories.
- Takaful surplus distribution mechanics:Cooperative profit-sharing structures constrain retained earnings accumulation versus conventional underwriting models.
Strategic Opportunities
- Central Region penetration gaps:Qassim and Ha'il provinces exhibit coverage density below one-third of Riyadh levels, presenting first-mover network expansion potential.
- Preventive screening bundling:Oncology and cardiovascular risk assessment packages align with MOH public health objectives and attract risk-adjusted premium incentives.
- Bancassurance channel activation:SAMA-licensed retail banking networks offer captive distribution to affluent Saudi households seeking family takaful upgrades.
Industry Challenges
- Actuarial talent scarcity:Qualified pricing specialists with takaful accounting fluency remain concentrated among established Riyadh-based underwriters.
- Legacy core system integration:Policy administration platforms from the 2000s resist API connectivity with emerging health-tech ecosystems.
- Claims adjudication automation:Manual pre-authorization workflows create settlement friction and elevate operational expense ratios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Health & Medical Insurance Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Individual, Family, Group, Corporate Plan Type: Health Maintenance Organization, Preferred Provider Organization, Exclusive Provider Organization, Fee-for-Service End User: Employers, Government, Individuals, Healthcare Providers Service Offerings: Inpatient Care, Outpatient Care, Preventive Services, Emergency Care |
| Companies Covered | Al Rajhi Company for Cooperative Insurance (Al Rajhi Takaful), Allianz Saudi Fransi Cooperative Insurance Company, Bupa Arabia for Cooperative Insurance, Malath Cooperative Insurance & Reinsurance Company, Al Alamiya for Cooperative Insurance Company, Tawuniya (The Company for Cooperative Insurance), Saudi Arabian Cooperative Insurance Company (SAICO), Walaa Co-operative Insurance, MedGulf (Mediterranean & Gulf Cooperative Insurance & Reinsurance), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Health & Medical Insurance Market Trends and Innovations
Digital health infrastructure and regulatory data mandates are compressing traditional intermediation layers, while beneficiary expectations shift toward real-time service orchestration rather than retrospective reimbursement.
AI-powered claims triage is displacing manual pre-authorization desks at major hospital groups. Bupa Arabia and Tawuniya have deployed machine learning models for outpatient procedure validation, cutting decision latency from days to hours. This capability is displacing traditional third-party administrator relationships as carriers bring adjudication in-house.
CCHI data interoperability mandates now require standardized electronic health record exchange between insurers and providers. The regulation forces unified coding protocols across previously fragmented hospital information systems. Smaller clinic networks in Jeddah and Dammam face compliance cost burdens that favor acquisition by larger integrated delivery systems.
Employer-sponsored wellness program adoption is accelerating among Saudi nationals in banking and petrochemical sectors. Comprehensive annual health assessments with biometric tracking replace basic inpatient coverage as the competitive differentiator in talent retention. This pattern concentrates in Riyadh's financial district and Jubail's industrial corridor where workforce composition skews toward mid-career professionals with dependent families.
Saudi Arabia Health & Medical Insurance Market Segmentation
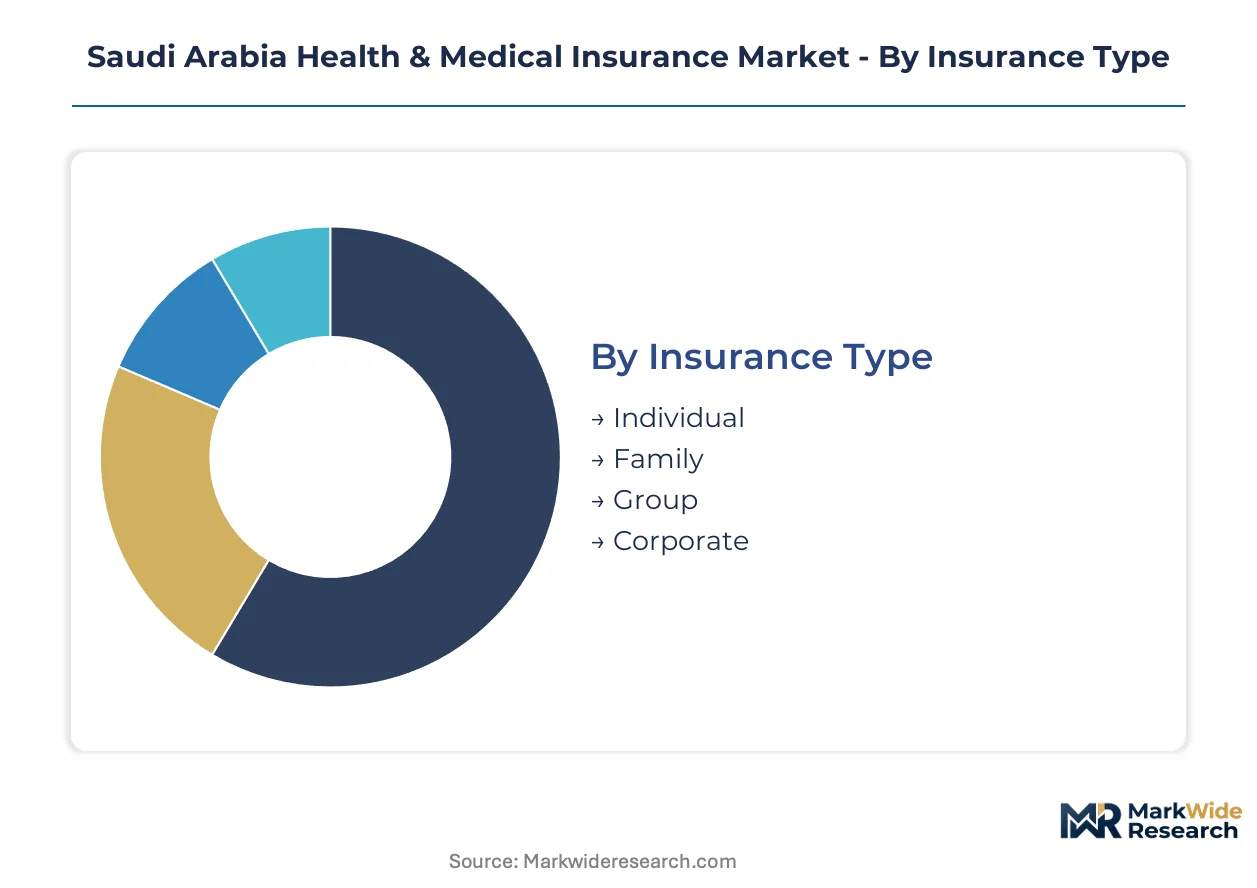
Segmentation in Saudi Arabia's health insurance market reveals how CCHI mandates and employer obligations channel demand through distinct policy structures. Carrier product development and network investments align tightly with these category boundaries.
Insurance Type:
Corporate intermediaries dominate volume flow, while direct-to-consumer channels serve evolving family coverage needs among Saudi nationals.
- Corporate:Employer-sponsored group policies covering expatriate workforces under CCHI compulsory coverage rules. Construction, hospitality, and domestic services sectors in Riyadh and Jeddah generate concentrated premium inflows through this channel.
- Group:Collective risk-pooled arrangements for employee cohorts with standardized benefit tiers. Large petrochemical and banking employers in Jubail's industrial corridor and Riyadh's financial district leverage these structures for talent retention.
- Family:Dependent coverage expansion among Saudi nationals responding to Nitaqat program incentives. Direct sales and bancassurance channels activate this segment for affluent households seeking takaful upgrades.
- Individual:Single-policyholder coverage purchased through broker networks or carrier direct platforms. Limited penetration outside mandatory employer schemes constrains volume.
Corporate dominates installed base. Family is where expansion concentrates.
Plan Type:
Cost tier stratification shapes network access breadth and out-of-pocket exposure for beneficiaries across income brackets.
- Health Maintenance Organization:Gatekeeper-model plans requiring primary care physician referrals for specialist access. Tight utilization controls and capitated provider payments attract price-sensitive employer sponsors in volume sectors.
- Preferred Provider Organization:Tiered network designs balancing cost containment with beneficiary choice flexibility. Mid-tier Saudi employers in competitive labor markets favor this structure for national talent recruitment.
- Exclusive Provider Organization:Restricted network plans with zero out-of-network coverage except emergencies. Lower premium positioning serves cost-constrained construction sector employers with high expatriate turnover.
- Fee-for-Service:Indemnity-style reimbursement allowing unrestricted provider selection. Limited market presence due to CCHI pressure toward managed care standardization.
Health Maintenance Organization captures the largest policy count. Preferred Provider Organization is climbing the fastest as employers balance cost control with workforce satisfaction.
End User:
Customer type determines purchasing authority, benefit design influence, and renewal negotiation leverage in policy lifecycles.
- Employers:Corporate sponsors holding procurement authority for expatriate and national worker coverage. CCHI compliance obligations and Nitaqat scoring incentives drive benefit tier decisions.
- Individuals:Direct purchasers lacking group purchasing power. Broker-assisted transactions concentrate among high-net-worth Saudi nationals seeking premium takaful products.
- Government:Public sector entities including MOH and state-owned enterprises. Separate procurement frameworks and sovereign guarantee backing distinguish this channel.
- Healthcare Providers:Institutional purchasers of malpractice and facility coverage. Distinct from beneficiary-side demand, governed by SFDA facility licensing requirements.
Employers control premium volume. Individuals represent the steepest expansion trajectory as bancassurance penetration deepens.
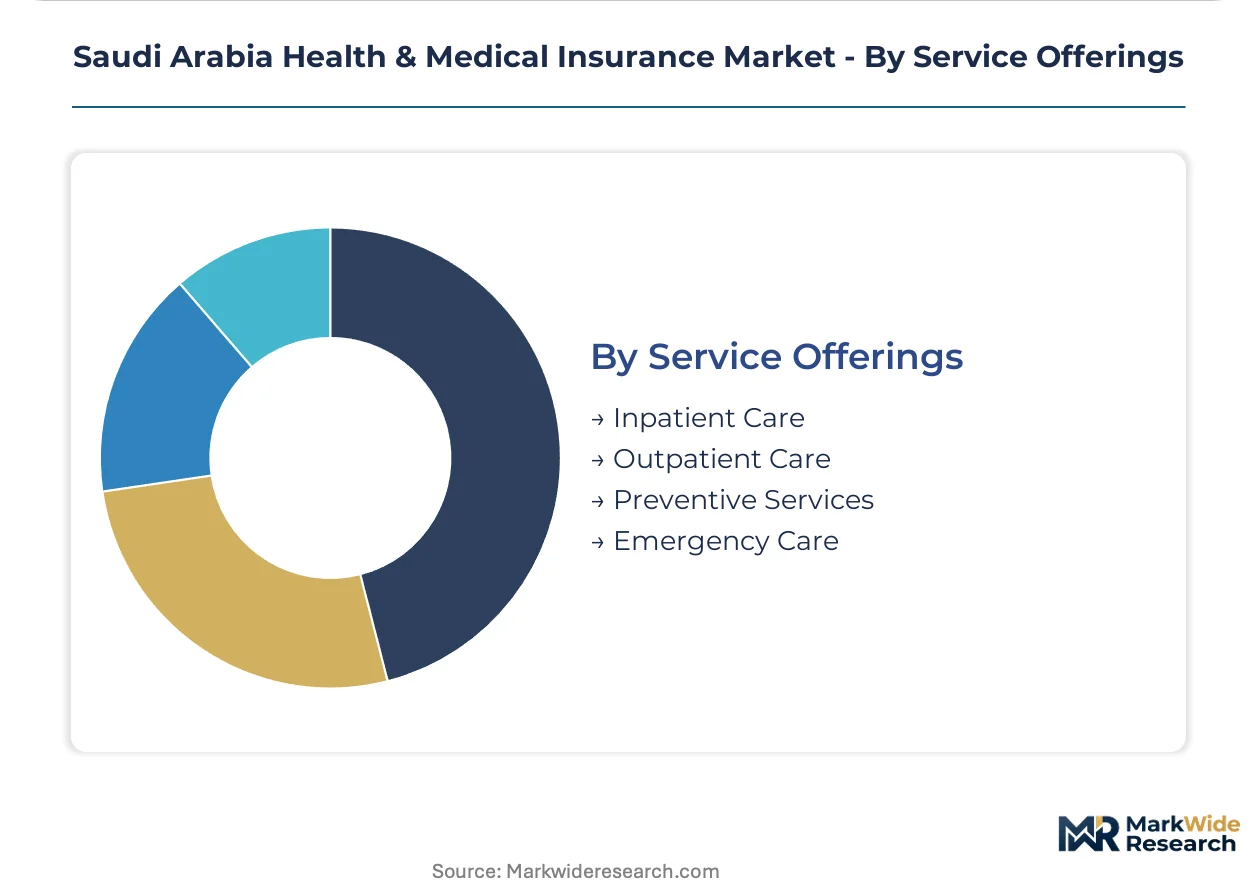
Service Offerings:
Application focus determines claims cost structure and insurer medical management investment priorities.
- Inpatient Care:Hospitalization coverage including surgical procedures, intensive care, and accommodation costs. Generates the largest claim outlays and drives reinsurance program design for primary carriers.
- Preventive Services:Screening, vaccination, and wellness program coverage. Oncology and cardiovascular risk assessment packages align with MOH public health objectives and attract risk-adjusted premium incentives.
- Outpatient Care:Physician consultations, diagnostic testing, and minor procedures without hospital admission. Telemedicine integration expands network reach into secondary cities under SFDA-approved remote diagnostic protocols.
- Emergency Care:Urgent treatment coverage including ambulance transport and stabilization services. Mandatory minimum benefits under CCHI directives ensure baseline availability across all policy tiers.
Inpatient Care absorbs the dominant share of claims expenditure. Preventive Services is gaining share fastest as risk-adjusted pricing models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier licensing and hospital network density concentrate premium volume in Riyadh and Jeddah, while secondary provinces present expansion corridors for digitized distribution models.
Riyadh
Corporate headquarters and CCHI regulatory operations anchor underwriting concentration here. The Nitaqat program drives employer-sponsored family coverage upgrades among financial sector employers. King Faisal Specialist Hospital and Research Centre anchors premium network access for high-tier policies.
Eastern Province
Petrochemical sector employment sustains group policy demand across Jubail and Dammam industrial zones. SAMR capital requirements filter out smaller operators from this high-volume corridor. Saudi Aramco-affiliated medical cities concentrate specialist provider capacity for tier-one network contracts.
Western Region
Jeddah's expatriate workforce density sustains mandatory employer coverage inflows under CCHI directives. The Hajj pilgrimage infrastructure generates seasonal emergency coverage demand. International Medical Center and King Abdulaziz University Hospital anchor preferred provider networks.
NEOM Northwest
Greenfield city development attracts insurer pilot programs for telemedicine-first coverage models. SFDA-approved remote diagnostic protocols enable network extension without legacy hospital infrastructure. The project zone operates under regulatory sandbox frameworks distinct from national CCHI administration.
Saudi Arabia Health & Medical Insurance Market Competitive Landscape
Concentration sits with takaful-specialist underwriters holding direct employer relationships and hospital network density. The carrier base compresses under SAMR capital adequacy requirements, forcing consolidation among sub-scale operators. Three archetypes dominate: cooperative takaful incumbents with scale, conventional-cum-takaful hybrids leveraging multinational reinsurance, and digital-first challengers attacking claims automation. Competitive moves center on network exclusivity negotiations and in-house claims adjudication technology deployment.
Among established cooperative underwriters, Bupa Arabia for Cooperative Insurance, Tawuniya, and Al Rajhi Takaful exemplify the three strategic positions. Bupa Arabia represents network-density-driven premium positioning. Tawuniya anchors the corporate group policy segment through direct employer channel control. Al Rajhi Takaful occupies the Shariah-compliant specialist tier, targeting conservative buyer segments with surplus-sharing product structures.
| Leading Market Players |
|---|
| Al Rajhi Company for Cooperative Insurance (Al Rajhi Takaful) |
| Allianz Saudi Fransi Cooperative Insurance Company |
| Bupa Arabia for Cooperative Insurance |
| Malath Cooperative Insurance & Reinsurance Company |
| Al Alamiya for Cooperative Insurance Company |
| Tawuniya (The Company for Cooperative Insurance) |
| Saudi Arabian Cooperative Insurance Company (SAICO) |
| Walaa Co-operative Insurance |
| MedGulf (Mediterranean & Gulf Cooperative Insurance & Reinsurance) |
| Others |
Pricing and Supply Chain Analysis
CCHI benefit minimums and SAMR capital adequacy protocols simultaneously gate carrier qualification and stratify premium positioning across employer-sponsored tiers. This regulatory architecture compresses margins for sub-scale takaful operators while rewarding network density with pricing power in corporate negotiations.
Pricing Analysis
CCHI dictates the pricing tier structure through mandatory benefit floors that establish baseline premium thresholds across all licensed carriers. Three-tier pricing separates comprehensive family takaful from standard group coverage from economy expatriate plans, with network breadth and claims adjudication speed as the primary differentiation drivers. Cost compression in economy tiers intensifies because SFDA pharmaceutical reimbursement lags provider pricing on high-cost therapeutics. Construction sector employers with high expatriate turnover exhibit the greatest price sensitivity, while petrochemical and banking employers in competitive labor pools absorb premium increases for faster claims resolution and broader specialist access.
Supply Chain Analysis
Strategic stockpiling of actuarial talent and hospital network contracts dominates inventory strategy over just-in-time capability acquisition. Primary reinsurance capacity draws from London and Singapore retrocession markets, with retention ratios climbing as catastrophe coverage faces capacity constraints. Medical management platforms, pharmaceutical formularies, and diagnostic imaging networks constitute critical input dependencies. Single-source vulnerability concentrates in specialized oncology and cardiovascular centers where King Faisal Specialist Hospital and Saudi Aramco-affiliated medical cities anchor tier-one network exclusivity. Distribution runs through direct employer relationships for corporate policies, while bancassurance channels activate family takaful upgrades among affluent Saudi households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story where CCHI licensing and hospital network density create switching costs that lock in employer sponsors. The structural moat deepens as SAMR capital requirements compress the carrier base and elevate operational barriers for challengers.
For Market Incumbents: Fortify network exclusivity through long-term contracts with King Faisal Specialist Hospital and Saudi Aramco-affiliated medical cities before digital-first challengers achieve comparable density. Deepen backward integration into claims adjudication technology to displace third-party administrator relationships and capture margin from automated pre-authorization workflows. The priority lever centers on proprietary AI-powered triage systems that cut decision latency from days to hours. For New Entrants and Emerging Players: Preventive screening bundling represents the most penetrable service layer where incumbents under-serve, particularly oncology and cardiovascular risk assessment packages aligned with MOH public health objectives. Qassim and Ha'il provinces offer geographic white space with coverage density below one-third of Riyadh levels and limited incumbent network investment. The go-to-market angle should leverage SFDA-approved telemedicine infrastructure to extend reach without proportional hospital capital expenditure. For Investors and Strategic Acquirers: SAMR capital adequacy enforcement reshapes the acquisition landscape by forcing consolidation among undercapitalized takaful operators and creating distressed asset opportunities. Long-term viability favors carriers with direct employer channel control and in-house claims automation capability over those dependent on third-party administrator relationships. The signal to watch is CCHI data interoperability mandate compliance cost burdens that favor acquisition of smaller clinic networks by integrated delivery systems.| Strategic Initiative | Industry Significance |
|---|---|
| Network Exclusivity Negotiation | Long-term contracts with King Faisal Specialist Hospital lock in tier-one positioning against competitors. |
| Claims Automation Investment | AI-powered triage systems displace third-party administrators and compress operational expense ratios. |
| Telemedicine Infrastructure Deployment | SFDA-approved remote diagnostic protocols enable network extension into secondary cities without legacy hospital capex. |
| Preventive Screening Bundling | Oncology and cardiovascular risk assessment packages align with MOH objectives and attract risk-adjusted premium incentives. |
| Bancassurance Channel Activation | SAMA-licensed retail banking networks offer captive distribution to affluent households seeking family takaful upgrades. |
Research Methodology
Cross-validation between primary interviews with underwriting executives, network contracting managers, and employer benefits administrators and secondary sources including CCHI regulatory filings, SAMR licensing databases, and hospital procurement records anchors the qualitative findings. Bottom-up policy volume estimates from carrier disclosures triangulate against top-down employer sponsorship models derived from Nitaqat program participation data.
Sensitivity analysis across premium growth assumptions, medical inflation scenarios, and reinsurance capacity constraints tests forecast robustness throughout the projection horizon. The analytical framework models segmentation across insurance type, plan design, end-user category, and service offering, with CAGRs derived from trend extrapolation adjusted for regulatory inflection points including CCHI data interoperability mandates and SAMR capital requirement phase-ins.
Underlying assumptions cover employer compliance rates with mandatory coverage rules, medical cost inflation differentials, and reinsurance market capacity availability, with deviation risk concentrated in regulatory enforcement intensity and pharmaceutical reimbursement protocol revisions. Revision becomes warranted when CCHI benefit minimum adjustments or SAMR solvency requirement changes cross implementation thresholds that alter carrier competitive dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Medical Professional Liability Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Small Business Insurance Market
Insurance
Global Fine Art Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
Commercial Cyber Insurance Market
Insurance
Japan Liability Insurance Market
Insurance
Auto Compulsory Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
Reinsurance Market
Insurance
US Homeowner's Insurance Market
Insurance
Dental Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Endowment Insurances Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Germany Health and Medical Insurance Market