
 United Kingdom Offshore Wind Energy Market | 2026-2036
United Kingdom Offshore Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Offshore Wind Energy Market Analytics
Modular turbine-generator packaging is decoupling hardware procurement from installation services, letting buyers split capex across multiple vendors. Ørsted leverages its pipeline dominance to control project development timelines. RWE anchors its position through backward integration into offshore construction management. Siemens Gamesa specializes in direct-drive turbine architecture for salt-heavy North Sea conditions.
United Kingdom offshore wind energy encompasses electricity generation from wind turbines sited in marine waters, typically using monopile or jacket foundations in depths under sixty meters and floating platforms beyond that threshold, with rotor diameters now exceeding two hundred meters to capture higher consistent wind speeds. The primary purpose is grid-scale clean power delivery to national transmission networks. Turbine generators command the largest share of capital deployment, while floating platforms represent the fastest-expanding installation category as deeper-water sites open off Scotland. Subsea cables concentrate margin pools due to specialized manufacturing and marine-lay complexity.
The Department for Business, Energy and Industrial Strategy shapes demand through Contracts for Difference auctions, while Ofgem regulates grid connection standards and revenue mechanisms. The Health and Safety Executive mandates offshore construction protocols that elevate equipment certification requirements. Stakeholders must monitor seabed leasing rounds and CfD strike-price trends to calibrate capital allocation timing.
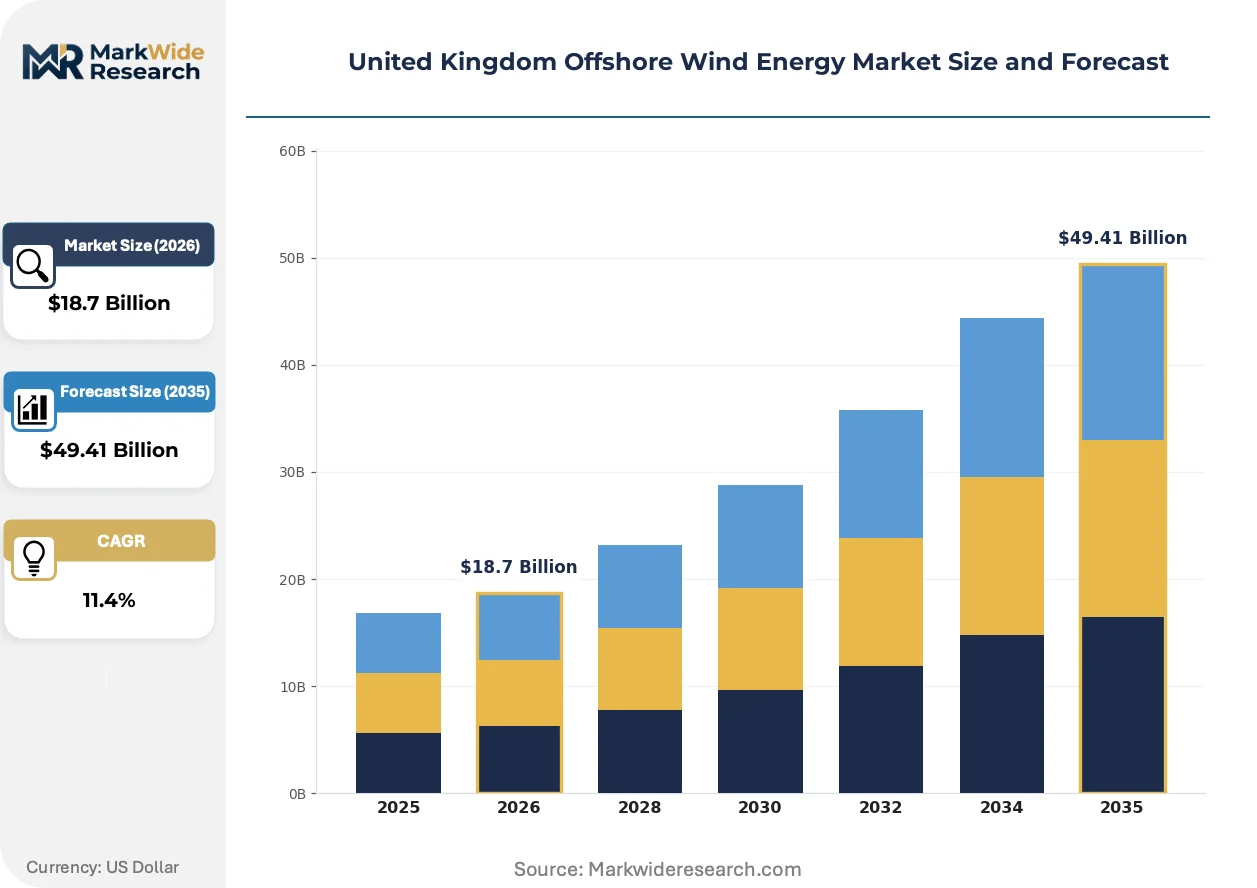
Market Dynamics
The Contracts for Difference scheme from the Department for Business, Energy and Industrial Strategy anchors project economics, while floating platform maturation unlocks deeper Scottish waters previously inaccessible to fixed-bottom installations.
Growth Catalysts
- Scotland's deeper-water leasing rounds:Crown Estate Scotland's seabed licensing opens sites beyond sixty-meter depths to floating turbine arrays, expanding addressable resource base.
- Contracts for Difference price floors:The Department for Business, Energy and Industrial Structure's auction mechanism de-risks long-term revenue streams for capital-intensive developments.
- East Anglia transmission clustering:Concentrated grid infrastructure in Norfolk and Suffolk waters reduces connection costs per megawatt for sequential project phases.
Market Restraints
- Steel and copper input volatility:Fluctuations in commodity markets directly pressure turbine tower and subsea cable manufacturing costs.
- Specialized vessel scarcity:Heavy-lift jack-up vessel availability concentrates among North Sea-based contractors, creating installation bottlenecks during weather windows.
- Grid connection queuing delays:Ofgem's connection application backlog extends project commissioning timelines beyond original development schedules.
Strategic Opportunities
- Celtic Sea floating deployment:Welsh and Cornish waters offer untapped capacity for next-generation semi-submersible platforms with higher capacity factors.
- Green hydrogen co-location:Electrolyzer integration at offshore substations creates offtake flexibility beyond grid-constrained periods.
- Power purchase agreement direct contracting:Corporate buyers are bypassing CfD auctions to secure renewable energy certificates from specific project phases.
Industry Challenges
- Marine electrical technician shortage:Specialized skills for high-voltage subsea cable termination and turbine maintenance outpace vocational training pipeline output.
- Health and Safety Executive certification timelines:Extended equipment approval processes for novel floating foundation designs delay construction mobilization.
- Multi-vendor system integration complexity:Split procurement of turbines, foundations, and cables creates interface risk during offshore commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Offshore Wind Energy Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbine Generators, Floating Platforms, Subsea Cables, Control Systems Installation Type: Fixed Offshore, Floating Offshore, Hybrid Platforms, Repowering End User: Utility Providers, Independent Power Producers, Offshore Developers, Government Agencies Technology: Direct Drive, Gear Driven, Hybrid Systems, Energy Storage |
| Companies Covered | RWE, Ørsted, Scottish Power UK, SSE, Siemens Gamesa, EDF, GE Renewable Energy, MHI Vestas, Innogy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Offshore Wind Energy Market Evolving Landscape
Modular component standardization is compressing project development cycles while digital twin deployment is reshaping operational maintenance models across the United Kingdom fleet.
Direct-drive generator architecture is unifying turbine drivetrain design by eliminating gearbox maintenance points. Developers in Scottish waters favor these configurations for reduced service vessel visits. This unification is compressing operational expenditure forecasts and extending asset life assumptions in financial models.
The Health and Safety Executive's updated offshore construction protocols are mandating enhanced emergency response capabilities and real-time personnel tracking. Project developers must now integrate dedicated rescue coordination centers into construction management plans. Floating platform deployments in deeper waters face the steepest compliance cost adjustments under these requirements.
Utility offtakers are unbundling turbine supply contracts from installation and operations agreements, fragmenting vendor relationships across project lifecycles. This disaggregation shifts performance risk allocation and complicates warranty claim resolution. The East Anglia cluster exhibits the most advanced contract segmentation, with separate parties handling foundation fabrication, turbine delivery, and marine logistics.
United Kingdom Offshore Wind Energy Market Segmentation
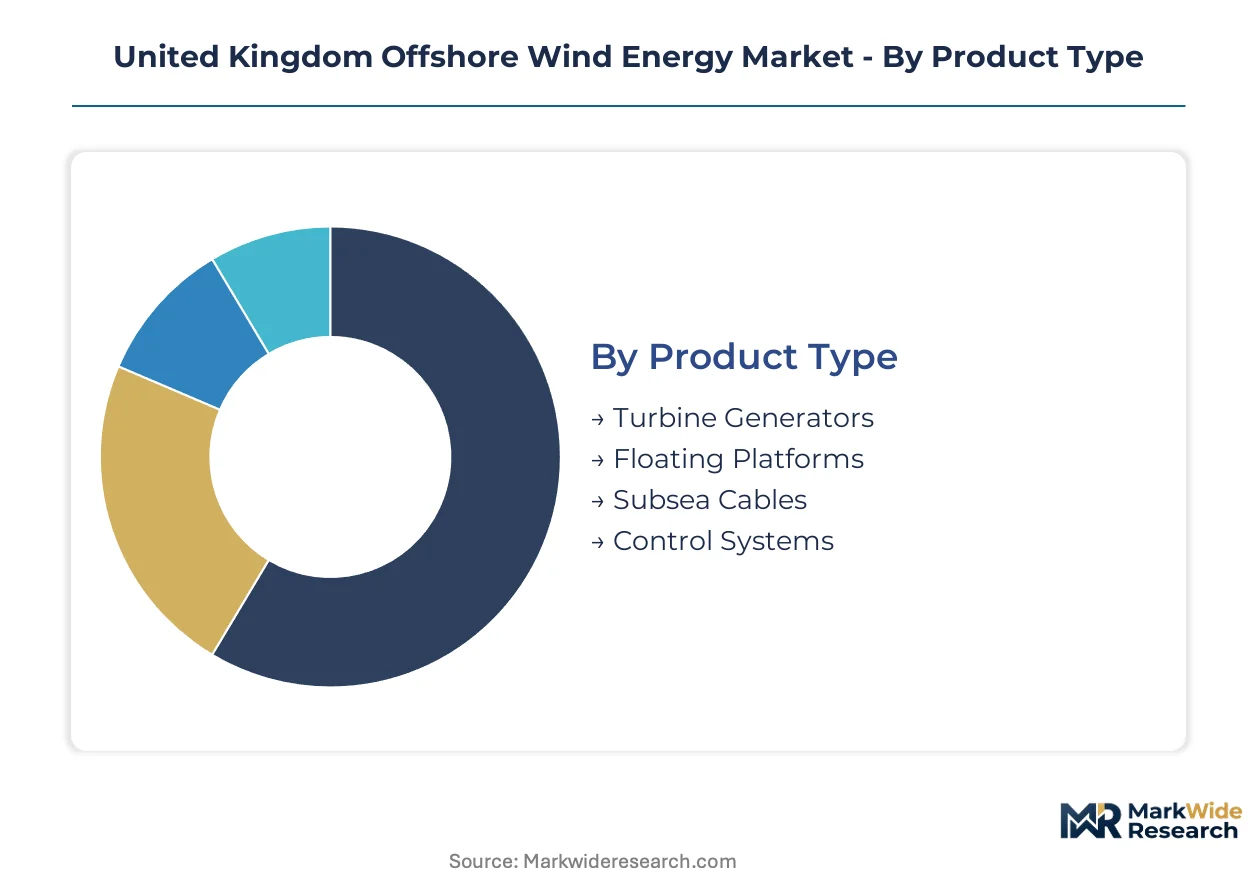
Segmentation in United Kingdom offshore wind energy reveals how capital flows across hardware, installation methods, and buyer types. Equipment choices and contracting structures directly shape project returns and operational risk profiles across Scottish waters and the East Anglia cluster.
Product Type:
Replacement cycles and technology upgrades are fragmenting procurement patterns across the hardware stack, with newer assets displacing earlier-generation equipment.
- Turbine Generators:Direct-drive and geared architectures now exceed two-hundred-meter rotor diameters for North Sea wind capture. Scottish and East Anglian developers concentrate orders here, driven by CfD auction deadlines that reward higher capacity factors.
- Floating Platforms:Semi-submersible and tension-leg designs enable deployment beyond sixty-meter depths previously inaccessible. Crown Estate Scotland's deeper-water leasing rounds concentrate demand in this segment, though Health and Safety Executive certification timelines extend construction mobilization.
- Subsea Cables:High-voltage direct-current and alternating-current export cables link offshore substations to onshore grids.
- Control Systems:Condition monitoring and pitch regulation electronics manage turbine performance across variable marine environments.
Turbine generators sit at the top of the volume ranking, with floating platforms climbing the fastest.
Installation Type:
Cost tier differentiation separates capital-light retrofit approaches from greenfield developments requiring full marine construction spreads.
- Fixed Offshore:Monopile and jacket foundations dominate shallower sites under sixty meters through established heavy-lift vessel deployment. East Anglia's sequential project phases concentrate here, exploiting clustered transmission infrastructure in Norfolk and Suffolk waters.
- Floating Offshore:Mooring systems and dynamic cables enable turbine placement in deeper Scottish waters without seabed-fixed structures. Crown Estate Scotland licensing unlocks this tier, though specialized vessel scarcity creates installation bottlenecks during weather windows.
- Hybrid Platforms:Combined fixed-floating designs adapt to transitional seabed gradients.
- Repowering:Blade and drivetrain upgrades extend operational life at existing sites without full foundation replacement.
Fixed offshore retains the largest installed base, while floating offshore gains share fastest.
End User:
Customer type determines contracting sophistication and risk tolerance across the project lifecycle.
- Utility Providers:Vertically integrated national and regional electricity suppliers dominate CfD auction participation. ScottishPower and SSE anchor procurement volumes, leveraging balance-sheet capacity to absorb construction risk and long-term power price exposure.
- Independent Power Producers:Specialized renewable developers without regulated utility status pursue project-specific financing. These firms concentrate in floating platform segments where technology differentiation attracts private equity and infrastructure fund capital.
- Offshore Developers:Pure-play marine wind project originators hold seabed leases and development rights.
- Government Agencies:Crown Estate Scotland and the Crown Estate manage seabed leasing and revenue collection.
Utility providers command the deepest procurement volumes, with independent power producers expanding most quickly.
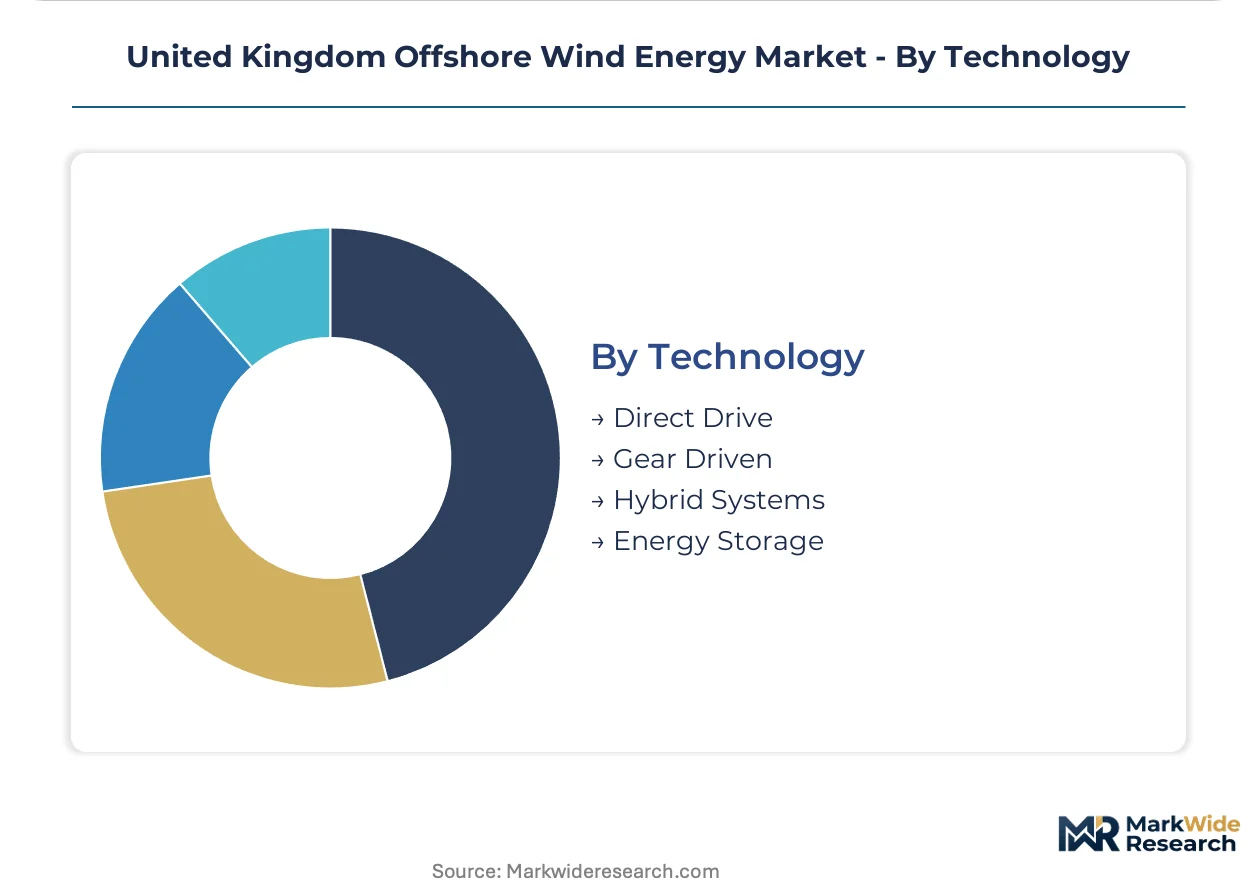
Technology:
Margin concentration follows manufacturing complexity and service intensity across drivetrain architectures.
- Direct Drive:Permanent-magnet generators eliminate gearbox components, reducing maintenance vessel visits in harsh North Sea conditions. Ørsted and RWE favor these configurations for Scottish floating arrays where service access is constrained.
- Gear Driven:High-speed generator designs with multi-stage gearboxes dominate earlier installed capacity. East Anglia's operational fleet retains substantial exposure here, with repowering decisions pending on gearbox replacement economics.
- Hybrid Systems:Medium-speed drivetrains combine gearbox stages with direct-drive elements.
- Energy Storage:Battery and hydrogen co-location systems manage intermittency and grid constraint periods.
Direct drive leads current procurement volumes, with energy storage showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom offshore wind sector traces its industrial lineage to Denmark's pioneering Horns Rev project, whose technical frameworks migrated across the North Sea to anchor British capacity build-out during the 2000s.
Scotland
Crown Estate Scotland's seabed licensing rounds unlock deeper-water sites beyond sixty meters for floating platform deployment. The Scottish Government's offshore wind policy statement mandates gigawatt-scale floating arrays by 2030. Aberdeen and the Cromarty Firth concentrate fabrication and marshalling infrastructure for these gravity-base and semi-submersible foundations.
East Anglia
Sequential project phases across Norfolk and Suffolk waters exploit clustered transmission infrastructure to compress connection costs per megawatt. National Grid's offshore coordination project streamlines grid access for multiple developments. Great Yarmouth and Lowestoft anchor marine logistics and operations bases serving this concentrated development corridor.
Wales
The Celtic Sea leasing round opens Welsh waters to floating platform pilots with higher capacity factors than southern North Sea sites. The Welsh Government's marine energy strategy targets specific gigawatt milestones for floating wind. Holyhead and Milford Haven concentrate port infrastructure upgrades for floating component assembly.
North East England
Monopile fabrication demand from Dogger Bank and Hornsea developments sustains heavy manufacturing employment. The Offshore Wind Growth Partnership channels BEIS funding into supply chain capability building. Teesside and the Port of Blyth anchor jacket foundation production and turbine component staging.
South East England
Interconnector landing points and grid reinforcement projects concentrate infrastructure investment across Kent and Sussex coastal zones. Ofgem's connection queue reforms aim to accelerate commissioning timelines for projects in this constrained transmission area. Rampion and future extensions demonstrate fixed-bottom viability in shallower Channel waters.
United Kingdom Offshore Wind Energy Market Competitive Landscape
The competitive structure tilts toward integrated developers with balance-sheet capacity to absorb construction risk across multi-gigawatt pipelines. Market concentration remains elevated among utility-backed entities that control seabed leasing positions and CfD auction participation. Three archetypes dominate: vertically integrated European utilities, turbine OEMs with service arms, and specialist offshore construction managers. Consolidation pressure intensifies through portfolio acquisitions and joint venture formation to spread capital deployment.
Among utility-backed developers, Ørsted anchors the integrated developer archetype through its pipeline dominance and in-house construction management capabilities. RWE occupies a parallel position representing German utility-backed expansion into British waters. Siemens Gamesa exemplifies the equipment-supplier archetype with direct-drive turbine specialization for North Sea salt exposure. These three entities collectively illustrate how market position derives from control over development timelines, manufacturing scale, or installation execution rather than any single capability.
| Leading Market Players |
|---|
| RWE |
| Ørsted |
| Scottish Power UK |
| SSE |
| Siemens Gamesa |
| EDF |
| GE Renewable Energy |
| MHI Vestas |
| Innogy |
| Others |
Value Network & Pricing Analysis
Marine electrical technician scarcity in Scottish waters and the Cromarty Firth widens labor-cost spreads between premium-tier installation contracts and economy-tier maintenance agreements. This workforce concentration shapes pricing-tier differentiation across floating platform deployments versus fixed-bottom retrofits.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs turbine supply and installation contracts in United Kingdom waters. Premium tiers attach to direct-drive generator configurations with extended warranty coverage, while economy tiers cover geared-architecture repowering without foundation replacement. Price erosion runs through standard-tier fixed-bottom projects as heavy-lift jack-up vessel scarcity compresses installation margins. Utility providers anchored by ScottishPower and SSE exhibit lowest price sensitivity due to balance-sheet absorption of construction risk, whereas independent power producers in floating segments negotiate hardest on capital equipment.
Supply Chain Analysis
Component refurbishment and turbine blade remanufacturing flows concentrate at Aberdeen and Great Yarmouth marshalling yards, extending asset life without full replacement procurement. Subsea cable manufacturing draws from Norway, Denmark, and Germany, with high-voltage direct-current systems resting on rare-earth magnet supply from Chinese processing facilities. Single-source vulnerability sits with specialized heavy-lift jack-up vessel operators based in the North Sea basin. Distribution runs through Crown Estate Scotland leasing rounds and CfD auction allocations that gate project development sequencing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United Kingdom offshore wind functions as a geographic-arbitrage play between Scottish deep-water floating premiums and East Anglia's transmission-clustered cost efficiencies. Regulatory divergence between Crown Estate Scotland's accelerated leasing timelines and Ofgem's connection queue bottlenecks creates deployable spreads.
For Market Incumbents: Anchor pipeline dominance through captive control of seabed leasing positions ahead of Crown Estate Scotland's deeper-water rounds. Absorb construction risk across multi-gigawatt portfolios to deter independent power producers from scaling floating platform expertise. Threat substitution from electrolyzer co-location at offshore substations demands backward integration into green hydrogen offtake contracting. Certification investment with the Health and Safety Executive for novel floating foundation designs preserves construction mobilization timelines against regulatory delay. For New Entrants and Emerging Players: Digital platform-based vessel-sharing marketplaces offer lowest-friction entry into marine logistics coordination without heavy-asset ownership. White-space concentrates in Welsh Celtic Sea floating pilots where Crown Estate licensing remains under-allocated versus Scottish competition. Target corporate power purchase agreement direct contracting as CfD auction bypass channels for renewable energy certificate offtake. Go-to-market angle rests on technology differentiation in semi-submersible platform design attracting infrastructure fund capital. For Investors and Strategic Acquirers: European utility-backed developers are the most active acquirers in this space, consolidating seabed lease portfolios through joint venture formation. Long-term viability across the five-to-ten-year window hinges on floating platform cost curves intersecting fixed-bottom economics in sixty-meter-plus depths. Acquisition target archetype: specialist offshore construction managers with Health and Safety Executive certification track records and jack-up vessel access agreements. Signal to watch: CfD strike-price trajectories in Scottish waters versus East Anglia clustering as indicator of capital allocation efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Seabed Lease Portfolio Consolidation | Crown Estate Scotland licensing concentration accelerates development timelines for floating arrays. |
| Direct-Drive Generator Scale-Up | Siemens Gamesa and MHI Vestas manufacturing expansion reduces service vessel visits in North Sea conditions. |
| Green Hydrogen Co-Location | Electrolyzer integration at offshore substations creates offtake flexibility beyond grid-constrained periods. |
| Corporate PPA Direct Contracting | Bypass of CfD auctions secures renewable energy certificate premiums from specific project phases. |
| Marine Logistics Platform Integration | Digital vessel-sharing marketplaces fragment heavy-lift jack-up scarcity bottlenecks across weather windows. |
Research Methodology
Multiple input streams — utility planning officer interviews, EPC contractor project databases, Crown Estate Scotland leasing records, and Ofgem connection queue filings — were reconciled to construct demand and supply estimates. Primary fieldwork captured perspectives from IPP project developers, grid operators, and marine electrical technician training providers. Secondary validation drew from BEIS Contracts for Difference auction results, Health and Safety Executive certification timelines, and subsea cable manufacturing trade data. Bottom-up project-level capacity aggregation was cross-checked against top-down national renewable energy target trajectories.
Data-stream reconciliation across the analysis window applied segmentation dimensions spanning installation type, technology architecture, water depth tier, and end-user contracting structure. CAGRs were derived from project pipeline maturation curves and CfD strike-price elasticity assumptions. Forecast inputs incorporated floating platform cost learning rates and specialized vessel day-rate volatility.
The model assumes a particular technology adoption path; alternative pathways for tension-leg versus semi-submersible floating foundations would alter the outlook for Scottish deployment economics. Forecasts reflect assumptions on Health and Safety Executive certification timeline compression and Crown Estate Scotland leasing round frequency. Practitioners should monitor CfD auction participation rates and jack-up vessel orderbook depth for early signals of supply constraint intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
Small Wind Turbine Market
Wind Energy Systems
Wind Power Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Wind Turbine Shaft Market
Wind Energy Systems
Global Small Wind Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Asia-Pacific Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
Wind Energy Market