
 Zero Emission Vehicle Market | 2026-2036
Zero Emission Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Zero Emission Vehicle Market Analysis
Extended range specifications above four hundred miles per charge is reorganizing buyer expectations across premium and mass-market tiers. Tesla leverages its proprietary Supercharger network to sustain geographic lock-in across North American corridors. BYD Company Limited anchors vertical integration through in-house battery cell production and semiconductor fabrication. Volkswagen Group differentiates via modular electric drive matrix platforms that scale across multiple brand portfolios.
Zero emission vehicles rely on electric drivetrains that eliminate tailpipe emissions through battery-electric or hydrogen fuel cell propulsion, with lithium-ion battery packs typically ranging from forty to one hundred twenty kilowatt-hours in passenger configurations. The primary commercial purpose centers on decarbonizing transportation while reducing lifetime operating costs versus internal combustion equivalents. Battery Electric Vehicles lead absolute volume across all geographies due to falling cell costs and expanding fast charging station networks. Solid-state battery technology represents the fastest-growing battery technology segment as manufacturers pursue higher energy density and reduced thermal management overhead. Hydrogen Fuel Cell Vehicles occupy narrow but defensible margin pools in heavy-duty trucking and long-haul logistics where battery weight penalties constrain payload capacity.
The EPA tailpipe standards and IRA clean vehicle tax credits in the United States shape demand through purchase incentives and manufacturing localization requirements. The EU Green Deal and F-Gas Regulation in Europe mandate fleet-average CO2 reductions while restricting fluorinated greenhouse gases in vehicle climate systems. China's MIIT dual carbon goals enforce new energy vehicle production quotas that manufacturers must satisfy or purchase credits to offset. Stakeholders must monitor regulatory fragmentation across these three jurisdictions as divergent certification timelines and subsidy phase-outs will determine competitive positioning and capital allocation priorities.
Market Dynamics
The transition to solid-state battery chemistry is compressing product development cycles and forcing incumbent manufacturers to accelerate R&D expenditure or risk obsolescence in premium passenger segments.
Growth Catalysts
- IRA clean vehicle tax credits:The United States manufacturing localization requirements are pulling battery cell production onshore and reshaping supplier geography across the Midwest and Southeast industrial corridors.
- Municipal transit fleet electrification:City procurement mandates in Germany, France, and the Netherlands are generating guaranteed offtake volumes for electric bus and commercial van manufacturers.
- Silicon-anode battery materials:Higher energy density configurations are extending range specifications above four hundred miles, eliminating range anxiety as a purchase barrier in premium and mass-market tiers simultaneously.
Market Restraints
- Lithium carbonate price volatility:Concentrated South American and Australian mining output creates input cost instability that compresses cell manufacturer margins during supply disruptions.
- Fast charging infrastructure gaps:Rural corridor coverage remains sparse outside China's State Grid network and Tesla's proprietary Supercharger system, constraining long-haul adoption.
- EU F-Gas Regulation compliance:Restrictions on fluorinated greenhouse gases in vehicle climate systems require costly refrigerant system redesigns for models targeting European type approval.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for advanced chemistry cell manufacturing offer first-mover advantages for suppliers establishing local gigafactory capacity.
- Hydrogen fuel cell heavy-duty trucking:Long-haul logistics applications where battery weight penalties constrain payload capacity represent defensible margin pools with limited competition.
- Battery-as-a-service business models:Subscription-based ownership structures separate battery capital cost from vehicle purchase price, unlocking price-sensitive buyer segments.
Industry Challenges
- Electrochemical engineering talent scarcity:Shortages of solid-state electrolyte specialists and thermal management systems engineers delay product validation timelines.
- Multi-jurisdiction certification complexity:Divergent EPA, EU Green Deal, and MIIT testing protocols force redundant validation cycles that extend time-to-market.
- Legacy dealership network reconfiguration:Reduced maintenance requirements disrupt established service revenue models and require retraining of technical staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero Emission Vehicle Market |
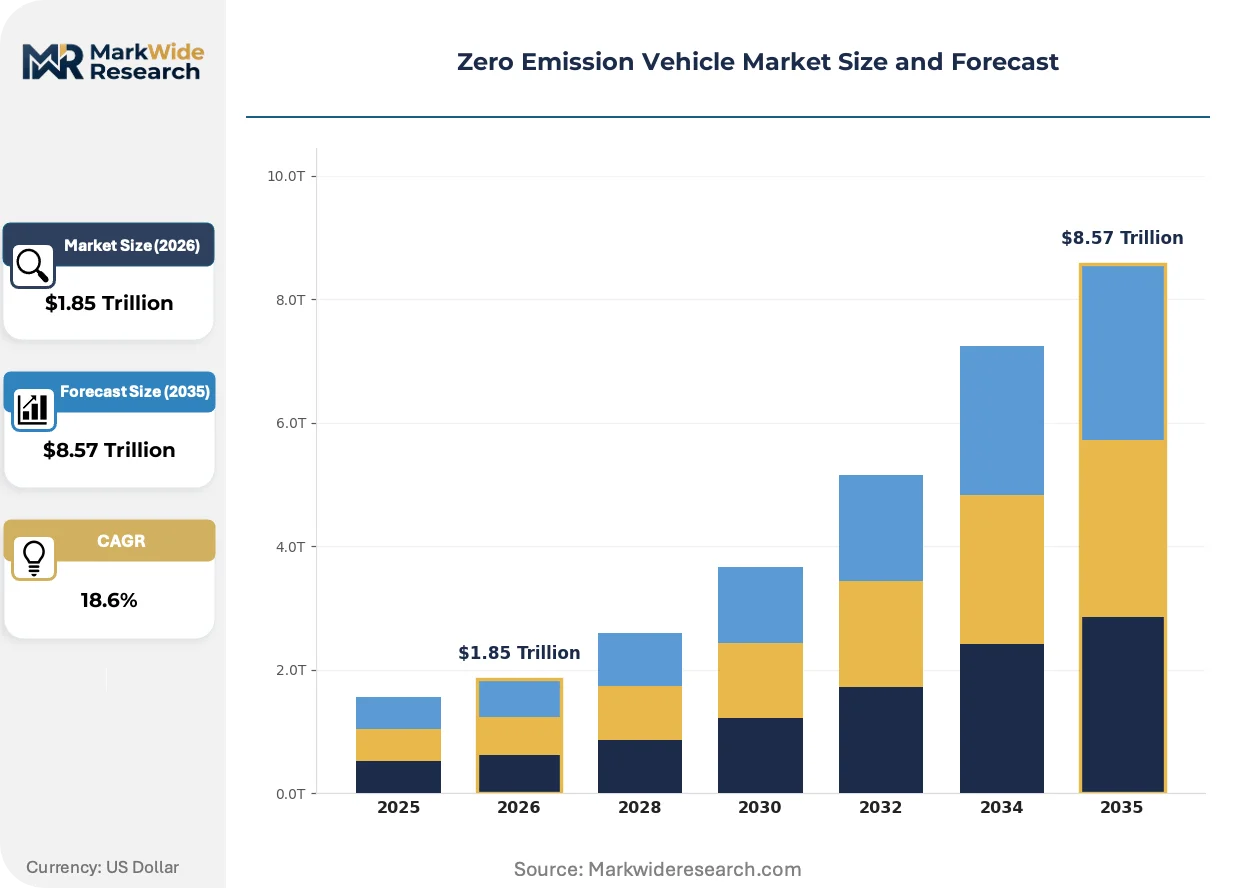
| Market Size in 2026 | $1.85 Trillion |
| Market Size in 2035 | $8.57 Trillion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Vehicles, Hydrogen Fuel Cell Vehicles, Plug-in Hybrid Electric Vehicles, Extended Range Electric Vehicles Battery Technology: Lithium-ion, Solid-State, Nickel-Metal Hydride, Flow Batteries Charging Infrastructure: Fast Charging Stations, Home Charging Solutions, Public Charging Networks, Wireless Charging Sales Channel: Online Sales, Dealerships, Direct-to-Consumer, Fleet Sales |
| Companies Covered | Tesla, BYD Company Limited, Volkswagen Group, General Motors, Toyota Motor Corporation, BMW Group, Hyundai Motor Company, Ford Motor Company, Stellantis NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero Emission Vehicle Market Emerging Trajectories
Solid-state battery commercialization is splitting the competitive landscape between early adopters pursuing premium positioning and cost-optimized incumbents defending lithium-ion scale advantages.
Solid-state battery technology replaces flammable liquid electrolytes with ceramic or glass-ceramic conductors, enabling higher energy density and reduced thermal management overhead. Luxury passenger vehicle manufacturers in Germany and South Korea are prioritizing this chemistry for flagship launches, accepting near-term cost premiums. The technology is bifurcating the supplier base into dedicated solid-state specialists and diversified lithium-ion incumbents with divergent capital allocation priorities.
The EU Green Deal vehicle mandates enforce fleet-average CO2 reductions that tighten annually through 2035, eliminating internal combustion engine sales. German and French automotive groups are accelerating platform consolidation to spread compliance costs across volume brands. Heavy-duty commercial vehicle segments face the steepest trajectory adjustments, driving joint venture formation between established truck manufacturers and battery cell suppliers.
Fleet procurement departments are consolidating supplier relationships and demanding guaranteed residual value structures for battery assets. Large logistics operators in the United States and Germany are bypassing traditional dealer networks for direct manufacturer negotiations. This concentration is visible most acutely in last-mile delivery segments where Amazon, DHL, and postal services negotiate multi-thousand unit contracts with standardized specifications.
Zero Emission Vehicle Market Segmentation
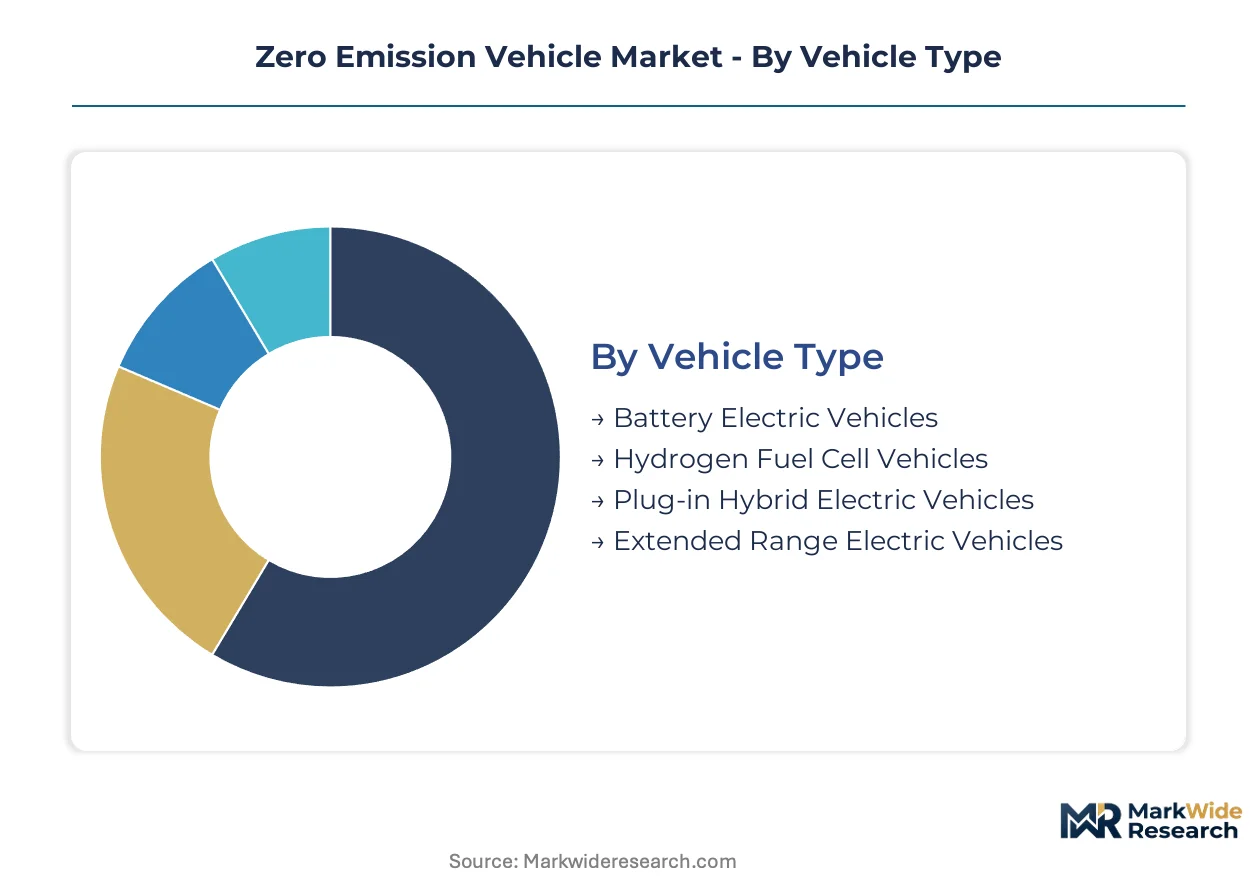
Segmentation in the Zero Emission Vehicle Market reveals how technology maturity, infrastructure availability, and procurement channels create divergent growth trajectories across passenger and commercial applications. Understanding these divides helps stakeholders allocate capital between proven volume segments and emerging niches with higher margin potential.
Vehicle Type:
Battery Electric Vehicles dominate domestic demand in China, the United States, and Germany, while Hydrogen Fuel Cell Vehicles concentrate in export-led heavy-duty corridors across Japan and South Korea.
- Battery Electric Vehicles:These configurations rely on lithium-ion battery packs ranging from forty to one hundred twenty kilowatt-hours, eliminating tailpipe emissions entirely through electric drivetrain propulsion. Demand concentrates in municipal transit fleets across Germany, France, and the Netherlands where procurement mandates guarantee offtake volumes. Falling cell costs and expanding fast charging networks compress total cost of ownership below internal combustion equivalents in premium and mass-market tiers simultaneously.
- Hydrogen Fuel Cell Vehicles:Proton exchange membrane stacks convert hydrogen into electricity, offering refueling parity with diesel in under ten minutes for commercial applications. Export-led demand centers on long-haul trucking routes in California and the Rhine-Alpine corridor where battery weight penalties constrain payload capacity. Limited hydrogen station density outside Japan and South Korea restricts passenger adoption despite superior energy density for heavy-duty cycles.
- Plug-in Hybrid Electric Vehicles:Dual powertrain architectures combine internal combustion range extension with electric-only urban operation, appealing to buyers in charging infrastructure gaps.
- Extended Range Electric Vehicles:Series-hybrid configurations use gasoline generators solely for battery replenishment, maintaining electric drivetrain simplicity while addressing range anxiety in rural United States markets.
Battery Electric Vehicles hold the largest share; momentum sits with Hydrogen Fuel Cell Vehicles in defensible commercial niches.
Battery Technology:
Cost tier stratification separates premium solid-state development from commoditized lithium-ion scale manufacturing.
- Lithium-ion:Layered oxide cathodes paired with graphite anodes deliver proven cycle life and manufacturing scalability across cylindrical, prismatic, and pouch form factors. Volume concentration in China, the United States, and Germany supports passenger vehicle cost parity with internal combustion engines. Cell manufacturers in the Midwest and Southeast industrial corridors expand capacity to satisfy IRA clean vehicle tax credit localization requirements.
- Solid-State:Ceramic or glass-ceramic electrolytes replace flammable liquid conductors, enabling higher energy density and reduced thermal management overhead. Premium positioning in German and South Korean luxury flagships accepts near-term cost premiums for safety and performance differentiation. Electrochemical engineering talent scarcity delays product validation timelines for mass-market deployment.
- Nickel-Metal Hydride:Mature chemistry persists in hybrid-electric auxiliary power applications where energy density requirements remain modest.
- Flow Batteries:Vanadium redox configurations suit stationary grid storage and commercial vehicle depot charging rather than onboard automotive propulsion.
Lithium-ion dominates absolute volume; solid-state chemistry climbs the fastest toward premium segment penetration.
Charging Infrastructure:
Customer type bifurcation separates fleet operators demanding guaranteed uptime from residential buyers prioritizing convenience.
- Fast Charging Stations:Direct current systems delivering one hundred fifty to three hundred fifty kilowatts replenish battery packs to eighty percent capacity in twenty to forty minutes. Fleet procurement departments in the United States and Germany negotiate direct manufacturer relationships for multi-thousand unit contracts with standardized specifications. Rural corridor coverage gaps outside China's State Grid network and Tesla's proprietary Supercharger system constrain long-haul adoption.
- Home Charging Solutions:Alternating current Level two units operating at two hundred forty volts provide overnight replenishment for single-family residential installations. Mass-market tier buyers in suburban United States and German markets treat home installation as a purchase prerequisite. Apartment and urban multi-unit dwelling access limitations exclude significant buyer segments from this channel.
- Public Charging Networks:Mixed-speed installations in retail and municipal parking structures serve urban dwellers without dedicated residential access.
- Wireless Charging:Inductive pad systems eliminate connector wear but suffer efficiency losses and standardization fragmentation across hardware suppliers.
Home Charging Solutions capture the largest installed base; Fast Charging Stations gain share fastest through fleet electrification mandates.
Sales Channel:
Supply concentration in direct manufacturer relationships is displacing legacy dealership networks for volume fleet transactions.
- Fleet Sales:Direct negotiation between manufacturers and logistics operators bypasses traditional dealer markups for standardized specifications in thousand-unit quantities. Amazon, DHL, and postal services across the United States and Germany consolidate supplier relationships and demand guaranteed residual value structures for battery assets. Municipal transit electrification in Germany, France, and the Netherlands generates guaranteed offtake volumes for electric bus and commercial van manufacturers.
- Direct-to-Consumer:Manufacturer-owned showrooms and digital configurators control pricing and customer experience in premium segments. Tesla's proprietary Supercharger network sustains geographic lock-in across North American corridors through integrated ownership experience. Legacy dealership network reconfiguration disrupts established service revenue models requiring technical staff retraining.
- Dealerships:Franchise networks retain relevance in mass-market tiers where local service infrastructure and trade-in handling remain valued.
- Online Sales:Digital-only transactions with home delivery expand in markets with mature consumer protection frameworks and return policies.
Fleet Sales command the steepest expansion trajectory; Direct-to-Consumer holds margin concentration in premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major automotive economies. China maintains substantial manufacturing surplus in battery electric vehicle exports. Germany and the United States absorb significant import volumes while scaling domestic cell production.
China
MIIT dual carbon goals enforce new energy vehicle production quotas that manufacturers must satisfy or purchase credits to offset. The Yangtze River Delta cluster around Shanghai anchors BYD and Tesla Gigafactory Shanghai output for domestic consumption and export markets. State Grid Corporation deploys fast charging corridors along highway networks at densities unmatched elsewhere.
United States
IRA clean vehicle tax credits pull battery cell production onshore across Midwest and Southeast industrial corridors. EPA tailpipe standards compress internal combustion timelines while manufacturing localization requirements reshape supplier geography. Michigan and Tennessee industrial clusters host expanding gigafactory construction for regional supply security.
Germany
KBA type approval protocols and EU Green Deal fleet-average CO2 mandates drive platform consolidation across Volkswagen Group and BMW portfolios. Bavaria and Baden-Württemberg concentrate engineering talent for solid-state battery development. Municipal transit procurement mandates in Berlin and Munich generate guaranteed offtake volumes for electric bus manufacturers.
South Korea
METI-aligned industrial policy supports hydrogen fuel cell commercialization through Hyundai Motor Company heavy-duty trucking programs. The Busan-Ulsan corridor concentrates fuel cell stack manufacturing and hydrogen station deployment. MFDS regulatory alignment with EU standards facilitates export market access for premium passenger configurations.
India
PLI scheme for automotive offers production-linked incentives for advanced chemistry cell manufacturing with first-mover advantages for local gigafactory establishment. Gujarat and Tamil Nadu industrial corridors attract supplier investments to serve domestic demand and regional export markets. BIS certification requirements and DGFT import tariffs protect nascent domestic manufacturing capacity.
Zero Emission Vehicle Market Vendor Landscape
Listed leaders compete with private specialists across capital access and technology development timelines. Market structure shows moderate consolidation with tiered differentiation between scale manufacturers and premium positioning specialists. Three archetypes dominate: vertically integrated battery producers, platform-scale automakers, and hydrogen fuel cell specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure cell supply and charging network access.
Within the platform-scale tier, Tesla and BYD Company Limited exemplify divergent geographic strategies. Tesla sustains geographic lock-in through proprietary Supercharger network integration across North American corridors. BYD Company Limited anchors vertical integration through in-house battery cell production and semiconductor fabrication capabilities. Volkswagen Group occupies a position bridging European engineering heritage with modular electric drive matrix platform scaling across multiple brand portfolios.
| Leading Market Players |
|---|
| Tesla |
| BYD Company Limited |
| Volkswagen Group |
| General Motors |
| Toyota Motor Corporation |
| BMW Group |
| Hyundai Motor Company |
| Ford Motor Company |
| Stellantis NV |
| Others |
Supply Flow & Price Mechanics
Silicon-anode battery materials replacing conventional graphite anodes are redrawing supplier geography toward Australian and Canadian mining corridors while compressing cell manufacturer margins through higher purity processing requirements. This substitution dynamic concentrates pricing power with cathode-active-material producers in China and South Korea as tiered sourcing strategies fragment procurement economics across premium and mass-market vehicle tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume commitments across multi-year horizons. Price differentiation stems from certification grade under EPA tailpipe standards and EU Green Deal compliance tiers alongside volume scale commitments above ten-thousand-unit annual thresholds. Cost compression in lithium carbonate feedstocks is intensifying because South American supply disruptions force spot-market exposure. Fleet procurement departments demonstrate lowest price sensitivity due to guaranteed residual value structures, while individual retail buyers in mass-market tiers exhibit highest elasticity to upfront capital costs.
Supply Chain Analysis
Container availability constraints across Pacific trade lanes from Shanghai to Long Beach are forcing inventory buffer expansion at Midwest gigafactory locations. Geographic supply concentration centers on China, South Korea, and Japan for cathode active materials, with Australia and Chile anchoring lithium spodumene extraction. Raw material dependencies rest on cobalt hydroxide, nickel sulfate, and lithium carbonate as primary feedstocks. Single-source vulnerability in solid-state electrolyte ceramic precursor supply threatens premium segment production schedules. Distribution runs through captive OEM logistics networks for cell delivery to final assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against hydrogen fuel cell incumbents capturing defensible margin pools in heavy-duty logistics corridors where battery weight penalties constrain payload economics.
For Market Incumbents: Secure captive lithium carbonate offtake from Australian hard-rock mines to insulate against South American brine supply disruptions. Accelerate solid-state electrolyte R&D expenditure to maintain technology leadership against Korean battery specialists. Prioritize backward integration into semiconductor fabrication for power electronics to reduce dependence on Taiwanese foundry capacity. For New Entrants and Emerging Players: EU F-Gas Regulation compliance fast-tracks offer entry pathways for climate-system specialists capable of refrigerant redesigns for European type approval. Target municipal transit electrification corridors in Germany, France, and the Netherlands where procurement mandates guarantee offtake volumes. Pursue battery-as-a-service subscription models to unlock price-sensitive buyer segments without competing on upfront vehicle capital. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated cell manufacturers with in-house cathode production and regional gigafactory footprints satisfying IRA localization requirements. Long-term viability favors suppliers with demonstrated solid-state chemistry validation timelines and established OEM qualification relationships. Watch hydrogen station deployment density along California freight corridors as inflection indicator for fuel cell commercial viability.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in lithium-ion cell capacity from CATL or LG Energy Solution for platform-scale production. |
| Charging Infrastructure Partnership | Expands fast charging coverage along rural corridors through Tesla Supercharger network access. |
| Platform Standardization | Spreads compliance costs across Volkswagen Group volume brands via modular electric drive matrix. |
| Geographic Manufacturing Footprint | Satisfies IRA clean vehicle tax credit localization requirements through Midwest gigafactory construction. |
| Software-Defined Vehicle Investment | Enables over-the-air revenue streams and reduces legacy dealership service dependency. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, MIIT production quota disclosures, EU Green Deal implementation texts, and IHS Markit vehicle registration databases. Primary interviews engaged OEM platform engineers, Tier 1 supplier procurement directors, municipal fleet managers, and solid-state battery R&D leads. Secondary validation drew from SEC 10-K supply chain disclosures, customs import records, and charging infrastructure deployment databases. Bottom-up cell demand modeling and top-down fleet electrification policy analysis were triangulated against manufacturer production announcements.
Segmentation dimensions modeled span vehicle type, battery technology chemistry, charging infrastructure category, and sales channel archetype across the projection horizon. CAGRs were derived from regression analysis against policy incentive trajectories and cell cost learning curves. Industry-specific forecast inputs include IRA tax credit phase-out schedules, EU fleet-average CO2 mandate tightening trajectories, and MIIT dual carbon goal enforcement intensity.
Underlying assumptions cover sustained lithium carbonate price normalization, stable trade policy environments, and incremental solid-state battery yield improvements, with deviation risk concentrated in electrochemical engineering talent scarcity and multi-jurisdiction certification timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Automotive Alternative Fuel Vehicle Market
Alternative Fuel Vehicles
North America Hydrogen Powered Tractor Market