
 India CNG Vehicles Market | 2026-2036
India CNG Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
India CNG Vehicles Market Foresight
Commercial fleet procurement is expanding faster than private retail sales in India's CNG vehicle landscape. Maruti Suzuki dominates passenger car conversions with factory-fitted CNG options across its hatchback and compact sedan range. Tata Motors anchors the bus and light commercial vehicle segment through dedicated CNG platforms for urban transport corporations. Hyundai competes in the premium bi-fuel space with turbocharged CNG powertrains that target fleet operators seeking lower total cost of ownership.
India CNG vehicles are factory-built or retrofitted automobiles engineered to operate on compressed natural gas stored in Type 1 or Type 2 composite cylinders at pressures of 200-250 bar, with bi-fuel systems incorporating electronic control units that switch between petrol and CNG injection. The primary purpose is to reduce particulate emissions and fuel expenditure in high-mileage applications. Passenger cars represent the mature volume base where Maruti Suzuki's factory-fitted dominance creates thin margins for aftermarket retrofitters. Bi-fuel systems capture the fastest growth trajectory as fleet operators demand operational flexibility where CNG infrastructure remains patchy. Three-wheelers constitute a concentrated margin pool in the aftermarket retrofit segment, driven by urban last-mile delivery electrification delays that push operators toward immediate CNG compliance.
BIS certification mandates cylinder and valve safety standards for all CNG kits sold in India, while the CEA regulates filling station pressure protocols and urban licensing. The PLI scheme administered by the Ministry of Heavy Industries directs subsidy flows toward OEMs achieving domestic value addition thresholds in alternative fuel powertrain manufacturing. State-level transport departments in Maharashtra, Gujarat, and Delhi enforce mandatory commercial fleet CNG conversion deadlines that compress demand timelines. Stakeholders must monitor station commissioning rates against vehicle sales velocity to identify infrastructure-constrained demand pockets before committing capacity.
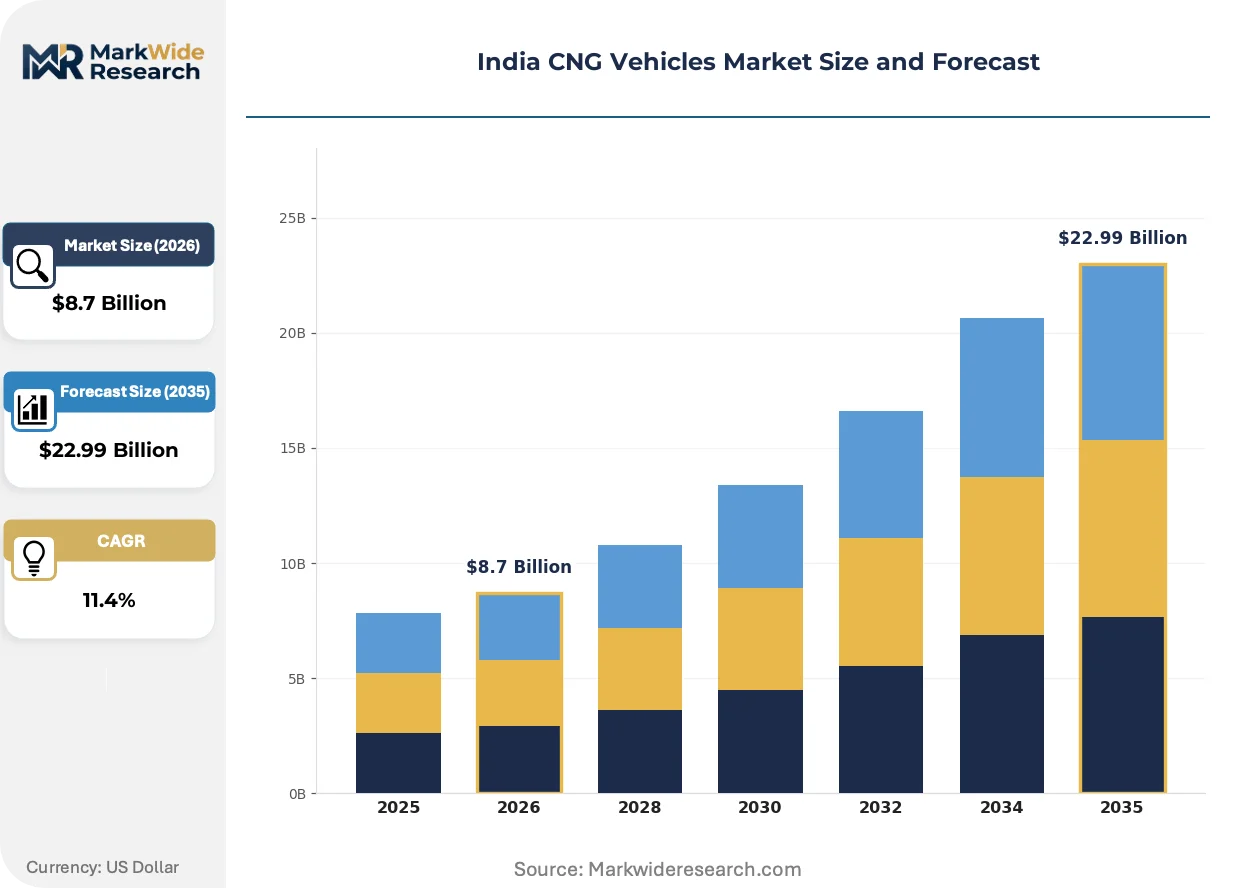
Market Dynamics
India's CNG vehicle market is being compressed by state-level fleet conversion mandates that outpace station commissioning capacity, creating geographic demand asymmetries between Maharashtra, Gujarat, and Delhi NCR versus infrastructure-deficient hinterlands.
Growth Catalysts
- PLI Scheme Thresholds:The Ministry of Heavy Industries directs subsidy flows toward OEMs achieving domestic value addition in alternative fuel powertrains, accelerating factory-fitted CNG platform development.
- Urban Last-Mile Delivery:Electrification delays in three-wheeler segments push logistics operators toward immediate CNG retrofit compliance to meet municipal emission deadlines.
- Bi-Fuel System Adoption:Fleet operators across patchy infrastructure corridors demand operational flexibility through electronic control units that switch between petrol and CNG injection.
Market Restraints
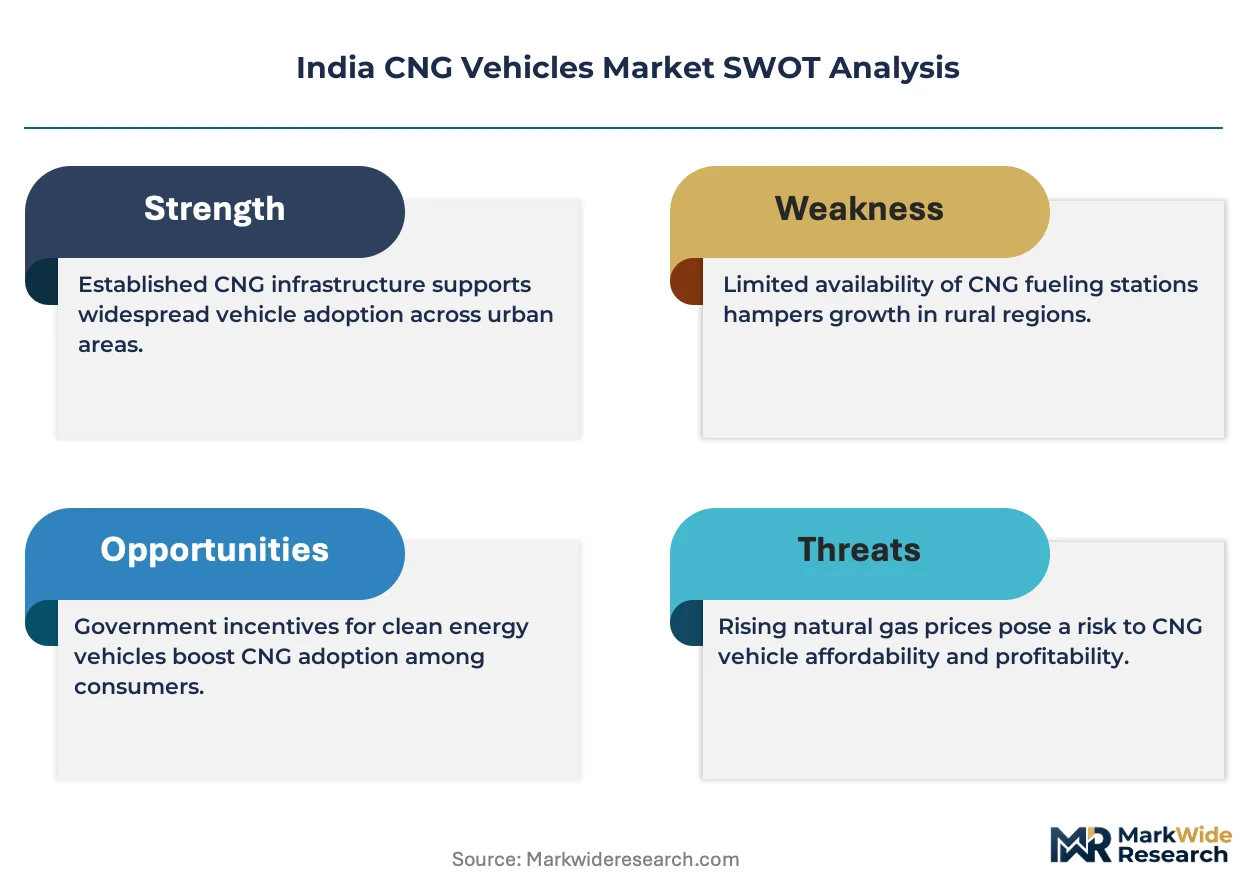
- Station Density Concentration:CNG dispensing infrastructure clusters disproportionately in western and northern India, leaving eastern and southern states supply-constrained.
- Type 2 Composite Cylinder Costs:High-pressure storage systems at 200-250 bar specifications carry material cost premiums that compress aftermarket retrofitter margins.
- Petrol Price Volatility:Bi-fuel switching economics weaken when compressed natural gas price differentials narrow against conventional fuels.
Strategic Opportunities
- Eastern State Expansion:Odisha, West Bengal, and the northeastern corridor present white-space demand where station commissioning lags vehicle sales velocity.
- Bus Fleet Electrification Gaps:Urban transport corporations facing battery supply constraints are extending CNG platform lifecycles as interim compliance pathways.
- BIS Certification Harmonization:Streamlined cylinder and valve safety standards could reduce aftermarket kit approval timelines from multiple regulatory touchpoints.
Industry Challenges
- Calibration Technician Shortage:Bi-fuel electronic control unit programming requires specialized skill sets that training institutes have not scaled to match conversion demand.
- CEA Pressure Protocol Compliance:Filling station operators face urban licensing bottlenecks that delay commissioning schedules against fleet operator procurement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India CNG Vehicles Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Buses, Three-Wheelers, Light Commercial Vehicles Fuel System Type: Bi-Fuel, Dedicated CNG, CNG-Diesel, Others End User: Private Users, Fleet Operators, Public Transport, Logistics Companies Production Stage: OEM, Aftermarket, Retrofit, Export |
| Companies Covered | Toyota, Honda, Maruti Suzuki, Nissan, Renault, Tata Motors, Kia, Maruti Suzuki Toyota, Hyundai, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India CNG Vehicles Market Shifts & Advancements
Factory-fitted CNG integration is reshaping competitive positioning in India's passenger vehicle segment, compressing aftermarket retrofitter relevance while elevating OEM-controlled bi-fuel architectures as the default procurement standard.
Sequential injection technology is overtaking conventional venturi-based CNG systems in factory installations. Maruti Suzuki and Hyundai have transitioned their hatchback and compact sedan ranges to dedicated CNG injectors with independent rail pressure management. This precision is enabling stricter emission compliance under evolving BIS test cycles while reducing the calibration burden on dealership service networks.
The PLI scheme administered by the Ministry of Heavy Industries is redirecting capital toward domestic powertrain component sourcing. OEMs meeting local value addition thresholds receive preference in subsidy allocation, compressing import dependency for high-pressure regulators and electronic control modules. Maharashtra and Gujarat-based manufacturing clusters are capturing disproportionate investment flows as a result.
Fleet procurement centralization is consolidating buyer power among logistics aggregators and urban transport corporations. Large operators now specify total cost of ownership guarantees and pan-India service network coverage in vendor selection criteria, displacing fragmented dealer-based retail transactions. This concentration is most visible in Delhi NCR and Ahmedabad metropolitan zones where municipal mandates enforce commercial vehicle emission deadlines.
India CNG Vehicles Market Segmentation
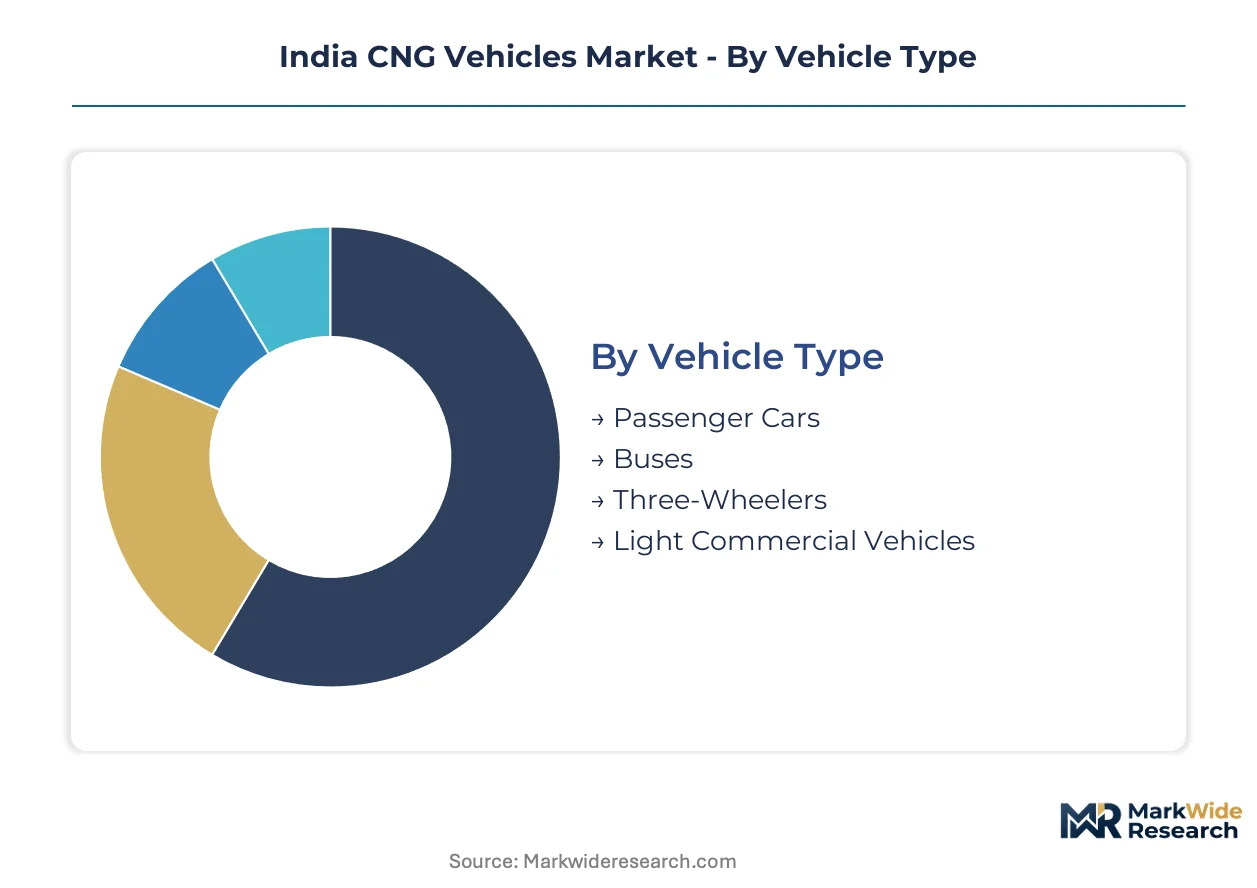
India's CNG vehicle market fragments across four distinct dimensions that determine procurement economics, regulatory compliance pathways, and infrastructure dependency. Understanding these segment boundaries reveals where factory-fitted OEM platforms displace aftermarket retrofits, and where bi-fuel flexibility commands premium positioning against dedicated CNG architectures.
Vehicle Type:
Fleet procurement scale and municipal mandate intensity drive category prioritization across vehicle formats.
- Passenger Cars:Factory-fitted CNG hatchbacks and compact sedans integrate sequential injection systems with independent rail pressure management. Maruti Suzuki's dominance across Maharashtra, Gujarat, and Delhi NCR corridors compresses aftermarket retrofitter margins through dealership-controlled service networks and BIS-certified cylinder installations.
- Three-Wheelers:Urban last-mile delivery operators facing electrification delays retrofit CNG kits onto existing petrol platforms for immediate emission compliance. Aftermarket conversion demand concentrates in Delhi NCR and Ahmedabad where municipal deadlines outpace battery supply availability.
- Buses:Urban transport corporations extend CNG platform lifecycles as interim solutions while battery electric procurement faces supply constraints. Tata Motors anchors this segment through dedicated CNG chassis for state road transport undertakings.
- Light Commercial Vehicles:Logistics aggregators specify bi-fuel configurations for intercity corridors with patchy CNG station density. Fleet procurement centralization demands pan-India service coverage and total cost of ownership guarantees.
Passenger cars lead on scale; three-wheelers lead on momentum.
Fuel System Type:
Operational flexibility requirements and infrastructure maturity determine system architecture selection.
- Bi-Fuel:Electronic control units enable seamless switching between petrol and CNG injection based on real-time pressure and availability. Fleet operators across eastern and southern India demand this architecture where station commissioning lags vehicle deployment.
- Dedicated CNG:Single-fuel systems eliminate petrol tank weight and injection complexity for maximum range efficiency. Municipal bus fleets in Delhi, Mumbai, and Ahmedabad adopt dedicated platforms where depot-based refueling infrastructure is captive.
- CNG-Diesel:Dual-fuel configurations for heavy commercial applications retain diesel pilot injection with CNG substitution ratios up to 90%. Limited adoption reflects calibration complexity and BIS certification bottlenecks for aftermarket installations.
- Others:Emerging architectures include CNG-hydrogen blends and cryogenic storage systems under pilot evaluation by PSU energy majors.
Bi-fuel systems dominate addressable market breadth; dedicated CNG commands infrastructure-captive niches.
End User:
Procurement centralization and compliance timeline pressure distinguish buyer categories.
- Fleet Operators:Logistics aggregators and ride-hailing platforms negotiate volume pricing and service level agreements with OEMs. Centralized procurement in Delhi NCR and Mumbai metropolitan zones displaces fragmented dealer retail.
- Public Transport:State road transport undertakings issue tender-based bulk orders with 10-15 year lifecycle specifications. CEA pressure protocol compliance and urban licensing requirements compress vendor qualification timelines.
- Private Users:Retail buyers prioritize factory-fitted CNG for warranty preservation and resale value protection. Maruti Suzuki and Hyundai dealership networks capture this demand through hatchback and compact sedan offerings.
- Logistics Companies:E-commerce fulfillment operators retrofit existing vehicle assets to meet municipal emission deadlines without awaiting new platform procurement.
Fleet operators lead on procurement volume; public transport leads on contract duration.
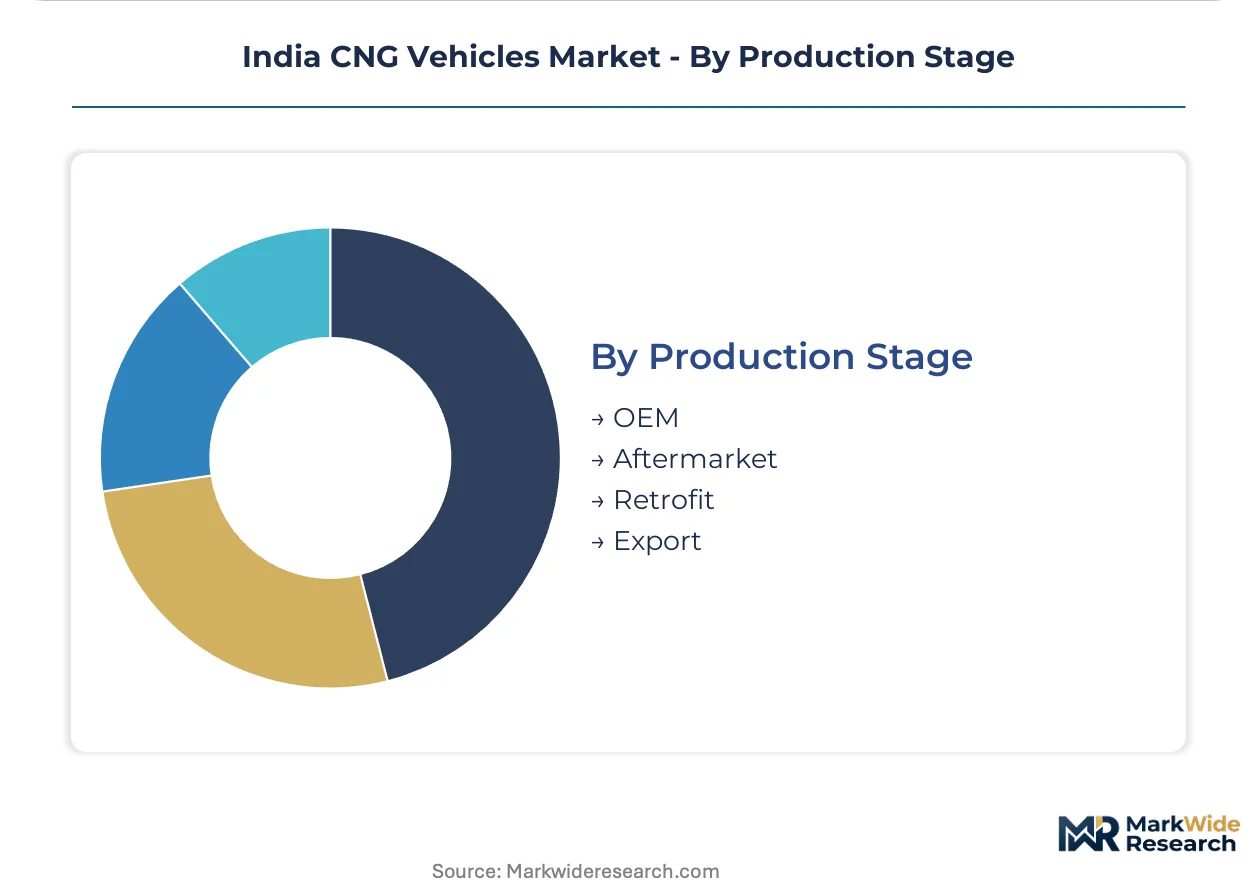
Production Stage:
Regulatory certification requirements and value addition thresholds segment manufacturing pathways.
- OEM:Factory-integrated CNG platforms from Maruti Suzuki, Tata Motors, and Hyundai meet PLI scheme domestic value addition criteria for subsidy eligibility. Maharashtra and Gujarat manufacturing clusters capture disproportionate investment flows.
- Aftermarket:BIS-certified kit installers face margin compression as OEM factory-fitted penetration deepens. Type 2 composite cylinder costs at 200-250 bar specifications strain retrofitter economics.
- Retrofit:Existing petrol vehicle conversions require RTO approval and cylinder hydrostatic testing under CEA protocols. Three-wheeler retrofits dominate this segment due to electrification delays in urban delivery.
- Export:Limited outbound shipment of CNG kits and components to South Asian and African markets with compatible BIS standards.
OEM production leads on quality integration; aftermarket retrofit leads on speed-to-compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production incentives under the PLI scheme administered by the Ministry of Heavy Industries are concentrating CNG vehicle manufacturing in states with established automotive clusters, creating cost-of-compliance arbitrage that favors Maharashtra and Gujarat over eastern and southern hinterlands.
Maharashtra
Mumbai-Pune corridor fleet operators drive passenger car and bus procurement under municipal emission mandates. The state transport department enforces commercial vehicle CNG conversion deadlines that compress demand timelines. Aurangabad-Nashik manufacturing belt captures OEM investment flows from Maruti Suzuki and Tata Motors seeking PLI scheme subsidy eligibility.
Gujarat
Ahmedabad-Surat logistics corridors anchor light commercial vehicle bi-fuel adoption for intercity freight operators. GAIL and Gujarat Gas commission CNG stations at twice the national average density, eliminating range anxiety for dedicated CNG platforms. Sanand-Vithalapur automotive cluster hosts Hyundai and Tata Motors factory-fitted CNG assembly lines.
Delhi NCR
Supreme Court-mandated commercial fleet emission standards push three-wheeler retrofits and bus fleet conversions ahead of battery electric supply availability. Delhi Transport Corporation extends CNG platform lifecycles through Tata Motors bulk tenders. Gurugram-Faridabad last-mile delivery operators retrofit existing petrol assets to meet municipal deadlines.
Karnataka
Bengaluru metropolitan bus procurement under BMTL emission targets lags station commissioning, forcing bi-fuel specifications for operational flexibility. State transport utilities face CEA urban licensing bottlenecks that delay filling station deployment against vehicle procurement schedules. Mysuru-Belagavi corridor presents white-space demand where infrastructure investment trails fleet operator interest.
Tamil Nadu
Chennai automotive manufacturing base exports CNG-compatible powertrain components to PLI scheme-compliant OEMs in western India. State-level commercial fleet mandates remain less stringent than Maharashtra or Delhi, compressing immediate retrofit demand. Coimbatore-Salem logistics operators await GAIL pipeline extensions before committing to dedicated CNG platform procurement.
India CNG Vehicles Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with factory-fitted OEM platforms commanding passenger car volumes while aftermarket retrofitters capture three-wheeler compliance demand. The structure concentrates around three archetypes: integrated automotive conglomerates with captive CNG engineering, dedicated alternative fuel powertrain specialists, and regional kit installers with BIS certification. Competitive moves center on PLI scheme qualification through domestic value addition thresholds, and backward integration into high-pressure regulator manufacturing to reduce import dependency.
Within the integrated automotive tier, Maruti Suzuki and Tata Motors exemplify divergent strategic positioning—Maruti Suzuki anchors factory-fitted passenger car dominance through hatchback and compact sedan CNG variants, while Tata Motors occupies the commercial vehicle vector with dedicated bus and light commercial platforms for state transport undertakings. Hyundai represents the premium bi-fuel specialist archetype, targeting fleet operators with turbocharged CNG powertrains that emphasize total cost of ownership guarantees.
| Leading Market Players |
|---|
| Toyota |
| Honda |
| Maruti Suzuki |
| Nissan |
| Renault |
| Tata Motors |
| Kia |
| Maruti Suzuki Toyota |
| Hyundai |
| Others |
Supply & Pricing Matrix
Factory-fitted OEM premium versus aftermarket retrofit economy pricing stratifies across certification grade, cylinder specification, and warranty bundling, compressing retrofitter margins while concentrating procurement power with Maruti Suzuki and Tata Motors dealership networks in Maharashtra and Gujarat.
Pricing Analysis
Distributor margins on BIS-certified Type 2 composite cylinders compress as OEM factory-fitted penetration deepens. Pricing stratifies across premium, standard, and economy tiers based on sequential injection technology grade and pan-India service coverage guarantees. Cost compression in the aftermarket retrofit segment intensifies because PLI scheme subsidies flow exclusively to domestic value-adding OEMs. Fleet operators demonstrate lowest price sensitivity due to total cost of ownership contracting, while individual three-wheeler owner-operators exhibit highest sensitivity to upfront kit costs.
Supply Chain Analysis
Freight costs from South Korean and Japanese high-pressure regulator suppliers elevate landed costs for aftermarket installers lacking OEM scale. Domestic manufacturing draws from Maharashtra and Gujarat automotive clusters for cylinder fabrication, while electronic control modules rest on semiconductor inputs from Taiwan and South Korea. Single-source vulnerability concentrates in specialized bi-fuel calibration software. Distribution runs through state transport department-approved installation networks and OEM captive service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India CNG vehicle market compounds steadily as state-level fleet conversion mandates outpace infrastructure buildout, creating persistent demand compression across compliance deadlines.
For Market Incumbents: Anchor factory-fitted platform dominance through backward integration into high-pressure regulator manufacturing, eliminating import dependency that aftermarket retrofitters cannot match. Defend against bi-fuel calibration technician shortages by scaling captive training programs ahead of municipal mandate waves. Prioritize PLI scheme threshold compliance to maintain subsidy eligibility against emerging OEM entrants. For New Entrants and Emerging Players: Capture eastern state white-space demand in Odisha and West Bengal where station commissioning lags vehicle sales velocity. Target three-wheeler retrofit compliance as the most penetrable segment given electrification delays and compressed municipal deadlines. Pursue direct partnerships with urban logistics aggregators specifying total cost of ownership guarantees rather than fragmented dealer retail. For Investors and Strategic Acquirers: Consolidation pressure builds where BIS certification bottlenecks and CEA licensing delays strand sub-scale retrofitters without OEM service network coverage. Frame long-term viability around captive CNG infrastructure ownership rather than vehicle manufacturing alone. Monitor station commissioning rates against fleet procurement timelines as the critical inflection signal for demand-constrained versus supply-constrained regional pockets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cylinder Manufacturing | Captures PLI scheme subsidies while reducing Type 2 composite import dependency from South Korean suppliers. |
| Bi-Fuel Calibration Training Scale-Up | Addresses technician scarcity that constrains aftermarket retrofitter capacity against municipal mandate deadlines. |
| Eastern State Infrastructure Partnership | Secures first-mover positioning in Odisha and West Bengal ahead of GAIL pipeline extension completion. |
| Fleet Operator TCO Guarantee Contracts | Locks in logistics aggregator volume through pan-India service coverage commitments and fuel cost hedging. |
| CEA Pressure Protocol Pre-Certification | Accelerates filling station commissioning timelines against compressed urban licensing bottlenecks. |
Research Methodology
Bottom-up fleet operator procurement modeling reconciled against top-down OEM production tracking forms the analytical core of this study. Primary interviews with state transport department officials, urban logistics aggregator procurement heads, aftermarket kit installers, and CEA-licensed station operators combined with secondary validation from BIS certification databases, Ministry of Heavy Industries PLI scheme disclosures, and GAIL infrastructure commissioning records. Triangulation across these sources ensures segment-level volume integrity.
Input-output matrices map vehicle class, fuel system architecture, production stage, and regional infrastructure maturity across the analysis window. CAGRs derive from logistic diffusion curves fitted to station density thresholds and fleet conversion mandate timelines. Industry-specific forecast inputs include CNG dispensing capacity additions under the CGD network expansion and state-level commercial vehicle registration compliance data.
Regulatory enforcement delays, CNG price volatility against petrol differentials, and battery electric vehicle supply chain normalization are the dominant revision risks to modeled projections. Stakeholders should weight assumptions against their own operating context and infrastructure access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Japan Next Generation Vehicle Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
North America Hydrogen Powered Tractor Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
Automotive Flex Fuel Engine Market
Alternative Fuel Vehicles
China Zero Emission Vehicle Market
Alternative Fuel Vehicles
Automotive Low Emission Vehicle Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Automotive Biofuel Market