
 Hydrogen Powered Transport Market | 2026-2036
Hydrogen Powered Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Powered Transport Market Insights
The direct sales channel for heavy-duty hydrogen trucks is fragmenting as fleet procurement moves toward long-term service contracts bundling vehicles, fuel, and maintenance. Toyota Motor Corporation leverages its multi-decade fuel cell patent portfolio to anchor early commercial deployments in bus and coach segments. Hyundai Motor Company competes through integrated manufacturing of both PEMFC stacks and complete vehicle platforms, while Nikola Corporation specializes in energy-as-a-service models that separate asset ownership from fuel supply.
Hydrogen powered transport encompasses vehicles utilizing proton-exchange membrane or solid-oxide fuel cells to convert stored hydrogen into electrical energy, with systems typically operating at 350-700 bar storage pressure and achieving 500-800 kilometer range per refill. The primary commercial purpose is decarbonizing long-haul freight and high-utilization public transit where battery-electric solutions face weight and charging-time constraints. Trucks dominate current revenue pools due to per-unit value concentration, while buses anchor deployment volume through municipal procurement programs with guaranteed utilization. PEMFC technology leads installed capacity but SOFC variants are gaining traction in rail applications where steady-state operation favors higher-temperature efficiency.
The EU Green Deal and F-Gas Regulation shape product standards by mandating phased carbon-intensity reductions across vehicle lifecycles, while Japan's METI coordinates hydrogen supply chain investments through its Green Growth Strategy. The US EPA and NHTSA jointly determine market access through tailpipe emission rules and safety certification protocols for high-pressure onboard storage. Stakeholders must monitor whether infrastructure build-out pace or vehicle cost curves become the binding constraint on fleet conversion decisions.
Market Dynamics
Fleet procurement contracts now bundle hydrogen supply with vehicle assets, compressing the traditional equipment sales cycle into integrated service agreements that transfer fuel price risk from operators to suppliers.
Growth Catalysts
- California's Advanced Clean Trucks regulation:Mandates zero-emission vehicle sales quotas for heavy-duty fleets, creating guaranteed demand anchors for hydrogen truck deployments through 2035.
- PEMFC stack cost decline:Manufacturing scale and platinum loading reduction are cutting fuel cell system costs, narrowing the total cost of ownership gap with diesel for long-haul routes.
- German hydrogen corridor build-out:State-backed H2Mobility infrastructure investments along the Rhine-Alpine freight corridor are eliminating range anxiety for cross-border logistics operators.
Market Restraints
- Electrolyzer capacity concentration:Proton-exchange membrane electrolyzer manufacturing concentrates in China and Germany, exposing supply chains to geopolitical friction and equipment lead times exceeding 18 months.
- Green hydrogen cost premium:Renewable-powered electrolysis remains two to three times the cost of gray hydrogen from steam methane reforming, compressing fleet operator margins until carbon pricing mechanisms mature.
- High-pressure storage certification:NHTSA and UN ECE R134 protocols for 700 bar composite tanks impose lengthy validation timelines, delaying new vehicle platform launches by 12-24 months.
Strategic Opportunities
- Rail freight electrification:Solid-oxide fuel cell systems for non-electrified rail corridors in Germany and Japan offer steady-state efficiency advantages that proton-exchange membrane cells cannot match.
- Municipal bus fleet conversion:Guaranteed utilization through public transit procurement in South Korea and Japan creates predictable revenue streams for hydrogen-as-a-service providers.
- EU Green Deal carbon border adjustments:Phased implementation of carbon intensity standards for imported goods is pressuring logistics operators to switch from diesel to certified low-carbon hydrogen.
Industry Challenges
- High-pressure systems engineering talent:Scarcity of specialists in cryogenic and compressed gas handling is extending R&D timelines for next-generation storage systems.
- Multi-standard refueling protocol fragmentation:Divergent SAE J2601 and ISO 19880-1 implementations across Japan, Germany, and California are forcing redundant vehicle certification investments.
- Fuel cell stack durability validation:Achieving 25,000-hour commercial vehicle lifetime targets requires extended real-world testing that compresses product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Powered Transport Market |
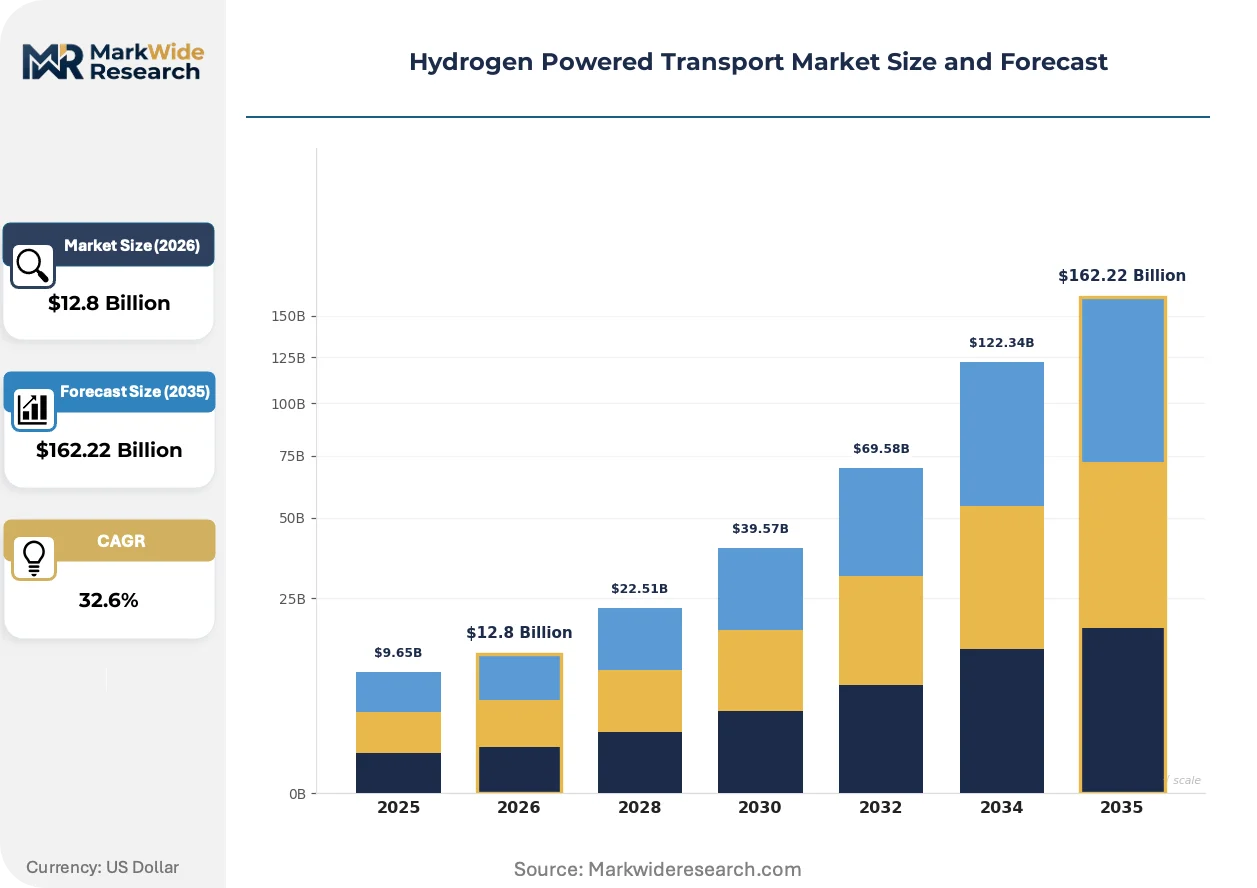
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $162.22 Billion |
| CAGR (2026 – 2036) | 32.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Cars, Buses, Trucks, Trains Fuel Cell Technology: PEMFC, SOFC, DMFC, AFC Infrastructure Type: Refueling Stations, Storage Facilities, Pipelines, Distribution Centers End User: Public Transport, Freight Transport, Logistics, Personal Transportation |
| Companies Covered | Toyota Motor Corporation, Hyundai Motor Company, Honda Motor Co., Ltd, BMW, Mercedes-Benz Group AG, Nikola Corporation, Volvo Group AB, Kia Corporation, Ballard Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Powered Transport Market Trends and Innovations
Technology convergence between fuel cell systems and battery-electric architectures is producing hybrid powertrain configurations that optimize capital deployment across duty cycles. Regulatory pressure on lifecycle carbon intensity is reshaping supplier qualification criteria.
Solid-oxide fuel cell technology is hybridizing with battery buffers for rail applications, combining the thermal efficiency of high-temperature electrochemical conversion with dynamic load balancing for grade transitions. Deutsche Bahn and JR East are piloting these hybrid configurations on regional freight routes where overhead electrification is uneconomical. The technology is hybridizing the competitive boundary between hydrogen and catenary infrastructure, enabling corridor-specific business cases that pure fuel cell or pure battery systems cannot serve.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in vehicle climate systems, forcing refrigerant transitions to CO2 or hydrocarbon-based alternatives that complicate thermal management integration with fuel cell waste heat recovery. Stack suppliers must redesign balance-of-plant components to maintain cabin conditioning without conventional heat pumps. Bus and coach segments face the steepest compliance costs due to larger cabin volumes and extended daily operating hours.
Fleet operators are consolidating procurement authority into centralized sustainability offices that negotiate enterprise-level hydrogen supply agreements separate from vehicle acquisition. Traditional dealer networks are losing influence to direct manufacturer relationships and energy trading houses that bundle fuel with asset financing. This concentration is most visible in German and Dutch road freight, where large logistics groups operate sufficient vehicle counts to justify dedicated refueling infrastructure commitments.
Hydrogen Powered Transport Market Segmentation
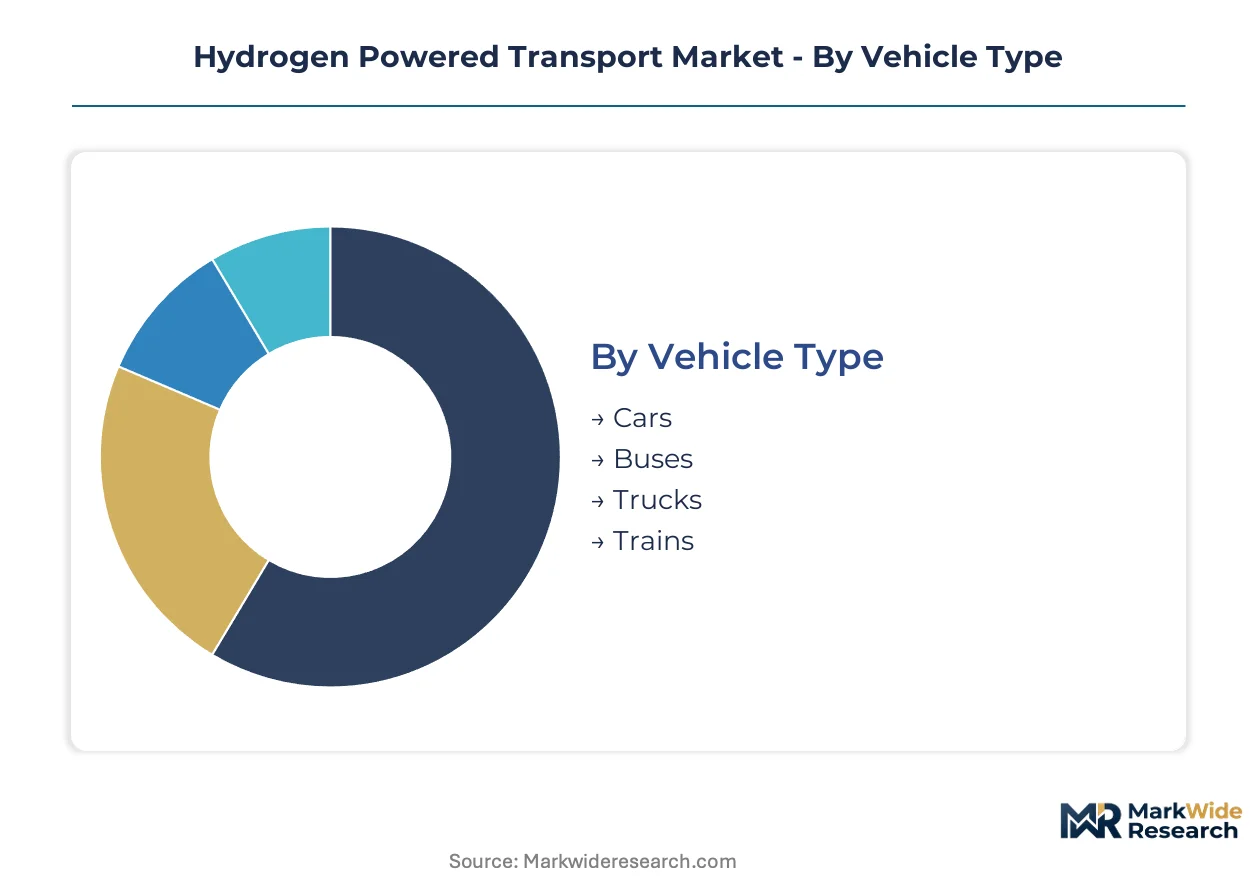
Segmentation in hydrogen powered transport reveals how capital cycles, technology maturity, and infrastructure availability create divergent investment timelines across vehicle categories and system architectures. Fleet operators prioritize segments with proven fuel cell durability and established refueling corridors.
Vehicle Type:
Replacement cycles vary dramatically across vehicle categories, with municipal buses turning over every 8-12 years while heavy-duty freight trucks operate 15-20 year lifespans, compressing near-term revenue into bus deployments while locking long-term value in truck platforms.
- Trucks:Heavy-duty fuel cell configurations utilize 350-700 bar composite storage and 200-300 kW PEMFC stacks optimized for sustained highway loads. Demand concentrates in German Rhine-Alpine freight corridors where H2Mobility infrastructure eliminates range constraints for cross-border logistics operators facing EU Green Deal carbon intensity mandates.
- Buses:Urban transit platforms integrate 60-100 kW fuel cell systems with 35-50 kg hydrogen capacity for 300-400 km daily duty cycles. Procurement clusters in South Korea and Japan where METI-coordinated municipal programs guarantee utilization rates that amortize high upfront capital costs across predictable revenue streams.
- Cars:Light-duty passenger vehicles employ compact 100 kW-class PEMFC architectures with 5-6 kg storage for 500-600 km range.
- Trains:Regional rail configurations apply hybrid SOFC-battery systems for non-electrified corridors in Germany and Japan.
Trucks dominate installed base value concentration. Buses are where expansion concentrates for near-term fleet conversion programs.
Fuel Cell Technology:
Cost structures diverge sharply across electrochemical architectures, with low-temperature proton-exchange systems achieving manufacturing scale while high-temperature solid-oxide variants command premium pricing for specialized steady-state applications.
- PEMFC:Proton-exchange membrane fuel cells operate at 60-80°C with platinum catalyst loadings that have declined 80% over successive generations, enabling automotive cost curves to approach parity with diesel powertrains for heavy-duty cycles. Manufacturing scale concentrates in South Korea and Japan where integrated stack-to-vehicle production lines compress learning curve timelines.
- SOFC:Solid-oxide systems achieve 60% electrical efficiency at 600-1000°C operating temperatures, favoring continuous-load rail and marine applications where waste heat recovery improves total system economics. Deployment focuses on German and Japanese regional rail corridors where steady-state operation justifies higher capital intensity against lifecycle fuel savings.
- DMFC:Direct methanol fuel cells utilize liquid fuel logistics that bypass compressed hydrogen infrastructure constraints for niche portable and light-duty applications.
- AFC:Alkaline fuel cell configurations offer platinum-free catalyst alternatives but face electrolyte degradation challenges that limit commercial vehicle adoption.
PEMFC commands the largest installed capacity. SOFC is climbing the fastest in rail and stationary transport applications.
Infrastructure Type:
Asset utilization rates determine infrastructure economics, with high-throughput refueling stations achieving break-even at 500+ kg daily throughput while distributed storage facilities serve seasonal demand fluctuations in industrial hydrogen supply.
- Refueling Stations:Public hydrogen dispensers operating at 350 bar for buses and 700 bar for passenger vehicles require 8-15 minute fill protocols standardized under SAE J2601 and ISO 19880-1. Deployment clusters along California's I-5 freight corridor and Germany's TEN-T core network where state-backed H2Mobility subsidies de-risk private capital deployment.
- Storage Facilities:Gaseous tube trailers and liquid cryogenic tanks buffer supply intermittency for fleet depots with captive demand, enabling 1-5 ton daily throughput without public network dependency.
- Pipelines:Dedicated hydrogen transmission infrastructure repurposes natural gas corridors in the Netherlands and Germany for industrial-scale supply to port and logistics clusters.
- Distribution Centers:Consolidated logistics hubs integrate on-site electrolysis or tube trailer receipt for last-mile fueling of captive fleet operations.
Refueling stations anchor public infrastructure investment. Storage facilities are gaining share fastest in private fleet depots.
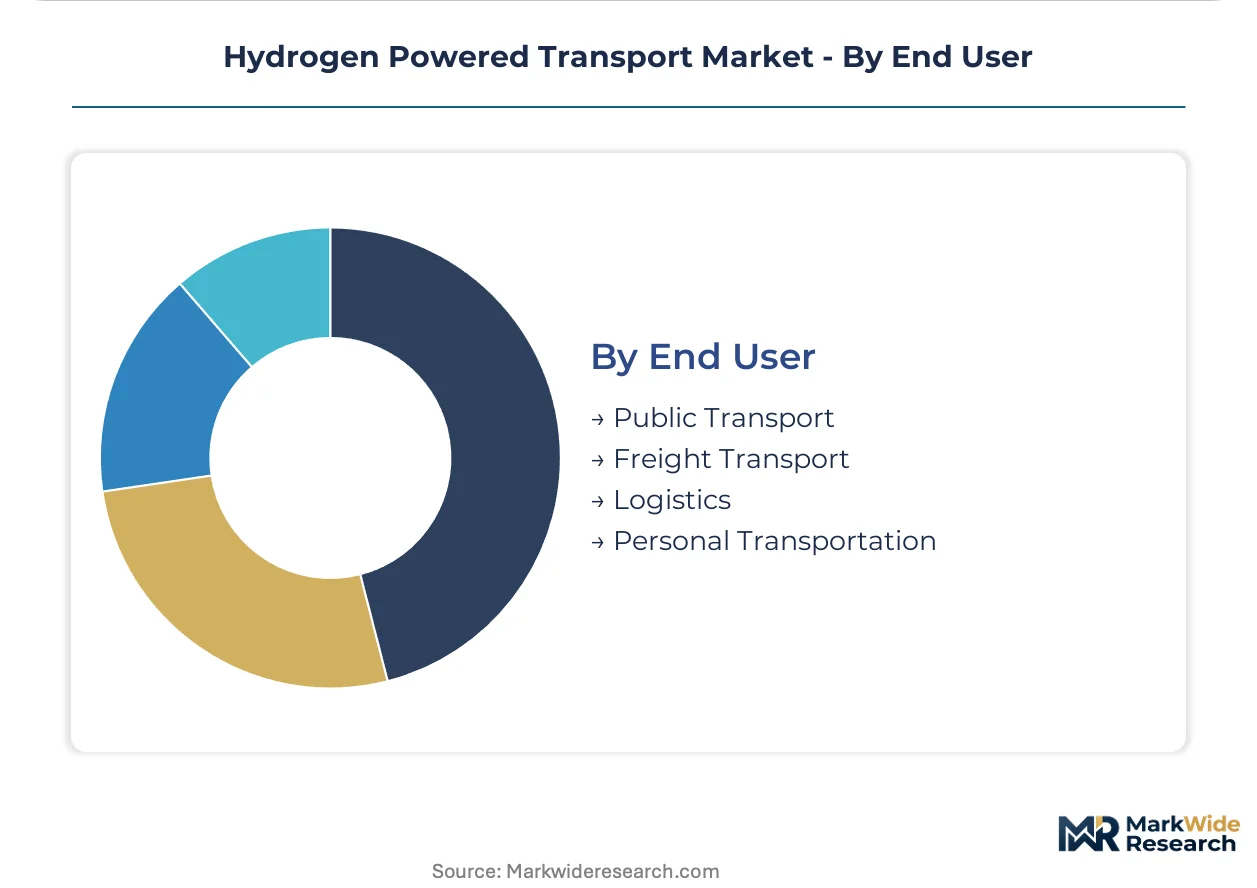
End User:
Procurement authority concentration shapes contract structures, with centralized municipal sustainability offices negotiating enterprise fuel supply agreements while fragmented logistics operators remain exposed to hydrogen price volatility.
- Freight Transport:Long-haul trucking and intermodal logistics operators face EU carbon border adjustment mechanisms that phase in lifecycle emission standards for imported goods, forcing diesel-to-hydrogen switching on cross-border routes. California's Advanced Clean Trucks regulation mandates zero-emission sales quotas that guarantee demand anchors through 2035.
- Public Transport:Municipal bus and rail operators leverage guaranteed utilization through scheduled service contracts that amortize fuel cell premium costs across 10-15 year procurement horizons. South Korean and Japanese transit authorities coordinate hydrogen supply chain investments through national green growth strategies that de-risk fleet conversion decisions.
- Logistics:Third-party fulfillment and warehousing operators pilot fuel cell forklifts and yard trucks in enclosed facilities where zero-emission mandates intersect with indoor air quality regulations.
- Personal Transportation:Individual passenger vehicle adoption remains constrained by refueling network density and total cost of ownership gaps against battery-electric alternatives.
Freight transport leads value concentration. Public transport is expanding most quickly through mandated municipal procurement programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing leverage through H2Mobility infrastructure subsidies that compress fleet operator conversion costs, while Japan extracts premium positioning via METI-coordinated supply chain investments that lock in domestic procurement preferences.
Germany
The Rhine-Alpine freight corridor anchors heavy-duty truck demand as logistics operators face EU Green Deal carbon intensity mandates. The KBA enforces UN ECE R134 certification protocols for 700 bar storage systems. Stuttgart and Munich clusters concentrate PEMFC stack manufacturing through integrated automotive supply chains.
Japan
Municipal bus procurement guarantees utilization rates that amortize fuel cell capital premiums across 10-year service contracts. METI's Green Growth Strategy coordinates hydrogen supply chain investments from production through refueling. The Kanto region around Tokyo hosts concentrated fuel cell stack manufacturing and vehicle platform integration.
South Korea
Public transit authorities in Seoul and Busan deploy hydrogen buses through guaranteed procurement programs that de-risk operator conversion decisions. The MFDS oversees safety certification for high-pressure onboard storage systems. The Ulsan-Gyeongbuk industrial corridor anchors integrated PEMFC stack-to-vehicle production.
United States
California's Advanced Clean Trucks regulation mandates zero-emission sales quotas through 2035 that create guaranteed demand anchors for hydrogen truck deployments. The EPA and NHTSA jointly determine market access through tailpipe emission rules and safety certification protocols. The I-5 freight corridor from Los Angeles to San Francisco concentrates early refueling infrastructure deployment.
China
Provincial governments in Guangdong and Shanghai subsidize fuel cell vehicle procurement through demonstration zone programs that compress fleet operator payback periods. The MIIT sets GB standards for fuel cell system performance and hydrogen storage safety. The Yangtze River Delta cluster concentrates electrolyzer manufacturing capacity that feeds vehicle supply chains.
Hydrogen Powered Transport Market Competitive Landscape
Integrated automakers and pure-play fuel cell specialists split the market along capital-intensity lines, with vehicle manufacturers leveraging captive demand through bundled service contracts while component suppliers pursue technology licensing to diversify revenue streams. The structure tilts toward consolidation as scale requirements for PEMFC manufacturing exceed mid-cap balance sheet capacity. Three archetypes dominate: vertically integrated vehicle OEMs with captive fuel cell production, independent stack suppliers licensing to multiple platforms, and energy-as-a-service operators separating asset ownership from fuel supply. Competitive moves concentrate on strategic partnerships for refueling infrastructure access and geographic expansion into state-subsidized demonstration zones.
Among integrated automotive manufacturers, Toyota Motor Corporation and Hyundai Motor Company exemplify the vertically integrated archetype through captive control of PEMFC stack production and complete vehicle platform assembly. Nikola Corporation occupies a distinct position within the energy-as-a-service tier, separating vehicle asset ownership from hydrogen fuel supply through long-term service contracts that transfer price risk from fleet operators to suppliers. Ballard Power Systems represents the independent stack supplier model, licensing fuel cell technology across multiple vehicle platforms without direct manufacturing exposure to complete vehicle assembly cycles.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Hyundai Motor Company |
| Honda Motor Co., Ltd |
| BMW |
| Mercedes-Benz Group AG |
| Nikola Corporation |
| Volvo Group AB |
| Kia Corporation |
| Ballard Power Systems |
| Others |
Pricing and Supply Chain Analysis
Ulsan-Gyeongbuk's integrated PEMFC stack-to-vehicle production clusters anchor manufacturing scale that compresses downstream fuel cell system costs, transferring pricing power toward OEMs with captive supply chains while independent stack suppliers face margin compression from platinum loading reduction programs.
Pricing Analysis
The configured-to-order premium spread for heavy-duty hydrogen trucks ranges from standard fleet procurement contracts to customized energy-as-a-service bundles separating asset ownership from fuel supply. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under UN ECE R134 protocols and volume scale commitments from logistics operators. Pricing pressure stems from green hydrogen cost premiums that remain two to three times gray hydrogen production costs, compressing fleet operator margins until carbon pricing mechanisms mature. Municipal transit authorities exhibit lowest price sensitivity due to guaranteed utilization amortizing capital premiums across 10-15 year service contracts.
Supply Chain Analysis
Export-control regimes limiting proton-exchange membrane electrolyzer technology flows concentrate manufacturing capacity in China and Germany, exposing supply chains to geopolitical friction and equipment lead times extending beyond 18 months. South Korea and Japan anchor fuel cell stack production while Germany and the Netherlands host pipeline infrastructure repurposing natural gas corridors. Raw material dependencies center on platinum group metals for PEMFC catalysts, rare earth elements for balance-of-plant components, and carbon fiber for 700 bar composite storage tanks. Single-source vulnerability in electrolyzer manufacturing creates chokepoint risk. Distribution runs through integrated OEM direct sales channels consolidating procurement authority away from traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering talent in cryogenic and compressed gas handling represents the critical capability gap constraining R&D timelines for next-generation storage systems, with scarcity extending product launch windows and amplifying returns for firms with captive expertise.
For Market Incumbents: Insulate market position through backward integration into PEMFC stack manufacturing and captive control of hydrogen supply infrastructure along priority freight corridors. Lock in municipal transit procurement contracts before California's Advanced Clean Trucks regulation mandates accelerate competitive bidding. Prioritize certification investment under evolving EU F-Gas Regulation thermal management requirements to maintain qualification status. For New Entrants and Emerging Players: Build out energy-as-a-service capabilities targeting mid-size logistics operators lacking capital for dedicated refueling infrastructure. Rail freight electrification presents the most penetrable white-space segment where SOFC-battery hybrid systems address non-electrified corridor gaps. Pursue geographic manufacturing partnerships in German H2Mobility-subsidized zones to de-risk infrastructure access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated stack-to-vehicle OEMs with demonstrated 25,000-hour durability validation and established refueling corridor partnerships over pure-play component suppliers facing licensing revenue dilution. Long-term viability across the analysis window rests on firms controlling both fuel cell manufacturing scale and hydrogen supply infrastructure. Watch electrolyzer capacity build-out pace as the inflection indicator for supply chain constraint resolution.| Strategic Initiative | Industry Significance |
|---|---|
| PEMFC Stack Cost Reduction Program | Platinum loading reduction initiatives under METI coordination narrow total cost of ownership gaps with diesel powertrains. |
| Hydrogen Corridor Infrastructure Partnership | German H2Mobility subsidies along Rhine-Alpine freight routes eliminate range anxiety for cross-border logistics operators. |
| SOFC-Battery Hybrid System Development | Deutsche Bahn and JR East pilot configurations combining thermal efficiency with dynamic load balancing for rail grade transitions. |
| Energy-as-a-Service Model Expansion | Nikola Corporation's bundled vehicle-fuel-maintenance contracts transfer price risk from fleet operators to suppliers. |
| EU F-Gas Regulation Compliance Investment | CO2 and hydrocarbon refrigerant transitions force balance-of-plant redesign for cabin conditioning without conventional heat pumps. |
Research Methodology
A standing panel of fuel cell system engineers, fleet procurement directors at logistics operators, hydrogen infrastructure project developers, and regulatory affairs specialists at automotive OEMs provided ongoing calibration against market developments. Primary interviews combined with secondary validation from SEC filings, IEA hydrogen supply chain reports, UN ECE regulatory submissions, and vehicle production databases. Bottom-up unit economics modeling triangulated against top-down market sizing across vehicle type, fuel cell technology, and infrastructure deployment segments.
Scenario-bracketing framed demand projections across infrastructure build-out pace and green hydrogen cost trajectories without assuming specific policy implementation timelines. Segmentation dimensions modeled included vehicle class, fuel cell architecture, storage pressure tier, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, fleet turnover rates, and state-backed procurement program commitments. Industry-specific forecast inputs incorporated H2Mobility station deployment schedules and METI-coordinated supply chain investment trajectories.
Stress conditions across electrolyzer manufacturing capacity, platinum group metal price volatility, and refueling protocol standardization timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding carbon pricing mechanism maturation and zero-emission vehicle mandate enforcement. Material shifts in EU Green Deal carbon border adjustment implementation schedules or California Advanced Clean Trucks regulation stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Air Powered Vehicle Market
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
Africa CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Zero Emission Vehicle Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
Automotive Flex Fuel Engine Market
Alternative Fuel Vehicles
Global CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Automotive Natural Gas Vehicle Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
India CNG Vehicles Market