
 Alternative Fuel and Hybrid Vehicle Market | 2026-2036
Alternative Fuel and Hybrid Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Alternative Fuel and Hybrid Vehicle Market Analysis
Multi-source battery cell procurement is pivoting toward in-house cathode and cell manufacturing across top OEMs. Tesla leverages its Nevada-based cell production to reduce dependency on Asian suppliers. BYD sustains full vertical integration from lithium refining through finished vehicles, anchoring cost leadership in the electric segment. Toyota dominates hybrid system architecture through two decades of Prius-series refinement, while BMW differentiates via flexible vehicle platforms accommodating multiple electrified powertrains.
Alternative fuel and hybrid vehicles integrate electric motors with energy storage systems—typically lithium-ion battery packs ranging from 40 kWh to over 100 kWh in passenger applications—or hydrogen fuel cells producing 60-160 kW continuous output, designed to displace internal combustion in transportation duty cycles. Battery electric technology occupies the largest share of current investment flows, though plug-in hybrid architectures retain structural importance where charging infrastructure remains sparse. Fuel cell applications concentrate in heavy-duty buses and long-haul trucks, segments where battery weight penalties compromise payload capacity.
The US EPA tailpipe emission standards and California Air Resources Board zero-emission vehicle mandates shape product planning timelines for manufacturers selling into North America. Europe's CO2 fleet targets and Euro 7 pollutant limits accelerate powertrain electrification across Volkswagen, BMW, and Daimler lineups. China's MIIT new energy vehicle credit system enforces minimum electric production ratios, compelling domestic and joint-venture OEMs to expand battery-electric output. Stakeholders must monitor how divergent regulatory stringency across these jurisdictions reshapes platform development budgets and regional model allocation strategies.
Market Dynamics
Powertrain electrification is compressing development cycles as OEMs retool assembly lines away from internal combustion architectures toward modular electric platforms that accommodate battery, fuel cell, and hybrid configurations within common vehicle structures.
Growth Catalysts
- EU CO2 Performance Standards:Fleet-average emission targets force Volkswagen, BMW, and Mercedes-Benz to expand battery-electric model ranges and phase out pure combustion drivetrains across passenger car segments.
- Lithium Refining:Australia's spodumene concentrate and Chile's brine extraction operations anchor cathode material supply chains, reducing dependency on single-source processed chemical imports.
- Transit Authority Procurement:Municipal fleet operators in California, New York, and Illinois accelerate battery-electric bus deployment to comply with state-level zero-emission vehicle mandates for public transportation.
Market Restraints
- Cathode Material Cost Volatility:Nickel and cobalt price swings on the London Metal Exchange compress cell manufacturer margins and destabilize long-term supply contracts with automotive OEMs.
- Semiconductor Supply Concentration:Taiwan-based foundries control advanced node production for power electronics and battery management systems, creating single-point vulnerability for inverter and DC-DC converter supply.
- Energy Density Limitations:Current lithium-ion cell chemistry plateau around 300 Wh/kg, constraining range extension in heavy-duty trucking applications where payload weight limits apply.
Strategic Opportunities
- India PLI Scheme for Auto:Production-linked incentives for advanced chemistry cell manufacturing attract BYD, Samsung SDI, and domestic conglomerates to establish gigafactory operations in Gujarat and Tamil Nadu.
- V2G Integration:Bidirectional charging hardware converges with home energy management systems, enabling fleet operators and residential customers to monetize stationary battery storage during grid peak events.
- Commercial Leasing Channels:Battery-as-a-service and powertrain subscription models reduce upfront capital barriers for small logistics operators transitioning from diesel vans to electric light commercial vehicles.
Industry Challenges
- Battery Thermal Management Expertise:OEMs and tier-1 suppliers face acute shortages of electrochemical engineers and simulation specialists capable of optimizing cell cooling architectures for fast-charging duty cycles.
- Homologation Timeline Compression:UN ECE R100 and FMVSS 305 certification requirements for high-voltage safety extend product validation schedules, delaying regional market entry for new electric platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternative Fuel and Hybrid Vehicle Market |
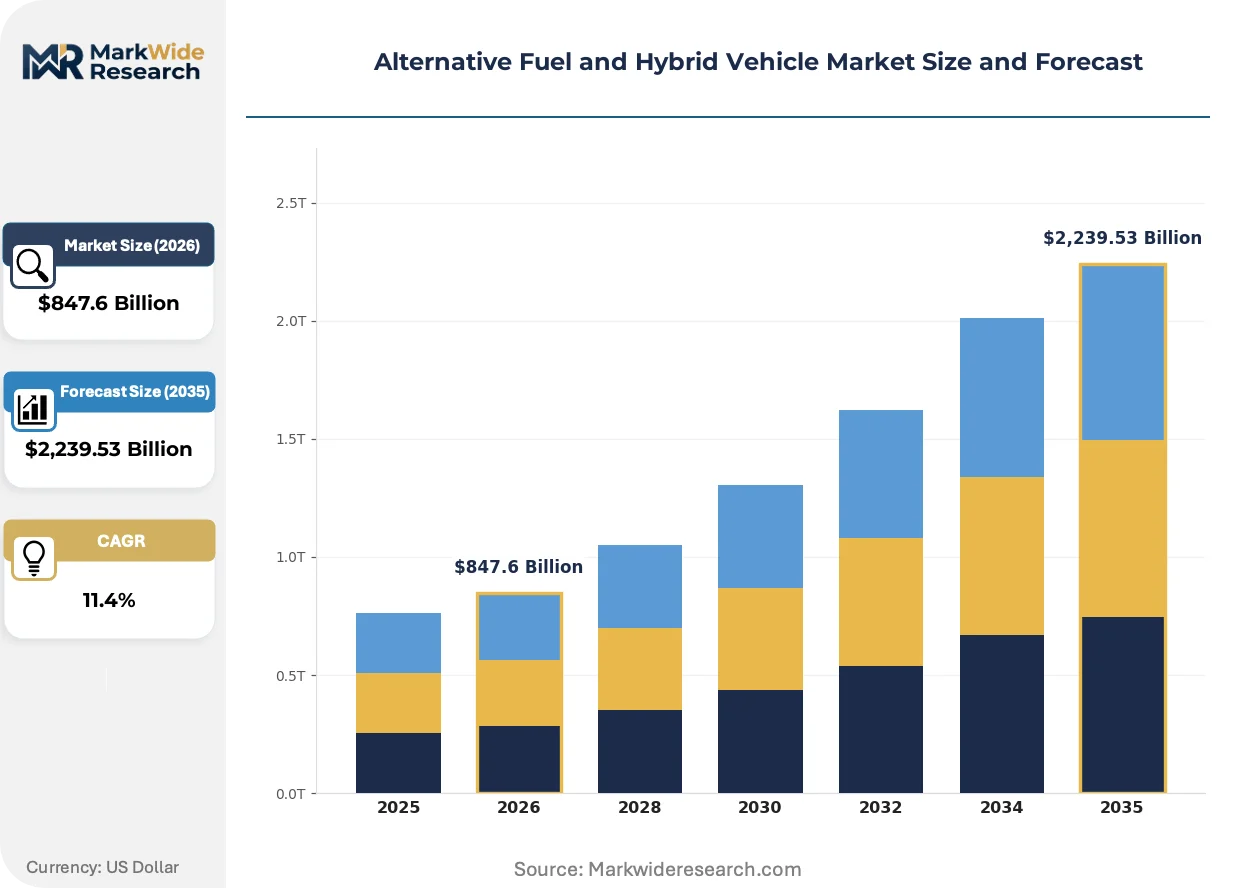
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $2,239.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Electric, Hydrogen, Biofuel, LPG Technology: Battery Electric, Plug-in Hybrid, Fuel Cell, Range Extended Electric Vehicle Category: Passenger Cars, Light Trucks, Buses, Vans Drive Train: All-Wheel Drive, Front-Wheel Drive, Rear-Wheel Drive, Two-Wheel Drive |
| Companies Covered | Tesla Inc., BYD Company Ltd., Toyota Motor Corporation, Volkswagen AG, Ford Motor Company, General Motors Company, BMW AG, Honda Motor Co., Ltd., Daimler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternative Fuel and Hybrid Vehicle Market Emerging Trajectories
Solid-state electrolyte chemistry and silicon-anode architectures are absorbing the majority of advanced battery research funding, while regulatory pressure on supply chain due diligence accelerates traceability technology deployment.
Solid-state battery technology replaces liquid electrolyte with ceramic or sulfide ionic conductors, enabling higher voltage operation and reduced thermal runaway risk. Toyota and QuantumScape target automotive qualification timelines for 2027-2028 production. This chemistry is absorbing engineering resources previously allocated to incremental lithium-ion improvements, compressing the competitive window for conventional cell architectures.
The EU Battery Regulation mandates carbon footprint declarations, recycled content minimums, and supply chain due diligence for all cells placed on the European market. Manufacturers must establish passport-style traceability systems linking raw material extraction to end-of-life recycling. Heavy-duty commercial vehicle segments face the steepest compliance burden, prompting Volvo and Daimler Truck to restructure supplier qualification protocols.
Fleet managers now specify total-cost-of-ownership calculations rather than sticker price in procurement evaluations, weighting energy costs, maintenance intervals, and residual value forecasts. This behavioral shift elevates battery-electric trucks against diesel alternatives in high-mileage urban delivery routes. The transformation is most visible in Germany's Ruhr industrial corridor, where logistics operators consolidate purchasing decisions at the fleet level rather than individual depot authorization.
Alternative Fuel and Hybrid Vehicle Market Segmentation
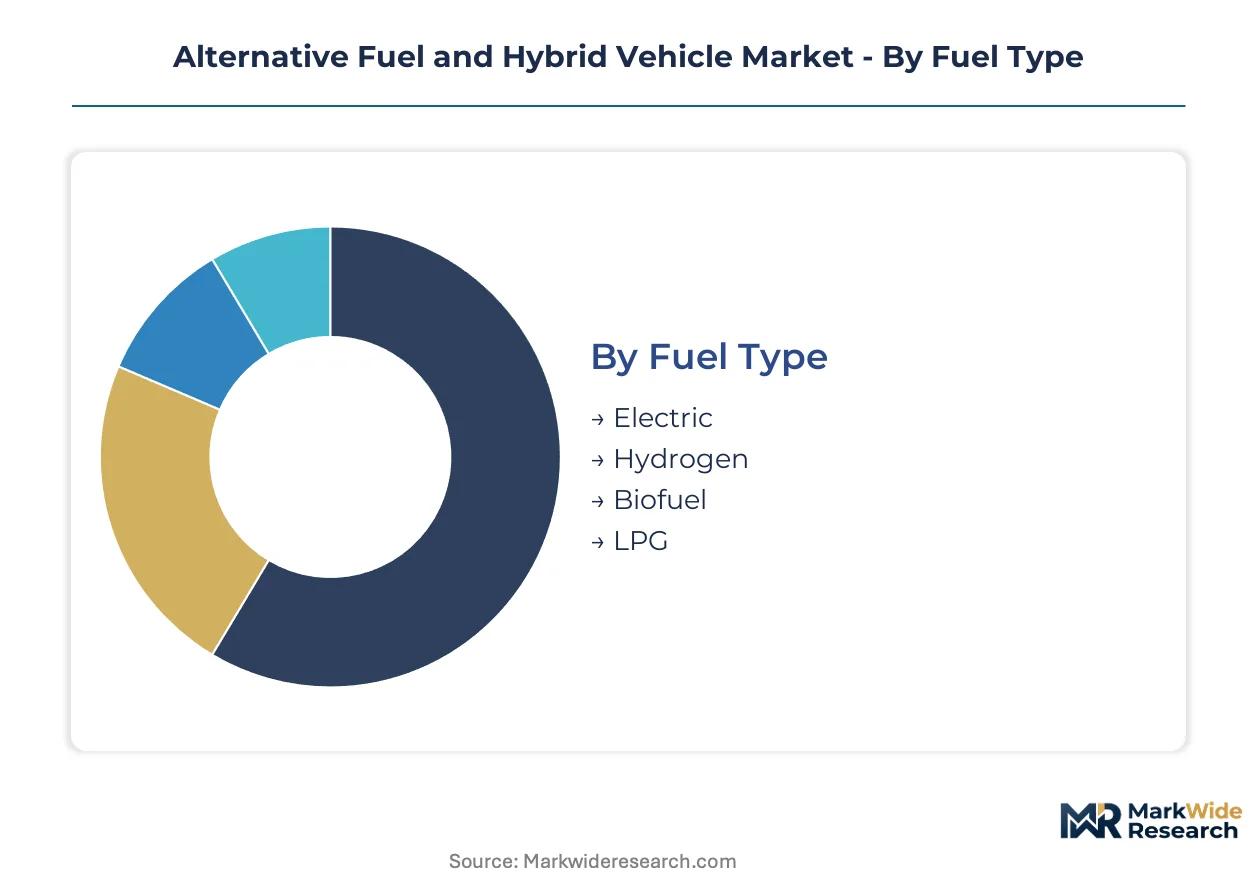
Segmentation in alternative fuel and hybrid vehicles reveals how powertrain diversity maps to distinct supply chain configurations, regulatory compliance pathways, and end-use economics. Manufacturers configure platform architectures around fuel type and technology combinations to capture fleet procurement cycles and consumer replacement demand across divergent infrastructure maturity levels.
Fuel Type:
Upstream material flows concentrate cathode chemical supply for electric and hydrogen pathways in Australia and Chile, while biofuel refining clusters around agricultural feedstock regions in Brazil and the US Midwest.
- Electric:Lithium-ion cells with nickel-manganese-cobalt or lithium-iron-phosphate cathodes dominate passenger car applications. China's Yangtze River Delta manufacturing corridor anchors global cell output, with BYD and CATL vertical integration capturing cost advantages against Western competitors.
- Hydrogen:Proton exchange membrane fuel cells convert compressed hydrogen to electricity at 60% system efficiency. Demand concentrates in California's heavy-duty trucking corridors and South Korea's Incheon bus fleet, where fast refueling offsets battery weight penalties in high-utilization duty cycles.
- Biofuel:Hydrotreated vegetable oil and ethanol blends drop into existing diesel and gasoline infrastructure. Brazilian sugarcane ethanol and US corn-based production supply regional markets with established agricultural processing capacity.
- LPG:Propane autogas conversions target commercial van operators in Turkey, South Korea, and Poland where refueling networks predate electric infrastructure buildout.
Today's leader: Electric. Tomorrow's challenger: Hydrogen.
Technology:
Cost tier differentiation separates premium battery-electric platforms from transitional plug-in architectures serving infrastructure-constrained markets.
- Battery Electric:Full-electric powertrains with 400-800V architectures enable DC fast charging at 150-350 kW. European CO2 fleet mandates and China's MIIT credit system accelerate OEM model proliferation in Germany, France, and China's tier-one cities.
- Plug-in Hybrid:Dual-mode systems with 15-25 kWh batteries provide 40-80 km electric range before combustion engagement. Japanese and European OEMs deploy PHEVs as compliance bridges where residential charging penetration lags urban density.
- Fuel Cell:Toyota Mirai and Hyundai Nexo architectures target markets with hydrogen station networks. South Korea's Ministry of Trade, Industry and Energy subsidies and California Air Resources Board incentives structure demand concentration.
- Range Extended Electric:Small combustion engines function as onboard generators, eliminating range anxiety without mechanical drivetrain complexity. BMW i3 REx and Nissan e-Power systems serve European and Japanese customers with mixed urban-highway usage patterns.
Premium tier: Battery Electric. Bridge technology: Plug-in Hybrid.
Vehicle Category:
Application-specific duty cycles determine powertrain sizing, thermal management requirements, and total cost of ownership calculations across procurement segments.
- Passenger Cars:Compact to midsize sedans and SUVs carry 50-100 kWh battery packs for 300-600 km range certification. Tesla's Shanghai Gigafactory and BYD's Shenzhen operations anchor volume concentration in China's consumer market.
- Light Trucks:Pickup configurations with 200+ kWh options target North American fleet operators in Texas, Michigan, and California commercial corridors. Ford F-150 Lightning and Rivian R1T platforms compete on towing capacity and worksite power export features.
- Buses:Single-deck urban transit vehicles with 250-350 kWh capacity enable 200+ km daily cycles. Shenzhen's complete fleet electrification and Santiago's Transantiago procurement demonstrate municipal-scale deployment feasibility.
- Vans:Last-mile delivery configurations with 40-80 kWh packs optimize cargo volume against battery intrusion. Amazon's Rivian order and Deutsche Post DHL's StreetScooter production in Germany reshape urban logistics procurement.
Volume concentration: Passenger Cars. Fastest expansion: Light Trucks.
Drive Train:
Customer type preferences for traction capability and packaging efficiency differentiate all-wheel traction from front-wheel economy configurations.
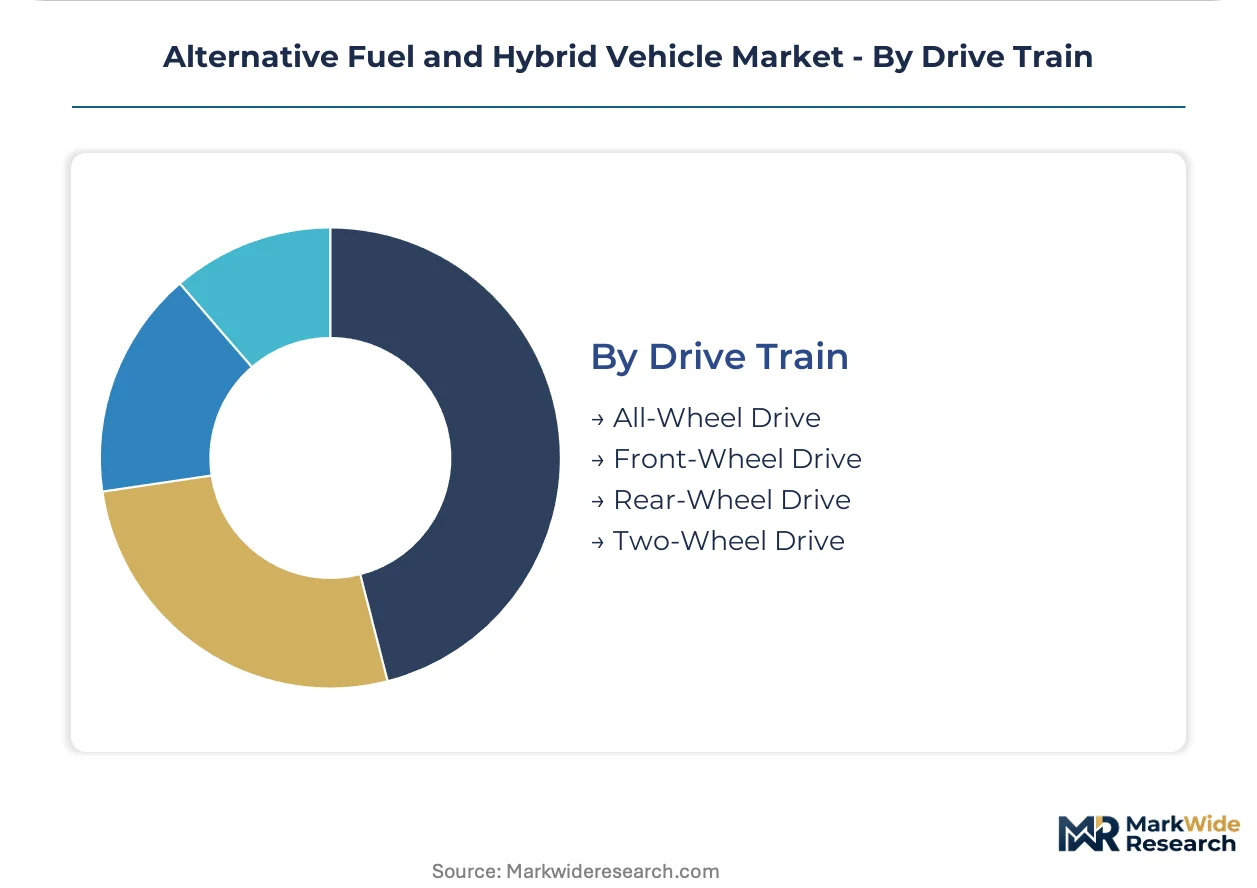
- All-Wheel Drive:Dual-motor or quad-motor layouts deliver torque vectoring and off-road capability. Premium SUV segments in Norway, Switzerland, and Colorado mountain markets specify AWD for snow traction and trail access.
- Front-Wheel Drive:Single-motor packaging maximizes cabin space in compact urban vehicles. European A-segment and Japanese kei-car regulations favor FWD efficiency in congested city environments.
- Rear-Wheel Drive:Performance-oriented layouts with balanced weight distribution target enthusiast segments. BMW and Porsche electric architectures preserve brand-specific handling characteristics.
- Two-Wheel Drive:Selectable configurations allow driver-controlled traction mode switching. Commercial operators in variable terrain markets specify 2WD/4WD toggle for fuel economy optimization.
Mainstream default: Front-Wheel Drive. Premium specification: All-Wheel Drive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta manufacturing corridor anchors global battery-electric vehicle production, with BYD and Tesla Shanghai operations concentrating cathode material refining, cell fabrication, and final assembly within a 300-kilometer radius.
United States
Fleet operators in Texas, Michigan, and California commercial corridors accelerate battery-electric truck procurement as total cost of ownership advantages widen against diesel. EPA tailpipe emission standards and California Air Resources Board zero-emission vehicle mandates shape product planning timelines for manufacturers. Detroit's automotive engineering base and Austin's emerging electric vehicle manufacturing cluster host powertrain development and battery pack assembly operations.
Germany
Logistics operators in the Ruhr industrial corridor consolidate fleet-level purchasing decisions for battery-electric vans and light trucks. EU CO2 performance standards and Euro 7 pollutant limits accelerate powertrain electrification across passenger car lineups. Stuttgart's engineering ecosystem and Munich's automotive technology corridor concentrate OEM headquarters and tier-1 supplier development centers.
Japan
Domestic fleet operators and consumer buyers sustain demand for hybrid architectures where residential charging penetration lags urban density. METI energy policy frameworks and carbon neutrality targets guide automotive manufacturer electrification roadmaps. Toyota City and Nagoya's Chubu industrial region anchor hybrid system manufacturing and fuel cell stack development facilities.
South Korea
Incheon's municipal bus fleet and Seoul Capital Area logistics operators deploy hydrogen fuel cell vehicles where fast refueling offsets battery weight penalties. Ministry of Trade, Industry and Energy subsidies structure demand concentration for fuel cell passenger cars and commercial vehicles. Ulsan's petrochemical-industrial complex and Gwangju's emerging battery manufacturing base support alternative fuel vehicle component supply chains.
India
State transit authorities in Gujarat and Tamil Nadu pilot battery-electric bus procurement under national clean mobility directives. PLI scheme for advanced chemistry cell manufacturing attracts domestic conglomerates and foreign cell manufacturers to establish gigafactory operations. Ahmedabad's automotive component ecosystem and Chennai's vehicle manufacturing corridor concentrate electric two-wheeler and three-wheeler production.
Alternative Fuel and Hybrid Vehicle Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent electrification spaces through platform diversification and energy service integration. Market structure consolidates around integrated powertrain manufacturers with captive battery supply, while specialist component suppliers occupy fragmented niches in charging hardware and thermal management. Three archetypes dominate: vertically integrated cell-to-vehicle producers, flexible-platform OEMs accommodating multiple electrified configurations, and energy-service providers monetizing battery assets beyond mobility. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with manufacturers securing cathode material offtake agreements and joint-venture cell production to reduce supply vulnerability.
Within the integrated producer archetype, Tesla Inc. and BYD Company Ltd. exemplify contrasting geographic footprints—Palo Alto-based and Shenzhen-based respectively—each representing scale-driven manufacturing models with upstream control over critical cell chemistry. Toyota Motor Corporation occupies a distinct position as the hybrid-system specialist, its two-decade Prius-series refinement exemplifying transitional technology persistence where full electrification faces infrastructure constraints. These three entities anchor competitive dynamics across battery-electric, plug-in hybrid, and fuel cell vectors without exclusive segment lock-in.
| Leading Market Players |
|---|
| Tesla Inc. |
| BYD Company Ltd. |
| Toyota Motor Corporation |
| Volkswagen AG |
| Ford Motor Company |
| General Motors Company |
| BMW AG |
| Honda Motor Co., Ltd. |
| Daimler AG |
| Others |
Supply Flow & Price Mechanics
Fleet procurement offices at municipal transit authorities and commercial logistics operators concentrate purchasing power, compressing contract margins for battery-electric bus and light truck manufacturers through competitive tender processes and total cost of ownership benchmarking against diesel equivalents.
Pricing Analysis
Input-cost pass-through from cathode material volatility on the London Metal Exchange dominates contract negotiations between cell manufacturers and automotive OEMs. Three-tier pricing structure across premium, standard, and economy levels separates nickel-manganese-cobalt formulations from lithium-iron-phosphate alternatives and entry-level LPG conversions. Pricing pressure stems from semiconductor supply concentration at Taiwan-based foundries for power electronics. Small logistics operators exhibit highest price sensitivity, while premium SUV segments absorb technology premiums for all-wheel-drive electric architectures.
Supply Chain Analysis
Workforce availability for electrochemical engineering talent constrains cell production expansion in Germany's Stuttgart corridor and South Korea's Gwangju battery manufacturing base. Supply concentrates in China's Yangtze River Delta, South Korea's industrial southeast, and Japan's Nagoya region for cathode active materials, separator films, and electrolyte formulations. Raw material dependencies draw from Australia's spodumene concentrate and Chile's lithium brine extraction operations. Single-source vulnerability for advanced node semiconductor production at Taiwan-based foundries threatens inverter and battery management system supply. Distribution runs through OEM captive assembly networks and tier-1 supplier direct shipment to vehicle plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in alternative fuel and hybrid vehicles rests on cathode chemistry cost-down curves and premium-tier battery-electric platform proliferation in European and Chinese passenger car segments.
For Market Incumbents: Deepen backward integration into lithium refining and cathode precursor manufacturing to offset nickel and cobalt price volatility exposure. Secure long-term offtake agreements with Australian spodumene and Chilean brine producers before competitor lock-up. Defend against emerging Chinese cell-to-vehicle specialists by accelerating solid-state battery qualification timelines. For New Entrants and Emerging Players: Capture white-space in India's Gujarat and Tamil Nadu gigafactory zones under PLI scheme incentives for advanced chemistry cell manufacturing. Target hydrogen fuel cell stack assembly for California heavy-duty trucking corridors where battery weight penalties limit payload capacity. Pursue battery-as-a-service subscription models to reduce upfront capital barriers for small commercial fleet operators. For Investors and Strategic Acquirers: Energy majors and utility operators are the most active acquirers in this space, seeking vehicle-to-grid integration capabilities and stationary storage monetization. Five-to-ten year viability hinges on solid-state electrolyte commercialization and thermal management IP consolidation. Watch for cathode material cost volatility spikes as inflection indicators for margin compression cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and BYD cell offtake contracts anchor Tesla Shanghai and Ford Lightning production schedules. |
| Backward Integration | Upstream control over lithium refining secures cost position against London Metal Exchange volatility. |
| Platform Standardization | BMW flexible architectures accommodate battery, fuel cell, and hybrid configurations within common vehicle structures. |
| Charging Infrastructure Partnership | Electrify America and Ionity networks reduce range anxiety barriers for premium battery-electric adoption. |
| Software-Defined Vehicle Investment | Over-the-air update capabilities extend revenue capture beyond initial vehicle sale in Tesla and Mercedes-Benz lineups. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with OEM platform engineers, tier-1 supplier procurement leads, transit authority fleet managers, and charging infrastructure operators. Secondary validation draws from EPA tailpipe emission filings, EU CO2 performance standard compliance data, China MIIT new energy vehicle credit disclosures, and IHS Markit vehicle registration databases. Bottom-up cell production capacity modeling triangulates against top-down OEM electrification spend forecasts.
Rate-of-change decomposition separates volume growth from mix-shift effects and pricing evolution across the projection horizon. Segmentation dimensions include fuel type, propulsion architecture, vehicle category, and regional regulatory cluster. CAGRs derive from production capacity buildout schedules, fleet replacement cycles, and compliance threshold phase-in trajectories. Forecast inputs incorporate lithium carbonate spot price trajectories and semiconductor lead time normalization assumptions.
Raw material supply disruption, regulatory stringency divergence across EPA, EU, and MIIT frameworks, and solid-state battery timeline slippage are the dominant revision risks. Forecasts reflect assumptions about cathode chemistry cost curves and charging infrastructure buildout rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market
Alternative Fuel Vehicles
Air Powered Vehicle Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
Ethanol Vehicle Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
North America Hydrogen Powered Tractor Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
Automotive Alternative Fuel Vehicle Market