
 Asia-Pacific Fuel Cell Vehicles Market | 2026-2036
Asia-Pacific Fuel Cell Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fuel Cell Vehicles Market Outlook
The dealership network across East Asia is fragmenting as direct sales and hybrid distribution models gain traction among fuel cell vehicle makers. Toyota Motor Corporation leverages its captive retail footprint to control buyer touchpoints in Japan and select Southeast Asian markets. Hyundai Motor Company anchors its position through dedicated hydrogen showrooms and fleet-service partnerships in South Korea. Tata Motors Limited competes via government-contract channels and state-backed pilot programs in India.
Asia-Pacific fuel cell vehicles convert hydrogen into electricity through electrochemical reaction, typically employing proton exchange membrane stacks operating at 60-80°C with power densities exceeding 2.5 kW/liter for automotive use. These systems serve commercial and public transport applications where battery-electric range and refueling time constraints persist. Passenger cars dominate current revenue pools, though buses and trucks represent the fastest-expanding vehicle type as municipal transit authorities and logistics operators pursue zero-emission mandates. Proton exchange membrane technology leads deployment due to its cold-start reliability and automotive packaging efficiency, while solid oxide systems occupy niche stationary-range-extender roles.
Japan's METI enforces hydrogen safety codes under the High Pressure Gas Safety Act, while China's MIIT administers NEV subsidy tiers that include fuel cell vehicles in designated demonstration zones. South Korea's Ministry of Trade, Industry and Energy coordinates the Hydrogen Economy Policy with KGS certification requirements for onboard storage tanks. Stakeholders must track how subsidy phase-out schedules interact with infrastructure build-out timelines across these jurisdictions.
Market Dynamics
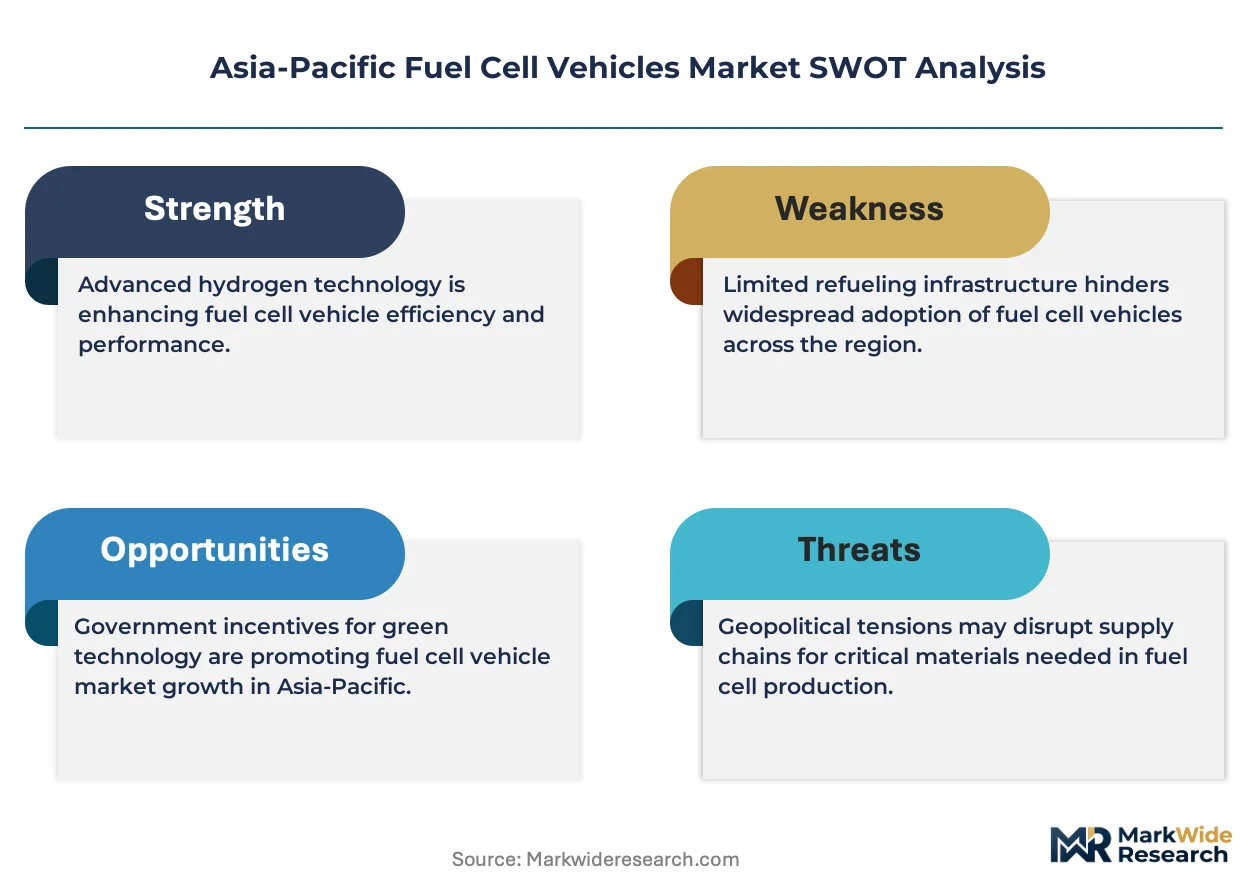
Government hydrogen roadmaps across East Asia are compressing infrastructure deployment timelines faster than vehicle cost curves can decline, creating a structural mismatch between refueling network availability and fleet operator readiness.
Growth Catalysts
- Japan's METI hydrogen roadmap:Mandates 1,000 hydrogen stations nationwide by 2030, directly expanding addressable fleet territory for commercial operators.
- Commercial logistics:Heavy-duty trucking corridors between Shanghai and Ningbo now prioritize fuel cell tractors for 500km+ routes where battery weight penalties erode payload economics.
- Proton exchange membrane cold-start reliability:Enables deployment in northern Chinese provinces where winter temperatures drop below -20°C, eliminating battery-electric operational dead zones.
Market Restraints
- Platinum loading requirements:Fuel cell stack catalysts still require 20-30 grams of platinum per vehicle, tying production costs to volatile precious metal markets.
- Electrolyzer manufacturing concentration:Over 60% of global proton exchange membrane electrolyzer capacity sits in Chinese and South Korean facilities, creating single-source vulnerability for hydrogen supply chains.
- High Pressure Gas Safety Act compliance:Japan's tank certification protocols add 18-24 months to vehicle homologation timelines versus conventional powertrains.
Strategic Opportunities
- India's National Hydrogen Mission:Green hydrogen production subsidies open fleet pilot opportunities in Gujarat and Tamil Nadu industrial corridors.
- Maritime port drayage:Busan and Shanghai container terminals are testing fuel cell yard tractors for 24-hour continuous operation cycles.
- Vehicle-to-grid integration:Solid oxide range extenders paired with battery buffers enable bidirectional power export for commercial microgrids.
Industry Challenges
- Hydrogen storage tank certification:KGS and Chinese GB standards diverge on composite overwrap testing protocols, forcing dual homologation expenses for cross-border fleet operators.
- Station maintenance technician scarcity:High-pressure cryogenic systems require specialized training that existing automotive service networks lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fuel Cell Vehicles Market |
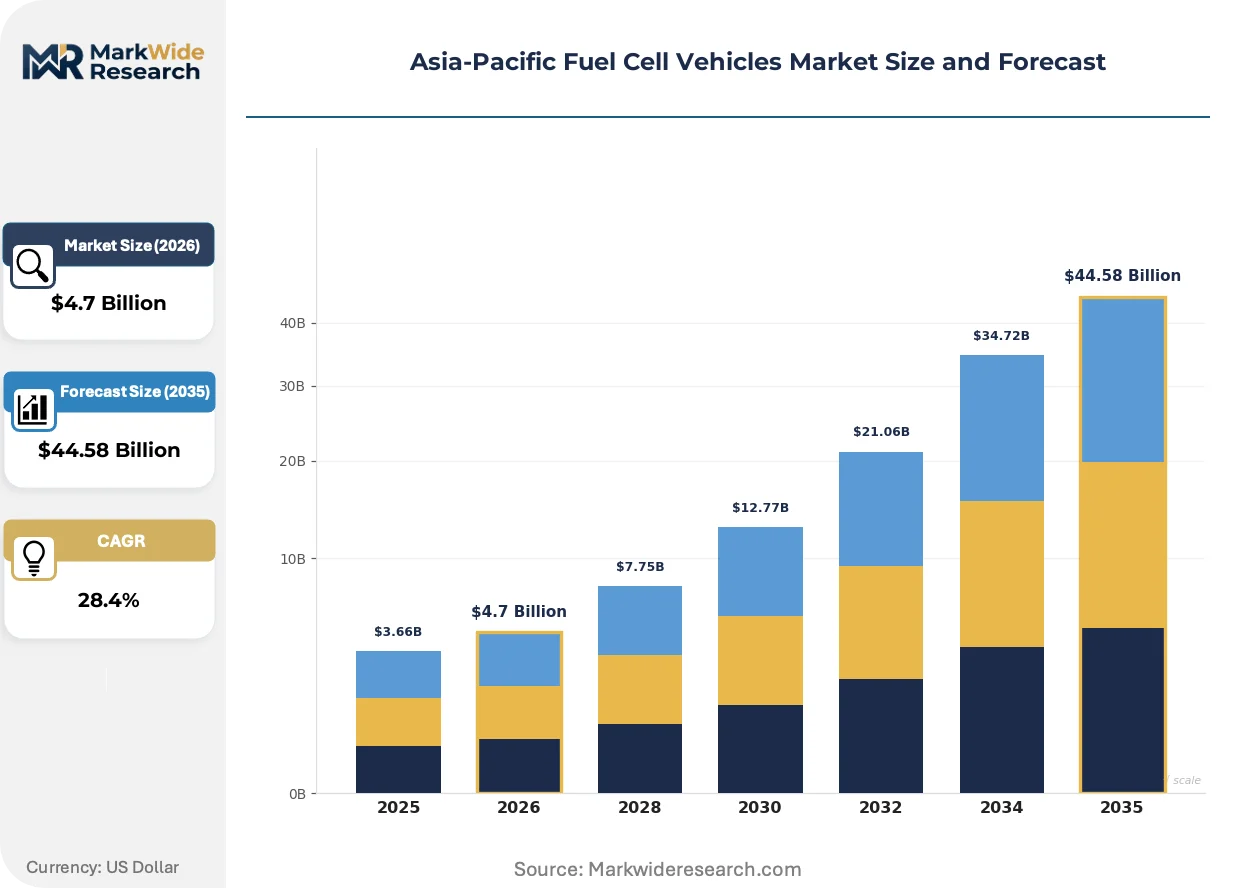
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $44.58 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Buses, Trucks, Two-Wheelers Technology: Proton Exchange Membrane, Solid Oxide, Alkaline, Direct Methanol End User: Public Transport, Commercial Fleets, Government, Private Owners Distribution Channel: Direct Sales, Online Platforms, Dealerships, Hybrid Models |
| Companies Covered | Toyota Motor Corporation, Hyundai Motor Company, Honda Motor Co., Ltd., Mitsubishi Motors Corporation, Nissan Motor Corporation, General Motors, Mercedes-Benz AG, Tata Motors Limited, Zhejiang Geely Holding Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fuel Cell Vehicles Market Strategic Shifts
Electrochemical system architecture is undergoing rapid compression as solid oxide and proton exchange membrane technologies converge toward hybrid configurations that optimize thermal efficiency against packaging constraints.
Membrane electrode assembly manufacturing is collapsing from batch-based screen printing toward continuous roll-to-roll coating processes. South Korean stack producers are adopting this equipment at commercial scale. The shift is collapsing unit production costs by eliminating solvent recovery steps and reducing catalyst waste from 40% to under 8%.
South Korea's Hydrogen Economy Policy now mandates that all new hydrogen stations include 700-bar dispensing capability, phasing out 350-bar infrastructure. This industrial consequence forces fleet operators to specify 700-bar onboard storage or face range penalties. Heavy-duty truck segments are responding by consolidating procurement around 70kg composite tank configurations that maximize single-fill range.
Commercial fleet procurement is consolidating around total-cost-of-ownership contracts that bundle vehicle lease, hydrogen supply, and maintenance into per-kilometer rates. Direct manufacturer-fleet relationships are displacing traditional dealer intermediaries in Japan and South Korea. This pattern is most visible among logistics operators running fixed-route hub-and-spoke networks where fuel consumption is predictable and hydrogen station locations are contractually secured.
Asia-Pacific Fuel Cell Vehicles Market Segmentation
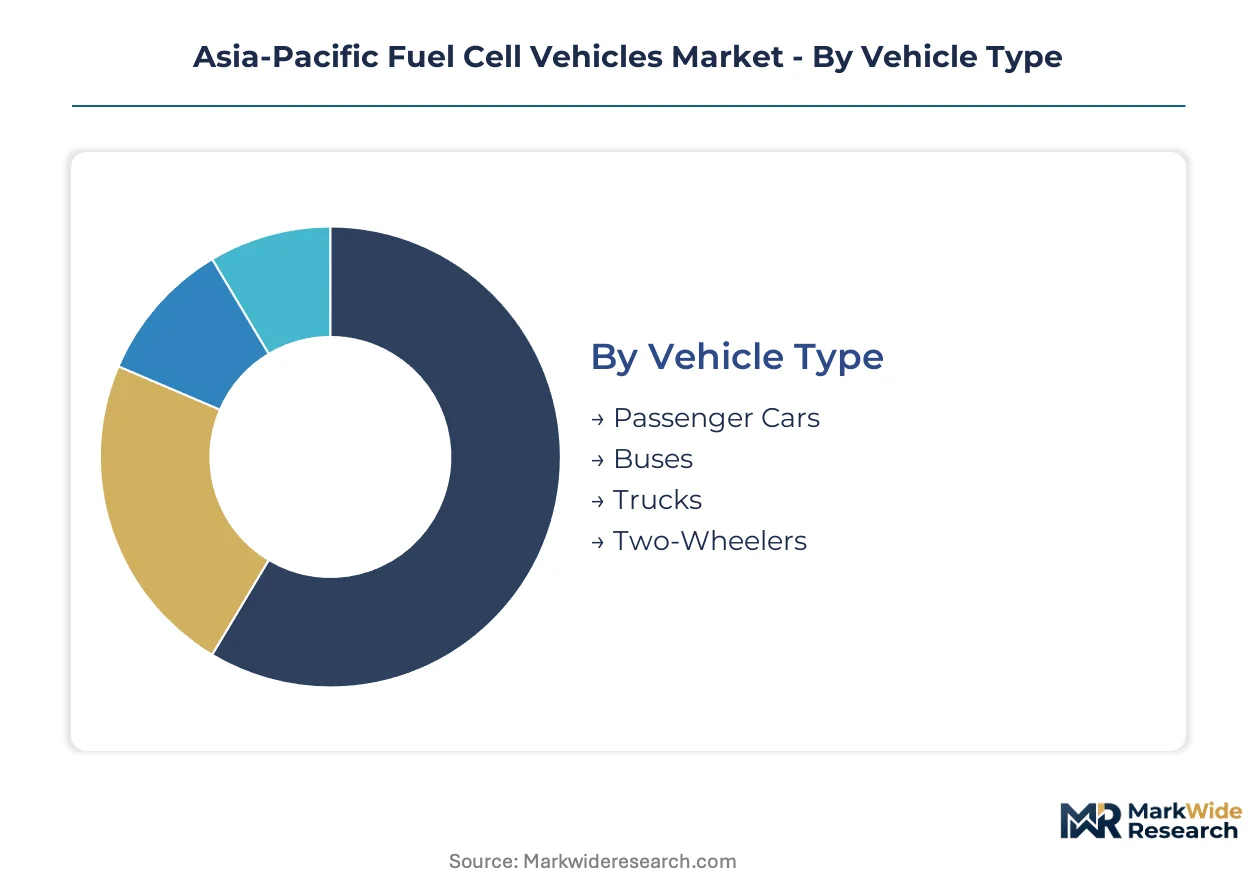
Segmentation in the Asia-Pacific fuel cell vehicles market reveals divergent service intensity requirements across vehicle classes and procurement channels. Each category carries distinct margin profiles and aftermarket dependencies that shape manufacturer channel strategies.
Vehicle Type:
After-sales service intensity escalates sharply with vehicle mass and duty cycle severity, driving divergent warranty structures across this category.
- Passenger Cars:Compact proton exchange membrane stacks rated 80-100kW power output serve urban commuting applications with standardized 5-year stack warranties. Demand concentrates in Tokyo, Seoul, and Shanghai where municipal parking subsidies offset hydrogen station scarcity. Private owners prioritize cold-start reliability over range optimization.
- Trucks:Heavy-duty configurations deploy 200kW+ multi-stack architectures with 700-bar storage for 800km corridor haulage. Fleet operators along China's Beijing-Shanghai expressway now specify these for payload-critical logistics where battery weight penalties exceed 15% cargo loss.
- Buses:Transit authorities in South Korea's Gyeonggi Province and Japan's Kansai region deploy 60-80 passenger articulated units with depot-based overnight refueling protocols.
- Two-Wheelers:Niche deployments in Indian industrial townships target last-mile delivery where hydrogen cylinder exchange networks outperform charging infrastructure buildout costs.
Passenger cars hold the largest share; momentum sits with trucks as logistics electrification deadlines tighten across East Asian manufacturing corridors.
Technology:
Stack architecture determines thermal management complexity and thus field service technician certification requirements across deployment zones.
- Proton Exchange Membrane:Automotive-grade membranes operate at 60-80°C with platinum catalyst loadings of 0.3-0.4g/kW. South Korean stack producers achieve power densities above 2.5kW/liter through thin-film electrode advancement. Cold-start capability below -25°C enables Heilongjiang and Hokkaido winter deployments where alkaline systems fail.
- Solid Oxide:High-temperature ceramic electrolyte systems at 600-800°C serve stationary-range-extender roles for commercial microgrids. Japanese manufacturers integrate these with battery buffers for vehicle-to-grid export in Osaka industrial parks.
- Alkaline:Liquid electrolyte configurations dominate early-stage Indian pilot programs where cost sensitivity outweighs packaging efficiency requirements.
- Direct Methanol:Methanol reformer-fed systems occupy material handling equipment niches in Southeast Asian ports where liquid fuel logistics precede hydrogen infrastructure.
Proton exchange membrane dominates installed capacity; solid oxide is climbing the fastest as hybrid architectures gain traction among commercial fleet specifiers.
End User:
Procurement scale and contract duration vary dramatically by buyer type, dictating manufacturer sales force specialization.
- Commercial Fleets:Logistics operators negotiate total-cost-of-ownership contracts bundling vehicle lease, hydrogen supply, and maintenance into per-kilometer rates. China's SF Express and South Korea's CJ Logistics now operate 500+ unit fuel cell tractor commitments with station-location contractual guarantees.
- Public Transport:Municipal transit authorities issue 10-year fleet replacement tenders with localized content requirements. Tokyo Metro and Seoul Metro specify domestic stack assembly thresholds in procurement scoring.
- Government:Central procurement pools in China's demonstration zones distribute vehicles to state-owned enterprises under MIIT subsidy tiers.
- Private Owners:Early adopter households in Japan's Aichi Prefecture access Toyota's Mirai lease programs with hydrogen fuel card subsidies.
Commercial fleets command the deepest order backlogs; public transport is gaining share fastest as zero-emission mandates harden across metropolitan jurisdictions.
Distribution Channel:
Channel economics shift with fleet size thresholds, compressing traditional dealer margins above 50-unit annual procurement volumes.
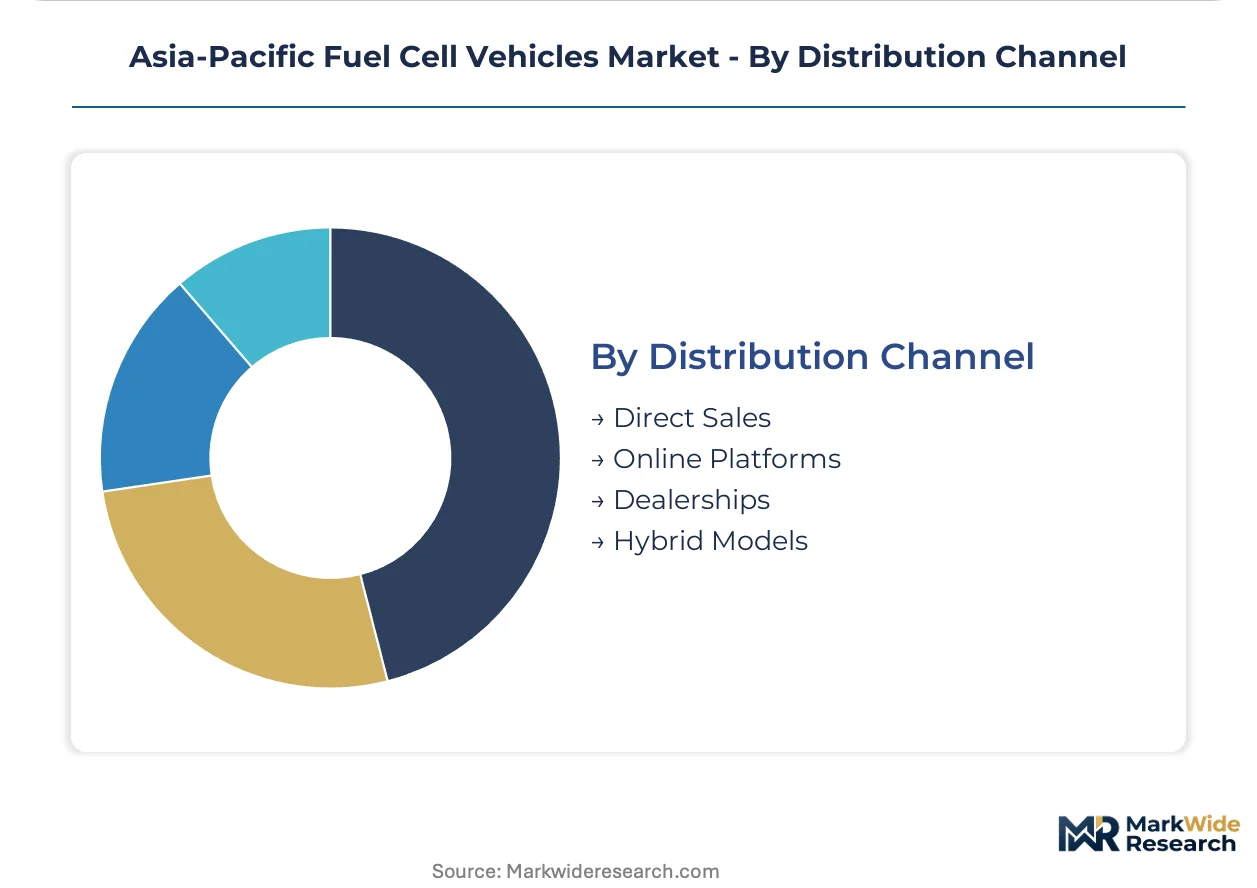
- Direct Sales:Manufacturers maintain captive account teams for logistics operators exceeding 100-unit annual procurement. Hyundai Motor Company anchors South Korean market position through dedicated hydrogen showrooms with on-site technical consultation.
- Hybrid Models:Blended arrangements combine manufacturer fleet pricing with local service subcontracting. Toyota leverages existing retail footprint for private buyer touchpoints while routing commercial inquiries to direct sales divisions.
- Dealerships:Traditional automotive retail networks retain passenger car volume in Japan's prefectural capitals where hydrogen station density supports consumer confidence.
- Online Platforms:Digital configuration tools serve two-wheeler and light commercial segments in India's Gujarat industrial corridors where pilot program eligibility screening occurs through government portals.
Direct sales holds the largest share; hybrid models are expanding most quickly as manufacturers balance control with service coverage requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands pricing premiums through captive retail networks, while Chinese fleet operators extract volume discounts via direct manufacturer negotiations. South Korea occupies a middle tier with hybrid distribution models. Infrastructure deployment timelines diverge sharply across these three markets.
Japan
Tokyo's metropolitan transit authority operates the world's densest fuel cell bus corridor, with 100+ units serving the waterfront district. METI's hydrogen roadmap mandates 1,000 stations nationwide by 2030, accelerating commercial fleet territory expansion. Aichi Prefecture's industrial belt hosts Toyota's captive leasing programs for early adopter households.
China
Heavy-duty logistics corridors between Shanghai and Ningbo prioritize fuel cell tractors for 500km+ routes where battery weight erodes payload economics. MIIT administers NEV subsidy tiers covering fuel cell vehicles in designated demonstration zones. The Beijing-Tianjin-Hebei cluster concentrates state-owned enterprise procurement under central government pilot programs.
South Korea
CJ Logistics and other freight operators negotiate total-cost-of-ownership contracts bundling vehicle lease, hydrogen supply, and maintenance into per-kilometer rates. The Ministry of Trade, Industry and Energy coordinates hydrogen economy policy with KGS certification requirements for onboard storage tanks. Gyeonggi Province's transit authorities deploy 60-80 passenger articulated buses with depot-based overnight refueling.
India
Gujarat and Tamil Nadu industrial corridors attract green hydrogen production subsidies under the National Hydrogen Mission. The country's national automotive regulator oversees safety certification for pilot fleet deployments. Last-mile delivery operators in industrial townships test hydrogen cylinder exchange networks against charging infrastructure economics.
Australia
Mining haulage operators in Western Australia's Pilbara region pilot fuel cell trucks for 24-hour continuous duty cycles. State-level renewable hydrogen strategies support fleet trials in Queensland's heavy transport corridors. The country's national standards body develops certification protocols for high-pressure onboard storage systems.
Asia-Pacific Fuel Cell Vehicles Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in membrane electrode assembly and stack manufacturing. The vendor base concentrates around three to five integrated automotive groups with captive fuel cell development programs, while upstream suppliers fragment across catalyst, bipolar plate, and compressor subsystems. Two strategic archetypes dominate: vertically integrated vehicle manufacturers and specialized stack producers serving multiple OEMs. Capacity expansion and strategic partnerships constitute the primary competitive moves, with manufacturers securing hydrogen supply contracts ahead of vehicle delivery.
Among Japan-based automotive groups, Toyota Motor Corporation exemplifies the platform-integrator archetype through captive retail footprint control. Hyundai Motor Company anchors South Korean market position via dedicated hydrogen showrooms and fleet-service partnerships. Tata Motors Limited occupies a distinct tier within India's government-contract channel, representing state-backed pilot program participation.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Hyundai Motor Company |
| Honda Motor Co., Ltd. |
| Mitsubishi Motors Corporation |
| Nissan Motor Corporation |
| General Motors |
| Mercedes-Benz AG |
| Tata Motors Limited |
| Zhejiang Geely Holding Group |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Ningbo heavy-duty trucking corridor anchors cost dynamics across the Asia-Pacific fuel cell vehicles market, where platinum catalyst sourcing concentration in South Korean and Japanese refiners amplifies downstream price differentiation between fleet-scale contracts and configured-to-order heavy-duty tractors. This geographic sourcing pattern feeds directly into manufacturer pricing power, with captive hydrogen supply contracts enabling volume discounts that independent operators cannot access.
Pricing Analysis
Configured-to-order heavy-duty tractors command a substantial premium over standard passenger car configurations, with price differentiation driven by certification grade under KGS and Chinese GB tank standards alongside after-sales service bundling intensity. Three-tier pricing structure across premium fleet contracts, standard municipal procurement, and economy pilot program tiers stratifies the market, though cost compression in the economy tier is intensifying due to membrane electrode assembly manufacturing automation. Commercial fleet operators exhibit the lowest price sensitivity due to total-cost-of-ownership contract structures, while private buyers in Japan's prefectural markets remain highly responsive to hydrogen fuel card subsidy fluctuations.
Supply Chain Analysis
Extended payment terms from South Korean stack producers to Chinese bipolar plate fabricators illustrate how supplier-financing facilities lubricate working capital across the Asia-Pacific fuel cell vehicles supply chain. Manufacturing concentration in China, South Korea, and Japan for proton exchange membrane stacks, platinum catalyst deposition, and 700-bar composite tank winding creates single-source vulnerability for cross-border fleet operators. The supply chain draws from iridium and platinum group metal feedstocks alongside carbon fiber composite precursors, with tariff exposure on Japanese carbon fiber imports into China representing a structural risk. Distribution runs through direct manufacturer-fleet relationships for commercial volumes, supplemented by hybrid models for private buyer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific fuel cell vehicles market functions as a defensive-moat arena where regulatory entrenchment through hydrogen station deployment mandates creates substantial switching costs for fleet operators locked into long-term fuel supply contracts. This structural advantage favors incumbents with captive infrastructure relationships.
For Market Incumbents: Pre-empt emerging Chinese stack producers by securing exclusive hydrogen supply contracts along the Beijing-Shanghai expressway corridor before subsidy phase-outs consolidate procurement around domestic suppliers. Accelerate backward integration into membrane electrode assembly production to defend margins against catalyst cost volatility, while investing in KGS certification capabilities to maintain cross-border fleet operator access as Chinese GB standards diverge. For New Entrants and Emerging Players: India's Gujarat industrial corridor represents the most penetrable entry point, where green hydrogen production subsidies under the National Hydrogen Mission create fleet pilot opportunities with lower incumbent saturation than East Asian markets. Two-wheeler last-mile delivery in Tamil Nadu industrial townships offers a second white-space target, with hydrogen cylinder exchange networks outperforming charging infrastructure economics. A go-to-market angle through state government portal eligibility screening bypasses traditional dealer network requirements. For Investors and Strategic Acquirers: Specialized stack producers with multi-OEM supply relationships and proven KGS/GB dual certification capabilities represent the most attractive acquisition target archetype for portfolio exposure to hydrogen economy policy execution. Long-term viability hinges on sustained government station build-out commitments across the analysis window. The signal to monitor is fleet operator contract renewal rates as initial subsidy-backed leases expire, revealing true underlying demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrode Assembly Capacity Expansion | South Korean roll-to-roll coating adoption collapses unit costs and catalyst waste rates. |
| 700-Bar Infrastructure Partnership | South Korea's Hydrogen Economy Policy mandates force fleet storage specification consolidation. |
| Platinum Catalyst Supply Agreement | Long-term offtake contracts with Japanese refiners hedge against precious metal volatility. |
| Dual Certification Investment | Parallel KGS and Chinese GB homologation enables cross-border logistics operator procurement. |
| Total-Cost-of-Ownership Platform Launch | Per-kilometer bundling of vehicle lease, hydrogen supply, and maintenance displaces dealer intermediaries. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial fleet procurement managers, hydrogen station developers, membrane electrode assembly manufacturing directors, and METI policy implementation officers. Secondary validation drew from MIIT NEV subsidy tier documentation, KGS certification protocols, South Korean Hydrogen Economy Policy white papers, and vehicle registration databases across Japan, China, and South Korea. Bottom-up unit economics modeling and top-down policy impact assessment were triangulated to reconcile segment-level projections.
Calibration against historical fleet deployment trajectories in Japan's Aichi Prefecture and China's Beijing-Tianjin-Hebei cluster anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass vehicle class, propulsion architecture, procurement channel structure, and regional regulatory cluster. CAGRs were derived from installed base growth rates adjusted for station deployment timelines and subsidy phase-out schedules. Industry-specific forecast inputs included platinum loading reduction curves and 700-bar tank manufacturing yield improvements.
Macroeconomic conditions sit as an overlay; deviation in hydrogen production electrolyzer capital costs, renewable electricity pricing, or yen-won-yuan exchange volatility would shift the trajectory. Forecasts reflect documented assumptions regarding policy continuity and infrastructure build-out execution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Ethanol Vehicle Market
Alternative Fuel Vehicles
North America Hydrogen Powered Tractor Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Air Powered Vehicle Market
Alternative Fuel Vehicles
Japan Next Generation Vehicle Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Automotive Alternative Fuel Vehicle Market
Alternative Fuel Vehicles
Automotive Flex Fuel Engine Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Automotive Fuel Cell System Market
Alternative Fuel Vehicles
Zero Emission Trucks Market