
 UK Autonomous Navigation Market | 2026-2036
UK Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
UK Autonomous Navigation Market Insights
The UK Maritime and Coastguard Agency's updated autonomous shipping codes is hardening certification requirements for unmanned marine systems. BAE Systems leverages its naval heritage to dominate defence-oriented autonomous platforms. QinetiQ sustains research intensity through its Long Ashton robotics proving grounds. Thales UK anchors civilian port automation with its sensor fusion architectures.
Autonomous navigation denotes self-directed positional guidance systems integrating multi-sensor arrays, Kalman-filtered inertial measurement units, and real-time path-planning algorithms to execute trajectories without continuous human intervention. Lidar and radar fusion architectures currently lead deployment in marine vessel applications where all-weather reliability proves critical. Computer vision segments are gaining fastest in last-mile delivery robotics, though margin pools remain concentrated in GPS-IMU integration layers serving mining contractors and offshore platform operators.
The Maritime and Coastguard Agency, the Civil Aviation Authority, and the Health and Safety Executive collectively shape UK autonomous navigation through vessel certification rules, beyond-visual-line-of-sight drone permissions, and workplace robotics safety directives. These frameworks restrict market access for uncertified platforms while channelling R&D investment toward audit-ready system architectures. Stakeholders must monitor forthcoming updates to the UK Code of Practice for autonomous maritime systems, as these will determine which sensor configurations gain rapid operational approval.
Market Dynamics
The Maritime and Coastguard Agency's updated autonomous shipping codes is compressing certification timelines while hardening sensor fusion requirements, forcing platform developers to front-load compliance investment ahead of revenue deployment.
Growth Catalysts
- Plymouth-Southampton port clustering:Maritime logistics operators are consolidating unmanned surface vessel trials within these twin hubs, creating dense testing ecosystems that accelerate iteration cycles.
- Offshore platform operator demand:GPS-IMU integration layers serving North Sea energy infrastructure are pulling autonomous positioning systems into hazardous-environment deployments.
- Beyond-visual-line-of-sight permissions:The Civil Aviation Authority's expanded drone operating envelopes are unlocking last-mile delivery robotics trials in Scottish Highlands corridors.
Market Restraints
- Lidar sensor supply concentration:Solid-state lidar fabrication capacity concentrates among East Asian contract manufacturers, exposing UK platform builders to input bottlenecks.
- Kalman-filter calibration complexity:Inertial measurement unit drift correction requires specialized marine engineering talent that remains scarce outside defence-adjacent labour pools.
- Workplace robotics safety directive friction:Health and Safety Executive inspection protocols for autonomous systems create deployment delays that extend commissioning timelines.
Strategic Opportunities
- Welsh coastal surveillance gaps:Cardiff and Milford Haven authorities lack persistent unmanned maritime patrol coverage, creating whitespace for long-endurance surface vessel operators.
- Sensor fusion architecture licensing:Civilian port automation vendors can monetize software stacks developed for Southampton container terminals through white-label arrangements.
- Computer vision convergence with thermal imaging:All-weather navigation systems combining optical and infrared arrays address fog-bound North Sea operational windows that radar-only systems cannot penetrate.
Industry Challenges
- Marine autonomy software certification:The Maritime and Coastguard Agency's code of practice lacks granular test-case specifications, forcing developers to absorb interpretive risk.
- Legacy vessel integration:Retrofitting autonomous navigation stacks onto existing fleet assets requires hull-by-hull sensor placement validation that fragments deployment economics.
- Cross-regulator coordination gaps:Jurisdictional ambiguity between the Maritime and Coastguard Agency and Civil Aviation Authority on hybrid air-sea platforms stalls multi-domain system approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Autonomous Navigation Market |
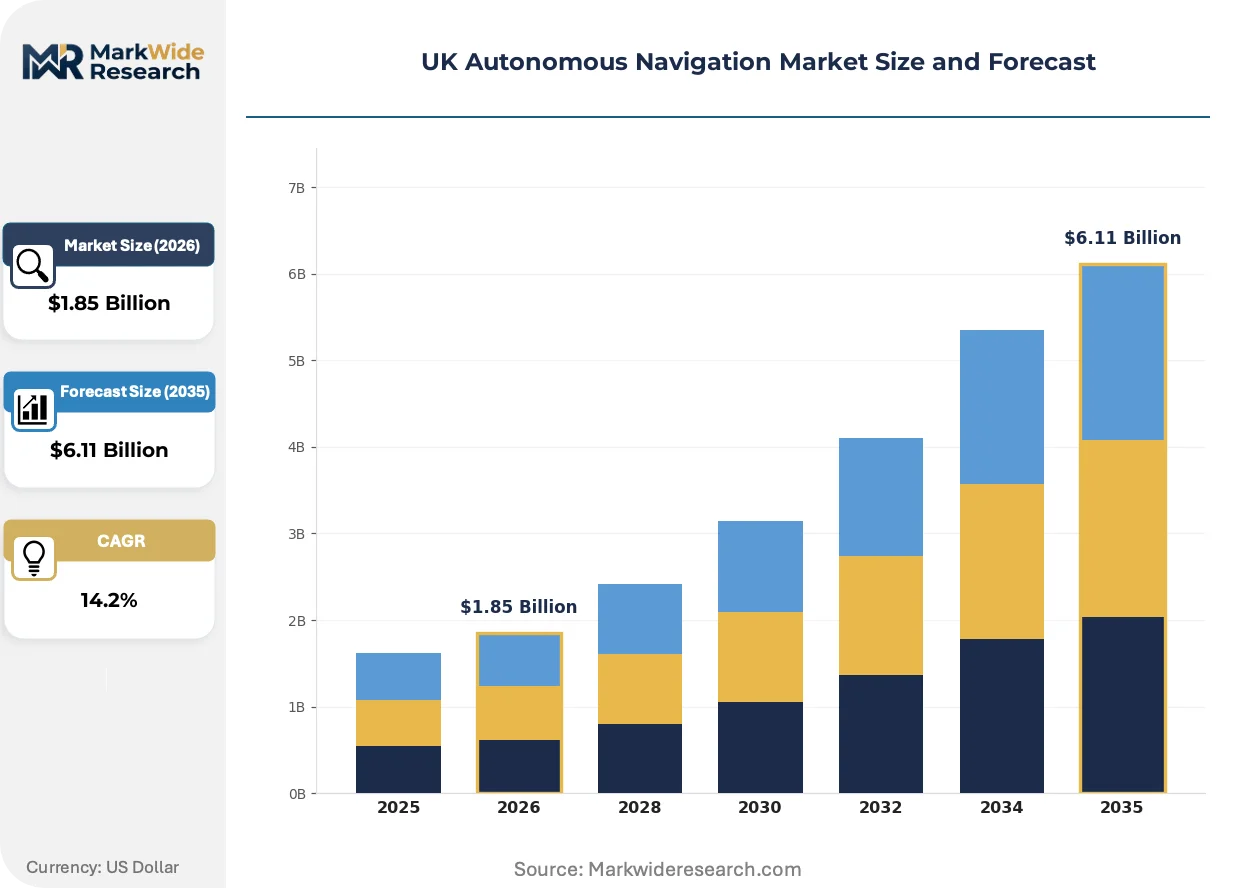
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.11 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Lidar, Radar, Computer Vision, Ultrasonic Sensors, GPS, IMU Application: Last-Mile Delivery, Industrial Automation, Agriculture Equipment, Unmanned Aerial Vehicles, Mining Operations, Marine Vessels Deployment Scenario: Urban Infrastructure, Warehouse Facilities, Farmland Areas, Offshore Platforms, Construction Sites, Ports End User Type: Logistics Providers, Manufacturing Plants, Farm Operators, Mining Contractors, Shipping Companies, Survey Firms |
| Companies Covered | BAE Systems, Thales UK, QinetiQ, Leonardo UK, MBDA UK, ASV Global, MSubs Ltd, Babcock International, Atlas Elektronik UK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Autonomous Navigation Market Trends and Innovations
Multi-sensor fusion architectures are displacing single-modality navigation systems across UK maritime and aerial autonomous platforms, with regulatory pressure and operational reliability demands converging to favor redundant perception stacks.
Lidar-radar fusion architectures are integrating real-time point-cloud generation with Doppler velocity mapping to deliver all-weather positional awareness for unmanned surface vessels. Offshore platform operators in the North Sea are adopting these stacks fastest, driven by helicopter-deck approach requirements in reduced-visibility conditions. This convergence is integrating previously siloed sensor procurement budgets into unified perception system contracts.
The Maritime and Coastguard Agency's updated code of practice for autonomous maritime systems is mandating fail-operational redundancy for navigation computers on vessels above 24 metres. Shipyards in Plymouth are reconfiguring build specifications to accommodate dual-inertial-measurement-unit architectures as standard fit. Classification societies are responding by developing unified type-approval protocols that span UK and Norwegian flag registries.
Scottish Highlands logistics operators are unbundling autonomous drone services from traditional freight contracts, purchasing flight-hours rather than aircraft. Highland Council procurement frameworks now specify outcome-based delivery windows rather than equipment ownership. This purchasing pivot is most visible in medical supply chains serving Isle of Skye and Outer Hebrides communities, where weather cancellation rates drive preference for autonomous reliability guarantees over conventional charter availability.
UK Autonomous Navigation Market Segmentation
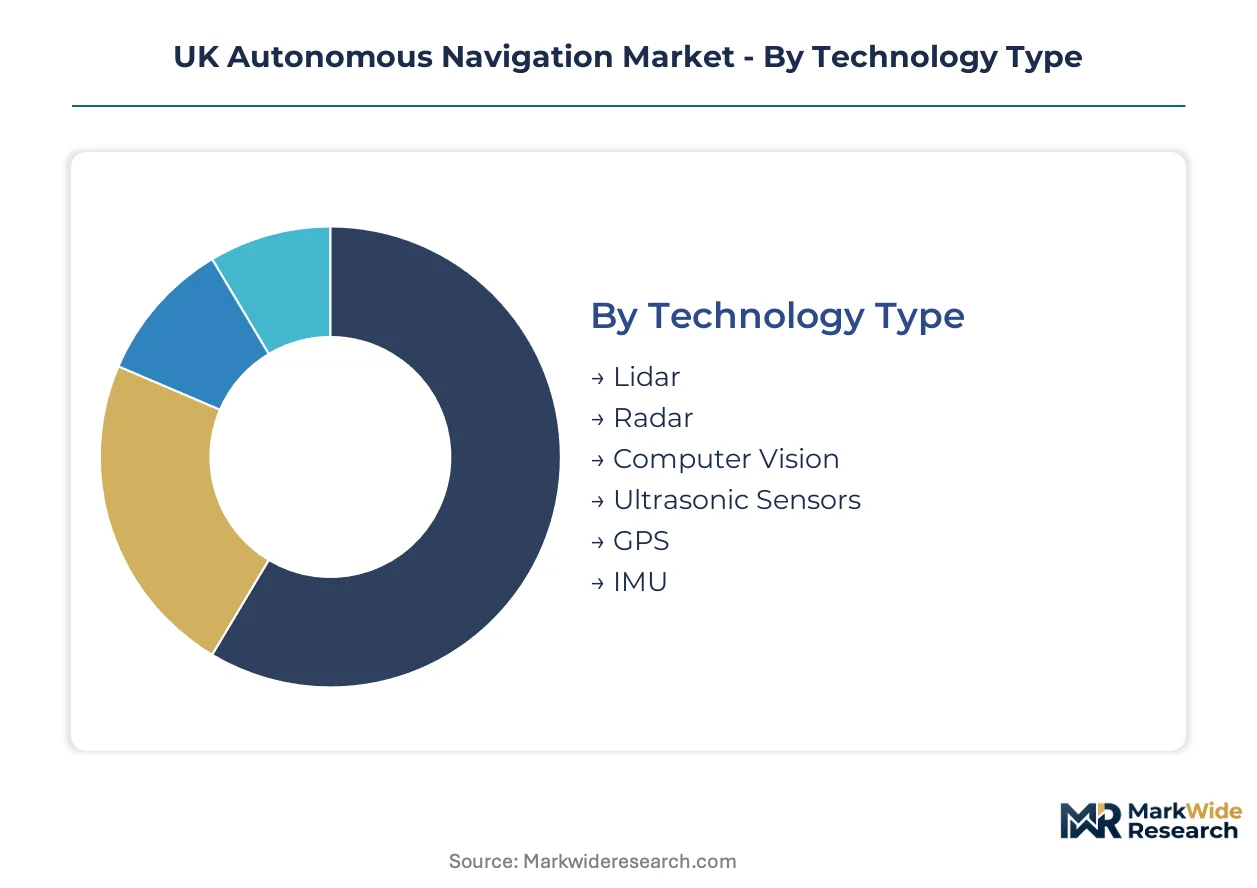
Autonomous navigation platforms fragment across sensor modalities, operational domains, and customer procurement patterns. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that reshape vendor go-to-market priorities.
Technology Type:
Sensor fabrication capacity concentrates among East Asian contract manufacturers, exposing UK platform builders to input bottlenecks and qualification delays.
- Lidar:Solid-state beam steering arrays generate dense point clouds for obstacle detection. Plymouth-Southampton port clusters deploy these units for unmanned surface vessel berthing operations where centimetre-scale precision proves mandatory.
- Radar:Doppler velocity mapping penetrates precipitation and sea spray that blind optical systems. North Sea offshore platform operators specify radar-primary architectures for helicopter deck approach in reduced-visibility windows.
- Computer Vision:Convolutional neural networks process optical feeds for last-mile delivery robotics in Scottish Highlands corridors.
- Ultrasonic Sensors:Short-range proximity detection serves warehouse automated guided vehicles with sub-metre obstacle clearance requirements.
- GPS:Multi-constellation receivers provide absolute positioning for open-field agriculture equipment across East Anglia farmland.
- IMU:Kalman-filtered inertial measurement units bridge satellite denial zones in subterranean mining operations.
Lidar and radar fusion architectures absorb the bulk of installed capacity in marine applications; computer vision is expanding most quickly in aerial delivery segments.
Application:
Procurement patterns diverge sharply between outcome-based service contracts and capital equipment purchases.
- Marine Vessels:Unmanned surface vessels integrate multi-sensor perception stacks for autonomous collision avoidance. Maritime and Coastguard Agency certification codes mandate fail-operational redundancy for vessels above twenty-four metres, hardening sensor fusion requirements.
- Last-Mile Delivery:Scottish Highlands logistics operators unbundle drone services from traditional freight contracts, purchasing flight-hours rather than aircraft. Highland Council procurement frameworks specify outcome-based delivery windows for medical supply chains serving Isle of Skye communities.
- Industrial Automation:Manufacturing plants deploy automated guided vehicles for intra-facility material transport.
- Agriculture Equipment:Autonomous tractors navigate open-field operations using RTK-GPS correction signals.
- Unmanned Aerial Vehicles:Survey firms acquire beyond-visual-line-of-sight permissions for infrastructure inspection.
- Mining Operations:Hazardous-environment positioning systems serve North Sea energy infrastructure with GPS-IMU integration layers.
Marine vessels absorb the bulk of installed capacity; last-mile delivery is climbing the fastest as Civil Aviation Authority permissions expand.
Deployment Scenario:
Geographic concentration of trials creates dense testing ecosystems that accelerate iteration cycles for qualified vendors.
- Ports:Southampton and Plymouth container terminals host concentrated unmanned surface vessel trials. Maritime logistics operators consolidate testing within these twin hubs, creating feedback loops between shipyards and sensor integrators.
- Offshore Platforms:North Sea energy infrastructure demands all-weather navigation reliability that radar-only systems cannot penetrate. Fog-bound operational windows favour multi-sensor fusion with thermal imaging augmentation.
- Urban Infrastructure:Last-mile delivery robotics navigate street-level obstacles in constrained Scottish Highlands corridors.
- Warehouse Facilities:Automated guided vehicles operate within controlled lighting and surface conditions.
- Farmland Areas:Open-field autonomy relies on consistent GPS signal availability across East Anglia.
- Construction Sites:Dynamic obstacle environments challenge perception system robustness.
Ports absorb the bulk of installed capacity; offshore platforms are gaining share fastest as helicopter deck approach requirements harden.
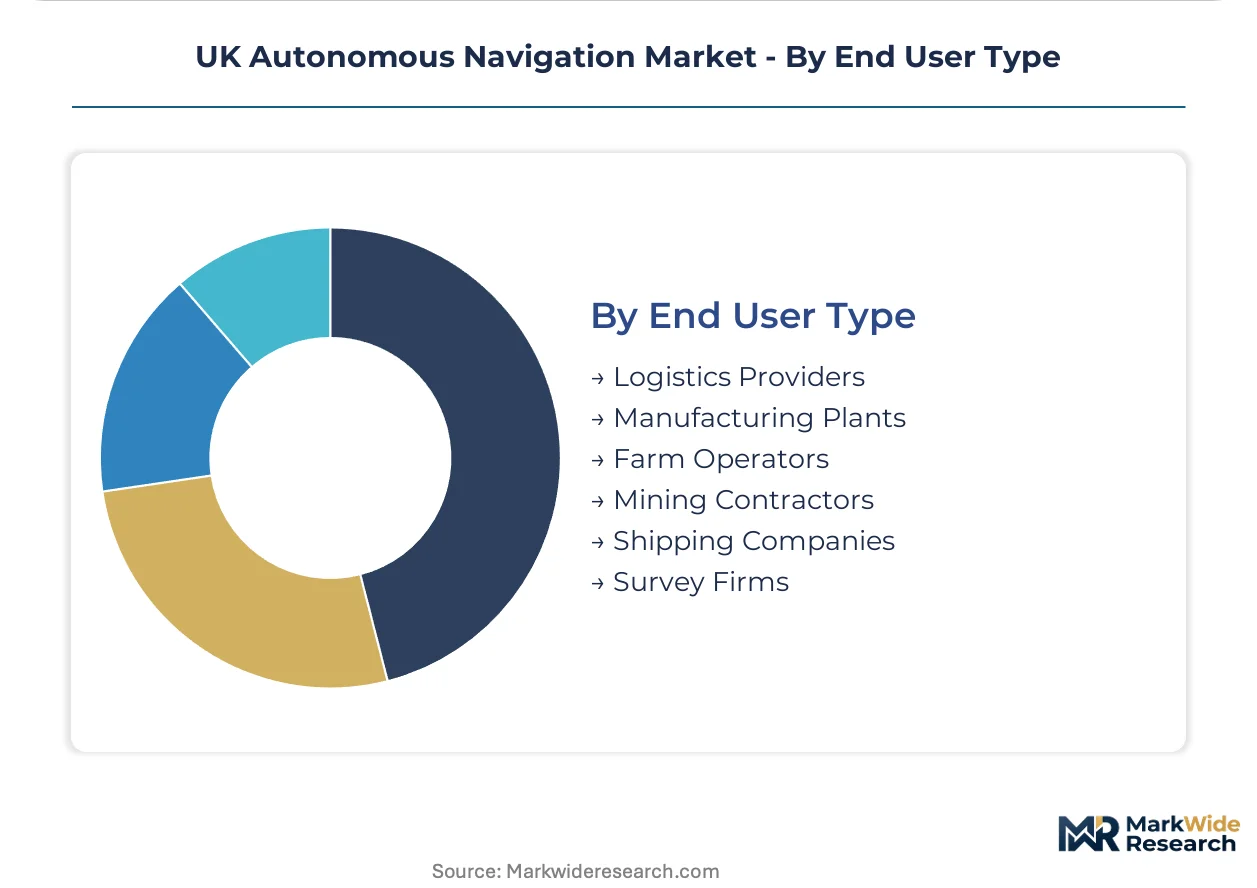
End User Type:
Customer technical sophistication determines procurement channel preferences and support contract structures.
- Shipping Companies:Vessel operators specify integrated navigation stacks through shipyard build contracts. Classification societies develop unified type-approval protocols spanning UK and Norwegian flag registries.
- Logistics Providers:Scottish Highlands freight operators purchase autonomous delivery as service outcomes rather than equipment assets.
- Mining Contractors:Subterranean operations require inertial positioning that functions without satellite coverage.
- Manufacturing Plants:Intra-facility automation deploys fixed-route automated guided vehicles.
- Farm Operators:Seasonal equipment utilisation shapes autonomous tractor leasing preferences.
- Survey Firms:Infrastructure inspection contracts specify beyond-visual-line-of-sight operational envelopes.
Shipping companies absorb the bulk of installed capacity; logistics providers are expanding most quickly through outcome-based procurement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK generates substantial autonomous navigation demand through its maritime logistics and defence procurement, though sensor component fabrication remains concentrated in East Asian manufacturing bases. Domestic value capture concentrates in system integration, software development, and port-side deployment infrastructure.
Southwest England
Plymouth and Southampton anchor the nation's unmanned surface vessel development, with Maritime and Coastguard Agency certification trials clustering in these port cities. The agency's updated autonomous shipping codes are compressing approval timelines for platforms tested in these waters. Shipyards in Devon and Hampshire are reconfiguring build specifications to accommodate dual-inertial-measurement-unit architectures as standard fit.
Scotland
North Sea offshore platform operators are pulling autonomous positioning systems into hazardous-environment deployments around Aberdeen and Shetland. The Civil Aviation Authority's expanded beyond-visual-line-of-sight permissions are unlocking drone delivery trials in Highland corridors serving Isle of Skye and Outer Hebrides communities. Edinburgh-based survey firms are acquiring permissions for infrastructure inspection across remote terrain.
Wales
Cardiff and Milford Haven authorities lack persistent unmanned maritime patrol coverage, creating whitespace for long-endurance surface vessel operators. The Welsh Government's maritime innovation funding is targeting coastal surveillance gaps in the Bristol Channel. Swansea University robotics research is feeding into port automation trials at Pembroke Dock.
North England
Subterranean mining operations in Yorkshire and County Durham require inertial positioning that functions without satellite coverage. The Health and Safety Executive's workplace robotics safety directives are shaping procurement specifications for hazardous-environment autonomous systems. Newcastle marine engineering talent pools are supporting Kalman-filter calibration for defence-adjacent programmes.
UK Autonomous Navigation Market Competitive Landscape
The competitive structure tilts toward defence-heritage system integrators with established Maritime and Coastguard Agency relationships. Tier-one vendors capture bulk procurement through shipyard build contracts, while specialist firms occupy niche testing and sub-system supply roles. Two archetypes dominate: naval contractors leveraging classification society protocols, and port automation vendors monetizing civilian sensor fusion architectures. Competitive moves centre on certification pre-qualification investment and white-label software licensing arrangements.
Among UK-based defence contractors, BAE Systems, QinetiQ, and Thales UK exemplify the integrated-systems archetype. BAE Systems occupies a position tied to naval heritage and platform-scale procurement. QinetiQ sits within the research-intensity tier through its proving grounds infrastructure. Thales UK anchors the civilian-automation vector with port-side deployment capabilities. These three represent distinct competitive positions without overlapping core specialisations.
| Leading Market Players |
|---|
| BAE Systems |
| Thales UK |
| QinetiQ |
| Leonardo UK |
| MBDA UK |
| ASV Global |
| MSubs Ltd |
| Babcock International |
| Atlas Elektronik UK |
| Others |
Pricing and Supply Chain Analysis
The Maritime and Coastguard Agency's updated autonomous shipping codes gates both qualified supply and premium-tier pricing access, forcing platform developers to absorb front-loaded certification costs before revenue deployment while concentrating margin capture among pre-qualified system integrators.
Pricing Analysis
Value-based pricing anchored to operational uptime guarantees dominates marine vessel contracts, with shipping companies paying premium rates for fail-operational redundancy on vessels above twenty-four metres. Pricing stratifies across certification grade, volume scale, and after-sales service bundling, with defence-adjacent labour pools commanding least price sensitivity due to scarce Kalman-filter calibration expertise. Cost compression in solid-state lidar tiers is intensifying because East Asian fabrication capacity expansion outpaces UK platform builder qualification timelines. Logistics providers purchasing outcome-based drone flight-hours in Scottish Highlands corridors exhibit highest price sensitivity, squeezing margin on per-hour delivery contracts.
Supply Chain Analysis
Freight costs from East Asian solid-state lidar manufacturers to Plymouth-Southampton port clusters absorb disproportionate working capital, with maritime logistics operators facing extended payment cycles for sensor fusion subsystems. UK platform builders draw from Taiwan, South Korea, and Japan for beam steering arrays, Doppler radar modules, and multi-constellation GPS receivers. Single-source vulnerability concentrates in solid-state lidar fabrication, where contract manufacturer qualification delays cascade into shipyard build schedule slippage. Distribution runs through shipyard-integrated procurement channels for marine vessels, while civilian port automation vendors white-label software stacks through direct licensing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK autonomous navigation market sits in a technology-transition phase, with multi-sensor fusion architectures displacing single-modality radar-primary systems that dominated prior-generation North Sea offshore deployments.
For Market Incumbents: Deepen vertical integration into sensor fusion software stacks to defend margin position against emerging white-label licensing competitors. Lock in shipyard build contract exclusivity through Maritime and Coastguard Agency certification co-investment, while expanding proving ground infrastructure at Plymouth to accelerate iteration cycles for dual-inertial-measurement-unit architectures. Certification pre-qualification investment remains the critical lever for maintaining tier-one vendor status. For New Entrants and Emerging Players: Port automation system integrators represent the most penetrable channel partner type for wedge positioning, particularly those serving Southampton container terminals with unmet software licensing demand. Target Welsh coastal surveillance gaps at Cardiff and Milford Haven, where persistent unmanned maritime patrol coverage whitespace exceeds incumbent capacity. Lead with computer vision-thermal imaging convergence for fog-bound North Sea operational windows as the differentiated go-to-market angle. For Investors and Strategic Acquirers: The Maritime and Coastguard Agency's forthcoming granular test-case specifications for marine autonomy software certification is the leading indicator that regulatory clarity will trigger consolidation among interpretive-risk-burdened developers. Long-term viability over the projection horizon favors acquisition targets with established classification society relationships and dual UK-Norwegian flag registry type-approval protocols. Monitor Civil Aviation Authority beyond-visual-line-of-sight permission expansion rates in Scottish Highlands corridors as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Qualification Investment | Maritime and Coastguard Agency code compliance accelerates platform approval timelines for qualified vendors. |
| Sensor Fusion Software Licensing | Civilian port automation vendors monetize Southampton-developed stacks through white-label arrangements. |
| Proving Ground Infrastructure Expansion | QinetiQ's Long Ashton robotics facilities anchor UK research intensity for defence-adjacent programmes. |
| Dual-IMU Architecture Standardization | Plymouth shipyards reconfigure build specifications to meet fail-operational redundancy mandates. |
| Outcome-Based Service Unbundling | Highland Council procurement frameworks specify delivery windows rather than equipment ownership. |
Research Methodology
Document review covered Maritime and Coastguard Agency certification filings, Civil Aviation Authority beyond-visual-line-of-sight permission registers, and Health and Safety Executive workplace robotics safety directives, complemented by interviews with autonomous navigation platform engineers, shipyard procurement managers, port automation system integrators, and North Sea offshore platform operations directors. Secondary validation drew from classification society type-approval protocols, customs import records for solid-state lidar components, and Scottish Highlands logistics operator procurement frameworks. Bottom-up vessel deployment counts triangulated against top-down market sizing across sensor modality and application segments.
Installed base projections and revenue estimates across the analysis window reflect segment-level modeling of technology type, operational domain, and customer procurement pattern dimensions. CAGRs were derived from regression analysis of historical adoption curves in comparable maritime automation markets, calibrated against UK-specific regulatory milestone schedules and port cluster infrastructure investment pipelines. Forecast inputs incorporated Maritime and Coastguard Agency code revision timelines, Civil Aviation Authority permission expansion trajectories, and East Asian sensor fabrication capacity expansion announcements.
Caveats apply where regulatory interpretation shifts, East Asian supply chain disruptions, or Kalman-filter calibration talent scarcity could materially shift the outlook beyond modeled scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Space Situational Awareness (SSA) Systems Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market
Communication Navigation & Surveillance
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market
Communication Navigation & Surveillance
High-End Inertial Systems Market
Communication Navigation & Surveillance
High Frequency Military Communications Market
Communication Navigation & Surveillance
Land-Based Situational Awareness Systems Market
Communication Navigation & Surveillance
Industrial Inertial Systems Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Space Situational Awareness Sensor and Tracking Performance Test Systems Market
Communication Navigation & Surveillance
Military Antenna Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market