
 Industrial Inertial Systems Market | 2026-2036
Industrial Inertial Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Inertial Systems Market Foresight
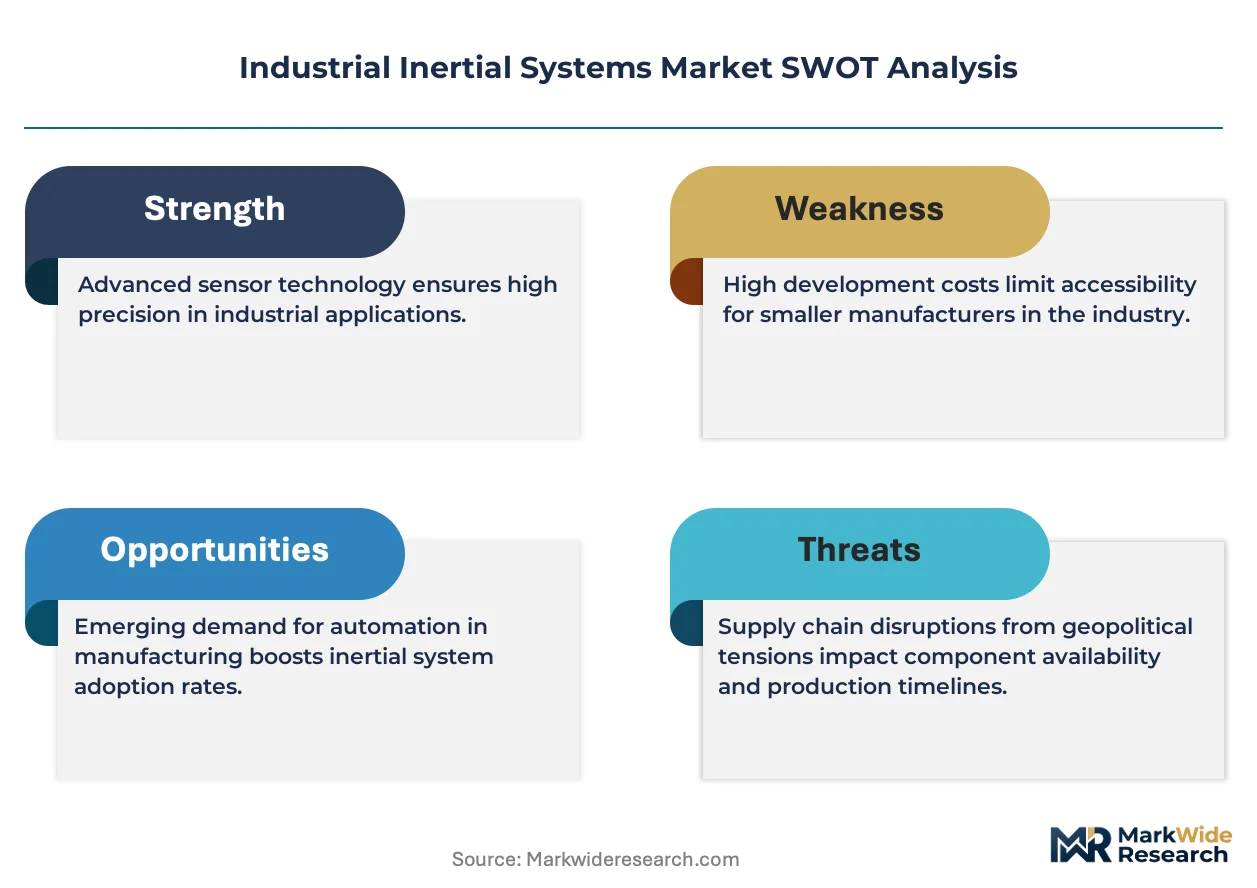
China is narrowing its technology gap in MEMS-based inertial manufacturing through state-backed foundry investments and domestic supply chain localization. Honeywell International Inc. leverages deep vertical integration across ring laser gyroscope production to sustain pricing power in defense-grade contracts. Safran S.A. anchors European aerospace demand through its specialized navigation suites for commercial and military platforms. L3Harris Technologies competes on R&D intensity, particularly in fiber optic gyroscopes for undersea and space applications.
Industrial inertial systems comprise gyroscopes, accelerometers, and inertial measurement units (IMUs) that detect angular rate and linear acceleration using Coriolis force or Sagnac effect principles, typically achieving bias stability below 0.01 degrees per hour in high-grade configurations. These systems enable dead-reckoning navigation, platform stabilization, and geophysical surveying in GPS-denied or high-interference environments. Fiber optic gyroscope technology leads in maritime and aerospace applications where drift tolerance demands justify unit costs above MEMS alternatives. Micro-Electro-Mechanical Systems technology represents the fastest-expanding segment as automotive OEMs and robotics integrators drive volume procurement of compact, low-power units. Quartz-based sensors occupy a mature niche in seismic monitoring where thermal stability requirements persist despite slower growth.
FAA certification standards for unmanned aircraft systems and EU MDR requirements for medical navigation robotics are tightening accuracy validation protocols, directly shaping product development roadmaps and testing expenditures. ISO 9001 and IEC 61508 functional safety frameworks further constrain market access for suppliers lacking certified quality management systems. Stakeholders must monitor how dual-use export control expansions affect component sourcing strategies and geographic manufacturing footprints.
Market Dynamics
The industrial inertial systems sector is compressing around autonomous navigation certification requirements, with the EU AI Act and FAA unmanned aircraft standards forcing suppliers to restructure testing protocols and accelerate bias-stability verification cycles before market access.
Growth Catalysts
- Warehouse Robotics Deployment:Autonomous mobile robots in logistics hubs are pulling MEMS-based inertial measurement units into high-volume procurement cycles for dead-reckoning navigation in GPS-denied environments.
- EU Machinery Safety Directives:Tighter performance certification mandates for autonomous platforms are creating regulated demand pull for industrial-grade gyroscopes and accelerometers with documented traceability.
- German Automotive Clustering:Precision manufacturing corridors around Stuttgart and Munich are concentrating sensor procurement for automated guided vehicles and quality-control stabilization systems.
Market Restraints
- Defense-Grade Component Concentration:Ring laser gyroscope supply chains concentrate among a handful of vertically integrated producers, creating single-source vulnerability for high-accuracy navigation contracts.
- MEMS Foundry Bottlenecks:Specialized MEMS fabrication capacity remains constrained in Taiwan and select European facilities, limiting volume scaling for cost-sensitive robotics integrators.
- Quartz Sensor Substitution Ceiling:Seismic monitoring applications resist MEMS migration due to thermal drift specifications that quartz-based sensors continue to satisfy at lower total cost of ownership.
Strategic Opportunities
- Undersea Navigation Expansion:Fiber optic gyroscope suppliers can penetrate maritime survey and subsea robotics segments where GPS denial and magnetic interference exclude alternative technologies.
- Medical Navigation Robotics:EU MDR certification requirements for surgical navigation systems are opening validated supply channels for high-stability inertial units in stereotactic and orthopedic applications.
- AI-Enabled Sensor Fusion:Convergence between machine learning-based error correction and raw inertial data streams is creating premium pricing tiers for intelligent IMU modules in autonomous platforms.
Industry Challenges
- Calibration Technician Scarcity:Specialized expertise in Allan variance analysis and temperature-compensated bias modeling remains concentrated among defense-aerospace veterans, constraining production scaling.
- Dual-Use Export Control Navigation:Expanding ITAR and EU dual-use regulations are complicating component sourcing strategies and forcing geographic manufacturing footprint reassessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Inertial Systems Market |
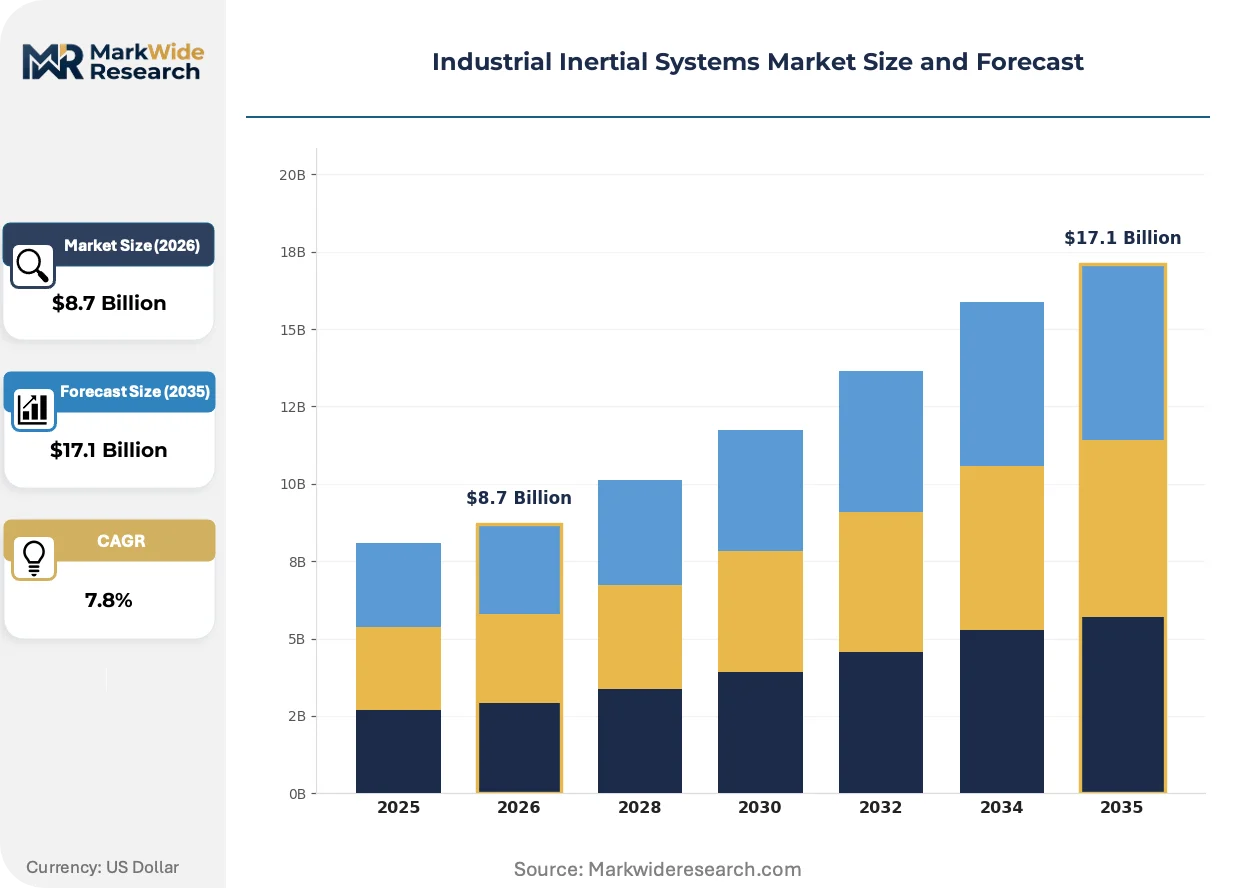
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gyroscopes, Accelerometers, IMUs, Sensors Technology: Micro-Electro-Mechanical Systems, Fiber Optic, Ring Laser, Quartz End User: Aerospace, Automotive OEMs, Robotics, Maritime Application: Navigation, Motion Tracking, Seismic Monitoring, Stabilization |
| Companies Covered | Honeywell International Inc., L3Harris Technologies, Safran S.A., Trimble Inc., SBG Systems, iXblue, Northrop Grumman Corporation, MEMSIC Semiconductor, VectorNav Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Inertial Systems Market Shifts & Advancements
Digital twin architectures are virtualizing sensor validation workflows, compressing development cycles and enabling predictive calibration models that reduce field failure rates in autonomous navigation platforms.
Silicon photonics integration is virtualizing traditional fiber optic gyroscope assembly by replacing discrete optical components with wafer-scale manufacturable waveguide structures. Maritime and aerospace integrators are piloting these platforms for volume-constrained programs. The technology is virtualizing cost structures that previously locked fiber optic gyroscopes into premium defense contracts.
The EU AI Act's risk-classification framework for autonomous systems is mandating documented accuracy thresholds for navigation sensors in high-risk industrial applications. Manufacturers must now maintain algorithmic transparency for sensor fusion logic alongside hardware specifications. German automotive suppliers are restructuring quality management systems to satisfy both IEC 61508 functional safety and emerging AI Act conformity requirements.
Buyer consolidation among warehouse automation OEMs is compressing supplier negotiation cycles and unbundling after-sales calibration services from hardware procurement. Large robotics integrators in the United States are demanding multi-year sensor performance guarantees with predictive maintenance telemetry. This restructuring is most visible in California and Texas logistics corridors where autonomous fulfillment scale is concentrating purchasing power.
Industrial Inertial Systems Market Segmentation
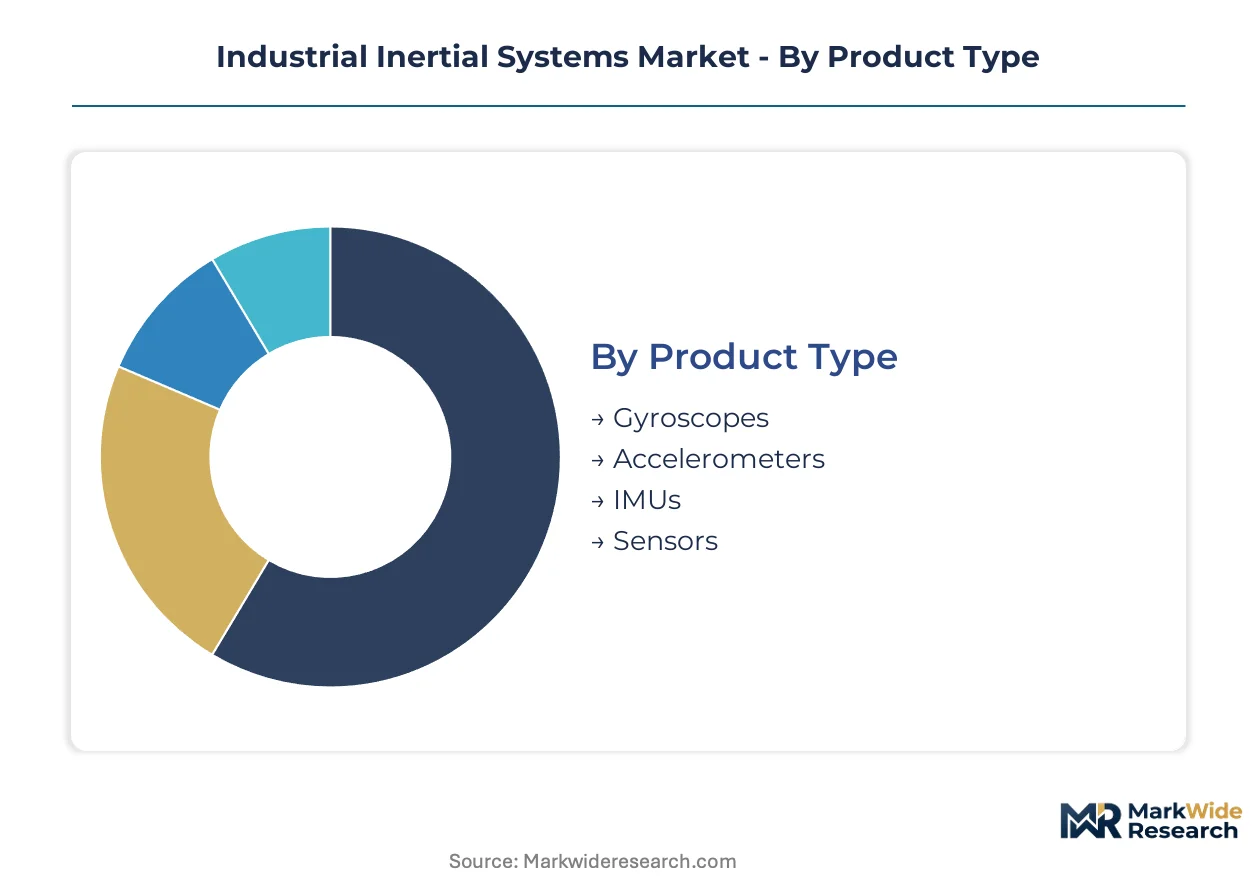
Industrial inertial systems segment heterogeneity reflects divergent calibration service intensities and certification burdens across gyroscopes, accelerometers, and integrated units. Procurement patterns bifurcate between defense-aerospace platforms demanding traceable maintenance contracts and high-volume robotics applications optimizing for disposable sensor economics.
Product Type:
After-sales calibration intensity varies sharply across product categories, with high-grade gyroscopes requiring periodic bias-stability verification while compact MEMS units ship with factory-sealed compensation profiles.
- Gyroscopes:Angular rate detection devices exploiting Coriolis force or Sagnac effect principles, achieving bias stability below 0.01 degrees per hour in ring laser configurations. Demand concentrates in German automotive corridors for automated guided vehicle navigation, where EU machinery safety directives mandate documented drift performance.
- Accelerometers:Linear acceleration sensors measuring specific force along defined axes, with quartz-based variants retaining thermal stability advantages in seismic applications. Robotics integrators in California logistics hubs are pulling MEMS accelerometers into high-volume procurement cycles for dead-reckoning in GPS-denied warehouse environments.
- IMUs:Integrated inertial measurement units combining gyroscopic and accelerometric sensing in compact packages, typically requiring field recalibration protocols for aerospace certification.
- Sensors:Discrete sensing elements sold for custom integration into larger navigation or stabilization systems, with aftermarket support obligations varying by application criticality.
By volume, IMUs lead through robotics and automotive integration. By growth pace, gyroscopes are ahead on autonomous navigation certification requirements.
Technology:
Cost tier stratification separates defense-grade ring laser systems from commoditized MEMS alternatives, with fiber optic platforms occupying a mid-tier position in maritime and aerospace applications.
- Micro-Electro-Mechanical Systems:Silicon-fabricated sensors leveraging batch semiconductor processing for sub-millimeter form factors and milliwatt power consumption. China's state-backed foundry investments are narrowing technology gaps through domestic supply chain localization, accelerating volume scaling for cost-sensitive robotics OEMs.
- Fiber Optic:Solid-state gyroscopes measuring phase shifts in counter-propagating light through coiled optical fiber, eliminating moving parts and magnetic sensitivity. Maritime survey operators and subsea robotics developers are expanding procurement where GPS denial and magnetic interference exclude alternative technologies.
- Ring Laser:High-accuracy gyroscopes employing helium-neon gas lasers within closed optical cavities, achieving navigation-grade precision for aerospace and strategic platforms.
- Quartz:Piezoelectric sensors exploiting temperature-stable crystalline resonators, retaining niche positioning in seismic monitoring where thermal drift specifications resist MEMS substitution.
MEMS dominates unit shipments through automotive and robotics volume. Fiber optic technology is expanding most quickly on undersea navigation and unmanned maritime platform procurement.
End User:
Customer type fragmentation spans capital-intensive OEMs with multi-year sensor performance guarantees versus integrators optimizing for spot procurement of disposable inertial modules.
- Aerospace:Commercial and military aircraft manufacturers requiring navigation-grade inertial systems with FAA certification documentation and predictive maintenance telemetry. Honeywell and Safran anchor this segment through specialized navigation suites with multi-decade service obligations.
- Automotive OEMs:Precision manufacturers around Stuttgart and Munich clustering sensor procurement for automated guided vehicles, quality-control stabilization, and emerging autonomous driving platforms subject to evolving UN ECE regulation.
- Robotics:Warehouse automation and logistics integrators demanding compact, low-power inertial units for dead-reckoning navigation in GPS-denied environments.
- Maritime:Shipbuilders, offshore survey contractors, and subsea equipment operators requiring drift-tolerant navigation independent of satellite or magnetic references.
Automotive OEMs generate the highest unit volumes through robotics and guided vehicle integration. Robotics applications are climbing the fastest on warehouse automation deployment acceleration.
Application:
Maturity gradients separate established seismic monitoring applications from emerging autonomous navigation segments where algorithmic transparency requirements are restructuring product development roadmaps.
- Navigation:Dead-reckoning position determination in GPS-denied or high-interference environments, encompassing aerospace flight management, maritime route plotting, and autonomous vehicle path tracking. EU AI Act risk-classification frameworks are mandating documented accuracy thresholds with algorithmic transparency for sensor fusion logic.
- Motion Tracking:Real-time orientation and displacement measurement for robotics control, platform stabilization, and human-machine interface applications.
- Seismic Monitoring:Geophysical surveying and structural health monitoring requiring thermal stability and long-term bias predictability, where quartz sensor economics resist MEMS displacement despite slower expansion.
- Stabilization:Active vibration suppression and platform leveling for precision manufacturing, optical systems, and heavy equipment operation.
Navigation commands the largest revenue base through aerospace and maritime procurement. Motion tracking is gaining share fastest on warehouse robotics and autonomous platform deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial inertial systems consumption patterns diverge sharply across geographies. Germany and China prioritize precision manufacturing integration, while the United States concentrates defense-aerospace procurement. Maritime applications dominate Nordic and Japanese demand profiles.
United States
FAA unmanned aircraft certification requirements and defense modernization budgets anchor high-grade gyroscope procurement. ITAR regulations constrain component sourcing strategies for non-domestic suppliers. California and Texas logistics corridors concentrate warehouse robotics deployment, pulling MEMS-based inertial measurement units into high-volume procurement cycles for autonomous fulfillment platforms.
Germany
EU machinery safety directives and the AI Act's risk-classification framework mandate documented accuracy thresholds for autonomous navigation systems. Stuttgart and Munich precision manufacturing clusters concentrate sensor procurement for automated guided vehicles and automotive quality-control stabilization. IEC 61508 functional safety compliance shapes supplier qualification protocols.
China
State-backed MEMS foundry investments and domestic supply chain localization initiatives narrow technology gaps in compact sensor manufacturing. MIIT industrial automation policies accelerate robotics integration in Yangtze River Delta manufacturing hubs. Shanghai and Shenzhen industrial corridors drive volume scaling for cost-sensitive integrators.
Japan
METI strategic technology roadmaps prioritize maritime and aerospace navigation system development. JIS standards and ISO 9001 certification requirements constrain market access for uncertified suppliers. Nagoya and Osaka industrial clusters concentrate precision equipment manufacturing with embedded inertial stabilization.
France
ANSM medical device regulations and EU MDR requirements open validated supply channels for surgical navigation robotics. Aerospace and defense procurement anchors through specialized navigation suite development. Toulouse and Paris-Saclay technology corridors concentrate avionics and autonomous systems research.
Industrial Inertial Systems Market Competitive Landscape
Capability concentration sits with defense-aerospace specialists sustaining navigation-grade precision; scale advantage sits with semiconductor-integrated fabricators serving robotics volume. The market structures around three tiers: vertically integrated defense primes, MEMS-focused automotive suppliers, and maritime-specialized navigation houses. Competitive moves center on backward integration into specialized foundry capacity and strategic partnerships for sensor fusion software development.
Among defense-aerospace anchors, Honeywell International Inc. and Northrop Grumman Corporation exemplify the vertically integrated tier with captive ring laser gyroscope production. Safran S.A. occupies a position within European navigation suite specialization. L3Harris Technologies represents R&D-intensive fiber optic platform development. MEMSIC Semiconductor and VectorNav Technologies sit within the scale-driven semiconductor-integrated segment serving robotics and automotive volume procurement.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| L3Harris Technologies |
| Safran S.A. |
| Trimble Inc. |
| SBG Systems |
| iXblue |
| Northrop Grumman Corporation |
| MEMSIC Semiconductor |
| VectorNav Technologies |
| Others |
Supply & Pricing Matrix
Undercapacity in Taiwan's specialized MEMS foundries is compressing lead times for robotics integrators while amplifying pricing leverage among ring laser gyroscope producers with captive helium-neon gas laser supply. This utilization asymmetry bifurcates supplier behavior: volume-tier MEMS vendors absorb margin pressure through semiconductor batch economics, while defense-grade producers extract premiums from documented bias-stability traceability.
Pricing Analysis
Long-term offtake contracts dominate aerospace and maritime procurement, with multi-year sensor performance guarantees bundling predictive maintenance telemetry and periodic Allan variance recalibration. Three-tier pricing structure across navigation-grade, industrial-grade, and commercial-grade levels separates bias stability below 0.01 degrees per hour from MEMS alternatives. Cost compression in robotics-destined MEMS units is intensifying because buyer consolidation among warehouse automation OEMs unbundles after-sales services. California logistics integrators exhibit highest price sensitivity; German automotive OEMs least, accepting IEC 61508 certification premiums.
Supply Chain Analysis
Contract manufacturing concentration sits with Taiwan Semiconductor Manufacturing Company and select European MEMS foundries holding specialized etching and wafer-bonding capacity. Geographic supply concentration spans Taiwan, Germany, and China's Yangtze River Delta for fabrication, with final assembly gravitating toward customer proximity in Stuttgart, California, and Shanghai. Raw material dependencies include high-purity quartz crystalline substrates, polarization-maintaining optical fiber, and helium-neon gas mixtures. Single-source vulnerability for ring laser gyroscope optical cavities threatens defense contract fulfillment. Distribution runs through direct OEM relationships for aerospace, with distributor networks serving spot procurement in robotics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-classification framework for autonomous navigation systems constitutes a regulatory inflection accelerating certification investment cycles and compressing market access for uncertified suppliers.
For Market Incumbents: Harden ring laser gyroscope supply chains through backward integration into helium-neon gas laser production, eliminating single-source vulnerability for defense contracts. Fortify MEMS foundry partnerships in Taiwan and Germany to secure wafer allocation against robotics volume surges. Certification investment in IEC 61508 functional safety and EU AI Act conformity represents the critical defensive lever against emerging Chinese foundry competitors. For New Entrants and Emerging Players: Southeast Asian maritime survey markets offer underpenetrated demand for fiber optic gyroscope platforms where GPS denial and magnetic interference exclude MEMS alternatives. Target EU MDR-certified surgical navigation robotics as a white-space application with validated supply channel requirements creating barrier protection. Partner with German automotive Tier 1s for automated guided vehicle IMU integration, leveraging Stuttgart cluster proximity for rapid qualification cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among defense-aerospace specialists with multi-decade navigation suite service obligations and predictive maintenance telemetry contracts. Long-term viability centers on dual-use technology holders with ITAR-compliant manufacturing footprints and algorithmic transparency capabilities for EU AI Act compliance. Monitor silicon photonics integration progress as an inflection indicator for fiber optic gyroscope cost-structure virtualization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Cavity Production | Eliminates single-source helium-neon laser dependency for ring laser gyroscope defense contracts. |
| EU AI Act Conformity Certification | Opens regulated demand channels for autonomous navigation systems in German automotive corridors. |
| Silicon Photonics Platform Development | Virtualizes fiber optic gyroscope assembly cost structures for maritime volume scaling. |
| Predictive Maintenance Telemetry Integration | Enables multi-year performance guarantees demanded by California robotics integrators. |
| MEMS Foundry Capacity Expansion | Addresses Taiwan utilization constraints constraining warehouse automation sensor procurement. |
Research Methodology
Operator-level perspectives from aerospace navigation engineers, MEMS foundry operations directors, robotics procurement leads, and maritime survey equipment specialists anchored the qualitative base. Primary interviews combined with secondary validation from FAA unmanned aircraft certification filings, EU MDR device registrations, SEC 10-K aerospace segment disclosures, and MIIT industrial automation policy documents. Bottom-up sensor shipment estimates triangulated against top-down navigation system market assessments.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across gyroscope/accelerometer/IMU product types, MEMS/fiber optic/ring laser/quartz technology tiers, and aerospace/automotive/robotics/maritime end-user categories. CAGRs derived from installed base growth rates, replacement cycles, and content-per-platform trajectories. Forecast inputs incorporated EU AI Act implementation timelines and FAA unmanned aircraft certification velocity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed MEMS foundries or silicon photonics entrants would shift outcomes. Cross-checking against IEA maritime survey vessel deployment data and German automotive AGV production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Asia-Pacific Autonomous Navigation Market
Communication Navigation & Surveillance
Land-Based Situational Awareness Systems Market
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market
Communication Navigation & Surveillance
UWB Anchor Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Inertial Navigation System Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market