
 Infrared Search and Track (IRST) System Market | 2026-2036
Infrared Search and Track (IRST) System Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Search and Track (IRST) System Market Analysis
Sensor fusion architectures that merge infrared imagery with artificial intelligence-driven threat classification is rewriting how modern IRST systems process detection cues. Leonardo S.p.A. leverages decades of electro-optical heritage to dominate European naval and airborne contracts. RTX Corp. sustains a broad technology portfolio spanning cryogenic coolers to advanced algorithms. Lockheed Martin Corp. anchors US fifth-generation fighter integration programs with captive supply of focal plane arrays.
An Infrared Search and Track (IRST) System detects, tracks, and classifies targets through passive thermal radiation sensing, typically operating in medium-wave infrared (MWIR, 3-5 μm) or long-wave infrared (LWIR, 8-12 μm) spectral bands using cooled mercury cadmium telluride or indium antimonide focal plane arrays. These systems serve military and security operators by enabling covert surveillance and missile warning without emitting detectable electromagnetic energy. Airborne Systems command the largest revenue share due to fighter jet modernization cycles across multiple air forces, while Hybrid Systems that blend passive infrared with digital signal processing represent the fastest-expanding technology category as operators demand reduced false-alarm rates in contested environments. Naval Systems attract concentrated R&D investment from shipbuilders seeking distributed aperture architectures for 360-degree perimeter defense.
The US Department of Defense drives procurement standards through MIL-STD-810 environmental testing and ITAR export controls, while NATO STANAG agreements harmonize interoperability requirements across allied forces. The EU Green Deal's fluorinated gas restrictions indirectly shape cooling system design choices for European manufacturers. Stakeholders must monitor how electromagnetic spectrum contestation doctrines reshape sensor prioritization budgets and dual-use technology transfer policies.
Market Dynamics
Passive detection architectures are displacing active radar dependencies across NATO air and naval platforms as electromagnetic spectrum contestation doctrines harden procurement priorities toward survivable sensor networks.
Growth Catalysts
- Electromagnetic Spectrum Superiority Mandates:The US Department of Defense's operational concepts prioritize passive sensing to reduce emitter detectability. Fighter modernization programs and naval destroyer upgrades absorb IRST units at accelerated refresh cycles.
- Mercury Cadmium Telluride Focal Plane Arrays:Cooled MWIR detectors deliver superior sensitivity for long-range target acquisition. Foundry capacity expansion at specialized compound semiconductor facilities is easing prior supply constraints.
- NATO STANAG Interoperability Frameworks:Allied force coordination requirements harmonize sensor data formats and interface standards. Cross-border joint operations drive standardized procurement specifications across member air forces.
Market Restraints
- Indium Antimonide Substrate Supply Concentration:Cryogenic detector manufacturing depends on limited foundry capacity concentrated in Western Europe and the United States. Geopolitical trade restrictions compound input scarcity risks.
- ITAR Export Control Friction:US State Department licensing requirements delay technology transfer to allied partners. Non-US buyers face extended approval timelines for focal plane array procurement.
- Fluorinated Gas Cooling Restrictions:The EU Green Deal's F-Gas Regulation limits refrigerant options for closed-cycle coolers. European manufacturers must redesign thermal management systems to maintain export compliance.
Strategic Opportunities
- Unmanned Aerial Vehicle Integration:MALE and HALE drone platforms lack mature passive detection suites. Sensor miniaturization programs open new addressable demand beyond manned fighter applications.
- Naval Distributed Aperture Architectures:Shipbuilders seek 360-degree perimeter defense through mast-mounted IRST clusters. Surface combatant modernization programs in Australia, Japan, and South Korea represent concentrated procurement windows.
- AI-Driven Threat Classification:Machine learning inference at the sensor edge compresses operator cognitive load. Software-defined detection algorithms enable post-deployment capability upgrades without hardware replacement.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Specialized expertise in Stirling cooler design and dewar vacuum integrity resides at a handful of defense contractors and national laboratories. Workforce pipeline constraints limit production scaling.
- MIL-STD-810 Qualification Timelines:Environmental testing for thermal shock, vibration, and humidity resistance extends development cycles. Platform integrators face schedule risk from sequential certification gates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Search and Track (IRST) System Market |
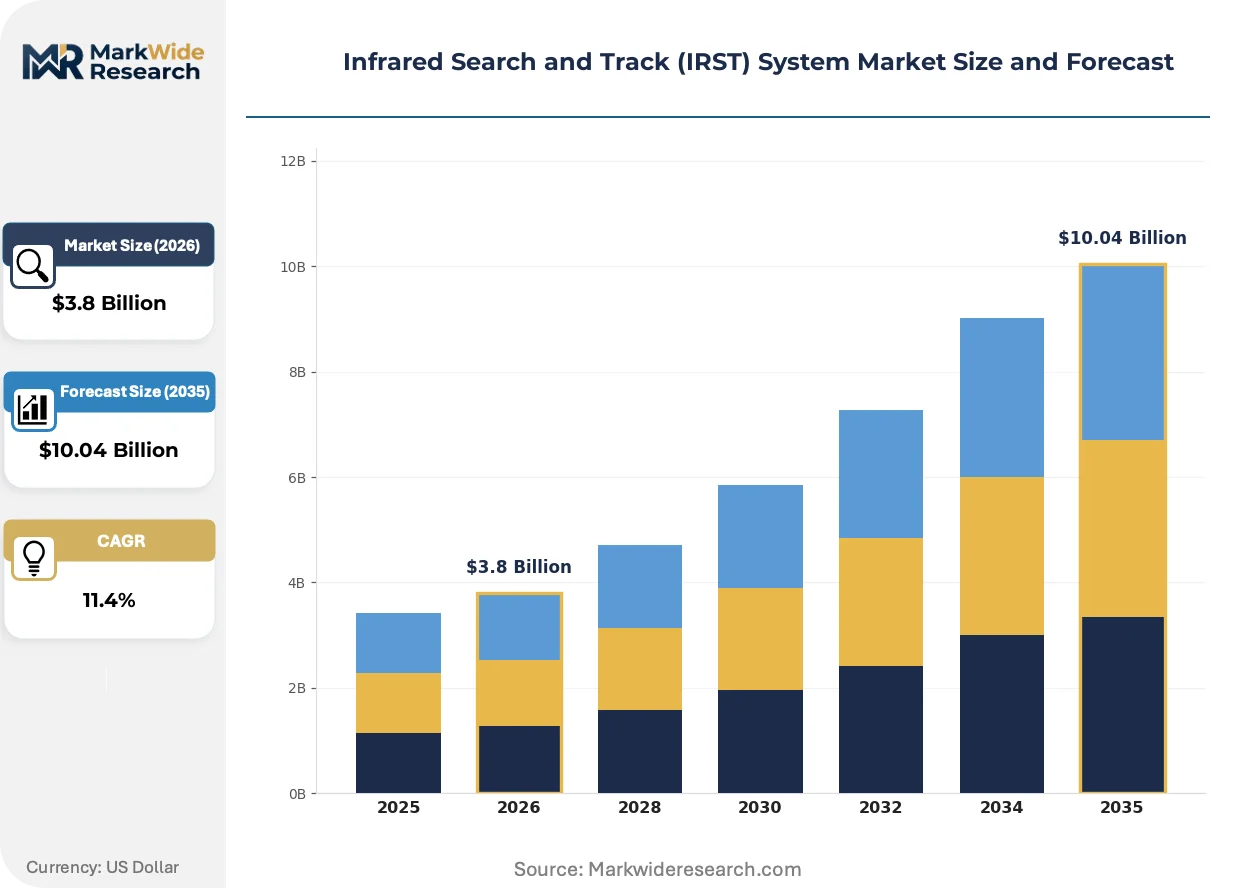
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Systems, Ground-Based Systems, Airborne Systems, Naval Systems Technology: Passive Infrared, Active Infrared, Hybrid Systems, Digital Signal Processing End User: Military, Aerospace, Law Enforcement, Security Agencies Application: Surveillance, Target Acquisition, Reconnaissance, Border Security |
| Companies Covered | Leonardo S.p.A., Elbit Systems Ltd., RTX Corp., Lockheed Martin Corp., HENSOLDT AG, Northrop Grumman Corp., L3Harris Technologies Inc., ASELSAN AS, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Search and Track (IRST) System Market Emerging Trajectories
Sensor fusion architectures are collapsing traditional boundaries between spectral bands and processing layers, compressing detection-to-classification timelines while expanding deployable platform categories beyond legacy fighter constraints.
Dual-band focal plane arrays combining MWIR and LWIR sensitivity are collapsing the prior trade-off between atmospheric transmission and target emissivity optimization. Naval destroyer programs and airborne early warning platforms are adopting these unified sensors to reduce aperture count and maintenance burden. The structural consequence is collapsing lifecycle cost models that previously justified single-band procurement.
The EU F-Gas Regulation is restricting hydrofluorocarbon refrigerants in closed-cycle coolers used for mercury cadmium telluride detector cooling. European manufacturers are redesigning thermal management around alternative chemistries or solid-state cooling approaches. Airborne systems procurement within EU member states faces compressed technology refresh timelines to meet phased compliance deadlines.
Platform integrators are unbundling sensor hardware from proprietary processing chains, demanding open-architecture middleware compatible with multiple vendor algorithms. Fifth-generation fighter programs in the United States and partner nations are specifying government-furnished reference architectures. This behavioral shift concentrates negotiation leverage with prime contractors while fragmenting subsystem supplier margins.
Infrared Search and Track (IRST) System Market Segmentation
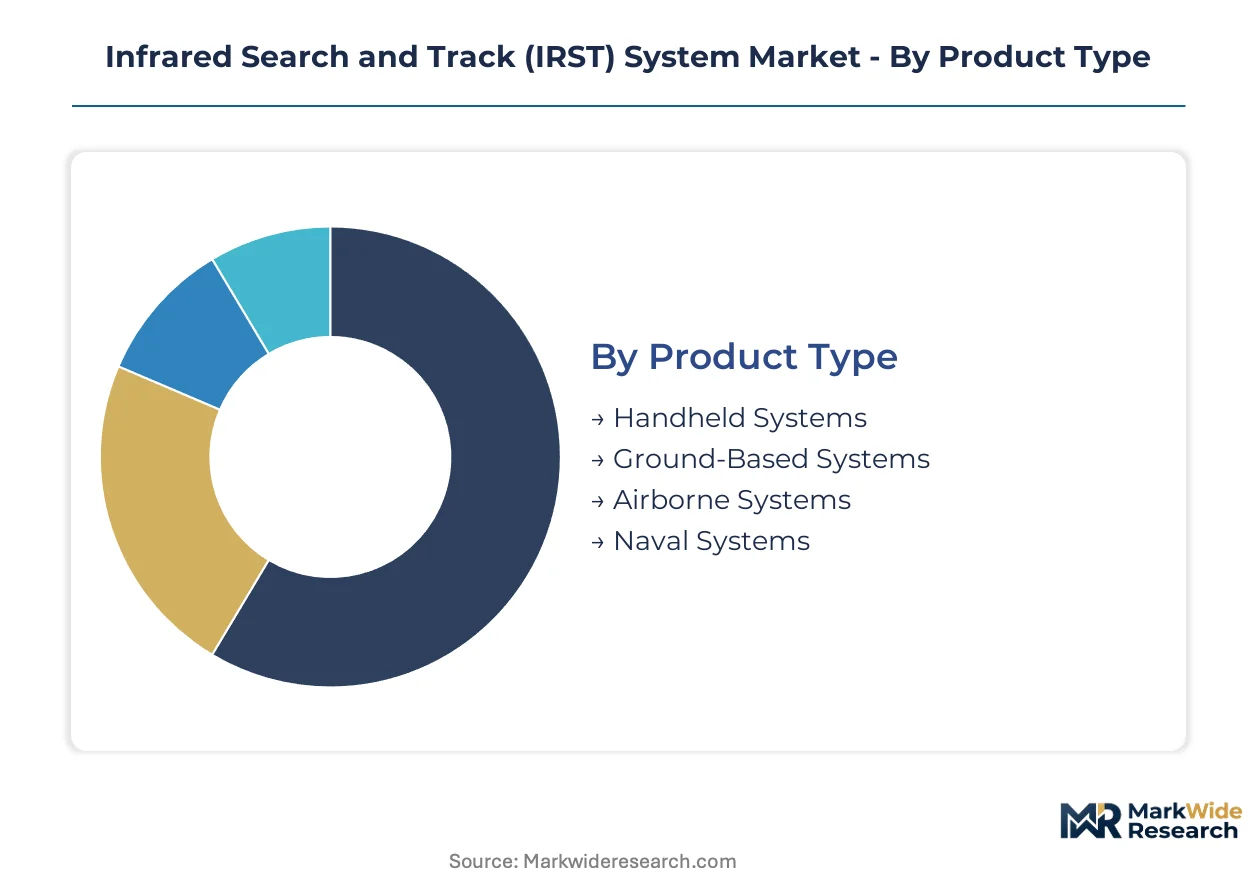
IRST procurement patterns diverge sharply across platform categories, with airborne and naval programs absorbing multi-year service contracts while handheld units generate spare parts revenue through depot-level maintenance cycles. Technology refresh timelines and platform integration complexity determine aftermarket profitability for each segment cluster.
Product Type:
After-sales intensity peaks with naval distributed aperture architectures requiring dockside cooler refurbishment and focal plane array recalibration, while airborne systems demand line-replaceable unit exchanges at forward operating bases.
- Airborne Systems:Fighter pod and nose-mounted configurations integrate cooled MWIR detectors with stabilized gimbals for high-altitude target detection. US Air Force F-35 and F-22 modernization programs, alongside NATO partner fighter upgrades, concentrate procurement volume through sole-source platform integration contracts.
- Naval Systems:Mast-mounted clusters and distributed aperture arrays deliver 360-degree perimeter defense for surface combatants. Australian, Japanese, and South Korean destroyer programs drive concentrated demand for salt-spray-qualified enclosures and shock-hardened gimbals.
- Ground-Based Systems:Tripod-mounted and vehicle-integrated units serve forward observation posts with reduced mobility requirements.
- Handheld Systems:Portable thermal viewers support dismounted infantry and special operations teams with uncooled microbolometer options.
By volume, Airborne Systems leads. By growth pace, Naval Systems is expanding most quickly through Asia-Pacific surface combatant programs.
Technology:
Cost tier separation is pronounced: cooled mercury cadmium telluride arrays command five-to-ten-fold premiums over uncooled alternatives, with hybrid architectures occupying a mid-tier pricing band that sacrifices some sensitivity for reduced logistics burden.
- Hybrid Systems:Dual-band MWIR/LWIR focal plane arrays merge atmospheric transmission advantages with target emissivity optimization in unified apertures. Naval early warning platforms and next-generation fighter programs in the United States and partner nations are standardizing on these configurations to reduce part count and maintenance intervals.
- Passive Infrared:Traditional single-band cooled detectors remain the baseline for long-range acquisition missions requiring maximum sensitivity. European NATO air forces continue procuring these systems for legacy fighter upgrades where platform electrical power and cooling capacity are constrained.
- Digital Signal Processing:Software-defined detection chains enable post-deployment algorithm updates without hardware replacement.
- Active Infrared:Laser-illuminated approaches serve niche applications requiring positive identification at extended ranges.
Passive Infrared dominates current installed base. Hybrid Systems gain share fastest as platform integrators prioritize lifecycle cost reduction.
End User:
Customer type determines contracting vehicle: military services employ indefinite-delivery indefinite-quantity frameworks with cost-plus incentive fee structures, while security agencies purchase through commercial terms with limited technical data rights.
- Military:Defense ministries across NATO and Indo-Pacific allied nations fund platform-integrated IRST through major capability acquisition programs. The US Department of Defense's electromagnetic spectrum superiority mandates accelerate refresh cycles for fighter and destroyer fleets.
- Aerospace:Commercial and government satellite operators procure space-qualified infrared sensors for missile warning constellations. This segment demands radiation-hardened electronics and extended thermal cycling qualification protocols.
- Law Enforcement:Border patrol and tactical units acquire portable systems through federal procurement vehicles with simplified environmental testing.
- Security Agencies:Critical infrastructure protection programs deploy ground-based perimeter sensors with reduced range requirements.
Military end users absorb the greatest absolute volume. Aerospace applications climb the fastest as missile warning satellite constellations expand.
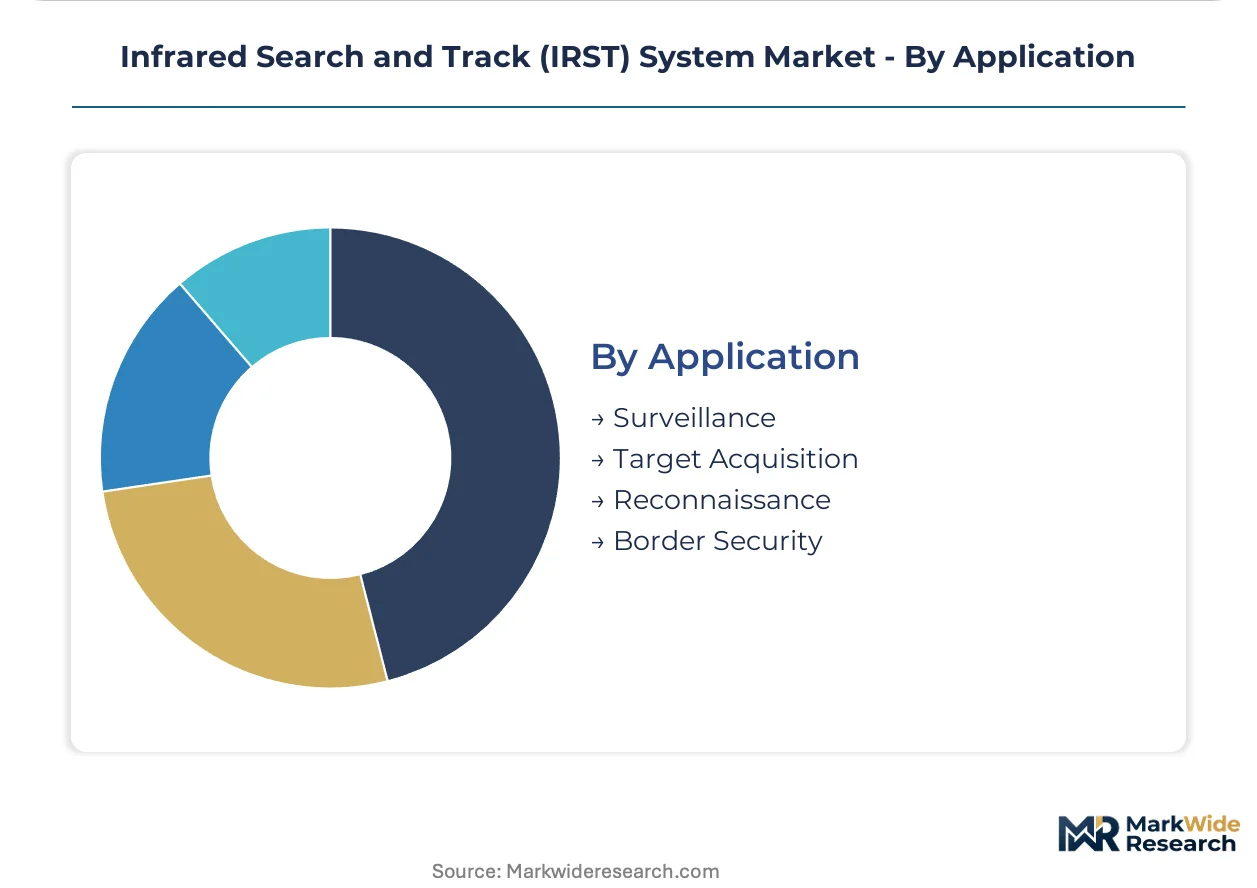
Application:
Application maturity varies: surveillance missions employ standardized hardware configurations with established depot maintenance procedures, while target acquisition programs demand customized integration with fire control systems and unique qualification protocols.
- Target Acquisition:Precision cueing for weapon systems requires sub-pixel tracking accuracy and low latency data links. Fifth-generation fighter programs in the United States specify tight integration with radar and electronic warfare suites for fused fire control solutions.
- Surveillance:Wide-area persistent coverage missions prioritize detection range and false alarm rate performance over precise tracking. Naval destroyer programs employ mast-mounted clusters for horizon search with automated threat prioritization algorithms.
- Reconnaissance:Standoff collection platforms balance resolution against platform survivability constraints.
- Border Security:Fixed-site installations emphasize unattended operation and remote diagnostics capability.
Surveillance leads by deployment volume. Target Acquisition shows the steepest expansion trajectory through precision strike modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices in the United States, European NATO members, and Asia-Pacific allied nations concentrate IRST demand through fighter modernization and naval destroyer programs. Platform integrators in these markets specify passive detection architectures aligned with electromagnetic spectrum superiority doctrines. Each geography imposes distinct regulatory and industrial constraints on supplier participation.
United States
The US Department of Defense accelerates technology refresh cycles through F-35 and F-22 modernization programs and Arleigh Burke-class destroyer upgrades. ITAR export controls administered by the State Department constrain focal plane array transfers to allied partners. Defense contractors cluster around Washington DC, Florida, and California aerospace corridors where platform integration contracts concentrate.
Germany
The Bundeswehr funds IRST integration into Eurofighter Typhoon fleets and F-126 frigate construction through NATO STANAG-aligned procurement frameworks. The EU F-Gas Regulation restricts hydrofluorocarbon refrigerants in closed-cycle coolers, forcing thermal management redesigns. Industrial activity concentrates in Bavaria and Baden-Württemberg where HENSOLDT AG and subsystem suppliers maintain electro-optical production facilities.
United Kingdom
The Royal Navy drives demand through Type 26 and Type 31 frigate programs specifying distributed aperture architectures for horizon search missions. UK Export Control Organisation licensing requirements govern technology transfers to Five Eyes partners. Defense electronics manufacturing clusters in Scotland and the Southwest around Glasgow and Bristol aerospace facilities.
Japan
The Japan Air Self-Defense Force procures IRST units for F-15J fighter upgrades and indigenous F-X sixth-generation fighter development through Ministry of Defense acquisition programs. METI industrial policy promotes domestic focal plane array foundry capacity to reduce import dependency. Mitsubishi Heavy Industries and subsystem suppliers operate from Nagoya and Komaki manufacturing centers.
South Korea
The Defense Acquisition Program Administration funds KF-21 Boramae fighter and KDDX destroyer programs with specified passive detection suites for electromagnetic spectrum contestation environments. MFDS regulations align with NATO STANAG frameworks for allied interoperability. Hanwha Aerospace and defense electronics clusters in Changwon and Sacheon execute platform integration contracts.
Infrared Search and Track (IRST) System Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a consolidated supplier base where platform integration contracts concentrate negotiation leverage with prime contractors. Tier-1 defense conglomerates anchor sole-source fighter and destroyer programs through captive electro-optical divisions. Tier-2 subsystem specialists supply focal plane arrays, cryogenic coolers, and stabilized gimbals under long-term supply agreements. Dominant competitive moves include strategic partnerships for sensor fusion algorithm development and vertical integration into compound semiconductor foundry capacity.
Within the platform-integration tier, Leonardo S.p.A. and Lockheed Martin Corp. exemplify prime-contractor positioning through electro-optical heritage and fifth-generation fighter program anchoring respectively. RTX Corp. occupies a diversified technology position spanning cryogenic subsystems to advanced processing chains. These three entities represent distinct competitive archetypes: European naval-airborne dual-capability, US fighter-captive integration, and broad technology portfolio diversification.
| Leading Market Players |
|---|
| Leonardo S.p.A. |
| Elbit Systems Ltd. |
| RTX Corp. |
| Lockheed Martin Corp. |
| HENSOLDT AG |
| Northrop Grumman Corp. |
| L3Harris Technologies Inc. |
| ASELSAN AS |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
Bavarian electro-optical manufacturing clusters anchor mercury cadmium telluride detector foundry capacity, concentrating upstream supply leverage among a handful of Western European and US defense contractors. This geographic concentration feeds directly into downstream pricing power, where sole-source platform integration contracts for F-35 and Eurofighter programs command substantial premiums over subsystem component sales.
Pricing Analysis
Cost-plus incentive fee structures with Bureau of Labor Statistics indexation dominate US Department of Defense procurement, while NATO partner nations employ fixed-price escalation clauses tied to EU harmonized indices. Price differentiation separates ITAR-restricted focal plane arrays from commercially exportable alternatives, with cryogenic cooler refurbishment bundling further stratifying lifecycle contracts. Pricing pressure stems from open-architecture middleware mandates fragmenting subsystem supplier margins. Military end users exhibit lowest price sensitivity due to electromagnetic spectrum superiority mandates, while security agencies purchasing portable units demonstrate highest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China compounds indium antimonide substrate scarcity risks concentrated in Western European foundries. Raw material dependencies center on mercury cadmium telluride wafers, Stirling cooler helium charge stocks, and stabilized gimbal precision bearings. Single-source vulnerability pervades cryogenic engineering talent pools residing at national laboratories and captive defense divisions. Distribution runs through prime contractor platform integration channels with long-term supply agreements, bypassing direct subsystem sales to end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform unbundling trends fragment traditional prime-contractor strongholds, creating white-space opportunities for specialized subsystem suppliers and algorithm developers. Unmanned aerial vehicle integration and naval distributed aperture architectures represent underserved demand pockets where technical differentiation commands premium positioning.
For Market Incumbents: Harden electromagnetic spectrum superiority positioning through backward integration into compound semiconductor foundry capacity, securing mercury cadmium telluride wafer supply against indium antimonide substrate volatility. Lock long-term supply agreements with Stirling cooler specialists to defend against cryogenic engineering talent scarcity. Anchor sole-source relationships with fifth-generation fighter program offices before open-architecture middleware mandates erode platform integration leverage. For New Entrants and Emerging Players: Establish a beachhead in unmanned aerial vehicle passive detection suites where incumbent prime contractors lack optimized form factors. Target naval distributed aperture architectures in Australian, Japanese, and South Korean destroyer programs requiring salt-spray-qualified enclosures outside traditional US-European supply bases. Pursue AI-driven threat classification software licensing to prime contractors as a capital-light entry vector. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dual-band focal plane array specialists with EU F-Gas Regulation-compliant thermal management designs. Long-term viability hinges on electromagnetic spectrum contestation doctrine durability across NATO and Indo-Pacific allied procurement offices. Watch for ITAR export control relaxation signals as inflection indicators for commercially addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Algorithm Development | Machine learning inference at the sensor edge compresses operator cognitive load for fifth-generation fighters. |
| Compound Semiconductor Foundry Investment | Mercury cadmium telluride wafer capacity expansion eases prior supply constraints for cooled MWIR detectors. |
| Open-Architecture Middleware Certification | Government-furnished reference architectures fragment subsystem supplier margins while enabling algorithm portability. |
| Naval Distributed Aperture Integration | Mast-mounted IRST clusters for Australian, Japanese, and South Korean destroyers drive concentrated procurement windows. |
| EU F-Gas Regulation Compliance Redesign | Alternative thermal management chemistries maintain export compliance for European airborne systems procurement. |
Methodological Framework
Initial hypotheses were tested against primary input from fighter program integration engineers, naval combat systems architects, cryogenic subsystem procurement leads, and defense ministry acquisition officers and refined through secondary validation against NATO STANAG documentation, US Department of Defense budget justification materials, EU F-Gas Regulation implementation guidance, and compound semiconductor trade flow data. Bottom-up platform deployment forecasts triangulated against top-down defense expenditure projections.
Demand-supply balance modeling across the projection horizon incorporated airborne versus naval versus ground-based system segmentation, cooled versus uncooled versus hybrid technology tiers, and military versus aerospace versus security agency end-user categories. CAGRs derived from platform modernization cycle timing and electromagnetic spectrum superiority mandate implementation pacing. Forecast inputs included fighter fleet replacement schedules, destroyer construction programs, and unmanned aerial vehicle procurement trajectories.
Sensitivities concentrate around ITAR export control relaxation timing, EU F-Gas Regulation phased compliance deadlines, and electromagnetic spectrum contestation doctrine durability across allied defense ministries. Forecasts reflect documented assumptions regarding platform integration contract concentration and cryogenic engineering workforce pipeline constraints. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
Space Situational Awareness Sensor and Tracking Performance Test Systems Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Industrial Inertial Systems Market
Communication Navigation & Surveillance
Autonomous Navigation System Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Flight Tracking System Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market
Communication Navigation & Surveillance
Tactical Radio Market