
 Automotive Electric Turbocharger Market | 2026-2036
Automotive Electric Turbocharger Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electric Turbocharger Market Intelligence
European production capacity for high-speed electric motors, a critical component, is shifting toward Tier-1 suppliers specializing in power electronics. This dynamic challenges traditional turbocharger manufacturers to adapt their supply chains and internal expertise. BorgWarner leverages its extensive portfolio in both turbocharging and electrification to offer integrated systems for hybrid vehicles. Garrett Motion specializes in advanced boosting technologies, focusing R&D on eliminating turbo lag in downsized internal combustion engines.
An automotive electric turbocharger is a forced induction device using an electric motor to spin its compressor, independent of exhaust gas flow. This design provides immediate boost at low engine RPMs, eliminating the lag common in conventional turbochargers. The electrically assisted turbocharger technology segment leads due to its integration with mild-hybrid systems. Demand from performance vehicles and commercial vehicles is expanding rapidly as OEMs prioritize both power and compliance with fuel economy standards.
Emissions standards are the primary regulatory driver, with the EU's Euro 7 proposals and the EPA's vehicle emissions rules in the United States setting stringent targets for NOx and CO2. China's Ministry of Ecology and Environment (MEE) enforces its own national standards, compelling both domestic and foreign automakers to adopt cleaner engine technologies. Stakeholder success depends on navigating the complex patent landscape for high-speed motor control and power management systems.
Market Dynamics
The convergence of stringent emissions regulations and the automotive industry's pursuit of enhanced engine performance defines the market's core dynamic. This dual pressure is forcing a technological pivot from conventional turbocharging to electrically assisted systems, fundamentally altering powertrain design and supply chain dependencies.
Growth Catalysts
- Stringent Emissions Mandates:Regulations such as the EU Green Deal and China's dual carbon goals compel automakers to adopt technologies that reduce CO2 and NOx, directly benefiting electric turbocharger adoption for improved engine efficiency.
- Engine Downsizing Trend:The industry-wide move toward smaller, more fuel-efficient internal combustion engines necessitates advanced boosting solutions like electric turbochargers to compensate for power loss and eliminate turbo lag.
- Performance Vehicle Demand:The high-performance and luxury vehicle segments prioritize immediate throttle response and increased power output, creating strong initial demand and a testbed for advanced electric turbocharger technologies.
Market Restraints
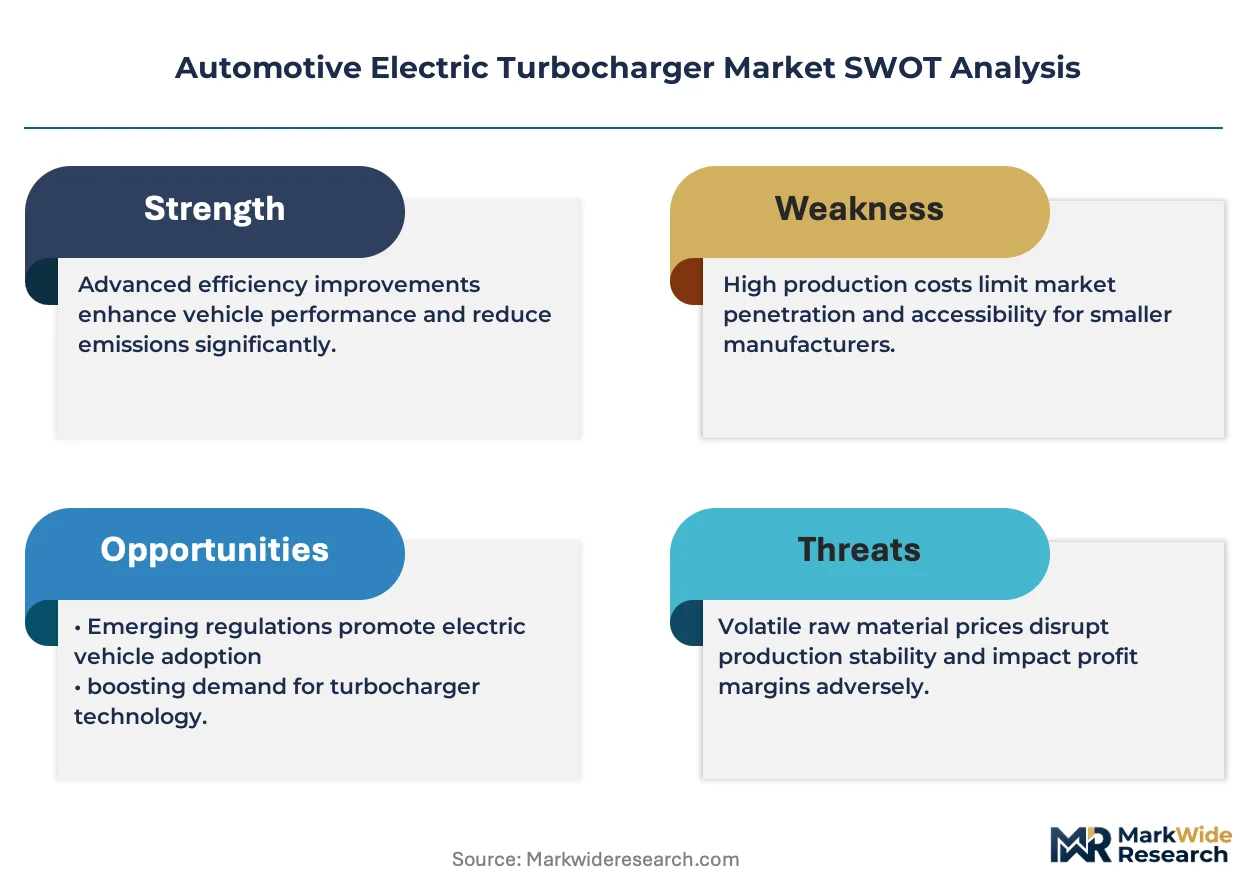
- High System Cost:The inclusion of a high-speed electric motor, sophisticated power electronics, and a dedicated energy storage system significantly increases the cost and complexity compared to traditional turbochargers.
- Thermal Management Complexity:Managing the heat generated by the high-speed electric motor and its associated electronics within the confined, high-temperature environment of an engine bay presents a significant engineering hurdle.
- Supply Chain Bottlenecks:Reliance on a limited number of Tier-1 suppliers for critical components like specialized power inverters and high-speed electric motors creates potential supply chain vulnerabilities and pricing power concentration.
Strategic Opportunities
- Commercial Vehicle Applications:Adapting electric turbocharger technology for heavy-duty diesel engines in commercial trucks and off-highway vehicles offers a substantial new market focused on improving fuel economy and meeting emissions standards.
- Integration with 48V Systems:The growing adoption of 48-volt mild-hybrid architectures provides a synergistic platform for electric turbochargers, creating opportunities for integrated system solutions that maximize efficiency gains.
- Aftermarket and Tuning Segments:Developing retrofit kits and solutions for the automotive aftermarket and performance tuning communities represents an untapped revenue stream, catering to enthusiasts seeking to upgrade older vehicle platforms.
Industry Challenges
- Intellectual Property Navigation:The patent landscape for high-speed motor control algorithms and power management systems is dense and complex, creating potential licensing hurdles and litigation risks for new entrants and established players alike.
- ECU Integration:Ensuring seamless software and hardware integration between the electric turbocharger's control unit and the vehicle's main Engine Control Unit (ECU) is a critical and complex task requiring deep systems-level expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electric Turbocharger Market |
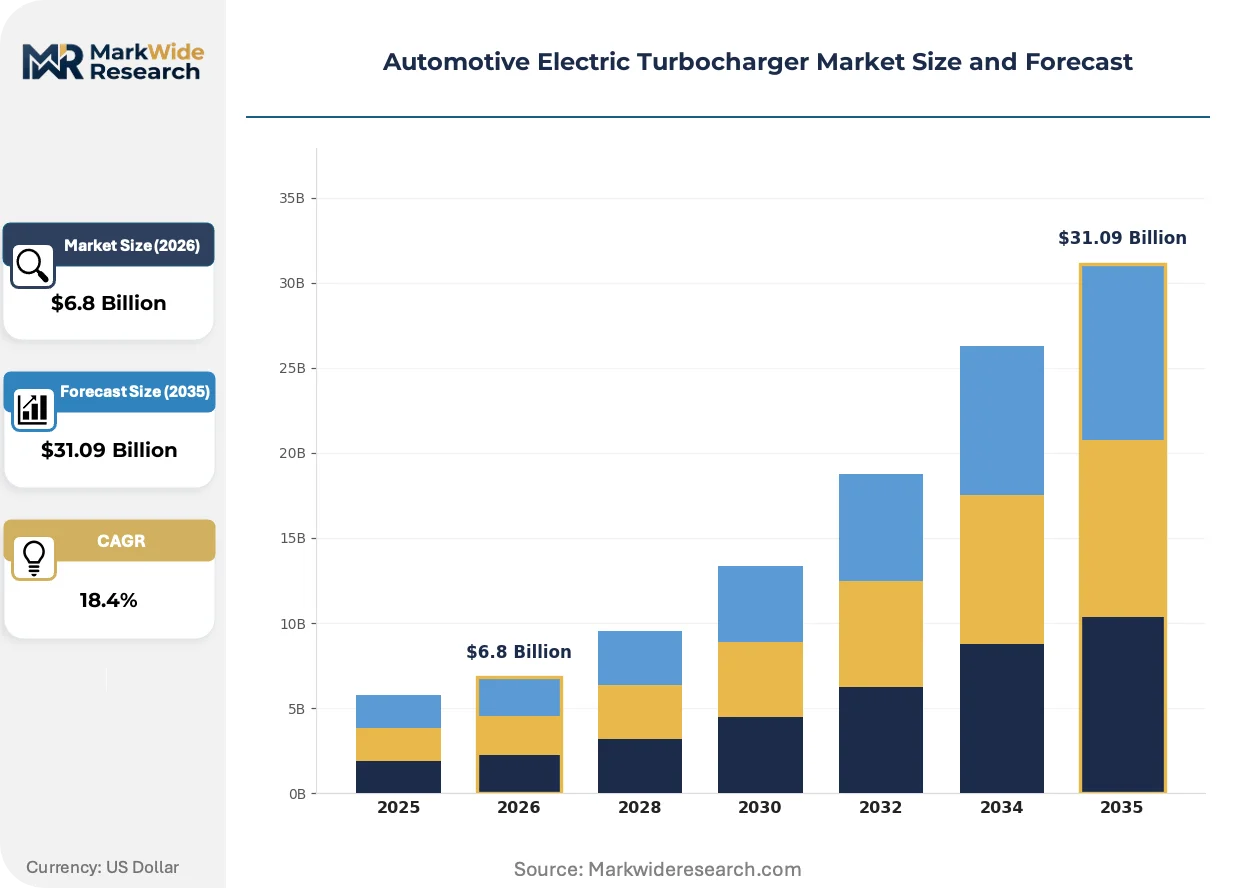
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Twin Stage, Variable Geometry, Sequential, Wastegate Technology: Brushless DC Motor, Permanent Magnet Synchronous Motor, Induction Motor, Electrically Assisted Turbocharger, Variable Frequency Drive Application: Performance Vehicles, Commercial Vehicles, Passenger Cars, Motorsport, Light Trucks End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Garrett Motion, BorgWarner, Cummins, IHI Corporation, Mitsubishi Heavy Industries, Continental, Honeywell International, Bosch Mahle, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electric Turbocharger Market Strategic Shifts & Innovations
The market's evolution is characterized by the deep integration of advanced electronics and software into traditional mechanical systems. This fusion is driven by a need to satisfy conflicting demands for power, efficiency, and regulatory compliance, pushing innovation in control systems and component design.
Advanced predictive boost control software utilizes an array of real-time sensor data and predictive algorithms to anticipate driver inputs and engine load. Performance and luxury vehicle manufacturers are the primary adopters, seeking to deliver instantaneous throttle response. This sophisticated software is automating the pre-spooling of the compressor based on driving style and conditions, effectively engineering turbo lag out of the system.
China's Ministry of Ecology and Environment (MEE) enforces its national standards as part of the country's broader "dual carbon" objectives. This regulatory pressure directly results in the accelerated adoption of cleaner powertrain technologies to meet aggressive targets for fuel consumption and pollutant output. The passenger vehicle segment in China is most affected, responding by designing new hybrid platforms that incorporate electric turbochargers as a core component.
A distinct shift in OEM procurement is underway, with automakers favoring the purchase of fully integrated boosting modules over individual components. This change disrupts the traditional model of sourcing a turbocharger from one supplier and electronics from another, giving an advantage to Tier-1 suppliers offering a complete system. This pattern is particularly evident in Germany's automotive sector, where system-level optimization and supply chain efficiency are paramount.
Automotive Electric Turbocharger Market Segmentation
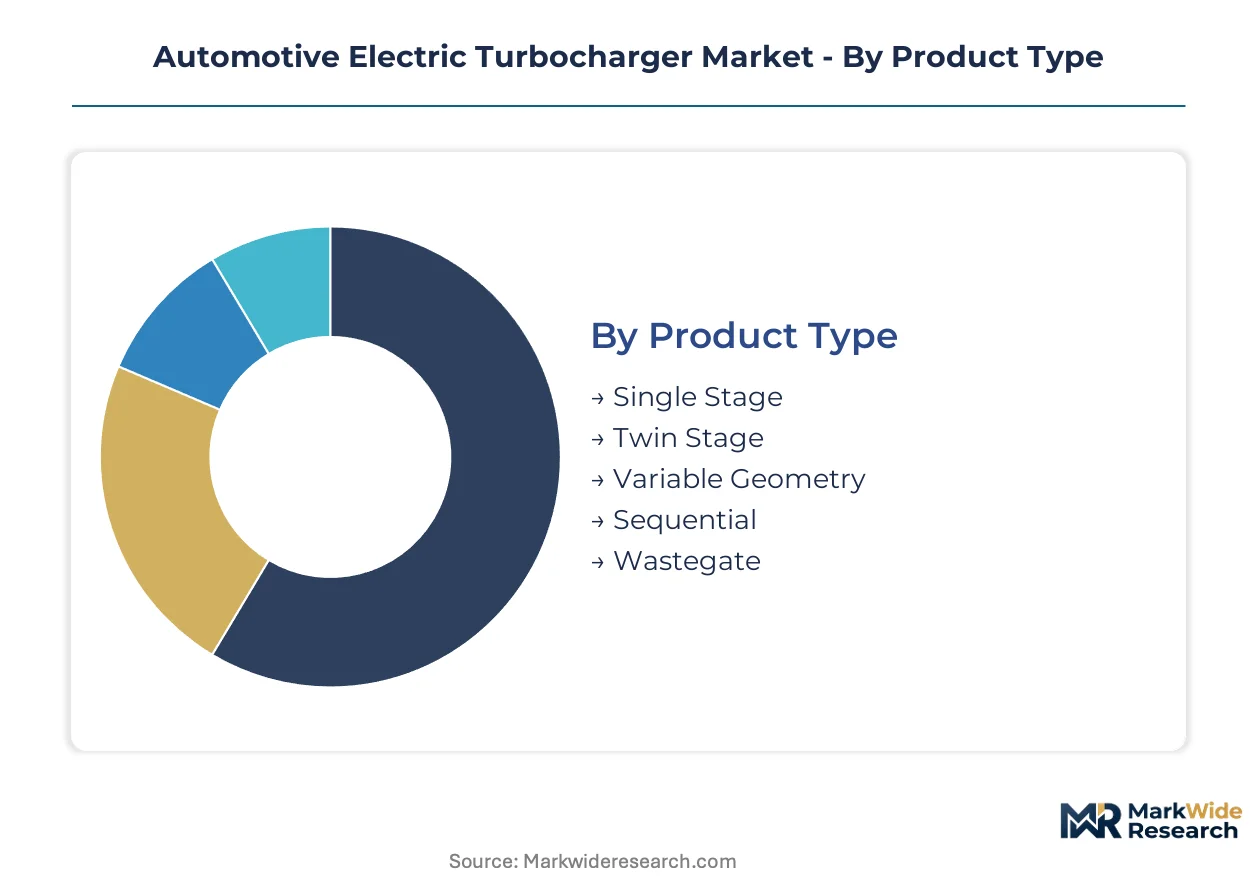
The Automotive Electric Turbocharger Market is segmented to provide a granular understanding of its diverse components and demand drivers. This segmentation highlights how various technologies, product types, applications, and end-users contribute to the market's overall expansion, reflecting the intricate needs of the automotive industry.
Product Type:
The upgrade cycle for automotive electric turbochargers is increasingly driven by the need for enhanced engine response and efficiency, pushing manufacturers towards more advanced designs. Automakers are replacing conventional boosting systems with electrically assisted units to meet both performance and emissions targets.
- Variable Geometry:This type incorporates movable vanes to alter exhaust gas flow to the turbine, optimizing boost pressure across a wider RPM range. Demand concentrates in performance and commercial vehicles in Germany, where precise engine control is critical for both power delivery and emissions compliance.
- Twin Stage:Twin-stage configurations combine two turbochargers of different sizes, often operating in series or parallel, to provide efficient boost across the entire engine speed range. The commercial vehicle segment in China heavily adopts this design to improve fuel economy and reduce emissions in heavy-duty applications.
- Single Stage:A single turbocharger unit provides boost, offering a cost-effective solution for basic engine enhancement in certain vehicle models.
- Sequential:This system uses multiple turbochargers that operate in sequence to optimize performance at different engine speeds.
- Wastegate:A wastegate controls exhaust gas flow around the turbine, regulating boost pressure to prevent over-speeding and protect the engine.
Variable Geometry sits at the top of the volume ranking, with Twin Stage climbing the fastest.
Technology:
The cost tiering within electric turbocharger technology reflects the complexity and integration required, influencing adoption rates across different vehicle segments. Advanced motor types and control systems command higher price points due to their performance benefits.
- Electrically Assisted Turbocharger:This technology integrates a small electric motor to spin the compressor at low engine speeds, eliminating turbo lag and improving transient response. Demand is significant in mild-hybrid systems, particularly within the European passenger car market, to meet stringent Euro 7 emissions proposals.
- Permanent Magnet Synchronous Motor:PMSMs offer high power density and efficiency due to their robust magnetic fields, making them ideal for high-speed, high-performance applications. Performance vehicle manufacturers in Japan increasingly utilize PMSMs for their superior torque delivery and compact design.
- Brushless DC Motor:BLDC motors provide good efficiency and control, serving as a cost-effective option for electrically assisted systems.
- Induction Motor:Induction motors are rugged and reliable, suitable for applications where extreme operating conditions are present.
- Variable Frequency Drive:VFDs precisely control the speed and torque of the electric motor, optimizing turbocharger performance across varying engine loads.
Electrically Assisted Turbocharger technology dominates the market, with Permanent Magnet Synchronous Motors gaining significant traction for their efficiency.
Application:
Volume considerations heavily influence the adoption of electric turbochargers, with certain vehicle categories driving mass market penetration due to their production scale. OEMs prioritize solutions that can be scaled across multiple platforms.
- Performance Vehicles:This segment demands immediate throttle response and maximum power output, making electric turbochargers essential for enhancing driving dynamics. Luxury automakers in Germany are primary adopters, leveraging the technology for superior acceleration.
- Commercial Vehicles:Electric turbochargers in heavy-duty trucks and buses improve fuel efficiency and reduce emissions, directly impacting operating costs. China's commercial vehicle market shows strong demand due to dual carbon goals and the need for cleaner logistics.
- Passenger Cars:Integration into mainstream passenger cars focuses on fuel economy improvements and emissions reduction, particularly in hybrid configurations.
- Motorsport:Racing applications utilize electric turbochargers for extreme performance gains and precise boost control in competitive environments.
- Light Trucks:This segment adopts the technology for improved towing capabilities and better fuel economy in utility vehicles.
Performance Vehicles command the highest value share, while Commercial Vehicles represent a rapidly expanding segment.
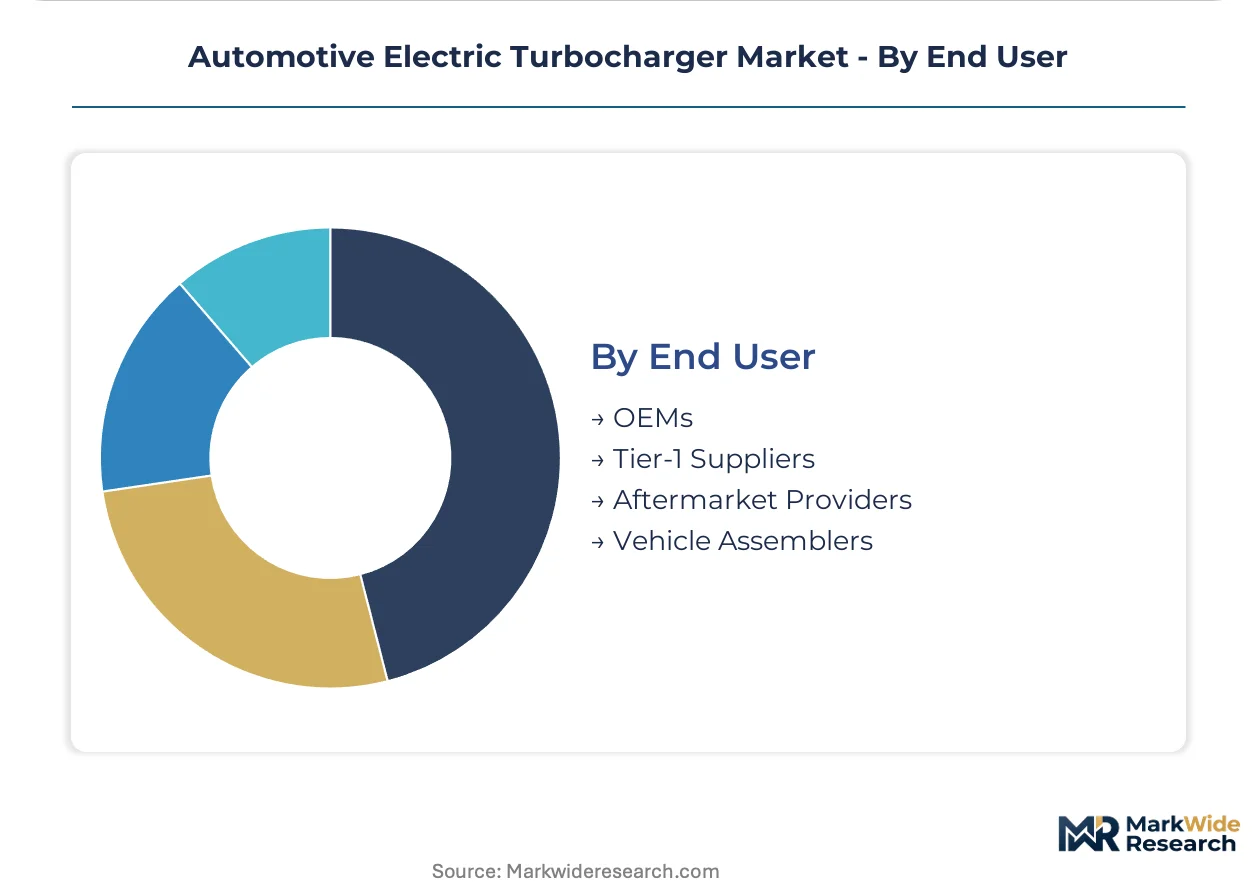
End User:
Supply concentration within the end-user segments dictates procurement strategies and market influence, with established players holding significant leverage. These entities shape product development and integration standards.
- OEMs:Original Equipment Manufacturers integrate electric turbochargers directly into new vehicle designs during the production phase, driving initial market volume. Major automakers in Japan and Germany are key purchasers, focusing on seamless powertrain integration.
- Tier-1 Suppliers:These suppliers develop and provide complete electric turbocharger systems or critical sub-components to OEMs, often specializing in power electronics and motor control. BorgWarner and Garrett Motion exemplify this role, offering integrated solutions to global vehicle manufacturers.
- Aftermarket Providers:Companies offering upgrade kits and replacement parts for existing vehicles cater to performance enthusiasts and repair needs.
- Vehicle Assemblers:These entities primarily integrate pre-assembled components into final vehicles, focusing on efficient assembly processes.
OEMs drive the largest procurement volumes, with Tier-1 Suppliers increasingly centralizing system development and supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive sector prioritizes advanced powertrain solutions, while Japan focuses on hybrid system integration, driving distinct electric turbocharger market dynamics. These leading manufacturing hubs exemplify varied approaches to adopting advanced boosting technologies. Global emissions targets and performance demands shape regional investment patterns.
Germany
Germany's luxury automakers demand immediate throttle response and high-efficiency engines, fueling electric turbocharger adoption for performance vehicles. The EU Green Deal and stringent Euro 7 proposals compel German manufacturers to integrate cleaner technologies. The Stuttgart region, home to major automotive OEMs, integrates electric turbochargers into premium and hybrid vehicle platforms.
Japan
Japanese manufacturers increasingly utilize permanent magnet synchronous motors for their superior torque delivery in hybrid applications. Japan's Ministry of Economy, Trade and Industry (METI) promotes advanced automotive technologies to enhance global competitiveness. The Nagoya automotive cluster develops compact and efficient electric boosting systems for diverse vehicle segments.
China
The Chinese market exhibits strong demand from commercial vehicles and passenger car hybrid platforms due to aggressive emissions targets. China's dual carbon goals and MEE national standards accelerate the adoption of cleaner powertrain solutions. The Yangtze River Delta region sees significant investment in electric turbocharger integration for mass-market vehicles.
United States
American automakers prioritize performance vehicles and light trucks, driving demand for electric turbochargers to improve fuel economy and power delivery. The EPA's vehicle emissions rules and the Inflation Reduction Act (IRA) incentivize cleaner engine technologies. Detroit's automotive hub integrates electric turbochargers into new light-duty truck and SUV models.
France
France's automotive industry integrates electric turbochargers into passenger cars to meet strict European emissions standards. The EU Green Deal and national incentives for low-emission vehicles support this technological shift. The Paris region supports R&D for advanced engine technologies, collaborating with European OEMs on electric boosting solutions.
Automotive Electric Turbocharger Market Key Industry Players
German Tier-1 suppliers anchor one tier of the market, while global turbocharging specialists hold significant positions in advanced boosting technologies. The market exhibits a tiered structure, with established players adapting to electrification alongside new entrants focused on power electronics. Archetypes include traditional mechanical component providers, integrated powertrain solution specialists, and high-speed motor control experts. Strategic partnerships between these diverse entities and portfolio diversification into hybrid systems are dominant competitive moves.
Among the integrated powertrain solution specialists, BorgWarner exemplifies a comprehensive approach, leveraging its extensive portfolio in both turbocharging and electrification to offer integrated systems for hybrid vehicles. Garrett Motion represents a traditional turbocharging expert, focusing R&D on eliminating turbo lag in downsized internal combustion engines, particularly for performance applications. Continental, a broad automotive supplier, occupies a position emphasizing integrated systems for hybrid vehicles, combining advanced boosting technology with sophisticated power electronics and control units.
| Leading Market Players |
|---|
| Garrett Motion |
| BorgWarner |
| Cummins |
| IHI Corporation |
| Mitsubishi Heavy Industries |
| Continental |
| Honeywell International |
| Bosch Mahle |
| Eaton |
| Others |
Cost & Logistics Intelligence
The EU Green Deal mandates for CO2 reductions gate qualified electric turbocharger supply and drive premium pricing for compliant systems. This regulatory pressure influences both component availability and the cost structures across the automotive value chain.
Pricing Analysis
Capacity additions in China are reshaping price floors for basic electrically assisted turbochargers, creating a bifurcated market. The dominant pricing model remains per-unit transactional for integrated modules, transitioning to contract-based long-term offtake agreements with major OEMs. Price differentiation stems from performance tier, integration complexity, and specific certification levels like Euro 7 compliance. Pricing pressure stems from the high R&D costs for advanced motor control systems and component scarcity, while mass-market applications face cost compression. Mass-market passenger car OEMs are most price-sensitive, whereas performance vehicle manufacturers prioritize technology over cost.
Supply Chain Analysis
High-speed electric motor supply rests heavily on specialized Tier-1 manufacturers in Germany and Japan. Raw material dependencies include rare earth magnets for Permanent Magnet Synchronous Motors and advanced semiconductors for power electronics. A structural risk involves single-source vulnerability for critical components like specialized power inverters. The distribution model primarily runs direct from Tier-1 suppliers to OEMs, with these suppliers acting as integrators for complex boosting systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Electric Turbocharger Market offers geographic arbitrage opportunities, driven by differing emissions targets between Europe and China, creating varied demand profiles. This dynamic allows for strategic positioning based on regional regulatory landscapes and market needs.
For Market Incumbents: Deploy strategic partnerships with power electronics specialists to address the threat of new entrants focused solely on electrification. Invest heavily in advanced motor control R&D to maintain a technological lead against evolving performance demands. Diversify the product portfolio into integrated hybrid systems, leveraging existing turbocharging expertise. Focus on intellectual property protection to safeguard core innovations against competitive threats.
For New Entrants and Emerging Players: Online configurators for aftermarket retrofit kits offer new entrants a direct-to-consumer channel, bypassing established OEM supply chains. Target the commercial vehicle segment in China for fuel economy improvements and emissions compliance, a less saturated market. Develop integrated 48V system solutions for mild-hybrid platforms, offering a complete boosting package. Focus on niche performance tuning markets to build brand recognition and specialized expertise.
For Investors and Strategic Acquirers: Valuations sit cheapest among traditional turbocharger manufacturers adapting to electrification, offering long-term upside. This market exhibits sustained growth driven by stringent emissions regulations and performance demands over the next decade. Acquisition targets should include Tier-1 suppliers specializing in power electronics or high-speed motor control systems. Successful integration of electric turbochargers into mainstream passenger car platforms by major OEMs signals a critical inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Power Electronics R&D | This initiative enhances system efficiency and reduces thermal management complexity for critical components. |
| Integrated System Development | This move offers OEMs complete boosting modules, streamlining procurement and integration processes. |
| Commercial Vehicle Application Expansion | This strategy taps into a substantial market segment focused on fuel economy and emissions reduction in heavy-duty engines. |
| Strategic IP Licensing | This approach allows for controlled dissemination of proprietary high-speed motor control algorithms to partners. |
| 48V System Integration Partnership | This collaboration maximizes efficiency gains by synergizing electric turbochargers with growing mild-hybrid architectures. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming a robust data foundation. Primary interviews involved OEM powertrain engineers, Tier-1 component procurement leads, vehicle performance specialists, and regulatory compliance officers. Secondary validation leveraged vehicle production databases, emissions regulatory documents from the EU, EPA, and China MEE, alongside patent databases for motor control systems. Both bottom-up and top-down triangulation methods ensured data consistency and accuracy across all segments.
The forecast framework anchored the projection horizon to historical reference periods, establishing a baseline for future growth. The analysis modeled segmentation dimensions including product type, technology, application, end-user, and regional production clusters. Compound Annual Growth Rates (CAGRs) derived from historical trends and projected technological adoption rates. Key industry-specific forecast inputs included OEM vehicle electrification roadmaps and specific country-level emissions reduction targets.
The model assumes a particular technology adoption path; alternative pathways for full battery electric vehicles would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and supply chain resilience over the projection period. Raw material price volatility, evolving emissions regulations, and rapid shifts in BEV adoption represent specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Automotive Evaporators and Blowers Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Tappet Market
Automotive Parts
Automotive Electric HVAC Compressor Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Automotive Hoses Market
Automotive Parts
Sintered Silencer Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
Automotive Propeller Shaft Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Speedometer Market
Automotive Parts
Engine Oil Pan Market