
 Business Cloud Voip and UC Services Market | 2026-2036
Business Cloud Voip and UC Services Market Size, Share, and Industry Trends Forecast 2026-2036
Business Cloud Voip and UC Services Market Outlook
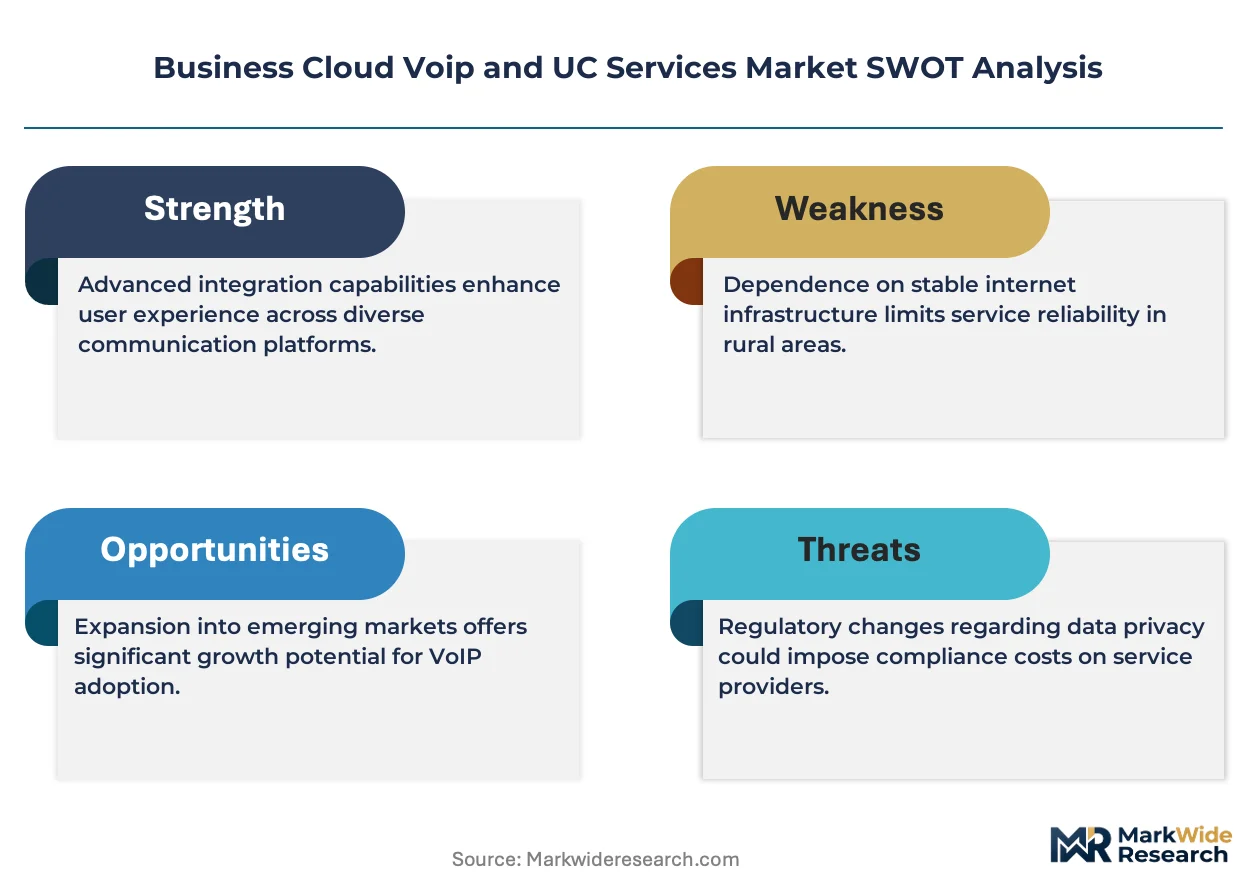
GDPR is pivoting European enterprise procurement toward EU-sovereign data residency clauses in vendor contracts. Microsoft sustains platform dominance through deep Teams-Office integration and government cloud certifications. Cisco leverages its Webex hardware ecosystem to anchor premium installed-base accounts. Zoom competes on video-first architecture, though it navigates enterprise security audits more intensively than incumbents.
Business Cloud VoIP and UC Services encompass internet-protocol voice transmission, session-initiation-protocol signaling, and real-time multimedia collaboration delivered from off-premises infrastructure with guaranteed quality-of-service thresholds. These systems replace legacy PBX hardware with software-defined communications that scale elastically across distributed workforces. Public cloud deployments lead volume due to minimal capital outlay and automatic feature updates, while hybrid cloud configurations capture the fastest expansion as regulated industries demand on-premises call control with cloud bursting for peak capacity. Large enterprises represent the deepest margin pool because of custom integration requirements and dedicated support tiers, though small enterprises generate the highest seat-count growth through standardized subscription bundles.
The FCC enforces network reliability and 911 location-accuracy rules that shape US provider infrastructure investments, while the EU AI Act imposes transparency obligations on automated call-routing and transcription services that vendors must architect around. HIPAA, enforced by HHS OCR, mandates encrypted voice and audit-logged messaging for healthcare subscribers, creating compliance differentiation among platforms. Stakeholders must monitor how NIS2 cybersecurity directives in Europe and emerging state-level data privacy laws in the US reshape cross-border service architectures and vendor qualification criteria.
Market Dynamics
SD-WAN backbone migration is compressing deployment timelines for mid-market buyers while HIPAA interoperability mandates force healthcare providers toward cloud-native contact centers. This structural shift toward software-defined infrastructure rewrites procurement criteria across regulated and unregulated verticals alike.
Growth Catalysts
- FCC Rural Broadband Subsidies:US federal funding programs accelerate enterprise refresh cycles in underserved markets. Mid-market buyers leverage these incentives to replace aging MPLS circuits with elastic cloud connectivity.
- Healthcare Cloud Migration:HIPAA interoperability mandates require encrypted voice and audit-logged messaging. Providers abandon on-premises PBX hardware for compliant cloud-native platforms with guaranteed quality-of-service thresholds.
- Hybrid Work Policy Normalization:Post-pandemic distributed workforce models sustain seat-count expansion. Enterprises demand elastic capacity that scales across geographic clusters without capital-intensive hardware refreshes.
Market Restraints
- EU AI Act Compliance Burden:Automated call-routing and transcription services face transparency obligations. Vendors must architect explainability features that extend development cycles and raise implementation costs.
- Legacy PSTN Interconnection Costs:Carriers maintain tariffed access charges for public switched telephone network termination. Cloud providers absorb these input costs, compressing margins on low-ARPU small enterprise segments.
- Skilled SIP Engineering Scarcity:Session initiation protocol expertise concentrates among veteran telecommunications engineers. Talent pipeline gaps delay complex hybrid cloud deployments for regulated industries.
Strategic Opportunities
- NIS2 Cybersecurity Alignment:European network and information security directives create vendor qualification barriers. Compliant platforms capture public sector and critical infrastructure contracts with multi-year terms.
- AI-Native Conversation Intelligence:Real-time transcription converges with predictive analytics for sales and support workflows. Early movers bundle these capabilities into premium subscription tiers.
- India PLI Scheme Leverage:Production-linked incentives for electronics manufacturing attract cloud hardware assembly. Regional data center buildout reduces latency for Asia-Pacific enterprise subscribers.
Industry Challenges
- Multi-Cloud Orchestration Complexity:Enterprises demand seamless failover between AWS, Azure, and Google Cloud voice infrastructure. Engineering teams struggle to maintain consistent quality-of-service across heterogeneous environments.
- E911 Location Accuracy Certification:FCC mandates require precise dispatchable address validation for nomadic users. Compliance testing extends onboarding timelines for distributed workforce deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Cloud Voip and UC Services Market |
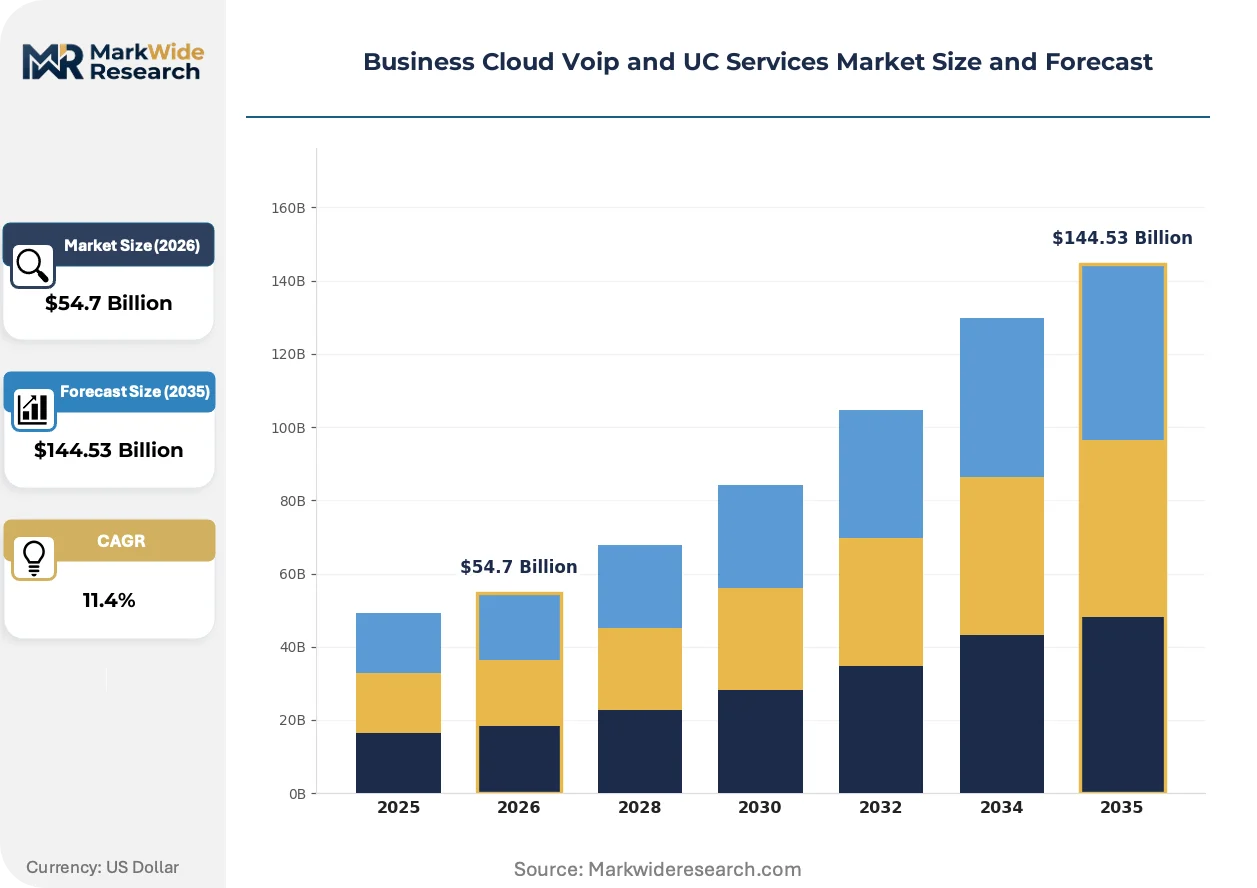
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $144.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: VoIP, Unified Communications, Video Conferencing, Collaboration Tools Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Small Enterprises, Medium Enterprises, Large Enterprises, Government Agencies Pricing Model: Subscription-Based, Pay-As-You-Go, Freemium, Tiered Pricing |
| Companies Covered | Cisco, Microsoft, Zoom, RingCentral, 8x8, Verizon Enterprise, AT&T, Nextiva, Sangoma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Cloud Voip and UC Services Market Strategic Shifts
Containerized microservices architecture is fragmenting monolithic UC platforms into composable components. Buyers assemble best-of-breed capabilities rather than accepting unified suite limitations, forcing vendors to expose APIs and interoperability layers.
CPaaS (Communications Platform as a Service) infrastructure is modularizing enterprise voice stacks. Financial services and retail buyers embed programmable SMS, voice, and video into customer-facing applications without managing underlying infrastructure. This decomposition compresses time-to-market for omnichannel experiences while shifting vendor relationships from seat-based subscriptions to usage-metered developer contracts.
The EU AI Act imposes algorithmic transparency requirements on automated call-routing systems. Vendors must document decision logic for AI-driven queue management and sentiment-based escalation. Healthcare and financial services subscribers in Germany and France now require audit trails that trace routing decisions to training data provenance, reshaping RFP technical specifications.
Enterprise buyers now unbundle implementation and support services from core platform subscriptions. Mid-market procurement teams engage specialized systems integrators for migration and change management, treating UCaaS as commodity infrastructure. This pattern concentrates most visibly in United States manufacturing verticals, where IT departments lack headcount for complex cutover orchestration.
Business Cloud Voip and UC Services Market Segmentation
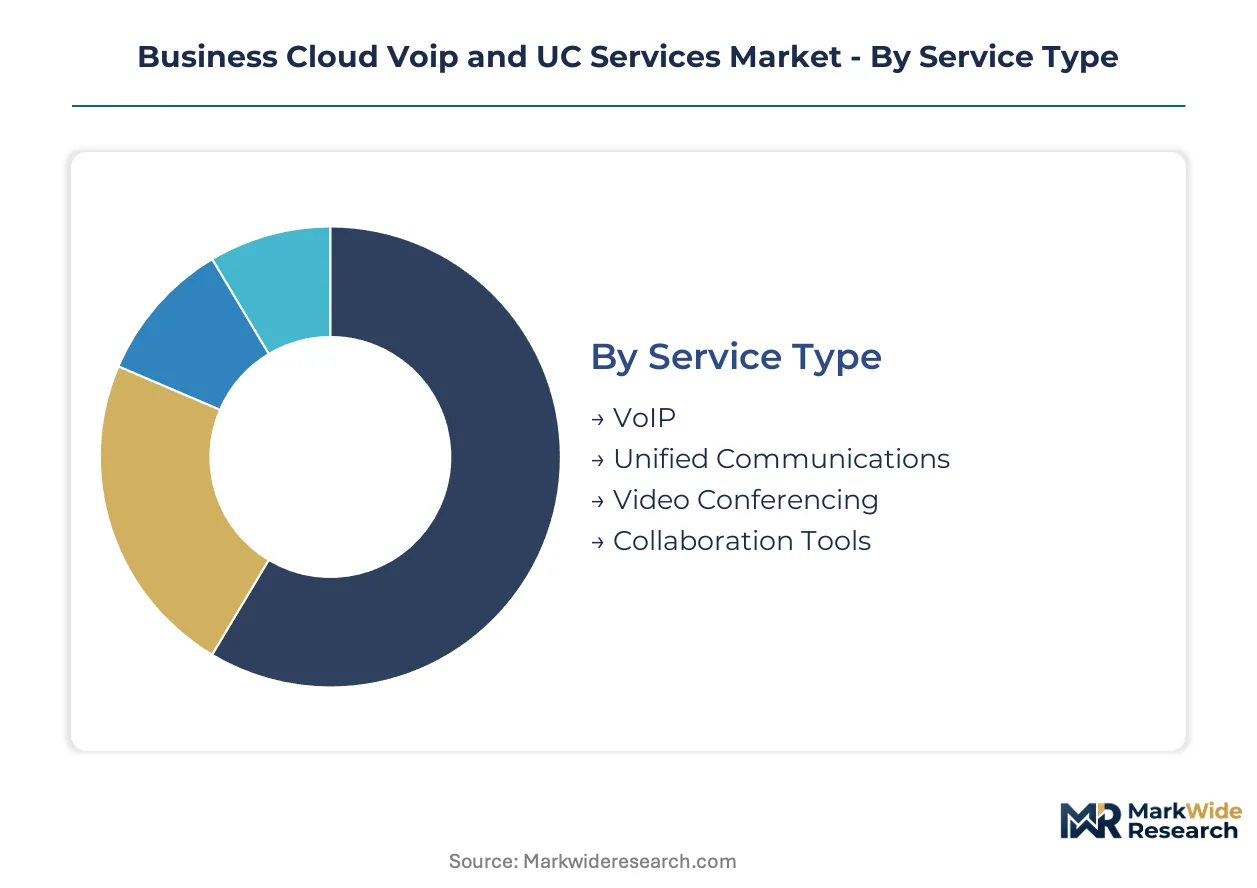
Cloud VoIP and UC services fragment across deployment architecture, customer scale, and commercial terms. Each dimension shapes vendor engineering priorities and margin structures differently.
Service Type:
Volume concentrates in commoditized voice transport while premium margins attach to integrated collaboration suites.
- VoIP:Session-initiation-protocol voice transmission replaces legacy PSTN circuits with packet-switched calling. Small enterprises in the United States drive seat-count expansion through FCC rural broadband subsidy programs that underwrite connectivity upgrades.
- Unified Communications:Integrated messaging, presence, and voice threading converge into single-pane workflows. Large enterprises with distributed workforces demand elastic capacity scaling across geographic clusters without hardware refresh cycles.
- Video Conferencing:Real-time multimedia sessions with guaranteed quality-of-service thresholds.
- Collaboration Tools:Persistent workspaces combining synchronous and asynchronous communication modes.
Mature deployment sits with VoIP. Newer deployment is concentrated in Unified Communications.
Deployment Model:
Capital intensity separates self-managed infrastructure from consumption-metered alternatives.
- Public Cloud:Multi-tenant infrastructure with automatic feature updates and minimal capital outlay. Mid-market buyers across manufacturing verticals compress deployment timelines by abandoning MPLS backbones for elastic cloud connectivity.
- Hybrid Cloud:On-premises call control with cloud bursting for peak capacity. Healthcare providers in the United States migrate contact centers to satisfy HIPAA interoperability mandates while retaining local encryption management.
- Private Cloud:Single-tenant dedicated infrastructure with custom security boundaries.
- On-Premises:Self-hosted hardware with full operational control and capital depreciation schedules.
On-Premises retains installed-base accounts with compliance constraints. Hybrid Cloud is climbing the fastest as regulated industries balance control with elasticity.
End User:
Customer scale dictates integration complexity and support tier economics.
- Large Enterprises:Custom integration requirements with dedicated support tiers and API orchestration. Financial services buyers embed programmable communications into customer-facing applications through CPaaS consumption models.
- Small Enterprises:Standardized subscription bundles with rapid self-service provisioning. Seat-count expansion accelerates through post-pandemic hybrid work policy normalization across United States professional services firms.
- Medium Enterprises:Balanced configuration flexibility with managed migration services.
- Government Agencies:FedRAMP or equivalent certification requirements with sovereign data residency clauses.
Government Agencies anchor longest contract terms. Small Enterprises generate steepest seat-count velocity.
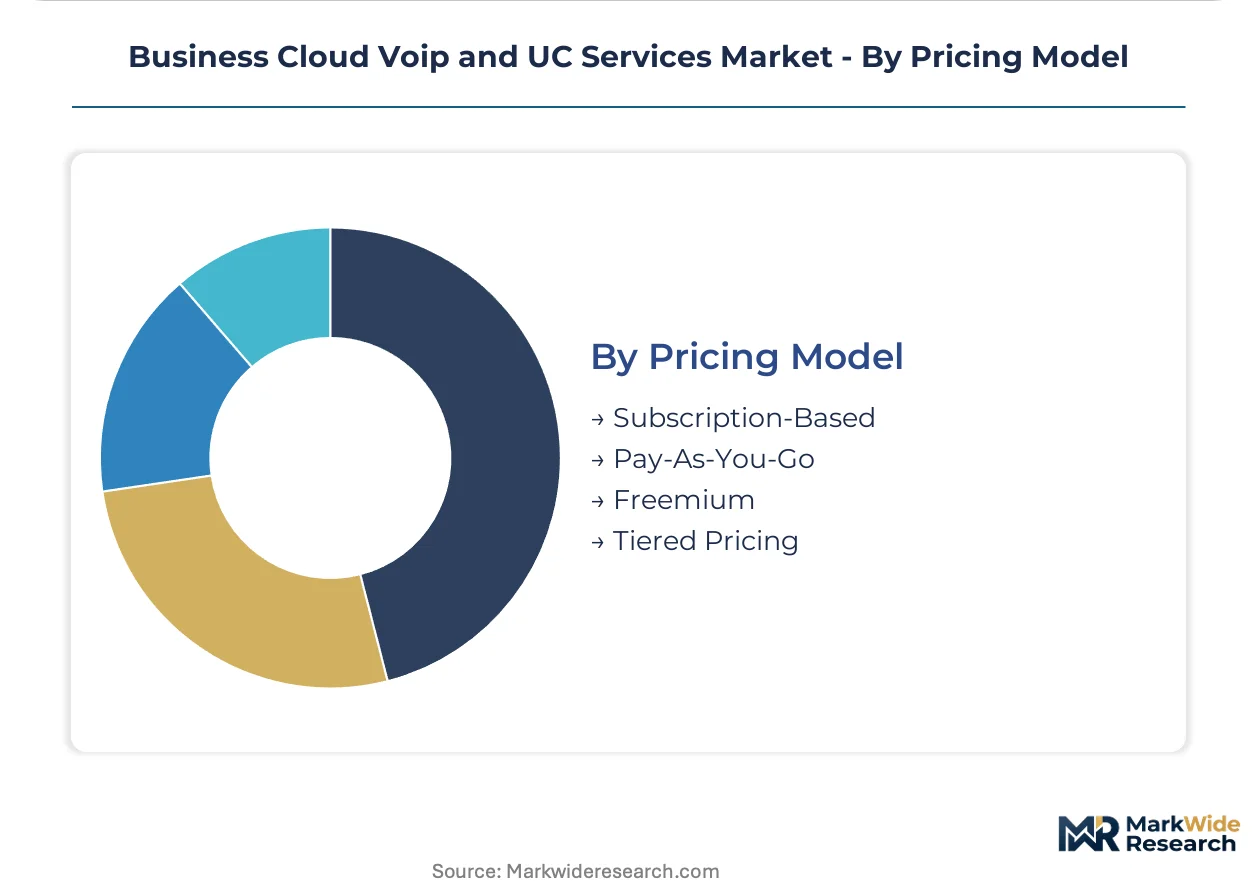
Pricing Model:
Revenue predictability trades off against usage flexibility across commercial structures.
- Subscription-Based:Fixed monthly per-seat fees with bundled feature tiers. Large enterprises prefer annual commitments with volume discounts that stabilize vendor cash flows and reduce procurement friction.
- Pay-As-You-Go:Metered consumption tied to actual minutes, messages, or API calls. Developer-centric buyers in retail and logistics optimize variable costs against seasonal demand patterns.
- Freemium:Base functionality with premium capability unlocks.
- Tiered Pricing:Three-level differentiation across premium, standard, and economy capability bundles.
Subscription-Based dominates enterprise procurement. Pay-As-You-Go is gaining share fastest among application-embedded communications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise demand concentrates in the United States, where federal broadband subsidies and hybrid work policies sustain refresh cycles. Europe follows with GDPR-driven procurement shifts toward sovereign data residency. Asia-Pacific expansion accelerates through manufacturing-linked electronics incentives and regional data center buildout.
United States
FCC rural broadband subsidies and post-pandemic hybrid work policies drive mid-market MPLS-to-SD-WAN migrations. HIPAA interoperability mandates from HHS OCR push healthcare providers toward cloud-native contact centers with encrypted voice requirements. Dallas-Fort Worth and Northern Virginia data center clusters anchor domestic cloud infrastructure expansion for low-latency enterprise services.
Germany
Industrial manufacturing hubs demand resilient unified communications for distributed production facilities. EU AI Act transparency obligations reshape automated call-routing procurement specifications. Frankfurt and Munich enterprise corridors lead cloud migration velocity among automotive and precision engineering verticals.
United Kingdom
Financial services firms in London embed CPaaS capabilities into customer-facing trading and support applications. Post-Brexit data localization requirements influence vendor contract negotiations for cross-border voice traffic. The Thames Valley technology corridor concentrates SaaS procurement decision-making for mid-market professional services.
India
IT services exporters and domestic enterprises scale seat-count through standardized subscription bundles. PLI scheme incentives for electronics manufacturing attract cloud hardware assembly and regional data center investment. Bengaluru and Hyderabad technology clusters drive developer-centric communications platform adoption.
Japan
Large enterprises with aging on-premises PBX infrastructure pursue hybrid cloud configurations for compliance retention. METI digital transformation directives accelerate legacy system modernization timelines. Tokyo and Osaka metropolitan areas concentrate financial services and manufacturing demand for guaranteed quality-of-service thresholds.
Business Cloud Voip and UC Services Market Competitive Environment
United States technology conglomerates anchor the platform tier; European and Asia-Pacific specialists hold vertical-specific positions. Market structure tilts toward consolidated platform dominance with persistent fragmentation in compliance-heavy niches. Three archetypes prevail: full-stack suite providers, video-first challengers, and carrier-integrated incumbents. Competitive moves concentrate on API ecosystem expansion and FedRAMP-equivalent certification acquisition.
Within the full-stack suite tier, Microsoft and Cisco exemplify platform consolidation through deep productivity software integration and hardware ecosystem anchoring respectively. Zoom occupies a position as the video-first challenger navigating enterprise security audit intensity. Among carrier-integrated alternatives, Verizon Enterprise represents legacy telecommunications infrastructure repurposed for cloud delivery models.
| Leading Market Players |
|---|
| Cisco |
| Microsoft |
| Zoom |
| RingCentral |
| 8x8 |
| Verizon Enterprise |
| AT&T |
| Nextiva |
| Sangoma |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up UCaaS specialists now dominate mid-market consolidation, concentrating pricing power among fewer platform owners while compressing procurement timelines through pre-negotiated carrier interconnects. This ownership pattern tightens margin discipline across voice transport tiers and accelerates vendor qualification barriers for new entrants.
Pricing Analysis
Premium pricing for sub-30-day deployment lead times now commands 15-25% uplifts over standard 90-day provisioning cycles, while spot inventory of pre-certified SIP trunking capacity trades at discounts during carrier oversupply windows. The dominant structure is three-tier subscription pricing across premium, standard, and economy capability bundles, with differentiation hinging on API access depth and dedicated support tiers. Cost compression in small enterprise voice segments is intensifying because legacy PSTN termination tariffs absorb margin. Healthcare providers show least price sensitivity due to HIPAA compliance mandates, while retail and logistics buyers optimize seasonal demand through metered consumption models.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing is reshaping cloud hardware sourcing, drawing assembly capacity from China and Taiwan toward Bengaluru and Hyderabad regional data centers. Infrastructure deployment draws from Taiwanese server components, South Korean memory modules, and domestic Indian cabinet assembly. Single-source vulnerability concentrates in specialized Session Border Controller chipsets from limited foundry sources. Distribution runs through hyperscaler marketplaces and direct carrier partnerships with systems integrators anchoring mid-market migration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform-scale players, with EU AI Act compliance costs forcing sub-scale vendors toward acquisition or exit. Margin compression in commoditized voice transport eliminates standalone specialists lacking adjacent collaboration revenue.
For Market Incumbents: Anticipate regulatory fragmentation as NIS2, GDPR, and emerging state-level US privacy laws multiply certification requirements. Defensive moves should prioritize FedRAMP-High and EU sovereign cloud qualification to anchor public sector contracts, while embedding conversation intelligence APIs to prevent disintermediation by CPaaS-native challengers. Carrier-integrated incumbents must renegotiate PSTN termination tariffs to preserve small enterprise margins.
For New Entrants and Emerging Players: The price-point gap between premium enterprise suites and economy small-business bundles offers white-space for mid-market vertical specialists. Target healthcare contact centers in secondary US metropolitan areas where HIPAA expertise scarcity delays incumbent deployments. Go-to-market should emphasize pre-configured compliance templates and rapid SD-WAN integration to compress procurement cycles below 60 days.
For Investors and Strategic Acquirers: NIS2 cybersecurity directive enforcement is the leading indicator that European public sector contract access will consolidate among compliant platforms. Long-term viability favors platforms with multi-cloud orchestration capabilities and established carrier interconnects over point-solution voice providers. Acquisition targets should show 40%+ recurring revenue concentration and demonstrated FedRAMP or equivalent certification progress.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Teams-Office anchoring captures enterprise productivity workflows and reduces churn. |
| Geographic Expansion | India PLI scheme leverage reduces Asia-Pacific latency and attracts regional enterprise subscribers. |
| Acquisition of Specialist Firm | CPaaS-native developers add programmable communications capabilities to legacy voice platforms. |
| Strategic Partnership | SD-WAN vendor alliances compress mid-market deployment timelines and expand channel reach. |
| Product Launch | AI-native conversation intelligence bundles predictive analytics into premium subscription tiers. |
Study Parameters
Document review covered FCC rulemakings, HHS OCR HIPAA guidance, EU AI Act implementation texts, and hyperscaler infrastructure disclosure filings, complemented by interviews with CTOs at mid-market enterprises, UCaaS platform engineers, healthcare IT compliance officers, and carrier wholesale product managers. Secondary validation drew from SEC 10-K infrastructure segment disclosures, TRAI telecom subscription data, and EU NIS2 transposition tracking databases. Bottom-up seat-count modeling and top-down IT spending allocation analysis were triangulated against vendor-reported subscriber metrics.
Segment-level value outputs were derived through elasticity-adjusted pricing models across deployment architecture, customer scale, and vertical regulatory intensity. The analytical framework incorporated hybrid cloud adoption velocity, CPaaS consumption growth patterns, and healthcare interoperability mandate compliance timelines. CAGRs were computed from normalized baseline values with cross-validation against carrier capex cycle indicators and enterprise refresh survey data.
Inputs from hyperscaler data center expansion announcements and carrier SD-WAN deployment disclosures were available through the study window; gaps in real-time small enterprise churn rates and private-cloud pricing transparency introduce uncertainty bands around mid-market penetration forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Unified Monitoring Market
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
High Definition HD Voice Market
Unified Communications
Ucaas in Banking Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
Europe IP Telephony and Unified Communications As-A-Service Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Global Mobile Voip Market
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
ASEAN Unified Communication-As-A-Service Market
Unified Communications
United States SMS and MMS Market
Unified Communications
Unified Communication Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Cloud UC Calling Market