
 Europe IP Telephony and Unified Communications As-A-Service Market | 2026-2036
Europe IP Telephony and Unified Communications As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Europe IP Telephony and Unified Communications As-A-Service Market Foresight
The capital-intensity divergence between hyperscale platform operators and regional service providers is unwinding competitive dynamics across Europe. Microsoft Corporation leverages its Azure cloud backbone to anchor enterprise deployments in Northern Europe. Cisco Systems Inc. competes through specialized hardware-software bundles that sustain channel partner loyalty. RingCentral Inc. differentiates via API-first architecture that positions its stack for mid-market expansion.
IP Telephony and Unified Communications As-A-Service delivers voice, video, messaging, and contact center functions through cloud-hosted infrastructure with SIP trunking, WebRTC protocols, and SLA-guaranteed uptime parameters. The primary commercial purpose is replacing on-premise PBX systems with elastic, subscription-based collaboration platforms. Public cloud deployment dominates volume, though hybrid cloud configurations capture margin pools from regulated European enterprises requiring data residency. Video conferencing and contact center service types are expanding fastest as distributed work patterns persist. API integration levels are deepening as CRM and ERP connectivity becomes standard rather than premium.
GDPR, the EU AI Act, and the NIS2 Directive shape vendor obligations around data sovereignty, automated decision transparency, and critical infrastructure security across member states. EMA guidelines for pharmaceutical communications and national healthcare regulators in Germany and France impose additional sector-specific compliance layers. Stakeholders must monitor how the European Commission's cloud certification schemes reshape procurement criteria and vendor eligibility before committing to long-term platform contracts.
Market Dynamics
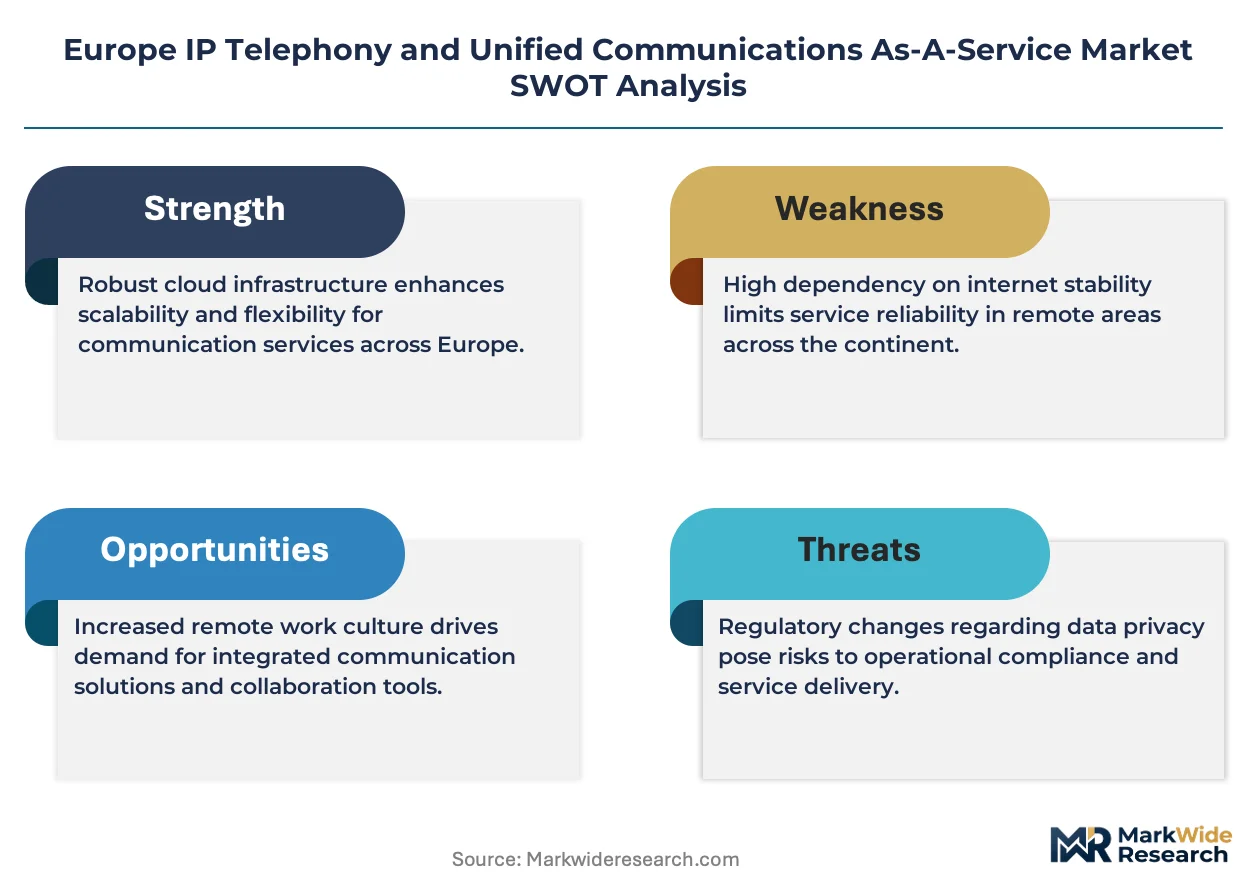
GDPR enforcement and the EU AI Act are compressing vendor qualification timelines while simultaneously expanding procurement budgets for compliant cloud communications infrastructure across European enterprises.
Growth Catalysts
- GDPR Data Residency Mandates:Organizations across Germany, France, and the United Kingdom are retiring on-premise PBX systems to satisfy data sovereignty requirements, accelerating cloud migration timelines.
- Healthcare Digitalization:EMA guidelines for pharmaceutical communications and national healthcare regulators in Germany and France are mandating secure, auditable collaboration platforms.
- WebRTC Protocol Maturation:Browser-native real-time communications are eliminating client software dependencies, reducing deployment friction for mid-market enterprises.
Market Restraints
- Hyperscale Cloud Concentration:Infrastructure dependency on a limited set of pan-European cloud providers creates single-point-of-failure risk for SLA-guaranteed uptime commitments.
- NIS2 Directive Compliance Costs:Critical infrastructure classification for healthcare and financial services imposes mandatory security audit burdens that inflate total cost of ownership.
- Legacy SIP Interoperability:Existing on-premise telephony investments in hybrid TDM-IP environments resist seamless cloud migration without gateway infrastructure expenditure.
Strategic Opportunities
- Eastern European Expansion:Poland, Romania, and the Czech Republic exhibit underpenetrated mid-market segments with accelerating foreign direct investment in shared service centers.
- Contact Center AI Convergence:Integration of large language models with workforce management platforms creates upsell potential beyond core telephony subscriptions.
- EU Green Deal Procurement Incentives:Public sector tenders increasingly weight energy-efficient cloud infrastructure, favoring vendors with carbon-neutral data center certifications.
Industry Challenges
- Certification Timeline Compression:EU Cloud Certification Scheme eligibility requirements demand extensive documentation that delays go-to-market for new market entrants.
- Hybrid Architecture Complexity:Enterprises maintaining split on-premise and cloud estates face configuration management burdens that strain internal IT capabilities.
- API Security Skill Scarcity:Deep CRM and ERP integration requirements expose shortage of developers proficient in OAuth 2.0 and zero-trust architecture implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe IP Telephony and Unified Communications As-A-Service Market |
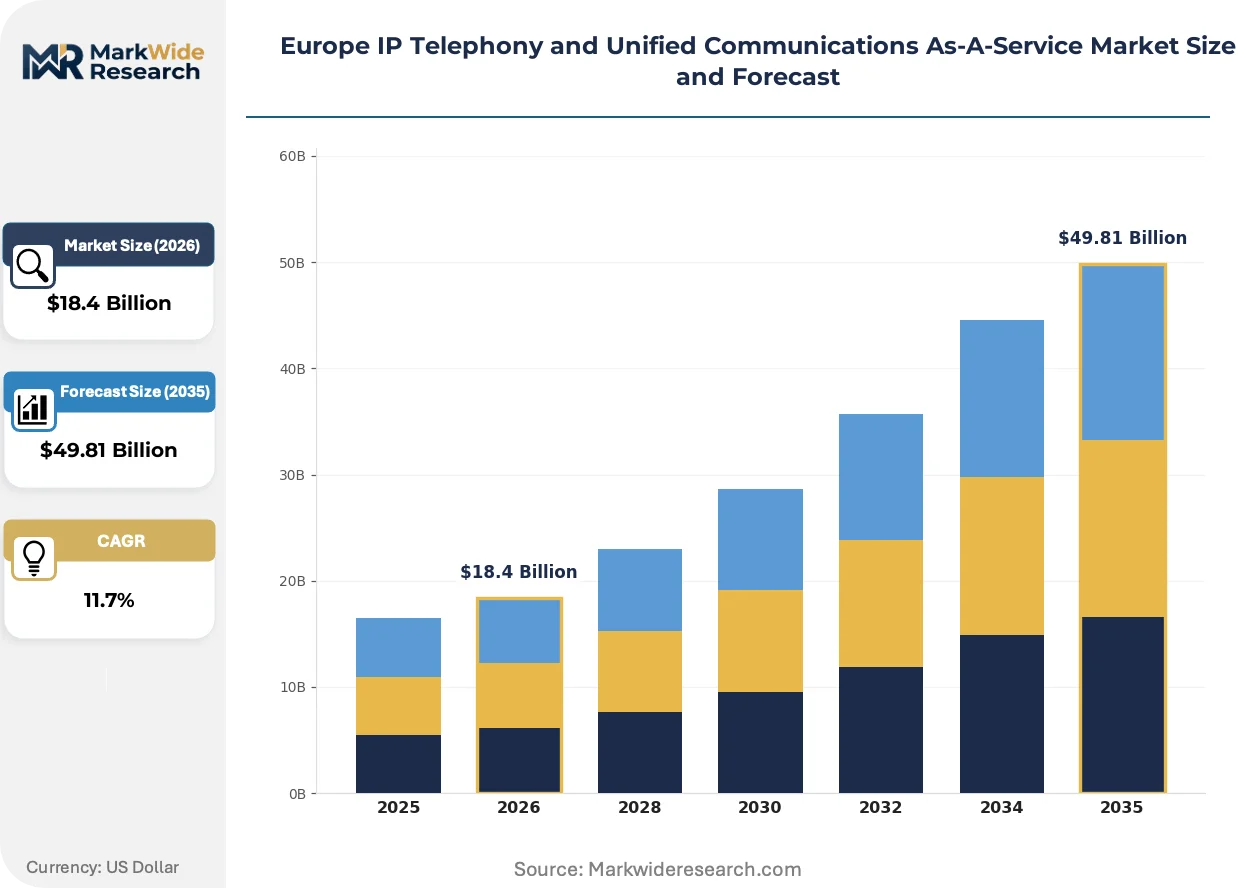
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $49.81 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Service Type: VoIP, Video Conferencing, Instant Messaging, Contact Center End User: SMEs, Large Enterprises, Government, Healthcare Integration Level: API Integration, CRM Integration, ERP Integration, Standalone |
| Companies Covered | Microsoft Corporation, Cisco Systems Inc., RingCentral Inc., 8x8 Inc., Mitel Networks Corporation, Vonage Holdings Corp., Avaya Holdings Corporation, Dialpad Inc., Dstny, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe IP Telephony and Unified Communications As-A-Service Market Shifts & Advancements
Edge computing deployment patterns are redistributing processing loads across European communications infrastructure. Vendor roadmaps increasingly emphasize sovereign cloud configurations.
Embedded communications platforms are miniaturizing voice and video functionality into business application workflows. Financial services institutions in the United Kingdom are adopting these lightweight integrations fastest. This architecture is miniaturizing the traditional standalone UCaaS client into invisible background infrastructure.
The EU AI Act transparency obligations are mandating algorithmic decision logging for automated call routing and sentiment analysis. Vendors must now maintain audit trails for machine-learning model outputs. Healthcare contact centers in France face the steepest compliance curve as ANSM guidelines intersect with automated quality management systems.
Enterprise buying committees are consolidating vendor relationships around platform ecosystems rather than best-of-breed point solutions. System integrators and managed service providers are capturing margin pools previously retained by direct vendor sales. This concentration is most pronounced in German manufacturing verticals where procurement functions centralize IT spending authority.
Europe IP Telephony and Unified Communications As-A-Service Market Segmentation
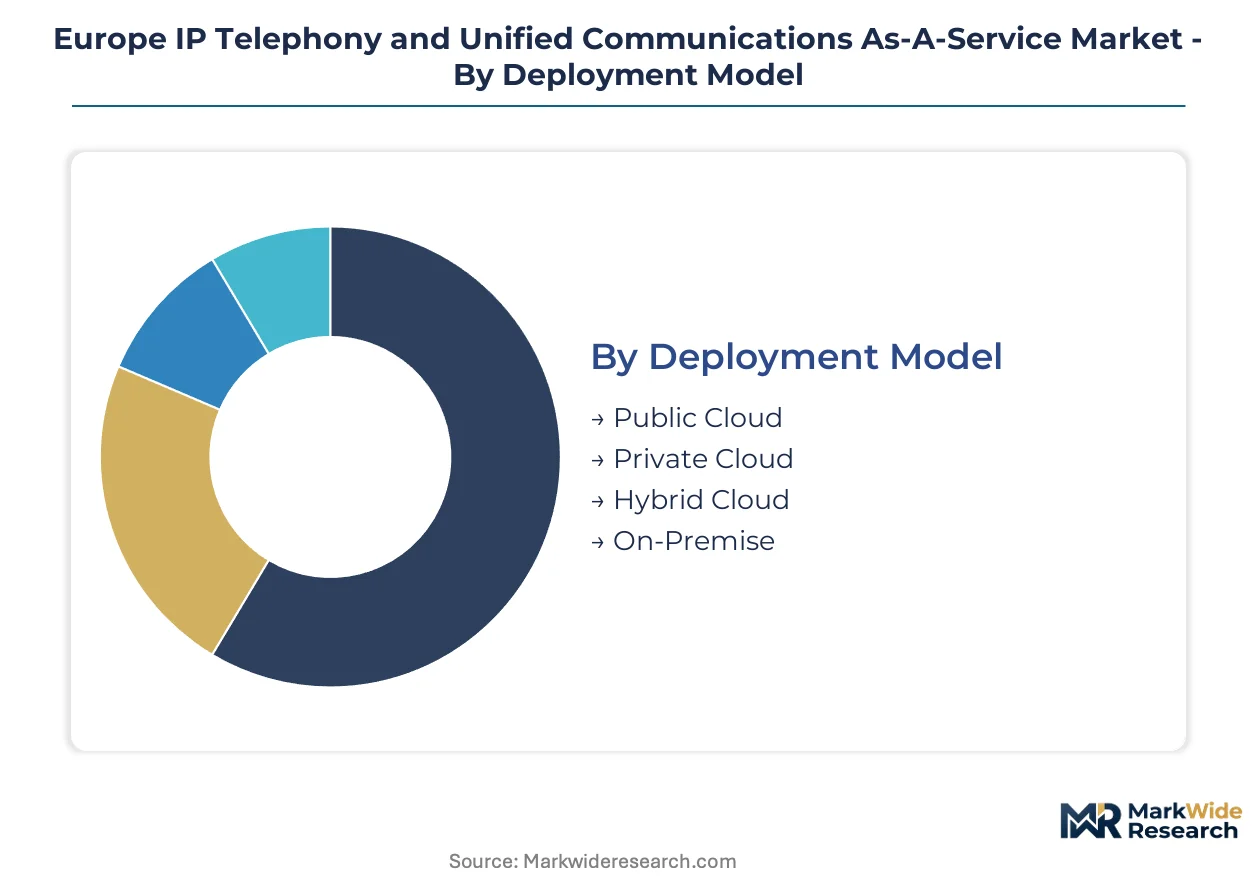
Segmentation in European UCaaS reveals how compliance mandates and infrastructure heterogeneity fragment procurement patterns. Deployment choices increasingly correlate with sector-specific data sovereignty requirements rather than pure cost optimization.
Deployment Model:
Substitution pressure from sovereign cloud alternatives is intensifying as GDPR enforcement hardens data localization expectations.
- Public Cloud:Multi-tenant infrastructure delivers elastic capacity scaling through pan-European hyperscale facilities. German financial services and French pharmaceutical firms concentrate demand here as they prioritize rapid provisioning over dedicated resource allocation. Microsoft Azure and AWS dominate substrate provision.
- Hybrid Cloud:Split architectures maintain sensitive call recordings on-premise while routing standard traffic through cloud SIP trunks. UK healthcare trusts and German automotive suppliers favor this configuration to satisfy NIS2 Directive audit requirements without full infrastructure replacement. Configuration complexity inflates total cost of ownership.
- Private Cloud:Single-tenant deployments hosted in certified European data centers serve defense contractors and critical infrastructure operators.
- On-Premise:Legacy PBX retention persists in Eastern European manufacturing facilities with limited IT modernization budgets.
Public Cloud retains volume leadership; Hybrid Cloud holds the steepest expansion curve as regulated enterprises seek middle-ground compliance architectures.
Service Type:
Cost tier differentiation separates commodity voice from premium collaboration suites with AI-augmented features.
- Contact Center:Omnichannel platforms integrate voice, chat, and social media routing with workforce management dashboards. French healthcare contact centers under ANSM supervision and UK insurance claims operations drive adoption of sentiment analysis and automated quality scoring. Real-time transcription and post-call summarization command premium pricing.
- Video Conferencing:WebRTC-based browser solutions eliminate client installation friction for mid-market distributed teams. German professional services firms and Dutch legal practices standardize on these platforms for client consultations requiring visual document collaboration. Persistent virtual rooms and recording retention policies differentiate vendor tiers.
- VoIP:SIP trunking replacement of ISDN circuits continues across European SMEs seeking per-seat pricing predictability.
- Instant Messaging:Persistent chat workspaces with threaded conversations and file sharing compete against standalone Slack or Microsoft Teams deployments.
VoIP retains volume leadership; Contact Center holds the steepest expansion curve as AI augmentation expands addressable use cases.
End User:
Customer type determines integration depth and security certification requirements rather than raw seat count.
- Large Enterprises:Multi-site deployments across 10,000+ users demand global dial plans, local number portability in 20+ countries, and dedicated technical account management. German automotive OEMs and UK banking groups concentrate procurement authority at headquarters level, favoring platform ecosystems over point solutions. Custom development portals and private marketplace apps justify enterprise licensing premiums.
- Healthcare:HIPAA-equivalent compliance under national regulators—ANSM in France, BfArM in Germany, MHRA in the UK—mandates encrypted recordings, access audit trails, and business associate agreements. Telemedicine expansion and pharmaceutical field force coordination drive specialized requirements for mobile-first clinical collaboration.
- SMEs:50-500 seat organizations prioritize rapid deployment and per-user pricing without capital expenditure.
- Government:Public sector tenders in France, Germany, and Italy impose EU Cloud Certification Scheme eligibility and carbon-neutral data center requirements.
SMEs retain volume leadership; Healthcare holds the steepest expansion curve as regulatory digitization mandates accelerate procurement timelines.
Integration Level:
Application maturity determines whether communications embed invisibly within workflows or remain standalone utilities.
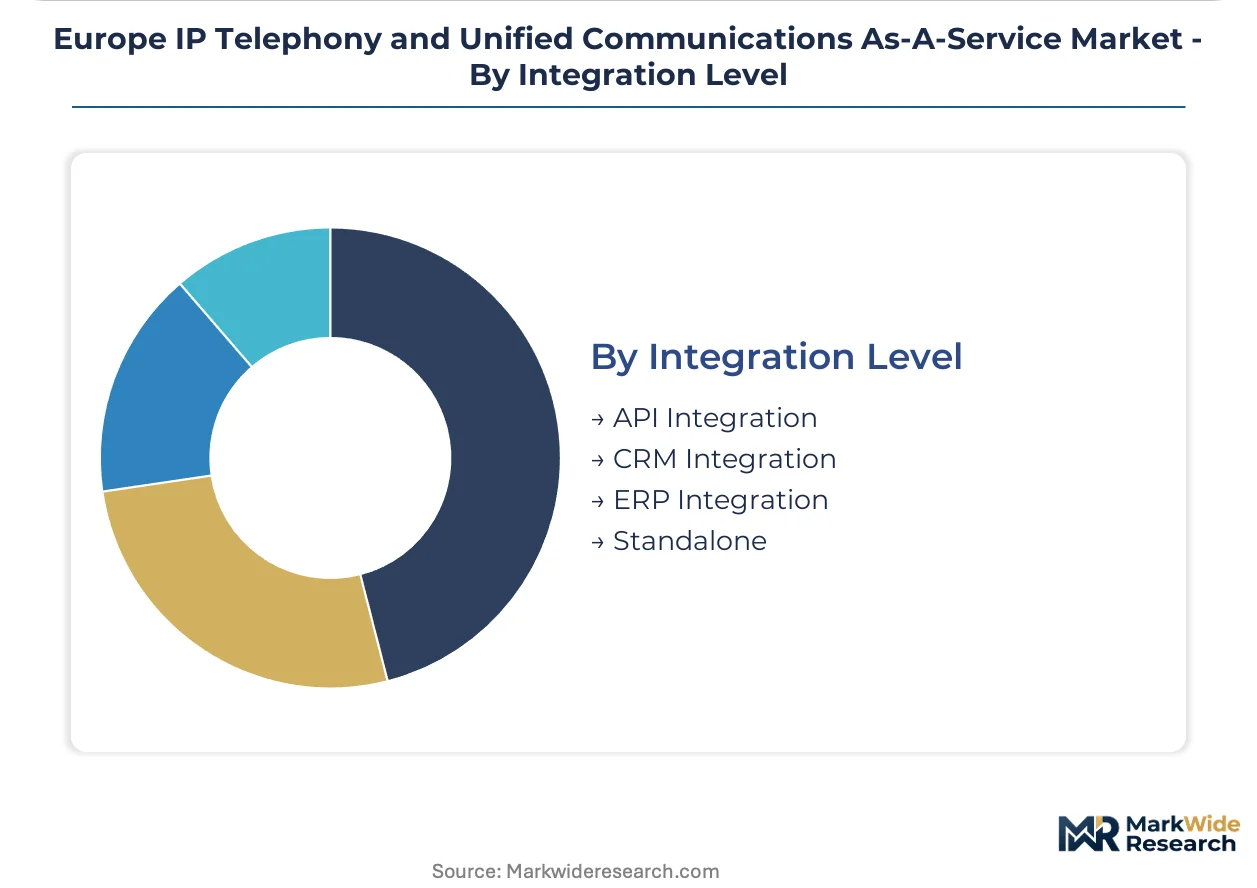
- API Integration:RESTful and GraphQL endpoints enable custom embedding of click-to-call, screen pop, and call logging within proprietary applications. French insurance technology startups and UK fintech challengers leverage these interfaces to differentiate customer experience without building telephony infrastructure from scratch. Developer sandbox environments and usage-based pricing lower experimentation barriers.
- CRM Integration:Native connectors to Salesforce, HubSpot, and Microsoft Dynamics synchronize contact records, call outcomes, and opportunity stages automatically. German B2B sales organizations and Dutch recruitment agencies treat this as table stakes, rejecting vendors lacking pre-built adapters for their installed CRM base.
- ERP Integration:SAP and Oracle connectors link communications metadata to financial reporting and supply chain workflows.
- Standalone:Web portal and softphone-only deployments persist in transitional migrations and temporary project teams.
CRM Integration retains volume leadership; API Integration holds the steepest expansion curve as embedded communications platforms miniaturize functionality into application workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's UCaaS landscape exhibits net import dependency for specialized contact center AI modules, while Nordic and German vendors export sovereign cloud configurations to Middle Eastern and Asian financial institutions seeking GDPR-equivalent compliance architectures.
Germany
Automotive OEMs and pharmaceutical manufacturers in Baden-Württemberg and Bavaria drive demand for hybrid cloud deployments that satisfy BfArM audit requirements. The NIS2 Directive classifies healthcare and transport operators as critical infrastructure, mandating penetration testing and incident reporting protocols. Frankfurt's financial district concentrates procurement authority for 10,000+ seat deployments across DAX-listed conglomerates.
United Kingdom
London-based insurance groups and fintech challengers prioritize API-first platforms for embedded customer communications. MHRA guidelines for pharmaceutical field force coordination mandate encrypted mobile collaboration with business associate agreements. The Midlands manufacturing belt shows accelerating ISDN replacement timelines as BT Group retires copper infrastructure.
France
ANSM supervision of healthcare contact centers in Île-de-France imposes the steepest algorithmic transparency requirements under the EU AI Act. Parisian banking groups and luxury houses demand sovereign cloud configurations with CNIL-certified data processing agreements. Lyon and Toulouse exhibit mid-market expansion as regional shared service centers consolidate telephony estates.
Netherlands
Amsterdam and Rotterdam harbor logistics operators deploy WebRTC-based dispatch communications to replace legacy maritime radio systems. Dutch healthcare trusts under the National Institute for Public Health and the Environment favor hybrid architectures for patient record access audit trails. Eindhoven's high-tech manufacturing cluster drives integration demand with SAP and Oracle ERP systems.
Poland
Warsaw and Krakow shared service centers for Western European enterprises represent underpenetrated mid-market expansion targets. The Polish Financial Supervision Authority's cloud guidance accelerates procurement timelines for banking sector modernizations. Wrocław's IT outsourcing hub concentrates developer talent for API customization and CRM connector deployment.
Europe IP Telephony and Unified Communications As-A-Service Market Competitive Landscape
Concentration sits with hyperscale platform operators leveraging existing cloud infrastructure to anchor enterprise deployments across Northern Europe. The vendor base stratifies into three tiers: global technology conglomerates with integrated productivity suites, specialized communications pure-plays with API-first architectures, and regional service providers with sovereign cloud certifications. Dominant competitive moves include strategic partnerships with system integrators for managed service delivery and portfolio diversification into contact center AI and workforce management modules.
Among North American-based platform operators, Microsoft Corporation exemplifies the ecosystem-anchored archetype through Azure cloud backbone integration. Cisco Systems Inc. occupies a position representing hardware-software bundle specialists sustaining channel partner loyalty across German manufacturing verticals. RingCentral Inc. sits within the API-first tier, anchoring mid-market expansion strategies through developer-centric positioning. These three patterns illustrate how vendor archetypes map to distinct procurement committee priorities across European enterprise segments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Cisco Systems Inc. |
| RingCentral Inc. |
| 8x8 Inc. |
| Mitel Networks Corporation |
| Vonage Holdings Corp. |
| Avaya Holdings Corporation |
| Dialpad Inc. |
| Dstny |
| Others |
Supply & Pricing Matrix
EU Cloud Certification Scheme eligibility gates both vendor qualification timelines and subscription pricing tiers simultaneously, compressing procurement cycles for certified providers while inflating total cost of ownership for uncertified alternatives across German and French enterprise segments.
Pricing Analysis
Industrial OEM buyers anchor per-seat subscription pricing across the European UCaaS landscape. Three-tier pricing structure across premium, standard, and economy levels separates API-enabled contact center suites from basic VoIP trunking and legacy PBX migration packages. Cost compression in the standard tier intensifies as hyperscale cloud providers bundle communications into productivity suites. SMEs exhibit the highest price sensitivity, while healthcare providers under ANSM and BfArM supervision demonstrate inelastic demand for certified sovereign cloud configurations.
Supply Chain Analysis
Inventory lead times for specialized SIP gateway hardware stretch procurement cycles for hybrid cloud deployments across UK healthcare trusts. Substrate provision concentrates in Ireland, the Netherlands, and Germany where hyperscale data center clusters anchor pan-European capacity. Component dependencies span WebRTC protocol stacks, encrypted recording modules, and API middleware layers. Single-source vulnerability in cloud infrastructure creates SLA fulfillment risk for regional service providers. Distribution runs through system integrators and managed service providers capturing margin pools from direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European UCaaS demand tracks enterprise IT modernization cycles, with cyclical recovery in capital expenditure budgets accelerating cloud migration timelines as organizations retire legacy on-premise PBX systems.
For Market Incumbents: Fortify channel partner loyalty through specialized hardware-software bundles that sustain Cisco Systems Inc.'s position in German manufacturing verticals. Deepen vertical integration into sovereign cloud certifications to defend margin position against hyperscale platform operators bundling communications into productivity suites. Prioritize NIS2 Directive compliance tooling as a differentiation lever against uncertified competitors.
For New Entrants and Emerging Players: Lead with API-first architectures targeting Polish and Romanian shared service centers where mid-market penetration remains underdeveloped. Capture white-space in embedded communications platforms miniaturizing voice and video into business application workflows. Deploy developer-centric go-to-market motions through sandbox environments and usage-based pricing to lower experimentation barriers for French insurtech startups.
For Investors and Strategic Acquirers: Carve-out targets emerge from regional service providers holding sovereign cloud certifications that exceed EU Cloud Certification Scheme thresholds. Long-term viability hinges on contact center AI convergence and workforce management module expansion beyond core telephony subscriptions. Monitor hyperscale bundling intensity as the critical inflection signal for standalone UCaaS valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Investment | EU Cloud Certification Scheme eligibility unlocks public sector procurement in France, Germany, and Italy. |
| Contact Center AI Integration | Large language model deployment with ANSM-compliant audit trails commands premium pricing in French healthcare. |
| API-First Platform Expansion | RESTful endpoint proliferation captures embedded communications demand from UK fintech challengers. |
| Channel Partner Consolidation | System integrator partnerships redistribute margin pools from direct vendor sales in German manufacturing. |
| Hybrid Cloud Configuration Development | Split architecture tooling satisfies NIS2 Directive requirements without full infrastructure replacement. |
Research Methodology
Initial hypotheses were tested against primary input from CTOs, IT procurement officers, platform engineers, and channel partners across Northern Europe and refined through secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory submissions, and hospital procurement databases. Bottom-up seat-count modeling triangulated against top-down addressable market sizing derived from enterprise telephony estate replacement cycles.
Variance decomposition across deployment model, organization size, vertical sector, integration complexity, and regional adoption pattern shaped analytical framework construction over the projection horizon. CAGRs were derived from segmented growth rate synthesis rather than single-point extrapolation. Forecast inputs incorporated WebRTC protocol maturation curves, GDPR enforcement intensity indices, and healthcare digitization mandate timelines.
Underlying assumptions cover regulatory enforcement continuity, hyperscale bundling stability, and enterprise IT budget recovery trajectories, with deviation risk concentrated in EU AI Act implementation timelines and NIS2 Directive audit requirement inflation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unified Communications
Unified Communications As a Service (Ucaas) Market
Unified Communications
Global Mobile Voip Market
Unified Communications
High Definition HD Voice Market
Unified Communications
Unified Communication Market
Unified Communications
Unified Communication (UC) and Business Headsets Market
Unified Communications
Business Cloud Voip and UC Services Market
Unified Communications
Global IP Telephony and Ucaas Market
Unified Communications
Cloud UC Calling Market
Unified Communications
Ucaas in the Manufacturing Market
Unified Communications
Mobile Unified Communications and Collaboration (Ucandc) Solution Market
Unified Communications
Airline Passenger Communications System Market
Unified Communications
Ucaas in Banking Market
Unified Communications
United States SMS and MMS Market
Unified Communications
Global Mobile Unified Communications and Collaboration Market
Unified Communications
Omni Channel Messaging Software Market
Unified Communications
Unified Monitoring Market