
 Blockchain in Energy Utilities Market | 2026-2036
Blockchain in Energy Utilities Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain in Energy Utilities Market Intelligence
Australia's rapid build-out of distributed solar and battery storage capacity is reconfiguring the traditional utility grid model. This shift creates a direct need for new transaction and data management systems. Power Ledger, an Australian firm, leverages its platform for peer-to-peer energy trading within these emerging microgrids. Siemens integrates blockchain capabilities into its existing grid management hardware and software suites. IBM Corporation competes by offering its Hyperledger-based platforms for consortiums of energy providers seeking enterprise-grade solutions.
Blockchain in energy utilities refers to the application of a distributed, cryptographically secured ledger to record transactions and manage data across the energy value chain. Its primary purpose is to enable secure, transparent, and automated execution of processes like energy trading and grid balancing without a central intermediary. Among applications, energy trading and grid management solutions command significant investment. Consortium blockchain models are favored by electricity providers for balancing data privacy with the need for inter-utility collaboration.
Regulatory frameworks such as the EU Green Deal in Europe and FERC Order 2222 in the United States create official pathways for distributed energy resources to participate in wholesale markets. These policies directly incentivize the use of blockchain for managing the complex transactions and data flows generated by these new participants. Stakeholders must now decide between building proprietary platforms or joining existing consortia like the Energy Web Foundation to achieve necessary scale and interoperability.
Market Dynamics
The decentralization of power generation, driven by renewable energy sources, is the central market force. This shift creates an urgent need for secure, automated, and transparent transactional frameworks that blockchain technology is uniquely positioned to provide.
Growth Catalysts
- Regulatory Mandates:Policies like the EU Green Deal and US FERC Order 2222 create market access for distributed energy resources, necessitating blockchain-based transactional layers.
- Grid Modernization:National programs in Germany and Australia installing smart meters generate data needing secure, distributed ledger management for settlement.
- Peer-to-Peer Trading Demand:Growth in residential solar and battery storage drives consumer interest in P2P energy trading, a key blockchain application for microgrids.
Market Restraints
- Scalability and Interoperability:Public blockchains face transaction speed limits while private consortiums struggle with interoperability, hindering data exchange between utility networks.
- High Implementation Costs:Integrating blockchain with legacy utility IT and OT systems requires significant upfront capital, a barrier for smaller municipal utilities.
- Regulatory Uncertainty:Ambiguous data ownership and liability rules for P2P trading create legal risks, slowing commercial deployments by cautious energy providers.
Strategic Opportunities
- Renewable Energy Certificate Trading:Automating the issuance, tracking, and retirement of RECs on a blockchain reduces fraud and administrative overhead for corporate sustainability reporting.
- Emerging Asian Grids:Economies in Southeast Asia can leapfrog legacy infrastructure by implementing blockchain-native microgrids as their power systems expand.
- Convergence with AI:Integrating artificial intelligence enables predictive grid balancing and autonomous energy trading, optimizing resource allocation from real-time forecasts.
Industry Challenges
- Legacy System Integration:Interfacing blockchain platforms with aged SCADA and grid management systems is a complex operational hurdle demanding specialized engineering expertise.
- Lack of Data Standards:A deficit of accepted data standards for energy transactions complicates collaboration between utility consortia and creates fragmented ecosystems.
- Skillset Scarcity:A shortage of professionals with dual expertise in energy operations and blockchain development hinders the creation of effective industry solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain in Energy Utilities Market |
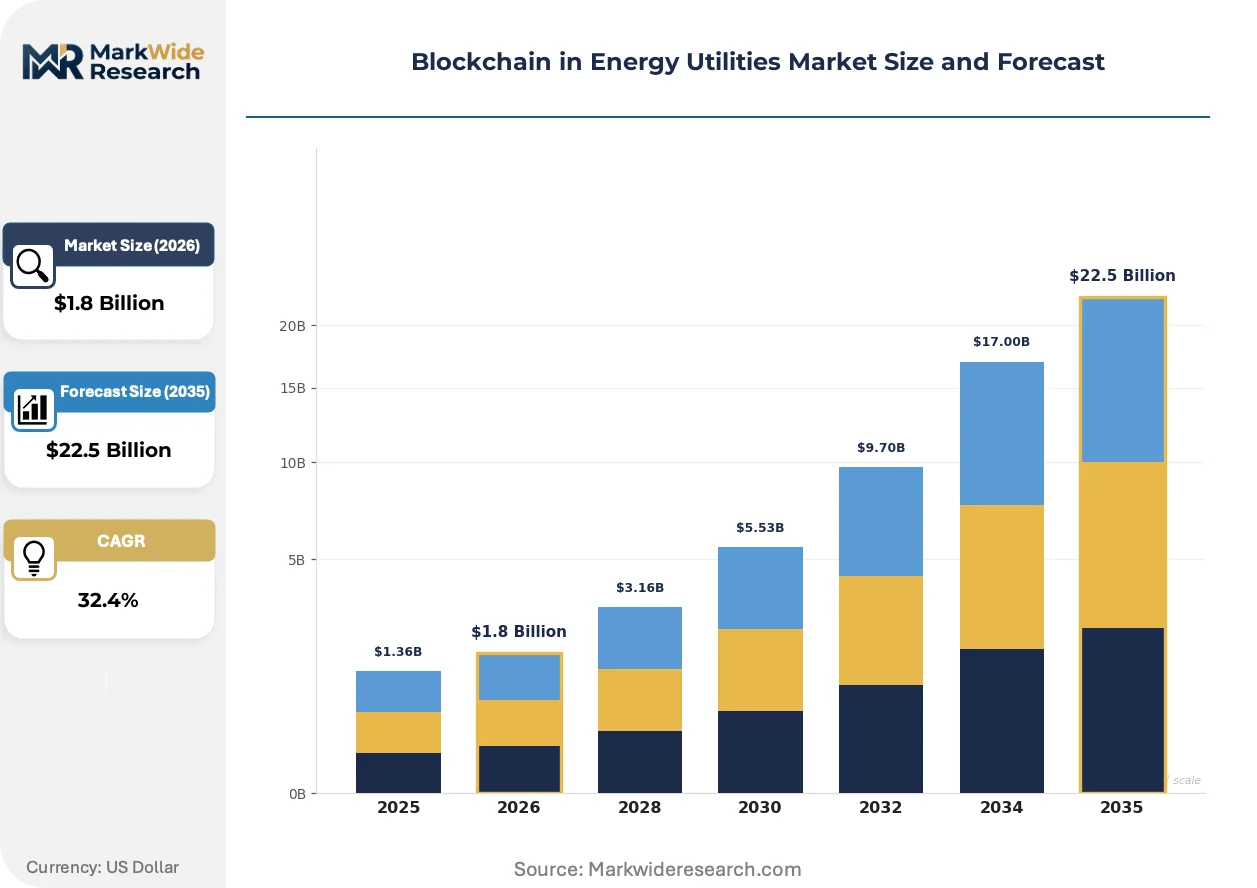
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $22.5 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Energy Trading, Grid Management, Renewable Certificates, Peer-to-Peer Payments, Smart Metering Solution Type: Public Blockchain, Consortium Blockchain, Private Blockchain, Hybrid Blockchain End User: Electricity Providers, Gas Suppliers, Water Utilities, Energy Retailers Deployment Model: On-Premises, Cloud-Based, Hybrid Cloud, Edge Computing |
| Companies Covered | Siemens, Oracle Corporation, IBM Corporation, LO3 Energy, SAP, Power Ledger, Accenture, DXC Technology, Energy Web Foundation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain in Energy Utilities Market Strategic Shifts & Innovations
Enterprise-grade applications are displacing theoretical pilots as the focus of innovation. Development is concentrating on creating interoperable platforms that manage the transactional complexity of a decentralized, multi-participant energy grid.
Digital twin technology, when combined with blockchain, creates an immutable and real-time replica of physical grid assets and energy flows. Grid operators in Europe and North America are adopting this to model the impact of distributed energy resources before they connect. This combination is virtualizing grid management, allowing for predictive maintenance and simulated stress testing without risking physical infrastructure.
Australia's regulatory framework for DER participation, managed by the Australian Energy Market Operator, is setting a precedent for market design. This structure mandates data visibility and settlement for small-scale solar, creating a business case for blockchain platforms. The residential energy storage segment is responding by integrating blockchain-ready software for P2P trading and grid services.
A shift towards consortium-based platform development is replacing the earlier model of proprietary, single-vendor systems. Large industrial energy consumers and utility providers are forming groups like the Energy Web Foundation to co-develop open-source standards and shared infrastructure. This collaborative procurement model is most prominent in Europe, where utilities seek to avoid vendor lock-in and ensure interoperability.
Blockchain in Energy Utilities Market Segmentation
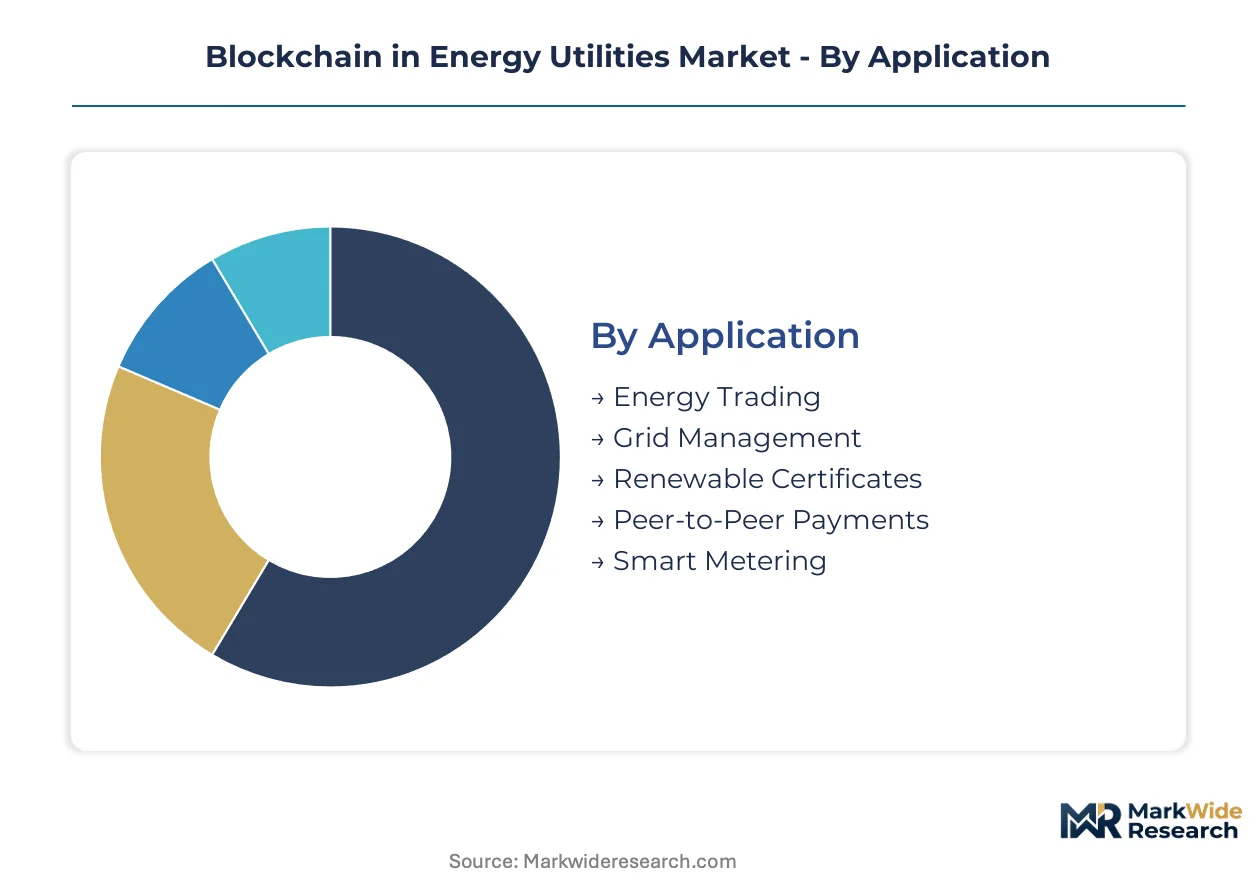
The Blockchain in Energy Utilities market is analyzed across key dimensions to understand its intricate structure and growth drivers. This segmentation provides clarity on how distributed ledger technology is being adopted across various operational aspects of the energy value chain. Understanding these distinct segments helps stakeholders identify specific investment opportunities and technological integration pathways.
Application:
The use-case spectrum for blockchain in energy utilities spans from transactional efficiencies to foundational grid infrastructure enhancements.
- Energy Trading:This application involves the secure and transparent exchange of energy between participants, often in peer-to-peer or microgrid settings. Demand is concentrating in countries like Australia, where regulatory frameworks support distributed energy resources participating in wholesale markets.
- Grid Management:Blockchain provides immutable data records for grid operations, facilitating balancing, demand response, and asset tracking across decentralized networks. European utilities are integrating these solutions to manage complex data flows from new distributed energy resources.
- Renewable Certificates:Blockchain streamlines the issuance, tracking, and retirement of renewable energy certificates (RECs), reducing fraud and administrative burdens.
- Peer-to-Peer Payments:This enables direct, automated financial settlements for energy transactions between prosumers without central intermediaries.
- Smart Metering:Blockchain secures data from smart meters, ensuring integrity for billing, consumption analysis, and grid optimization.
Established volume favors Energy Trading; emerging adoption favors Grid Management.
Solution Type:
Blockchain solutions for energy utilities are differentiated by their architectural design and access controls, serving distinct operational needs.
- Consortium Blockchain:Managed by a group of pre-selected organizations, these platforms balance decentralization with controlled access, ideal for inter-utility collaboration. European energy providers favor these models for shared infrastructure and data exchange.
- Private Blockchain:Operated by a single entity with restricted access, these offer high transaction speeds and data privacy for internal utility operations. Large electricity providers utilize private chains for secure, in-house data management.
- Public Blockchain:Open to all participants, these decentralized networks offer transparency but often face scalability challenges for enterprise energy applications.
- Hybrid Blockchain:Combining elements of both private and public chains, these solutions offer flexibility in data visibility and access control.
The fastest expansion is observed in Consortium Blockchain solutions, while Private Blockchain maintains a stable operational base.
End User:
The adoption of blockchain technology varies across different energy utility end-user types, reflecting their unique operational complexities and regulatory environments.
- Electricity Providers:These entities leverage blockchain for managing decentralized generation, grid balancing, and wholesale energy market participation. Utilities in Germany are actively investing in these platforms for grid modernization and renewable integration.
- Energy Retailers:Companies selling energy directly to consumers use blockchain for transparent billing, peer-to-peer trading platforms, and loyalty programs. Australian energy retailers are increasingly offering blockchain-enabled solutions for residential solar prosumers.
- Gas Suppliers:Blockchain supports gas supply chain traceability, transaction verification, and emissions reporting for natural gas and hydrogen networks.
- Water Utilities:This segment explores blockchain for secure water usage data, smart metering, and efficient resource management.
Electricity Providers hold the largest share, with Energy Retailers demonstrating significant growth potential.
Deployment Model:
Deployment models for blockchain in energy utilities range from fully controlled local infrastructure to flexible, scalable cloud-based solutions.
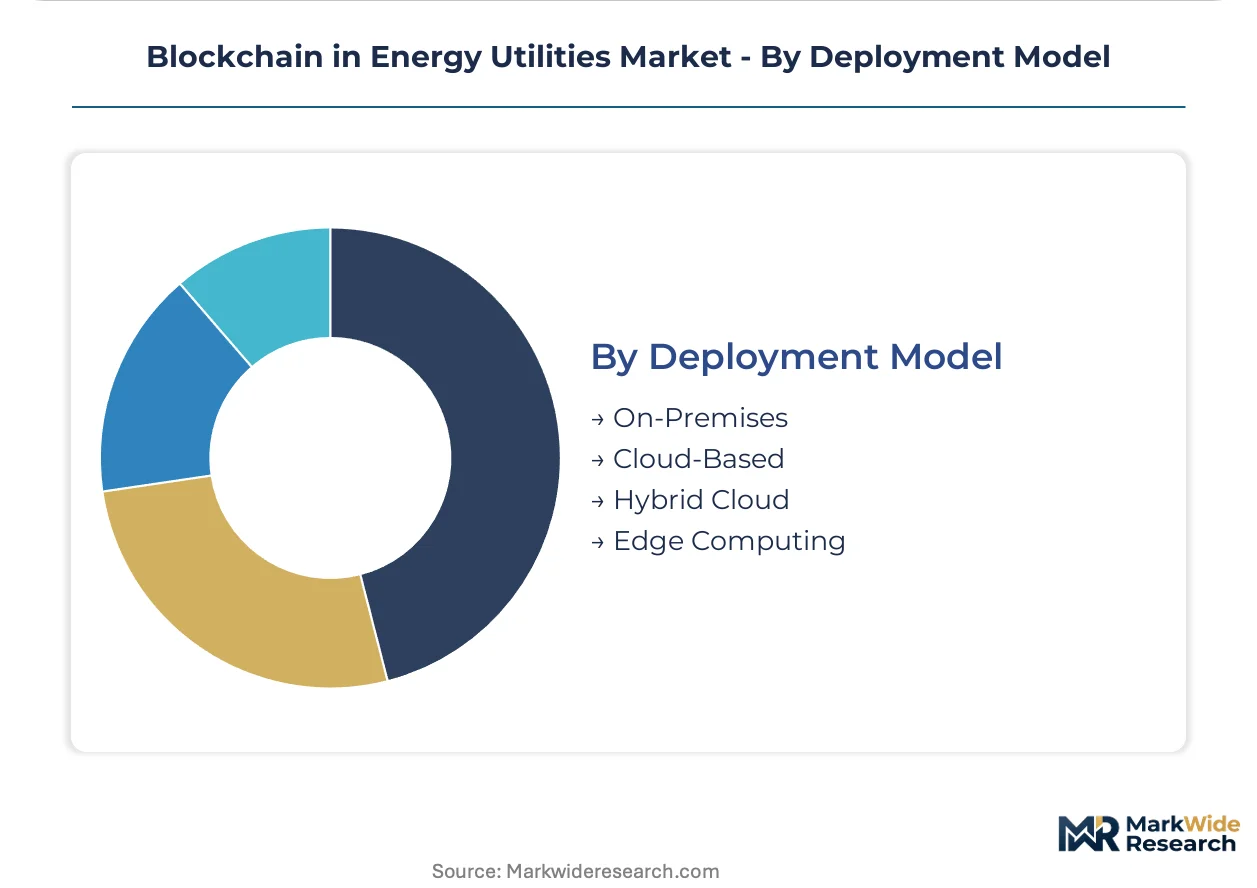
- Cloud-Based:These solutions host blockchain infrastructure on public or private cloud services, offering scalability, reduced upfront costs, and simplified maintenance. Smaller municipal utilities often prefer cloud deployments for their flexibility.
- Hybrid Cloud:Combining on-premises and cloud environments, this model allows utilities to maintain sensitive data locally while leveraging cloud resources for less critical operations. IBM Corporation offers such flexible deployments for energy consortiums.
- On-Premises:Blockchain infrastructure is hosted within the utility's own data centers, offering maximum control and security for critical systems.
- Edge Computing:This deploys blockchain nodes closer to data sources like smart meters or distributed energy resources, reducing latency and improving real-time processing.
While On-Premises offers control, Cloud-Based provides adaptability for future expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration of supply-side innovation in blockchain for energy utilities is evident across several technologically advanced nations. These countries are actively modernizing their energy infrastructure and integrating decentralized energy resources. This global shift necessitates robust transactional frameworks, driving significant investment in blockchain solutions.
Germany
Germany's push for grid modernization and renewable energy integration drives demand for blockchain in energy trading and grid management. The EU Green Deal provides a strong regulatory tailwind for decentralized energy resources. Utilities in Berlin and Munich are actively piloting consortium blockchain models for secure data exchange.
Australia
Australia's rapid build-out of distributed solar and battery storage creates a strong need for peer-to-peer energy trading platforms. The Australian Energy Market Operator's framework for DER participation mandates data visibility and settlement. Firms in Sydney and Melbourne leverage blockchain to manage transactions within emerging microgrids.
United States
The United States sees demand for blockchain in integrating distributed energy resources into wholesale markets. FERC Order 2222 creates official pathways for these resources, necessitating new transactional layers. Energy providers in California and Texas explore Hyperledger-based platforms for consortium-driven solutions.
Netherlands
The Netherlands prioritizes sustainable energy transition, fostering demand for blockchain in smart grid applications and renewable energy certificate trading. European utilities, including those in the Netherlands, favor consortium blockchain models for interoperability. Amsterdam and Rotterdam are hubs for pilot projects focused on local energy communities.
Japan
Japan's focus on grid resilience and smart city initiatives generates interest in blockchain for secure data management and energy trading. METI policies encourage digital transformation within the energy sector to enhance efficiency. Tokyo and Osaka are exploring blockchain-native microgrids as their power systems expand.
Blockchain in Energy Utilities Market Key Industry Players
Large technology providers and specialized energy blockchain firms split the market for blockchain in energy utilities, creating a tiered competitive landscape. This structure features established industrial giants offering integrated solutions alongside agile blockchain-native companies developing niche applications. These archetypes often pursue strategic partnerships to integrate blockchain capabilities into existing infrastructure. Key competitive moves include technology licensing for broader market adoption and portfolio diversification into energy-specific blockchain solutions.
Within the integrated solutions archetype, IBM Corporation offers Hyperledger-based platforms for energy consortiums seeking enterprise-grade solutions. This approach caters to large energy providers requiring robust, scalable distributed ledger technology. Siemens, a prominent industrial player, integrates blockchain capabilities directly into its existing grid management hardware and software suites, providing comprehensive operational tools. Power Ledger, an Australian firm, exemplifies the specialized blockchain-native archetype, leveraging its platform for peer-to-peer energy trading within emerging microgrids. This firm focuses on decentralized consumer-level transactions. These companies anchor different segments of the market, from large-scale utility integration to localized energy exchange.
| Leading Market Players |
|---|
| Siemens |
| Oracle Corporation |
| IBM Corporation |
| LO3 Energy |
| SAP |
| Power Ledger |
| Accenture |
| DXC Technology |
| Energy Web Foundation |
| Others |
Cost & Logistics Intelligence
Intercontinental fiber optic networks dictate the underlying cost structure for blockchain platforms, influencing how supply concentration in development hubs affects downstream service pricing for energy utilities.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure for blockchain solutions, particularly for renewable energy certificate (REC) trading platforms. SaaS-tiered and project-based models dominate, with price differentiation driven by customization level and after-sales service integration. Pricing pressure stems from the high upfront implementation costs, especially for integrating with legacy utility IT systems. Smaller municipal utilities demonstrate high price sensitivity, while large electricity providers prioritize robust, enterprise-grade solutions over cost.
Supply Chain Analysis
Specialized software development talent forms the upstream feedstock for blockchain in energy utilities, concentrating in technology hubs across the United States, Germany, and Australia. Key dependencies include open-source blockchain protocols like Hyperledger and cloud computing infrastructure providers. A significant supply chain risk is the acute skillset scarcity, hindering effective industry solution creation. Distribution runs through direct sales channels to large electricity providers and consortium-based licensing agreements for shared infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blockchain in energy utilities market navigates a critical capability gap, particularly in professionals combining energy operations knowledge with blockchain development skills. This scarcity impedes the creation and deployment of effective industry solutions.
For Market Incumbents: Insulate existing grid management hardware and software suites by embedding advanced blockchain capabilities. Form strategic technology licensing agreements with agile blockchain-native firms to counter disruption from specialized peer-to-peer trading platforms. Investment in R&D for interoperable platform development serves as a key lever against emerging entrant archetypes. This approach defends market share against rapid innovation.
For New Entrants and Emerging Players: Establish a beachhead in renewable energy certificate (REC) trading, leveraging blockchain to automate issuance and tracking. Target emerging Asian grids that can leapfrog legacy infrastructure with blockchain-native microgrids. The most penetrable application remains peer-to-peer energy trading for residential solar prosumers in regions like Australia. A collaborative procurement model through open-source consortiums offers a viable go-to-market angle.
For Investors and Strategic Acquirers: FERC Order 2222 reshapes the acquisition landscape, creating demand for platforms enabling distributed energy resource participation in wholesale markets. Long-term viability remains strong over the next 5-10 years, driven by grid modernization and decentralization trends. Acquisition targets should be specialized blockchain-native firms offering interoperable solutions for grid management and energy trading. The widespread adoption of digital twin technology by grid operators serves as a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing | Broadens market reach for blockchain platforms like Power Ledger into new utility segments. |
| Platform Integration | Embeds blockchain capabilities into existing grid management hardware, as demonstrated by Siemens. |
| Strategic Partnership | Enables large energy providers to leverage Hyperledger-based platforms from IBM Corporation. |
| Acquisition of Specialist Firm | Bolsters enterprise capabilities in peer-to-peer trading or renewable energy certificate management. |
| Open-Source Standard Development | Fosters interoperability and reduces vendor lock-in for European utility consortia. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with extensive secondary validation. Engagements included utility planning officers, energy retailers, blockchain solution architects, and regulatory affairs specialists. Secondary data sources comprised IEA reports, government energy policy documents, company financial disclosures, and academic research on distributed ledger technology. Bottom-up and top-down triangulation ensured data integrity and market sizing accuracy.
The analytical framework was calibrated through iterative scenario modeling across the analysis window, integrating historical data with projected market dynamics. Segmentation dimensions modeled included application, solution type, end user, and deployment model. Compound Annual Growth Rates were derived from historical growth patterns and projected adoption curves. Key industry-specific forecast inputs included renewable energy capacity additions and smart meter deployment rates.
Macroeconomic conditions sit as an overlay; deviation in global energy prices or interest rates would shift the trajectory. Forecasts reflect documented assumptions, though regulatory uncertainty and technological obsolescence pose specific risk factors. Cross-checking against the IEA's World Energy Outlook is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Blockchain in Smart Home Market
Blockchain Technology
Global Blockchain Government Market
Blockchain Technology
Global Blockchain in Agriculture and Food Supply Chain Market
Blockchain Technology
Blockchain in Mining Market
Blockchain Technology
Smart Contracts on Blockchain Market
Blockchain Technology
Global Blockchain in Telecom Market
Blockchain Technology
Blockchain Messaging Apps Market
Blockchain Technology
Enterprise-Grade DLT Market
Blockchain Technology
Bitcoin Project Incubator Service Market
Blockchain Technology
Global Blockchain Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Global Blockchain Software Market