
 United States Rigid Plastic Packaging Market | 2026-2036
United States Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Rigid Plastic Packaging Market Insights
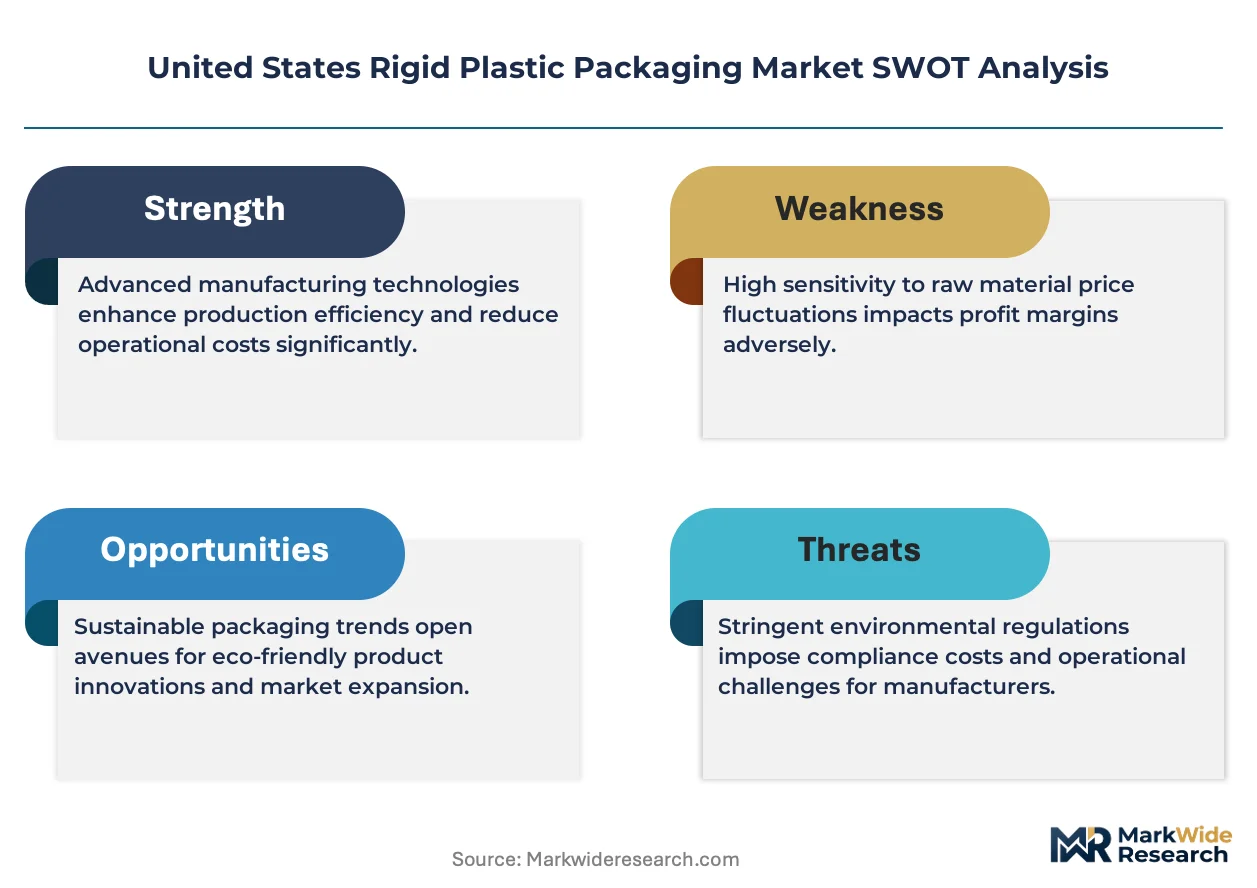
Post-consumer resin integration is reshaping competitive economics across the value chain. Berry Global Inc. leverages vertical integration into recycled pellet supply to control input costs. Amcor Group GmbH anchors its position through lightweighting R&D programs that reduce resin intensity per unit. Plastipak Holdings, Inc. dominates the beverage bottle segment through high-speed blow molding scale in the Midwest.
United States Rigid Plastic Packaging comprises thermoformed or blow-molded containers manufactured from polyethylene, polypropylene, PVC, or polystyrene with wall thicknesses typically exceeding 0.010 inches, designed to protect goods during distribution, retail display, and consumer use without deformation under standard load conditions. The bottles category leads volume throughput due to carbonated soft drink and bottled water demand, while the containers segment captures premium margins in foodservice and industrial applications. Polyethylene occupies the largest material share given its cost-position and chemical resistance, though polypropylene is gaining traction in hot-fill and retort applications where thermal stability commands price premiums.
FDA food-contact notification requirements govern resin approvals and additive migrations, while EPA regulations on industrial emissions shape blow molding plant siting and compliance costs. State-level extended producer responsibility frameworks in California, Oregon, and Maine are forcing reformulation timelines and recycled-content minimums. Stakeholders must monitor how PCR certification standards and state patchworks alter sourcing geography and capital deployment priorities.
Market Dynamics
State-level recycled-content mandates and FDA food-contact compliance timelines are forcing simultaneous reformulation across resin grades, blow molding equipment, and supplier qualification protocols. This regulatory stacking compresses capital deployment cycles while fragmenting procurement geography.
Growth Catalysts
- Lightweighting mandates:Beverage bottlers are driving PET container gauge reduction to cut resin intensity per unit. FDA clearance for novel barrier coatings accelerates adoption in carbonated soft drinks.
- Extended producer responsibility frameworks:California, Oregon, and Maine laws establish minimum post-consumer resin thresholds. These statutes create guaranteed offtake for recycled pellet producers.
- Hot-fill polypropylene substitution:Thermal stability improvements in clarified PP resins enable displacement of glass and metal in ready-to-drink tea and juice segments. Midwest blow molders are retooling lines for higher temperature tolerance.
Market Restraints
- Post-consumer resin price volatility:PCR flake supply concentrates in Great Lakes collection and reprocessing infrastructure. Baled bottle availability swings with municipal recycling program funding.
- Blow molding equipment lead times:High-speed electric stretch-blow machinery from European and Asian suppliers faces 18-24 month delivery queues. This constrains capacity expansion for beverage converters.
- Multi-layer barrier incompatibility:Current mechanical recycling streams cannot sort EVOH or nylon intermediate layers. Design-for-recycling guidelines from the Association of Plastic Recyclers limit material options.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and depolymerization investments in Texas and Louisiana could supply food-grade resin feedstock. EPA permitting pathways for these facilities are clarifying.
- Industrial bulk container conversion:HDPE intermediate bulk containers are displacing steel drums in agricultural chemicals and food ingredients. The shift requires UN certification but captures durable goods margins.
- Direct-to-retail distribution bypass:E-commerce fulfillment centers are sourcing custom thermoformed trays and dunnage directly from converters. This disintermediates traditional packaging distributors in the Southeast.
Industry Challenges
- Blow molding technician scarcity:Electric machine programming and mold-temperature control expertise is concentrated among aging workforces in Ohio and Indiana. Community college pipeline programs are insufficient to replace retirements.
- PCR certification complexity:Multiple third-party standards—ISCC PLUS, SCS Global Services, and APR design recognition—create audit redundancy. Qualifying a single resin grade across buyer specifications extends commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Rigid Plastic Packaging Market |
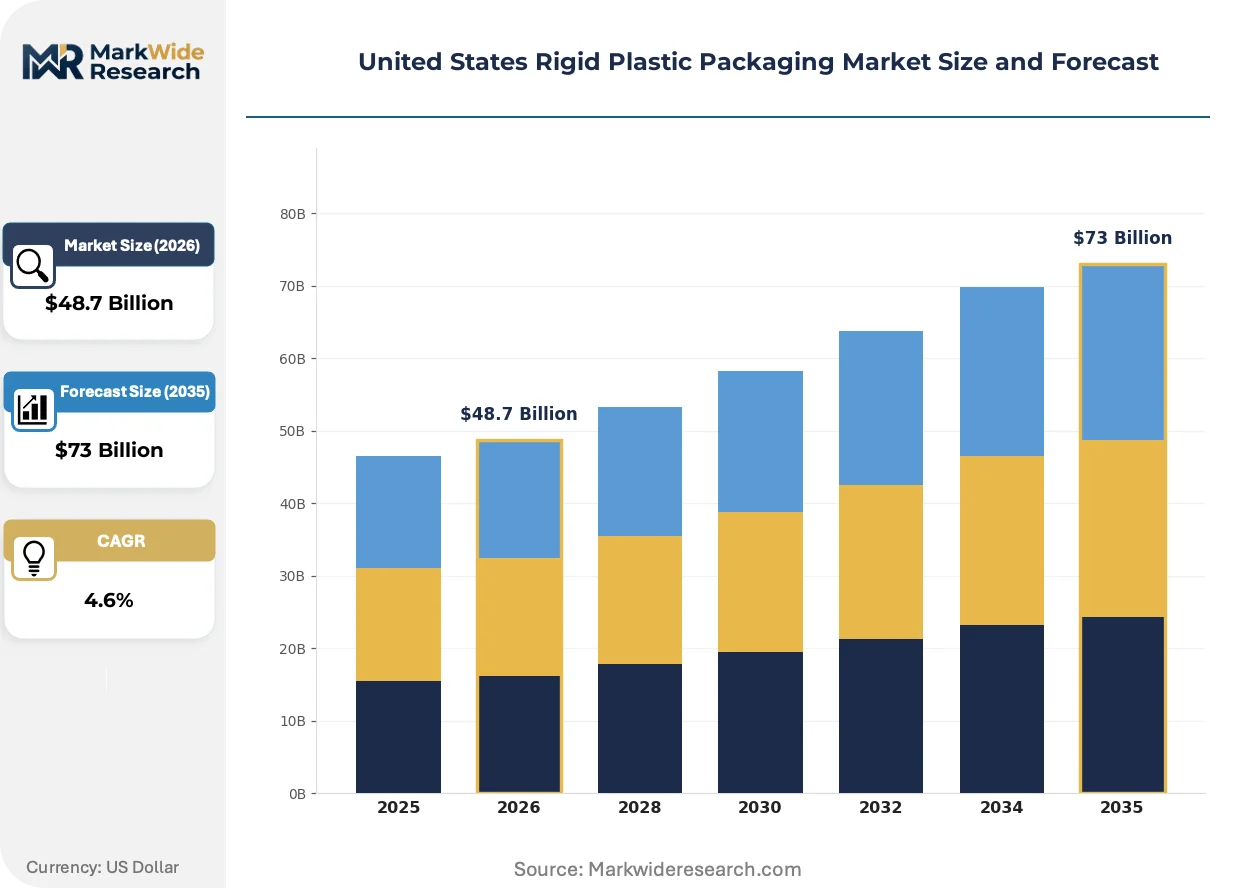
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Tubs End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Material: Polyethylene, Polypropylene, PVC, Polystyrene Closure Type: Screw Caps, Snap Caps, Flip Top, Push-Pull Caps |
| Companies Covered | Berry Global Inc., Amcor Group GmbH, Sonoco Products Company, Silgan Holdings Inc., Pactiv Evergreen Inc., Altium Packaging, Graham Packaging Company, Plastipak Holdings, Inc., Aptar Group Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Rigid Plastic Packaging Market Trends and Innovations
Material science breakthroughs and regulatory compliance automation are converging to redefine competitive advantage. Converters are racing to integrate real-time quality verification with sustainable feedstock traceability.
Mono-material barrier structures are collapsing the historical trade-off between shelf-life extension and recyclability. EVOH scavenger layers coextruded within single-resin PET or HDPE walls maintain oxygen transmission rates without sortation contamination. Major beverage brands are qualifying these structures for 12-month shelf-life products, forcing legacy multi-layer suppliers to accelerate R&D or exit premium segments.
California's SB 54 implementation rules are mandating 25% recycled content thresholds by 2025, with escalating annual increments. The California Department of Resources Recycling and Recovery is finalizing enforcement mechanisms that tie producer registration fees to compliance verification. Food-contact converters in the state are pre-purchasing PCR volumes three years forward to lock in supply and hedge price exposure.
Brand-owner procurement teams are consolidating supplier panels around integrated design-to-recycling partnerships. Single-source accountability for container performance, regulatory documentation, and end-of-life recovery is displacing fragmented multi-vendor arrangements. This concentration is most visible in the bottled water segment, where top-five producers are reducing qualified converter pools by 40% to simplify compliance management.
United States Rigid Plastic Packaging Market Segmentation
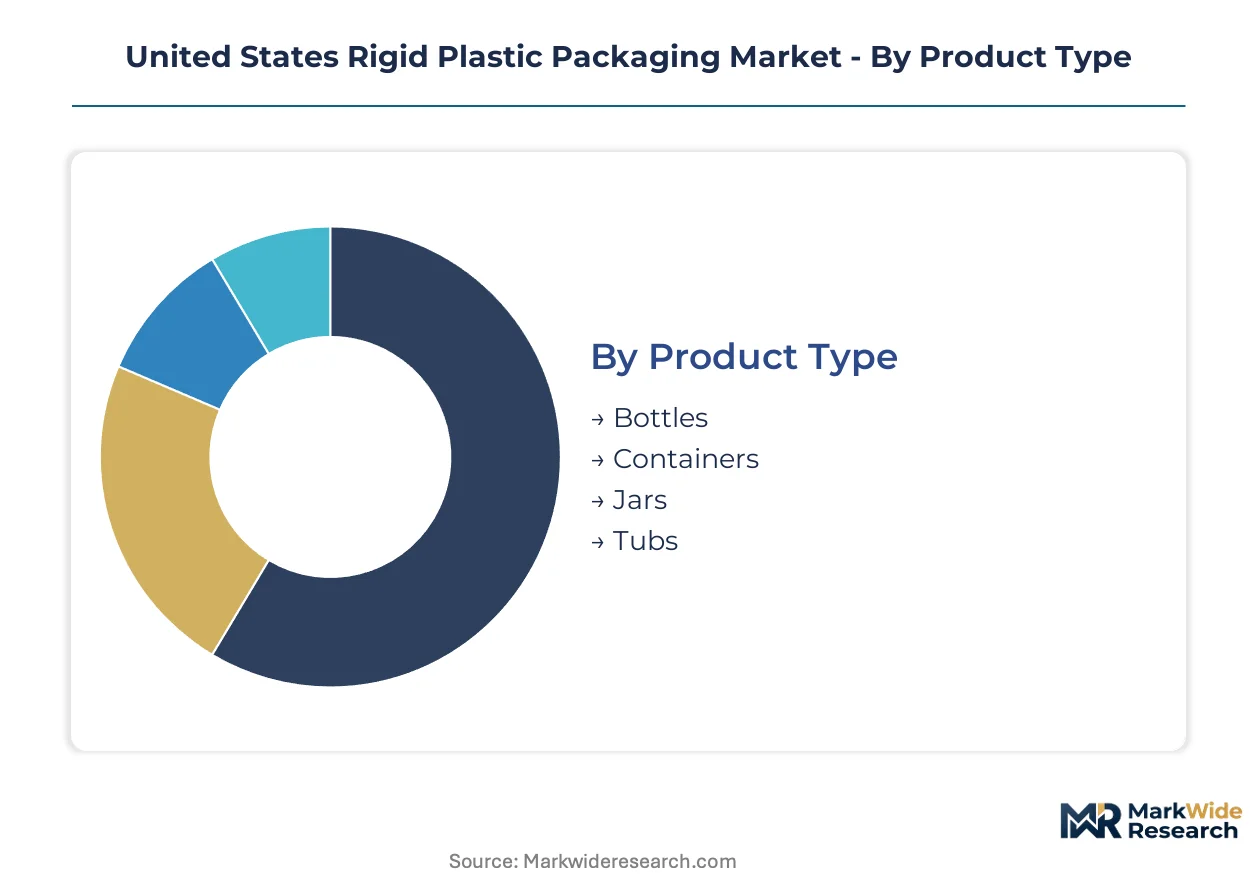
Rigid plastic packaging segmentation reveals divergent margin profiles and technical requirements across product formats. Converter specialization deepens as FDA compliance timelines and recycled-content mandates force dedicated production lines by segment.
Product Type:
After-sales service intensity varies sharply across formats, with bottles demanding blow molding technical support and containers requiring custom thermoforming die maintenance programs.
- Bottles:Stretch-blow molded PET and HDPE vessels with calibrated neck finishes for carbonated soft drinks, bottled water, and dairy. Demand concentrates with beverage bottlers in the Great Lakes corridor amid lightweighting mandates that reduce resin intensity per unit. FDA clearance for novel barrier coatings accelerates adoption in extended-shelf-life applications.
- Containers:Thermoformed or injection-molded rectangular and cylindrical vessels for foodservice, industrial, and retail distribution. Food ingredient processors in the Midwest drive specifications for UN-certified intermediate bulk formats that displace steel drums. Custom dunnage and tray programs for e-commerce fulfillment centers capture premium margins through direct-to-retail distribution bypass.
- Jars:Wide-mouth cylindrical containers with threaded finishes for preserves, sauces, and personal care creams. Clarity requirements in food applications favor clarified polypropylene over traditional glass substitution.
- Tubs:Shallow cylindrical or rectangular vessels with snap-fit or heat-sealed lids for dairy, deli, and fresh produce. Margins compress in commoditized foodservice formats while tamper-evident designs command premiums in retail channels.
By volume, bottles leads. By growth pace, containers is ahead.
End User:
Cost tier stratification separates premium pharmaceutical compliance investments from commodity household product specifications.
- Food & Beverage:The largest demand concentration spanning carbonated drinks, bottled water, dairy, and processed foods. California SB 54 mandates force reformulation across resin grades and supplier qualification protocols. Hot-fill polypropylene substitution in ready-to-drink tea and juice segments drives thermal stability improvements in clarified PP resins.
- Personal Care:Premium cosmetic and skincare packaging with decoration-intensive surfaces and airless pump integration. Mono-material barrier structures maintain oxygen transmission rates without sortation contamination, satisfying design-for-recycling guidelines.
- Pharmaceuticals:Child-resistant and senior-friendly closures with FDA drug master file documentation. Compliance costs concentrate with blow molding equipment validation and cleanroom production requirements.
- Household Products:Industrial chemical and cleaning supply containers with chemical resistance specifications. HDPE intermediate bulk containers capture durable goods margins in agricultural chemical distribution.
By revenue contribution, food & beverage dominates. By margin expansion, pharmaceuticals posts the steepest trajectory.
Material:
Volume concentration in polyethylene reflects established recycling infrastructure, while polypropylene gains share in thermal stability applications.
- Polyethylene:HDPE and LDPE resins dominate cost-position and chemical resistance across bottles, containers, and industrial formats. Great Lakes reprocessing infrastructure supports post-consumer resin integration for food-contact applications.
- Polypropylene:Clarified and nucleated grades enable hot-fill and retort applications where thermal stability commands price premiums. Midwest blow molders retool lines for higher temperature tolerance in ready-to-drink segments.
- PVC:Rigid formulations for blister packs and clamshells with specific barrier properties. Regulatory pressure from state environmental statutes limits expansion in food-contact applications.
- Polystyrene:Crystal and high-impact grades for thermoformed trays and disposable foodservice. Mechanical recycling stream contamination concerns accelerate displacement by PET alternatives.
By installed capacity, polyethylene leads. By qualification velocity for recycled content, polypropylene is climbing fastest.
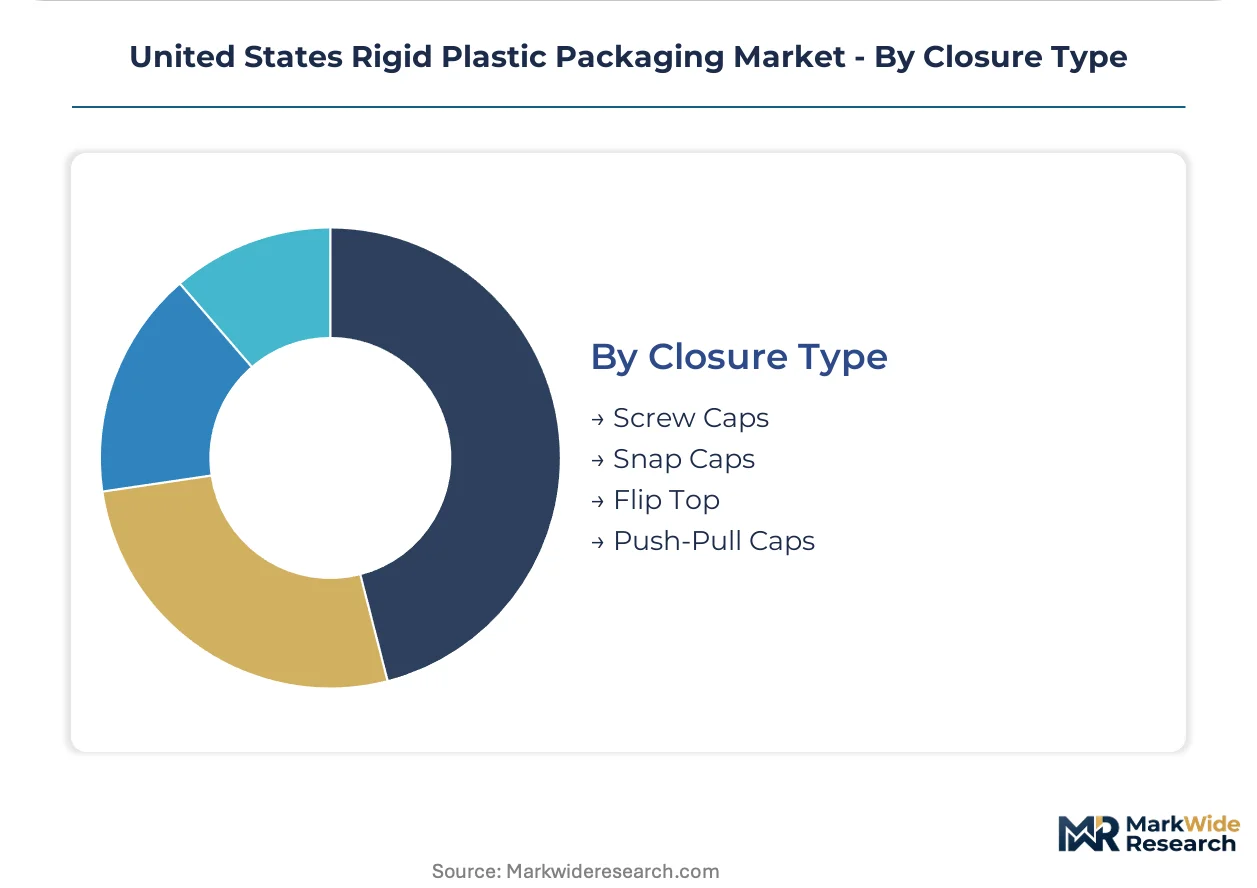
Closure Type:
Application requirements dictate tamper evidence, dispensing convenience, and child-resistance specifications across end-use segments.
- Screw Caps:Continuous thread finishes with induction seals for carbonated beverages and pharmaceuticals. Lightweighting mandates drive gauge reduction in HDPE and PP formats.
- Snap Caps:Hinged or separate lid designs for dairy tubs and wet wipe containers. Ease-of-opening specifications differentiate premium from standard tiers.
- Flip Top:One-handed dispensing for condiments, personal care, and household products. Living hinge durability testing determines supplier qualification.
- Push-Pull Caps:Sports bottle and squeeze tube formats with flow control mechanisms. Fitness and outdoor recreation end-uses concentrate demand in the Southeast and West Coast.
By unit volume, screw caps leads. By innovation intensity, flip top captures the most patent filings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers in the Great Lakes corridor exhibit the lowest price elasticity as lightweighting mandates compress resin intensity per unit, while foodservice buyers in the Southeast trade specifications aggressively on volume contracts. California's recycled-content premiums create the widest regional cost spread.
California
SB 54 implementation rules mandate escalating post-consumer resin thresholds that force converters to pre-purchase PCR volumes three years forward. The California Department of Resources Recycling and Recovery ties producer registration fees to compliance verification. Los Angeles basin blow molders are consolidating supplier panels to simplify documentation management.
Texas
Chemical recycling investments in pyrolysis and depolymerization facilities target food-grade resin feedstock supply for beverage bottlers. EPA permitting pathways for these Gulf Coast facilities are clarifying through regional office guidance. Houston-area industrial bulk container converters capture agricultural chemical distribution margins through UN-certified HDPE intermediate formats.
Ohio
Great Lakes reprocessing infrastructure concentrates baled bottle collection and mechanical recycling capacity for FDA food-contact applications. State-level extended producer responsibility discussions remain less advanced than West Coast frameworks. Cleveland-Akron blow molding clusters face technician scarcity as electric machine programming expertise concentrates among aging workforces.
Illinois
Midwest food ingredient processors drive specifications for hot-fill polypropylene substitution in ready-to-drink tea and juice segments. Chicago-area converters retool lines for higher temperature tolerance in clarified PP resins. The state's manufacturing corridor links resin distribution to Wisconsin and Indiana blow molding demand.
Southeast
E-commerce fulfillment centers in Florida and Georgia source custom thermoformed trays and dunnage directly from converters, disintermediating traditional packaging distributors. Lower recycled-content mandates than California create arbitrage opportunities for virgin resin formulations. Atlanta-based foodservice container demand concentrates in commoditized formats with compressed margins.
United States Rigid Plastic Packaging Market Competitive Landscape
Capability concentration sits with integrated resin-to-container specialists; scale advantage sits with high-volume blow molding operators serving national beverage accounts. The market structure tiers between backward-integrated PCR controllers and lightweighting-focused equipment innovators. Three archetypes dominate: vertical resin integrators, barrier technology licensors, and regional fulfillment specialists. Consolidation through bolt-on recycling assets and line-speed automation partnerships represent the dominant competitive vectors.
Among North American packaging conglomerates, Berry Global Inc., Amcor Group GmbH, and Plastipak Holdings, Inc. occupy distinct positioning within this tiered structure. Berry exemplifies the backward-integrated archetype through captive recycled pellet supply. Amcor represents the multinational technology licensing model with barrier coating R&D programs. Plastipak anchors the high-speed blow molding scale tier concentrated in Midwest beverage supply. These three entities illustrate how capability depth and geographic footprint separate premium-tier converters from regional competitors.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor Group GmbH |
| Sonoco Products Company |
| Silgan Holdings Inc. |
| Pactiv Evergreen Inc. |
| Altium Packaging |
| Graham Packaging Company |
| Plastipak Holdings, Inc. |
| Aptar Group Inc. |
| Others |
Pricing and Supply Chain Analysis
Great Lakes blow molding clusters in Ohio and Indiana concentrate high-speed PET production capacity, granting incumbent converters pricing power over beverage bottlers facing lightweighting mandates and recycled-content deadlines. This geographic concentration amplifies margin capture for suppliers with integrated post-consumer resin supply while squeezing independent converters dependent on spot pellet markets.
Pricing Analysis
After-sales service contracts for blow molding die maintenance and electric machine programming support drive lifetime value capture for equipment-intensive converters. Three-tier pricing structure across premium, standard, and economy levels segments buyers by FDA compliance tier and PCR certification grade. Cost compression in commoditized foodservice formats is intensifying because virgin resin arbitrage from the Southeast undercuts Midwest recycled-content premiums. Private-label beverage bottlers exhibit highest price sensitivity, while pharmaceutical and infant nutrition brands accept premium tiers for drug master file documentation and cleanroom production protocols.
Supply Chain Analysis
Extended payment terms from 60 to 90 days and supply-chain finance facilities through resin distributors characterize working capital arrangements for mid-tier converters. Raw material supply draws from Texas and Louisiana petrochemical complexes, Great Lakes mechanical recycling infrastructure, and emerging pyrolysis facilities on the Gulf Coast. Post-consumer flake availability swings with municipal recycling program funding, creating single-source vulnerability for converters without captive pellet supply. Distribution runs through direct mill-to-plant resin delivery for national beverage accounts, while regional converters rely on distributor warehouses in Chicago, Atlanta, and Los Angeles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California SB 54 implementation creates a high-growth disruption as recycled-content mandates force simultaneous reformulation across resin grades, blow molding equipment, and supplier qualification protocols. This regulatory inflection compresses capital deployment cycles while fragmenting procurement geography for unprepared converters.
For Market Incumbents: Harden backward integration into post-consumer resin supply to control input cost volatility and PCR certification timelines. Consolidate supplier panels around integrated design-to-recycling partnerships that simplify compliance documentation for brand-owner procurement teams. Prioritize capacity addition in Texas chemical recycling corridors to capture food-grade resin feedstock premiums.
For New Entrants and Emerging Players: E-commerce fulfillment centers in Florida and Georgia seeking custom thermoformed trays and dunnage represent the most penetrable entry point, bypassing traditional packaging distributor relationships. Direct-to-retail distribution models capture premium margins through specification partnerships with Southeast fulfillment operators. Lead with rapid prototyping capabilities and short-run flexibility that incumbent high-speed blow molders cannot match.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because brand-owner procurement teams are reducing qualified converter pools by 40 percent to simplify compliance management. Target mid-scale converters with captive PCR supply and FDA food-contact notification expertise. Monitor California Department of Resources Recycling and Recovery enforcement mechanism finalization as the signal for accelerated M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PCR Supply | Captive post-consumer resin production hedges price volatility and secures California SB 54 compliance. |
| Lightweighting R&D Partnerships | Barrier coating innovation with FDA clearance reduces resin intensity per unit for carbonated soft drink bottlers. |
| Chemical Recycling Scale-Up | Pyrolysis investments in Texas and Louisiana supply food-grade resin feedstock for beverage applications. |
| Direct-to-Retail Distribution Bypass | E-commerce fulfillment center partnerships in Florida and Georgia disintermediate traditional packaging distributors. |
| Electric Machine Automation | High-speed stretch-blow molding upgrades address technician scarcity in Ohio and Indiana workforce clusters. |
Research Methodology
The analysis maps bottles, containers, jars, and tubs segments, each validated through blow molding plant managers, resin procurement leads at beverage bottlers, FDA regulatory affairs specialists, and aftermarket service technicians. Primary fieldwork combined with secondary validation from EPA industrial emissions databases, FDA food-contact notification filings, state extended producer responsibility statute texts, and SEC 10-K disclosures from packaging conglomerates. Bottom-up capacity modeling and top-down demand triangulation cross-verify volume estimates.
Assumptions held fixed include California SB 54 recycled-content thresholds, FDA compliance timelines, and Great Lakes reprocessing infrastructure capacity. Variables modeled across the analysis window span product format, end-use segment, material grade, and closure type. CAGRs derive from segment-level demand elasticity and supply-side capacity expansion schedules. Forecast inputs incorporate lightweighting mandate adoption curves and hot-fill polypropylene substitution rates in ready-to-drink segments.
Practitioners should monitor municipal recycling program funding volatility, chemical recycling EPA permitting clarity, and blow molding equipment delivery queue lengths for early signals of forecast deviation. Macroeconomic contraction in beverage consumption, regulatory delay in state extended producer responsibility frameworks, or breakthrough mono-material barrier alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
GCC Packaging Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
US Rigid Thermoform Plastic Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
Rigid Packaging Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
Collapsible Rigid Containers Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Bulk Packaging Market