
 Surgical Mesh Market | 2026-2036
Surgical Mesh Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Mesh Market Outlook
Project finance tied to hospital capital expenditure cycles is rewriting competitive access for mesh suppliers. Medtronic leverages long-term equipment leasing partnerships to secure shelf space in integrated delivery networks. W. L. Gore & Associates anchors its position through captive manufacturing of expanded polytetrafluoroethylene biomaterials. Johnson & Johnson navigates procurement consolidation by bundling mesh with suture and stapler contracts.
Surgical mesh comprises a woven or knitted fabric scaffold, typically constructed from polypropylene, polyester, or biologic collagen matrices, engineered to reinforce weakened fascia or support tissue ingrowth during wound healing. The device serves primarily to reduce recurrence rates in abdominal wall defects and pelvic organ prolapse. Biological mesh commands premium positioning in contaminated surgical fields where synthetic implantation risks infection, while non-absorbable polypropylene variants dominate clean hernia repair volumes due to durable tensile strength and favorable cost profiles. Ambulatory surgical centers represent the fastest-growing end-user channel as payors shift reimbursement toward outpatient settings.
FDA 510(k) clearance pathways and EU MDR conformity assessment procedures govern market entry, with both frameworks intensifying clinical evidence requirements for permanent implantable devices. The EPA regulates perfluorinated compound emissions from polytetrafluoroethylene processing facilities, influencing raw material sourcing decisions for mesh manufacturers. Stakeholders must monitor evolving biocompatibility testing standards and reimbursement coding changes that determine site-of-care economics.
Market Dynamics
FDA premarket notification tightening for permanent implants is compressing competitive entry timelines while hospital procurement consolidation forces mesh suppliers into bundled contracting arrangements with integrated delivery networks.
Growth Catalysts
- Ambulatory surgical center expansion:Payor reimbursement shifts toward outpatient hernia repair procedures accelerate same-day discharge protocols and drive demand for low-profile synthetic meshes.
- EU MDR conformity assessment:Enhanced clinical evidence requirements for permanent implantable devices elevate barriers for marginal competitors and consolidate market access for established manufacturers with robust technical documentation.
- Biologic collagen matrix adoption:Contaminated surgical fields in complex abdominal wall reconstruction create preference for absorbable biological scaffolds despite premium positioning.
Market Restraints
- Polypropylene raw material concentration:Petrochemical feedstock volatility and limited domestic polymer production capacity expose mesh manufacturers to input cost swings.
- Perfluorinated compound regulation:EPA emissions controls on polytetrafluoroethylene processing facilities constrain expanded PTFE biomaterial sourcing flexibility for specialized mesh applications.
- Synthetic mesh litigation exposure:Product liability claims related to chronic pain and erosion complications generate defensive R&D redirection toward resorbable alternatives.
Strategic Opportunities
- India surgical infrastructure buildout:Government hospital modernization programs and medical device PLI scheme incentives create localized manufacturing and distribution footholds for international mesh suppliers.
- 3D-printed patient-specific implants:Additive manufacturing convergence with digital surgical planning enables anatomically matched scaffold geometries for complex pelvic floor reconstruction.
- Site-of-care economics optimization:Value-based care contracts reward reduced recurrence rates, creating preference for higher-performance mesh configurations in accountable care organization networks.
Industry Challenges
- Biocompatibility testing standard evolution:ISO 10993 series updates and novel pyrogenicity assay requirements extend preclinical validation timelines for next-generation mesh surfaces.
- Cleanroom manufacturing capex intensity:EU MDR Annex I sterility assurance and particulate control mandates require facility retrofit investments that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Mesh Market |
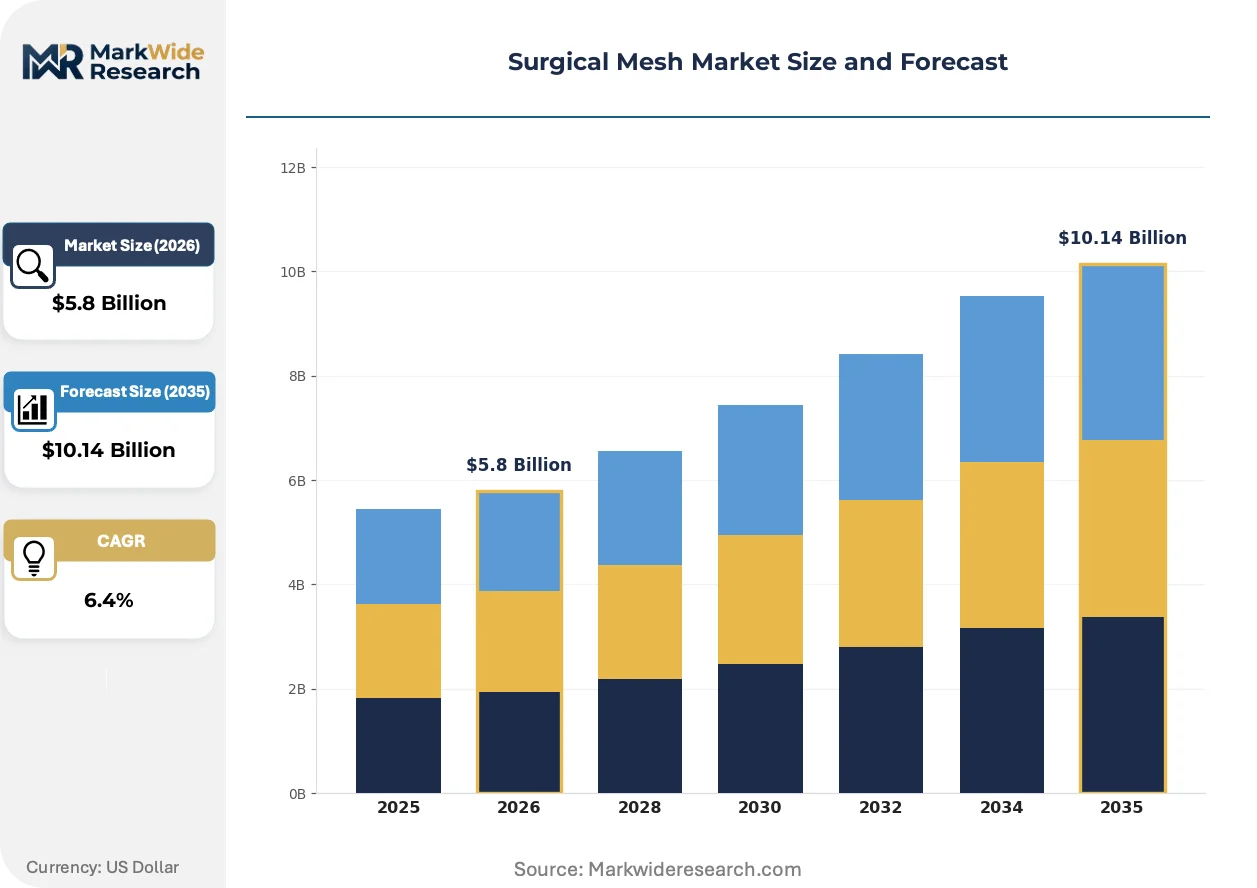
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Mesh, Absorbable Mesh, Non-Absorbable Mesh, Biological Mesh End User: Hospitals, Clinics, Ambulatory Surgical Centers, Specialty Clinics Material: Polypropylene, Polyester, Polyglactin, Polytetrafluoroethylene Application: Hernia Repair, Pelvic Floor Repair, Stoma Management, Surgical Application |
| Companies Covered | Medtronic, BD, Johnson & Johnson, B. Braun, Cook Medical, W. L. Gore & Associates, Ethicon, Baxter International, TELA Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Mesh Market Strategic Shifts
Material science advances and regulatory evidence requirements are converging to reshape mesh product architectures, with hybrid synthetic-biologic constructs and digital surgical integration emerging as defining vectors of competitive differentiation.
Barrier-coated polypropylene mesh is hybridizing conventional tensile strength with anti-adhesive surface properties. Ambulatory surgical centers in the United States are standardizing these configurations for laparoscopic ventral hernia repair. The technology is hybridizing cost structures by reducing operative time and postoperative complication management expenses.
EU MDR clinical evaluation report requirements for permanent implants are intensifying post-market surveillance obligations. Manufacturers must now maintain systematic literature review protocols and periodic safety update reports across product lifecycles. Class III implantable device categories face the steepest documentation burden, compressing smaller competitors from premium segments.
Surgeon preference is consolidating around pre-shaped three-dimensional mesh geometries matched to specific defect classifications. Academic medical centers are displacing flat sheet configurations with anatomically contoured designs in complex incisional hernia repair. Germany and the Netherlands lead European adoption of these patient-matched implant protocols.
Surgical Mesh Market Segmentation
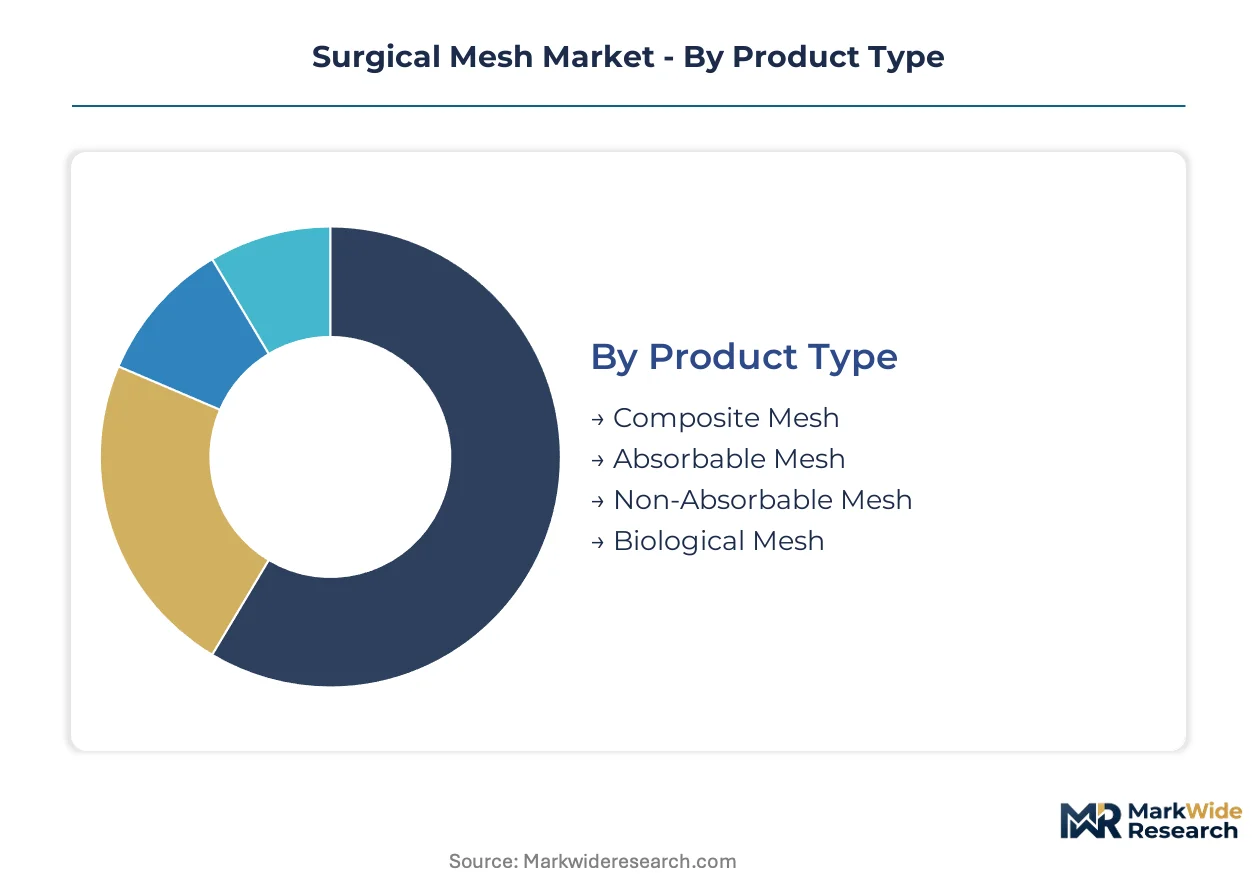
Segmentation in surgical mesh reveals distinct procurement cycles and clinical decision hierarchies that determine supplier access. Material selection drives replacement frequency, while site-of-care shifts reshape volume distribution across channel types.
Product Type:
Replacement cycles vary sharply across product categories, with absorbable formats turning over within months versus permanent synthetics remaining implanted for decades.
- Non-Absorbable Mesh:Woven or knitted polypropylene scaffolds engineered for permanent fascial reinforcement. Demand concentrates in North American hospital systems where durable tensile strength reduces hernia recurrence liability under value-based care contracts.
- Biological Mesh:Sterilized collagen matrices derived from human or animal tissue sources. Complex abdominal wall reconstruction in contaminated surgical fields drives preference despite premium positioning and supply constraints.
- Composite Mesh:Dual-layer constructions combining synthetic strength with anti-adhesive barriers. Laparoscopic ventral hernia repair protocols standardize these configurations.
- Absorbable Mesh:Polyglactin or polyglycolic acid constructs providing temporary support during tissue remodeling. Pediatric and contaminated field applications favor these resorbable formats.
Non-absorbable mesh dominates installed base. Biological mesh is where expansion concentrates.
End User:
Capital intensity and procurement autonomy separate institutional customers, with integrated delivery networks exercising volume leverage unavailable to standalone facilities.
- Hospitals:Inpatient surgical departments with dedicated hernia centers and complex reconstruction capabilities. Academic medical centers in the United States anchor demand for premium biologic and patient-matched configurations.
- Ambulatory Surgical Centers:Same-day discharge protocols for inguinal and uncomplicated ventral hernia repair. United States payor reimbursement shifts accelerate volume migration toward these lower-cost settings.
- Clinics:Office-based surgical suites handling minor hernia repairs with limited mesh inventory breadth.
- Specialty Clinics:Urogynecology and colorectal focused practices performing pelvic floor reconstruction with specialized biologic mesh protocols.
Hospitals retain the deepest mesh formularies. Ambulatory surgical centers are climbing the fastest.
Material:
Feedstock availability and processing chemistry create tiered supply security profiles that influence manufacturer sourcing strategies.
- Polypropylene:Thermoplastic polymer dominating synthetic mesh production due to tensile strength and biocompatibility profile. Petrochemical feedstock volatility exposes manufacturers to margin pressure.
- Polytetrafluoroethylene:Expanded PTFE biomaterials providing microporous structures for specialized adhesion-resistant applications. EPA emissions controls constrain domestic processing capacity.
- Polyester:Alternative synthetic with flexibility advantages in certain anatomic conformations. European manufacturers favor this material for specific hernia classifications.
- Polyglactin:Absorbable copolymer used in temporary reinforcement scaffolds and composite mesh absorbable components.
Polypropylene anchors volume production. Polytetrafluoroethylene commands the steepest expansion trajectory in specialized barrier applications.
Application:
Procedure volume and reimbursement coding determine addressable market scope, with hernia repair offering scale unavailable to niche reconstructive indications.
- Hernia Repair:Inguinal, ventral, and incisional hernia procedures representing the core volume indication. Laparoscopic technique adoption in the United States and Germany standardizes low-profile synthetic mesh configurations.
- Pelvic Floor Repair:Stress urinary incontinence and pelvic organ prolapse procedures utilizing biologic or macroporous synthetic slings. Litigation exposure has redirected R&D toward resorbable alternatives.
- Stoma Management:Parastomal hernia prevention and repair surrounding colostomy or ileostomy sites. Specialist colorectal surgical centers drive demand for customized mesh geometries.
- Surgical Application:Miscellaneous reinforcement procedures including diaphragmatic repair and chest wall reconstruction with case-specific mesh selection.
Hernia repair commands procedure volume leadership. Pelvic floor repair is gaining share fastest amid technique refinement and patient-matched implant adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in surgical mesh track closely to regulatory approval velocity and hospital procurement sophistication. Net exporters cluster in jurisdictions with established FDA or EU MDR clearances, while import-dependent markets are expanding domestic manufacturing through targeted incentive schemes.
United States
Academic medical centers in Boston and Houston drive demand for patient-matched three-dimensional mesh configurations. FDA 510(k) tightening for permanent implants compresses competitive entry timelines while favoring established manufacturers with robust technical documentation. The Minneapolis-St. Paul corridor anchors specialized biomaterial processing clusters serving integrated delivery networks.
Germany
University hospitals in Munich and Heidelberg standardize anatomically contoured mesh designs for complex incisional hernia repair. EU MDR conformity assessment procedures elevate clinical evidence requirements and consolidate market access for manufacturers with systematic post-market surveillance protocols. The Baden-Württemberg region concentrates precision polymer processing capabilities for specialized barrier-coated constructs.
India
Government hospital modernization programs in Maharashtra and Karnataka accelerate mesh adoption in tier-two cities. CDSCO medical device regulations and PLI scheme incentives attract international suppliers toward localized manufacturing footprints. The Chennai-Telangana corridor emerges as a distribution hub for cost-optimized synthetic mesh serving South Asian markets.
Japan
Aging demographics and laparoscopic technique diffusion expand hernia repair volumes in Tokyo and Osaka metropolitan areas. PMDA marketing authorization requirements for permanent implants mandate rigorous biocompatibility testing that extends preclinical validation timelines. The Nagoya industrial zone sustains captive polymer supply chains for domestic mesh manufacturers.
Brazil
Private hospital networks in São Paulo and Rio de Janeiro anchor demand for premium biologic matrices in contaminated surgical fields. ANVISA medical device registration pathways are harmonizing with international standards to accelerate import substitution initiatives. The Minas Gerais corridor develops regional distribution infrastructure serving the Mercosur trade bloc.
Surgical Mesh Market Competitive Environment
On the supply side, the industry is consolidating around three distinct competitive tiers. Tier-one multinational conglomerates leverage long-term equipment leasing partnerships to secure formulary placement in integrated delivery networks. Tier-two regional specialists exploit geographic proximity and regulatory familiarity to defend niche segments. Tier-three emerging entrants target price-sensitive ambulatory surgical center channels through streamlined product portfolios. Dominant competitive moves include strategic bundling of mesh with complementary surgical devices and backward integration into captive biomaterial manufacturing.
Among diversified healthcare conglomerates, Medtronic, Johnson & Johnson, and Baxter International exemplify the scale-driven archetype that dominates hospital procurement consolidation. These entities anchor competitive positioning through bundled contracting arrangements spanning sutures, staplers, and mesh configurations. W. L. Gore & Associates occupies a specialized position representing the materials-science-intensive segment focused on expanded polytetrafluoroethylene biomaterials. BD and B. Braun sit within the European-rooted tier that leverages regional manufacturing proximity to serve EU MDR compliance requirements.
| Leading Market Players |
|---|
| Medtronic |
| BD |
| Johnson & Johnson |
| B. Braun |
| Cook Medical |
| W. L. Gore & Associates |
| Ethicon |
| Baxter International |
| TELA Bio |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock volatility determines both tiered pricing spreads across polypropylene-based meshes and the geographic configuration of polymer sourcing networks. Manufacturers with captive biomaterial production command premium positioning while exposed competitors absorb margin compression from input cost swings.
Pricing Analysis
Hospital procurement committees anchor contract-based long-term offtake structures that stratify across premium biologic, standard composite, and economy synthetic tiers. Price differentiation rests on FDA 510(k) clearance tier and volume scale commitments under integrated delivery network agreements. Cost compression in economy synthetics is intensifying because ambulatory surgical centers demand low-profile configurations at reimbursement-constrained price points. Standalone clinics exhibit highest price sensitivity; academic medical centers with dedicated hernia centers show lowest sensitivity due to outcome-based contracting.
Supply Chain Analysis
Export-control restrictions on perfluorinated compound processing limit expanded PTFE biomaterial flows from domestic facilities to specialized mesh applications. Polypropylene feedstock concentrates in the United States, Germany, and Saudi Arabia; biological collagen matrices draw from bovine and porcine tissue processors in the United States and Ireland. Single-source vulnerability in expanded PTFE microporous structures creates exposure to EPA emissions enforcement actions. Distribution runs through integrated delivery network central warehouses and specialized surgical device distributors serving ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical mesh market sits at a regulatory inflection where EU MDR clinical evidence requirements and FDA 510(k) tightening favor incumbents with systematic post-market surveillance infrastructure. Three-dimensional patient-matched geometries and hybrid synthetic-biologic constructs represent the technological disruption vector.
For Market Incumbents: Pre-empt emerging entrant encroachment in ambulatory surgical center channels through equipment leasing partnerships that lock in formulary placement. Deepen backward integration into captive polypropylene polymerization to insulate margins from petrochemical volatility. Prioritize CE marking pathway investments for Class III implantable categories before EU MDR documentation burdens compress smaller competitors from premium segments. For New Entrants and Emerging Players: Cost-optimized synthetic meshes for tier-two hospital systems in India represent the most penetrable entry point amid government modernization programs and PLI scheme incentives. 3D-printed patient-specific implants for complex pelvic floor reconstruction in German university hospitals offer white-space access through digital surgical planning partnerships. Pursue hospital system partnership go-to-market models that bundle mesh with navigation software and surgeon training protocols. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors materials-science-intensive specialists with expanded PTFE biomaterial captive production. Five-to-ten year viability hinges on regulatory clearance velocity and reimbursement coding capture in value-based care networks. Acquisition target archetype: regional European manufacturers with EU MDR technical documentation completeness and Baden-Württemberg precision polymer processing proximity. Watch FDA premarket notification submission volumes as early signal of competitive entry compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Submission | Accelerates market access for permanent implantable devices under tightening notification pathways. |
| EU MDR CE Marking Pathway | Establishes systematic post-market surveillance protocols for Class III implantable device categories. |
| Hospital System Partnership | Secures formulary placement through bundled contracting with integrated delivery networks. |
| Backward Integration into Polymerization | Captures upstream control over polypropylene feedstock to buffer petrochemical cost volatility. |
| Reimbursement Strategy | Aligns mesh configuration selection with site-of-care economics in accountable care organization networks. |
Study Parameters
Initial hypotheses were tested against primary input from hernia center surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers and refined through secondary validation. FDA 510(k) clearances, EU MDR clinical evaluation reports, hospital procurement databases, and CMS Medicare reimbursement data anchored quantitative baselines. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation converged on segment-level outputs.
Demand-supply balance modeling across the analysis window incorporated product type, material chemistry, end-user channel, and application-specific procedure coding dimensions. CAGRs were derived from fitted growth curves applied to baseline volume data. Forecast inputs included laparoscopic technique diffusion rates, ambulatory surgical center reimbursement policy shifts, and biologic collagen matrix supply constraints.
Practitioners should monitor FDA premarket notification backlog clearance rates and EU MDR notified body capacity constraints for early signals of competitive access compression. Forecasts reflect assumptions regarding petrochemical feedstock stability and reimbursement coding continuity. Material shifts in EPA perfluorinated compound enforcement intensity or value-based care contract penetration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Struts Implants Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Global Joint Pain Injections Market
Medical Devices
Ablation Devices Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Luer Lock Connector Market
Medical Devices
Global Auto-Injectors Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Peak Flow Meters Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
Hybrid Grafts Market
Medical Devices
South Africa Minimally Invasive Surgical Devices Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market