
 Europe Modular Construction Market | 2026-2036
Europe Modular Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Modular Construction Market Foresight
Project finance tied to green bonds and sustainability-linked loans is fragmenting capital access across the Europe modular construction landscape. Skanska AB leverages its Nordic project development pipeline to anchor factory-to-site workflows in Sweden and Norway. Laing O'Rourke competes through its Explore Industrial Park facility near Sheffield, sustaining high-throughput manufacturing of volumetric modules. Vinci S.A. differentiates via integrated design-build-operate contracts that extend from French social housing into Belgian and German infrastructure-adjacent projects.
Europe modular construction encompasses factory-built volumetric units, panelized assemblies, and prefabricated structural components manufactured under controlled conditions with specified tolerances, then transported and craned into final position. Off-site manufacturing reduces embodied carbon through optimized material flows and waste minimization, serving residential, commercial, and institutional end uses where speed and quality consistency matter. Panelized systems dominate volume in single-family and low-rise residential applications across Northern Europe, while modular components capture margin in complex commercial and educational facilities requiring MEP integration. Prefabricated buildings represent the fastest-growing product category as French and Dutch developers scale permanent multi-story housing programs.
The EU Green Deal and national transpositions through France's RE2020 environmental regulation and the UK's Future Homes Standard shape product specifications, mandating lifecycle carbon disclosure that favors factory-controlled supply chains. CE marking under the Construction Products Regulation governs market access, with ECHA REACH compliance adding material traceability requirements for imported timber and steel inputs. Stakeholders must monitor how the EU AI Act and emerging digital product passports reshape quality assurance protocols and cross-border module certification.
Market Dynamics
The EU Green Deal's embodied carbon reporting mandate is compressing project timelines and forcing developers toward factory-controlled production methods that can document lifecycle emissions with precision.
Growth Catalysts
- France's RE2020 environmental regulation:RE2020 mandates lifecycle carbon disclosure for new buildings, pushing French developers toward modular systems that optimize material flows and waste minimization.
- Skilled labor shortages in construction:Persistent deficits of qualified tradespeople across Germany, the Netherlands, and Scandinavia are accelerating factory-based prefabrication that reduces on-site labor dependence.
- Cross-laminated timber (CLT) integration:CLT panels manufactured under controlled conditions enable rapid assembly of multi-story residential structures while meeting stringent fire safety and acoustic standards.
Market Restraints
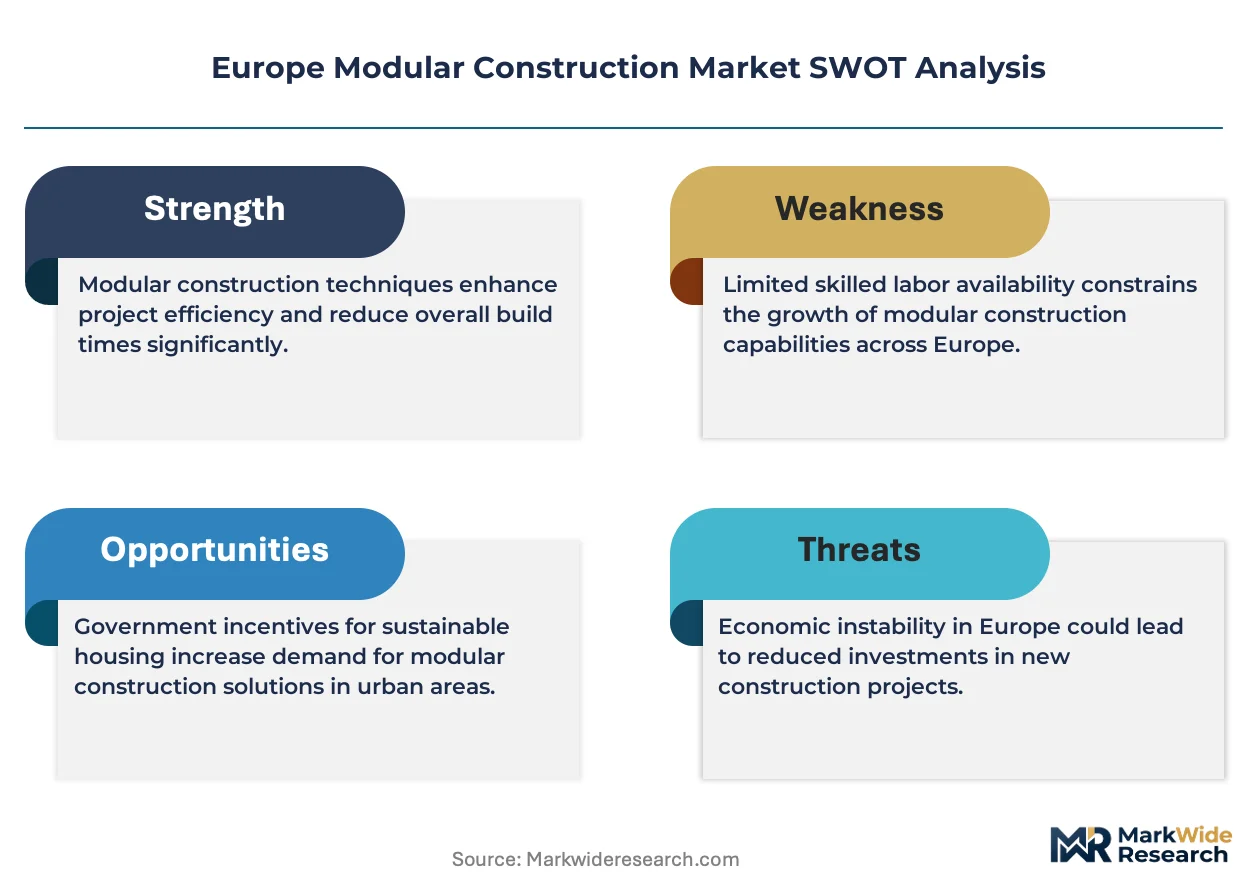
- Steel and timber input cost volatility:Fluctuating prices for structural steel and engineered wood products compress margins for fixed-price modular contracts, particularly in high-inflation environments.
- Transportation infrastructure constraints:Narrow rural roads and low bridge clearances across rural France and Northern England limit module dimensions and increase logistics costs for remote sites.
- CE marking complexity under CPR:The Construction Products Regulation's module-specific certification requirements create timeline friction for cross-border projects between EU member states.
Strategic Opportunities
- Belgian social housing pipeline:Flemish and Walloon regional governments are expanding subsidized housing programs that favor standardized volumetric modules for speed of delivery.
- Digital product passports:The EU's emerging digital product passport framework creates first-mover advantage for modular manufacturers with integrated material traceability systems.
- Healthcare facility retrofit:Aging hospital infrastructure across Italy and Spain presents demand for rapid-deployment modular wards and diagnostic units with integrated MEP systems.
Industry Challenges
- Building information modeling (BIM) integration:Fragmented BIM standards between architectural firms and modular factories create coordination errors during design-to-manufacture handoffs.
- Site preparation synchronization:Foundation and utility readiness delays at construction sites force costly module storage and crane re-mobilization, eroding schedule advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Modular Construction Market |
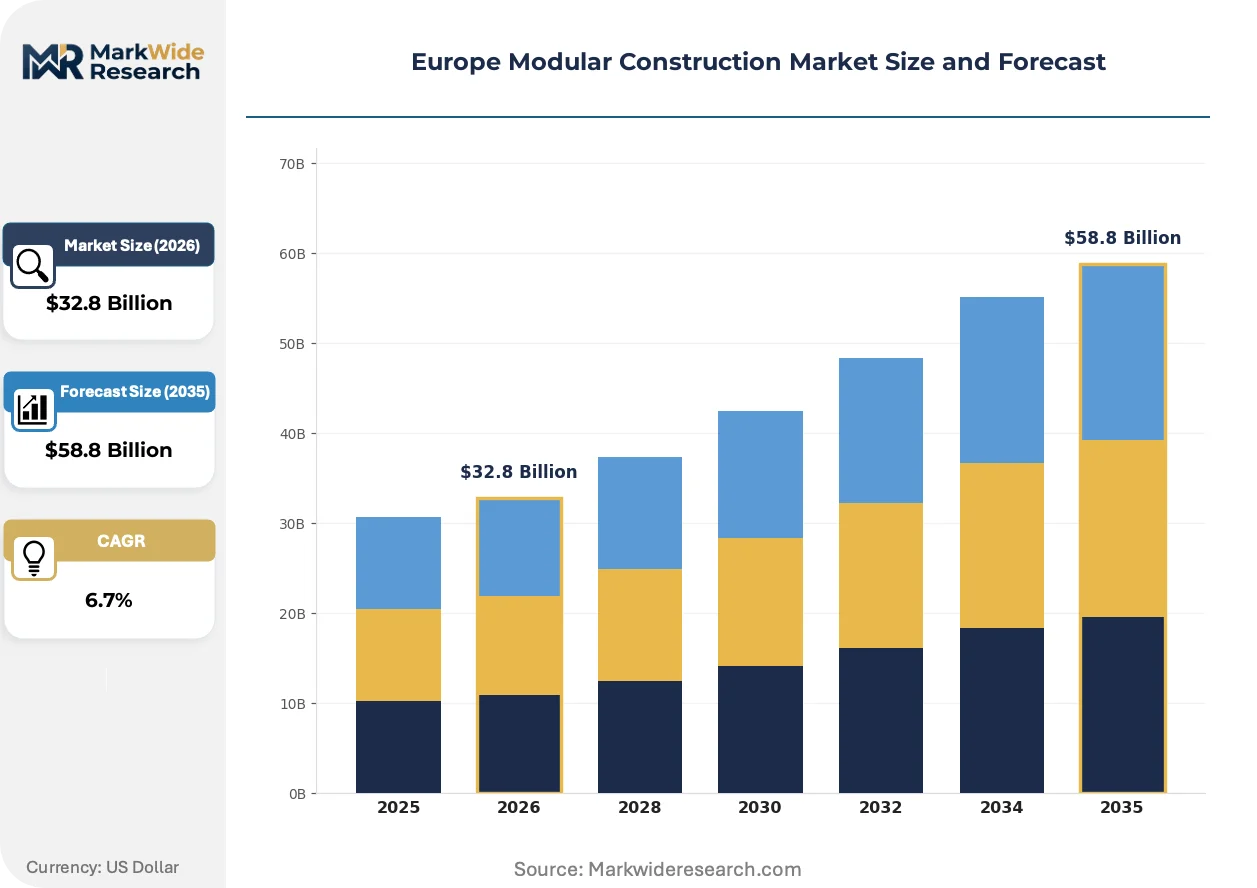
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $58.8 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Off-site Manufacturing, Panelized Systems, Modular Components, Prefabricated Buildings Application: Residential Buildings, Commercial Facilities, Industrial Projects, Educational Institutions End User: Construction Firms, Developers, Government Entities, Architects Installation Type: Permanent Structures, Temporary Structures, Lightweight Modules, Heavy-duty Modules |
| Companies Covered | Modulaire Group, Lendlease Corporation Limited, Laing O'Rourke, Vinci S.A., Elements Europe Ltd, Skanska AB, Kleusberg GmbH & Co. KG, CIMC Modular Building Systems, Bouygues Construction, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Modular Construction Market Shifts & Advancements
Factory-to-site workflow digitization is collapsing traditional construction sequencing, compressing program durations while embedding quality assurance at the point of manufacture rather than final inspection.
Light-gauge steel framing systems with integrated MEP rough-ins are collapsing the distinction between structural shell and finished interior, enabling Swedish and Norwegian developers to deliver multi-family housing with 40% fewer on-site trades. Residential contractors in Copenhagen and Oslo are specifying these systems for projects above six stories where traditional timber faces fire code constraints. The technology is collapsing the competitive position of conventional stick-built methods in Northern European urban infill sites.
The EU AI Act's quality assurance provisions are reshaping factory inspection protocols, mandating documented algorithmic transparency for automated welding and dimensional verification systems. German modular manufacturers near Dortmund and Hanover are retrofitting production lines with explainable AI vision systems to maintain CE marking eligibility. Panelized producers serving Dutch social housing programs face the steepest compliance ramps given their reliance on robotic cutting and fastening equipment.
Developer procurement is consolidating around design-build-operate contracts that transfer long-term performance risk to modular suppliers. French institutional investors in Paris and Lyon are favoring twenty-year service agreements covering energy performance and maintenance over traditional capital expenditure models. This pattern is most pronounced in student housing and senior living verticals where operational cost predictability outweighs first-cost minimization.
Europe Modular Construction Market Segmentation
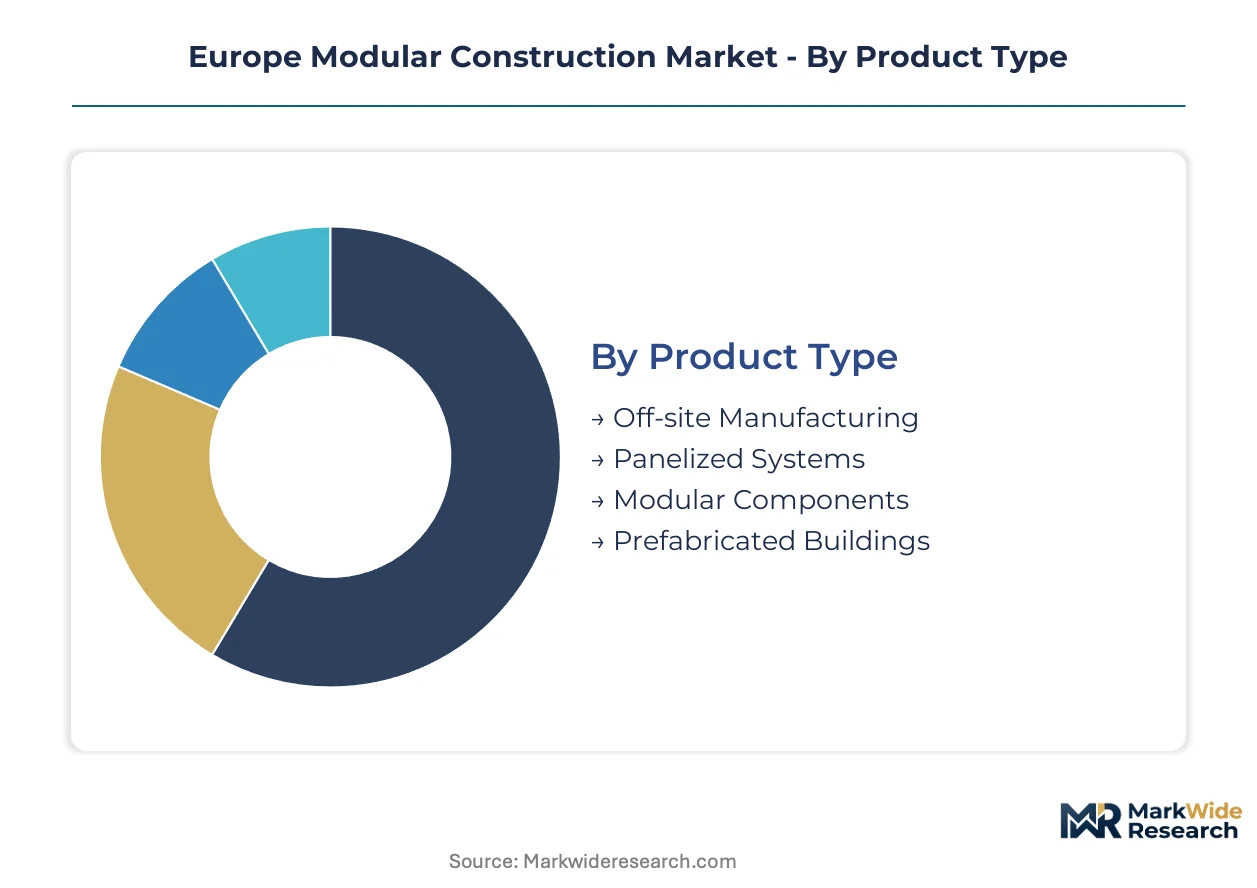
Modular construction segments diverge sharply by capital intensity, regulatory exposure, and supply chain configuration. Understanding these boundaries clarifies where factory-controlled production methods displace conventional site-built approaches across European markets.
Product Type:
Cost tier differentiation separates high-volume panelized systems from premium volumetric modules requiring integrated MEP rough-ins.
- Off-site Manufacturing:Factory-controlled production of structural elements under specified tolerances enables precision engineering for complex geometries. German and Scandinavian residential developers anchor procurement here for multi-family housing where embodied carbon reporting under RE2020 and the EU Green Deal mandates documented lifecycle emissions. Skilled labor shortages across the Netherlands and Germany accelerate adoption as factory workflows reduce on-site trade dependence.
- Panelized Systems:Flat-packed wall, floor, and roof assemblies manufactured for rapid on-site erection dominate single-family and low-rise residential applications across Northern Europe. French and Dutch developers specify these for speed of delivery in subsidized housing programs where standardized dimensions compress program timelines. The format struggles in complex commercial facilities requiring volumetric MEP integration.
- Modular Components:Prefabricated structural elements including CLT panels and light-gauge steel framing systems serve mid-rise residential and institutional projects.
- Prefabricated Buildings:Complete volumetric units craned into final position capture margin in healthcare and educational facilities requiring rapid deployment.
Panelized systems command the established base. The steepest expansion runs through prefabricated buildings as French and Dutch developers scale permanent multi-story housing programs.
Application:
End-use maturity determines where factory-to-site workflows compress program durations versus where conventional methods retain cost advantages.
- Residential Buildings:Multi-family housing across Germany, France, and the Netherlands drives procurement volume as labor shortages intersect with housing deficits. RE2020 lifecycle carbon disclosure and the UK's Future Homes Standard favor controlled manufacturing environments that document embodied emissions with precision. Copenhagen and Oslo developers specify light-gauge steel systems above six stories where timber faces fire code constraints.
- Commercial Facilities:Office and retail fit-outs with repetitive bay spacing leverage modular MEP integration for speed of tenant occupancy. Belgian and German infrastructure-adjacent projects favor design-build-operate contracts transferring long-term performance risk to suppliers. The segment demands higher engineering margins than residential applications.
- Industrial Projects:Manufacturing facilities and logistics centers utilize heavy-duty modules for rapid capacity expansion.
- Educational Institutions:Schools and university facilities require acoustic performance and fire safety certification that factory-controlled environments standardize efficiently.
Residential buildings anchor volume concentration. Commercial facilities are climbing the fastest as institutional investors favor operational cost predictability over first-cost minimization.
End User:
Customer type shapes procurement sophistication and contract structure preferences across the value chain.
- Construction Firms:General contractors integrating modular subassemblies into broader site-built programs dominate panelized system procurement. German and UK firms face compressed margins when foundation delays force costly module storage and crane re-mobilization.
- Developers:French institutional investors in Paris and Lyon favor twenty-year service agreements covering energy performance and maintenance. Student housing and senior living verticals drive this shift toward outcome-based contracting.
- Government Entities:Flemish and Walloon regional governments expanding subsidized housing programs favor standardized volumetric modules.
- Architects:Design firms specifying modular systems face fragmented BIM standards creating coordination errors during design-to-manufacture handoffs.
Construction firms retain the incumbent position. Developers are gaining share fastest as procurement consolidates around long-term performance guarantees.
Installation Type:
Structural permanence and load-bearing requirements segment logistics complexity and foundation engineering demands.
- Permanent Structures:Foundation-anchored modules designed for fifty-plus year lifespans dominate French social housing and Belgian subsidized programs. CE marking under the Construction Products Regulation governs market access with ECHA REACH compliance adding material traceability for imported timber and steel inputs.
- Temporary Structures:Rapid-deployment units for healthcare retrofit and emergency housing serve aging hospital infrastructure across Italy and Spain. The format sacrifices thermal performance for speed of installation.
- Lightweight Modules:Reduced structural loads enable deployment on constrained urban infill sites with limited crane access.
- Heavy-duty Modules:Reinforced framing supports industrial applications and multi-story residential above eight levels.
Permanent structures hold the revenue base. Lightweight modules are expanding most quickly as urban infill constraints intensify across Northern European cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's RE2020 environmental regulation and the EU Green Deal's embodied carbon mandates are redirecting capital toward factory-controlled construction methods across Northern and Western Europe. National transpositions vary in stringency, creating differentiated adoption curves by member state.
Germany
Multi-family housing developers in Berlin and Munich face acute shortages of qualified tradespeople, accelerating procurement of panelized systems and volumetric modules. The federal government's KfW energy efficiency programs tie subsidized financing to documented lifecycle carbon performance, favoring factory-controlled supply chains. Industrial clusters near Dortmund and Hanover host retrofitting production lines with explainable AI vision systems to maintain CE marking eligibility under emerging EU AI Act provisions.
France
Paris and Lyon institutional investors favor twenty-year design-build-operate contracts for student housing and senior living, transferring long-term performance risk to modular suppliers. RE2020 mandates lifecycle carbon disclosure for new buildings, pushing developers toward systems that optimize material flows and waste minimization. Factory-to-site workflows concentrate in Île-de-France and Auvergne-Rhône-Alpes where social housing programs require speed of delivery.
United Kingdom
The Future Homes Standard shapes product specifications for low-rise residential applications across England and Wales, mandating thermal performance thresholds that factory environments standardize efficiently. Laing O'Rourke's Explore Industrial Park facility near Sheffield sustains high-throughput manufacturing of volumetric modules for complex commercial and educational facilities. Narrow rural roads and low bridge clearances across Northern England constrain module dimensions and inflate logistics costs for remote sites.
Netherlands
Subsidized housing programs in Amsterdam and Rotterdam specify standardized panelized dimensions to compress program timelines, with robotic cutting and fastening equipment facing steep compliance ramps under EU AI Act quality assurance provisions. Dutch social housing corporations consolidate procurement around outcome-based contracting models. Randstad logistics infrastructure supports rapid module distribution despite constrained urban infill sites.
Sweden
Skanska AB leverages its Nordic project development pipeline to anchor factory-to-site workflows across Stockholm and Oslo corridors. Light-gauge steel framing systems with integrated MEP rough-ins enable multi-family housing delivery above six stories where timber faces fire code constraints. Copenhagen developers specify these systems for urban infill projects, collapsing the competitive position of conventional stick-built methods in Scandinavian markets.
Europe Modular Construction Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered vendor base where scale advantages concentrate in integrated design-build-operate platforms. The market fragments between Nordic construction conglomerates with captive manufacturing capacity, Continental European engineering specialists, and Asian fabricators supplying structural components. Three archetypes dominate: vertically integrated developers controlling project pipelines, independent module manufacturers serving third-party contractors, and material-agnostic system integrators sourcing across steel, timber, and composite substrates. Competitive moves center on strategic partnerships anchoring factory-to-site workflows and portfolio diversification into healthcare and educational verticals.
Within the integrated developer tier, Skanska AB and Vinci S.A. exemplify channel-controlling strategies that internalize project origination through final assembly. Laing O'Rourke occupies a position bridging British infrastructure contracting with captive manufacturing capacity. Among independent specialists, Kleusberg GmbH & Co. KG represents German engineering-focused fabrication, while Elements Europe Ltd anchors UK-based volumetric production for complex commercial programs. Bouygues Construction and Lendlease Corporation Limited sit within the multinational contractor archetype, leveraging balance sheet scale to underwrite long-term service agreements. Modulaire Group and CIMC Modular Building Systems exemplify asset-light leasing and containerized module platforms respectively, each targeting temporary and permanent structure deployments across divergent regulatory environments.
| Leading Market Players |
|---|
| Modulaire Group |
| Lendlease Corporation Limited |
| Laing O'Rourke |
| Vinci S.A. |
| Elements Europe Ltd |
| Skanska AB |
| Kleusberg GmbH & Co. KG |
| CIMC Modular Building Systems |
| Bouygues Construction |
| Others |
Supply & Pricing Matrix
Dortmund and Hanover industrial clusters anchor German modular manufacturing capacity, concentrating supply-side leverage among producers with integrated steel fabrication and timber processing capabilities. Factory-controlled production environments with CE marking compliance extract pricing premiums from developers facing RE2020 carbon disclosure mandates, while input cost volatility in structural steel and engineered wood compresses margins for fixed-price contracts.
Pricing Analysis
Certification level under CE marking and the EU AI Act creates the primary spread between premium volumetric modules and commodity panelized systems. Three-tier pricing structure across premium certified, standard compliant, and economy-grade tiers reflects documentation intensity for lifecycle carbon reporting. Cost compression in economy-grade panelized segments is intensifying because of timber input volatility and logistics constraints across rural France. Social housing developers in the Netherlands exhibit highest price sensitivity, while French institutional investors in Paris and Lyon prioritize long-term performance guarantees over first-cost minimization.
Supply Chain Analysis
Tariff exposure between EU member states and third-country timber suppliers dominates supply chain risk assessment for modular manufacturers. Production gravity centers on Germany, Sweden, and the Netherlands, with cross-laminated timber inputs drawing from Austrian and Finnish forestry operations. Single-source vulnerability in specialized MEP rough-in components creates bottleneck risk for volumetric module assemblers. Distribution runs through project-specific factory-to-site workflows with crane logistics and foundation readiness synchronization determining final mile economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe modular construction is approaching a platform-economics inflection where digital product passports and BIM-to-factory data interoperability will determine competitive viability. Ecosystem consolidation around design-build-operate contracts rewards suppliers with integrated material traceability and long-term service infrastructure.
For Market Incumbents: Insulate core margins by deepening captive supply of cross-laminated timber and light-gauge steel framing systems near Dortmund and Hanover production clusters. Acquire or partner with BIM software specialists to eliminate design-to-manufacture handoff errors that currently force costly module rework. The EU AI Act's quality assurance provisions threaten CE marking eligibility for producers lacking explainable AI vision systems in automated welding lines. For New Entrants and Emerging Players: Belgian social housing pipeline expansion in Flemish and Walloon regions represents the most penetrable entry point for standardized volumetric modules with rapid-deployment credentials. Healthcare facility retrofit demand across aging Italian and Spanish hospital infrastructure offers second-mover advantage for modular ward and diagnostic unit specialists. Go-to-market positioning should emphasize outcome-based contracting with energy performance guarantees rather than capital expenditure competition. For Investors and Strategic Acquirers: Long-term, this sits as a decarbonization infrastructure play because embodied carbon reporting mandates under the EU Green Deal and national transpositions like RE2020 structurally favor factory-controlled supply chains over conventional site-built methods. Acquisition targets should prioritize modular manufacturers with integrated design-build-operate platforms and established relationships with institutional investors in student housing and senior living verticals. Monitor digital product passport implementation timelines as the critical inflection signal for first-mover advantage in material traceability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CLT Manufacturing | Austrian and Finnish timber supply control secures input cost predictability for German producers facing RE2020 compliance. |
| Digital Product Passport Readiness | Material traceability systems position modular manufacturers for EU regulatory first-mover advantage in cross-border certification. |
| Design-Build-Operate Contract Expansion | Twenty-year service agreements with French institutional investors transfer long-term performance risk from capital markets. |
| AI Vision System Retrofit | Explainable quality assurance maintains CE marking eligibility under emerging EU AI Act factory inspection protocols. |
| Healthcare Vertical Diversification | Rapid-deployment modular wards address aging hospital infrastructure deficits across Italy and Spain with integrated MEP systems. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with modular manufacturing executives, construction firm procurement directors, social housing corporation investment officers, and BIM integration specialists; and secondary validation through EU Construction Products Regulation filings, ECHA REACH compliance databases, national housing agency procurement records, and trade flow data for engineered timber and structural steel inputs. Bottom-up module production estimates and top-down construction spend allocation were triangulated against factory capacity utilization rates reported by industrial clusters near Dortmund, Hanover, and Sheffield.
Forecast inputs considered product type segmentation across volumetric modules, panelized systems, and prefabricated structural components; application splits between residential, commercial, and institutional end uses; and end-user procurement sophistication ranging from general contractors to institutional investors. CAGRs were derived from regression analysis of historical factory output growth against housing permit issuance and labor shortage indices across Germany, France, the Netherlands, and Scandinavia. Cross-border module shipment volumes and crane logistics cost structures provided additional calibration points.
Practitioners should monitor EU AI Act implementation timelines, digital product passport regulatory finalization, and RE2020 enforcement stringency variations across member states for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Indonesia Infrastructure Market
Building Construction
Prefabricated Construction Market
Building Construction
Ireland Data Center Construction Market
Building Construction
China Prefabricated Buildings Market
Building Construction
Europe 3D Printing Construction Market
Building Construction
GCC Cement Market
Building Construction
Vietnam Prefabricated Buildings Market
Building Construction
North America Modular Construction Market
Building Construction
Honduras Construction Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
GCC Advanced Buildings Materials Market
Building Construction
China Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
El Salvador Construction Market
Building Construction
Oman Construction Market
Building Construction
Energy-Efficient Building Market